
 Usage-Based Insurance for Automotive Market | 2026-2036
Usage-Based Insurance for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Usage-Based Insurance for Automotive Market Intelligence
Telematics-grade data fidelity is bifurcating the competitive landscape into precision insurers and legacy carriers. Progressive Casualty Insurance Company leverages its Snapshot program to sustain leadership in behavioral pricing models. Allstate Insurance Company anchors its market position through proprietary mobile application architecture that reduces hardware dependency.
Usage-Based Insurance for Automotive deploys connected vehicle sensors, GPS tracking modules, and onboard diagnostic ports to capture real-time driving behavior and mileage data for dynamic premium calculation. The system transmits encrypted telematics streams to insurer cloud platforms where algorithmic risk scoring replaces traditional demographic rating factors. Pay-How-You-Drive programs command expanding margin pools as behavioral data enables granular risk segmentation beyond basic mileage verification. Fleet Operators represent the fastest-growing customer type as logistics companies mandate driver accountability tools and fuel efficiency monitoring through integrated telematics dashboards.
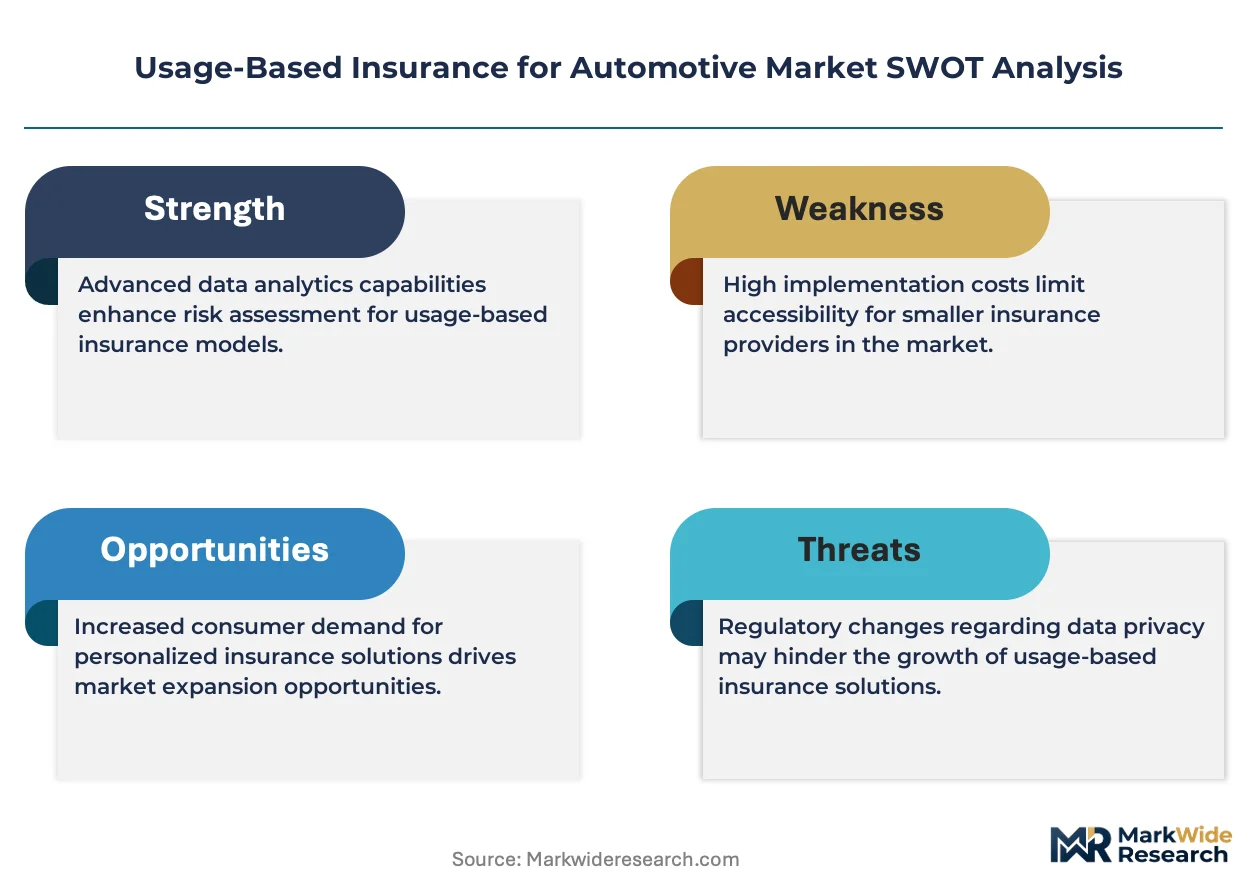
NHTSA guidelines on vehicle connectivity standards intersect with state-level insurance commissioner mandates for data transparency across the United States. The EU AI Act imposes algorithmic accountability requirements on automated underwriting decisions while GDPR restricts cross-border telematics data flows. Stakeholders must monitor evolving regulatory fragmentation between federal mobility frameworks and patchwork state privacy laws that threaten platform scalability.
Market Dynamics
Algorithmic underwriting is compressing actuarial cycles from annual to real-time recalibration, forcing insurers to rebuild core systems around streaming telematics ingestion rather than static risk pools.
Growth Catalysts
- Fleet telematics mandates:Logistics operators in Germany and the Netherlands now require driver behavior monitoring for commercial auto coverage, expanding addressable policy volumes.
- EU AI Act algorithmic accountability:Automated decision-making frameworks for premium pricing gain regulatory clarity, reducing compliance uncertainty for European insurers deploying behavioral models.
- 5G-V2X integration:Vehicle-to-everything communication protocols enable millisecond-latency crash detection and dynamic premium adjustment at the point of incident.
Market Restraints
- GDPR cross-border data friction:Telematics streams originating in EU member states face restricted transfer mechanisms to cloud infrastructure hosted outside the European Economic Area.
- Silicon sensor supply concentration:Automotive-grade accelerometer and gyroscope production clusters in Taiwan and South Korea create single-source vulnerability for hardware-dependent UBI programs.
- Legacy policy administration systems:Mainframe-based rating engines at incumbent carriers cannot ingest sub-second telematics feeds without complete architectural replacement.
Strategic Opportunities
- India's digitized motor insurance push:The country's central bank and insurance regulator are mandating linked vehicle data for commercial fleet coverage in metropolitan corridors.
- Embedded insurance at OEM point-of-sale:Factory-integrated telematics modules allow insurers to underwrite new vehicles before first registration, capturing lifetime policy value.
- Carbon-intensity scoring convergence:Linking driving behavior data with emissions tracking creates dual-revenue streams from ESG-conscious fleet managers and sustainability-linked finance providers.
Industry Challenges
- Actuarial-technologist talent scarcity:Underwriting teams lack data engineering capacity to build and validate machine learning models that satisfy internal model risk governance.
- Multi-jurisdiction certification timelines:State insurance commissioners in the United States impose varying prior-approval requirements for telematics-based rating factors, fragmenting product launch velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Usage-Based Insurance for Automotive Market |
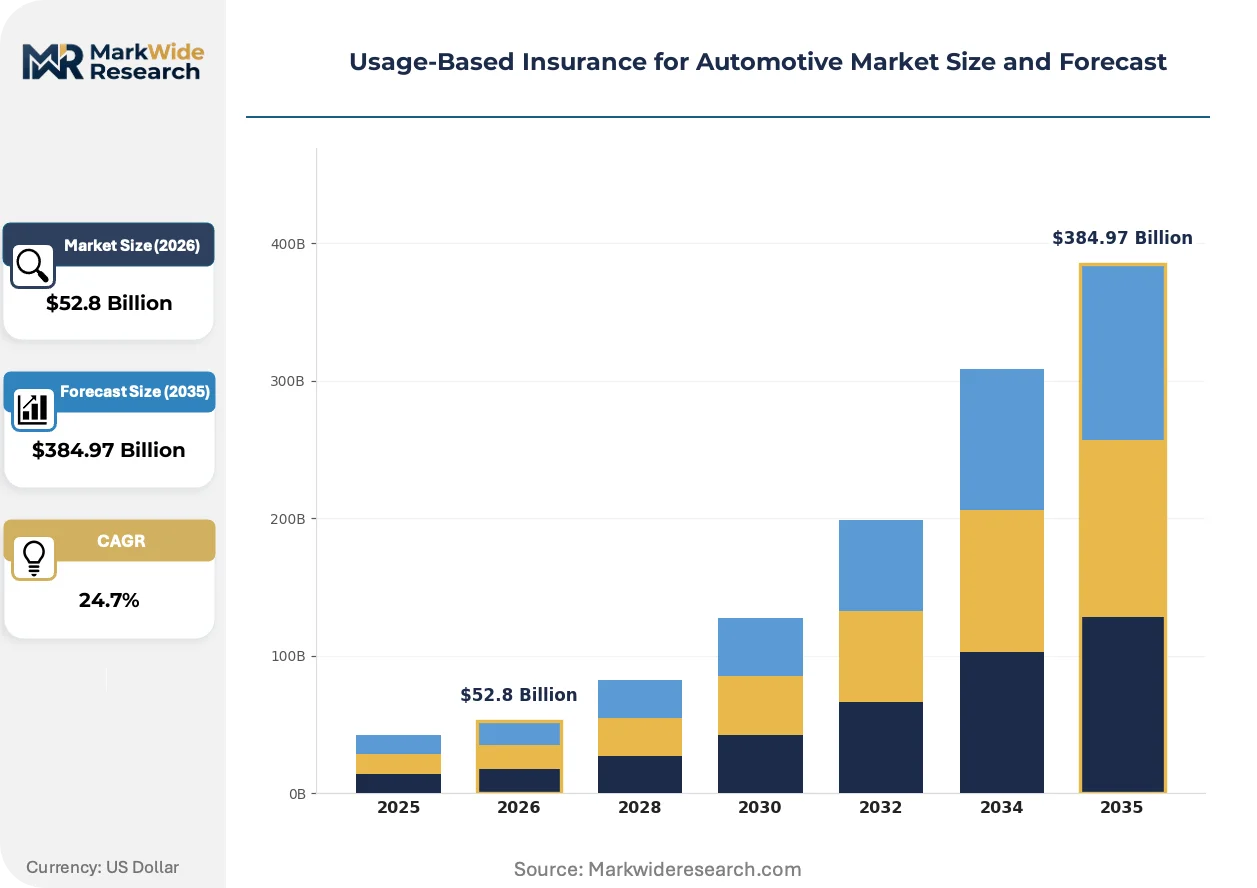
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $384.97 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pay-As-You-Drive, Pay-How-You-Drive, Mileage-Based, Time-Based Technology: Telematics, GPS Tracking, Mobile Applications, On-Board Diagnostics Customer Type: Individual Drivers, Fleet Operators, Car Sharing Services, Ride-Hailing Services Coverage Type: Comprehensive, Third-Party Liability, Collision, Personal Injury Protection |
| Companies Covered | State Farm Mutual Automobile Insurance Company, Allstate Insurance Company, Progressive Casualty Insurance Company, Liberty Mutual Insurance, AXA, Allianz, Nationwide, MAPFRE, Farmers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Usage-Based Insurance for Automotive Market Strategic Shifts & Innovations
Telematics infrastructure is fragmenting into modular component layers, enabling insurers to unbundle hardware procurement from data analytics and algorithmic pricing engines.
Edge computing architectures are decomposing centralized cloud dependency for real-time risk scoring. Progressive carriers deploy in-vehicle inference chips that process driving behavior locally, transmitting only aggregated risk tiers rather than raw sensor streams. This compression of data gravity reduces latency for usage-based premium adjustments while lowering cellular transmission costs.
The EU AI Act imposes explainability requirements on automated underwriting decisions that affect premium pricing or coverage denial. Insurers must now document algorithmic logic trails and provide human-review pathways for contested scores. European fleet programs face the steepest compliance burden as commercial policies involve higher claim values and stricter fiduciary scrutiny.
Fleet procurement teams now demand unbundled telematics service contracts separate from insurance binding. Large logistics operators in the United States negotiate direct relationships with hardware providers and data platforms, treating insurance as a commodity overlay on self-owned risk infrastructure. This disintermediation compresses carrier margins while elevating platform vendors to primary supplier status.
Usage-Based Insurance for Automotive Market Segmentation
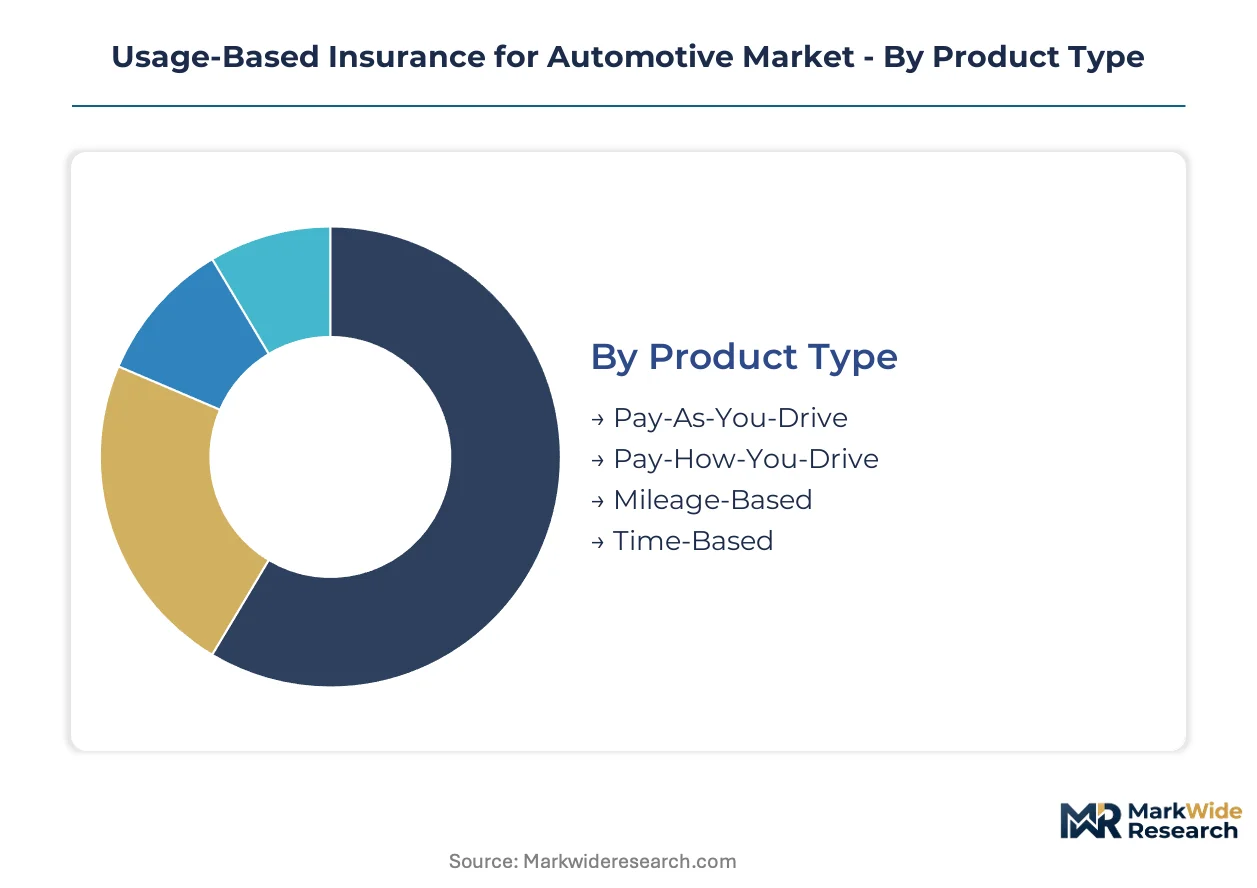
Usage-Based Insurance for Automotive segments reveal divergent growth vectors across behavioral data sophistication and customer risk profiles. Product architecture choices directly determine hardware requirements, data pipeline complexity, and regulatory exposure across jurisdictions.
Product Type:
Domestic markets favor mileage-verification models with minimal hardware friction, while export-oriented programs in Germany and the Netherlands emphasize granular behavioral scoring for fleet accountability.
- Pay-As-You-Drive:Pure mileage verification through odometer readings or GPS distance tracking. Demand concentrates in United States urban commuter corridors where low-mileage households seek proportional premium relief from annual fixed-rate structures.
- Pay-How-You-Drive:Multi-dimensional behavioral scoring incorporating acceleration patterns, braking intensity, and cornering forces. European fleet operators in Germany and the Netherlands mandate this tier for commercial auto coverage, expanding addressable policy volumes through driver accountability frameworks.
- Mileage-Based:Simplified distance-only models with monthly or per-mile billing cycles. United States direct-to-consumer channels favor this architecture for rapid onboarding without hardware installation delays.
- Time-Based:Coverage activation tied to specific driving windows or seasonal usage patterns. Northern European markets with pronounced winter driving risk differentials show emerging appetite for this flexibility.
Pay-As-You-Drive holds the largest share; momentum sits with Pay-How-You-Drive.
Technology:
Hardware-dependent architectures carry higher upfront capital requirements but yield richer data streams, while software-only deployments accelerate customer acquisition at the cost of fidelity degradation.
- Telematics:Dedicated black-box devices capturing accelerometer, gyroscope, and GPS data with forensic-grade timestamp precision. Taiwan and South Korea supply chain concentration creates procurement vulnerability for carriers scaling hardware-dependent programs.
- GPS Tracking:Location-centric modules prioritizing route verification and geofencing compliance. Logistics operators in United States long-haul corridors deploy this layer for cargo security integration alongside insurance functions.
- Mobile Applications:Smartphone sensor harvesting with algorithmic trip reconstruction. Allstate Insurance Company anchors market position through proprietary mobile architecture that reduces hardware dependency and eliminates installation friction.
- On-Board Diagnostics:OBD-II port interfaces extracting engine performance metrics and diagnostic trouble codes. United States vehicle fleet standardization since 1996 enables universal plug-and-play deployment across domestic passenger vehicles.
Telematics commands premium pricing power; mobile applications are climbing the fastest.
Customer Type:
Commercial procurement patterns diverge sharply from individual consumer acquisition, with fleet managers demanding unbundled data ownership and direct hardware relationships.
- Individual Drivers:Private vehicle owners seeking premium reduction through behavioral transparency. United States direct-to-consumer marketing channels concentrate acquisition spend on this segment through smartphone-first onboarding.
- Fleet Operators:Commercial vehicle managers with centralized risk oversight requirements. Large United States logistics operators now negotiate direct telematics platform relationships, treating insurance as commodity overlay on self-owned risk infrastructure.
- Car Sharing Services:Short-term rental platforms requiring per-trip coverage activation. Urban mobility hubs in United States metropolitan corridors drive integration demand with automated fleet management systems.
- Ride-Hailing Services:App-based transportation networks with driver-participant coverage gaps. Platform liability frameworks in multiple United States jurisdictions mandate supplemental coverage layers beyond personal auto policies.
Fleet Operators hold the largest share; momentum sits with Car Sharing Services.
Coverage Type:
Regulatory mandates shape baseline coverage requirements, while optional protection layers create margin expansion opportunities through risk-pool segmentation.
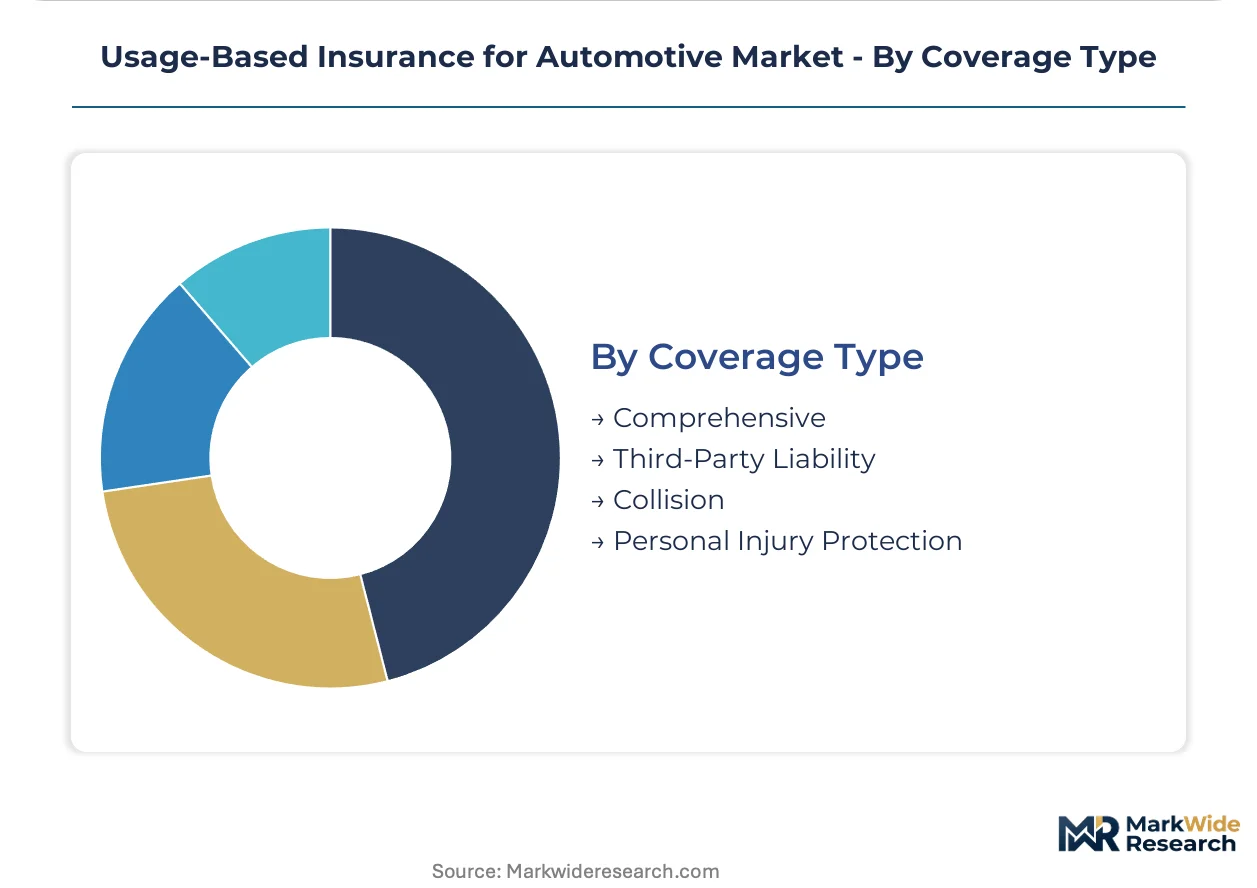
- Comprehensive:All-peril protection encompassing theft, vandalism, and weather damage. European markets under EU AI Act algorithmic accountability requirements face steepest compliance burden for automated underwriting of high-value comprehensive policies.
- Third-Party Liability:Mandatory minimum coverage for bodily injury and property damage to others. Germany and Netherlands fleet telematics mandates now require driver behavior monitoring as condition of commercial third-party coverage.
- Collision:Physical damage protection for policyholder vehicles regardless of fault. United States state-level insurance commissioner mandates for data transparency create patchwork approval requirements for telematics-based collision rating factors.
- Personal Injury Protection:No-fault medical expense and lost wage coverage. United States no-fault jurisdictions concentrate demand for this layer with telematics integration enabling fraud detection through trip verification.
Third-Party Liability holds the largest share; momentum sits with Comprehensive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German telematics infrastructure exports drive fleet adoption across the Netherlands and Scandinavian corridors, while United States carriers refine behavioral pricing models for domestic deployment.
United States
Progressive Casualty Insurance Company and State Farm have built mature telematics infrastructures that sustain consumer trust in behavioral pricing. NHTSA guidelines on vehicle connectivity standards intersect with state-level insurance commissioner mandates for data transparency. California and Texas concentrate program deployment where direct-to-consumer channels prioritize smartphone-first onboarding.
Germany
Logistics operators now mandate driver behavior monitoring for commercial auto coverage, expanding addressable policy volumes. The EU AI Act imposes algorithmic accountability requirements on automated underwriting decisions. Munich and Stuttgart anchor fleet telematics procurement as commercial vehicle managers seek granular risk visibility.
Netherlands
Fleet telematics mandates require driver accountability tools and fuel efficiency monitoring through integrated dashboards. GDPR compliance requirements reshape how insurers process telematics data across European markets. Rotterdam logistics corridors drive cross-border policy standardization with German fleet operators.
India
The country's central bank and insurance regulator mandate linked vehicle data for commercial fleet coverage in metropolitan corridors. National digitization pushes accelerate smartphone-based policy acquisition without hardware installation friction. Maharashtra and Karnataka concentrate telematics platform deployment where logistics companies seek driver accountability frameworks.
United Kingdom
Insurtech specialists compete with incumbent carriers on mobile-native policy architectures that reduce hardware dependency. GDPR restricts cross-border telematics data flows to cloud infrastructure outside the European Economic Area. London anchors algorithmic underwriting development while regional fleet operators demand unbundled data ownership.
Usage-Based Insurance for Automotive Market Key Industry Players
Listed leaders compete with private specialists across pricing model sophistication and telematics infrastructure ownership. The competitive structure bifurcates between precision insurers with proprietary data pipelines and legacy carriers retrofitting mainframe systems for streaming ingestion. Three archetypes dominate: behavioral pricing pioneers, mobile-native challengers, and fleet-focused platform vendors. M&A activity concentrates on data analytics capabilities while strategic partnerships target OEM embedded insurance integration.
Within the behavioral pricing tier, Progressive Casualty Insurance Company and State Farm Mutual Automobile Insurance Company exemplify infrastructure-heavy market positions. Allstate Insurance Company represents the mobile-native vector through proprietary application architecture that reduces hardware dependency. These three carriers anchor distinct competitive approaches to telematics data fidelity and customer acquisition economics.
| Leading Market Players |
|---|
| State Farm Mutual Automobile Insurance Company |
| Allstate Insurance Company |
| Progressive Casualty Insurance Company |
| Liberty Mutual Insurance |
| AXA |
| Allianz |
| Nationwide |
| MAPFRE |
| Farmers |
| Others |
Cost & Logistics Intelligence
Smartphone sensor harvesting replacing dedicated black-box hardware is redrawing procurement geography from Taiwan-South Korea manufacturing clusters toward software development centers in India and Eastern Europe, collapsing upfront hardware costs while shifting value capture toward algorithmic licensing fees.
Pricing Analysis
Current-generation telematics black-box programs command premium subscription rates against prior-generation GPS-only mileage verification and next-generation edge-computing inference chip architectures. Three-tier pricing structure across premium behavioral-scoring, standard mileage-based, and economy time-limited coverage levels reflects data fidelity gradients. Pricing pressure stems from fleet operators demanding unbundled data ownership that strips carrier margin from integrated hardware-software bundles. Individual drivers exhibit highest price sensitivity, while commercial fleet managers prioritize risk visibility over per-policy cost.
Supply Chain Analysis
Inbound logistics costs through the Taiwan Strait and Busan port corridors expose hardware-dependent carriers to container availability volatility on Asia-North America trade lanes. Automotive-grade accelerometer and gyroscope production clusters in Taiwan, South Korea, and Japan create concentrated single-source vulnerability for black-box procurement. Raw material dependencies span silicon wafers, rare-earth magnets, and lithium-ion power cells. Distribution runs through OEM embedded partnerships, direct-to-consumer cellular provisioning, and fleet management platform integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics infrastructure unbundling fragments value chains across hardware vendors, data platforms, and insurance overlays, creating entry niches for specialists serving fleet operators seeking direct data ownership.
For Market Incumbents: Fortify algorithmic underwriting capabilities against mobile-native challengers harvesting smartphone sensor data without hardware installation friction. Invest in proprietary edge-computing inference architectures that reduce cloud dependency and cellular transmission costs. Prioritize certification investment for EU AI Act algorithmic accountability compliance in European fleet programs. For New Entrants and Emerging Players: Lead with smartphone-first onboarding architectures targeting United States individual driver segments where hardware installation delays suppress conversion rates. Penetrate India's digitized motor insurance corridors through regulatory-aligned telematics platforms for commercial fleet coverage. Pursue embedded insurance partnerships with OEM factory-integrated telematics modules at point-of-sale. For Investors and Strategic Acquirers: Capital is best deployed toward data analytics specialists with validated machine learning models satisfying EU AI Act explainability requirements and internal model risk governance. Long-term viability hinges on algorithmic differentiation rather than hardware procurement scale. Monitor fleet operator procurement patterns shifting toward direct telematics platform relationships as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Embedded Insurance Partnership | Factory-integrated telematics modules capture lifetime policy value before first registration. |
| Edge Computing Architecture Deployment | In-vehicle inference chips reduce latency and cellular costs for real-time premium adjustment. |
| EU AI Act Compliance Certification | Algorithmic accountability documentation satisfies automated underwriting decision requirements. |
| Fleet Telematics Platform Acquisition | Direct data ownership relationships disintermediate traditional carrier-insured intermediation. |
| Carbon-Intensity Scoring Integration | Emissions-linked driving behavior creates dual-revenue streams from ESG-conscious fleet managers. |
Research Approach
The analysis maps Pay-As-You-Drive, Pay-How-You-Drive, and embedded insurance sub-sectors, each validated through underwriting executives, fleet procurement managers, telematics platform engineers, and regulatory affairs specialists at national insurance commissioners. Primary fieldwork combined with secondary validation against NHTSA vehicle connectivity guidelines, EU AI Act implementation documents, GDPR regulatory guidance, and state-level insurance commissioner filings. Bottom-up policy volume modeling and top-down premium pool estimation triangulate market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across behavioral pricing sophistication tiers, hardware-software deployment models, and customer type segmentation. The analytical framework models propulsion architecture, vehicle class, content per vehicle, OEM tier relationships, and regional regulatory clusters throughout the forecast period. CAGRs derive from telematics adoption curve modeling and fleet operator procurement velocity inputs without year-specific assumptions.
The analysis sits within stated boundaries; outcomes outside sustained 5G-V2X infrastructure deployment, stable EU-U.S. data transfer mechanisms, and continued silicon sensor supply availability would require recalibration. Forecasts reflect assumptions about regulatory clarity for algorithmic underwriting and fleet operator willingness to adopt behavioral monitoring frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Business Insurance Market
Insurance
Specialty Insurance Market
Insurance
Japan Bancassurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
Asia-Pacific Surety Market
Insurance
Digital Innovation in Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
US Travel Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Insurance Claims Services Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Global AI in Auto-Insurance Market