
 Convergent Billing Market | 2026-2036
Convergent Billing Market Size, Share, and Industry Trends Forecast 2026-2036
Convergent Billing Market Intelligence
The EU Digital Markets Act is pivoting how communications service providers architect their monetization stacks, forcing decoupling of billing from core network layers. Amdocs leverages its managed services footprint to sustain multi-tenant cloud deployments across European Tier-1 operators. Oracle Corporation anchors enterprise-grade convergent charging through its acquired policy control assets. Huawei Technologies competes on 5G slice-based billing orchestration in markets outside North America.
Convergent billing denotes a unified charging and invoicing framework that consolidates multiple service lines—voice, data, content, IoT—into a single customer account and bill cycle, operating on real-time rating engines that process event records within milliseconds to enable balance updates and policy enforcement. Its primary commercial purpose is to eliminate revenue leakage from fragmented product silos while supporting dynamic pricing models across prepaid, postpaid, and usage-based contracts. Cloud-based deployment now leads solution type adoption as carriers seek elastic capacity for traffic spikes without stranded capital in on-premises hardware. Subscription management represents the fastest-expanding solution segment, driven by bundled OTT and enterprise SaaS provisioning where margin pools concentrate in recurring revenue assurance and partner settlement workflows.
GDPR and the EU AI Act shape how billing platforms handle subscriber data profiling and automated credit-scoring algorithms, compelling vendors to embed privacy-by-design into rating engines. The Federal Communications Commission in the United States enforces truth-in-billing rules that mandate clear line-item disclosure across bundled services, directly influencing invoice presentation layer requirements. Stakeholders must monitor how open API mandates under the EU Interoperability Framework reshape vendor lock-in dynamics and procurement evaluation criteria for next-generation billing transformations.
Market Dynamics
Cloud-native billing architectures are compressing deployment timelines from 18-month waterfall implementations to 8-week agile sprints, forcing legacy vendors to restructure professional services margins around API consumption models rather than perpetual license fees.
Growth Catalysts
- GDPR Article 30 compliance mandates:German CSPs must maintain granular audit trails of subscriber data processing, driving replacement of opaque mainframe billing stacks with transparent event-streaming platforms that expose data lineage APIs to regulators.
- 5G network slicing monetization:Telecommunications providers in South Korea and Japan are deploying slice-aware charging functions that correlate quality-of-service tiers with real-time usage metering, unlocking enterprise verticals from connected manufacturing to remote surgery.
- IoT device proliferation:Connected vehicle fleets and smart utility meters generate billions of micro-transactions monthly, requiring rating engines capable of sub-second event processing without batch latency that previously obscured revenue recognition.
Market Restraints
- Data residency infrastructure costs:EU Digital Markets Act data localization requirements force operators to maintain sovereign cloud instances in each member state, duplicating compute capacity that hyperscale architectures otherwise consolidate.
- Mainframe skill scarcity:COBOL and Assembler expertise required to maintain 1990s-era billing platforms commands premium labor rates exceeding 300% of contemporary full-stack developer compensation, constraining migration velocity.
- Interoperability standard fragmentation:TM Forum Open APIs compete with proprietary vendor middleware layers, creating integration tax for operators seeking best-of-breed component assembly rather than single-stack lock-in.
Strategic Opportunities
- Embedded finance convergence:Billing platforms integrating with licensed payment institutions can offer subscriber micro-lending and wallet services, capturing interchange revenue streams adjacent to core connectivity margins.
- Carbon-aware rating engines:EU Green Deal disclosure requirements create demand for billing systems that surface Scope 3 emissions per service consumption unit, enabling enterprise customers to meet CSRD supply chain reporting obligations.
- API marketplace monetization:Exposing charging and policy functions as developer-consumable microservices allows CSPs to revenue-share with third-party SaaS providers embedding telecom capabilities without direct carrier integration.
Industry Challenges
- Real-time tax engine complexity:India's GST council and Brazil's ICMS regime require jurisdiction-aware rating modifications within 48 hours of regulatory change, straining DevOps pipelines architected for quarterly release cycles.
- Hybrid cloud orchestration:Operators maintaining sensitive subscriber data on-premises while bursting compute-intensive mediation workloads to public cloud must engineer zero-trust segmentation that satisfies both internal risk committees and external audit firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Convergent Billing Market |
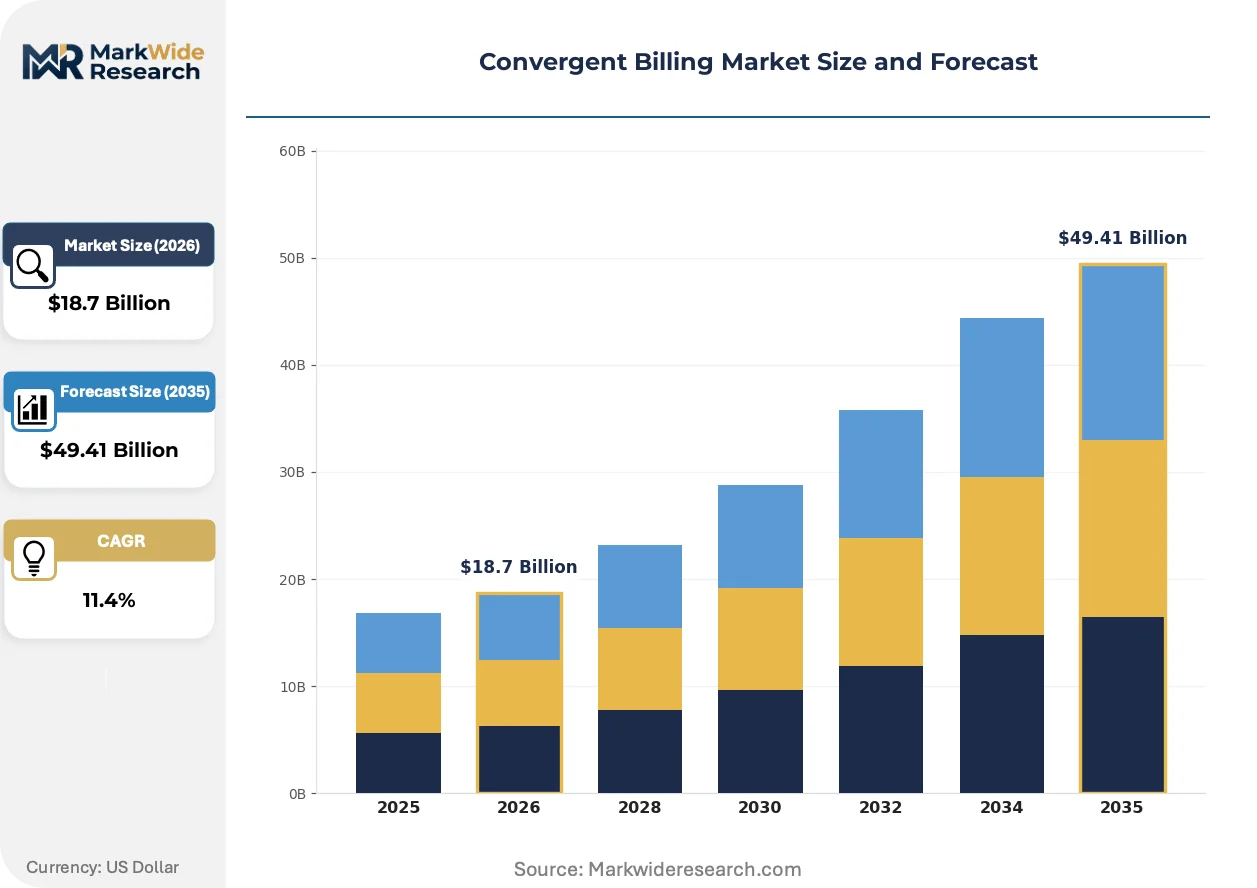
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Real-Time Billing, Postpaid Billing, Prepaid Billing, Usage-Based Billing, Subscription Management End User Industry: Telecommunications Providers, Media & Entertainment, Utilities, Financial Services, Education Integration Level: Payment Gateway, Customer Relationship Management, Enterprise Resource Planning, Fraud Management, Analytics Platforms |
| Companies Covered | Amdocs, CSG Systems International, Huawei Technologies, Oracle Corporation, Telefonaktiebolaget LM Ericsson, Nokia Corporation, SAP SE, Optiva Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Convergent Billing Market Strategic Shifts & Innovations
Machine learning inference at the network edge is rewriting how usage anomalies trigger policy interventions, compressing the gap between service degradation detection and automated credit issuance or upsell prompts.
Reinforcement learning-based revenue assurance is automating pattern recognition across billions of call detail records to isolate provisioning errors and fraudulent SIM cloning before monthly invoice generation locks in revenue leakage. Tier-1 operators in Germany and France are deploying these models within 50-millisecond latency envelopes that preserve real-time charging session integrity. The technology is automating forensic audit workloads previously requiring 200-person analyst teams, redirecting human capital toward commercial pricing strategy.
EU AI Act risk classification frameworks now categorize automated credit-scoring algorithms as high-risk AI systems, mandating human-in-the-loop override capabilities and algorithmic impact assessments before deployment. Billing platform vendors must engineer explainability layers that render rating decisions interpretable to non-technical auditors. Operators serving small-business segments face particular exposure, as algorithmic denial of service credit limits without documented justification triggers regulatory penalty provisions.
Enterprise procurement teams are consolidating vendor relationships from twelve-point billing ecosystems to three-platform core-and-rim architectures, privileging suppliers offering ISO 27001-certified managed services over self-hosted perpetual licenses. This concentration favors vendors with multi-tenant infrastructure investments and 24/7 security operations centers. The shift is most pronounced among European mid-market CSPs seeking to deflect GDPR liability through shared responsibility models with hyperscale infrastructure partners.
Convergent Billing Market Segmentation
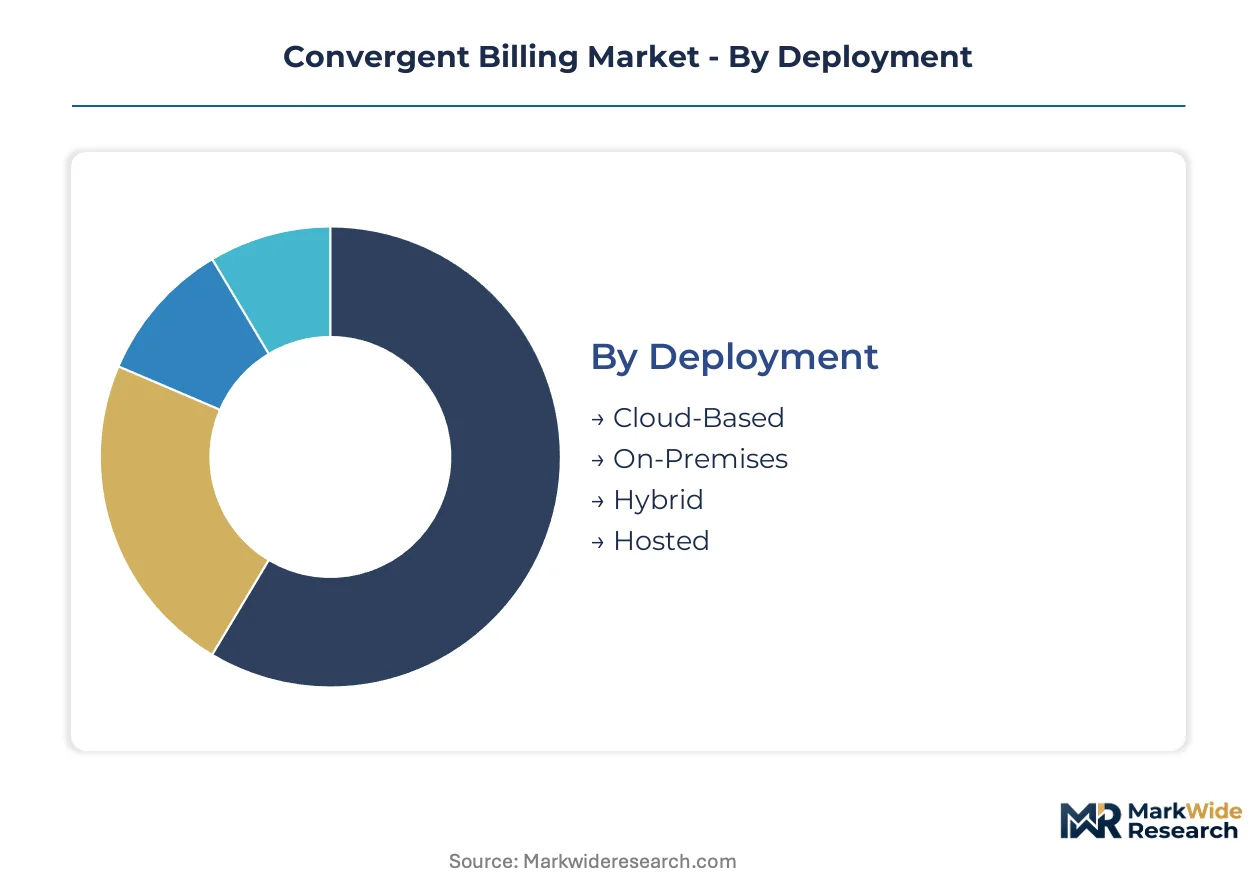
Segmentation in convergent billing reveals how capital allocation and architectural choices determine competitive positioning across deployment models, solution types, and integration depths. Vendors and operators must align infrastructure investments with specific regulatory environments and end-use monetization patterns to capture margin in this expanding market.
Deployment:
Capital-intensity varies sharply across deployment modes, with sovereign cloud instances requiring redundant compute clusters in multiple jurisdictions while on-premises deployments demand heavy upfront hardware commitments.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning eliminate stranded capacity during traffic spikes. German CSPs under GDPR Article 30 are migrating here for transparent audit trails, though EU Digital Markets Act data localization forces duplicated regional instances.
- On-Premises:Dedicated infrastructure maintains sensitive subscriber data within operator-controlled facilities. Legacy COBOL-dependent mainframe stacks persist here, constraining migration velocity due to scarce Assembler expertise commanding premium labor rates.
- Hybrid:Sensitive data resides on-premises while compute-intensive mediation bursts to public cloud. Zero-trust segmentation engineering satisfies internal risk committees and external audit firms simultaneously.
- Hosted:Third-party data center operators manage physical infrastructure while operators retain application control. This model concentrates among European mid-market CSPs seeking to deflect GDPR liability through shared responsibility frameworks.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as operators balance sovereignty requirements against elastic scaling demands.
Solution Type:
Margin pools concentrate differently across billing modalities, with subscription management capturing recurring revenue assurance workflows while real-time engines command premium pricing for sub-second latency guarantees.
- Real-Time Billing:Event-streaming platforms process usage records within milliseconds to enable balance updates and policy enforcement. South Korean and Japanese operators deploy these for 5G network slice monetization correlating quality-of-service tiers with enterprise verticals from connected manufacturing to remote surgery.
- Subscription Management:Bundled OTT and enterprise SaaS provisioning workflows concentrate margin in partner settlement and recurring revenue assurance. This segment expands most quickly as CSPs pivot from transactional to relationship-based monetization models.
- Postpaid Billing:Monthly invoice generation with usage aggregation and credit risk assessment. FCC truth-in-billing rules in the United States mandate clear line-item disclosure across bundled services, influencing presentation layer requirements.
- Prepaid Billing:Balance-decrement architectures with voucher-based or digital wallet funding mechanisms. Dominates in emerging markets with limited credit infrastructure and high churn sensitivity.
- Usage-Based Billing:Metered consumption models for IoT device fleets and utility smart meters generating billions of micro-transactions monthly. Requires rating engines capable of sub-second event processing without batch latency obscuring revenue recognition.
Revenue concentration remains highest in Real-Time Billing. Subscription Management gains share fastest as bundled service portfolios expand across telecommunications providers.
End User Industry:
Application complexity drives segmentation divergence, with telecommunications providers demanding full-stack charging orchestration while adjacent verticals seek modular API consumption.
- Telecommunications Providers:Full convergent charging spanning voice, data, content, and IoT with unified customer accounts. German Tier-1 operators under EU AI Act mandates deploy explainability layers rendering automated credit-scoring decisions interpretable to non-technical auditors.
- Media & Entertainment:Content bundling and digital rights management integration with subscriber entitlement platforms. OTT providers leverage billing APIs for global rollout without direct carrier integration.
- Utilities:Smart meter data aggregation and time-of-use pricing with regulatory tariff compliance. Connected infrastructure generates high-volume, low-margin transactions requiring efficient mediation.
- Financial Services:Embedded finance convergence enabling subscriber micro-lending and wallet services. Billing platforms integrating with licensed payment institutions capture interchange revenue adjacent to core connectivity margins.
- Education:Campus network provisioning and device management for connected learning environments. Lower transaction volumes favor standardized SaaS billing templates over customized implementations.
Deployment value concentrates in Telecommunications Providers. Financial Services demonstrates the steepest adoption trajectory as embedded finance models mature.
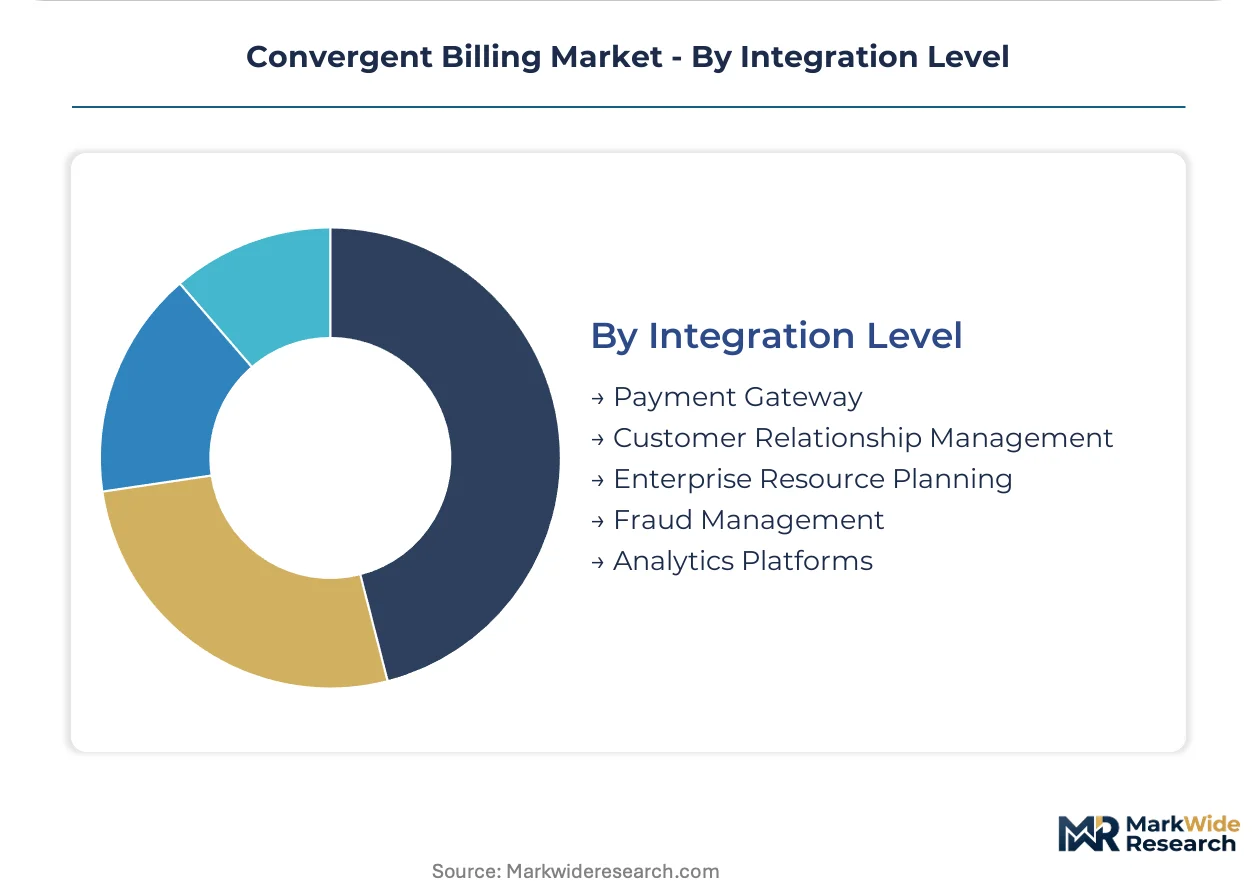
Integration Level:
System interconnection depth determines operational friction, with fraud management and analytics platforms commanding integration priority due to direct revenue protection impact.
- Payment Gateway:Licensed payment institution connectivity enabling subscriber wallet services and micro-lending. Interchange revenue streams supplement core connectivity margins for integrated operators.
- Customer Relationship Management:Unified subscriber profiles spanning sales, service, and billing touchpoints. Reduces churn through consistent experience orchestration across channels.
- Enterprise Resource Planning:Financial consolidation and procurement workflow integration for multi-service operators. Essential for accurate revenue recognition across fragmented product silos.
- Fraud Management:Real-time pattern recognition across billions of call detail records isolating provisioning errors and SIM cloning before invoice generation locks in revenue leakage. Tier-1 operators in France deploy reinforcement learning models within 50-millisecond latency envelopes.
- Analytics Platforms:Consumption pattern visualization and predictive churn modeling. Carbon-aware rating engines here surface Scope 3 emissions per service unit for EU Green Deal compliance.
Integration investment concentrates in Fraud Management. Analytics Platforms expand most quickly as CSRD supply chain reporting obligations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Convergent billing platforms first achieved commercial scale in North American telecommunications markets during the 1990s, where deregulation forced carriers to unify disparate service billing. European operators subsequently adopted these architectures to manage multi-country roaming complexity. Asian markets now deploy the most advanced real-time charging implementations for 5G network slicing.
United States
FCC truth-in-billing rules mandate granular line-item disclosure across bundled connectivity and content services. Tier-1 operators in Dallas and Atlanta are consolidating twelve-point vendor ecosystems into three-platform core-and-rim architectures. This procurement concentration privileges ISO 27001-certified managed service providers over perpetual license models.
Germany
GDPR Article 30 compliance mandates granular audit trails of subscriber data processing. CSPs in Munich and Frankfurt are replacing opaque mainframe billing stacks with transparent event-streaming platforms exposing data lineage APIs to regulators. The EU AI Act further compels explainability layers for automated credit-scoring algorithms.
South Korea
5G network slicing monetization drives demand for slice-aware charging functions correlating quality-of-service tiers with enterprise verticals. Operators in Seoul deploy real-time rating engines processing usage records within 50-millisecond latency envelopes. Connected manufacturing and remote surgery applications require sub-second event processing without batch latency.
Japan
METI industrial digitization programs accelerate IoT billing platform adoption for connected vehicle fleets and smart utility meters. Osaka-based system integrators engineer rating engines capable of handling billions of micro-transactions monthly. Carbon-aware rating engines surface Scope 3 emissions per service consumption unit for corporate sustainability reporting.
India
TRAI interconnect regulations and GST council tax engine complexity strain DevOps pipelines requiring jurisdiction-aware rating modifications within 48 hours of regulatory change. Bengaluru and Hyderabad host development centers architecting hybrid cloud orchestration for operators maintaining sensitive subscriber data on-premises while bursting compute-intensive mediation workloads to public cloud.
Convergent Billing Market Key Industry Players
Premium-margin players sit above commodity-margin players across managed service depth and multi-tenant cloud infrastructure scale. The vendor base organizes into three tiers: full-stack convergent charging specialists, component API providers, and legacy mainframe maintainers. Consolidation pressures favor suppliers with 24/7 security operations centers and sovereign cloud instances in multiple jurisdictions. Dominant competitive moves include strategic partnerships with hyperscale infrastructure providers and portfolio diversification into embedded finance convergence.
Within the full-stack convergent charging tier, Amdocs and Oracle Corporation represent established managed services anchors. Amdocs leverages multi-tenant cloud deployments across European Tier-1 operators, while Oracle Corporation anchors enterprise-grade charging through policy control assets. Huawei Technologies occupies a position in 5G slice-based billing orchestration for markets outside North America, exemplifying the component API provider archetype with network-native integration depth.
| Leading Market Players |
|---|
| Amdocs |
| CSG Systems International |
| Huawei Technologies |
| Oracle Corporation |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| SAP SE |
| Optiva Inc. |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Assembler and COBOL labor premiums cascade through legacy maintenance tiers, compressing margins on mainframe-dependent deployments while API-first architectures capture subscription-based recurring revenue streams from cloud-native operators in Germany and South Korea.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by managed service depth and multi-tenant infrastructure scale. Price differentiation hinges on ISO 27001 certification status and sovereign cloud instance availability across EU member states. Cost compression in standard tiers intensifies as hyperscale infrastructure partners absorb capital expenditure burdens. Enterprise telecommunications providers demonstrate lowest price sensitivity, while European mid-market CSPs prioritize shared responsibility models that deflect GDPR liability.
Supply Chain Analysis
Direct-to-CSP channels handle Tier-1 operator demand, while systems integrators and channel partners serve mid-market deployments. Supply concentrates in Germany, the United States, and India for core platform development, with delivery anchored in regional sovereign cloud instances. Raw material dependencies center on specialized semiconductor components for edge inference, proprietary database licenses, and scarce mainframe expertise. Single-source vulnerability in legacy COBOL talent pools constrains migration velocity. Distribution runs through managed service providers with 24/7 security operations centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German GDPR compliance costs exceed Indian development center economics by multiples sufficient to justify hybrid cloud orchestration investments.
For Market Incumbents: Anchor multi-tenant infrastructure investments in sovereign cloud instances across EU member states to preempt Digital Markets Act localization mandates. Defend against API-first entrants by embedding explainability layers for EU AI Act high-risk algorithm classification. Prioritize certification maintenance for ISO 27001 and regional data residency standards.
For New Entrants and Emerging Players: Edge-native machine learning inference for real-time revenue assurance offers entry into 5G slice-based billing orchestration. White-space concentrates in carbon-aware rating engines for EU Green Deal CSRD compliance and embedded finance convergence with licensed payment institutions. Go-to-market through developer-consumable API marketplaces bypasses direct carrier procurement cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where mainframe skill scarcity commands premium labor rates exceeding contemporary full-stack compensation. Long-term viability favors vendors with backward integration into policy control assets and managed services depth. Acquisition targets include component API providers with TM Forum Open API certification. The signal to watch is TRAI or GST council regulatory velocity straining quarterly release architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Expansion | EU Digital Markets Act data localization forces redundant compute clusters in each member state. |
| API Marketplace Monetization | Exposing charging functions as microservices enables revenue-sharing with third-party SaaS providers. |
| Embedded Finance Convergence | Integration with licensed payment institutions captures interchange revenue adjacent to connectivity margins. |
| Carbon-Aware Rating Engine Development | EU Green Deal disclosure requirements surface Scope 3 emissions per service consumption unit. |
| Reinforcement Learning Revenue Assurance | Pattern recognition across billions of call detail records isolates provisioning errors before invoice generation. |
Research Approach
Multiple input streams — primary interviews with CSP billing architects, regulatory compliance officers, and systems integration leads, alongside secondary validation from TM Forum Open API documentation, FCC truth-in-billing enforcement records, and EDPB GDPR Article 30 guidance — were reconciled through bottom-up and top-down triangulation. SEC filings from publicly traded vendors and hyperscaler capex disclosures provided infrastructure investment benchmarks.
Data-stream reconciliation across deployment models, solution types, and integration levels generated volume and value outputs throughout the forecast period. Segmentation dimensions modeled include cloud-native versus legacy architectures, real-time versus batch processing latency tiers, and regional regulatory framework clusters. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure replacement cycle analysis. Industry-specific forecast inputs incorporated 5G network slicing deployment timelines and IoT device transaction volume projections.
The model holds under stable regulatory enforcement intensity; deviation in EU AI Act implementation velocity or TRAI interconnect modification frequency would shift vendor competitive positioning. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
Spain Mobile Payment Market
Payments
Brazil Real Time Payments Market
Payments
Payment Card Market
Payments
Global Smart Payment Systems Market
Payments
Mobile Point of Sale (POS) Market
Payments
Credit Card Payments Market
Payments
Europe Payment Gateways Market
Payments
Electronic Payment System for Transportation Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Canada Buy Now Pay Later Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Global Wearable Payment Device Market
Payments
Norway Payments Market
Payments
Outdoor Payment Terminal Market