
 France POS Terminal Market | 2026-2036
France POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
France POS Terminal Market Foresight
Aftermarket service revenue is fragmenting across hardware maintenance, software subscription tiers, and payment processing add-ons. Ingenico Group (Worldline) leverages its embedded base of legacy terminals to sustain recurring revenue streams. Verifone competes through cloud-native platform architectures that reduce field-service dependency. SumUp Limited anchors the micro-merchant segment with simplified onboarding and flat-rate pricing structures.
A point-of-sale terminal is an electronic device combining secure payment card reading, PIN entry, and transaction authorization within a hardened hardware enclosure certified to PCI PTS standards, designed to capture retail payment data and route it through acquiring networks. Fixed terminals retain dominant installed-base share across French hypermarkets and grocery chains, while mobile and smart terminal categories capture incremental growth from pop-up retail and delivery-centric hospitality workflows. Android-based operating systems displace proprietary platforms as application marketplaces become a margin pool for independent software vendors.
CNIL data-protection audits and PSD2 strong-customer-authentication rules from the European Banking Authority shape terminal encryption requirements and biometric integration roadmaps. French merchant acquirers must certify devices against CB Groupe standards, creating a compliance gate that favors established vendors with testing relationships. Stakeholders should monitor how the EU AI Act intersects with fraud-detection algorithms embedded in next-generation terminals.
Market Dynamics
Android-based operating systems are dismantling proprietary terminal platforms across France, compressing hardware margins while opening software revenue pools for independent vendors and merchant acquirers.
Growth Catalysts
- PSD2 Strong Customer Authentication:The European Banking Authority's mandate for biometric verification and dynamic cryptogram generation forces terminal refresh cycles across French retail networks.
- Quick-Service Restaurant Digitalization:French QSR chains deploy contactless-enabled terminals to reduce transaction friction during peak service windows.
- Paris-Ile-de-France Merchant Density:Concentrated small-business formation in the capital corridor sustains terminal deployment velocity unmatched by other French regions.
Market Restraints
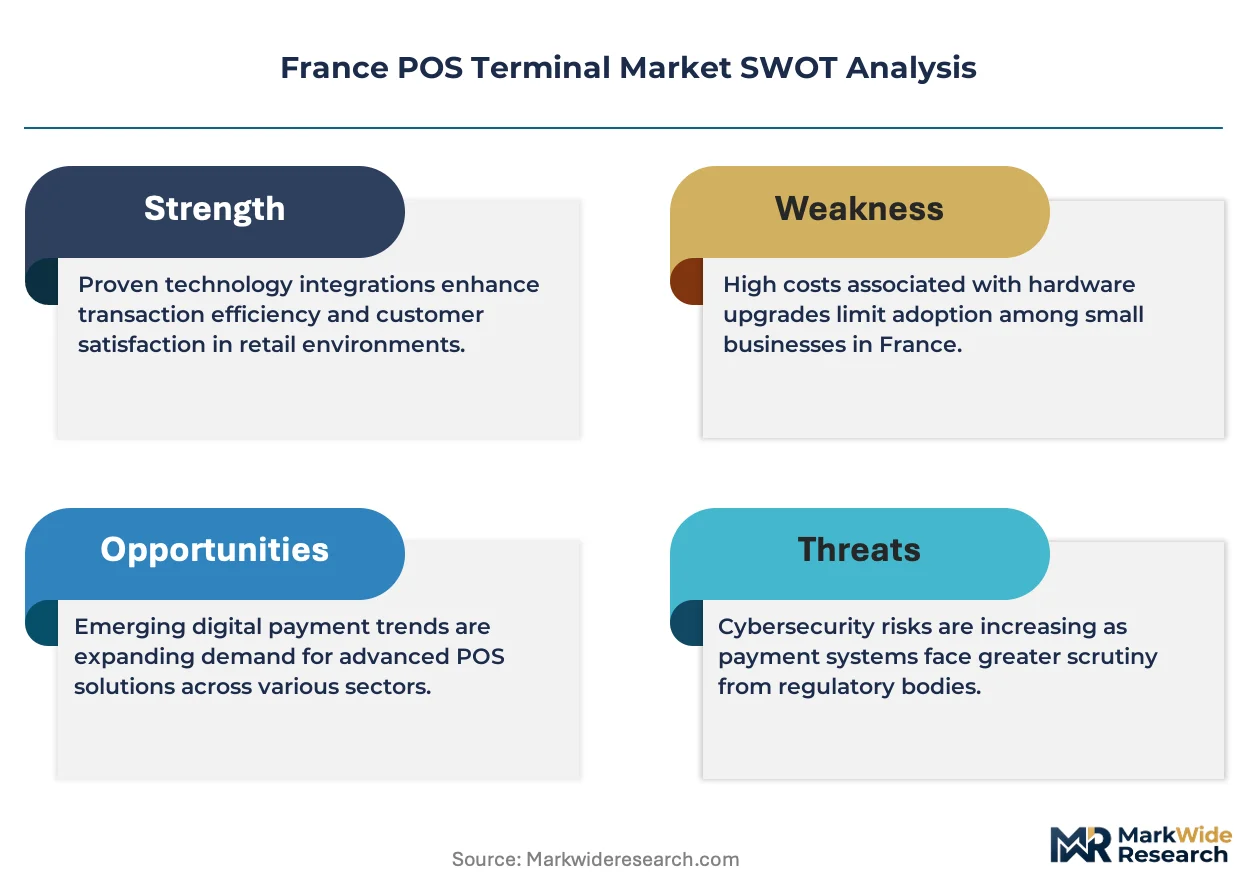
- CNIL Data-Protection Compliance Costs:Encryption audits and biometric data handling certifications impose recurring certification burdens on terminal vendors.
- CB Groupe Certification Gate:French acquirer certification requirements favor established testing relationships, restricting new hardware entrants.
- Semiconductor Supply Concentration:Secure element and NFC controller sourcing depends on concentrated Asian foundry capacity, exposing lead-time volatility.
Strategic Opportunities
- Pop-Up Retail and Delivery Hospitality:Mobile and smart terminal categories capture incremental demand from temporary retail formats and ghost kitchen operations.
- EU AI Act Fraud-Detection Integration:Next-generation terminals embedding machine-learning transaction scoring gain regulatory tailwind for biometric-authentication roadmaps.
- Software Subscription Unbundling:Application marketplaces on Android terminals create recurring revenue streams independent of hardware shipment cycles.
Industry Challenges
- Legacy Terminal Integration Complexity:Merchant acquirers face friction migrating proprietary-protocol estates to open-platform architectures without service disruption.
- PCI PTS Certification Timelines:Hardware security standard recertification cycles delay product launches and compress development windows.
- Embedded-Base Service Talent Scarcity:Field technicians skilled in both legacy Ingenico estates and cloud-native Verifone platforms command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France POS Terminal Market |
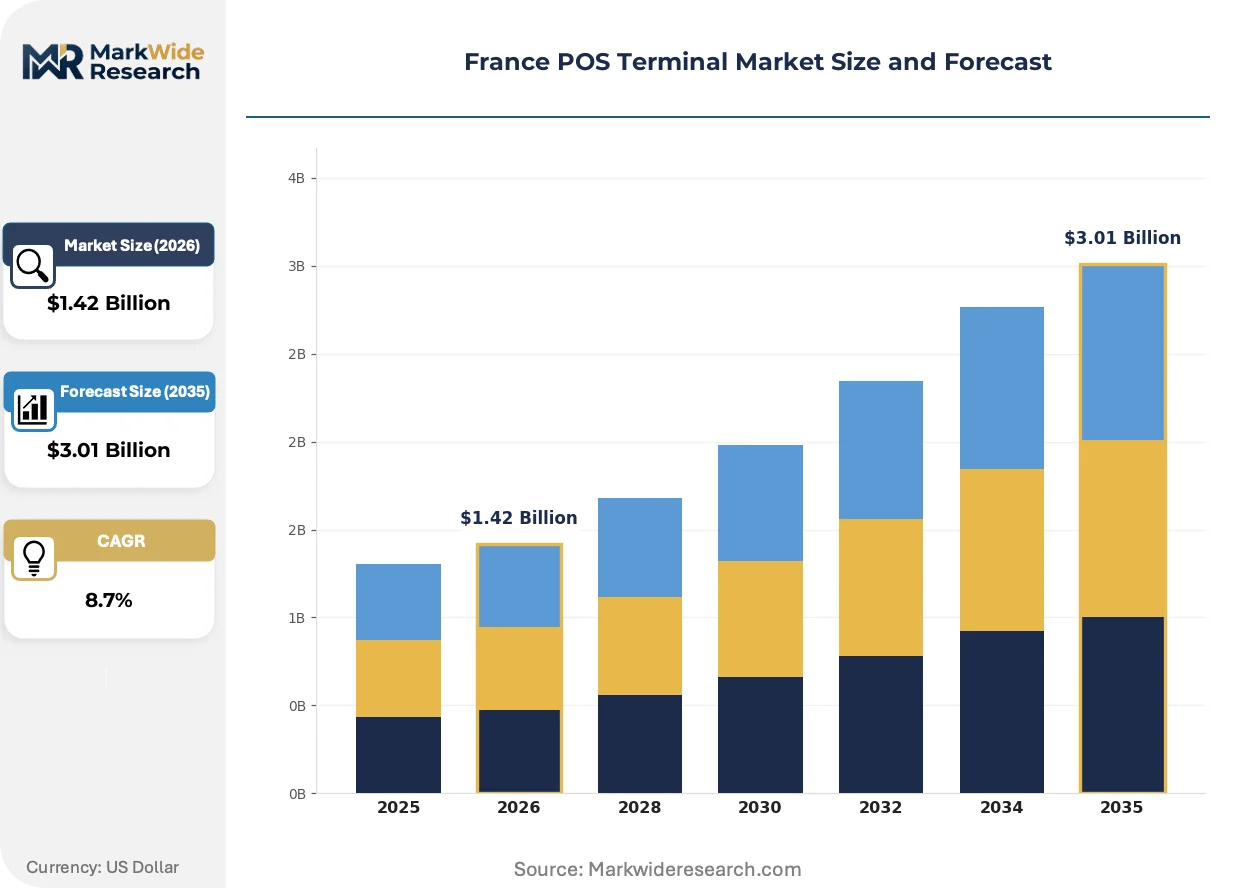
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connectivity: Wired, Wireless, Bluetooth, NFC End User: Retailers, Restaurants, Hospitality, E-commerce Terminal Type: Fixed, Mobile, Smart, Self-service Operating System: Android, iOS, Windows, Linux |
| Companies Covered | SumUp Limited, Diebold Nixdorf, Ingenico Group (Worldline), AURES Group, NEC Corporation, PAX Technology, Verifone, myPOS World Ltd, Zettle (PayPal), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France POS Terminal Market Shifts & Advancements
Payment terminal architecture is converging with general-purpose computing platforms, dissolving the boundary between payment hardware and retail software ecosystems.
SoftPOS technology is migrating from pilot deployments to mainstream merchant adoption. French micro-merchants and sole proprietors deploy smartphone-based card acceptance without dedicated hardware investment. This shift compresses addressable hardware volumes in the sub-500-euro terminal segment while expanding software-licensing addressable market.
CNIL enforcement of GDPR-aligned biometric data governance intersects with PSD2 authentication mandates. Terminal vendors must engineer fingerprint and facial-recognition modules that satisfy both privacy and security frameworks. The French retail banking channel faces the steepest compliance burden as it processes the highest volume of authenticated card-not-present transactions.
Merchant purchasing patterns are fragmenting across hardware-as-a-service, flat-rate processing bundles, and unbundled software subscriptions. French independent retailers increasingly reject multi-year terminal leases in favor of month-to-month SaaS arrangements. This behavioral shift concentrates in the Provence-Alpes-Côte d'Azur region where seasonal tourism businesses demand payment infrastructure flexibility.
France POS Terminal Market Segmentation
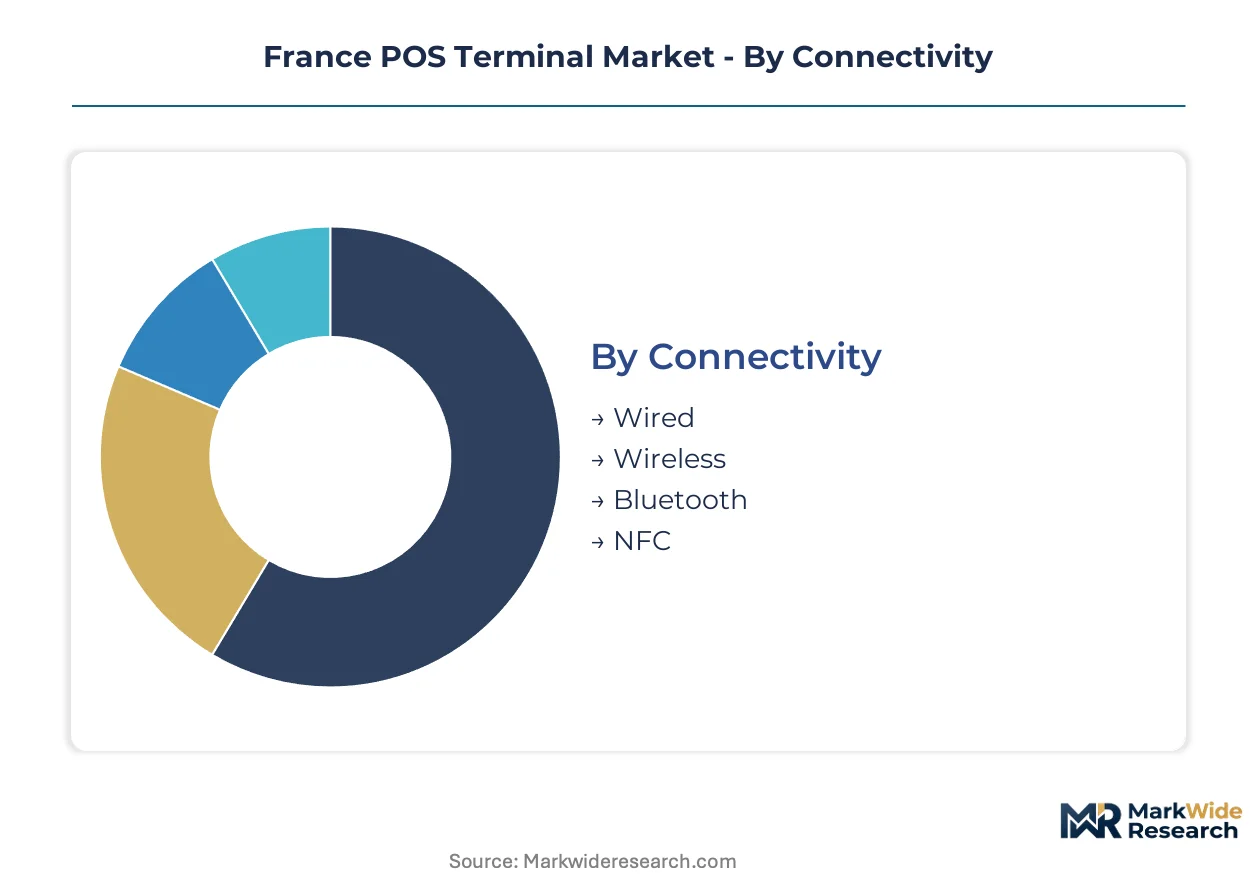
Terminal segmentation in France reflects divergent merchant workflows across fixed retail footprints, mobile service environments, and software ecosystem preferences. Understanding these dimensional splits clarifies where hardware refresh cycles concentrate versus where software licensing models displace capital expenditure.
Connectivity:
Connection modality determines terminal deployment flexibility and transaction authorization latency across French merchant tiers.
- Wired:Ethernet-connected terminals deliver uninterrupted connectivity for high-volume hypermarket checkout lanes. French grocery chains in the Paris-Ile-de-France corridor standardize on wired infrastructure to eliminate wireless interference during peak transaction windows.
- Wireless:Cellular-enabled terminals support merchant mobility without local network dependency. Provence-Alpes-Côte d'Azur seasonal vendors deploy wireless units to accommodate outdoor market setups and festival retail configurations.
- Bluetooth:Short-range pairing enables peripheral integration for tablet-based checkout systems. French boutique retailers combine Bluetooth terminals with consumer-grade tablets to reduce hardware capital outlay.
- NFC:Contactless proximity communication supports tap-to-pay transaction volumes mandated by PSD2 strong customer authentication requirements. Quick-service restaurants across Lyon and Marseille prioritize NFC-enabled terminals to minimize queue abandonment.
Wired connectivity holds installed capacity. Wireless is rotating up the share rankings.
End User:
Merchant sector dictates terminal feature requirements from inventory integration to tip-adjustment workflows.
- Retailers:Department stores and specialty merchants demand barcode scanning integration and loyalty program connectivity. French fashion retailers in Paris deploy terminals with embedded customer relationship management hooks to unify payment and preference data.
- Restaurants:Table-service and quick-service operators require split-check functionality and kitchen display system integration. French bistro chains prioritize terminals with offline transaction buffering to sustain service during network interruptions.
- Hospitality:Hotels and accommodation providers need property management system interoperability and multi-currency settlement. Alpine resort properties in the Auvergne-Rhône-Alpes region specify terminals with dynamic currency conversion for international guest billing.
- E-commerce:Online merchants utilize virtual terminal interfaces and secure payment gateway integration rather than physical hardware. French marketplace sellers leverage browser-based terminal emulations to process card-not-present transactions without dedicated devices.
Retailers hold installed capacity. Restaurants are rotating up the share rankings.
Terminal Type:
Physical form factor selection balances counter space constraints against staff mobility requirements.
- Fixed:Countertop-mounted units with tethered power and network connections serve permanent checkout positions. French supermarket operators standardize on fixed terminals with integrated receipt printers to minimize peripheral footprint.
- Mobile:Battery-powered handheld devices enable pay-at-table and curbside transaction capture. Parisian food delivery platforms equip drivers with mobile terminals to complete transactions at customer doorsteps.
- Smart:Application-capable terminals supporting third-party software installation replace proprietary closed systems. French pharmacy chains deploy smart terminals to integrate prescription management with payment acceptance on unified hardware.
- Self-service:Unattended kiosks with integrated card readers serve fuel stations and ticketing environments. SNCF railway stations across France install self-service terminals to reduce staffed ticket counter dependency.
Fixed terminals hold installed capacity. Smart terminals are rotating up the share rankings.
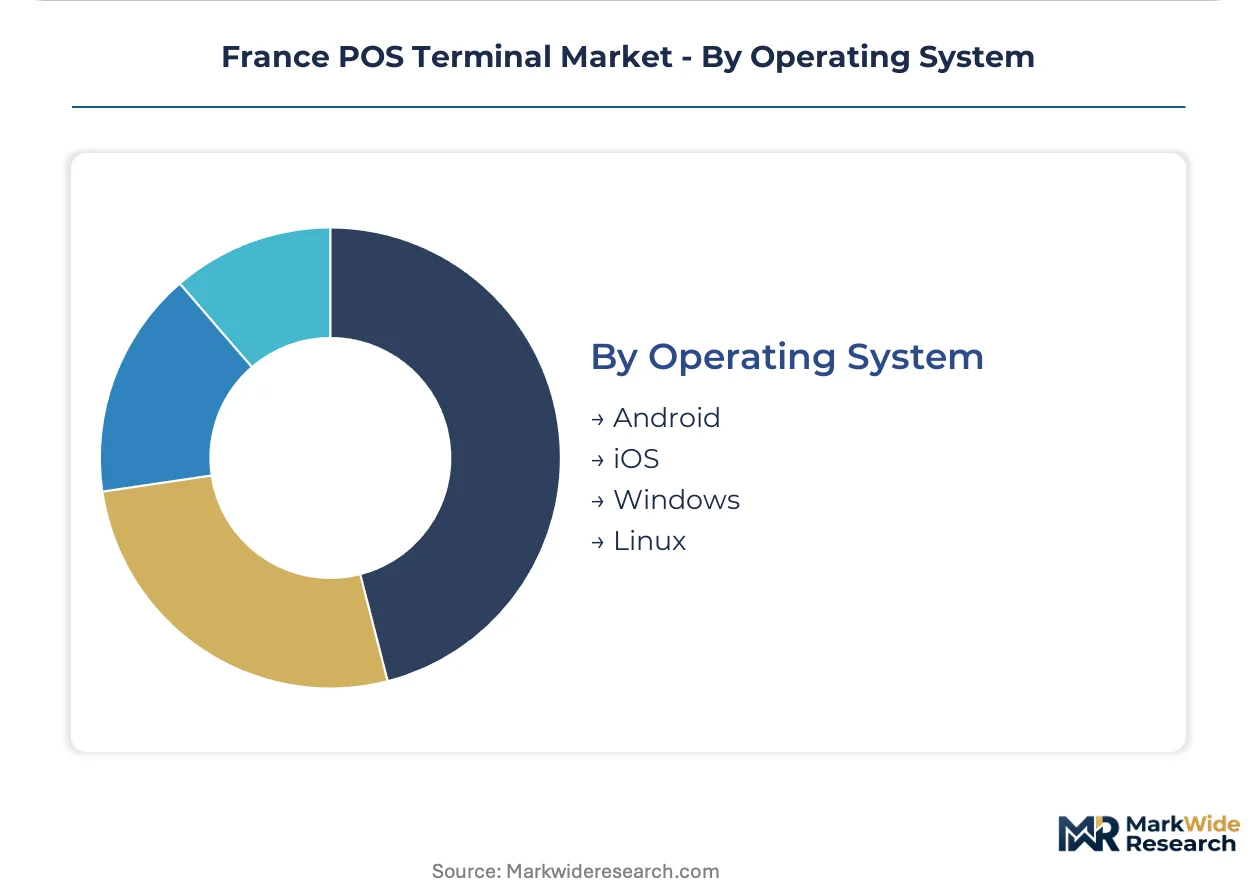
Operating System:
Software platform selection determines application ecosystem access and vendor lock-in exposure.
- Android:Open-source mobile operating system enables independent software vendor marketplace distribution. French merchant acquirers favor Android terminals to unbundle hardware from proprietary payment application constraints.
- iOS:Apple's mobile platform supports SoftPOS deployments on consumer iPhones with card reader peripherals. French micro-merchants leverage iOS-based acceptance to avoid dedicated terminal procurement entirely.
- Windows:Legacy embedded operating system persists in enterprise retail environments with custom application dependencies. French department store chains maintain Windows terminal estates to preserve existing software investments.
- Linux:Customizable open-source kernel supports hardened security configurations for specialized payment environments. French banking infrastructure providers specify Linux-based terminals for high-security vault and treasury applications.
Windows holds installed capacity. Android is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant density and regulatory stringency vary sharply across French sub-regions. The Paris corridor concentrates high-volume fixed terminal deployment, while southern coastal zones favor mobile solutions for seasonal operations.
Île-de-France
Hypermarket chains and flagship retail drive demand for wired, high-throughput terminals. CNIL audits concentrate enforcement resources here due to transaction volume exposure. La Défense business district sustains smart terminal deployment for corporate food service and hospitality.
Auvergne-Rhône-Alpes
Alpine resort properties require multi-currency terminals with dynamic currency conversion capabilities. PSD2 strong authentication mandates reshape ski rental and hospitality payment workflows. Lyon anchors regional demand from quick-service restaurant digitalization.
Provence-Alpes-Côte d'Azur
Seasonal tourism businesses favor month-to-month SaaS terminal arrangements over multi-year leases. Outdoor market vendors deploy wireless cellular terminals for festival retail mobility. Nice and Cannes hospitality clusters drive mobile terminal adoption for pay-at-table service.
Hauts-de-France
Industrial logistics and cross-border commerce with Belgium sustain demand for ruggedized mobile terminals. CB Groupe certification requirements shape acquirer relationships in this northern corridor. Lille's retail banking density supports branch-based terminal distribution networks.
Nouvelle-Aquitaine
Wine tourism and agricultural direct-to-consumer sales create niche demand for simplified onboarding solutions. Bordeaux merchant acquirers compete on flat-rate processing bundles for small vineyard operations. Coastal oyster farming cooperatives deploy Bluetooth-paired tablet systems to minimize hardware capital.
France POS Terminal Market Competitive Landscape
Capability concentration sits with legacy hardware incumbents possessing certification relationships; scale advantage sits with cloud-native challengers and micro-merchant specialists. The vendor base stratifies across three tiers: established acquirer-integrated hardware suppliers, platform-agnostic software layer providers, and simplified-entry mobile-first entrants. Dominant competitive moves include unbundling hardware from payment processing subscriptions and consolidating field service networks to reduce legacy estate maintenance costs.
Among the acquirer-integrated tier, Ingenico Group (Worldline) and Verifone occupy positions defined by embedded legacy terminal bases and certification gate access. SumUp Limited anchors the micro-merchant segment with streamlined onboarding architectures. These three exemplify how competitive positioning fragments across hardware dependency, software platform openness, and merchant segment specialization.
| Leading Market Players |
|---|
| SumUp Limited |
| Diebold Nixdorf |
| Ingenico Group (Worldline) |
| AURES Group |
| NEC Corporation |
| PAX Technology |
| Verifone |
| myPOS World Ltd |
| Zettle (PayPal) |
| Others |
Supply & Pricing Matrix
Secure element foundries in Taiwan and South Korea concentrate upstream supply for NFC controllers and cryptographic processors, anchoring margin capture at the semiconductor tier while French terminal vendors compete downstream through software subscription unbundling.
Pricing Analysis
Long-term SaaS contracts dominate French merchant relationships, displacing multi-year hardware leases with month-to-month arrangements that concentrate in Provence-Alpes-Côte d'Azur tourism corridors. Price differentiation rests on certification grade—CB Groupe compliance separates premium vendor tiers from unlicensed hardware—and volume scale, with hypermarket chains commanding processing rate discounts unavailable to micro-merchants. Cost compression in the sub-500-euro terminal segment intensifies because SoftPOS alternatives eliminate dedicated hardware procurement for sole proprietors. Micro-merchants exhibit highest price sensitivity, rejecting upfront capital outlays, while Paris-Ile-de-France retail banking channels absorb premium pricing for biometric-enabled PSD2 compliance.
Supply Chain Analysis
Export-control regimes restricting advanced semiconductor lithography equipment to China reshape secure element sourcing patterns, forcing French terminal vendors toward Taiwanese and South Korean foundry relationships. Component dependencies span NFC controllers from NXP Semiconductors, ARM-based application processors from MediaTek, and hardened security modules from Infineon. Single-source vulnerability concentrates in secure element supply, where qualified foundry relationships require 18-24 month certification cycles. Distribution runs through merchant acquirer channel partnerships, with Worldline and domestic French banks controlling terminal deployment velocity through certified device lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France POS Terminal Market sits in early-cycle expansion as Android-based open platforms displace proprietary estates, with PSD2 biometric mandates forcing terminal refresh cycles across retail networks that expand addressable software licensing pools.
For Market Incumbents: Pre-empt cloud-native platform erosion by consolidating field service networks for legacy Ingenico estates while accelerating Android application marketplace development. Vertical integration into secure element procurement hedges Taiwanese foundry concentration risk. Certification investment in CNIL-aligned biometric data governance defends against regulatory challengers.
For New Entrants and Emerging Players: Build out SoftPOS deployment capabilities targeting French micro-merchants and seasonal tourism operators in Provence-Alpes-Côte d'Azur, the most penetrable segment given rejection of multi-year hardware commitments. Direct-to-merchant SaaS onboarding without acquirer intermediation offers the cleanest go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant acquirers possessing embedded terminal bases but lacking cloud platform architecture. Long-term viability favors vendors with unbundled software revenue streams decoupled from hardware shipment cycles. The signal to watch is CB Groupe certification timeline compression, which would accelerate competitive rotation toward software-native entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Android Platform Migration | Open-source operating systems dismantle proprietary vendor lock-in, expanding ISV marketplace revenue pools. |
| Biometric Authentication Integration | PSD2 strong customer authentication mandates from the European Banking Authority force hardware refresh cycles. |
| SoftPOS Technology Deployment | Smartphone-based acceptance eliminates dedicated terminal procurement for French micro-merchant segments. |
| Field Service Network Consolidation | Legacy estate maintenance costs compress margins for incumbents with distributed technician footprints. |
| Merchant Acquirer Partnership Restructuring | Certification gate access through CB Groupe shapes competitive positioning for hardware vendors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and payment industry association reports. Interviews with merchant acquirer procurement directors, terminal vendor product managers, CNIL compliance officers, and hospitality operations executives informed demand-side validation. Secondary sources include European Banking Authority PSD2 implementation guidance, CB Groupe certification databases, and Worldline SEC disclosures. Bottom-up terminal deployment estimates triangulate against top-down payment transaction volume projections.
Forecast inputs span connectivity modality, terminal type, operating system platform, and merchant sector end-use across the analysis window. CAGRs derive from segment-level penetration modeling against French retail formation and QSR expansion trajectories. Specific inputs include PSD2 compliance deadline enforcement patterns, CNIL audit frequency trends, and SoftPOS adoption curves among micro-merchants.
Stress conditions across semiconductor lead times, biometric certification delays, and merchant acquirer consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and terminal replacement cycle stability. Material shifts in EU AI Act fraud-detection algorithm requirements or CB Groupe certification timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
North America Real Time Payment Market
Payments
Denmark Payments Market
Payments
Contactless Payment Ring Market
Payments
Contactless Payment Market
Payments
Romania POS Terminals Market
Payments
China Forex Cards Market
Payments
Vietnam Payments Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
Buy Now Pay Later Market
Payments
Japan Virtual Cards Market
Payments
Malaysia Payments Market
Payments
Egypt Mobile Payments Market
Payments
Asia Pacific Real Time Payment Market
Payments
Thailand Mobile Payments Market
Payments
Buy Now Pay Later Platform Market
Payments
Uganda Mobile Money Market