
 Cloud Computing Banking Market | 2026-2036
Cloud Computing Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Computing Banking Market Analysis
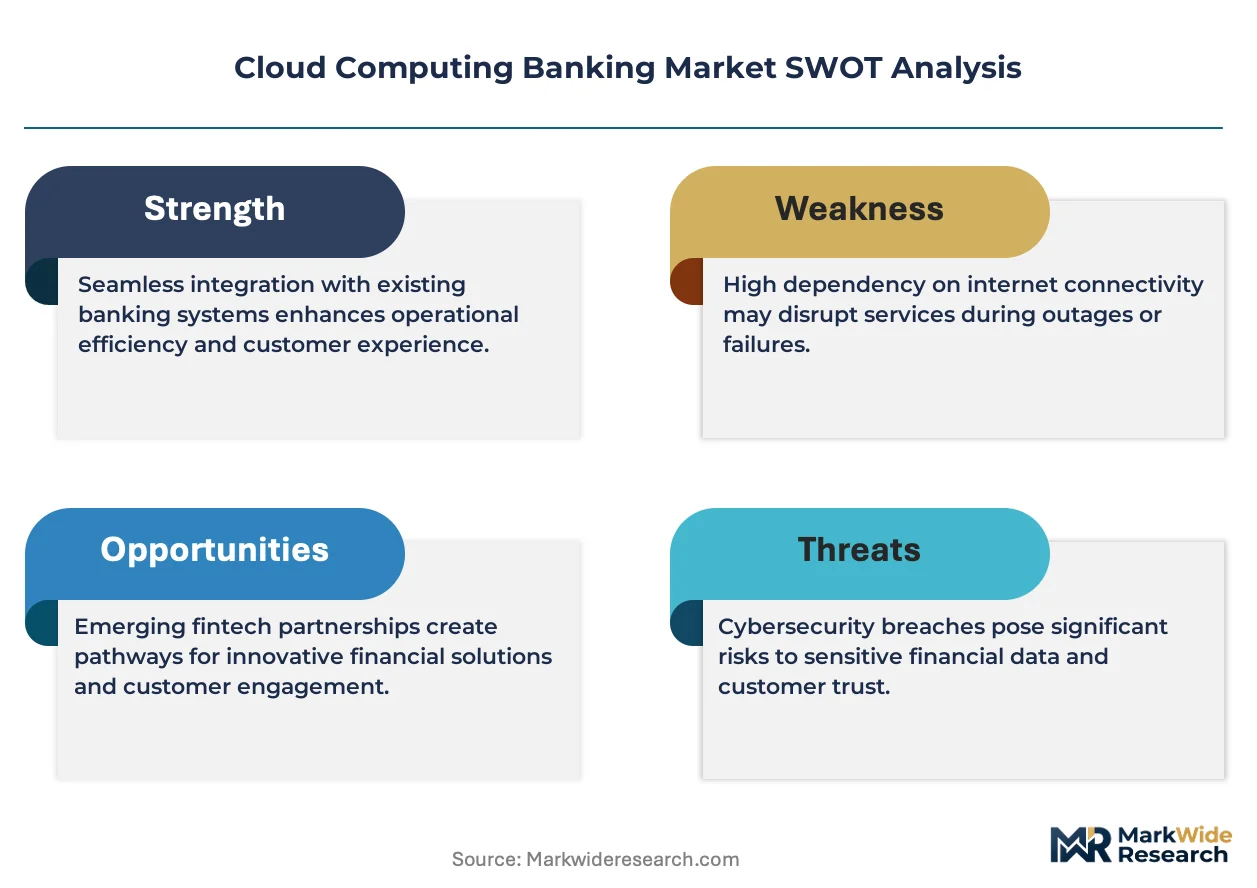
Enterprise-grade security certification is redrawing competitive thresholds in cloud banking infrastructure. Amazon Web Services leverages its FedRAMP and PCI DSS accreditations to anchor public-sector and payment-processor relationships. Microsoft Azure sustains hybrid-cloud dominance through dedicated banking industry clouds in multiple jurisdictions. Oracle Cloud specializes in core banking modernization, competing on database-to-cloud continuity for tier-one institutions.
Cloud computing in banking delivers on-demand compute, storage, and analytics resources through virtualized infrastructure over secure networks, typically requiring encryption at rest and in transit alongside sub-50-millisecond latency for real-time payment processing. Its primary purpose is to replace capital-intensive on-premise data centers with elastic operational expenditure models that scale with transaction volumes. Infrastructure as a Service occupies the largest revenue pool as banks retain control over application layers while outsourcing physical infrastructure. Hybrid Cloud deployments are expanding fastest as institutions balance regulatory data-residency requirements against public-cloud innovation cycles. Software as a Service is maturing in customer-facing channels, though margin pools remain thinner due to vendor consolidation.
FFIEC examination guidelines, PCI DSS Level 1 certification mandates, and GDPR cross-border data-transfer mechanisms collectively shape procurement criteria and vendor qualification timelines for financial institutions. The EU AI Act and emerging algorithmic-audit requirements are adding compliance layers to machine-learning deployments in credit scoring and fraud detection. Stakeholders must weigh sovereign-cloud investments against interoperability costs as regulatory fragmentation deepens across jurisdictions.
Market Dynamics
Core banking modernization is compressing procurement cycles as institutions migrate from monolithic mainframes to API-native cloud architectures, forcing vendors to recertify under tightened PCI DSS and GDPR data-sovereignty protocols.
Growth Catalysts
- Real-time payment infrastructure:FedNow and SEPA Instant settlement mandates in the United States and European Union are forcing banks to abandon batch-processing architectures for sub-50-millisecond cloud-native cores.
- GDPR cross-border data mechanisms:Standard contractual clauses and adequacy decisions are reducing legal friction for multi-jurisdiction cloud deployments, accelerating vendor consolidation among compliant hyperscalers.
- Singapore sovereign cloud capacity:The Monetary Authority of Singapore's Project Guardian is establishing regulatory sandboxes for tokenized asset settlement, drawing regional bank headquarters to locally certified facilities.
Market Restraints
- Data residency hardware costs:Dedicated sovereign cloud zones require banks to maintain redundant physical infrastructure across jurisdictions, inflating operational expenditure models versus pure public cloud economics.
- Hyperscaler concentration risk:Three vendors control over eighty percent of banking-grade cloud certifications, creating single-point-of-failure exposure for tier-one institutions with systemic importance designations.
- Quantum decryption threat horizon:NIST post-quantum cryptography standards remain in draft, leaving long-dated financial data vulnerable to harvest-now-decrypt-later attacks on current encryption-at-rest protocols.
Strategic Opportunities
- Embedded finance APIs:Banking-as-a-Service licensing in Germany and the United Kingdom is enabling non-bank retailers to offer deposit and lending products through white-labeled cloud middleware.
- AI Act algorithmic auditing:EU-mandated explainability requirements for credit-scoring models are creating specialized compliance software categories for machine-learning operations in cloud environments.
- Edge computing convergence:5G network slicing combined with containerized microservices is enabling branch-level transaction processing with centralized reconciliation, reducing last-mile latency for rural banking networks.
Industry Challenges
- Mainframe-to-cloud skill migration:COBOL and assembler expertise is retiring faster than Kubernetes and Terraform proficiency accumulates, creating talent bottlenecks for core system replatforming.
- FFIEC examination timeline compression:Regulators are demanding cloud migration evidence within eighteen-month windows, forcing banks to parallelize security testing with functional deployment rather than sequential validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Computing Banking Market |
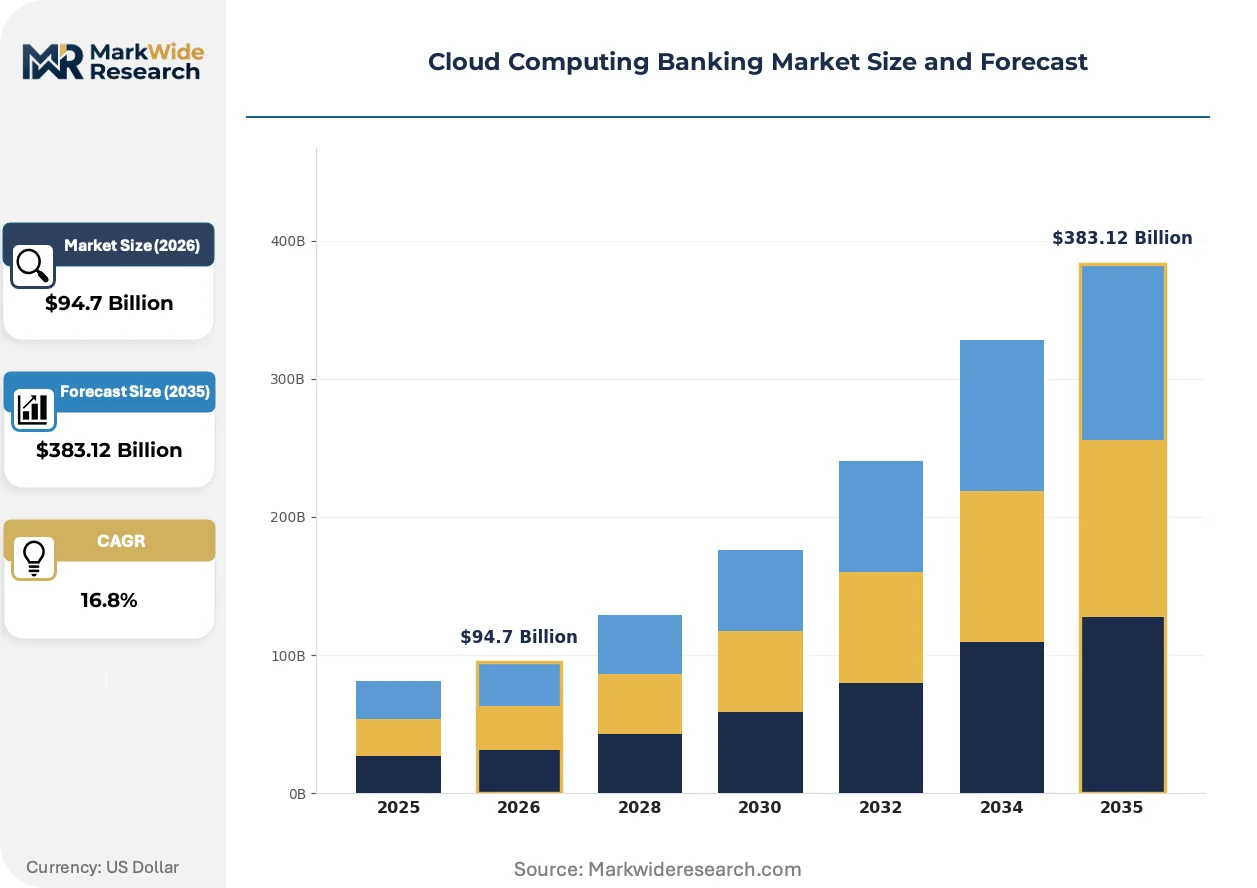
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $383.12 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Software as a Service, Platform as a Service, Backup as a Service Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Retail Banks, Investment Banks, Credit Unions, Payment Processors Compliance Standard: PCI DSS, GDPR, SOX, FFIEC |
| Companies Covered | IBM Cloud, Wipro, Amazon Web Services, Avenga, Cognizant, Microsoft Azure, Oracle Cloud, 10Clouds, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Computing Banking Market Emerging Trajectories
Distributed ledger integration and sovereign cloud localization are recasting infrastructure procurement from cost-center optimization to strategic regulatory positioning, with latency requirements now dictating vendor selection ahead of unit pricing.
Confidential computing using hardware-based trusted execution environments is fragmenting the security perimeter for payment processing. Tier-one institutions in the United States are deploying AMD SEV-SNP and Intel TDX instances for card-not-present transaction validation. This encryption-in-use capability is compressing the attack surface for insider threats while complicating forensic auditing protocols.
The EU AI Act's risk-based classification system is mandating human-in-the-loop overrides for automated credit decisions above defined thresholds. European banks are rearchitecting decision engines to maintain audit trails across cloud regions. High-risk system providers are absorbing compliance costs into platform fees, shifting procurement evaluation toward explainability metrics from raw throughput benchmarks.
Consumption-based pricing for core banking workloads is displacing reserved-instance commitments in procurement negotiations. German and Singaporean institutions are piloting transaction-volume-linked contracts that scale compute allocation with payment message traffic. This elasticity is visible most acutely in retail banking channels where seasonal spikes previously required overprovisioned disaster-recovery capacity.
Cloud Computing Banking Market Segmentation
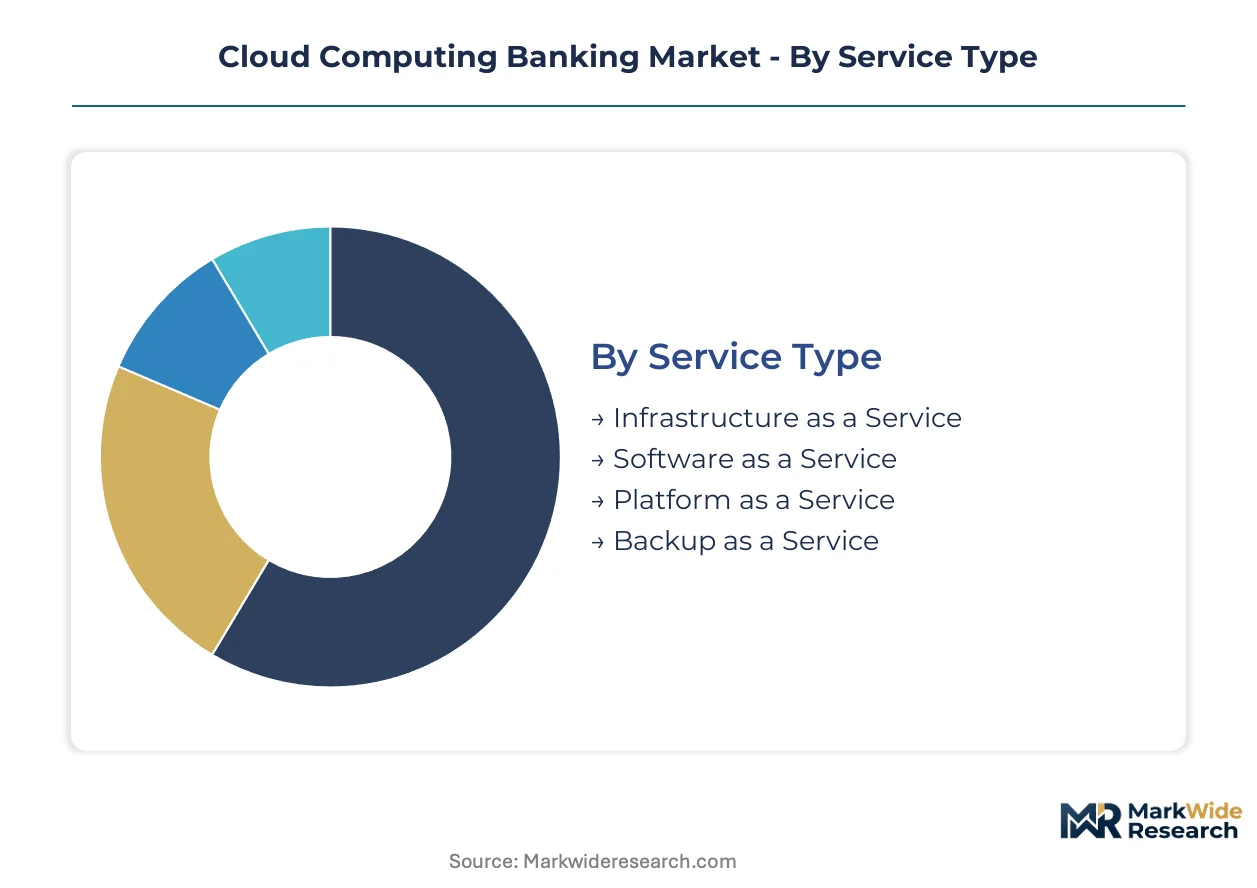
Cloud banking procurement hinges on matching service architecture to regulatory jurisdiction and data gravity. Banks segment their cloud portfolios across service layers, deployment topologies, and compliance frameworks to balance innovation velocity against sovereign data requirements.
Service Type:
PCI DSS Level 1 certification requirements differentiate vendor eligibility across service tiers, with infrastructure and platform layers facing stricter audit protocols than application-level offerings.
- Infrastructure as a Service:Raw compute, storage, and networking resources delivered through virtualized data centers with encryption-at-rest mandates. United States retail banks concentrate demand here for core banking workloads, driven by FedRAMP accreditation requirements for federal-facing institutions.
- Software as a Service:Pre-configured banking applications including CRM, loan origination, and digital onboarding portals. German institutions favor SaaS for customer-facing channels under BSI IT-Grundschutz compliance, though margin compression from vendor consolidation limits expansion.
- Platform as a Service:Managed development environments enabling API-native core modernization without underlying infrastructure administration. Singapore's Project Guardian participants deploy PaaS for tokenized asset sandboxing.
- Backup as a Service:Automated disaster recovery with immutable snapshot retention for ransomware resilience. Credit unions in rural United States markets adopt this for FFIEC-mandated business continuity.
Infrastructure as a Service handles the majority of throughput; Backup as a Service is gaining share fastest as ransomware threats intensify.
Deployment Model:
Cost tiering separates hyperscale public deployments from sovereign-zone premiums, with hybrid configurations occupying the middle pricing band.
- Hybrid Cloud:Split workloads across on-premise private infrastructure and public cloud burst capacity. Investment banks in London and Frankfurt deploy this model to satisfy GDPR data-residency while accessing AI training clusters.
- Public Cloud:Shared infrastructure with multi-tenant isolation and pay-as-you-go economics. United States payment processors route transaction spikes through public regions during holiday retail surges.
- Private Cloud:Dedicated single-tenant environments with physical hardware segregation. Swiss private banks mandate this for client asset data under FINMA outsourcing circulars.
- Multi-Cloud:Orchestrated workloads across two or more hyperscalers to mitigate concentration risk. Singaporean tier-one institutions pilot this for systemic resilience against single-vendor failure.
Hybrid Cloud dominates procurement volume; Multi-Cloud exhibits the steepest expansion trajectory as concentration risk awareness spreads.
End User:
Application complexity and transaction volume shape technology requirements across institutional categories.
- Retail Banks:High-volume, low-margin transaction processing with seasonal demand spikes. United States regional banks migrating from Fiserv and Jack Henry cores drive cloud-native replacement demand.
- Investment Banks:Compute-intensive risk modeling and real-time trading analytics. Frankfurt and London trading desks require sub-millisecond co-location proximity to exchanges.
- Credit Unions:Member-owned cooperatives with limited IT budgets and NCUA examination requirements. Cloud adoption concentrates in core processing replacement rather than innovation workloads.
- Payment Processors:Network-scale transaction routing with 99.999% uptime SLAs. Visa and Mastercard network partners in Singapore and Germany deploy edge-connected cloud for authorization latency.
Retail Banks account for the largest workload volume; Payment Processors are expanding most quickly as real-time settlement mandates proliferate.
Compliance Standard:
Certification scope determines vendor qualification timelines and geographic deployment permissions.
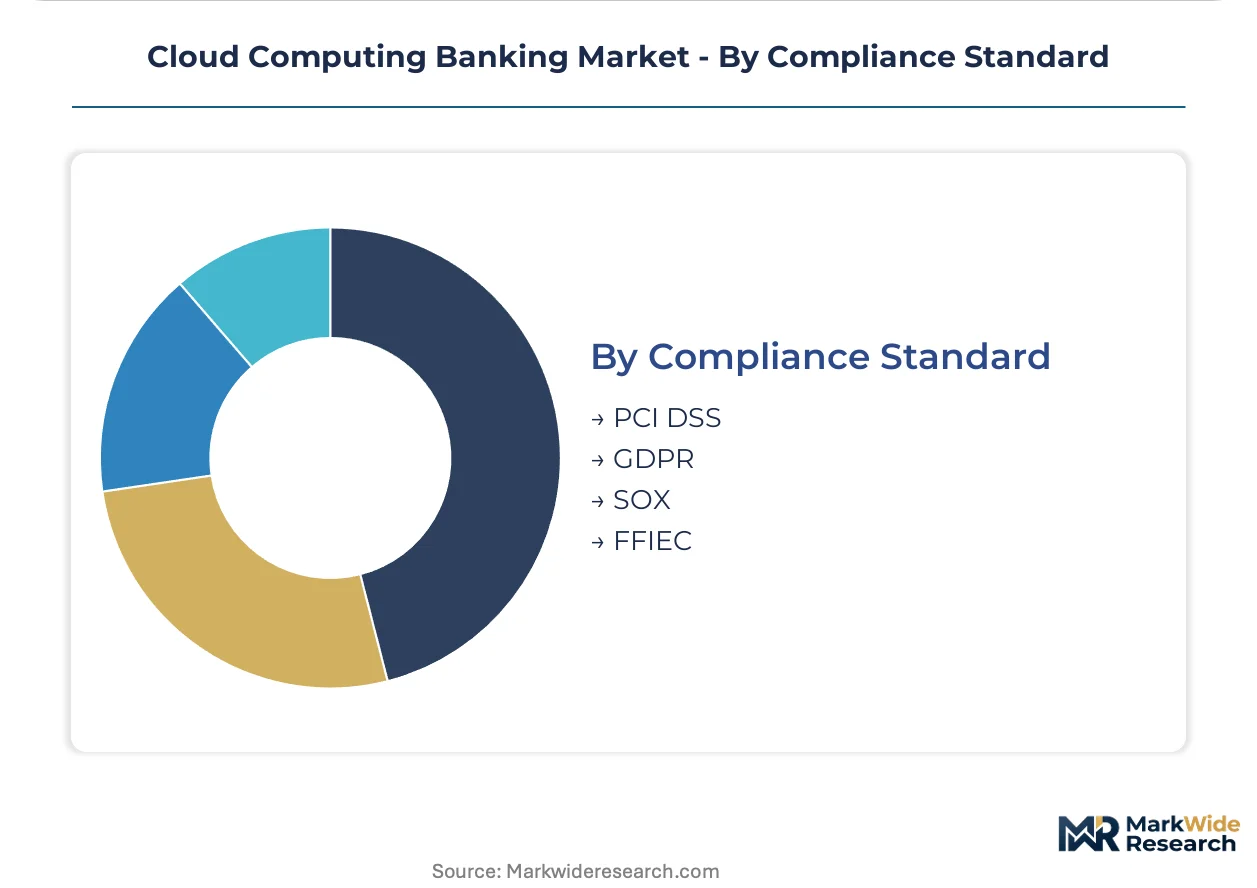
- PCI DSS:Payment card industry security standards governing cardholder data environments. Level 1 certification requires annual on-site audits and quarterly network scans.
- GDPR:European data protection framework mandating cross-border transfer mechanisms and data subject rights. Standard contractual clauses enable multi-region cloud continuity.
- SOX:United States financial reporting controls requiring IT general controls documentation for publicly traded banks. Cloud migrations trigger material weakness assessments.
- FFIEC:United States federal examination guidelines for technology service provider oversight. Examiners demand eighteen-month migration evidence packages.
PCI DSS certification gates the broadest vendor participation; GDPR mechanisms are climbing fastest as European AI Act layers add algorithmic audit requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler certification density concentrates cloud banking infrastructure investment in jurisdictions with mature financial regulatory frameworks. Sovereign data requirements and real-time payment mandates are redrawing regional deployment priorities.
United States
FedNow real-time settlement infrastructure and FFIEC examination timelines are accelerating core banking migrations. FedRAMP accreditation requirements filter vendor participation for federal-facing institutions. New York and Chicago financial centers host concentrated cloud-native core deployments among regional banks exiting legacy Fiserv and Jack Henry architectures.
Germany
BSI IT-Grundschutz compliance and BaFin outsourcing circulars mandate stringent data residency for core banking workloads. The EU AI Act's algorithmic audit requirements layer additional compliance burdens on credit-scoring cloud deployments. Frankfurt's trading infrastructure demands sub-millisecond co-location proximity, favoring hybrid configurations over pure public cloud.
Singapore
Project Guardian's tokenized asset settlement sandboxes and MAS digital banking licenses are attracting regional headquarters to locally certified facilities. Cross-border data mechanisms under ASEAN frameworks enable multi-jurisdiction continuity. The city-state's sovereign cloud capacity expansion supports payment processor edge deployments for 99.999% uptime SLAs.
Switzerland
FINMA outsourcing circulars and private banking confidentiality traditions enforce dedicated single-tenant environments for client asset data. Zürich and Geneva private banks mandate physical hardware segregation, sustaining premium pricing for sovereign cloud zones despite higher operational expenditure models.
United Kingdom
Banking-as-a-Service licensing frameworks and PRA cloud guidance are enabling embedded finance API proliferation. The Financial Conduct Authority's operational resilience requirements compress migration evidence timelines. London's investment banking concentration drives demand for compute-intensive risk modeling clusters with hybrid burst capacity.
Cloud Computing Banking Market Vendor Landscape
Concentration sits with hyperscale cloud providers holding banking-grade security certifications. Three vendors control over eighty percent of PCI DSS Level 1 and FedRAMP accreditations, creating tiered procurement access. Strategic archetypes include full-stack hyperscalers, core banking specialists, and systems integrators with compliance expertise. Dominant competitive moves encompass sovereign zone expansion and vertical capability acquisition.
Among full-stack hyperscalers, Amazon Web Services, Microsoft Azure, and Google Cloud Platform occupy positions defined by accreditation breadth and jurisdictional coverage. Oracle Cloud exemplifies the core banking specialist archetype through database-to-cloud continuity positioning. Systems integrators including IBM Cloud, Wipro, Cognizant, and Avenga represent the compliance-heavy implementation tier, anchoring migration execution for tier-one institutions.
| Leading Market Players |
|---|
| IBM Cloud |
| Wipro |
| Amazon Web Services |
| Avenga |
| Cognizant |
| Microsoft Azure |
| Oracle Cloud |
| 10Clouds |
| Google Cloud Platform |
| Others |
Supply Flow & Price Mechanics
Transaction-volume-linked contracts anchor cloud banking procurement, locking in compute allocation elasticity while binding price visibility to payment message traffic across FedNow and SEPA Instant settlement corridors. This structure concentrates pricing power with hyperscalers holding PCI DSS Level 1 and FedRAMP dual certification, forcing tier-one institutions into multi-year commitments to secure sovereign zone capacity.
Pricing Analysis
PCI DSS Level 1 certification dictates the pricing tier structure across infrastructure and platform layers, with annual audit costs and quarterly network scan requirements feeding into platform fees. Consumption-based pricing for core banking workloads is displacing reserved-instance commitments, particularly among German and Singaporean institutions piloting seasonal elasticity models. Price differentiation centers on certification grade and data residency guarantees, with dedicated sovereign cloud zones commanding premiums over multi-tenant public deployments. Credit unions and rural United States institutions exhibit highest price sensitivity due to NCUA examination constraints and limited IT budgets, while investment banks in London and Frankfurt absorb premium pricing for sub-millisecond co-location proximity.
Supply Chain Analysis
Hyperscaler concentration risk creates a chokepoint where three vendors control over eighty percent of banking-grade cloud certifications, tethering tier-one institutions to single-source vulnerability for systemic resilience. Physical infrastructure dependencies rest on specialized semiconductor fabrication in Taiwan and South Korea for confidential computing hardware, alongside dedicated server assembly in United States and German facilities. Supply chain risk concentrates in regulatory restriction exposure, as GDPR cross-border data mechanisms and EU AI Act algorithmic audit requirements fragment vendor qualification timelines. Distribution runs through systems integrators including IBM Cloud, Wipro, and Cognizant, which anchor migration execution and compliance-heavy implementation for institutions lacking Kubernetes and Terraform proficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud banking infrastructure sits in early-cycle expansion as real-time payment mandates force abandonment of batch-processing architectures, creating procurement urgency among regional banks exiting legacy core systems.
For Market Incumbents: Shield certification moats by accelerating sovereign zone expansion into Singapore and Switzerland, where FINMA outsourcing circulars and MAS Project Guardian sandboxes concentrate premium demand. Deepen vertical integration through confidential computing hardware partnerships with AMD and Intel, insulating against quantum decryption threats while complicating forensic auditing protocols for competitors. Concentration risk from emerging multi-cloud orchestration specialists demands defensive API-native core acquisitions.
For New Entrants and Emerging Players: Lead with AI Act algorithmic auditing software for European credit-scoring deployments, where EU-mandated explainability requirements create specialized compliance categories absent from incumbent platform offerings. Target credit unions and rural United States markets with Backup as a Service solutions, exploiting FFIEC-mandated business continuity gaps and limited internal Kubernetes expertise. White-label embedded finance APIs through German and United Kingdom Banking-as-a-Service licensing frameworks.
For Investors and Strategic Acquirers: Capital is best deployed toward systems integrators with compliance expertise and established FFIEC examination track records, as eighteen-month migration evidence timelines compress procurement cycles. Long-term viability hinges on sovereign cloud capacity positioning across jurisdictions with tightening data residency rules. The signal to watch is FedRAMP accreditation density among federal-facing institutions, which gates public-sector relationships and anchors payment-processor partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Zone Expansion | Secures PCI DSS and GDPR compliance positioning in Germany and Singapore financial hubs. |
| Confidential Computing Partnership | Deploys AMD SEV-SNP and Intel TDX for encryption-in-use payment validation capabilities. |
| AI Act Compliance Software Development | Captures EU-mandated explainability requirements for credit-scoring model audit trails. |
| Embedded Finance API Licensing | Enables non-bank retailers to offer deposit products through white-labeled cloud middleware. |
| Multi-Cloud Orchestration Investment | Mitigates hyperscaler concentration risk for systemically important tier-one institutions. |
Methodological Framework
Operator-level perspectives from cloud infrastructure procurement officers, core banking modernization leads, regulatory compliance directors, and systems integrator engagement managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation across FFIEC examination guidelines, PCI DSS certification registries, GDPR adequacy decision databases, and hyperscaler sovereign zone disclosure filings. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across service type, deployment topology, and compliance framework dimensions.
Sensitivity analysis tested forecast robustness across alternative regulatory scenarios and quantum cryptography standardization timelines. The analytical framework modeled Infrastructure as a Service, Platform as a Service, Software as a Service, and Backup as a Service segments alongside hybrid, public, private, and multi-cloud deployment configurations. CAGRs derived from transaction volume elasticity curves and core banking replacement cycle acceleration patterns, with FedNow and SEPA Instant settlement mandates serving as demand inflection inputs.
The analysis sits within stated boundaries; outcomes outside sustained real-time payment infrastructure rollout or draft NIST post-quantum cryptography finalization would require recalibration. Forecasts reflect documented assumptions regarding regulatory fragmentation depth and sovereign cloud capacity expansion trajectories. Revision becomes warranted when hyperscaler concentration thresholds or GDPR cross-border mechanism rulings cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking As a Service (BAAS) Market
Banking
Latin America Neo Banking Services Market
Banking
Banking Smart Cards Market
Banking
E-Banking Market
Banking
Banking Maintenance Support and Services Market
Banking
Armenia Banking Market
Banking
Banking CRM Software Market
Banking
GCC Mobile Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Bank Kiosk Market
Banking
Global Retail Core Banking Systems Market
Banking
Investment Banking and Trading Services Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Latin America Banking As a Service Market
Banking
Banking Tax Management Software Market
Banking
Core Banking Solutions Market