
 China Payments Market | 2026-2036
China Payments Market Size, Share, and Industry Trends Forecast 2026-2036
China Payments Market Analysis
The People's Bank of China's third-party payment licensing framework is realigning the cost-of-entry calculus for new fintech entrants. Ant Group leverages its embedded finance ecosystem across Alibaba Group commerce platforms to sustain merchant lock-in. Tencent Holdings anchors consumer payment habits through WeChat Pay's super-app integration, while China UnionPay competes via its cross-border clearing infrastructure and bank partnerships.
China payments encompass digital fund transfer systems spanning mobile applications, point-of-sale terminals, automated teller machines, and internet-based gateways that settle transactions through centralized clearing networks with real-time authentication protocols. The primary commercial purpose is reducing cash handling costs while accelerating transaction velocity for retail and enterprise commerce. Mobile channel penetration leads transaction volume growth as smartphone-based QR settlement displaces card-present methods, while e-wallet transaction methods capture the fastest expansion within debit-dominated consumer banking. Enterprise customer segments concentrate margin pools through treasury management and supply chain finance integrations.
SAMR enforces anti-monopoly provisions against payment platform exclusivity, while the PBOC's digital yuan initiative mandates technical interoperability standards that reshape product architecture requirements. The country's national financial regulator also imposes reserve deposit ratios on customer funds held by non-bank payment institutions, compressing interest income models. Stakeholders must monitor central bank digital currency API access policies to determine platform differentiation strategies.
Market Dynamics
The People's Bank of China's interoperability mandates for central bank digital currency integration are compressing legacy payment architecture timelines while forcing third-party platforms to restructure technical stacks for e-CNY settlement compatibility.
Growth Catalysts
- Dual Circulation Policy:China's domestic consumption reinforcement strategy accelerates rural digital payment penetration as county-level commercial banks upgrade core banking systems to support real-time QR settlement networks.
- MIIT 5G Infrastructure Rollout:Ultra-low latency connectivity enables merchant acquirers to deploy contactless point-of-sale terminals in previously underserved township retail corridors.
- SME Digitalization Mandates:Jiangsu and Guangdong provincial governments subsidize cloud-based treasury management adoption, concentrating payment volume growth in manufacturing supply chain hubs.
Market Restraints
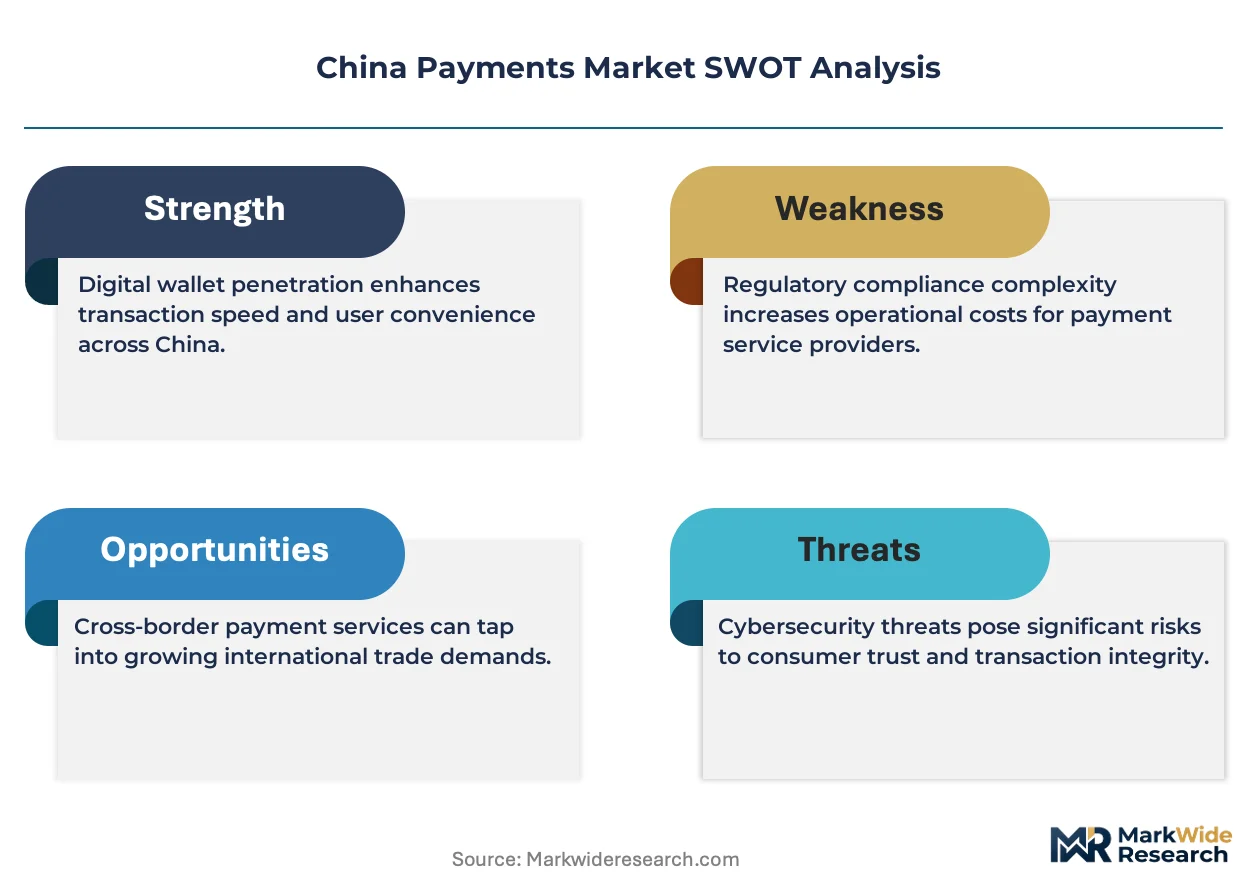
- Reserve Deposit Requirements:The PBOC's 100% custodial fund reserve ratio eliminates interest income arbitrage for non-bank payment institutions, compressing net margin structures.
- Antitrust Enforcement:SAMR's exclusivity prohibitions prevent platform lock-in through merchant routing restrictions, fragmenting transaction volume across competing acquirers.
- Technical Debt Burden:Legacy core banking systems at joint-stock banks require multi-year migration paths to support CBDC API standards, delaying interoperability gains.
Strategic Opportunities
- Cross-Border RMB Settlement:China UnionPay's Belt and Road corridor expansion creates acquiring opportunities for Chinese e-wallet providers in Southeast Asian tourism and education payment verticals.
- Supply Chain Finance Integration:Embedded working capital products linked to payment data streams capture enterprise treasury management budgets previously held by commercial banks.
- Tier-Two City CBDC Pilots:Municipal governments in Chengdu and Suzhou deploy consumption voucher programs through digital yuan wallets, accelerating merchant onboarding velocity.
Industry Challenges
- API Standardization Complexity:PBOC's evolving technical specifications for e-CNY integration force payment platforms to maintain parallel development tracks, inflating engineering overhead.
- Data Localization Compliance:Cybersecurity Law requirements for domestic server storage of transaction records impose infrastructure duplication costs for multinational payment service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Payments Market |
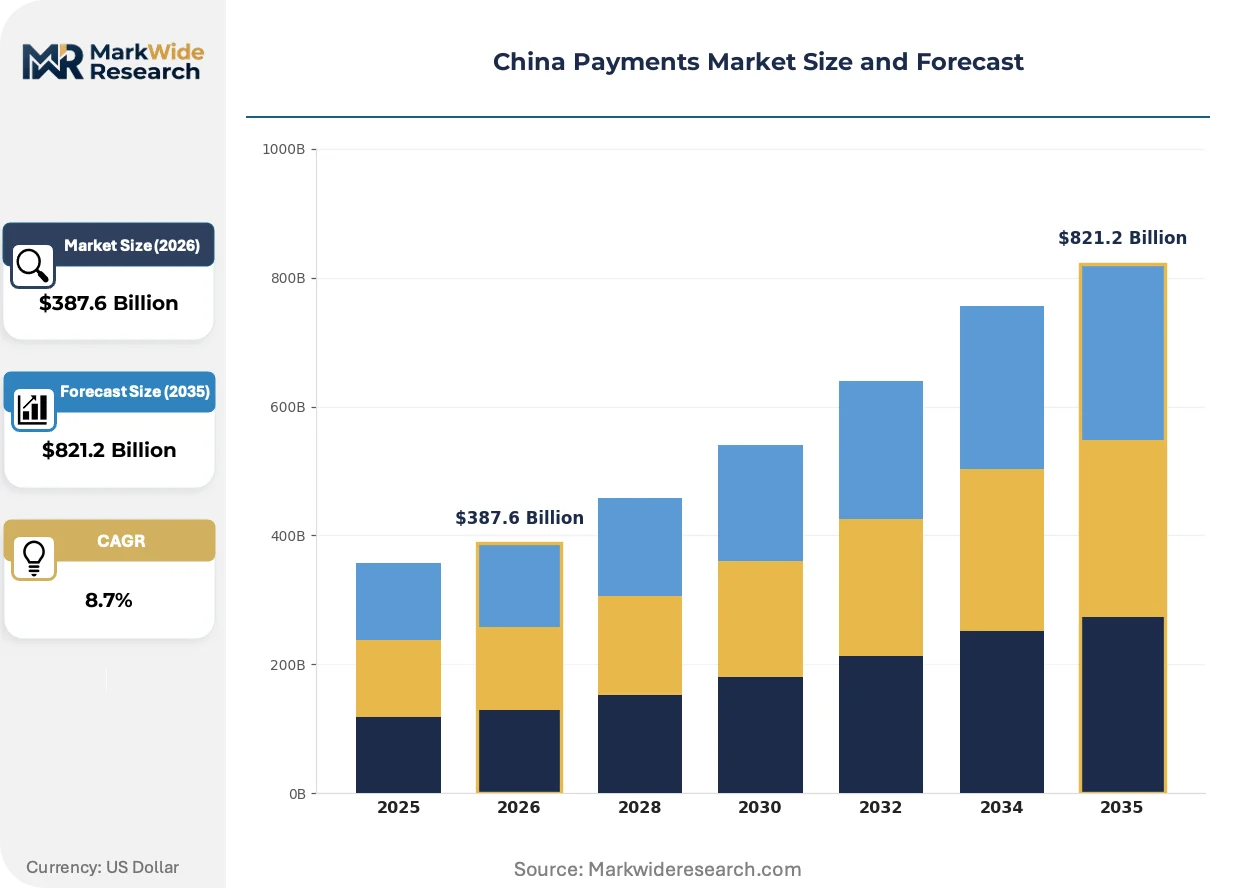
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Channel Type: Online, Mobile, POS, ATM Transaction Method: Credit Card, Debit Card, E-Wallet, Bank Transfer Payment Service Provider: Alipay, WeChat Pay, UnionPay, Paypal Customer Segment: Retail, E-commerce, Enterprises, Government |
| Companies Covered | PayEase, Ant Group, Alipay, Alibaba Group, Tencent Holdings, WeChat Pay, 99Bill, China UnionPay, UnionPay International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Payments Market Emerging Trajectories
Payment infrastructure convergence around central bank digital currency rails is collapsing traditional distinctions between retail and wholesale settlement layers while compressing merchant acquisition cost structures.
Biometric authentication protocols are consolidating identity verification steps into single-touch payment flows. Tier-three city retail merchants adopt facial recognition terminals at accelerated rates as hardware costs decline below magnetic stripe reader replacement thresholds. This consolidation is eliminating password-based authentication as a viable competitive feature in consumer-facing payment applications.
SAMR's anti-monopoly guidelines on payment platform exclusivity are forcing merchant acquirers to support multi-wallet acceptance without routing preference penalties. The industrial consequence fragments transaction volume concentration previously held by dominant super-app ecosystems. SME merchants in Zhejiang province respond by diversifying checkout options to capture consumer preference flexibility.
Corporate treasury departments are unbundling payment processing from integrated banking relationships, selecting specialized fintech providers for cross-border settlement while retaining deposit accounts with incumbent lenders. This disintermediation compresses commercial bank payment fee income while expanding independent software vendor market access. Manufacturing exporters in the Pearl River Delta exhibit the most aggressive unbundling behavior, driven by multi-currency hedging requirements.
China Payments Market Segmentation
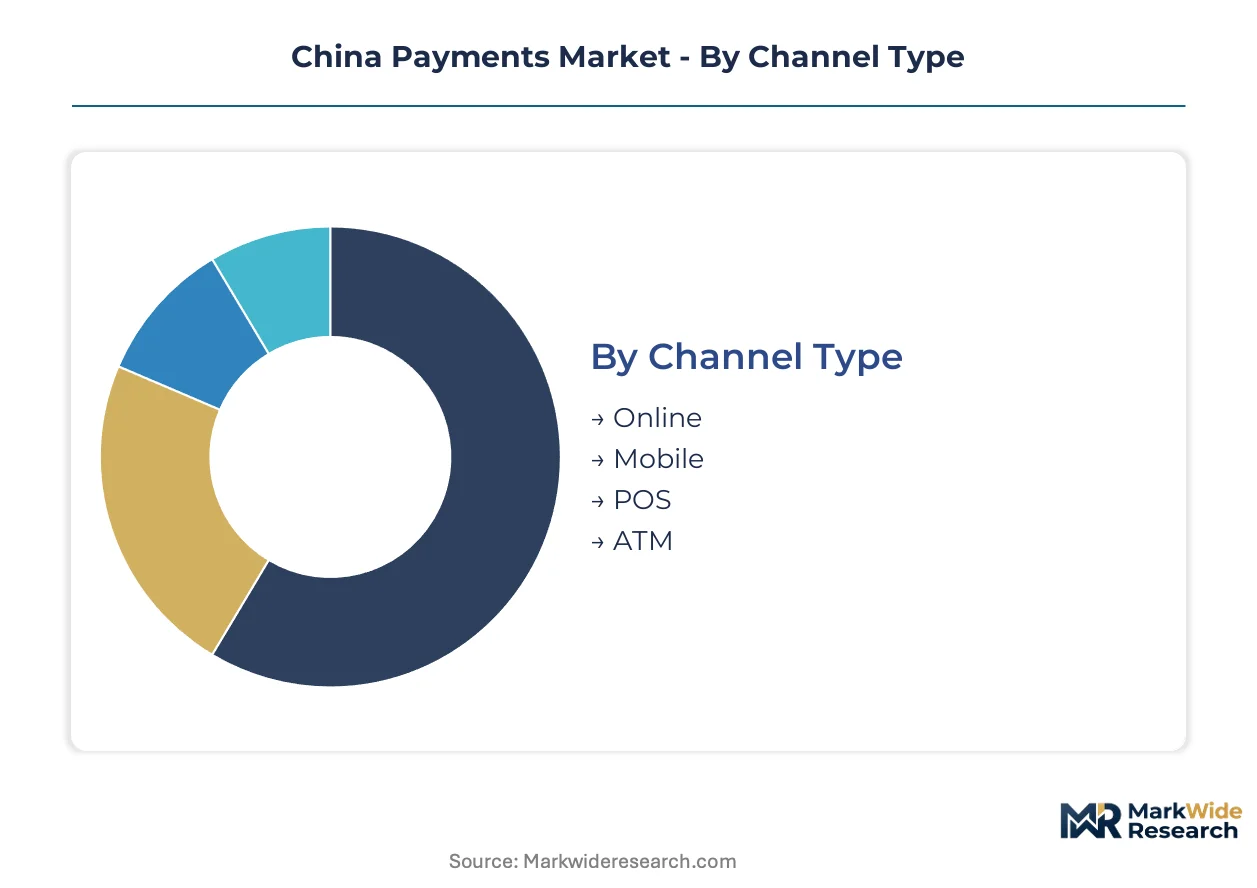
Payment channel fragmentation across China reflects divergent technical integration requirements and merchant acquisition cost structures. Segment boundaries are blurring as central bank digital currency rails force interoperability across previously siloed settlement systems.
Channel Type:
Standalone mobile applications dominate consumer-facing transaction volumes while embedded POS infrastructure requires deeper merchant system integration.
- Mobile:QR-code settlement protocols running on smartphone applications displace card-present methods in tier-one through tier-four cities. Demand clusters in Guangdong province where SME merchant onboarding subsidies accelerate smartphone-based acceptance infrastructure deployment.
- Online:Browser-based gateway authentication supporting e-commerce checkout flows with real-time bank routing. Transaction volume concentrates in Jiangsu province manufacturing export corridors where cross-border settlement integration drives merchant platform selection.
- POS:Terminal-based card and contactless acceptance at physical retail locations.
- ATM:Automated cash dispensing and deposit networks with declining transaction frequency.
Volume placements concentrate in Mobile; the faster expansion belongs to Online.
Transaction Method:
Cost tier differentiation separates high-interchange credit products from zero-fee debit rails and subsidized e-wallet promotions.
- E-Wallet:Stored-value accounts linked to bank cards or direct balance funding, settling through third-party payment institution licenses. Embedded finance ecosystems in Alibaba Group commerce platforms sustain merchant lock-in through integrated treasury management tools.
- Debit Card:Direct bank account deduction through UnionPay network rails with immediate settlement. Rural county-level commercial banks leverage debit dominance to upgrade core banking systems for real-time QR compatibility under Dual Circulation Policy mandates.
- Credit Card:Revolving credit lines with interest-bearing balances and merchant interchange fees.
- Bank Transfer:Direct account-to-account settlement through corporate banking portals.
Volume placements concentrate in Debit Card; the steepest expansion trajectory belongs to E-Wallet.
Payment Service Provider:
Platform market maturity separates entrenched super-app ecosystems from newer entrants competing on specialized vertical integration.
- Alipay:Ant Group's embedded finance platform spanning e-commerce, wealth management, and merchant services with proprietary risk engines.
- WeChat Pay:Tencent Holdings' payment layer integrated into messaging and mini-program ecosystems.
- UnionPay:State-backed card network with cross-border clearing infrastructure and commercial bank partnerships.
- Paypal:Cross-border remittance and merchant acquiring services for Chinese exporters.
Volume placements concentrate in Alipay; the faster expansion belongs to UnionPay.
Customer Segment:
Application complexity separates standardized retail checkout from customized enterprise treasury workflows and government procurement systems.
- Enterprises:B2B payment flows integrating supply chain finance, multi-currency hedging, and automated reconciliation. Manufacturing exporters in the Pearl River Delta unbundle payment processing from commercial banking relationships to capture specialized fintech capabilities.
- E-commerce:Platform-integrated checkout with escrow protection and dispute resolution mechanisms. Merchant concentration in Zhejiang province drives demand for multi-wallet acceptance without routing preference penalties under SAMR anti-monopoly guidelines.
- Retail:Consumer-facing point-of-sale and remote payment acceptance.
- Government:Public procurement, tax collection, and social benefit disbursement systems.
Volume placements concentrate in Retail; the faster expansion belongs to Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment volume concentrates in coastal provinces where SME digitalization subsidies and central bank digital currency pilots intersect. Provincial governments in manufacturing corridors drive merchant onboarding velocity through targeted infrastructure programs.
Guangdong Province
SME merchant onboarding subsidies accelerate smartphone-based acceptance infrastructure deployment across the Pearl River Delta. The provincial government subsidizes cloud-based treasury management adoption for manufacturing exporters. Shenzhen anchors merchant acquirer competition as hardware costs for facial recognition terminals decline below magnetic stripe reader replacement thresholds.
Jiangsu Province
Cross-border settlement integration drives merchant platform selection in manufacturing export corridors. The provincial administration enforces SME digitalization mandates through subsidized core banking system upgrades. Suzhou municipal government deploys consumption voucher programs through digital yuan wallets, accelerating merchant onboarding velocity.
Zhejiang Province
SME merchants diversify checkout options to capture consumer preference flexibility under SAMR anti-monopoly guidelines. The provincial commerce department enforces multi-wallet acceptance without routing preference penalties. Hangzhou concentrates e-commerce platform merchant demand for integrated escrow protection and dispute resolution mechanisms.
Sichuan Province
Rural county-level commercial banks upgrade core banking systems for real-time QR compatibility under Dual Circulation Policy mandates. The Chengdu municipal government pilots tier-two city CBDC consumption voucher programs. The Chengdu-Chongqing economic circle attracts payment infrastructure investment as 5G rollout enables contactless terminal deployment in township retail corridors.
Shandong Province
Manufacturing supply chain hubs concentrate enterprise treasury management demand for embedded working capital products. The provincial technology department enforces MIIT 5G infrastructure rollout timelines for merchant acquirers. Qingdao anchors cross-border RMB settlement demand through China UnionPay's Belt and Road corridor expansion.
China Payments Market Vendor Landscape
Hangzhou-based platform operators anchor one tier; Beijing and Shenzhen specialists hold differentiated positions in enterprise and cross-border segments. The vendor structure consolidates around super-app ecosystems with embedded finance capabilities, while state-backed networks compete on clearing infrastructure. Three archetypes dominate: commerce-integrated platforms, messaging-layer payment providers, and bank-network hybrids. Competitive moves center on CBDC API compliance restructuring and supply chain finance product unbundling.
Within the commerce-integrated tier, Ant Group and Alibaba Group represent embedded finance ecosystem consolidation, while Tencent Holdings and WeChat Pay exemplify messaging-layer payment integration. China UnionPay occupies the state-backed network position with cross-border clearing infrastructure. These entities sit within a regulatory environment where SAMR anti-monopoly enforcement and PBOC interoperability mandates reshape technical architecture requirements.
| Leading Market Players |
|---|
| PayEase |
| Ant Group |
| Alipay |
| Alibaba Group |
| Tencent Holdings |
| WeChat Pay |
| 99Bill |
| China UnionPay |
| UnionPay International |
| Others |
Supply Flow & Price Mechanics
Horizontal integration across merchant acquirer networks anchors supply positioning for payment terminal manufacturers while concentrating pricing power among firmware developers and biometric authentication chip suppliers. Ant Group's captive production of QR code scanning modules and Tencent's in-house mini-program payment rails demonstrate how control over critical hardware and software layers translates into margin protection against commoditized processing fees.
Pricing Analysis
Volume placements in debit card rails run on near-zero interchange while credit and e-wallet products capture wider spreads through merchant service bundles. Pricing stratifies across premium facial recognition terminals, standard QR code scanners, and economy magnetic stripe readers based on authentication sophistication and integration depth. Cost compression in entry-level POS hardware is intensifying because MIIT 5G infrastructure rollout enables software-defined terminal substitution. SME merchants in township retail corridors exhibit highest price sensitivity; enterprise treasury clients prioritize API reliability over per-transaction fees.
Supply Chain Analysis
Dual-sourcing requirements from PBOC-licensed payment institutions mandate qualified suppliers for both EMV chip modules and domestic encryption processors. Manufacturing concentrates in China, Taiwan, and South Korea for NFC controllers, secure elements, and camera-based biometric sensors. Raw material dependencies include rare earth magnets for contactless antennae, advanced packaging substrates for system-on-chip integration, and gallium nitride components for power management. Single-source vulnerability sits with domestic server storage compliance under Cybersecurity Law mandates. Distribution runs through tiered merchant acquirer networks terminating at county-level commercial banks and independent software vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into core banking system software and captive biometric sensor production defines competitive positioning as PBOC interoperability mandates compress third-party platform margins. Players securing upstream control over CBDC API compliance layers and downstream merchant onboarding infrastructure capture durable pricing power.
For Market Incumbents: Hedge against SAMR exclusivity prohibitions by diversifying merchant acquirer partnerships beyond proprietary super-app ecosystems. Invest in supply chain finance product suites that unbundle commercial bank treasury relationships. The reserve deposit requirement elimination of interest income arbitrage demands cost compression through cloud-native core banking migrations rather than legacy system maintenance. For New Entrants and Emerging Players: Begin with embedded working capital products targeting manufacturing exporters in the Pearl River Delta where commercial bank disintermediation is most advanced. White-space concentrates in cross-border RMB settlement corridors along Belt and Road tourism and education verticals. A regulatory technology go-to-market angle—automated PBOC compliance reporting—differentiates against incumbent platform complexity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by commerce-platform operators seeking payment infrastructure control or by bank-network hybrids filling CBDC capability gaps. Long-term viability hinges on 5-10 year central bank digital currency API access policies determining platform differentiation potential. Monitor tier-two city CBDC pilot expansion velocity as inflection indicator for merchant onboarding tool demand.| Strategic Initiative | Industry Significance |
|---|---|
| CBDC API Compliance Restructuring | PBOC technical interoperability mandates force parallel development tracks for e-CNY settlement compatibility. |
| Supply Chain Finance Product Launch | Embedded working capital tools capture enterprise treasury budgets from commercial bank incumbents. |
| Cross-Border Acquiring Partnership | China UnionPay Belt and Road corridor expansion enables Southeast Asian merchant network access. |
| Biometric Terminal Hardware Integration | Facial recognition authentication consolidation eliminates password-based competitive features. |
| Cloud-Native Core Banking Migration | Real-time QR settlement compatibility under Dual Circulation Policy mandates infrastructure modernization. |
Methodological Framework
Independent corroboration across payment platform executives, PBOC regulatory affairs specialists, and county-level commercial bank technology officers underwrites the qualitative findings. Primary interviews with merchant acquirer operations heads, biometric terminal hardware engineers, and supply chain finance product managers combined with secondary validation from MIIT 5G infrastructure disclosures, SAMR anti-monopoly enforcement records, and PBOC digital yuan pilot documentation. Bottom-up merchant onboarding velocity estimates and top-down transaction volume projections from centralized clearing network data complete the triangulation.
Comparable-period anchoring to historical mobile wallet penetration curves and CBDC pilot expansion timelines structured the forecast window across the analysis window. Segmentation dimensions modeled include payment channel type, transaction method tier, customer segment application complexity, and provincial regulatory cluster adoption patterns. CAGRs derive from slope-consistent trajectory analysis applied to SME digitalization subsidy disbursement rates and 5G terminal deployment timelines.
PBOC reserve requirement adjustments, SAMR exclusivity enforcement intensity, and CBDC technical specification volatility are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding merchant acquirer cost pass-through elasticity and biometric hardware cost decline curves. A model refresh is warranted upon material change in tier-two city CBDC pilot municipal subsidy allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
B2B Payments Platform Market
Payments
Ghana Mobile Money Market
Payments
Digital Payment in Healthcare Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Japan POS Terminals Market
Payments
Asia-Pacific Payments Market
Payments
Uganda Mobile Money Market
Payments
Face-Swiping Payment Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Transaction Monitoring Market
Payments
Tanzania Mobile Money Market
Payments
Bus Card Reader Market
Payments
Global Financial Cards and Payments Market
Payments
France POS Terminal Market
Payments
Saudi Arabia Buy Now Pay Later Services Market