
 Vietnam E-Wallet Market | 2026-2036
Vietnam E-Wallet Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam E-Wallet Market Intelligence
Biometric authentication integration into mobile payment architectures is reconfiguring how e-wallet providers build trust and reduce friction at checkout. MoMo leverages its agent network density to sustain cash-in/cash-out dominance across provincial Vietnam. VNPAY anchors the B2B segment through bank-integrated QR infrastructure that merchants adopt at scale. ZaloPay competes by embedding payment flows within Vietnam's dominant social messaging ecosystem.
An e-wallet is a software-based payment system that stores financial credentials on mobile or web platforms, employing tokenization, SSL encryption, and real-time fraud scoring to execute peer-to-peer transfers, bill settlements, and merchant purchases without physical card presentment. Its commercial purpose is to displace cash handling costs while capturing transaction data for credit underwriting and loyalty program targeting. Mobile Application platforms lead volume due to smartphone penetration rates exceeding fixed broadband access, while QR Code interfaces represent the fastest-growing technological platform as street vendors and informal merchants adopt zero-hardware acceptance. API Integration segments concentrate margin pools among enterprise clients requiring payroll disbursement and supply chain settlement automation.
The State Bank of Vietnam enforces licensing under Circular 23, mandating capital reserves and interoperability standards that filter out undercapitalized entrants. The country's national cybersecurity regulator imposes data localization requirements that shape cloud infrastructure decisions for foreign-invested platforms. Anti-money laundering protocols from the central bank extend KYC obligations to agent networks, raising compliance costs but deepening formal financial inclusion. Stakeholders must monitor whether the State Bank tightens foreign ownership caps in payment services as domestic champions scale toward profitability.
Market Dynamics
The State Bank of Vietnam's Circular 23 interoperability mandates are forcing e-wallet providers to dismantle closed-loop architectures and share transaction rails, compressing margins while accelerating formal financial inclusion across provincial agent networks.
Growth Catalysts
- Agent Network Density:Cash-in/cash-out infrastructure in Mekong Delta provinces and Central Highlands provinces is extending financial access to unbanked rural populations previously excluded from formal banking.
- QR Code Standardization:Vietnam's national QR code specification for retail payments is eliminating hardware costs for street vendors and informal merchants, collapsing barriers to merchant acceptance.
- Biometric Authentication Mandates:The State Bank of Vietnam's enhanced KYC protocols are driving liveness detection and facial recognition deployment across mobile onboarding flows, reducing identity fraud incidence.
Market Restraints
- Capital Reserve Requirements:Circular 23 mandates minimum paid-in capital thresholds for e-wallet licensing that filter out undercapitalized domestic entrants and raise barriers for foreign-invested platforms.
- Data Localization Compliance:Vietnam's cybersecurity framework requires domestic server deployment for transaction data storage, inflating cloud infrastructure costs for operators with regional technology stacks.
- Agent Network Oversight:Anti-money laundering protocols extend KYC obligations to provincial cash-in/cash-out agents, multiplying compliance audit costs across dispersed geographic footprints.
Strategic Opportunities
- Cross-Border Remittance Corridors:Vietnamese diaspora populations in Taiwan, South Korea, and Japan represent underpenetrated corridors for wallet-to-wallet international transfer services.
- Embedded Payroll Disbursement:Manufacturing and construction sector employers in Binh Duong and Dong Nai provinces are adopting API-integrated wage distribution to reduce cash handling security risks.
- Supply Chain Settlement Automation:Agricultural cooperatives in Mekong Delta provinces are piloting blockchain-anchored payment flows for rice and seafood export receivables financing.
Industry Challenges
- Interoperability Technical Debt:Legacy wallet architectures built on proprietary closed-loop systems require expensive middleware redevelopment to connect with national switching infrastructure.
- Fraud Detection Talent Scarcity:Real-time transaction monitoring and machine learning model development expertise concentrates in Ho Chi Minh City and Hanoi, constraining provincial platform expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam E-Wallet Market |
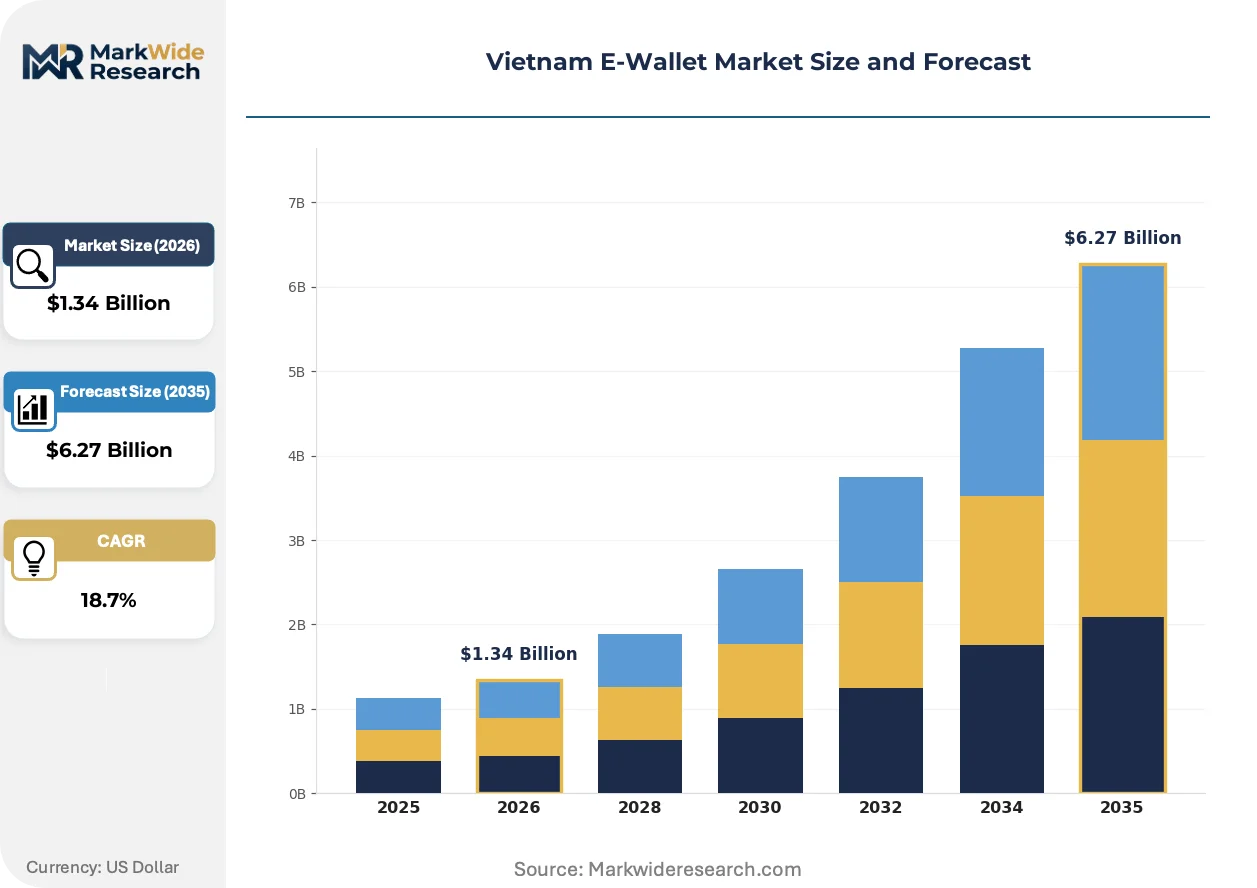
| Market Size in 2026 | $1.34 Billion |
| Market Size in 2035 | $6.27 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recharge, P2P Transfer, Bill Payment, Online Shopping Customer Type: Retail Consumers, Small Businesses, Corporates, Freelancers Technological Platform: Mobile Application, Web Application, API Integration, QR Code Security Measure: Two-Factor Authentication, Biometric Verification, Encryption, Fraud Monitoring |
| Companies Covered | ViettelPay, Vietcombank, MoMo, Grab Financial Group Vietnam, VietinBank Group, ZaloPay, ShopeePay, MOCA System Inc., VNPAY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam E-Wallet Market Strategic Shifts & Innovations
Biometric liveness detection, open banking API standardization, and social commerce payment embedding are converging to redefine trust architecture and transaction origination patterns across Vietnamese digital finance.
Tokenized payment credentials stored in secure enclaves are collapsing the distinction between device-native wallets and cloud-hosted alternatives. Smartphone manufacturers and chipset vendors are embedding hardware-backed key storage in mid-tier devices, enabling provincial consumers to authenticate high-value transfers without SMS one-time passwords. This hardware security module diffusion is compressing fraud liability exposure for issuers while accelerating merchant confidence in remote payment acceptance.
The State Bank of Vietnam's draft open banking framework is mandating standardized API access for account information and payment initiation services. Commercial banks must expose transaction history and balance inquiry endpoints to licensed third-party providers by specified implementation deadlines. This regulatory pressure is forcing incumbent financial institutions to restructure core banking architectures and negotiate data-sharing commercial terms with wallet operators that previously relied on screen-scraping integrations.
Social commerce payment flows are displacing standalone e-commerce checkout experiences as the dominant origination channel. Live-stream sellers on domestic platforms are embedding one-tap purchase buttons within video interfaces, collapsing the friction between product discovery and transaction completion. This behavioral shift concentrates payment volume within super-app ecosystems and challenges standalone wallet applications to embed themselves in content and communication platforms where purchase intent forms.
Vietnam E-Wallet Market Segmentation
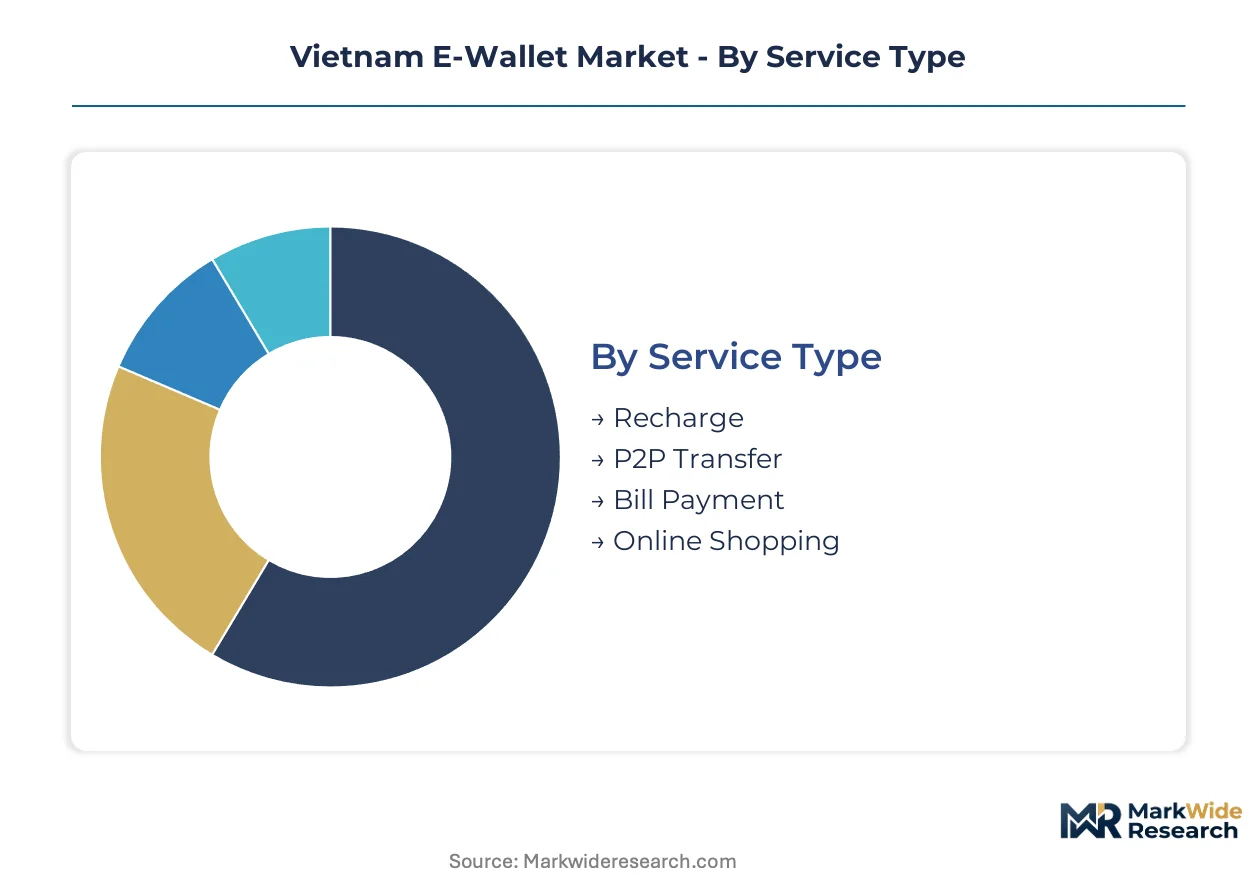
E-wallet providers in Vietnam design service architectures around distinct usage patterns and risk profiles. Each segment demands differentiated infrastructure investments, compliance protocols, and partnership strategies to capture transaction volume.
Service Type:
After-sales service intensity varies sharply across transaction categories, with dispute resolution and reconciliation support requirements scaling with transaction complexity and merchant involvement.
- Recharge:Cash-in operations through agent networks and linked bank accounts form the liquidity foundation for wallet ecosystems. Demand concentrates in Mekong Delta provinces where rural consumers rely on provincial agent density for digital financial access. The State Bank of Vietnam's agent oversight mandates raise operational compliance costs but deepen formal inclusion.
- P2P Transfer:Peer-to-peer flows enable informal economy settlements and family remittances between urban and rural households. Ho Chi Minh City and Hanoi users drive volume through salary sharing and informal lending circles. Interoperability mandates under Circular 23 are forcing cross-wallet compatibility that erodes proprietary network advantages.
- Bill Payment:Utility and telecommunications settlement interfaces aggregate recurring payment relationships. Electricity and water providers in provincial cities are integrating direct wallet connections to reduce cash collection logistics.
- Online Shopping:E-commerce checkout flows compete with cash-on-delivery through escrow and buyer protection features. Domestic marketplace platforms in fashion and electronics verticals are embedding native wallet options to reduce payment friction.
By volume, Recharge leads. By growth pace, Online Shopping is expanding most quickly.
Customer Type:
Margin structures diverge across customer categories, with enterprise relationships requiring dedicated integration engineering and account management that small business self-service models cannot support.
- Retail Consumers:Individual users executing daily transactions through smartphone applications represent the volume base for network effects. QR code adoption at street vendors across Ho Chi Minh City districts is collapsing cash dependency for food and transport purchases. Biometric KYC requirements are raising onboarding friction but reducing fraud losses.
- Small Businesses:Informal merchants and micro-enterprises adopt zero-hardware QR acceptance to displace cash handling risks. Central Highlands province vendors are accelerating adoption as provincial bank branches retreat from rural service.
- Corporates:Large employers in manufacturing and logistics sectors deploy API-integrated payroll disbursement to reduce cash security exposure. Binh Duong province electronics assemblers are piloting wallet-based wage distribution for migrant worker populations.
- Freelancers:Platform economy workers and gig operators require rapid settlement and cross-border receipt capabilities. Creative professionals in Hanoi are adopting wallet solutions for international client payments.
By volume, Retail Consumers lead. By growth pace, Small Businesses are gaining share fastest.
Technological Platform:
Platform selection determines capital intensity and geographic reach, with mobile-first architectures dominating where fixed broadband infrastructure remains underdeveloped.
- Mobile Application:Native smartphone interfaces leverage camera and biometric hardware for QR scanning and authentication. Smartphone penetration exceeding fixed-line access across Red River Delta provinces is concentrating transaction origination on mobile channels.
- Web Application:Browser-based access serves desktop-dependent corporate users and older demographics less comfortable with app installations. Enterprise accounting departments in Hanoi favor web dashboards for bulk payment authorization.
- API Integration:Direct system connections enable automated payroll, supply chain, and treasury operations. Agricultural cooperatives in Mekong Delta provinces are testing blockchain-anchored API flows for export receivables.
- QR Code:Static and dynamic code interfaces eliminate terminal hardware requirements for merchant acceptance. Vietnam's national QR specification is standardizing interoperability across bank and wallet platforms.
By volume, Mobile Application leads. By growth pace, QR Code is climbing the fastest.
Security Measure:
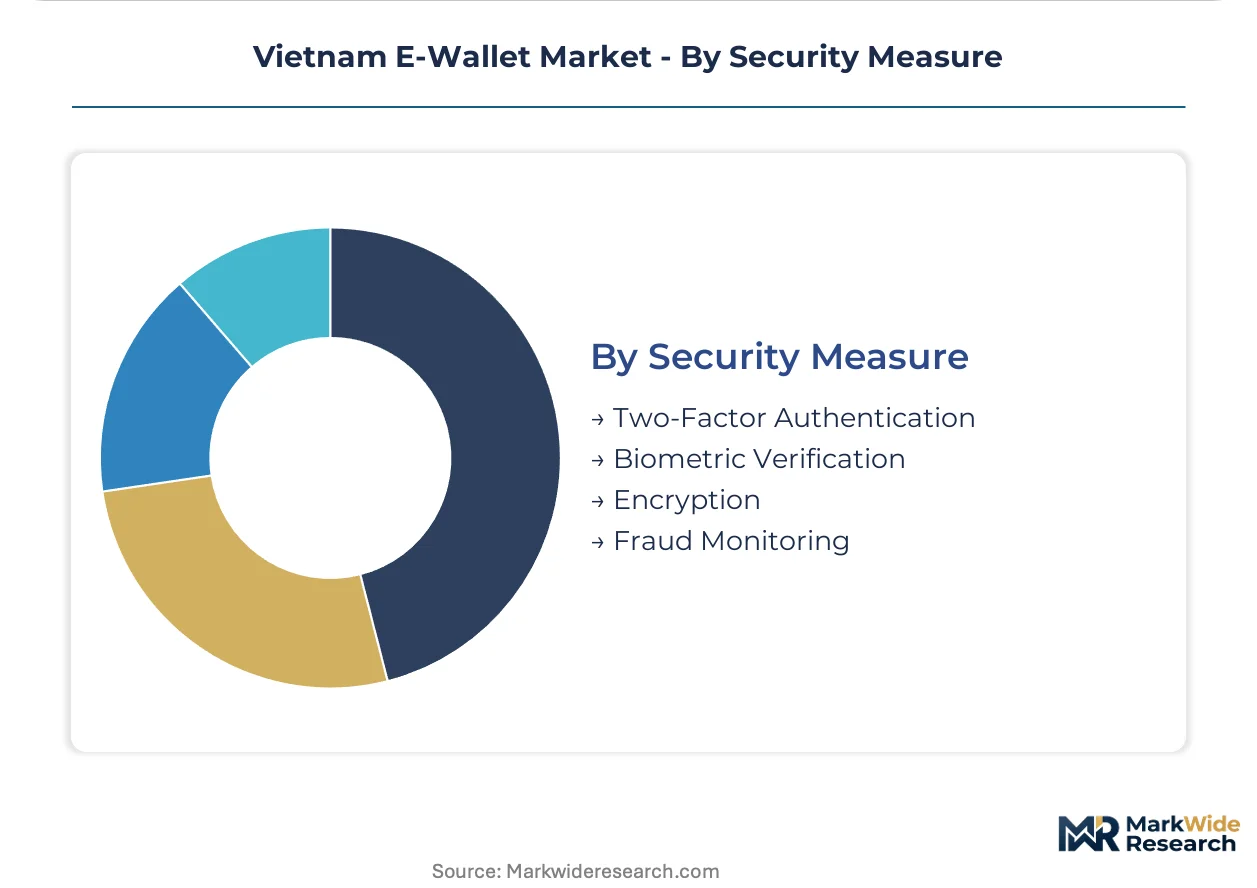
Authentication tier selection reflects transaction value thresholds and regulatory compliance requirements, with biometric mandates reshaping provider technology roadmaps.
- Two-Factor Authentication:SMS and email one-time passwords remain prevalent for low-value transactions and legacy user bases. Network reliability gaps in Central Highlands provinces create delivery failures that degrade user experience.
- Biometric Verification:Facial recognition and liveness detection satisfy enhanced KYC protocols for high-value transfers and account opening. The State Bank of Vietnam's mandates are accelerating deployment across provincial onboarding flows.
- Encryption:SSL and tokenization protocols protect credential transmission and storage. Data localization requirements are forcing domestic server deployment that inflates infrastructure costs.
- Fraud Monitoring:Real-time transaction scoring and machine learning models detect anomalous patterns. Talent scarcity in Ho Chi Minh City and Hanoi constrains model development for provincial platform expansion.
By volume, Two-Factor Authentication leads. By growth pace, Biometric Verification shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial merchant networks and urban consumer density drive adoption patterns across Vietnam's sub-regional markets. The State Bank of Vietnam's interoperability mandates reshape competitive dynamics differently across northern, central, and southern economic corridors.
Ho Chi Minh City
Street vendor QR acceptance and manufacturing payroll disbursement dominate transaction volume. The State Bank of Vietnam's Circular 23 compliance deadlines pressure wallet providers to restructure legacy architectures. Binh Duong and Dong Nai industrial zones anchor B2B payment automation for electronics assemblers and logistics operators.
Hanoi
Government salary distribution and creative freelancer payments concentrate demand in the capital region. Enhanced KYC protocols from the central bank accelerate biometric onboarding deployment. Hai Phong port corridor merchants are adopting zero-hardware acceptance for seafood export supply chain settlements.
Mekong Delta
Rural agent network density sustains cash-in/cash-out liquidity for unbanked agricultural households. Agent oversight mandates extend anti-money laundering audits across dispersed provincial footprints. Can Tho and Long An rice cooperatives pilot blockchain-anchored receivables financing for export shipments.
Central Highlands
Provincial bank branch retreat creates vacuum for mobile-first financial access among coffee and pepper farming communities. Data localization requirements force domestic server deployment that inflates infrastructure costs. Da Lat and Pleiku micro-enterprises accelerate QR adoption as formal banking presence contracts.
Vietnam E-Wallet Market Key Industry Players
Channel-controlling players compete with product-specialist players across Vietnam's e-wallet sector. The market structure concentrates around three domestic champions with bank-integrated or telecom-backed distribution networks. Strategic archetypes include agent-network operators, bank-integrated infrastructure providers, and super-app embedded payment layers. Dominant competitive moves encompass interoperability middleware redevelopment and biometric authentication platform deployment.
Among domestic champions, MoMo, VNPAY, and ZaloPay occupy distinct positioning vectors. MoMo exemplifies the agent-network archetype through provincial cash-in/cash-out density. VNPAY anchors bank-integrated QR infrastructure adoption among formal merchants. ZaloPay sits within the super-app embedded tier, leveraging Vietnam's dominant social messaging ecosystem for transaction origination.
| Leading Market Players |
|---|
| ViettelPay |
| Vietcombank |
| MoMo |
| Grab Financial Group Vietnam |
| VietinBank Group |
| ZaloPay |
| ShopeePay |
| MOCA System Inc. |
| VNPAY |
| Others |
Cost & Logistics Intelligence
The Hai Phong–Hanoi logistics corridor's rising freight costs are compressing margins for cloud infrastructure providers serving provincial e-wallet operators, forcing price differentiation between Ho Chi Minh City metro deployments and Central Highlands agent network coverage.
Pricing Analysis
Cost-plus contracts with quarterly cloud compute indexation dominate enterprise API integration pricing, separating bank-integrated infrastructure tiers from standalone wallet premiums. Biometric verification modules command higher rates due to liveness detection licensing fees from chipset vendors. Pricing pressure stems from Circular 23 interoperability mandates requiring middleware redevelopment. Small businesses show highest price sensitivity, while corporate payroll clients accept premium tiers for SLA guarantees.
Supply Chain Analysis
Upstream semiconductor feedstock for secure enclave chipsets draws from Taiwan, South Korea, and USA fabrication facilities. Facial recognition algorithm licensing hinges on Chinese and Israeli software houses. Domestic server assembly for data localization compliance rests on Chinese and Korean memory component imports. Single-source vulnerability concentrates in advanced node chipsets. Distribution runs through Ho Chi Minh City and Hanoi systems integrators to provincial agent networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards platforms that control scarce fraud detection engineering talent and dense agent network real estate, as both assets determine who can extend biometric KYC compliance to provincial Vietnam profitably.
For Market Incumbents: Build regulatory compliance moats through proactive Circular 23 middleware certification ahead of enforcement deadlines. Deepen vertical integration into biometric hardware security module distribution to capture chipset vendor margins. Threaten margin compression from ShopeePay's e-commerce checkout integration. Leverage captive agent audit infrastructure as a barrier to foreign-invested entrants facing AML oversight multiplication. For New Entrants and Emerging Players: Establish a beachhead in cross-border remittance corridors serving Vietnamese workers in Taiwan and South Korea, where incumbent agent network density offers no advantage. Target freelancer payment receipt as the most penetrable segment, with creative professionals in Hanoi showing willingness to switch for faster international settlement. Pursue API-first go-to-market partnerships with agricultural cooperatives in Mekong Delta provinces testing blockchain-anchored receivables. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with installed biometric authentication infrastructure that can absorb open banking API traffic without core system replacement. Long-term viability rests on who controls agent network economics as cash-in/cash-out formalizes. Watch for State Bank foreign ownership cap tightening as a signal to accelerate domestic champion consolidation. Acquisition targets should show provincial agent audit compliance systems already deployed.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Platform Deployment | Meets State Bank KYC mandates while collapsing fraud liability exposure for high-value transfers. |
| Interoperability Middleware Certification | Unlocks national switching infrastructure access before Circular 23 enforcement deadlines. |
| Agent Network Audit Automation | Reduces AML compliance cost per outlet across Mekong Delta and Central Highlands provinces. |
| Cross-Border Remittance Licensing | Captures Vietnamese diaspora flows from Taiwan, South Korea, and Japan corridors. |
| Open Banking API Integration | Positions for draft framework account information and payment initiation service mandates. |
Research Approach
A spread of perspectives from e-wallet platform CTOs, State Bank regulatory affairs officers, provincial agent network operators, and cloud infrastructure procurement leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against State Bank circulars, cybersecurity localization directives, and customs semiconductor import records. Bottom-up transaction volume modeling triangulated against top-down GDP financial inclusion proxies.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type, customer category, technological platform, and security authentication tier. CAGRs derived from S-curve adoption pattern fitting against smartphone penetration trajectories and QR merchant acceptance curves. Forecast inputs included Circular 23 implementation timeline assumptions and biometric hardware cost decline trajectories.
Stress conditions across central bank capital reserve tightening, foreign ownership restriction scenarios, and chipset supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on interoperability technical debt resolution pace and provincial agent network expansion feasibility. Cross-checking against State Bank payment system statistical bulletins is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Proximity Mobile Payment Market
Payments
Spain Real Time Payments Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
UAE Card Payments Market
Payments
US Buy Now Pay Later Services Market
Payments
GCC Payment Gateway Market
Payments
Portugal POS Terminals Market
Payments
Finland Payments Market
Payments
Spain Payments Market
Payments
B2B Payments Platform Market
Payments
Tanzania Mobile Money Market
Payments
India RTP Market
Payments
Europe Virtual Cards Market
Payments
Remote Deposit Capture Market
Payments
Cryptocurrency Payment Apps Market
Payments
Indonesia Mobile Payments Market