
 Global Telecom Billing Market | 2026-2036
Global Telecom Billing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecom Billing Market Foresight
Cloud-native architecture is fragmenting traditional monolithic billing stacks into microservices-based deployments. Amdocs leverages its extensive managed services footprint to sustain long-term operator relationships across North America and Europe. Oracle anchors its competitive position through deep database integration with enterprise-grade rating engines. Huawei Technologies dominates deployment scale across emerging Asian markets where cost-optimized infrastructure carries priority.
Telecom billing encompasses the software systems and operational processes that calculate usage charges, generate invoices, collect payments, and manage revenue recognition for communication service providers, typically processing billions of call detail records daily through real-time rating engines. Revenue Management and Fraud Management segments are capturing disproportionate investment as carriers confront subscription fraud and revenue leakage in 5G and IoT service layers. Cloud Computing and Artificial Intelligence technologies are displacing legacy on-premise installations, with machine learning-driven predictive analytics now embedded in leading payment processing and customer care workflows.
The Federal Communications Commission (FCC) enforces billing transparency rules in the United States, while the European Union's GDPR and the EU AI Act impose strict data governance and algorithmic accountability requirements on automated billing decisions. India's TRAI mandates itemized billing disclosure and tariff reporting standards that shape vendor product roadmaps for the subcontinent. Stakeholders must evaluate whether their platform architectures can absorb emerging regulatory mandates around AI explainability and cross-border data localization without forcing complete system replacement.
Market Dynamics
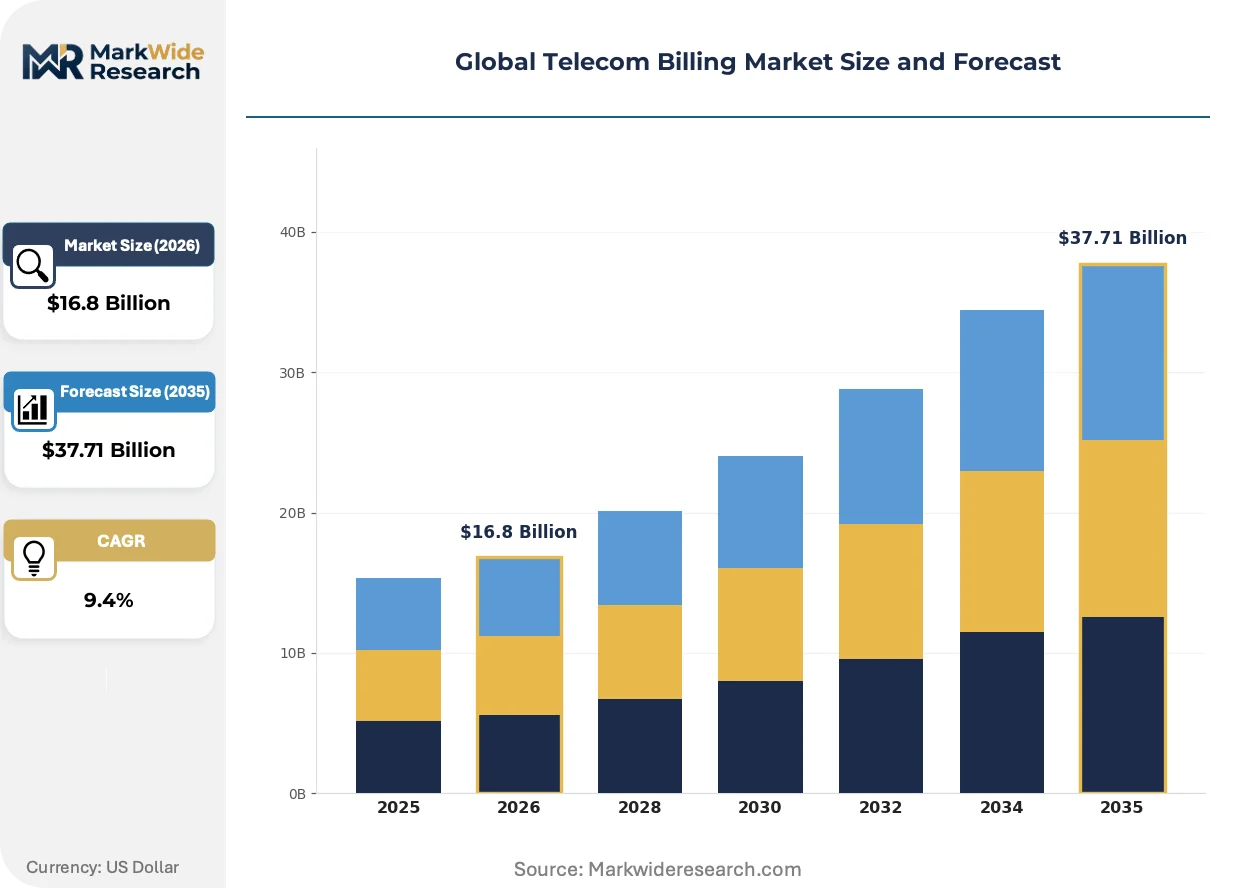
Cloud-native microservices architectures are dismantling monolithic billing stacks as carriers confront 5G service complexity and real-time rating demands. This structural shift forces vendors to reengineer deployment models while operators weigh migration costs against agility gains.
Growth Catalysts
- EU AI Act Compliance:European carriers face algorithmic accountability mandates for automated billing decisions, accelerating investment in explainable AI systems for revenue assurance.
- India TRAI Transparency Mandates:Itemized billing disclosure requirements for over one billion mobile subscribers are driving demand for granular usage analytics platforms.
- Real-Time 5G Rating Engines:Network slicing and dynamic QoS tiers require sub-second charging calculations that legacy batch systems cannot execute.
Market Restraints
- Legacy System Entrenchment:Decades-old COBOL-based billing cores in tier-one carriers resist cloud migration without multi-year parallel operation costs.
- Data Localization Requirements:Cross-border transaction processing faces friction from India's data protection rules and EU GDPR territorial scope limitations.
- Specialized Talent Scarcity:Shortage of engineers proficient in both telecommunications domain logic and Kubernetes orchestration constrains deployment velocity.
Strategic Opportunities
- Brazilian IoT Monetization:ANVISA-connected health devices and smart metering create greenfield billing requirements unencumbered by legacy infrastructure.
- Convergent AI-Blockchain Settlements:Immutable ledger technology paired with machine learning fraud detection enables automated inter-carrier reconciliation.
- Embedded Finance Integration:Telecom wallets and BNPL services transform billing platforms into full-stack financial service orchestrators.
Industry Challenges
- Multi-Vendor Integration Complexity:API fragmentation between charging engines, CRM systems, and payment gateways demands costly custom middleware development.
- Revenue Assurance Skill Gaps:Shortage of analysts capable of correlating network usage data with financial leakage patterns limits fraud detection effectiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecom Billing Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $37.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Billing Mediation, Revenue Management, Customer Care, Billing and Rating, Payment Processing, Fraud Management Technology: Artificial Intelligence, Machine Learning, Cloud Computing, Big Data Analytics, Blockchain, Edge Computing Application: Prepaid Services, Postpaid Services, Data Services, Roaming, Value-Added Services, Mobile Payments End User: Mobile Network Operators, Internet Service Providers, Fixed-Line Operators, Virtual Network Operators, Satellite Service Providers |
| Companies Covered | Amdocs, Oracle, Huawei Technologies, CSG Systems International, Cerillion Technologies, Comarch, SAP SE, Netcracker Technology, Telefonaktiebolaget LM Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecom Billing Market Shifts & Advancements
Machine learning is embedding predictive capabilities throughout the billing lifecycle, from usage forecasting to churn-triggered retention offers. This intelligence layer transforms billing from back-office cost center to strategic monetization engine.
Containerized microservices is rendering obsolete rigid on-premise billing monoliths that required six-month release cycles for tariff changes. Tier-two Asian carriers are adopting Kubernetes-orchestrated rating engines within twelve-month deployment windows. The shift collapses time-to-market for new service bundles from quarters to weeks.
GDPR and the EU AI Act impose algorithmic transparency requirements on automated credit scoring and payment routing decisions. European operators must now document training data lineage and model drift for billing AI. This regulatory pressure favors vendors with built-in explainability dashboards over black-box machine learning imports.
Enterprise procurement teams are consolidating vendor relationships from point-solution billing modules to full-stack revenue management suites. Carriers in Germany and France now issue RFPs spanning charging, collections, and partner settlement in single awards. This bundling trend squeezes standalone fraud management and mediation specialists.
Global Telecom Billing Market Segmentation
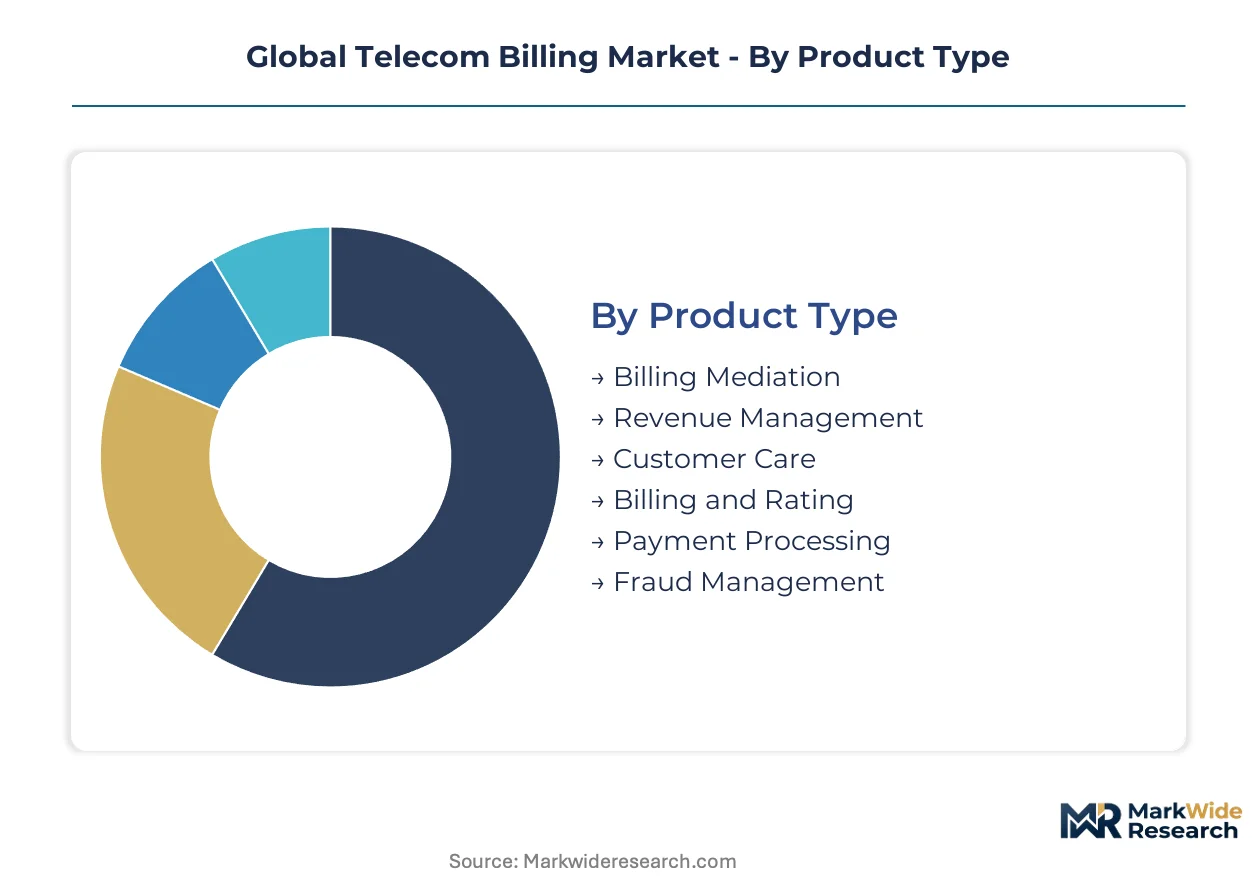
Telecom billing segmentation reveals how vendors architect revenue capture across divergent network technologies and customer engagement models. Each dimension exposes distinct integration complexity, regulatory exposure, and margin architecture that shapes procurement decisions.
Product Type:
After-sales service intensity varies dramatically across billing modules, with mediation and revenue assurance demanding continuous algorithmic tuning while payment processing requires 24/7 operational uptime guarantees.
- Revenue Management:Orchestrates rating, charging, and financial reconciliation across convergent service bundles. Indian operators under TRAI transparency mandates deploy granular usage analytics here to satisfy itemized disclosure requirements for prepaid and postpaid subscribers alike.
- Fraud Management:Deploys machine learning pattern recognition to detect subscription fraud, SIM-box arbitrage, and international revenue share bypass schemes. European carriers facing EU AI Act algorithmic accountability rules invest heavily in explainable detection models that document decision rationale for regulatory audit.
- Billing Mediation:Normalizes raw call detail records from heterogeneous network elements into standardized charging formats.
- Customer Care:Integrates billing inquiry resolution with churn prediction and retention offer orchestration.
- Billing and Rating:Executes real-time tariff calculation and balance management for prepaid accounts.
- Payment Processing:Manages multi-channel collections, dunning workflows, and payment gateway reconciliation.
By volume, Billing and Rating leads due to universal prepaid penetration. By growth pace, Fraud Management is ahead as 5G and IoT attack surfaces expand.
Technology:
Cost tier stratification separates commodity cloud infrastructure from premium AI/ML layers that command implementation fees and ongoing model retraining contracts.
- Artificial Intelligence:Powers predictive churn scoring, dynamic pricing optimization, and automated revenue leakage detection. German and French operators now require explainable AI documentation for credit scoring algorithms under GDPR automated decision-making rules.
- Cloud Computing:Delivers elastic compute for rating engines and distributed data storage for call detail record archives. Tier-two Asian carriers adopt Kubernetes-orchestrated deployments to collapse tariff change cycles from quarters to weeks.
- Machine Learning:Embedded in usage forecasting and anomaly detection workflows with continuous model retraining pipelines.
- Big Data Analytics:Processes petabyte-scale usage patterns for customer segmentation and network planning correlation.
- Blockchain:Enables immutable inter-carrier settlement records and automated roaming charge reconciliation.
- Edge Computing:Deploys localized rating functions for ultra-low latency 5G network slicing scenarios.
By deployment scale, Cloud Computing dominates new installations. By investment intensity, Artificial Intelligence commands the steepest expansion trajectory.
Application:
Customer type divergence splits between high-touch postpaid account management and high-volume prepaid automation with divergent margin profiles.
- Data Services:Manages tiered data allowances, zero-rating partnerships, and fair usage policy enforcement. Indian operators process over one billion subscriber data charges under TRAI-mandated transparency frameworks that require granular usage disclosure.
- Mobile Payments:Transforms billing platforms into financial service orchestrators spanning wallets, remittances, and BNPL offerings. Brazilian operators leverage greenfield infrastructure to embed ANVISA-connected health device payments without legacy constraint.
- Prepaid Services:Real-time balance management and recharge facilitation for pay-as-you-go accounts.
- Postpaid Services:Monthly invoice generation, credit risk scoring, and collections workflow management.
- Roaming:Inter-carrier settlement, wholesale rate management, and fraud detection for international usage.
- Value-Added Services:Third-party content billing, subscription management, and revenue sharing.
By subscriber count, Prepaid Services leads. By revenue per user expansion, Mobile Payments is gaining share fastest.
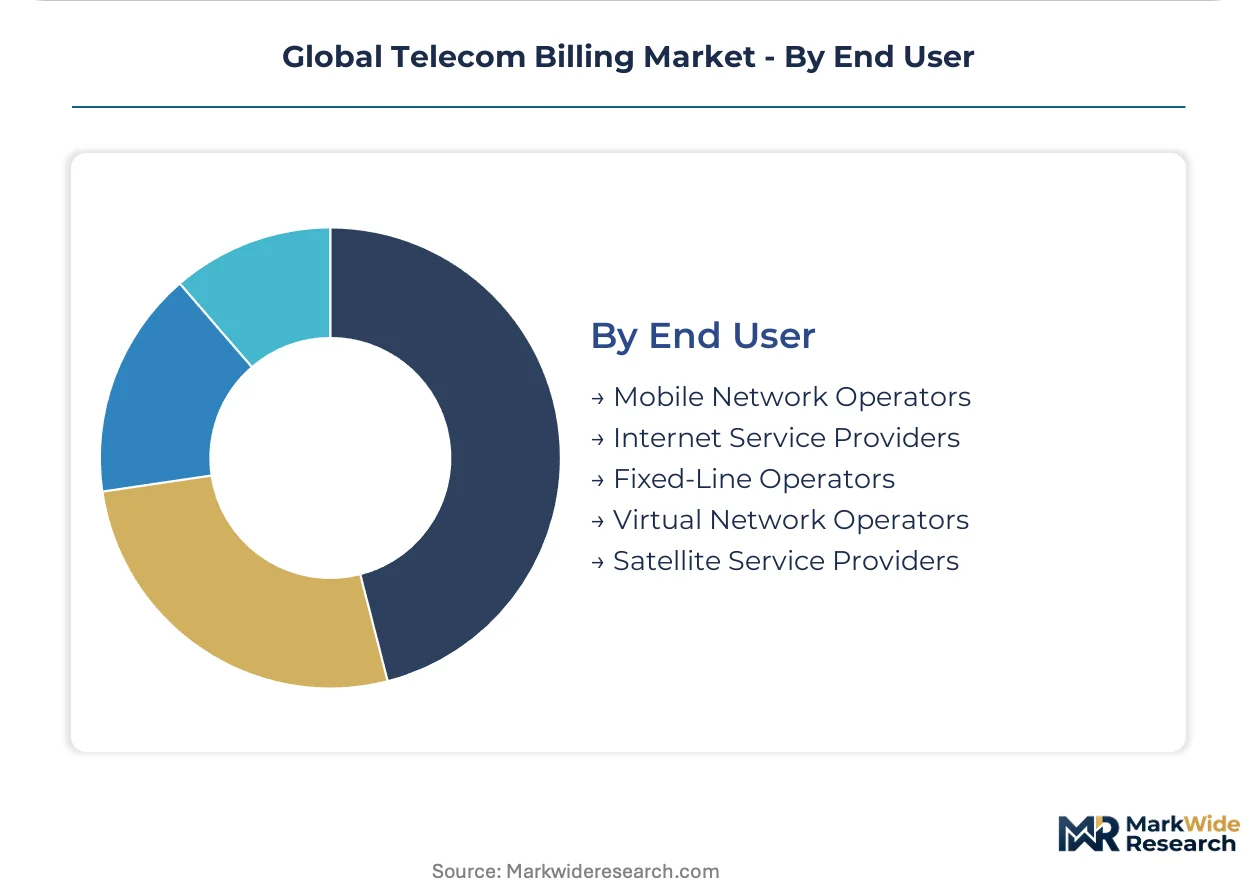
End User:
Supply concentration clusters around Mobile Network Operators that consolidate procurement across convergent billing suites, squeezing standalone specialists.
- Mobile Network Operators:Drive platform requirements through 5G network slicing complexity and IoT monetization demands. Tier-one carriers in Germany and France now issue unified RFPs spanning charging, collections, and partner settlement in single awards.
- Internet Service Providers:Require convergent billing for fixed-mobile bundles and bandwidth tier management.
- Fixed-Line Operators:Legacy copper and fiber billing with declining voice revenue and growing broadband emphasis.
- Virtual Network Operators:Wholesale-dependent business models requiring lean, cloud-native billing with minimal capex.
- Satellite Service Providers:Emerging low-earth orbit constellations demand real-time usage rating for global mobility services.
By platform spend, Mobile Network Operators lead. By adoption velocity, Virtual Network Operators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports telecom billing software development and managed services to European and North American carriers modernizing revenue assurance platforms for 5G monetization. Cloud-native deployment expertise flows from Indian IT hubs into German and French operator procurement cycles.
United States
FCC billing transparency rules and 5G network slicing complexity drive carrier investment in real-time rating engines. Tier-one operators in Dallas and Atlanta run parallel COBOL-core and cloud-native systems during multi-year migrations. Seattle-based cloud infrastructure specialists supply Kubernetes orchestration layers to accelerate deployment velocity.
Germany
GDPR automated decision-making rules and EU AI Act algorithmic accountability mandates reshape procurement specifications for revenue assurance systems. Deutsche Telekom and Vodafone Germany issue unified RFPs spanning charging, collections, and partner settlement. Munich and Frankfurt clusters host vendor engineering centers serving Central European operator requirements.
India
TRAI itemized billing disclosure mandates for over one billion mobile subscribers create demand for granular usage analytics platforms. Jio and Bharti Airtel deploy cloud-native mediation engines to process prepaid and postpaid data charges. Bengaluru and Hyderabad development centers export billing platform customization to Middle Eastern and African carriers.
Brazil
ANVISA-connected health devices and smart metering create greenfield IoT billing requirements without legacy infrastructure constraints. TIM and Vivo embed telecom wallets and BNPL services into billing platforms. São Paulo fintech clusters collaborate with operators on financial service orchestration capabilities.
Japan
METI digital transformation directives and 5G standalone network rollouts accelerate replacement of batch-process billing systems. NTT Docomo and SoftBank deploy edge-computing rating functions for ultra-low latency service tiers. Tokyo and Osaka vendor partnerships focus on AI-driven churn prediction and dynamic pricing optimization.
Global Telecom Billing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where full-stack revenue management suites squeeze standalone fraud and mediation modules. North American and European carriers consolidate procurement relationships, reducing vendor counts from point-solution portfolios to integrated platforms. Two archetypes dominate: database-anchored enterprise software houses with deep telco verticalization, and cloud-native specialists winning greenfield Asian and Latin American deployments. Competitive moves center on M&A absorption of AI/ML analytics startups and strategic partnerships embedding billing into hyperscaler cloud marketplaces.
Within the enterprise software tier, Oracle and SAP SE occupy positions anchored by database integration and ERP ecosystem lock-in. Amdocs exemplifies the managed-services archetype sustaining long-term operator relationships through outsourcing contracts spanning North America and Europe. Huawei Technologies sits within the scale-driven emerging-market tier, dominating cost-optimized infrastructure deployment across Asian geographies where procurement prioritizes capital efficiency over incumbent vendor continuity.
| Leading Market Players |
|---|
| Amdocs |
| Oracle |
| Huawei Technologies |
| CSG Systems International |
| Cerillion Technologies |
| Comarch |
| SAP SE |
| Netcracker Technology |
| Telefonaktiebolaget LM Ericsson |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud-native billing platform development across Indian IT hubs is compressing implementation margins while accelerating vendor competition for European and North American operator contracts. This utilization dynamic rewards buyers with negotiating leverage on SaaS tiers while forcing suppliers toward outcome-based pricing models that tie fees to revenue assurance performance.
Pricing Analysis
Legacy COBOL-core maintenance commands premium pricing against collapsing cloud-native deployment costs as tier-two Asian carriers drive commoditization of containerized rating engines. Three-tier pricing structure across premium, standard, and economy levels separates Oracle's database-anchored enterprise suites from Amdocs managed-service bundles and Huawei's cost-optimized emerging-market offerings. Cost compression in standard-tier SaaS subscriptions is intensifying because Kubernetes orchestration expertise is proliferating beyond traditional telecom vendor bases. Virtual Network Operators exhibit highest price sensitivity due to wholesale-dependent margins, while tier-one Mobile Network Operators prioritize integration depth over unit cost.
Supply Chain Analysis
Systems integration capacity concentrates among Bengaluru and Hyderabad development centers serving global carrier modernization programs, with Frankfurt and Munich engineering hubs anchoring EU AI Act compliance customization. Platform development draws from open-source Kubernetes distributions, proprietary database licenses, and machine learning training pipelines sourced from hyperscaler marketplaces. Single-source vulnerability in AI/ML model training data creates regulatory audit exposure under GDPR automated decision-making rules. Distribution runs through direct vendor-operator procurement relationships for tier-one carriers, with channel partners and systems integrators penetrating mid-market Virtual Network Operator segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telecom billing is transitioning from perpetual license hardware attach to recurring-revenue SaaS models where revenue assurance algorithm tuning and continuous fraud model retraining expand faster than core charging engine deployments.
For Market Incumbents: Build switching-cost moats through deep ERP integration and managed services outsourcing contracts that embed Amdocs-style long-term operator relationships. Defensive consolidation should absorb AI/ML analytics specialists to fortify explainable AI capabilities for EU AI Act compliance. Capacity addition in Indian development centers sustains cost competitiveness against emerging cloud-native challengers. For New Entrants and Emerging Players: Build out greenfield IoT monetization platforms for Brazilian health device and smart metering verticals where ANVISA regulations create billing requirements unencumbered by legacy COBOL cores. White-space concentration in Virtual Network Operator segments offers fastest penetration due to minimal capex thresholds and cloud-native procurement preferences. Go-to-market positioning through hyperscaler marketplace listings reduces enterprise sales cycle friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fraud management and revenue assurance specialists where continuous algorithmic tuning mandates ongoing service contracts. Long-term viability over the coming decade favors vendors with embedded finance orchestration capabilities transforming billing platforms into full-stack financial service engines. Monitor TRAI enforcement intensity in India as signal for granular usage analytics platform demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI/ML Analytics Specialist | Fortifies explainable AI documentation capabilities for EU AI Act algorithmic accountability mandates. |
| Hyperscaler Cloud Marketplace Listing | Accelerates Virtual Network Operator penetration through pre-integrated Kubernetes deployment templates. |
| Embedded Finance Capability Buildout | Transforms billing platforms into BNPL and telecom wallet orchestrators per Brazilian fintech collaboration models. |
| Indian Development Center Expansion | Captures TRAI-mandated transparency engineering demand while serving Middle Eastern and African carrier exports. |
| Blockchain Settlement Integration | Enables automated inter-carrier reconciliation for 5G roaming and IoT revenue sharing complexity. |
Research Methodology
A spread of perspectives from chief technology officers at tier-one Mobile Network Operators, revenue assurance directors, systems integration architects, and procurement leads at Virtual Network Operators converged on the working assumptions shaping this analysis. Primary interview insights were validated against secondary sources including FCC enforcement actions, TRAI tariff reporting databases, EU AI Act implementation guidance, and SEC filings from publicly traded billing vendors. Bottom-up segmentation modeling and top-down market sizing triangulated on volume and value estimates.
Demand-supply balance framing anchored the forecast framework across the analysis window, with segmentation dimensions spanning product type, deployment technology, application layer, and end-user archetype. CAGRs were derived from weighted growth projections across these dimensions, incorporating 5G network slicing complexity, IoT device proliferation rates, and regulatory compliance investment intensity as industry-specific inputs.
Sensitivities concentrate around EU AI Act enforcement timing, TRAI transparency mandate implementation rigor, and legacy COBOL migration velocity at tier-one carriers. Quarterly review of operator RFP bundling patterns, hyperscaler marketplace transaction volumes, and fraud management venture funding levels is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Mexico Payments Market
Payments
Online Charging System (OCS) Market
Payments
China Real Time Payments Market
Payments
United Kingdom Payment Market
Payments
Biometric Payment Cards Market
Payments
Italy POS Terminals Market
Payments
Global Accounts Payable Automation Market
Payments
Direct Carrier Billing Market
Payments
India Mobile Payments Market
Payments
United Arab Emirates Payment Market
Payments
Digital Money Transfer Market
Payments
South Korea Digital Payments Market
Payments
China Payment Gateway Market
Payments
In-Vehicle Payment Services Market
Payments
Europe Virtual Cards Market
Payments
Australia Mobile Payment Market