
 Tea-Based Skin Care Products Market | 2026-2036
Tea-Based Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Tea-Based Skin Care Products Market Analytics
The EU Green Deal is pivoting European cosmetic procurement toward plant-derived, low-carbon ingredient sourcing. Amorepacific anchors its competitive position through captive green tea plantations in Jeju Island. L'Oréal S.A. extends its R&D network across multiple botanical extraction centers. Unilever dominates mass-market tea-infused cleansers through controlled retail distribution in Asia-Pacific.
Tea-based skin care products incorporate concentrated polyphenol extracts, typically standardized to epigallocatechin gallate content between 50% and 98%, formulated into topical delivery systems for antioxidant and anti-inflammatory action. Green tea serums lead ingredient innovation due to higher catechin stability in lipid-based carriers, while moisturizers occupy the largest volume position across mass and prestige channels. Anti-aging applications concentrate margin pools as consumers pay premiums for clinically substantiated wrinkle-reduction claims.
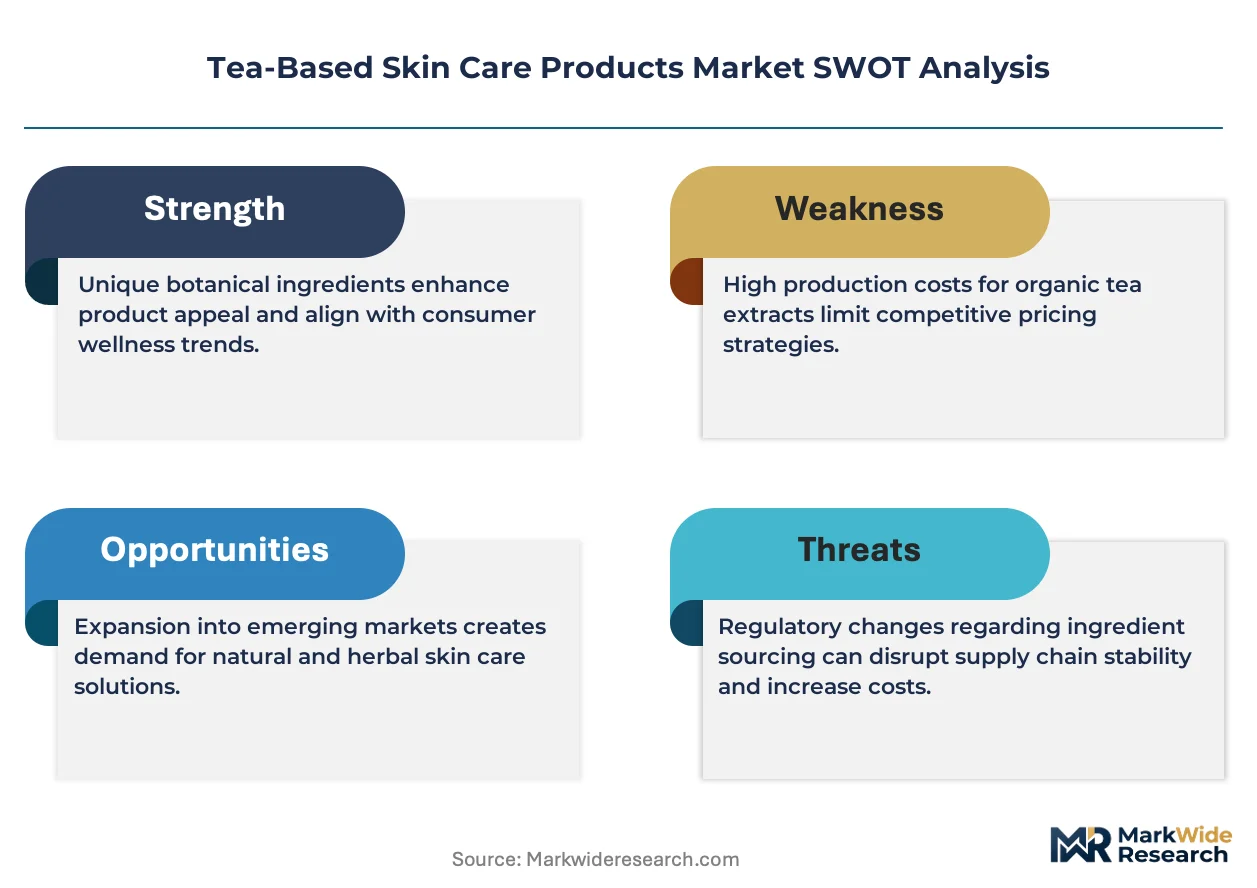
EMA cosmetic guidelines, REACH chemical safety protocols, and FDA cosmetic labeling rules collectively tighten ingredient disclosure and substantiation requirements. These frameworks elevate compliance costs for smaller brands while rewarding enterprises with pre-validated botanical supply chains. Stakeholders must monitor evolving bioprospecting regulations that could restrict wild-harvested tea extract sourcing.
Market Dynamics
Polyphenol stabilization technology is concentrating competitive advantage among suppliers with proprietary lipid-encapsulation capabilities, forcing mid-tier brands toward contract manufacturing partnerships.
Growth Catalysts
- EU REACH chemical safety protocols:Ingredient disclosure mandates accelerate consumer trust in certified organic tea extracts. Reformulation investments by European brands create premium positioning opportunities.
- Green tea catechin stability in lipid-based carriers:Advanced encapsulation extends shelf life and bioavailability. Korean and Japanese formulators lead adoption of this delivery technology.
- Young urban consumers in Seoul and Tokyo:Social media-driven trial rates for serum-essence routines outpace traditional moisturizer categories. Influencer education compresses adoption cycles for multi-step regimens.
Market Restraints
- Epigallocatechin gallate raw material volatility:Concentration requirements between 50% and 98% standardization create input cost pressure. Climate sensitivity of Camellia sinensis harvests amplifies price swings.
- Captive plantation concentration in Jeju Island:Single-source dependency for premium green tea extract creates supply vulnerability. Alternative sourcing regions lack equivalent polyphenol profiles.
- Clinical substantiation requirements:Anti-aging wrinkle-reduction claims demand dermatological testing. Smaller brands face capital barriers to evidence generation.
Strategic Opportunities
- Underpenetrated brightening treatment demand in India:Premium mask adoption lags East Asian penetration rates. Localized marketing around turmeric-tea ingredient stories could accelerate trial.
- EU Green Deal plant-derived procurement mandates:Low-carbon ingredient sourcing preferences reward tea extract suppliers with verified carbon footprints. Certified organic positioning aligns with public procurement criteria.
- Direct-to-consumer subscription channels:Serum replenishment models bypass traditional retail margin structures. Personalized skin assessment tools drive recurring revenue capture.
Industry Challenges
- Botanical extraction talent scarcity:Phytochemistry expertise for polyphenol preservation commands premium compensation. Universities produce fewer specialists than formulation demand requires.
- Bioprospecting permit timelines:Wild-harvested tea genetic material faces expanding access-and-benefit-sharing documentation. Sourcing teams navigate multi-year approval processes for novel cultivars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea-Based Skin Care Products Market |
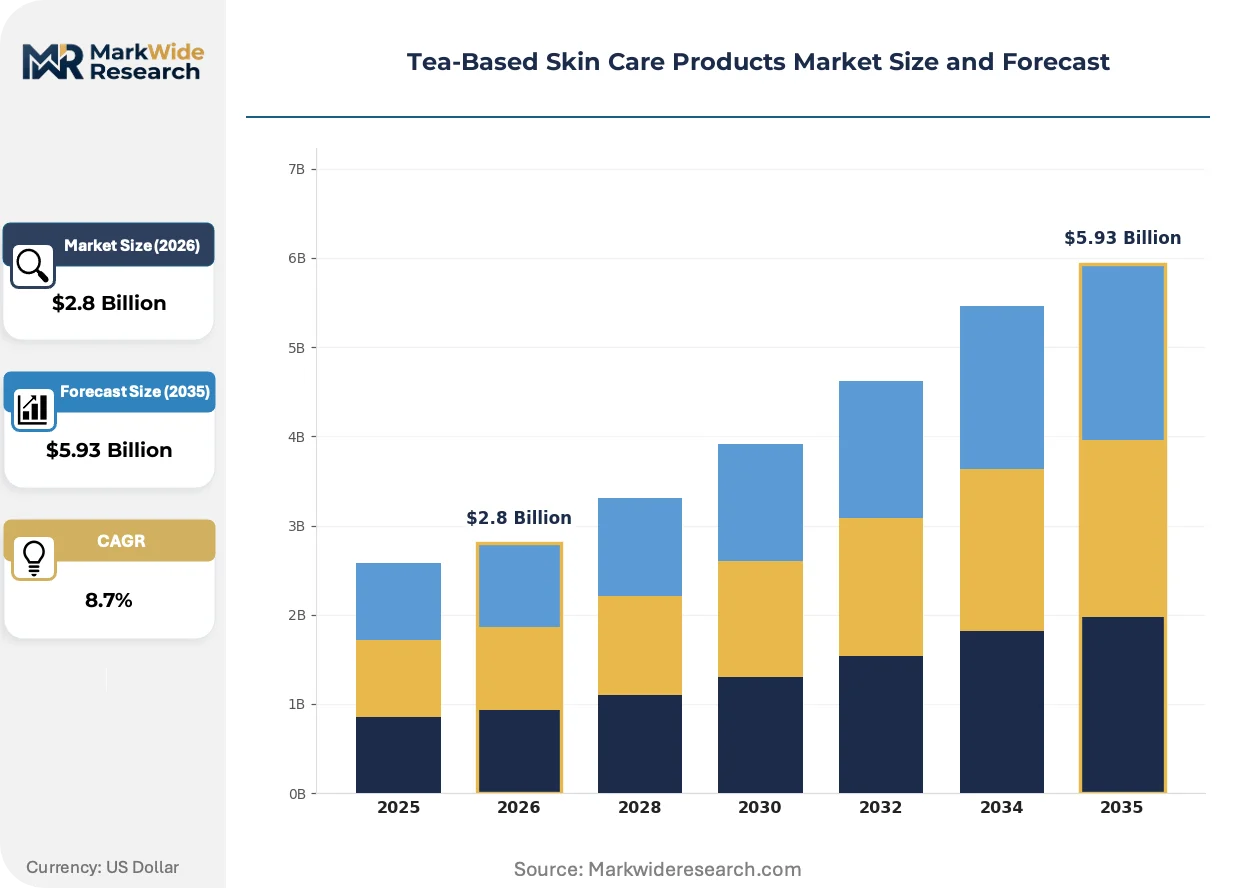
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Cleansers, Masks Ingredient Type: Green Tea, Black Tea, Herbal Extracts, White Tea Application: Anti-Aging, Hydration, Brightening, Sun Protection End User: Women, Men, Teens, Sensitive Skin |
| Companies Covered | Amorepacific, L'Oréal S.A., Unilever, Natura &Co, The Body Shop, 100% PURE, ORGANIC TEA COSMETICS, Avon, Lu Ming Tang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea-Based Skin Care Products Market Evolving Landscape
Lipid nanocarrier technology is compressing formulation timelines while elevating efficacy substantiation standards across prestige and mass channels.
Nanoliposome encapsulation systems are rewriting how epigallocatechin gallate reaches dermal layers. Prestige serum manufacturers in South Korea and Japan deploy this technology to justify 40-60% price premiums over conventional extracts. The structural consequence compresses R&D cycles for clinical claim validation while raising barriers for brands without co-development partnerships with specialized biotech suppliers.
EMA cosmetic guidelines on ingredient safety dossiers tighten documentation requirements for botanical extracts. European manufacturers must demonstrate batch-to-batch polyphenol consistency through chromatographic fingerprinting. Anti-aging serum categories face the steepest compliance investments, driving consolidation among brands with pre-validated supply chains.
Subscription-based replenishment models displace traditional retail discovery for core serum categories. Direct-to-consumer platforms capture recurring revenue from urban professionals in Seoul, Shanghai, and Mumbai who prioritize convenience over in-store sampling. This channel shift concentrates customer data ownership with vertically integrated brands, enabling predictive inventory and personalized formulation matching.
Tea-Based Skin Care Products Market Segmentation
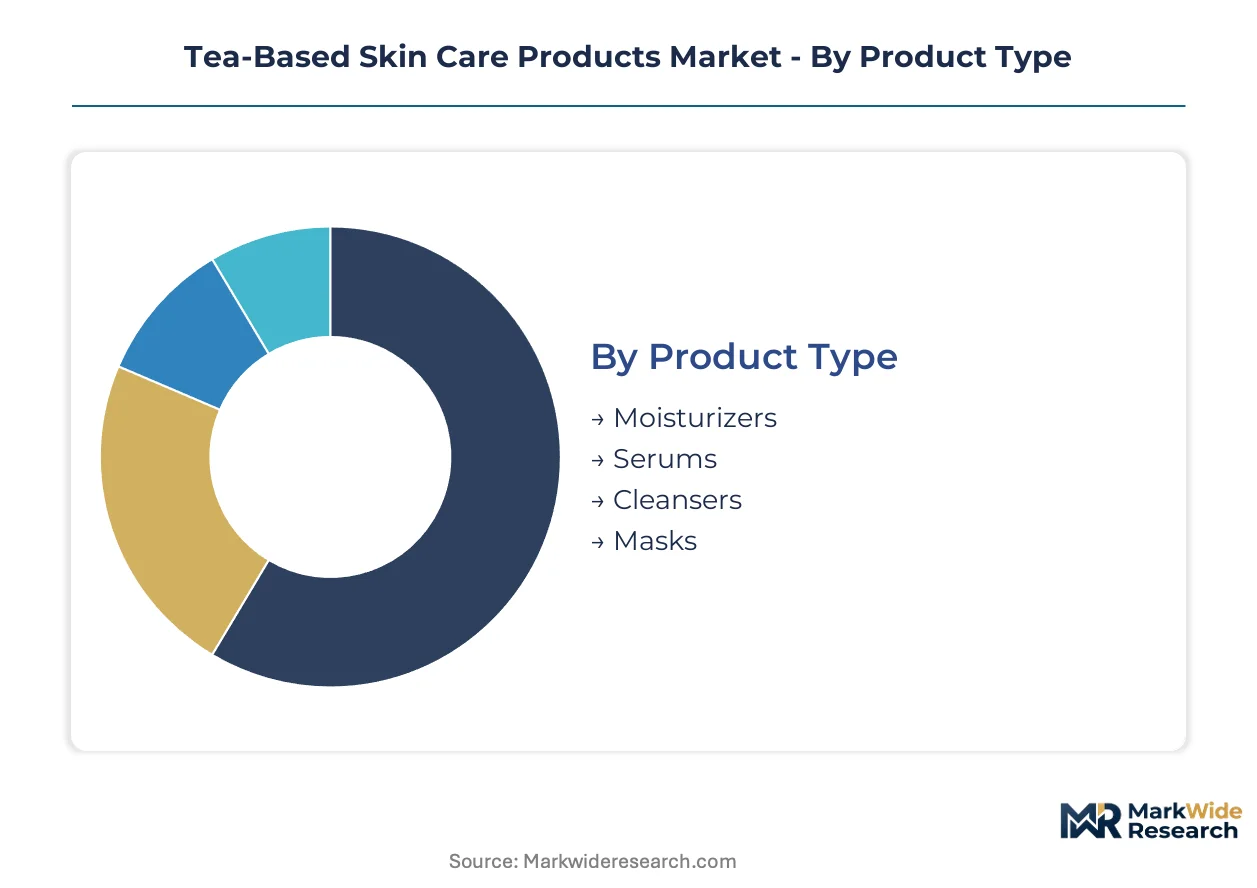
Polyphenol concentration and delivery format determine margin capture across tea-based skin care. Formulators segment offerings by bioactive standardization levels, vehicle chemistry, and targeted dermal action to align with divergent consumer willingness to pay for clinical substantiation.
Product Type:
Lipid-based carrier compatibility varies sharply across topical formats, concentrating R&D investment where epigallocatechin gallate stability can be engineered.
- Serums:High-concentration polyphenol formulations in lipid nanocarrier systems deliver enhanced dermal penetration. Demand concentrates in Seoul and Tokyo among young urban consumers pursuing multi-step regimens with clinically substantiated wrinkle-reduction claims.
- Moisturizers:Emulsion-based delivery systems accommodate broader catechin concentration ranges while maintaining shelf stability. Volume leadership across mass and prestige channels reflects lower price elasticity and routine replenishment behavior in Shanghai and Mumbai.
- Cleansers:Rinse-off formats limit polyphenol residence time on skin, favoring lower-cost extract grades.
- Masks:Occlusive delivery vehicles enable higher single-dose polyphenol loading for intensive treatment positioning.
Mature deployment sits with Moisturizers. Newer deployment is concentrated in Serums.
Ingredient Type:
Camellia sinensis cultivar selection and harvest timing create distinct polyphenol fingerprints that brands leverage for premium positioning.
- Green Tea:Epigallocatechin gallate concentrations between 50% and 98% standardization anchor antioxidant claims. Jeju Island captive plantations supply premium extracts, though climate sensitivity creates raw material volatility that amplifies price swings.
- Black Tea:Oxidation-derived theaflavins offer alternative antioxidant mechanisms with distinct sensorial profiles. Formulators in India and China deploy black tea extracts for brightening treatment lines targeting underpenetrated mask demand.
- Herbal Extracts:Non-Camellia botanicals including rooibos and chamomile expand polyphenol diversity for sensitive skin positioning.
- White Tea:Minimal processing preserves catechin profiles with lower tannin content, supporting gentle formulation claims.
Volume concentration remains with Green Tea. Steepest expansion trajectory is occurring in Black Tea as regional formulators develop localized ingredient stories.
Application:
Clinical claim requirements and margin pools diverge sharply across dermatological benefit categories.
- Anti-Aging:Wrinkle-reduction claims demand dermatological testing and batch-to-batch polyphenol consistency documentation under EMA cosmetic guidelines. European and East Asian prestige brands concentrate investment here, absorbing compliance costs that exclude smaller competitors.
- Brightening:Tyrosinase inhibition claims from tea polyphenols drive mask and serum development for India and China markets. Localized marketing around turmeric-tea combinations accelerates trial in underpenetrated regions.
- Hydration:Barrier support claims require less stringent substantiation, supporting mass-market volume positioning.
- Sun Protection:Photoprotective polyphenol action remains secondary to SPF ratings, limiting standalone positioning.
Margin capture peaks with Anti-Aging. Brightening applications are gaining share fastest among emerging market entrants.
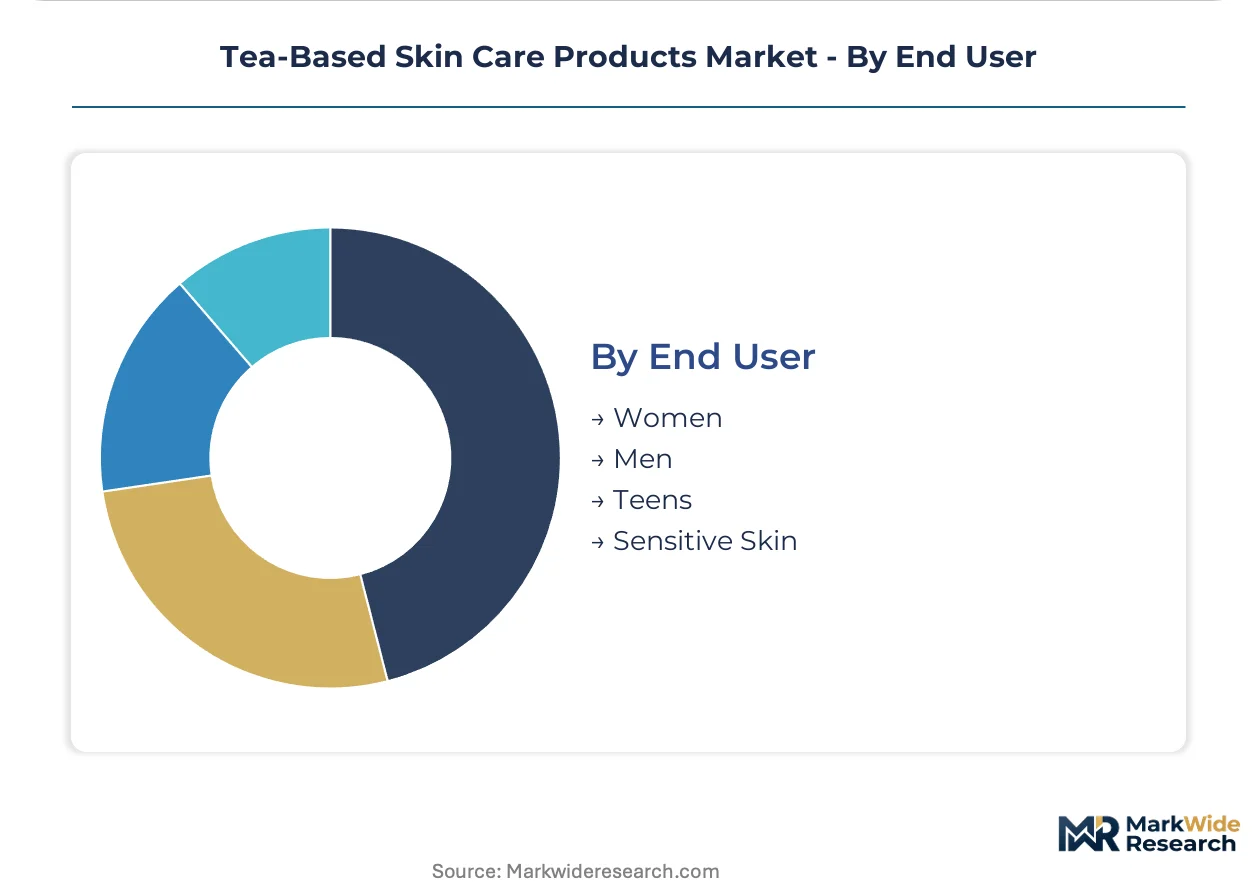
End User:
Skin sensitivity profiles and regimen complexity preferences segment addressable demand across demographic and physiological dimensions.
- Women:Core addressable market for multi-step serum-essence routines with premium polyphenol concentrations. Subscription replenishment models in Seoul, Shanghai, and Mumbai capture recurring revenue through personalized skin assessment tools.
- Sensitive Skin:Formulation requirements for reduced irritant loads command premium positioning. White tea and herbal extract bases support clean beauty claims with verified carbon footprints under EU Green Deal procurement criteria.
- Men:Simplified regimen preferences favor cleanser-moisturizer combinations over complex serum layering.
- Teens:Price-sensitive entry point for basic hydration and oil-control positioning with lower polyphenol standardization.
Established revenue concentration sits with Women. Emerging formulation investment targets Sensitive Skin as regulatory disclosure mandates elevate trust in certified organic extracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the highest per-capita consumption of multi-step tea-infused regimens, with Apgujeong and Gangnam districts driving serum-essence trial rates through dermatologist clinic partnerships.
South Korea
Young urban consumers in Seoul and Busan compress adoption cycles for green tea catechin serums through social media-driven education. MFDS cosmetic safety dossiers mandate batch-to-batch polyphenol consistency documentation. Jeju Island's captive Camellia sinensis plantations supply premium epigallocatechin gallate extracts, though climate sensitivity creates raw material volatility.
Japan
Tokyo's Shibuya and Shinjuku districts concentrate demand for lipid-encapsulated green tea formulations with clinically substantiated wrinkle-reduction claims. METI standards on cosmetic ingredient labeling accelerate reformulation toward certified organic tea extracts. Osaka-based formulators lead nanoliposome delivery technology adoption for prestige serum categories.
China
Shanghai and Beijing urban professionals drive premium mask demand for brightening treatments combining tea polyphenols with localized ingredient stories. NMPA cosmetic registration requirements tighten botanical extract documentation, elevating compliance costs for smaller brands. Hangzhou's biotech clusters develop proprietary lipid-encapsulation capabilities for domestic serum manufacturers.
India
Mumbai and Delhi consumers represent underpenetrated brightening treatment demand, with turmeric-tea combination marketing accelerating trial in premium mask categories. BIS cosmetic standards on ingredient disclosure align with rising consumer trust in certified organic positioning. Bangalore's contract manufacturing hubs expand polyphenol extraction capacity for regional brands.
Germany
Berlin and Munich consumers pivot procurement toward plant-derived, low-carbon ingredient sourcing under EU Green Deal mandates. REACH chemical safety protocols and EMA cosmetic guidelines collectively tighten epigallocatechin gallate documentation requirements. Hamburg's botanical extraction specialists develop verified carbon footprint certification for tea extract suppliers.
Tea-Based Skin Care Products Market Competitive Landscape
The competitive structure tilts toward vertically integrated plantation holders and multinational R&D networks. Mid-tier brands face consolidation pressure from proprietary lipid-encapsulation technology scarcity. Three archetypes dominate: captive plantation operators with Jeju-sourced supply control, mass-market distributors with Asia-Pacific retail density, and prestige formulators with nanocarrier co-development partnerships. M&A activity concentrates on biotech suppliers with polyphenol stabilization patents, while geographic expansion targets India's underpenetrated brightening segment.
Within the captive plantation tier, Amorepacific anchors supply security through Jeju Island green tea operations. L'Oréal S.A. and Unilever occupy positions spanning prestige R&D networks and mass-market retail distribution respectively. These three exemplify divergent strategic paths: backward integration into raw material control, multi-hub botanical extraction investment, and channel dominance through replenishment infrastructure. Smaller specialists including 100% PURE and ORGANIC TEA COSMETICS sit within certified organic positioning archetypes, competing on transparency credentials rather than scale.
| Leading Market Players |
|---|
| Amorepacific |
| L'Oréal S.A. |
| Unilever |
| Natura &Co |
| The Body Shop |
| 100% PURE |
| ORGANIC TEA COSMETICS |
| Avon |
| Lu Ming Tang |
| Others |
Value Network & Pricing Analysis
Phytochemistry specialists concentrated in South Korea's Jeju Island and Japan's Osaka prefecture command premium compensation that widens spreads between prestige serum tiers and mass-market moisturizer positioning. Labor-cost differentials between these extraction hubs and contract manufacturing zones in China's Hangzhou and India's Bangalore feed directly into three-tier pricing stratification across certified organic, conventional extract, and basic cleanser grades.
Pricing Analysis
Clinically substantiated wrinkle-reduction claims anchor value-based pricing for anti-aging serums, with epigallocatechin gallate standardization level and nanoliposome encapsulation certification as primary differentiation drivers. Pricing pressure intensifies in rinse-off cleanser categories where polyphenol residence time limitations compress margins. Mass-market buyers in Mumbai and Delhi exhibit highest price sensitivity, while Seoul's young urban consumers accept premiums for lipid-stabilized delivery systems.
Supply Chain Analysis
Regional distribution centers in Shanghai, Mumbai, and Hamburg orchestrate hub-and-spoke patterns for finished goods, while raw material flows draw from South Korea's Jeju Island, China's Zhejiang province, and India's Assam region. Camellia sinensis leaf supply, lipid-encapsulation technology, and chromatographic testing equipment constitute critical input dependencies. Single-source vulnerability around Jeju's captive plantations amplifies climate-driven disruption risk. Distribution runs through direct-to-consumer subscription platforms and controlled retail partnerships in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH chemical safety protocols and EMA cosmetic guidelines have erected a cost-of-compliance moat that rewards pre-validated botanical supply chains while excluding capital-constrained entrants. This regulatory barrier-to-entry concentrates margin capture among enterprises with existing polyphenol documentation infrastructure.
For Market Incumbents: Anchor supply security through backward integration into certified organic Camellia sinensis cultivation or exclusive co-development partnerships with nanoliposome technology holders. Defend against mid-tier contract manufacturers by accelerating batch-to-batch chromatographic fingerprinting capabilities that smaller brands cannot replicate. Prioritize channel control in India's underpenetrated brightening treatment segment before regional formulators consolidate localized turmeric-tea positioning.
For New Entrants and Emerging Players: Dermatologist clinic partnerships in Seoul's Gangnam district offer lowest customer acquisition costs for prestige serum trial generation. Subscription replenishment models for lipid-encapsulated green tea formulations bypass traditional retail margin structures while capturing recurring revenue from urban professionals. Target sensitive skin positioning with white tea and rooibos bases where EU Green Deal procurement criteria favor verified carbon footprint suppliers lacking established incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with biotech suppliers holding proprietary polyphenol stabilization patents given accelerating reformulation demand under tightening EMA cosmetic guidelines. Long-term viability across the analysis window favors enterprises with dual capabilities in extraction and encapsulation technology. Monitor bioprospecting permit approval timelines as an inflection signal for wild-harvested tea genetic material access restrictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plantation Acquisition | Jeju Island green tea operations secure epigallocatechin gallate supply against climate volatility. |
| Nanoliposome Co-Development Partnership | Osaka-based biotech collaboration elevates serum bioavailability claims for prestige positioning. |
| Direct-to-Consumer Subscription Launch | Seoul and Mumbai replenishment models displace traditional retail discovery for core categories. |
| Certified Organic Repositioning | EU Green Deal alignment opens public procurement channels for verified carbon footprint extracts. |
| India Brightening Treatment Localization | Turmeric-tea combination marketing accelerates trial in underpenetrated premium mask demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this tea-based skin care products analysis. Primary interviews with formulation chemists, cosmetic regulatory affairs leads, retail category buyers, and plantation operations managers combined with MFDS, EMA, and NMPA submission databases. Bottom-up triangulation across polyphenol extraction capacity and top-down reconciliation against finished goods trade flows validated market sizing.
Data-stream reconciliation employed multi-dimensional segmentation across product type, ingredient standardization tier, application claim intensity, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating epigallocatechin gallate raw material price indices, social media-driven trial rate proxies, and channel shift velocity toward subscription replenishment. Forecast inputs included climate sensitivity models for Camellia sinensis harvests and bioprospecting permit approval timelines.
Caveats apply where EMA cosmetic guideline enforcement intensity, REACH chemical safety protocol expansion, or bioprospecting access-and-benefit-sharing documentation requirements could materially shift the outlook. Forecasts reflect documented assumptions around polyphenol stabilization technology adoption curves and channel migration patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Madecassoside Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Tamanu Oil Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Global Pet Food Flavors Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
North America Grape Seed Extract Market