
 Madecassoside Market | 2026-2036
Madecassoside Market Size, Share, and Industry Trends Forecast 2026-2036
Madecassoside Market Insights
Capital-intensity divergence between extraction-scale producers and formulation-focused brands is bifurcating competitive dynamics in madecassoside supply. Biopurify Phytochemicals leverages captive botanical sourcing in Sichuan province to secure raw material throughput. Sabinsa Corporation anchors its position through US-based phytochemistry R&D and standardized extract protocols. Xi'an Lyphar Biotech competes on fermentation-derived alternatives that reduce Centella asiatica crop dependency.
Madecassoside, a pentacyclic triterpenoid saponin extracted from Centella asiatica, typically assays at 90-95% purity for cosmetic-grade applications and functions primarily as a collagen synthesis stimulant and anti-inflammatory agent in topical therapeutics. Serums command premium positioning due to higher active loading and clinical positioning, while creams dominate volume through mass-market dermocosmetic penetration. Skincare applications lead absolute demand, though dermatological treatments represent the fastest-growing channel as prescription-adjacent topologies expand.
REACH registration requirements in Europe and China's SAMR cosmetic ingredient filing system mandate batch-level triterpene profiling and heavy metal screening for market access. The US FDA exercises oversight through cosmetic labeling regulations rather than pre-market approval, creating divergent compliance burdens across export destinations. Stakeholders must monitor regulatory harmonization pressures between ISO botanical extract standards and emerging national pharmacopeia monographs for Centella derivatives.
Market Dynamics
Centella asiatica crop volatility and REACH-mandated purity thresholds are compressing supply elasticity while K-beauty export channels accelerate formulation demand. The resulting tension between agricultural input constraints and cosmetic-grade extraction standards defines current competitive positioning.
Growth Catalysts
- K-Beauty Export Channels:South Korean dermocosmetic brands drive serum and cream formulation demand through cross-border e-commerce platforms penetrating Southeast Asian and North American markets.
- Collagen Synthesis Positioning:Clinical validation of madecassoside as a topical anti-inflammatory agent expands prescription-adjacent dermatological applications beyond cosmetic skincare.
- China's GB Standards:Tightened cosmetic safety thresholds for triterpene extracts force domestic manufacturers toward higher-purity sourcing, consolidating demand for certified suppliers.
Market Restraints
- Agricultural Input Volatility:Centella asiatica harvest yields fluctuate with monsoon patterns across Sichuan and Yunnan provinces, destabilizing raw material throughput for extraction-scale producers.
- Extraction Technology Concentration:Supercritical CO2 and ethanol extraction capabilities cluster among a limited set of phytochemical specialists, creating bottleneck risk in upstream processing.
- Substitution Threat:Synthetic triterpenoid analogs and fermentation-derived alternatives reduce crop dependency for cost-sensitive formulation houses.
Strategic Opportunities
- Fermentation-Derived Production:Microbial biosynthesis of madecassoside eliminates agricultural exposure while meeting pharmaceutical-grade purity specifications for injectable applications.
- SAMR Filing Acceleration:China's streamlined cosmetic ingredient registration creates first-mover advantage for suppliers achieving batch-level triterpene profiling compliance ahead of enforcement deadlines.
- Dermatological Channel Expansion:Prescription-adjacent topologies for barrier repair and post-procedure recovery represent underpenetrated clinical positioning beyond mass-market skincare.
Industry Challenges
- Phytochemistry Talent Scarcity:Specialized expertise in triterpene isolation and standardized extract protocols concentrates among legacy botanical suppliers, constraining new entrant scale-up.
- Batch Certification Timelines:REACH registration and ISO botanical extract harmonization require 18-24 month validation cycles, delaying market access for novel extraction methods.
- Heavy Metal Screening Infrastructure:Arsenic and lead detection capabilities at parts-per-billion thresholds demand capital-intensive analytical equipment investments from mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Madecassoside Market |
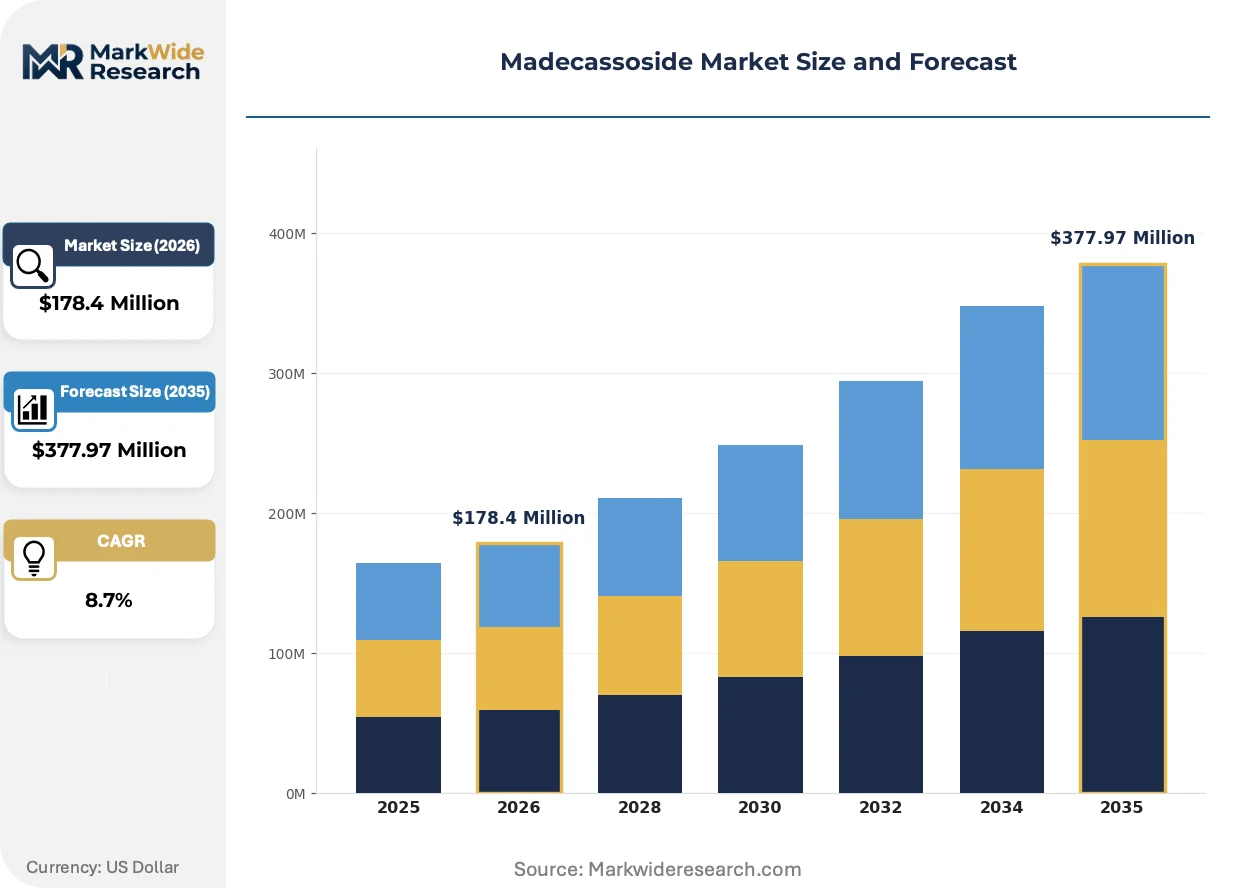
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $377.97 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Creams, Masks, Gels Application: Skincare, Dermatological Treatments, Anti-Aging, Wound Healing End User: Consumers, Dermatologists, Hospitals, Beauty Salons Distribution Channel: Online Retailers, Pharmacies, Specialty Stores, Supermarkets |
| Companies Covered | Biopurify Phytochemicals, Mediheal, Krackeler Scientific, Xi'an Lyphar Biotech, Sabinsa Corporation, OK Chem, Benefittw Bio-Tech, Shaanxi Bolin Biotechnology, Indena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Madecassoside Market Trends and Innovations
Fermentation biotechnology and regulatory purity mandates are restructuring how madecassoside reaches formulation houses. These forces compress traditional agricultural supply chains while elevating analytical compliance as a competitive differentiator.
Bioreactor-based triterpenoid synthesis is decomposing the historical link between Centella asiatica cultivation and active pharmaceutical ingredient supply. Contract manufacturers in China's biotech corridors are scaling microbial platforms to produce assay-grade madecassoside without crop dependency. This shift enables year-round production scheduling and eliminates monsoon-driven yield volatility that constrains extraction-based competitors.
REACH batch-level triterpene profiling requirements are forcing extraction houses to deploy high-performance liquid chromatography fingerprinting across every production lot. European cosmetic brands now reject shipments lacking heavy metal certificates at parts-per-billion thresholds. German and French formulators have consolidated supplier relationships to three certified partners, compressing vendor diversity in favor of compliance reliability.
Clinical positioning has displaced mass-market moisturization as the primary value proposition for madecassoside serums. South Korean dermocosmetic brands now lead with barrier repair claims validated through corneometer studies, commanding price multiples over basic hydration products. This behavioral pivot concentrates premium demand among consumers seeking prescription-strength outcomes without dermatologist intermediation.
Madecassoside Market Segmentation
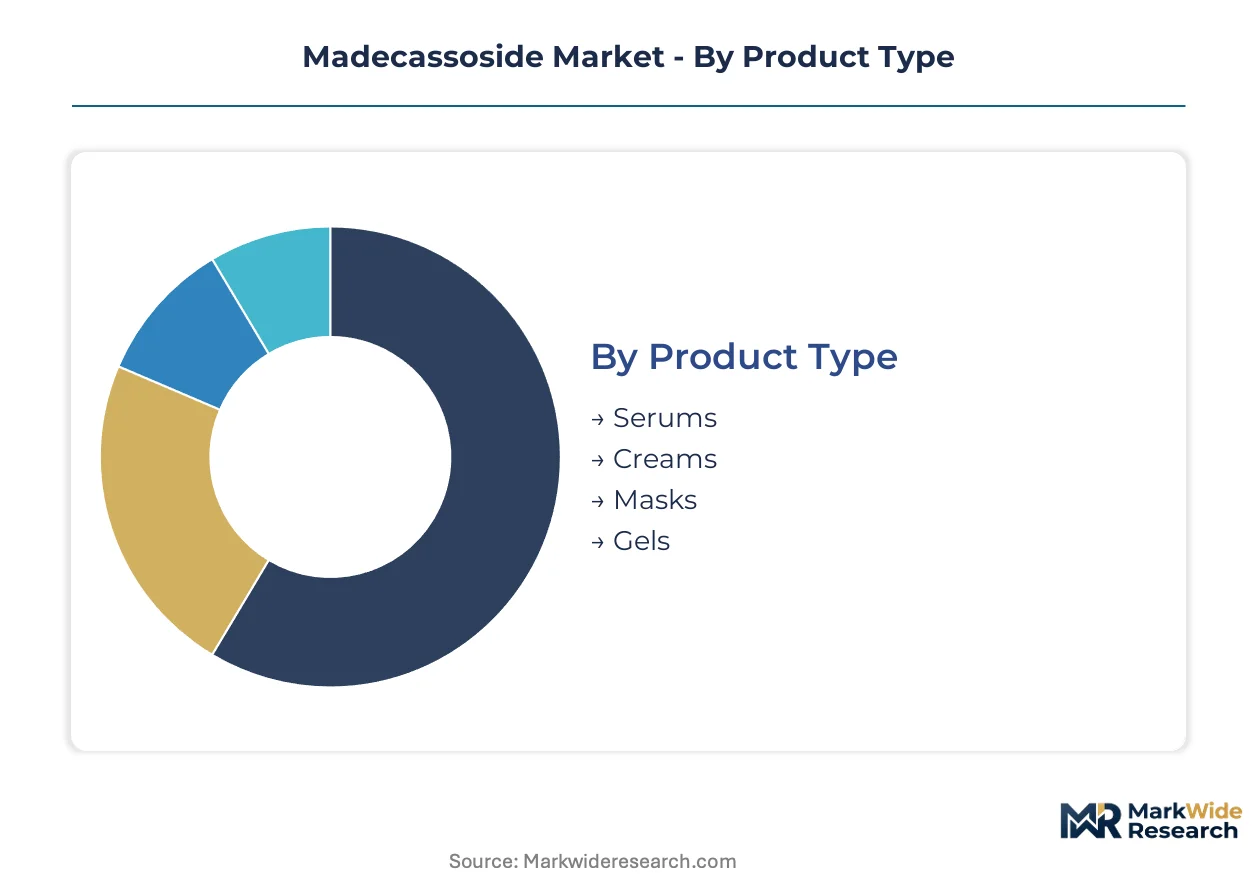
Madecassoside formulations diverge sharply across delivery systems and clinical positioning. Channel economics and purity requirements determine which segments capture premium pricing versus volume scale.
Product Type:
Serums and creams flow through distinct channel mixes—dermocosmetic clinics and e-commerce platforms respectively—creating parallel demand architectures with different margin profiles.
- Serums:High-concentration aqueous solutions typically load 0.1-0.5% madecassoside for targeted barrier repair. Demand concentrates through South Korean dermocosmetic brands and prescription-adjacent clinics where clinical validation commands price multiples.
- Creams:Emulsion-based vehicles with lower active loading dominate mass-market penetration through drugstore and supermarket channels. China's domestic manufacturers drive volume production for GB-standard compliance.
- Masks:Sheet and wash-off formats serve K-beauty export channels seeking ritualistic positioning.
- Gels:Lightweight aqueous systems target post-procedure recovery applications in clinical settings.
By volume, creams lead. By growth pace, serums are expanding most quickly.
Application:
Cost tier stratification separates cosmetic-grade positioning from pharmaceutical-grade pricing, with purity thresholds and regulatory filing requirements determining margin capture.
- Skincare:Cosmetic-grade formulations at 90-95% purity serve daily barrier maintenance and anti-inflammatory maintenance. Mass-market brands in China and South Korea drive formulation demand through cross-border e-commerce.
- Dermatological Treatments:Prescription-adjacent topologies for eczema, psoriasis, and post-procedure recovery require batch-level triterpene profiling under REACH and SAMR standards. German and French formulators consolidate supplier relationships around certified partners.
- Anti-Aging:Collagen synthesis claims validated through corneometer studies command premium positioning in clinical channels.
- Wound Healing:Traditional medicinal applications in Centella asiatica's native geographies sustain extraction-scale demand.
Skincare leads absolute volume. Dermatological treatments gain share fastest.
End User:
Customer type determines specification stringency—from consumer self-selection to institutional procurement protocols with mandated certificate of analysis requirements.
- Consumers:Individual purchasers through online retailers and specialty stores drive serum and cream volume. K-beauty influencer marketing accelerates trial conversion in Southeast Asian and North American markets.
- Dermatologists:Clinical prescribers require heavy metal certificates at parts-per-billion thresholds and ISO botanical extract compliance. European and South Korean practitioners consolidate around three certified suppliers per practice.
- Hospitals:Institutional procurement mandates REACH registration and batch-level triterpene fingerprinting for formulary inclusion.
- Beauty Salons:Professional treatment providers seek mid-tier purity grades for procedural applications without prescription oversight.
Consumers dominate transaction volume. Dermatologists deliver steepest expansion trajectory.
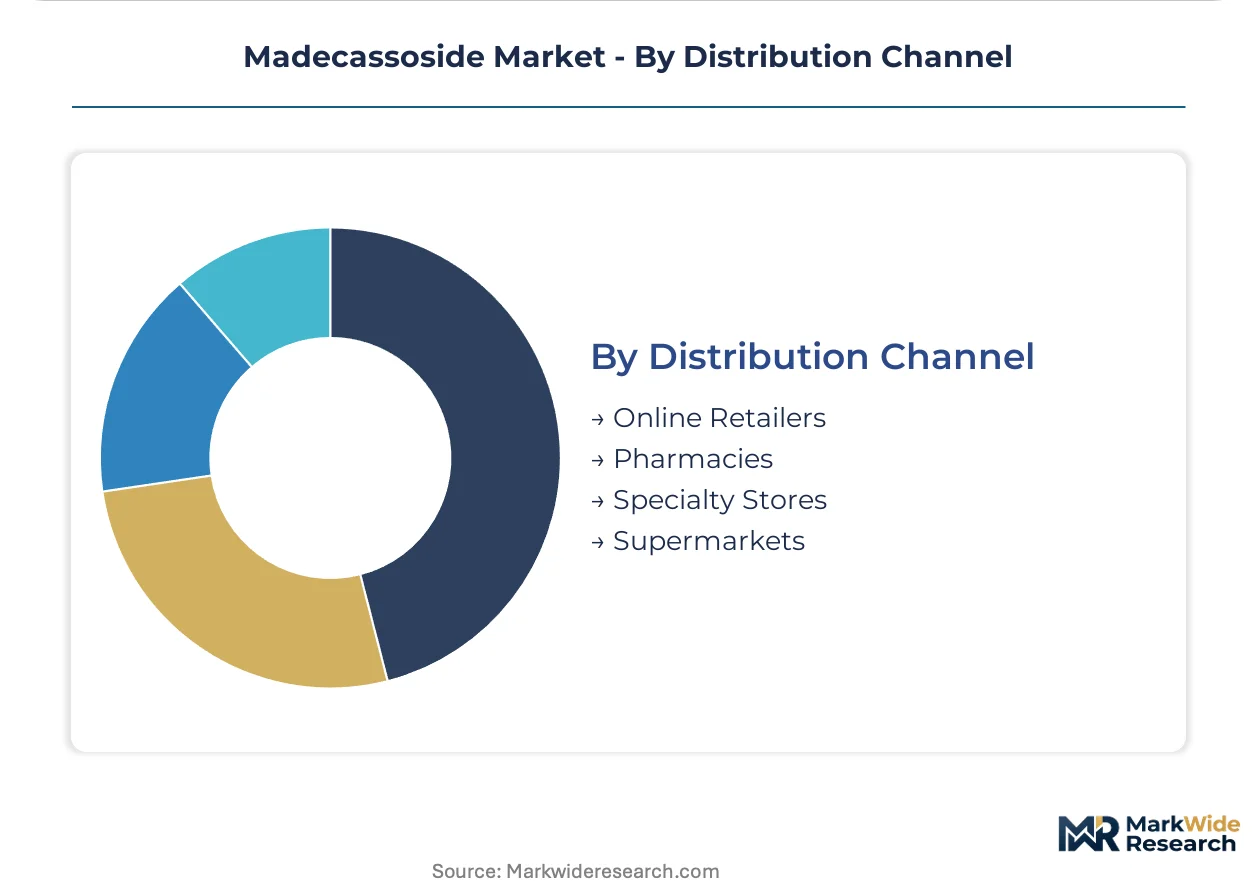
Distribution Channel:
Supply concentration in extraction technology creates channel-specific bottlenecks, with supercritical CO2 capabilities clustering among limited phytochemical specialists.
- Online Retailers:Cross-border e-commerce platforms—particularly those serving K-beauty export channels—accelerate serum demand through influencer-driven discovery. South Korean brands leverage TikTok and Instagram commerce for Southeast Asian penetration.
- Pharmacies:Regulated retail channels in Europe and China enforce REACH and GB standard compliance through mandatory certificate of analysis presentation. German pharmacy chains require ISO botanical extract harmonization.
- Specialty Stores:Dermocosmetic boutiques and professional beauty retailers serve clinical-positioned brands with higher active loading.
- Supermarkets:Mass-market cream formulations reach price-sensitive consumers through high-volume, lower-margin distribution.
Online retailers lead volume growth. Pharmacies command premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea and China consume madecassoside through dermocosmetic serum formulations, while European demand concentrates in prescription-adjacent dermatological channels with stricter purity mandates.
South Korea
K-beauty export channels drive serum demand through cross-border e-commerce platforms penetrating Southeast Asian markets. MFDS cosmetic ingredient regulations enforce batch-level documentation for triterpene extracts. Seoul-based dermocosmetic brands leverage influencer marketing to accelerate clinical-positioned product discovery.
China
Domestic dermocosmetic manufacturing absorbs volume through GB-standard compliance for cosmetic safety. SAMR's streamlined ingredient filing system consolidates demand toward certified suppliers. Sichuan province anchors extraction-scale production with captive Centella asiatica sourcing.
Germany
Pharmacy chains enforce REACH-mandated triterpene profiling and heavy metal screening at parts-per-billion thresholds. ECHA registration requirements compress supplier diversity to certified partners. Frankfurt and Munich clusters concentrate formulation R&D for barrier repair topologies.
United States
FDA cosmetic labeling regulations create divergent compliance burdens compared to European pre-market standards. Clinical validation of collagen synthesis claims expands prescription-adjacent dermatological applications. New Jersey and California host phytochemistry R&D facilities for standardized extract protocols.
France
ANSM oversight of cosmetic safety reinforces REACH batch certification requirements for triterpene extracts. Paris-based formulators consolidate supplier relationships around three certified partners per practice. Lyon and Marseille clusters specialize in high-performance liquid chromatography fingerprinting infrastructure.
Madecassoside Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with extraction-scale producers controlling upstream throughput while formulation-focused brands capture downstream margin. The competitive landscape bifurcates between agricultural-dependent extractors and fermentation-based alternatives. Three archetypes dominate: Sichuan-based botanical sourcers, US-based phytochemistry R&D houses, and Chinese biotech corridors pursuing microbial biosynthesis. Capacity expansion and regulatory compliance acceleration constitute the dominant competitive moves.
Within the integrated extraction tier, Biopurify Phytochemicals and Sabinsa Corporation exemplify contrasting geographic anchoring strategies. Xi'an Lyphar Biotech occupies a position representing fermentation-derived alternatives that reduce crop dependency. These three entities collectively illustrate how competitive positioning diverges between agricultural supply chain control and biotechnological substitution pathways.
| Leading Market Players |
|---|
| Biopurify Phytochemicals |
| Mediheal |
| Krackeler Scientific |
| Xi'an Lyphar Biotech |
| Sabinsa Corporation |
| OK Chem |
| Benefittw Bio-Tech |
| Shaanxi Bolin Biotechnology |
| Indena |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month REACH batch certification timelines concentrate pricing power among extraction-scale producers with validated protocols, while fermentation alternatives compress contract premiums for agricultural-dependent suppliers. This lead-time asymmetry stratifies procurement economics across dermocosmetic formulation houses.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade procurement, locking in Centella asiatica extract supply at fixed purity thresholds for 24-36 month windows. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and feedstock-grade levels reflects batch-level triterpene profiling compliance and heavy metal screening depth. Cost compression in cosmetic-grade tiers is intensifying because fermentation-derived alternatives eliminate crop dependency. Mass-market formulation houses in China exhibit highest price sensitivity, while European dermocosmetic brands prioritize certificate-of-analysis reliability over unit economics.
Supply Chain Analysis
Supercritical CO2 extraction capacity clustering in Sichuan province creates a chokepoint constraining throughput for REACH-compliant cosmetic-grade supply. China, India, and South Korea anchor global extraction infrastructure, with Sichuan and Yunnan provinces feeding raw Centella asiatica biomass. Supply chain risk centers on monsoon-driven yield volatility across southwestern Chinese cultivation zones. Distribution runs through certified phytochemical specialists to formulation houses, with German and French pharmacy chains enforcing batch-level documentation at receipt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in batch certification and regulatory filing support are expanding faster than base extract supply, as formulation houses outsource REACH and SAMR compliance documentation to specialized partners.
For Market Incumbents: Shield market position through captive Centella asiatica cultivation contracts in Sichuan province and accelerated SAMR filing infrastructure investment. Synthetic triterpenoid substitution threats demand backward integration into fermentation biotechnology R&D. Certification investment in ISO botanical extract harmonization creates switching costs for European dermocosmetic clients. For New Entrants and Emerging Players: Differentiate on microbial biosynthesis platforms eliminating agricultural exposure, targeting pharmaceutical-grade injectable applications with year-round production scheduling. Prescription-adjacent dermatological channels in Germany and France represent the most penetrable white space, given incumbent supplier consolidation around three certified partners per practice. Go-to-market leverage rests on ECHA pre-registration completion ahead of enforcement deadlines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified botanical extract houses with underutilized supercritical CO2 capacity and dormant SAMR filing capabilities. Five-to-ten-year viability hinges on fermentation technology maturation and regulatory purity mandate harmonization. Watch for ECHA registration deadline acceleration as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Centella Cultivation | Sichuan province contracts secure raw material throughput against monsoon volatility. |
| Fermentation Platform Scale-Up | Microbial biosynthesis eliminates crop dependency for pharmaceutical-grade purity tiers. |
| SAMR Filing Infrastructure Investment | Streamlined registration creates first-mover advantage in China's cosmetic ingredient market. |
| REACH Batch Certification Acceleration | ECHA compliance compresses supplier diversity to certified partners in European channels. |
| Clinical Validation Partnership | Corneometer studies enable prescription-adjacent positioning beyond mass-market skincare. |
Research Methodology
A standing panel of extraction-scale plant managers, dermocosmetic formulation R&D directors, regulatory affairs specialists at SAMR and ECHA, and pharmacy chain procurement managers provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with secondary validation through customs records, SEC filings of publicly traded phytochemical suppliers, ClinicalTrials.gov entries for madecassoside dermatological studies, and REACH registration databases. Bottom-up triangulation against top-down trade flow analysis ensured segment-level consistency.
Consistency checks validated volume and value outputs against external benchmarks including regional customs data for Centella asiatica extract shipments and dermocosmetic brand revenue disclosures. Segmentation modeling spanned product type, application tier, end-user category, and distribution channel across the projection horizon. CAGRs were derived from regression analysis of historical purity-premium relationships and regulatory filing velocity. Forecast inputs incorporated SAMR enforcement timeline assumptions and fermentation technology cost curves.
Material uncertainties — regulatory harmonization delays, synthetic substitution acceleration, and Centella asiatica crop disease outbreaks — sit outside the modeled envelope. Forecasts reflect documented assumptions about REACH batch certification timeline stability and K-beauty export channel growth continuity. Practitioners should keep alternative scenarios live as ECHA registration enforcement intensity and microbial biosynthesis yield improvements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Aromatherapy Carrier Oil Market