
 Normal and Specialty Fats Market | 2026-2036
Normal and Specialty Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Normal and Specialty Fats Market Intelligence
Production capacity consolidation in Southeast Asia is restructuring the supply base for palm-derived fats. Major agribusinesses like Cargill Incorporated leverage extensive global distribution networks to manage supply chain volatility. AAK AB specializes in high-value co-developed fat solutions for the food industry. Wilmar International dominates upstream palm oil processing, controlling a significant portion of raw material supply.
Normal and specialty fats are lipid-based ingredients, primarily derived from vegetable and animal sources, engineered for specific functional properties. These properties, such as precise melting points and fatty acid compositions, are critical for creating texture, stability, and mouthfeel in finished products. Within the food industry application, confectionery and bakery segments command the largest share due to requirements for cocoa butter equivalents and shortenings. The demand for food grade vegetable fats, particularly in solid and semi-solid forms, continues to outpace other categories.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) impose strict limits on trans fats and mandate clear nutritional labeling. These rules directly influence product reformulation and the selection of specialty fat ingredients. Consequently, navigating the complex web of international food safety standards and sustainability certifications remains a critical success factor for market participants.
Market Dynamics
Regulatory pressure on trans-fat content, coupled with functional demands from the confectionery sector, represents the central force shaping the market. This creates a technical challenge for ingredient suppliers to develop healthier fats that mimic the performance of traditional ones.
Growth Catalysts
- Confectionery Sector Growth:Demand for cocoa butter equivalents and improvers in chocolate and compound coatings provides a consistent growth engine, especially in emerging markets.
- EU Trans-Fat Regulation:Strict limits imposed by the European Food Safety Authority (EFSA) on industrial trans fats are forcing widespread product reformulation, favoring specialty fat solutions.
- Sustainable Sourcing Mandates:Corporate commitments to use certified sustainable palm oil (CSPO) are creating a premium market for traceable, deforestation-free fat ingredients.
Market Restraints
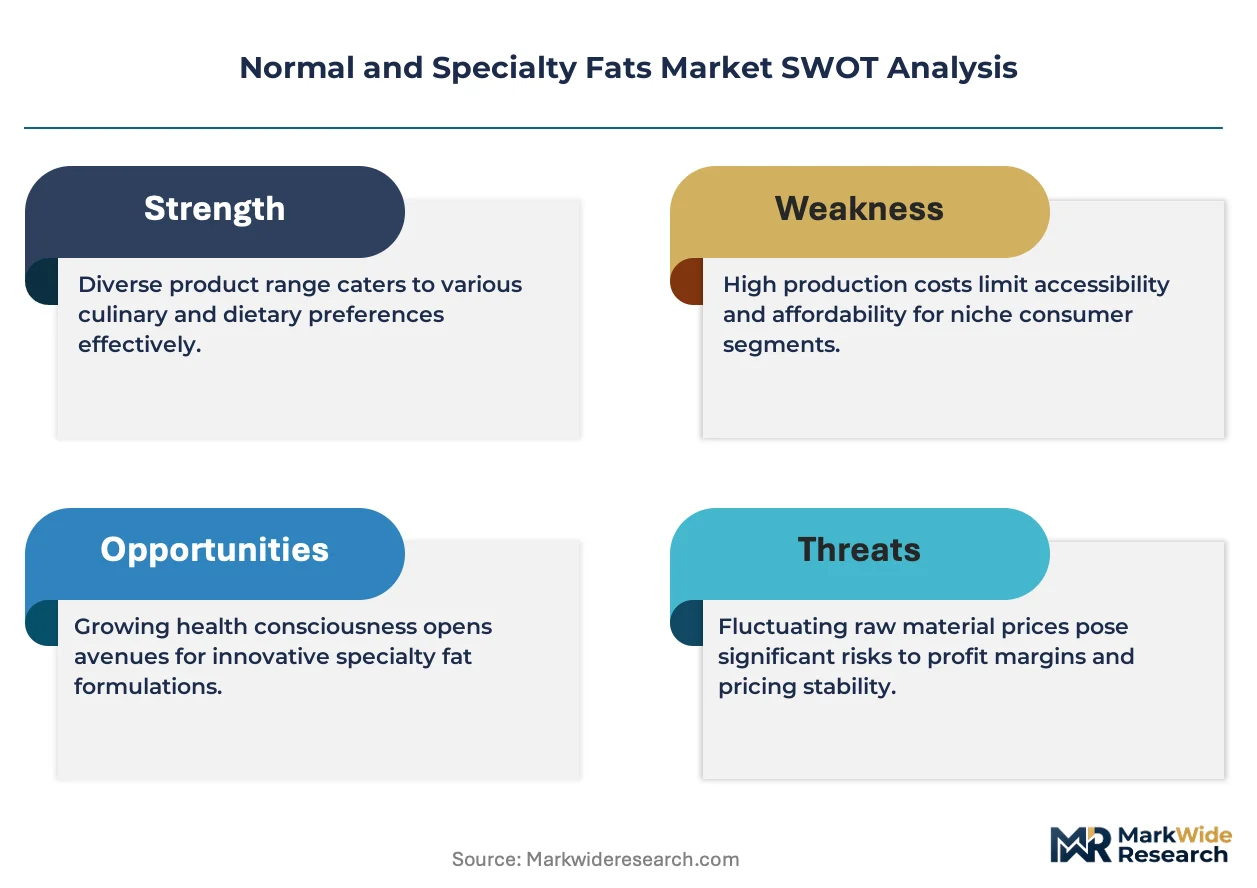
- Feedstock Price Volatility:The market is highly susceptible to price fluctuations in key raw materials like palm and soybean oil, impacting processor margins.
- Supply Chain Concentration:Heavy reliance on palm oil from Indonesia and Malaysia creates geopolitical and logistical risks, from export policies to weather events.
- Substitution from Liquid Oils:In some bakery applications, formulation advances allow for the partial replacement of solid fats with less expensive, healthier liquid oils.
Strategic Opportunities
- Plant-Based Foods:Developing customized fats that replicate the texture and mouthfeel of animal fats presents a significant opportunity within the expanding plant-based meat and dairy alternative segments.
- Oleogel Technology:Commercializing oleogels, which structure liquid oils into solid-like fats without hydrogenation, offers a pathway to create clean-label, low-saturated fat products.
- Infant Nutrition Formulation:Creating fats that mimic the fatty acid profile of human milk, such as OPO (Oleic-Palmitic-Oleic) fats, addresses a high-value niche in the infant formula industry.
Industry Challenges
- Certification Complexity:Adhering to the multiple, often overlapping, standards for sustainability, such as RSPO, and non-GMO verification adds significant cost and administrative burden.
- Capital-Intensive Processing:The high cost of building and maintaining fractionation and interesterification facilities creates a substantial barrier to entry for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Normal and Specialty Fats Market |
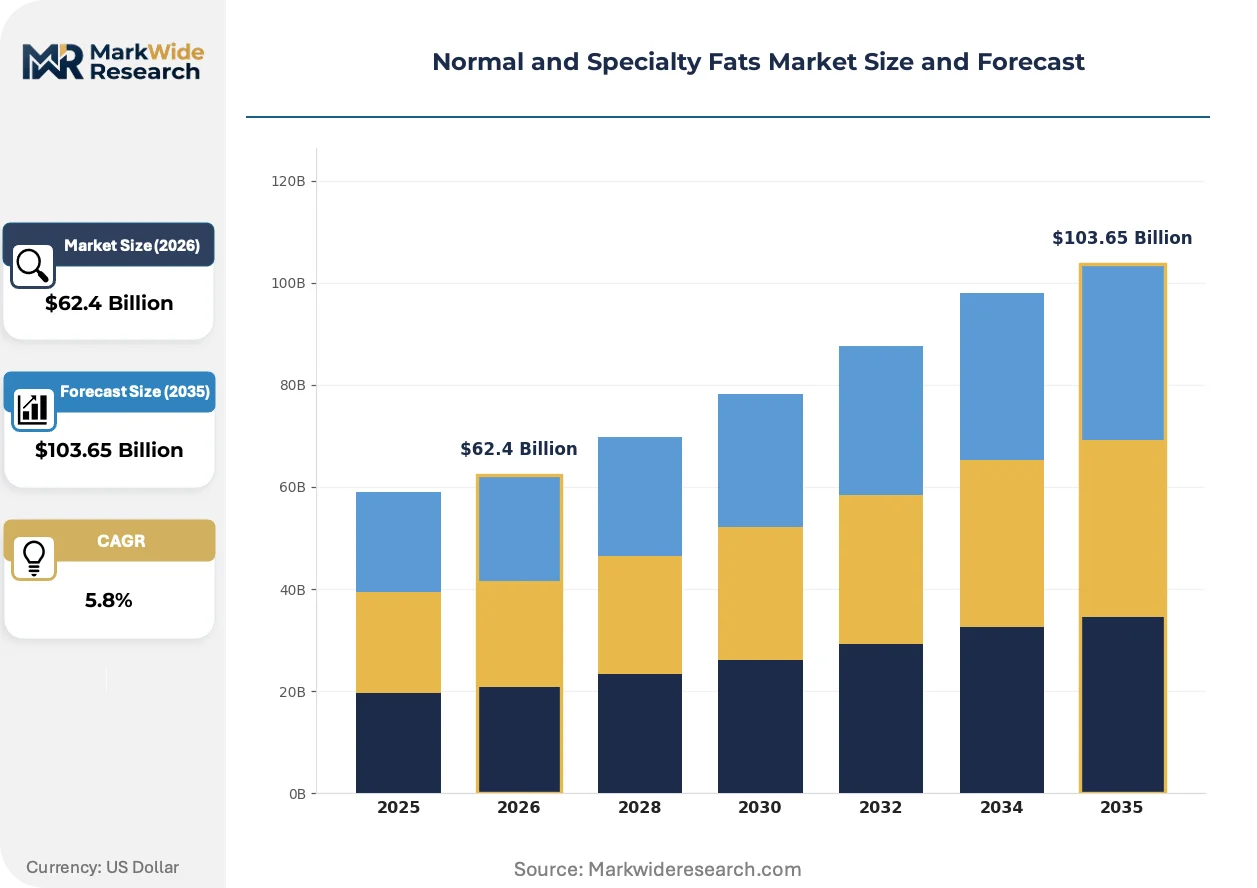
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Fats, Animal Fats, Trans Fats, Saturated Fats Application: Food Industry, Confectionery, Bakery, Personal Care Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Form: Liquid, Solid, Semi-Solid, Powdered |
| Companies Covered | Wilmar International, Fuji Oil Holdings, Cargill Incorporated, Musim Mas Holdings, IOI Group, Archer Daniels Midland Company, AAK AB, Sime Darby Plantation Berhad, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Normal and Specialty Fats Market Strategic Shifts & Innovations
Product reformulation is the dominant theme, driven by a convergence of consumer health awareness and stringent regulatory action against specific fatty acids. This pushes innovation away from cost optimization alone and toward creating functional, compliant, and clean-label ingredients.
Enzymatic interesterification is a key technology that modifies the structure of fats and oils to achieve desired melting points without creating trans fats. Food manufacturers in the bakery and infant formula sectors are rapidly adopting this process for creating healthier product profiles. This technology is expanding into specialized medical nutrition, where precise lipid structures are needed for clinical dietary management.
European Food Safety Authority (EFSA) regulations imposing strict limits on trans fats directly influence ingredient selection across the food industry. This mandate forces the replacement of partially hydrogenated oils, which were once a staple for their functional properties and low cost. The bakery and confectionery segments are most affected, accelerating their shift toward non-hydrogenated shortenings and cocoa butter equivalents.
A notable shift in buying behavior prioritizes ingredients with verifiable sustainability credentials over those selected on price alone. This disrupts traditional procurement channels, forcing suppliers to provide extensive documentation on sourcing, such as RSPO certification for palm oil derivatives. This preference for transparent supply chains is most pronounced in consumer-facing brands operating in North America and Western Europe.
Normal and Specialty Fats Market Segmentation
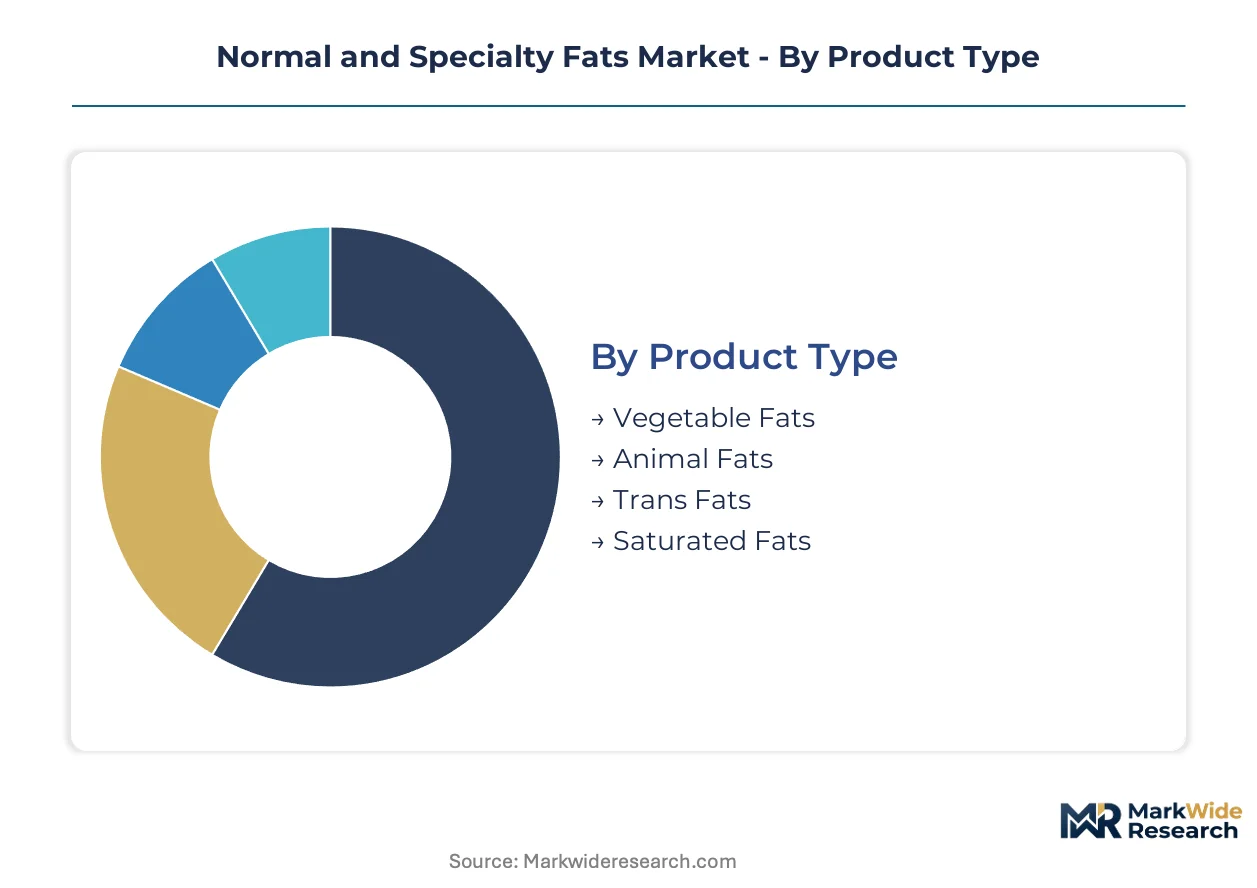
The normal and specialty fats market segments across diverse functional and application-specific requirements, highlighting the varied demands of food manufacturers and other industries. Understanding these distinct segments reveals where innovation and investment are concentrating to meet evolving consumer preferences and regulatory mandates.
Product Type:
The customization-vs-standardization spectrum in product types defines ingredient versatility across industries.
- Vegetable Fats:Derived from plant sources like palm, soybean, and sunflower, these fats offer a wide range of melting profiles and textures. Demand in the food industry is concentrating as consumers seek plant-based alternatives and healthier options.
- Saturated Fats:These fats contain no double bonds in their fatty acid chains, providing solid texture and stability at room temperature. The confectionery sector drives their use for cocoa butter equivalents, despite regulatory scrutiny in some markets.
- Animal Fats:Rendered from animal tissues, these provide distinct mouthfeel and flavor, particularly in traditional bakery and savory products.
- Trans Fats:Industrially produced through partial hydrogenation, these are now largely phased out due to strict health regulations from EFSA and FDA.
Leading the category by volume: Vegetable Fats. Growing fastest: Saturated Fats.
Application:
Application versatility drives demand for tailored fat solutions across diverse end-use sectors.
- Food Industry:This broad category encompasses all food manufacturing, requiring fats for texture, flavor, and stability in numerous products. Health-conscious consumer trends and regulatory shifts from the FDA and EFSA significantly influence ingredient selection.
- Confectionery:This segment demands precise melting profiles and mouthfeel for products like chocolate, candies, and fillings. The need for cocoa butter equivalents and improvers provides a consistent growth engine for specialty fat suppliers.
- Bakery:Fats provide structure, tenderness, and shelf-life extension in breads, pastries, and biscuits, with reformulation often targeting trans-fat reduction.
- Personal Care:Fats function as emollients, emulsifiers, and thickeners in cosmetics and skincare products, valued for their skin-conditioning properties.
This category sees the Food Industry dominating overall volume, while Confectionery applications demonstrate the steepest expansion trajectory.
Grade:
Regulatory compliance and end-use sensitivity dictate requirements across various fat grades.
- Food Grade:These fats meet stringent safety and quality standards set by bodies like the FDA and EFSA for human consumption. They are essential across bakery, confectionery, and processed food sectors.
- Pharmaceutical Grade:Requiring the highest purity and precise specifications, these fats serve as excipients, drug delivery vehicles, and active pharmaceutical ingredients. Stringent regulatory oversight applies to their manufacture and use.
- Industrial Grade:These fats are utilized in non-food applications such as lubricants, biofuels, and chemical intermediates, valuing cost-effectiveness and performance.
- Cosmetic Grade:Employed in skincare and makeup, these fats offer emollient and textural properties, adhering to specific safety and stability requirements.
Food Grade products account for the largest market share, with Pharmaceutical Grade segments gaining share fastest due to specialized demand.
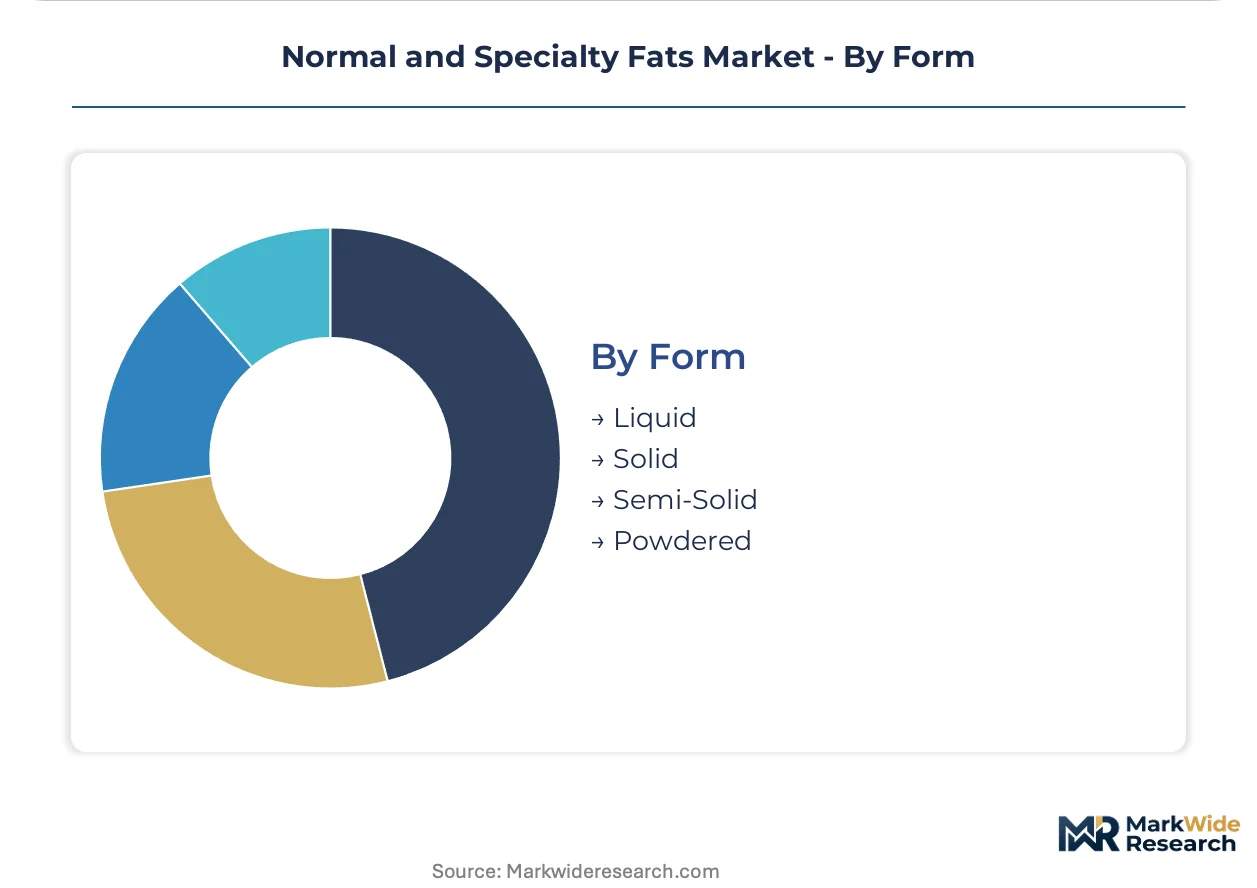
Form:
Volume and processing convenience often determine the preferred physical form of fats for different applications.
- Solid:These fats provide structure, stability, and mouthfeel in products requiring firmness, such as chocolate and shortenings. Their precise melting points are critical for specific applications.
- Semi-Solid:Offering a balance of spreadability and structure, these fats are versatile for applications like margarines, spreads, and certain bakery items. They combine liquid and solid fat characteristics.
- Liquid:Predominantly oils, these are used for frying, dressings, and as ingredients where fluidity is desired, often offering cost advantages.
- Powdered:Encapsulated or spray-dried fats provide convenience in dry mixes, nutritional supplements, and specific food formulations requiring precise dispersion.
Solid forms drive the highest consumption volumes, while Powdered formats exhibit the most rapid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asia's dominant palm oil production anchors the global normal and specialty fats market. Key processing hubs in Indonesia and Malaysia manage significant raw material supply. These regions influence global pricing and availability for fat derivatives.
Indonesia
Indonesia drives significant demand for specialty fats, particularly for its expanding domestic food and confectionery industries. The Indonesian Sustainable Palm Oil (ISPO) standard governs sustainable production practices. Major processing facilities in Sumatra and Kalimantan refine crude palm oil into various fat fractions for global and local markets.
Malaysia
Malaysian processors focus on high-value palm oil derivatives for both food and non-food industrial applications. The Malaysian Sustainable Palm Oil (MSPO) certification ensures responsible sourcing for international trade. Industrial clusters in Johor and Selangor specialize in fractionation and interesterification processes.
Germany
German food manufacturers seek specialty fats for bakery and confectionery, driven by consumer health trends. European Food Safety Authority (EFSA) regulations on trans-fats compel continuous product reformulation. Food ingredient innovation centers in Hamburg and North Rhine-Westphalia develop advanced fat solutions.
United States
The United States market demands diverse specialty fats for processed foods, plant-based alternatives, and infant nutrition. US Food and Drug Administration (FDA) regulations mandate clear nutritional labeling and effectively restrict artificial trans fats. Agricultural processing centers in the Midwest and innovation hubs in California drive fat ingredient development.
India
India's expanding confectionery and bakery sectors fuel substantial demand for normal and specialty fats. The Food Safety and Standards Authority of India (FSSAI) sets quality and safety standards for edible fats. Food processing zones in Maharashtra and Gujarat host significant fat production and blending facilities.
Normal and Specialty Fats Market Key Industry Players
Global majors compete with regional champions across production scale and specialized ingredient formulation within the normal and specialty fats market. The market exhibits a tiered structure, with large agribusinesses controlling upstream raw material supply and global distribution. Specialty fat producers often focus on co-development with food manufacturers, offering tailored solutions. Companies engage in strategic partnerships and portfolio diversification to manage supply chain volatility and meet diverse customer needs across various applications.
At the scale-driven end, Wilmar International exemplifies a vertically integrated agribusiness, controlling significant upstream palm oil processing capacity and raw material supply. Cargill Incorporated represents a global distribution powerhouse, leveraging its extensive network to manage supply chain volatility and deliver diverse fat ingredients worldwide. AAK AB occupies a position as a high-value specialty fat co-developer, focusing on tailored lipid solutions for specific food industry applications requiring precise functional properties.
| Leading Market Players |
|---|
| Wilmar International |
| Fuji Oil Holdings |
| Cargill Incorporated |
| Musim Mas Holdings |
| IOI Group |
| Archer Daniels Midland Company |
| AAK AB |
| Sime Darby Plantation Berhad |
| Bunge Limited |
Cost & Logistics Intelligence
Feedstock prices, particularly for palm and soybean oil, significantly influence the normal and specialty fats market, dictating processor margins and downstream product costs. This volatility permeates the entire supply chain, from raw material extraction in Southeast Asia to ingredient delivery for global food manufacturers.
Pricing Analysis
Product customization, rather than simple bundling, defines the pricing structure for specialty fats, where functional properties are paramount. Contract-based long-term offtake agreements dominate for large-volume purchases, while smaller, highly specialized orders often command value-based pricing. Certification levels, such as RSPO or MSPO, drive price differentiation, reflecting added costs of sustainable sourcing and traceability. Pricing pressure stems from feedstock price volatility and intense competition among suppliers for commodity-grade fats. Food manufacturers in the infant nutrition segment exhibit lower price sensitivity due to stringent performance and safety requirements, contrasting with highly price-sensitive industrial buyers.
Supply Chain Analysis
Malaysian and Indonesian sustainable palm oil mandates reshape sourcing, driving investments in certified production. Geographic supply concentration in Indonesia and Malaysia creates a heavy reliance on these nations for palm oil and its derivatives. Key raw material dependencies include palm oil, soybean oil, and sunflower oil. A structural risk arises from geopolitical and logistical disruptions, such as export policies or weather events in major producing regions. Global distribution networks, often managed by major agribusinesses like Cargill Incorporated, serve as the dominant downstream model, ensuring widespread availability of fat ingredients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The normal and specialty fats market is now a vertical-integration race, with companies pursuing control over raw material sourcing or advanced co-development capabilities to secure competitive advantage.
For Market Incumbents: Anchor processing capacities in key regions like Southeast Asia to maintain cost efficiency and raw material access. Consolidate smaller, less efficient fractionation facilities to optimize operational scale. Regulatory shifts, such as stricter trans-fat limits, pose a continuous threat, necessitating ongoing portfolio reformulation. Invest in advanced enzymatic interesterification R&D to produce healthier, functional fat solutions without trans-fats.
For New Entrants and Emerging Players: Begin with niche segments like plant-based meat and dairy alternatives, where demand for customized fat solutions is expanding rapidly. Target underpenetrated applications in specialized medical nutrition, requiring precise lipid structures. The infant nutrition segment, with its demand for OPO fats, represents a penetrable high-value niche. Co-development partnerships with innovative food startups offer a strong go-to-market angle.
For Investors and Strategic Acquirers: Widespread commercialization of oleogel technology is the leading indicator that the market is entering a new phase of healthy fat innovation. The market demonstrates long-term viability, driven by health-conscious consumer trends and regulatory compliance over the next decade. Acquisition targets should include mid-sized specialty fat producers with proprietary oleogel or enzymatic interesterification capabilities. Watch for increased patent filings in clean-label fat modification as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Certified Sustainable Palm Oil (CSPO) Sourcing | Secures supply chain integrity and meets growing consumer and corporate sustainability mandates. |
| Invest in Enzymatic Interesterification Facilities | Enables production of trans-fat-free specialty fats, aligning with global health regulations. |
| Develop Tailored Oleogel Solutions | Addresses demand for clean-label, low-saturated fat alternatives in bakery and confectionery. |
| Form Strategic Partnerships for Plant-Based Applications | Captures growth in alternative protein markets by providing essential texture and mouthfeel. |
| Consolidate Processing Capacity in Southeast Asia | Optimizes operational efficiency and leverages proximity to primary palm oil feedstock sources. |
Research Approach
EFSA reports, FDA guidance documents, and RSPO certification databases formed the secondary backbone for this analysis, providing critical regulatory and sustainability context. Primary research involved interviews with food R&D directors, procurement managers at confectionery firms, specialty fat chemists, and regulatory affairs specialists. This approach combined qualitative insights from industry stakeholders with quantitative data validation from public sources. Bottom-up and top-down triangulation ensured robust market size and forecast estimations.
A bottom-up analytical lens was applied to build market size estimates, aggregating data from key product types, applications, and geographic regions. Segmentation dimensions modeled included product type (vegetable, saturated), application (confectionery, bakery, infant nutrition), grade (food, pharmaceutical), form (solid, powdered), and regional demand. Compound Annual Growth Rates were derived from historical data analysis and projected future trends across the analysis window. Industry-specific forecast inputs included palm oil yield forecasts and regulatory timelines for trans-fat bans.
Underlying measurement precision varies by segment; food grade and confectionery applications carry tighter precision than others due to more extensive public data. Forecasts reflect assumptions concerning future regulatory changes and consumer preference shifts. Geopolitical instability in key sourcing regions and unexpected shifts in commodity prices are specific risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Tamanu Oil Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Benzoe Siam Market