
 Organic Tea Market | 2026-2036
Organic Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Tea Market Analysis
Premium single-origin certification is rotating toward the center of supplier strategy as conventional commodity-grade volumes face margin compression. Unilever PLC leverages its Lipton and Tazo brand architectures to sustain mass-market shelf presence while piloting organic transitions in select European markets. Tata Consumer Products Limited anchors its organic growth narrative through Tetley-branded certified lines and direct plantation partnerships in Assam and Darjeeling. Numi Inc. specializes exclusively in Fair Trade and organic positioning, occupying the premium tier with compostable packaging and direct-trade sourcing claims.
Organic tea comprises Camellia sinensis leaves and herbal infusions cultivated without synthetic pesticides, herbicides, or genetically modified organisms, processed under certified organic handling standards that restrict chemical inputs across soil management, harvesting, and drying stages. Green tea and herbal tea command the fastest volume acceleration within the product type dimension, driven by functional wellness positioning and caffeine-flexible consumption occasions. Ready-to-drink formulations represent the most contested margin pool within the form category, as bottling infrastructure and cold-chain logistics create barriers that few pure-play organic brands can independently surmount.
USDA Organic and EU Organic Regulation frameworks govern certification legitimacy across North American and European trade corridors, while India's FSSAI and APEDA enforce export-grade organic compliance for its dominant role in global leaf supply. These standards shape demand by mandating traceable supply chains that exclude conventional blending practices and require third-party audit continuity. Stakeholders must monitor how carbon border adjustment mechanisms and evolving pesticide maximum residue limits will reshape sourcing economics for certified organic leaf procurement.
Market Dynamics
EU Green Deal pesticide residue thresholds and carbon border adjustment mechanisms are restructuring sourcing economics for certified organic leaf, forcing procurement offices to abandon conventional blending practices and rebuild traceable supply chains from soil to shelf.
Growth Catalysts
- EU Green Deal Farm-to-Fork targets:Tightening maximum residue limits for agricultural imports entering European markets are accelerating certified organic conversion among export-oriented plantations.
- Specialty cafe procurement:Wellness-focused hospitality channels in Germany and France are expanding certified organic loose-leaf procurement as menu differentiation against commodity-grade competitors.
- Functional wellness positioning:Green tea and herbal infusions are capturing caffeine-flexible consumption occasions through antioxidant and adaptogenic health claims.
Market Restraints
- Organic input cost volatility:Natural pest management inputs and compost-based fertilizers command premiums over synthetic alternatives, compressing margins for smallholder cooperatives.
- Certification audit continuity:USDA Organic and EU Organic Regulation frameworks require annual third-party verification that creates administrative burdens for multi-origin blenders.
- Ready-to-drink bottling barriers:Cold-chain logistics infrastructure concentration limits pure-play organic brands from contesting margin pools in convenience retail.
Strategic Opportunities
- Direct-trade channel innovation:Plantation-to-retailer digital traceability platforms are enabling price premiums through transparent provenance storytelling.
- Compostable packaging technology:Biodegradable sachet materials are converging with organic certification to capture premium-tier shelf space in German and Austrian retail.
- India FSSAI export-grade compliance:APEDA-enforced organic standards for Assam and Darjeeling origins are opening certified supply corridors into EU and North American markets.
Industry Challenges
- Soil conversion timeline:Three-year transition periods for synthetic-free cultivation create revenue gaps for estates switching from conventional production.
- Blending facility segregation:Certified organic handling standards require dedicated processing lines that complicate multi-certification manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Tea Market |
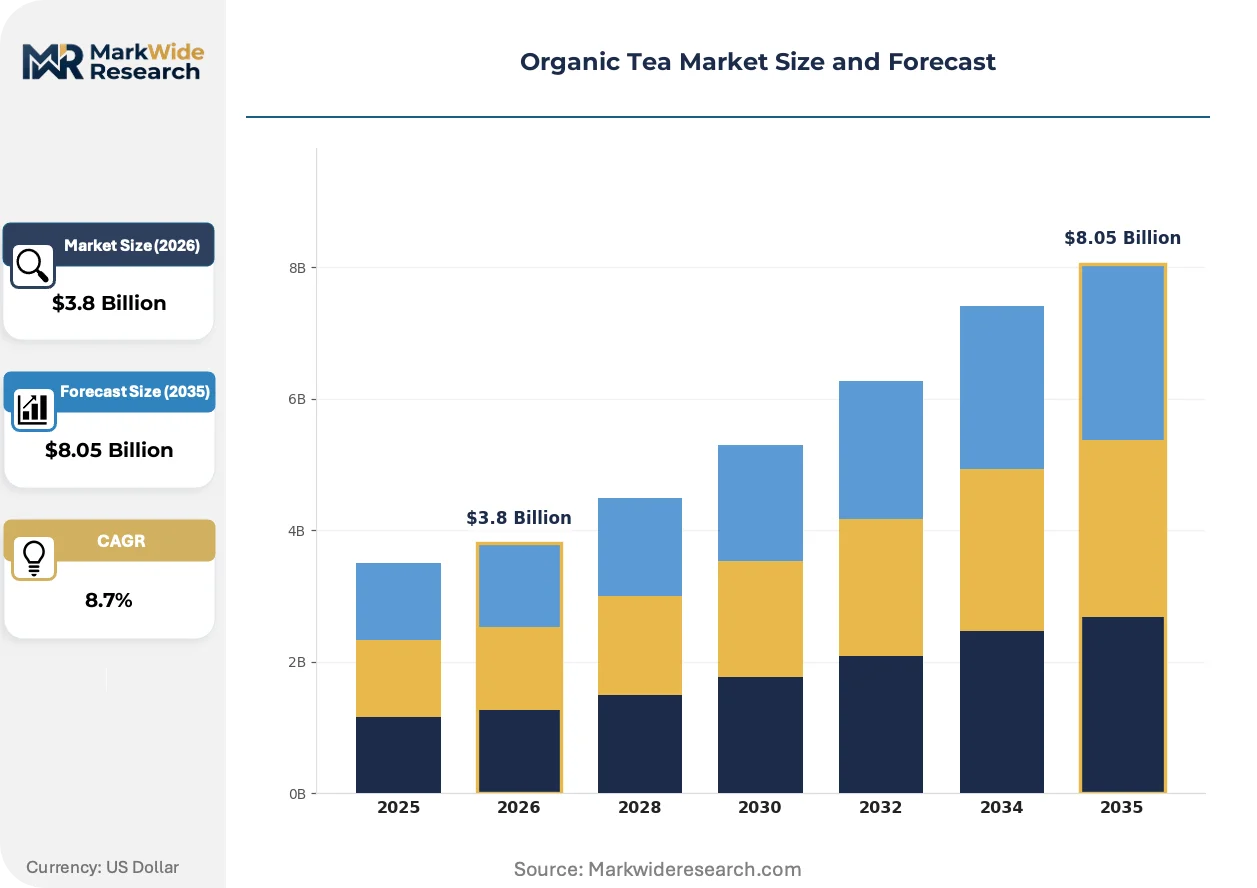
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, White Tea End User: Households, Cafes, Restaurants, Specialty Stores Form: Loose Leaf, Tea Bags, Powdered, Ready-to-Drink Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Direct Sales |
| Companies Covered | Unilever PLC, Tata Consumer Products Limited, Hain Celestial Group, Numi Inc., Bigelow Tea Company, Davidson's Organics, Associated British Foods plc, Harney & Sons Fine Teas, The Republic of Tea Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Tea Market Emerging Trajectories
Digital traceability infrastructure and biodegradable material science are converging with regulatory tightening to reshape how organic tea moves from plantation to consumer, compressing traditional opaque supply structures.
Blockchain-enabled provenance tracking is supplanting paper-based chain-of-custody documentation across EU-importing supply chains. German retail buyers and Dutch specialty distributors are mandating real-time harvest-to-port visibility. This technology is compressing audit costs while enabling premium pricing for single-origin certified lots.
EU Organic Regulation 2018/848 implementation is tightening equivalence agreements with third-country certifiers, forcing Indian and Sri Lankan exporters to recertify under stricter EU-recognized bodies. Control bodies in Assam and Darjeeling are consolidating to meet accreditation density requirements. Smallholder cooperatives face consolidation pressure from compliance cost concentration.
Specialty hospitality buyers are unbundling procurement from traditional commodity brokers, establishing direct relationships with certified estates through dedicated sourcing managers. Wellness-focused hotel chains in Germany and boutique cafe networks in France are negotiating multi-year offtake agreements. This pattern is most visible in Berlin and Munich procurement offices where sustainability officers hold veto authority over beverage supplier selection.
Organic Tea Market Segmentation
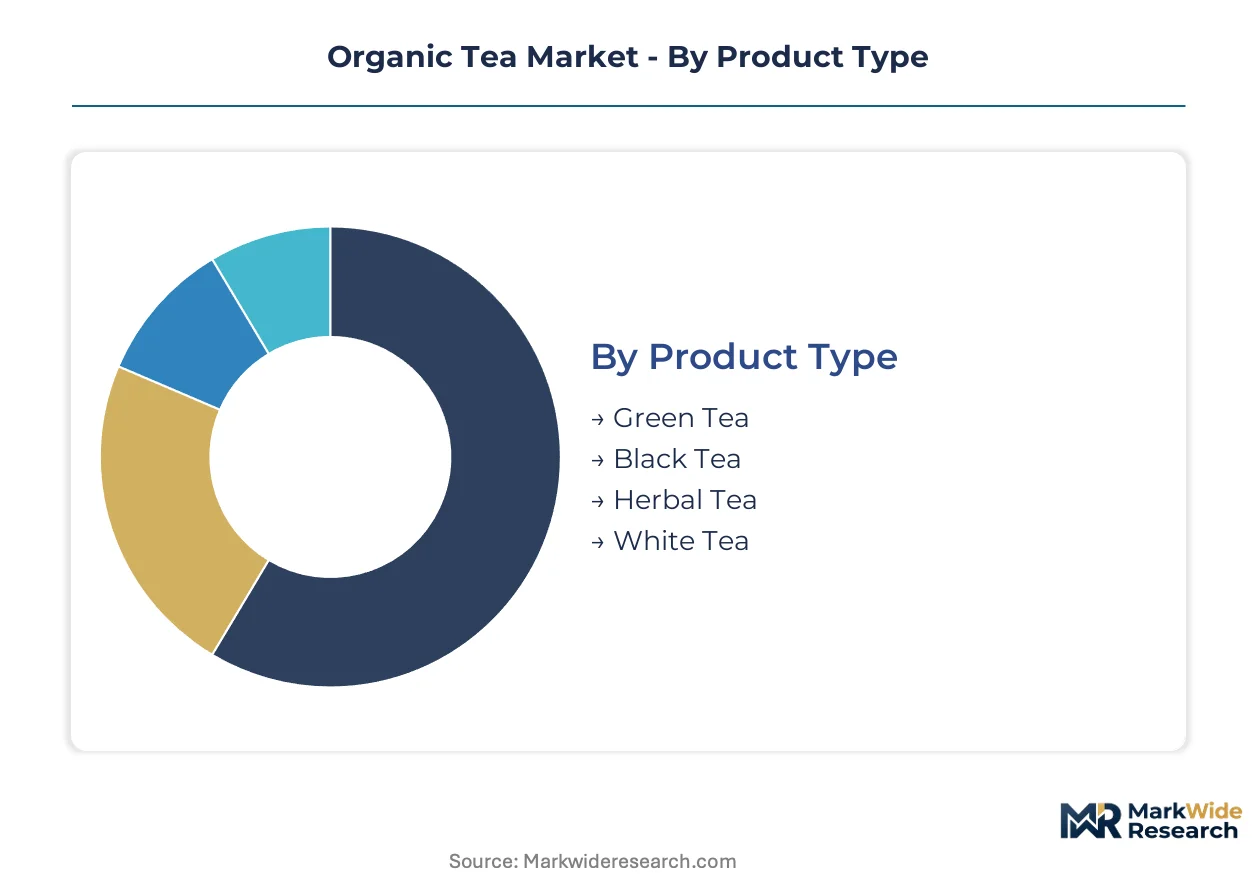
Certification standards fragment the organic tea landscape into distinct procurement tiers, with regulatory compliance costs concentrating supply among vertically integrated estates. Segmentation reveals how USDA Organic and EU Organic Regulation frameworks reshape competitive positioning across product formats and channel access.
Product Type:
USDA Organic and EU Organic Regulation frameworks govern residue thresholds and handling protocols differently across oxidized and non-oxidized leaf categories, creating tiered compliance burdens.
- Green Tea:Minimally oxidized Camellia sinensis leaves retain higher catechin concentrations that support functional wellness claims in German and French retail. Demand concentrates in specialty cafe channels where barista-crafted matcha preparations command price premiums through ceremonial-grade certification.
- Herbal Tea:Non-Camellia botanical infusions including chamomile, peppermint, and rooibos cultivated under organic soil management standards. Volume accelerates in caffeine-flexible consumption occasions as wellness-positioned hospitality buyers in Munich and Berlin expand procurement of certified loose-leaf varieties.
- Black Tea:Fully oxidized leaves from Assam and Darjeeling estates meeting APEDA-enforced export-grade organic compliance.
- White Tea:Minimal processing preserves delicate flavor profiles requiring dedicated handling lines under certified organic standards.
Established volume favors Black Tea; emerging adoption favors Herbal Tea.
End User:
Procurement authority varies sharply across buyer types, with sustainability officers in hospitality chains wielding veto power over supplier selection that household purchasers lack.
- Cafes:Wellness-focused hospitality channels in Germany and France unbundle procurement from commodity brokers to negotiate direct estate relationships. Menu differentiation drives certified organic loose-leaf expansion as sustainability credentials influence consumer choice in high-traffic urban locations.
- Specialty Stores:Curated retail environments in Vienna and Amsterdam emphasize single-origin provenance storytelling through blockchain-enabled traceability displays. Staff training investments support premium pricing for compostable-packaged certified lines.
- Households:Supermarket aisle penetration concentrates in Germany where organic certification outpaces other national markets.
- Restaurants:Fine-dining beverage programs leverage certified organic positioning for course-pairing narratives.
Margin concentration sits with Specialty Stores; volume scale sits with Households.
Form:
Processing infrastructure requirements create divergent barriers to entry, with cold-chain bottling concentrating ready-to-drink supply among multinationals while loose-leaf remains accessible to estate-direct brands.
- Ready-to-Drink:Bottled formulations requiring aseptic filling lines and refrigerated distribution networks that few pure-play organic brands can independently surmount. Convenience retail margin pools attract Unilever PLC and Tata Consumer Products Limited through existing beverage infrastructure.
- Loose Leaf:Whole-leaf formats favored by specialty hospitality buyers seeking brewing ritual authenticity and transparent provenance. German and Austrian retail buyers mandate compostable packaging convergence with organic certification for premium shelf placement.
- Tea Bags:Sachet formats face biodegradable material transition costs under EU Single-Use Plastics Directive pressure.
- Powdered:Instant and matcha preparations serving functional beverage formulation channels.
Capital intensity gates Ready-to-Drink; agility advantages accrue to Loose Leaf.
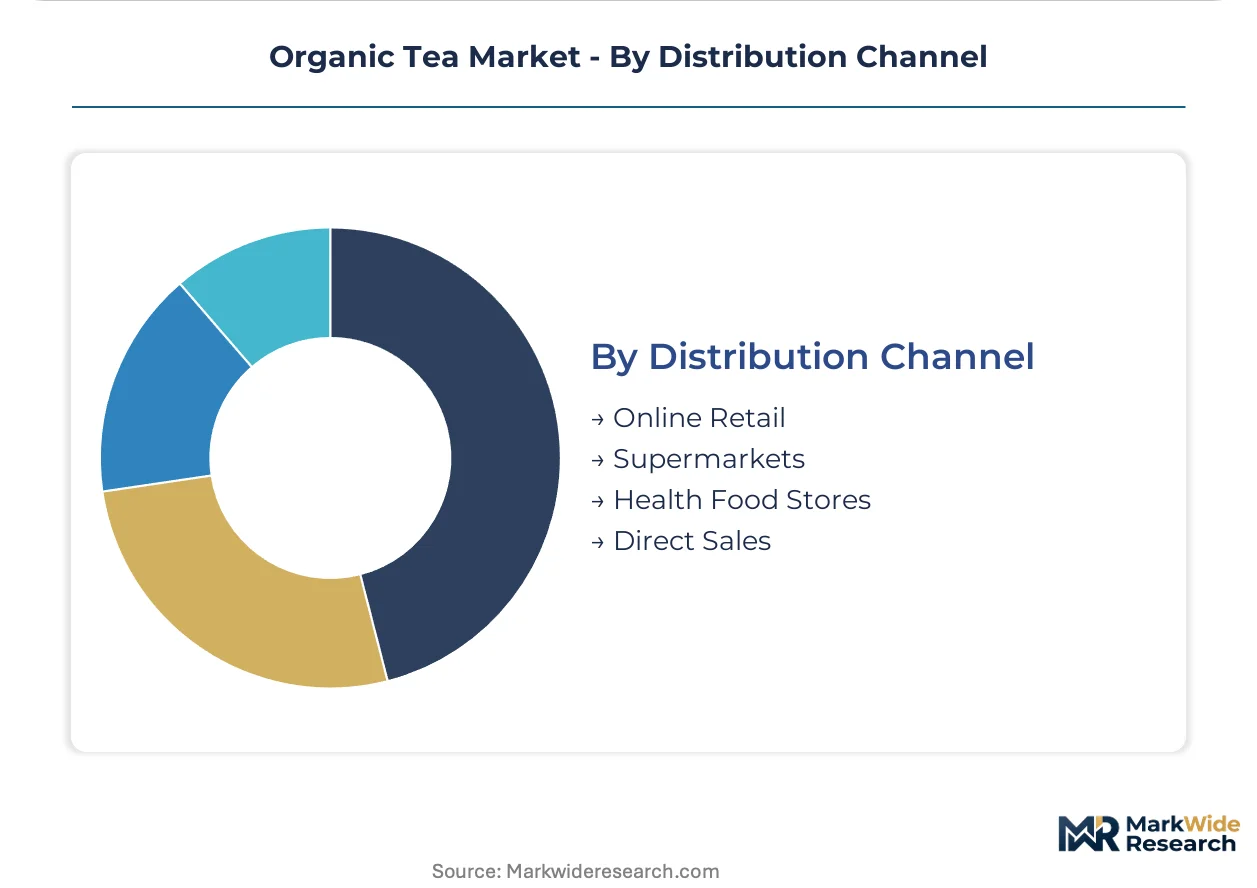
Distribution Channel:
Traceability requirements reshape channel economics, with digital provenance platforms enabling direct-to-consumer premiums that supermarket slotting fees erode.
- Online Retail:Plantation-to-consumer digital traceability platforms compress traditional opaque supply structures. Subscription models in Dutch and Belgian markets capture recurring revenue through curated single-origin certified lots with harvest-to-port visibility.
- Health Food Stores:Assortment depth in certified organic SKUs exceeds conventional supermarket offerings, with trained staff supporting premium price realization for compostable-packaged lines in German-speaking markets.
- Supermarkets:Mass-market shelf presence requires scale economics that favor Lipton and Tetley brand architectures.
- Direct Sales:Estate-direct relationships bypass broker margins for smallholder cooperatives meeting FSSAI export compliance.
Margin protection favors Online Retail; volume throughput favors Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across demand centers, with German retail buyers accepting steep premiums for certified organic provenance while price-sensitive mass markets in India and Brazil compress margins on conventional-grade conversions.
Germany
Specialty hospitality channels in Berlin and Munich unbundle procurement from commodity brokers to negotiate direct estate relationships. EU Green Deal Farm-to-Fork targets tighten maximum residue limits for agricultural imports entering through Hamburg and Bremen ports. Bavarian wellness hotel chains wield veto authority over beverage supplier selection, mandating compostable packaging convergence with organic certification.
United States
USDA Organic certification penetration drives shelf-space competition between mass-market brand architectures and premium direct-trade challengers. FDA labeling requirements for health claims constrain antioxidant positioning on ready-to-drink formulations. Pacific Northwest specialty cafe networks in Portland and Seattle expand certified loose-leaf procurement as menu differentiation.
India
Export-oriented plantations in Assam and Darjeeling convert synthetic-dependent acreage under APEDA-enforced organic compliance timelines. FSSAI export-grade standards open certified supply corridors into EU and North American markets. Smallholder cooperatives in West Bengal face consolidation pressure from certification audit cost concentration.
France
Boutique cafe networks in Paris and Lyon establish multi-year offtake agreements with certified estates, bypassing traditional commodity brokers. ANSM oversight of botanical health claims shapes functional wellness positioning for herbal infusions. Provence-Alpes-Côte d'Azur hospitality buyers emphasize single-origin provenance storytelling through blockchain-enabled traceability displays.
United Kingdom
Health food store chains in London and Manchester emphasize curated assortment depth exceeding conventional supermarket organic SKU counts. FSA guidance on novel food ingredients affects adaptogenic herbal blend formulations. Southeast England specialty distributors mandate real-time harvest-to-port visibility for EU-importing supply chains.
Organic Tea Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with digital traceability platforms enabling premium pricing for plantation-direct brands while multinational beverage infrastructure captures ready-to-drink margin pools through scale economics. The vendor base clusters around three strategic archetypes: vertically integrated plantation-to-retail specialists, mass-market brand licensors with organic transition pilots, and pure-play premium positioning specialists. Dominant competitive moves include direct-trade channel innovation and compostable packaging technology convergence.
Within the mass-market transition archetype, Unilever PLC and Tata Consumer Products Limited represent legacy brand architectures piloting certified organic lines in select European markets. Numi Inc. exemplifies the pure-play premium positioning specialist, occupying the certified tier through exclusive Fair Trade and organic focus. These three anchors illustrate how procurement authority is shifting from commodity brokers toward sustainability officers in hospitality chains and specialty retail buyers demanding transparent provenance.
| Leading Market Players |
|---|
| Unilever PLC |
| Tata Consumer Products Limited |
| Hain Celestial Group |
| Numi Inc. |
| Bigelow Tea Company |
| Davidson's Organics |
| Associated British Foods plc |
| Harney & Sons Fine Teas |
| The Republic of Tea Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day harvest-to-port lead times for certified organic leaf from Assam and Darjeeling estates compress pricing power for smallholder cooperatives while concentrating margin capture among vertically integrated exporters with dedicated EU-recognized control body accreditation.
Pricing Analysis
Subscription and multi-year offtake contracts drive lifetime value for plantation-direct brands negotiating with German specialty hospitality buyers. Pricing stratifies across ceremonial-grade single-origin, certified organic blending stock, and conventional commodity tiers. Cost compression in smallholder cooperatives is intensifying because natural pest management inputs and compost-based fertilizers command premiums over synthetic alternatives. Specialty cafe procurement officers in Berlin and Munich show least price sensitivity; mass-market supermarket buyers in price-sensitive markets compress margins on conventional-grade conversions.
Supply Chain Analysis
Port congestion at Hamburg and container availability constraints on Asia-Europe trade lanes extend inbound logistics costs for Indian and Sri Lankan exporters. Supply concentrates in India, Sri Lanka, and Kenya for Camellia sinensis leaf, with herbal botanicals drawing from Egypt, Morocco, and South Africa. Raw material dependencies rest on organic compost inputs, natural pest management formulations, and biodegradable packaging materials. Single-source vulnerability sits with EU-recognized certification bodies consolidating in Assam and Darjeeling. Distribution runs through specialty hospitality procurement offices, health food store chains, and plantation-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as sustainability officers in hospitality chains and specialty retail buyers unbundle procurement from commodity brokers, creating niche entry points for transparent provenance storytellers.
For Market Incumbents: Compound brand equity in mass-market shelf presence by piloting certified organic transitions in select European markets. Invest in backward integration into Assam and Darjeeling plantation partnerships to secure FSSAI export-grade compliance. Certification audit cost concentration threatens smallholder supply bases; capture this consolidation through direct estate relationships. For New Entrants and Emerging Players: Anchor in the direct-to-consumer subscription channel where digital traceability platforms compress traditional opaque supply structures. Target Dutch and Belgian markets with curated single-origin certified lots. Lead with compostable packaging technology convergence as the go-to-market differentiator for German and Austrian retail buyers. For Investors and Strategic Acquirers: Long-term, this sits as a premiumization play because functional wellness positioning and EU Green Deal regulatory tightening structurally expand addressable demand for certified organic provenance. Acquisition target archetype: vertically integrated plantation-to-retail specialists with EU-recognized control body accreditation and existing specialty hospitality offtake agreements. Watch carbon border adjustment mechanism implementation timelines as the inflection indicator for sourcing economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Trade Channel Innovation | Plantation-to-retailer digital traceability platforms enable price premiums through transparent provenance storytelling in German specialty hospitality. |
| Compostable Packaging Technology | Biodegradable sachet materials converge with EU Organic Regulation certification to capture premium-tier shelf space in Austrian retail. |
| EU-Recognized Control Body Consolidation | Accreditation density requirements in Assam and Darjeeling force recertification under stricter EU Organic Regulation 2018/848 equivalence agreements. |
| Specialty Hospitality Procurement Unbundling | Wellness-focused hotel chains in Bavaria bypass commodity brokers to negotiate multi-year offtake agreements with certified estates. |
| FSSAI Export-Grade Compliance Investment | APEDA-enforced organic standards for Indian plantations open certified supply corridors into EU and North American markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with sustainability officers in German hospitality chains, specialty cafe procurement managers in Berlin and Munich, plantation directors in Assam and Darjeeling, health food store category buyers in Vienna and Amsterdam, and organic certification control body auditors. Secondary validation drew from EU Organic Regulation 2018/848 implementation documents, APEDA export compliance filings, USDA Organic handler databases, customs trade data for organic tea shipments through Hamburg and Bremen ports, and Nielsen retail audit data for German supermarket organic SKU penetration. Bottom-up volume modeling triangulated with top-down value estimates across certification tiers.
Across the analysis window, the forecast framework modeled product type segmentation between green, herbal, black, and white tea; form factors spanning loose-leaf, tea bags, ready-to-drink, and powdered; and end-user categories including cafes, specialty stores, households, and restaurants. CAGRs were derived from weighted average growth assumptions across these dimensions, incorporating EU Green Deal Farm-to-Fork target compliance timelines, carbon border adjustment mechanism phase-in schedules, and specialty hospitality procurement expansion rates in Germany and France.
Material uncertainties — regulatory equivalence agreement revisions, carbon border adjustment mechanism implementation scope, and smallholder cooperative consolidation rates — sit outside the modeled envelope. Forecasts reflect assumptions about certification audit continuity and biodegradable packaging cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Nitro Tea Market
Tea
Africa Tea Market
Tea
Bottled Milk Tea Market
Tea
Europe Green Tea Market
Tea
Asia-Pacific Tea Market
Tea
Out of Home Tea Market
Tea
Mate Tea Market
Tea
US Ready to Drink Tea Market
Tea
Black Tea Extracts Market
Tea
Asia-Pacific Green Tea Market
Tea
Green Tea Extract Market
Tea
South America Tea Market
Tea
High Protein Tea Market
Tea
Middle East Ready to Drink Tea Market
Tea
Oolong Tea Market
Tea
Kombucha Tea Market