
 Specialty Ingredients Market | 2026-2036
Specialty Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Ingredients Market Outlook
Buyer concentration in the food processing sector is pivoting toward mid-sized clean-label producers alongside dominant multinational processors. Cargill Incorporated leverages its grain origination network to anchor supply security for plant-derived emulsifiers. Kerry Group plc differentiates through taste and nutrition integration labs spanning four continents. Givaudan specializes in captive biotechnology for natural fragrance precursors, reducing reliance on botanical harvesting cycles.
Specialty ingredients comprise functionally active compounds formulated at precise concentrations—typically 0.1% to 5% by weight—to deliver texture stability, flavor modulation, or bioactive efficacy in finished goods. Industrial production employs controlled fermentation, solvent extraction, or enzymatic conversion to achieve batch-to-batch consistency exceeding 99% purity thresholds. Flavoring agents and emulsifiers together command the dominant value share, reflecting entrenched demand from beverage reformulation and dairy alternative platforms. The natural source segment attracts premium positioning as clean-label procurement policies at North American and European retailers tighten synthetic additive exclusion lists. Powdered form factors lead volume throughput due to extended shelf stability and reduced logistics complexity.
The FDA's Food Safety Modernization Act mandates preventive controls for ingredient suppliers exporting to the United States, while REACH registration requirements in Europe compel full toxicological dossiers for novel synthetic molecules. India's BIS certification for food-grade additives and China's GB standards for pharmaceutical excipients create layered compliance thresholds that filter market entry. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Clean-label procurement mandates from North American and European retailers are compressing synthetic additive pipelines while fermentation-derived actives capture premium positioning. This structural pivot forces reformulation cycles across food, personal care, and pharmaceutical verticals.
Growth Catalysts
- Fermentation biotechnology:Controlled microbial production of bioactive compounds eliminates botanical harvesting variability. Personal care manufacturers in South Korea deploy this platform for peptide and enzyme actives.
- REACH registration requirements:Full toxicological dossiers for novel synthetic molecules in Europe filter competition and advantage dossier-ready suppliers. This regulatory threshold accelerates consolidation among compliant producers.
- India's pharmaceutical excipient corridor:Concentrated demand from generic drug manufacturers drives volume absorption of high-purity binders and disintegrants. Domestic BIS certification creates localized supply advantages.
Market Restraints
- Input cost volatility:Agricultural feedstock prices for plant-derived emulsifiers fluctuate with grain futures. Cargill's origination network partially insulates but cannot eliminate this exposure.
- Supply concentration risk:China's GB standards for pharmaceutical excipients create single-point qualification dependencies. Foreign suppliers face extended approval timelines for excipient registration.
- Technical limitation in natural preservation:Clean-label antimicrobial systems lack the broad-spectrum efficacy of synthetic alternatives. Beverage reformulation platforms accept shortened shelf lives as trade-offs.
Strategic Opportunities
- Underpenetrated geography:Brazil's ANVISA regulatory alignment with ICH guidelines opens excipient qualification pathways previously blocked by divergent standards. Local production partnerships reduce import duty exposure.
- Emerging application:Dairy alternative platforms require emulsifier systems that replicate mouthfeel without casein functionality. Oat and pea protein bases drive tailored hydrocolloid development.
- Regulatory tailwind:The EU Green Deal's tightening chemical disclosure rules for imported formulations advantage suppliers with transparent supply chain documentation. Early compliance converts into retailer preferred vendor status.
Industry Challenges
- Certification timeline compression:India's BIS certification for food-grade additives requires 18-24 month qualification cycles. Reformulation projects stall awaiting batch release approvals.
- Integration complexity with legacy systems:Powdered ingredient handling infrastructure at mid-sized clean-label producers lacks the containment and traceability of multinational facilities. Capital retrofit requirements strain procurement budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Ingredients Market |
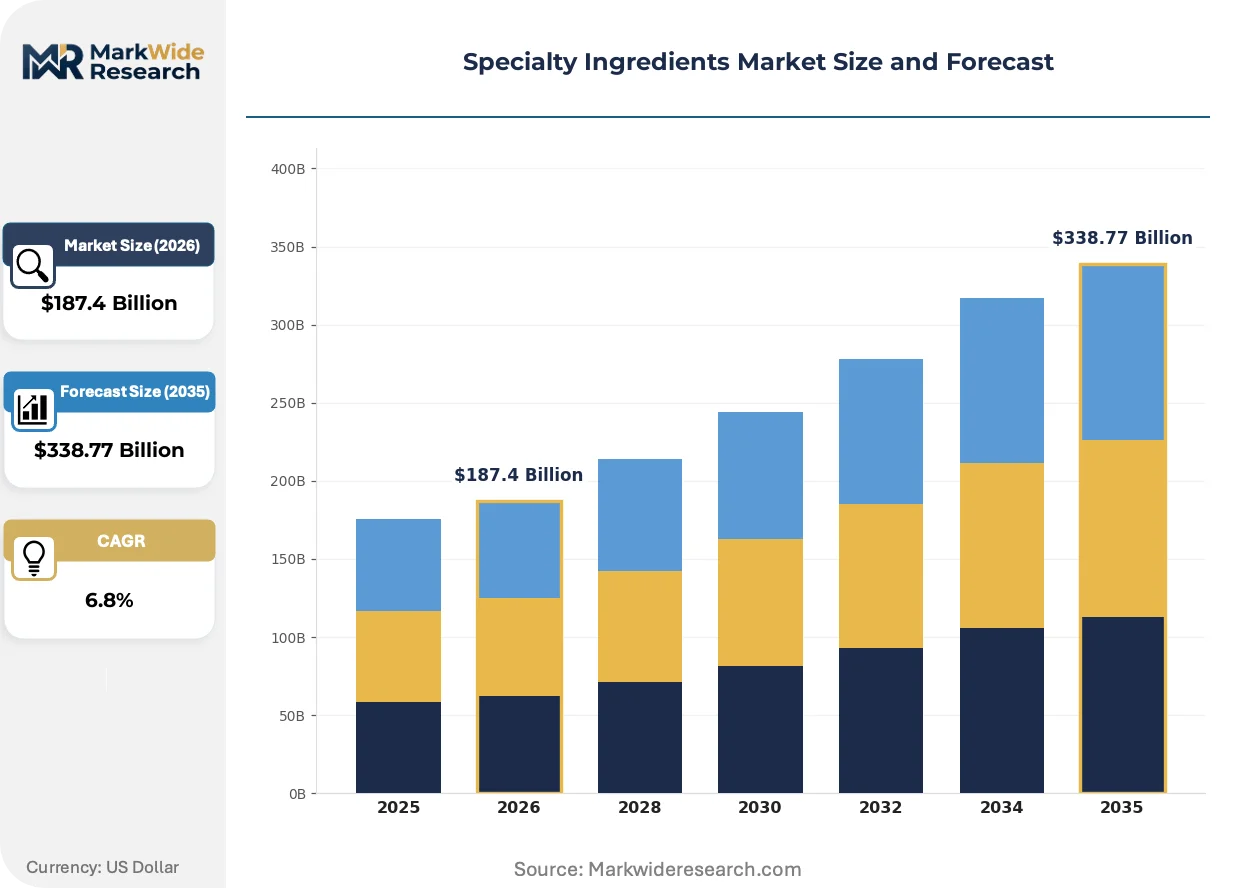
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flavoring Agents, Emulsifiers, Thickeners, Colorants Application: Food & Beverage, Pharmaceuticals, Personal Care, Animal Feed Form: Powdered, Liquid, Granular, Paste Source: Natural, Synthetic, Fermentation, Enzymatic |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Kerry Group plc, Ingredion Incorporated, Tate & Lyle plc, DuPont de Nemours Inc., Koninklijke DSM N.V., International Flavors & Fragrances Inc., Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Ingredients Market Strategic Shifts
Fermentation-derived actives, regulatory disclosure mandates, and procurement consolidation are restructuring how specialty ingredients move from production to formulation. These forces compress traditional supply hierarchies.
Precision fermentation platforms are absorbing the production of high-value bioactives previously extracted from botanical sources. Cosmetic formulators in South Korea adopt these actives at accelerated qualification paces. The technology is absorbing margin pressure from weather-dependent crop yields while delivering batch-to-batch consistency above 99% purity thresholds.
REACH registration requirements in Europe compel full toxicological dossiers for novel synthetic molecules. Industrial consequence includes multi-year qualification timelines that filter market entry to well-capitalized suppliers. Pharmaceutical excipient categories face the most acute compliance burden, driving backward integration into captive toxicology testing.
Buyer concentration in the food processing sector pivots toward mid-sized clean-label producers alongside dominant multinational processors. Direct supplier relationships displace distributor intermediaries for technical ingredient categories. North American retailer clean-label procurement policies accelerate this channel compression.
Specialty Ingredients Market Segmentation
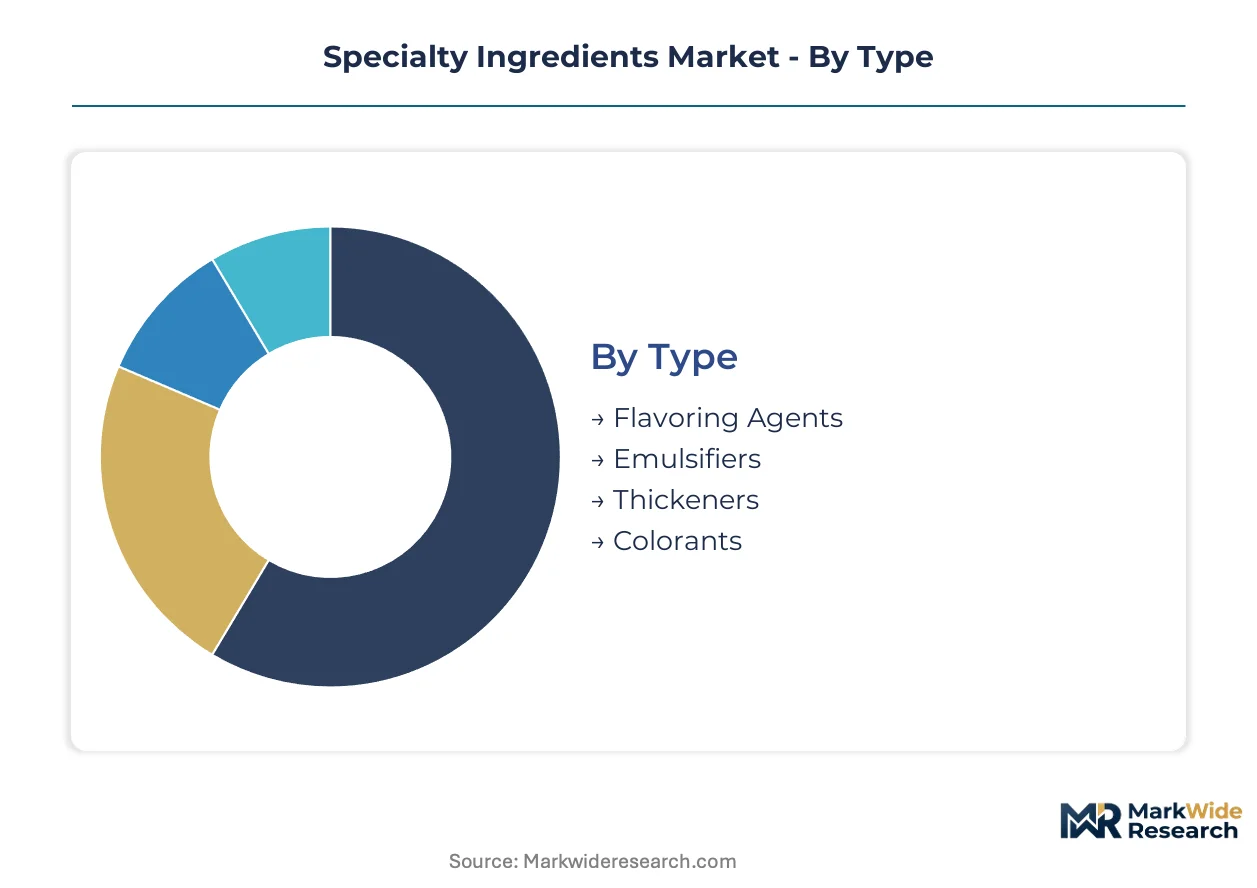
Specialty ingredients require precise functional matching between chemical specifications and end-use processing constraints. Formulators select segments based on stability thresholds, regulatory clearance status, and compatibility with existing production lines.
Type:
Buyers prioritize functional efficacy and label positioning when selecting ingredient types.
- Flavoring Agents:Complex volatile compounds formulated at 0.01% to 2% concentration to deliver taste modulation without caloric load. Beverage reformulation platforms in the United States absorb the largest volumes as sugar reduction mandates tighten. Natural extraction and fermentation-derived alternatives command premium positioning over synthetic counterparts.
- Emulsifiers:Surface-active agents stabilizing immiscible phases at oil-water interfaces, typically lecithin, mono- and diglycerides, or polysorbates. Dairy alternative manufacturers deploy tailored hydrocolloid systems to replicate casein mouthfeel in oat and pea protein bases. Clean-label procurement policies exclude synthetic emulsifiers from retailer-approved formulations.
- Thickeners:Hydrocolloids and starches modifying viscosity and texture in finished goods.
- Colorants:Pigments and dyes achieving visual appeal across packaged food and personal care applications.
Flavoring agents lead on scale; emulsifiers lead on momentum.
Application:
Application selection hinges on regulatory pathway complexity and batch size requirements.
- Food & Beverage:The largest absorption channel spanning bakery, confectionery, beverages, and savory applications. FDA Food Safety Modernization Act preventive controls and EU food additive regulations create layered compliance thresholds. Clean-label mandates from North American retailers compress synthetic additive pipelines.
- Pharmaceuticals:High-purity excipients including binders, disintegrants, and coating agents for solid dosage forms. India's pharmaceutical corridor concentrates demand from generic drug manufacturers; BIS certification creates localized supply advantages. REACH registration requirements in Europe filter competition to dossier-ready suppliers.
- Personal Care:Active ingredients and functional additives for skin, hair, and oral care formulations.
- Animal Feed:Palatability enhancers and nutritional supplements for livestock and pet nutrition.
Food & beverage dominates volume absorption; pharmaceuticals climbs fastest on regulatory premium capture.
Form:
Form factor selection balances shelf stability against dissolution kinetics and handling infrastructure.
- Powdered:Dried particulate forms offering extended shelf stability and reduced logistics complexity. Mid-sized clean-label producers favor powders for compatibility with existing pneumatic conveying systems. Moisture sensitivity remains the primary storage constraint.
- Liquid:Ready-to-dispense solutions eliminating reconstitution steps in continuous processing lines. Beverage manufacturers prefer liquid colorants and flavors for uniform distribution in high-speed filling operations.
- Granular:Free-flowing intermediate particle sizes combining powder stability with liquid dispersibility.
- Paste:High-viscosity semi-solids for concentrated flavor delivery and controlled release applications.
Powdered form leads on scale; liquid form gains share fastest in beverage processing.
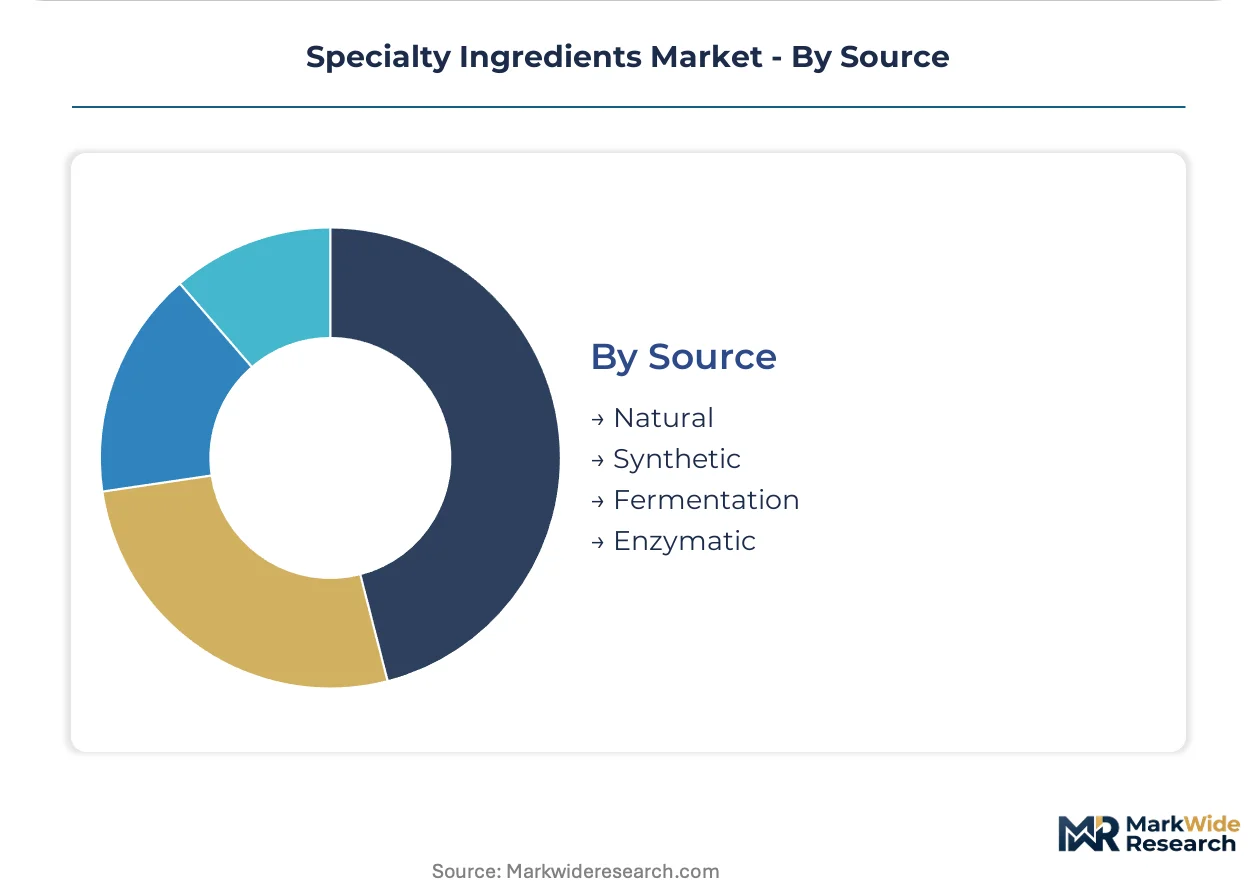
Source:
Source selection increasingly reflects procurement policy constraints rather than purely technical specifications.
- Natural:Botanical extracts and minimally processed derivatives meeting clean-label exclusion criteria. EU Green Deal disclosure rules for imported formulations advantage suppliers with transparent botanical harvesting documentation. Weather-dependent crop yields introduce supply variability that fermentation platforms now address.
- Synthetic:Petrochemical-derived molecules offering batch consistency and cost efficiency. REACH registration requirements and retailer exclusion lists compress addressable market share in Europe and North America.
- Fermentation:Controlled microbial production of bioactive compounds achieving purity thresholds above 99%. Personal care manufacturers in South Korea deploy this platform for peptide and enzyme actives at accelerated qualification paces.
- Enzymatic:Biocatalytic conversion processes modifying substrate specificity and reaction conditions.
Natural source leads on scale; fermentation source expands most quickly on biotechnology investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical excipient corridor absorbs high-purity binders at scale, while South Korean personal care manufacturers deploy fermentation-derived actives with accelerated qualification timelines. These contrasting demand profiles illustrate how regional specialization shapes ingredient sourcing patterns.
United States
Beverage reformulation platforms drive absorption of sugar-reduction flavor systems and clean-label emulsifiers. The FDA's Food Safety Modernization Act mandates preventive controls for ingredient suppliers, filtering market entry through compliance capability. Chicago and Minneapolis anchor Midwest processing clusters where mid-sized clean-label producers retrofit pneumatic conveying infrastructure.
Germany
REACH registration requirements compel full toxicological dossiers for novel synthetic molecules, advantageing dossier-ready suppliers with captive testing capabilities. The EU Green Deal tightens chemical disclosure rules for imported formulations, converting early compliance into retailer preferred vendor status. Frankfurt's logistics hub concentrates excipient distribution for European pharmaceutical manufacturers.
China
GB standards for pharmaceutical excipients create single-point qualification dependencies that extend foreign supplier approval timelines. Domestic fermentation biotechnology platforms achieve batch-to-batch consistency exceeding 99% purity thresholds for bioactive compounds. Shanghai's Yangtze River Delta cluster houses concentrated taste and nutrition integration facilities serving Asian beverage markets.
India
Generic drug manufacturers in the pharmaceutical excipient corridor drive volume absorption of high-purity binders and disintegrants. BIS certification for food-grade additives creates localized supply advantages through 18-24 month qualification cycles. Hyderabad and Mumbai anchor domestic production of pharmaceutical-grade hydrocolloids and starch derivatives.
South Korea
Personal care manufacturers deploy precision fermentation platforms for peptide and enzyme actives at accelerated qualification paces. MFDS regulatory alignment with ICH guidelines streamlines excipient registration for domestic formulators. Seoul Capital Area laboratories specialize in captive biotechnology for natural fragrance precursors, reducing reliance on botanical harvesting cycles.
Specialty Ingredients Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across ingredient categories, creating a tiered structure where scale-driven processors anchor supply security while biotechnology laboratories capture premium positioning. The vendor base stratifies across three archetypes: grain-origination networks securing agricultural feedstock pipelines, taste-and-nutrition integrators operating multi-continent technical facilities, and captive biotechnology platforms eliminating botanical variability. Consolidation pressures intensify as REACH dossier requirements and retailer clean-label mandates filter competition toward well-capitalized, compliance-ready producers. Dominant competitive moves include backward integration into captive toxicology testing and geographic expansion through local production partnerships.
Within the diversified agribusiness tier, Cargill Incorporated exemplifies supply security strategies through grain origination networks, while Archer Daniels Midland Company occupies a comparable position in agricultural processing infrastructure. Kerry Group plc represents the taste-and-nutrition integrator archetype with technical facilities spanning multiple continents. These three entities anchor competitive positioning across distinct capability vectors.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Kerry Group plc |
| Ingredion Incorporated |
| Tate & Lyle plc |
| DuPont de Nemours Inc. |
| Koninklijke DSM N.V. |
| International Flavors & Fragrances Inc. |
| Givaudan |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in India's pharmaceutical excipient corridor anchor supply discipline through multi-decade customer relationships, converting BIS certification timelines into pricing power that offsets agricultural feedstock volatility elsewhere.
Pricing Analysis
Capacity additions in China's fermentation biotechnology platforms are reshaping price floors for natural-source actives, compressing premiums previously captured by botanical extract suppliers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered synthetic molecules from clean-label natural derivatives and commodity-grade alternatives. Pricing pressure stems from clean-label procurement mandates excluding synthetic emulsifiers, forcing reformulation costs onto suppliers. Mid-sized clean-label producers exhibit highest price sensitivity due to capital constraints on pneumatic conveying retrofits, while multinational processors absorb premiums for supply security.
Supply Chain Analysis
Freight cost differentials between powdered and liquid form factors determine regional sourcing radii, with moisture-sensitive powders favoring localized production. Supply concentrates in India, China, and Germany for pharmaceutical-grade hydrocolloids, fermentation-derived bioactives, and REACH-compliant synthetics respectively. Raw material dependencies include grain futures for plant-derived emulsifiers, microbial feedstocks for precision fermentation, and petrochemical derivatives for synthetic colorants. Single-source vulnerability runs through China's GB standards for excipient registration, extending foreign supplier qualification timelines. Distribution runs through direct supplier relationships displacing distributor intermediaries for technical ingredient categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
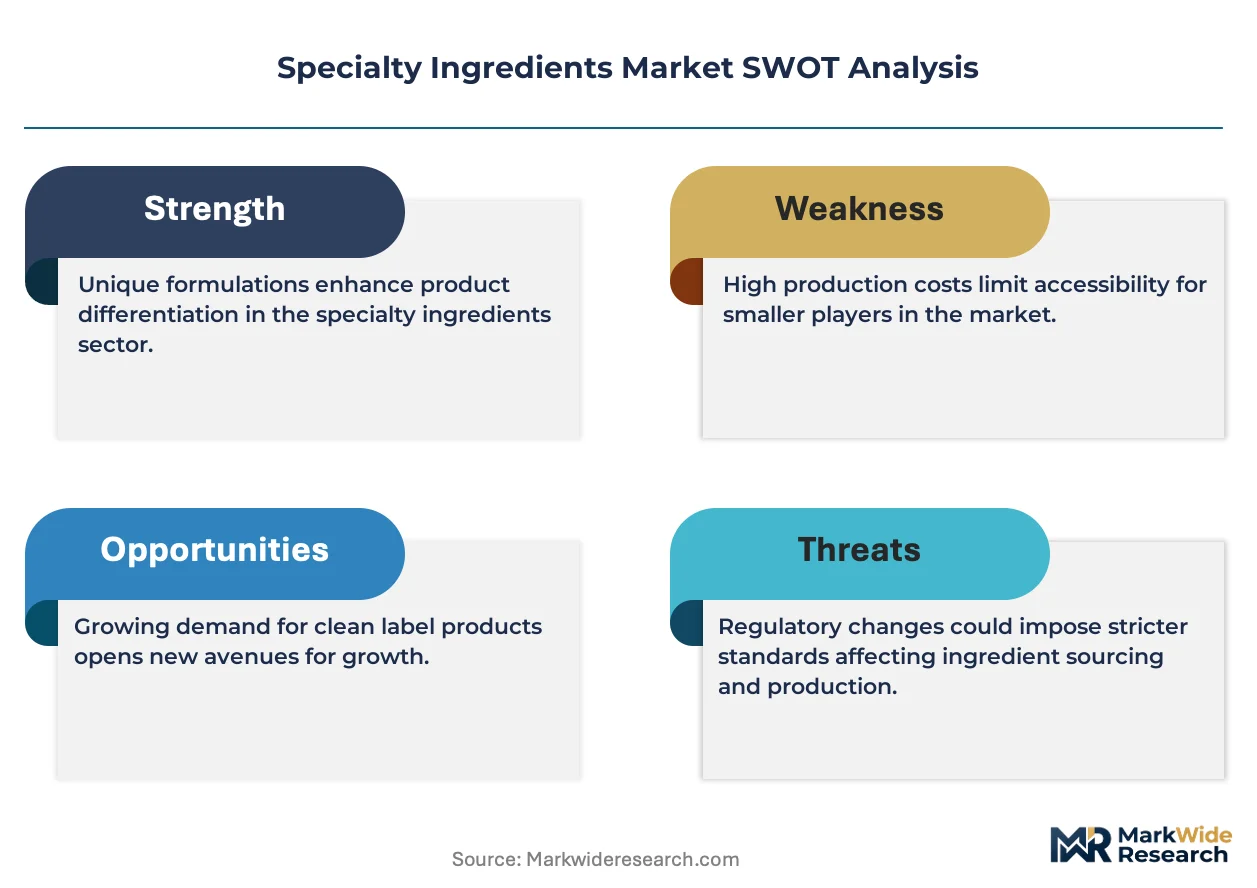
Margin expansion in specialty ingredients rests on fermentation biotechnology cost curves flattening faster than botanical harvesting cycles, while clean-label premiums widen the standard-economy spread.
For Market Incumbents: Deploy backward integration into captive toxicology testing to compress REACH dossier timelines and filter competition. Secure grain origination networks to insulate plant-derived emulsifier margins from agricultural volatility. Consolidate around taste-and-nutrition integration labs spanning multiple continents to capture dairy alternative platform demand. Counter threat from precision fermentation entrants by accelerating BIS certification batch releases in India's pharmaceutical corridor. For New Entrants and Emerging Players: Launch via local production partnerships in Brazil's ANVISA-aligned regulatory environment to bypass import duty exposure and excipient qualification barriers. Target Brazil's underpenetrated clean-label food processing sector where mid-sized producers lack pneumatic conveying infrastructure. Exploit technical limitation in natural preservation systems by developing clean-label antimicrobial platforms with acceptable shelf-life trade-offs. Penetrate through direct supplier relationships offering formulation technical service that distributor intermediaries cannot match. For Investors and Strategic Acquirers: Valuations sit cheapest among fermentation biotechnology pure-plays lacking downstream formulation integration. Long-term viability favors suppliers with captive supply of microbial feedstocks and multi-jurisdiction regulatory dossiers. Acquisition target archetype: mid-cap specialists with BIS certification and established relationships in India's pharmaceutical excipient corridor. Watch for inflection when EU Green Deal disclosure rules convert early compliance into retailer preferred vendor status.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Fermentation | Eliminates botanical harvesting variability while achieving 99% purity thresholds for South Korean personal care manufacturers. |
| REACH Dossier Completion | Filters synthetic molecule competition to well-capitalized suppliers with European pharmaceutical excipient access. |
| Local Production Partnership in Brazil | Reduces ANVISA import duty exposure and accelerates excipient qualification previously blocked by divergent standards. |
| Clean-Label Antimicrobial Development | Addresses technical efficacy gaps that currently force beverage reformulation platforms into shortened shelf-life trade-offs. |
| BIS Certification Investment | Creates 18-24 month localized supply advantages in India's pharmaceutical corridor through batch release control. |
Study Parameters
Multiple input streams — primary interviews with plant managers and procurement leads at downstream food and pharmaceutical manufacturers, technical R&D directors at fermentation biotechnology platforms, and distribution channel partners — were reconciled against secondary validation from customs and trade data, SEC filings of diversified ingredient suppliers, and regulatory dossier databases including FDA Food Safety Modernization Act guidance documents and ECHA REACH registration records. Bottom-up volume estimates by segment were triangulated against top-down market sizing.
Historical capacity utilization patterns were cross-referenced against panel input from industry stakeholders to model growth trajectories across the projection horizon. Segmentation dimensions included ingredient type, application vertical, form factor, and source technology, with regional production hub clustering as an additional modeling layer. CAGRs were derived through regression analysis of historical absorption rates and forward-looking qualification timeline assumptions. Forecast inputs incorporated BIS certification cycle lengths, EU Green Deal implementation phasing, and fermentation platform yield improvements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained agricultural commodity volatility or abrupt regulatory divergence between FDA preventive controls and EU disclosure mandates. Model assumptions reflect documented stakeholder input and published regulatory guidance. A model refresh is warranted upon material change in REACH registration fee structures or MFDS regulatory alignment revisions affecting South Korean excipient pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Mango Butter Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Specialty Meat Ingredients Market