
 Tamanu Oil Market | 2026-2036
Tamanu Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Tamanu Oil Market Analysis
Multi-source procurement among Pacific Island cooperatives and Southeast Asian processors is rebalancing toward vertically integrated estate operations. Henry Lamotte Oils anchors European pharmaceutical-grade supply through controlled cold-chain logistics. Mountain Rose Herbs competes via certified organic sourcing protocols and direct farmer partnerships. NOW Foods extends retail penetration through mass-market personal care channels in North America.
Tamanu oil is a fixed vegetable oil cold-pressed from the kernels of Calophyllum inophyllum, containing calophyllolide and inophyllum as characteristic bioactive lactones with documented cicatrizing and antimicrobial properties. Cosmetics applications dominate volume consumption, with cold-pressed grades commanding premium positioning due to intact polyphenol retention. Pharmaceutical applications represent the fastest-expanding segment, driven by wound-healing and dermatological formulation demand. Bulk container packaging for business-to-business channels captures the largest margin pool, while sachet formats penetrate emerging direct-to-consumer segments.
USDA organic certification and EU REACH registration govern raw material acceptance criteria for international market access. FDA oversight of cosmetic ingredient safety through the Voluntary Cosmetic Registration Program shapes US import documentation burdens. ISO 17025-accredited testing for calophyllolide content and oxidative stability indicators determines batch eligibility for pharmaceutical contracts. Stakeholders must calibrate inventory strategies against cyclical kernel harvest variability and evolving bioprospecting regulations in source countries.
Market Dynamics
Cold-chain logistics standardization is rewriting procurement hierarchies in pharmaceutical-grade tamanu oil, compressing margins for intermediaries while rewarding processors with ISO 17025-accredited laboratories and direct estate control over kernel sourcing.
Growth Catalysts
- EU Cosmetics Regulation enforcement:Traceability mandates for natural ingredients are pulling cosmetic formulators toward certified organic supply chains with documented chain-of-custody records.
- Wound-healing formulation demand:Pharmaceutical laboratories are expanding calophyllolide assay requirements for cicatrizing applications in dermatological preparations.
- Vietnamese cultivation clusters:Kernel harvest consolidation around Mekong Delta processing cooperatives is shortening supply lead times for European cold-press facilities.
Market Restraints
- Kernel supply cyclicality:Calophyllum inophyllum harvests fluctuate with monsoon patterns, creating raw material availability gaps that strain inventory planning for continuous processors.
- REACH registration costs:Small-scale Pacific Island cooperatives face documentation burdens that exclude them from direct EU market access without toll-processing arrangements.
- Synthetic emollient substitution:Petrochemical-derived alternatives with stable pricing and consistent specifications capture cost-sensitive personal care formulations.
Strategic Opportunities
- Direct-to-consumer sachet formats:Single-use packaging is opening retail penetration in urban Vietnamese and Indonesian markets previously served only by bulk B2B channels.
- USDA Organic certification tailwind:Premium personal care brands in North America are mandating certified organic inputs, creating price premiums for compliant suppliers.
- Bioprospecting framework evolution:Nagoya Protocol implementation in source countries is enabling benefit-sharing agreements that secure long-term estate access for vertically integrated processors.
Industry Challenges
- Calophyllolide assay standardization:Variable testing protocols across ISO 17025 laboratories create batch rejection disputes between processors and pharmaceutical contract manufacturers.
- Skilled cold-press technician scarcity:Temperature-controlled extraction expertise concentrates in French and German processing facilities, limiting quality replication in emerging supply regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tamanu Oil Market |
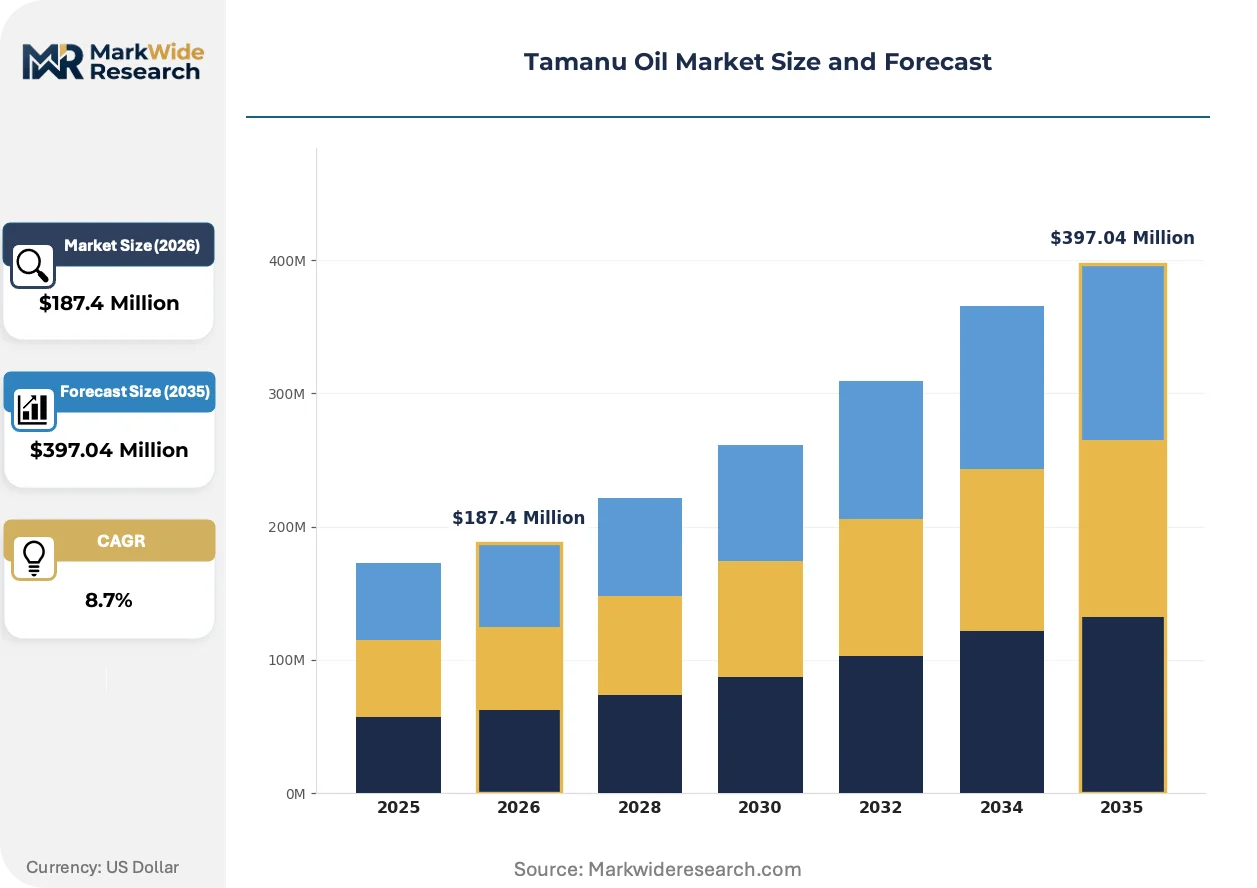
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed, Refined, Organic, Conventional Application: Cosmetics, Pharmaceuticals, Food Industry, Personal Care End User: Manufacturers, Retailers, Distributors, Consumers Packaging Type: Bottles, Jars, Bulk Containers, Sachets |
| Companies Covered | NOW Foods, Mountain Rose Herbs, Henry Lamotte Oils, Nutiva, Aditi Essentials, Earthoil, US Organic Group Corp., Leven Rose, Aura Cacia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tamanu Oil Market Emerging Trajectories
Supercritical CO2 extraction is displacing conventional cold-press methods in premium cosmetic applications, while blockchain traceability platforms and regenerative agriculture protocols are converging to reshape buyer qualification criteria.
Supercritical CO2 extraction systems are rewriting quality benchmarks for polyphenol retention in cosmetic-grade tamanu oil. French and German formulators are adopting this technology at pilot scale, demanding certificates of analysis with expanded oxidative stability indicators. The technology is compressing the viable supplier base toward capital-intensive processors with in-house analytical capabilities.
EU REACH registration deadlines for existing natural substances are forcing inventory requalification across cosmetic and pharmaceutical supply chains. Industrial consequence includes mandatory safety data sheet updates and extended substance volume tracking. German importers are responding by consolidating procurement around pre-registered suppliers with established dossier maintenance.
Certification-driven procurement is fragmenting buyer-seller relationships in North American retail channels. Mass-market personal care brands are unbundling from traditional distributors to source directly from USDA Organic-certified estates, replacing spot-market purchasing with annual offtake agreements. This pattern concentrates in California and Pacific Northwest natural product retail clusters.
Tamanu Oil Market Segmentation
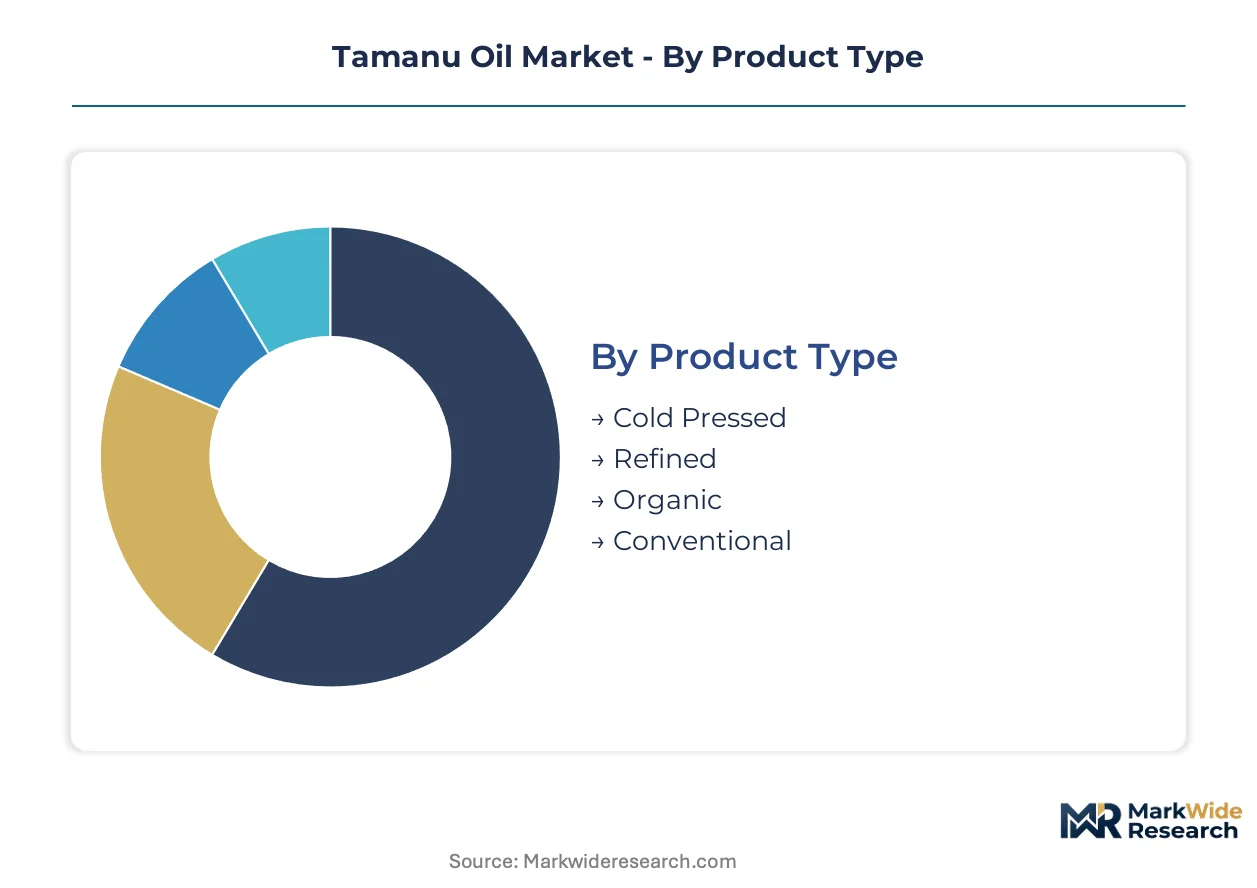
Tamanu oil segmentation reflects divergent buyer requirements across pharmaceutical precision and cosmetic volume markets. Cold-pressed grades command specification rigor from European formulators, while mass-market channels absorb refined variants at scale. Understanding these tiered demand profiles enables processors to align extraction investments with margin capture opportunities.
Product Type:
Customization intensity spans from artisanal cold-pressed batches to standardized refined commodities, with organic certification adding a parallel qualification layer.
- Cold Pressed:Temperature-controlled extraction below 40°C preserves calophyllolide and inophyllum lactones intact. French pharmaceutical laboratories specify this grade for wound-healing formulations, with Henry Lamotte Oils maintaining cold-chain logistics from Vietnamese estates to European ports.
- Organic:USDA certification and EU organic seals mandate kernel traceability to pesticide-free cultivation plots. North American premium personal care brands now require certified organic inputs, creating price premiums for Mekong Delta cooperatives with documented conversion timelines.
- Refined:Bleached and deodorized for color consistency in mass cosmetic bases.
- Conventional:Standard extraction without certification overlay serves cost-sensitive industrial buyers.
Leading the category by volume: Conventional. Growing fastest: Organic.
Application:
End-use differentiation separates high-assay pharmaceutical contracts from cosmetic volume plays, with food industry penetration emerging as a regulatory frontier.
- Pharmaceuticals:Cicatrizing and antimicrobial properties drive dermatological formulation demand. ISO 17025-accredited calophyllolide assays determine batch eligibility, with German contract manufacturers expanding assay requirements for wound-healing preparations.
- Cosmetics:Polyphenol retention determines premium positioning for anti-aging and skin repair serums. Supercritical CO2 extraction systems in French pilot facilities are rewriting quality benchmarks for this segment.
- Personal Care:Mass-market lotions and hair oils absorb refined grades at volume scale.
- Food Industry:Novel food approval pathways in EU and US markets remain underdeveloped for tamanu oil.
Pharmaceuticals capture the steepest expansion trajectory. Cosmetics anchor current volume concentration.
End User:
Channel structure concentrates procurement power among manufacturers while direct-to-consumer formats fragment final-mile distribution.
- Manufacturers:Cosmetic and pharmaceutical formulators drive specification-setting with certified organic and cold-pressed requirements. Annual offtake agreements are replacing spot-market purchasing for California and Pacific Northwest natural product clusters.
- Distributors:Traditional intermediaries face margin compression from cold-chain logistics standardization and blockchain traceability platforms that enable direct estate relationships.
- Retailers:Natural product stores and apothecaries curate certified organic SKUs for ingredient-conscious consumers.
- Consumers:Direct-to-consumer sachet formats are penetrating urban Vietnamese and Indonesian markets previously served only by bulk B2B channels.
Manufacturers dominate procurement volume. Consumers represent the most rapidly expanding channel.
Packaging Type:
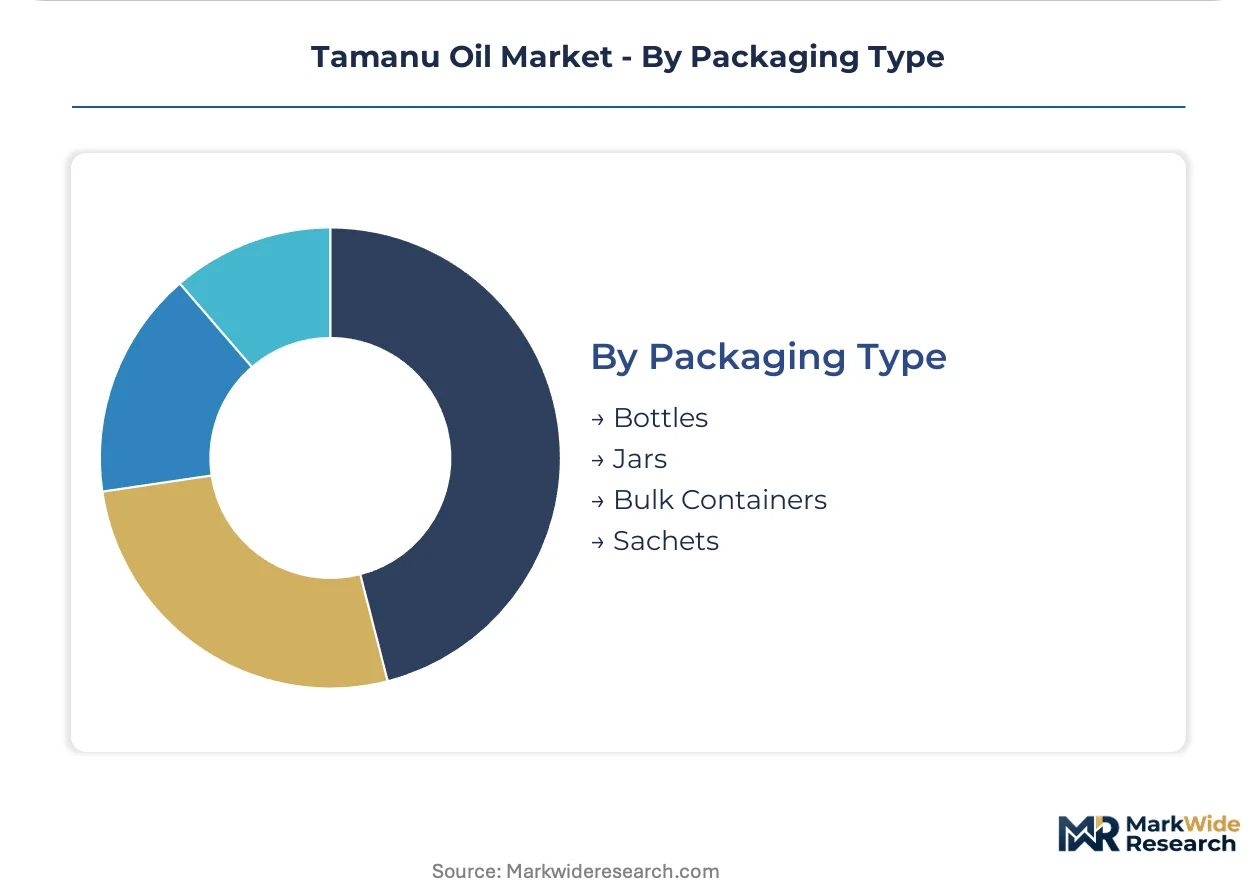
Format economics separate industrial margin pools from retail accessibility plays, with single-use innovations disrupting traditional bulk dominance.
- Bulk Containers:Stainless steel drums and intermediate bulk containers capture the largest margin pool for pharmaceutical and cosmetic manufacturers. Vietnamese processors are consolidating procurement around Mekong Delta cooperatives to shorten supply lead times for European cold-press facilities.
- Sachets:Single-use 5-10ml formats are opening retail penetration in Southeast Asian urban markets. Indonesian direct-to-consumer brands are piloting subscription models for monthly sachet deliveries.
- Bottles:Amber glass and PET formats serve apothecary and natural product retail channels.
- Jars:Cosmetic-grade packaging for balms and concentrated repair creams.
Bulk containers lead by volume. Sachets are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kernel harvests from Vietnamese Mekong Delta estates and Indonesian archipelago cooperatives anchor raw material flows for pharmaceutical and cosmetic processors across three continents.
Vietnam
Mekong Delta cultivation clusters supply cold-pressed grades to French pharmaceutical laboratories. The Ministry of Agriculture and Rural Development enforces Good Agricultural Practice protocols for export-bound kernel lots. Ho Chi Minh City processing facilities consolidate procurement from Ben Tre and Tien Giang province cooperatives, shortening supply lead times for European cold-press operations.
Indonesia
Archipelago-wide Calophyllum inophyllum estates feed both domestic cosmetic brands and bulk pharmaceutical exporters. The National Agency for Drug and Food Control regulates novel ingredient notifications for dermatological preparations. Sulawesi and Maluku island processors direct organic-certified output toward North American premium personal care channels through Jakarta export consolidators.
Germany
Pharmaceutical-grade importers drive calophyllolide assay standardization across EU supply chains. ECHA REACH registration requirements filter raw material acceptance toward pre-registered Vietnamese and Indonesian suppliers. Hamburg and Bremen port facilities maintain cold-chain logistics for temperature-sensitive pharmaceutical contracts.
France
Premium cosmetic formulators in Provence and Île-de-France specify supercritical CO2 extraction outputs for polyphenol-retentive applications. ANSM oversight of cosmetic ingredient safety shapes documentation burdens for imported natural substances. Grasse-area compounding laboratories pilot blockchain traceability platforms for certified organic supply verification.
United States
California and Pacific Northwest natural product retail clusters mandate USDA Organic certification for shelf placement. FDA Voluntary Cosmetic Registration Program documentation shapes import screening for Vietnamese and Indonesian kernel derivatives. Oregon and Washington State-based direct-to-consumer brands unbundle from traditional distributors to source via annual offtake agreements.
Tamanu Oil Market Vendor Landscape
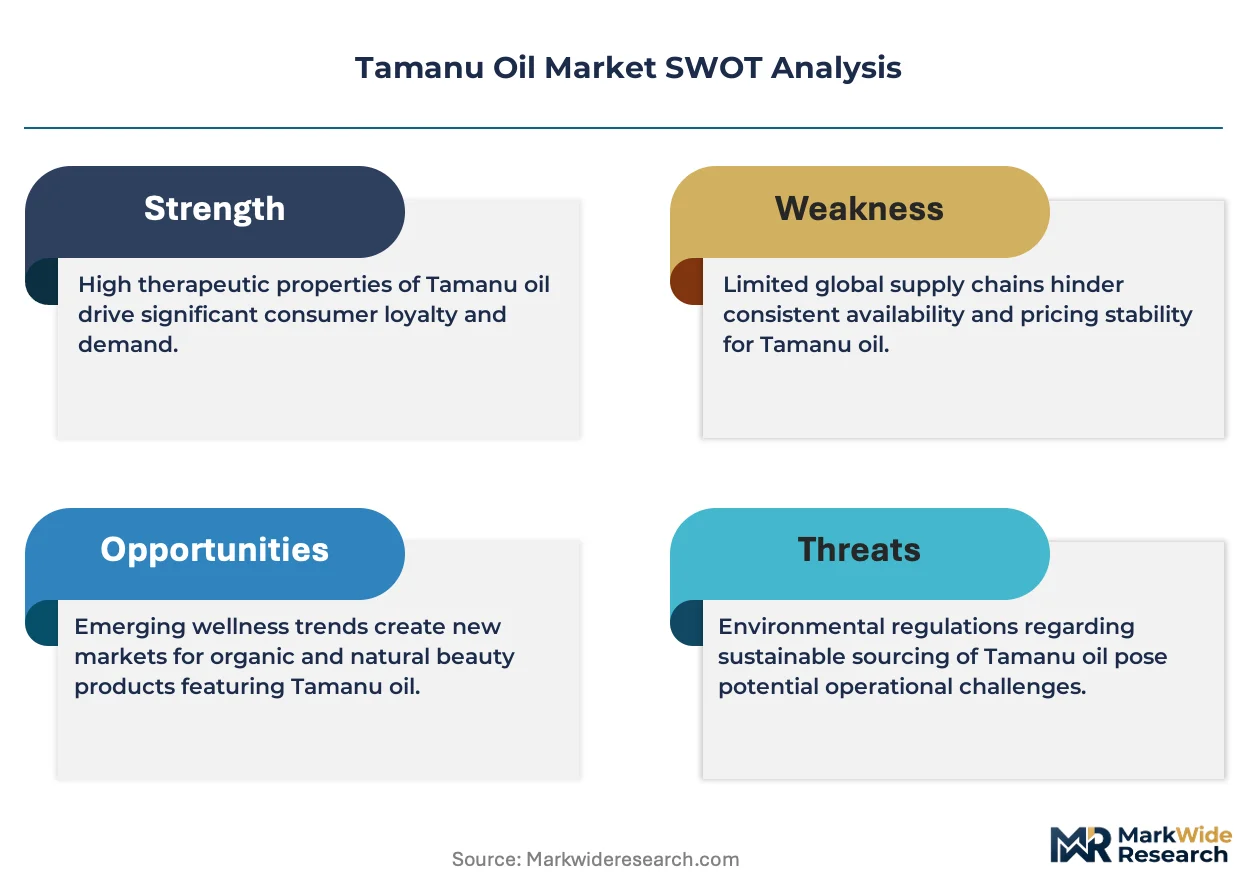
Backward integration into kernel sourcing dominates the current landscape as processors secure estate access against harvest cyclicality. The vendor base stratifies across capital-intensive European pharmaceutical-grade specialists, certified organic estate operators in Southeast Asia, and mass-market personal care distributors in North America. Three archetypes define positioning: vertically integrated cold-chain logistics providers, direct farmer partnership models, and retail channel consolidators. Competitive intensity concentrates around cold-press technician recruitment and ISO 17025 laboratory accreditation.
Among European pharmaceutical-grade specialists, Henry Lamotte Oils anchors quality benchmarks through controlled logistics infrastructure. Mountain Rose Herbs occupies a position within the certified organic archetype, exemplifying direct farmer partnership protocols. NOW Foods sits within the mass-market retail tier, representing channel penetration through personal care distribution networks. These three entities collectively illustrate the geographic and strategic segmentation shaping procurement hierarchies.
| Leading Market Players |
|---|
| NOW Foods |
| Mountain Rose Herbs |
| Henry Lamotte Oils |
| Nutiva |
| Aditi Essentials |
| Earthoil |
| US Organic Group Corp. |
| Leven Rose |
| Aura Cacia |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade buyers in France and Germany anchor pricing power through calophyllolide assay requirements and cold-chain logistics mandates. Their procurement concentration forces three-tier pricing structure across certified organic, cold-pressed pharmaceutical, and refined commodity grades.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical contracts from unbundled cosmetic spot purchases. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification status and ISO 17025 laboratory accreditation. Cost compression in refined commodity tiers is intensifying because petrochemical emollient substitution erodes volume demand. Mass-market personal care manufacturers exhibit highest price sensitivity; wound-healing pharmaceutical laboratories show lowest.
Supply Chain Analysis
EU REACH registration and USDA Organic certification gate direct market access for Vietnamese and Indonesian processors. Raw material flows draw from Mekong Delta estate clusters, Sulawesi island cooperatives, and Maluku cultivation plots. Kernel supply rests on monsoon-dependent Calophyllum inophyllum harvests, cold-press equipment, and analytical testing capacity. Single-source vulnerability concentrates in French and German technician expertise for temperature-controlled extraction. Distribution runs through Ho Chi Minh City and Jakarta export consolidators toward European port cold-chain facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ECHA REACH registration creates a barrier-to-entry moat for pre-registered suppliers with established dossier maintenance capabilities.
For Market Incumbents: Lock in estate access through Nagoya Protocol benefit-sharing agreements with Vietnamese and Indonesian cooperatives. Deepen backward integration into kernel sourcing to defend against harvest cyclicality. Prioritize ISO 17025 laboratory accreditation investments to capture pharmaceutical contract expansion. For New Entrants and Emerging Players: Launch via direct-to-consumer sachet subscription models in urban Indonesian and Vietnamese retail corridors. Target USDA Organic certification gaps in North American premium personal care channels. Exploit toll-processing arrangements for Pacific Island cooperatives excluded from direct EU market access. For Investors and Strategic Acquirers: The window for entry favors vertically integrated processors with captive cold-chain logistics and pre-registered REACH dossiers. Long-term viability hinges on securing estate access ahead of bioprospecting framework maturation. Watch calophyllolide assay standardization disputes as inflection indicator for quality-tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Logistics Infrastructure | Henry Lamotte Oils anchors pharmaceutical-grade supply through controlled temperature protocols from Vietnamese estates. |
| Organic Certification Investment | USDA Organic and EU organic seals unlock price premiums in California and Pacific Northwest natural product clusters. |
| Supercritical CO2 Extraction Scale-Up | French pilot facilities are rewriting polyphenol retention benchmarks for premium cosmetic applications. |
| Blockchain Traceability Platform | Grasse-area laboratories pilot distributed ledger verification for certified organic chain-of-custody documentation. |
| Direct Farmer Partnership | Mountain Rose Herbs exemplifies estate relationship models that bypass traditional distributor margin extraction. |
Methodological Framework
Independent corroboration across calophyllolide assay laboratories, EU import customs records, and organic certification databases underwrites the qualitative findings. Primary interviews with cold-press facility managers, cosmetic formulators, pharmaceutical procurement leads, and cooperative estate directors combined with secondary validation from ECHA registration filings, USDA organic operator databases, and Vietnamese Ministry of Agriculture export statistics. Bottom-up kernel harvest estimates and top-down pharmaceutical contract value triangulation anchored volume assessments.
Comparable-period anchoring linked projection assumptions to historical cold-press capacity utilization and organic certification conversion timelines across the modeling period. Segmentation dimensions spanned extraction technology, certification tier, end-use application, packaging format, and regional regulatory cluster. CAGRs derived from kernel supply elasticity estimates and pharmaceutical formulation penetration curves. Forecast inputs incorporated monsoon pattern variability and REACH dossier maintenance cost trajectories.
Harvest shortfalls, regulatory requalification delays, and synthetic emollient price volatility are the dominant revision risks. Forecasts reflect documented assumptions on estate access security and laboratory accreditation expansion. A model refresh is warranted upon material change in Nagoya Protocol implementation enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Aromatherapy Oils Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Specialty Meat Ingredients Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Madecassoside Market