
 Tea Polyphenols Market | 2026-2036
Tea Polyphenols Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Polyphenols Market Analysis
Green extraction technologies using supercritical CO2 and enzyme-assisted processing is rewriting manufacturing economics for tea polyphenol suppliers. Givaudan leverages captive botanical sourcing networks across Asia to secure consistent catechin profiles. DSM anchors its position through fermentation-derived alternatives that complement traditional leaf extraction. Martin Bauer Group specializes in organic-certified supply chains serving European nutraceutical contract manufacturers.
Tea polyphenols comprise catechins, theaflavins, thearubigins, and flavonoids extracted from Camellia sinensis leaves, typically standardized to 50-98% polyphenol content with EGCG as the principal bioactive marker compound. These molecules function primarily as natural antioxidants in food preservation, functional beverages, and dermocosmetic formulations where oxidative stress mitigation drives formulation value. Green tea extract occupies the dominant margin pool due to higher catechin density and established EFSA health claim pathways, while black tea extract competes on theaflavin uniqueness for cardiovascular positioning. Nutraceuticals represents the fastest-growing end user channel as supplement brands shift from synthetic vitamins to plant-standardized actives with clinical dossiers.
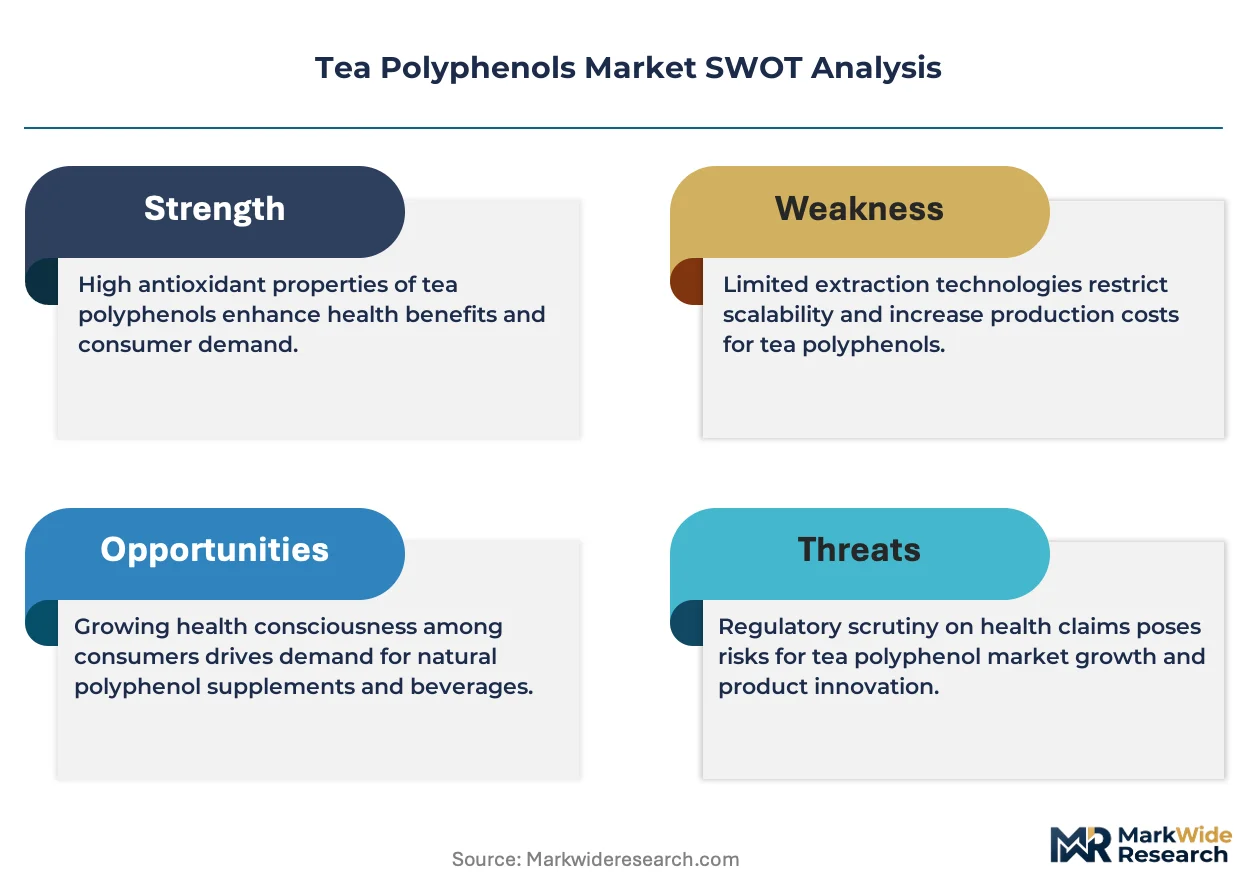
EFSA novel food assessments and EU health claim regulations shape product development timelines and label permissibility for polyphenol suppliers seeking European market access. FDA GRAS self-affirmation and NDI notification requirements govern US entry for concentrated extract formats above traditional food use levels. Stakeholders must monitor evolving pharmacokinetic study demands from regulators and prioritize investments in human intervention trials that substantiate bioavailability claims.
Market Dynamics
Supercritical CO2 extraction is compressing manufacturing costs while EU Novel Food purity thresholds are forcing suppliers to requalify supply chains. These dual pressures are restructuring competitive positioning between legacy solvent processors and enzymatic extraction specialists.
Growth Catalysts
- EFSA Health Claim Pathways:The European regulator's substantiated antioxidant claims enable German and French nutraceutical brands to command premium positioning for EGCG-standardized supplements.
- Clean-Label Beverage Reformulation:Camellia sinensis-derived extracts replace synthetic preservatives in Italian and Spanish functional drink portfolios as consumer ingredient scrutiny intensifies.
- Enzyme-Assisted Processing:Biocatalytic extraction methods unlock higher catechin yields from lower-grade leaf inputs, improving margin structures for mid-volume processors.
Market Restraints
- Camellia Sinensis Supply Concentration:Raw leaf sourcing clusters in Zhejiang and Fujian provinces, exposing European formulators to climate-driven harvest volatility and freight cost spikes.
- EFSA Novel Food Timelines:The regulator's 12-18 month assessment windows for new polyphenol formats delay product launches and freeze R&D budgets.
- Synthetic Antioxidant Substitution:Butylated hydroxytoluene retains cost advantage in mass-market food preservation, capping tea extract penetration in price-sensitive categories.
Strategic Opportunities
- India Functional Beverage White Space:FSSAI's evolving standards for plant-based actives create first-mover potential for catechin-fortified regional drink launches.
- Dermocosmetic Channel Expansion:Oxidative stress mitigation claims align with K-beauty and J-beauty ingredient preferences across South Korean and Japanese skincare formulators.
- EU Green Deal Bioeconomy Incentives:Circular processing subsidies support investment in spent-leaf valorization for secondary polyphenol recovery.
Industry Challenges
- Pharmacokinetic Study Talent Scarcity:Human bioavailability trials require specialized clinical investigators; qualified CRO capacity concentrates in Switzerland and the Netherlands.
- Multi-Jurisdiction GRAS/NDI Parallel Tracks:FDA self-affirmation and EFSA novel food processes demand duplicative toxicology dossiers, stretching regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Polyphenols Market |
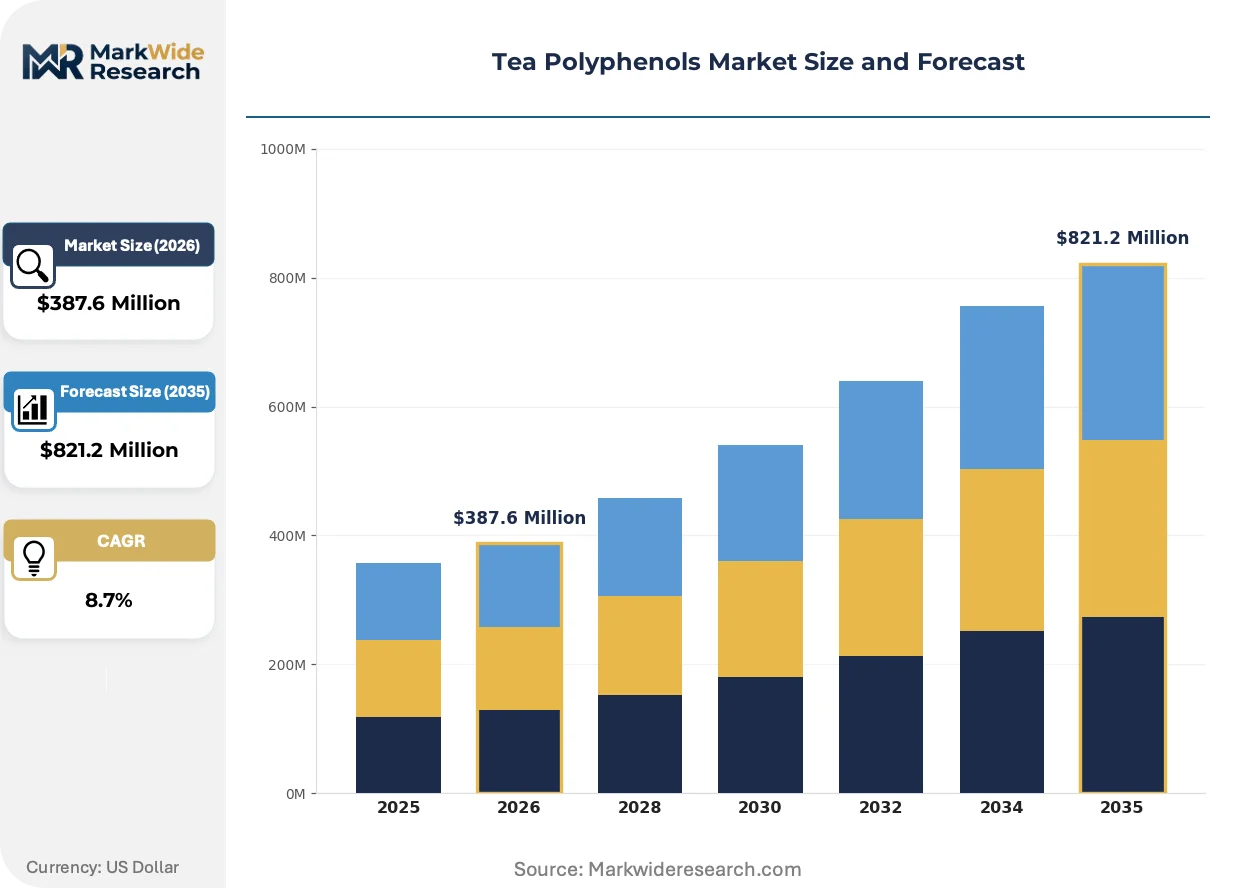
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea Extract, Black Tea Extract, White Tea Extract, Herbal Tea Extract End User: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Source: Camellia Sinensis, Herbal Sources, Decaffeinated Sources, Others Form: Powder, Liquid, Capsule, Tea Bags |
| Companies Covered | Givaudan, Symrise, Sensient Technologies Corporation, International Flavors & Fragrances, Amax NutraSource, Indena, DSM, Martin Bauer Group, Layn Natural Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Polyphenols Market Emerging Trajectories
Digital quality assurance systems and green chemistry advances are compressing extraction timelines while raising purity benchmarks. These developments favor suppliers with integrated analytical capabilities.
Supercritical CO2 extraction systems are virtualizing traditional solvent-based manufacturing economics. German and Italian nutraceutical contract manufacturers adopt these units to eliminate residual solvent concerns and accelerate EFSA compliance timelines. The technology is virtualizing capital allocation decisions, pushing mid-scale processors toward equipment leasing models rather than ownership.
REACH registration requirements for novel extraction solvents are tightening purity documentation burdens across European supply chains. ECHA's evolving substance evaluation protocols now demand full toxicological profiles for enzymatic processing aids previously treated as processing exemptions. Black tea extract suppliers targeting cardiovascular positioning face compressed dossier preparation timelines as thearubigin characterization standards harden.
Ingredient sourcing decisions now hinge on certified organic and fair-trade credentials rather than price alone. French and German beverage brands audit leaf-to-extract chain of custody, displacing spot-market procurement with multi-year cultivation contracts. This behavioral pivot concentrates volume with Martin Bauer Group and similar certified-supply specialists serving European contract manufacturers.
Tea Polyphenols Market Segmentation
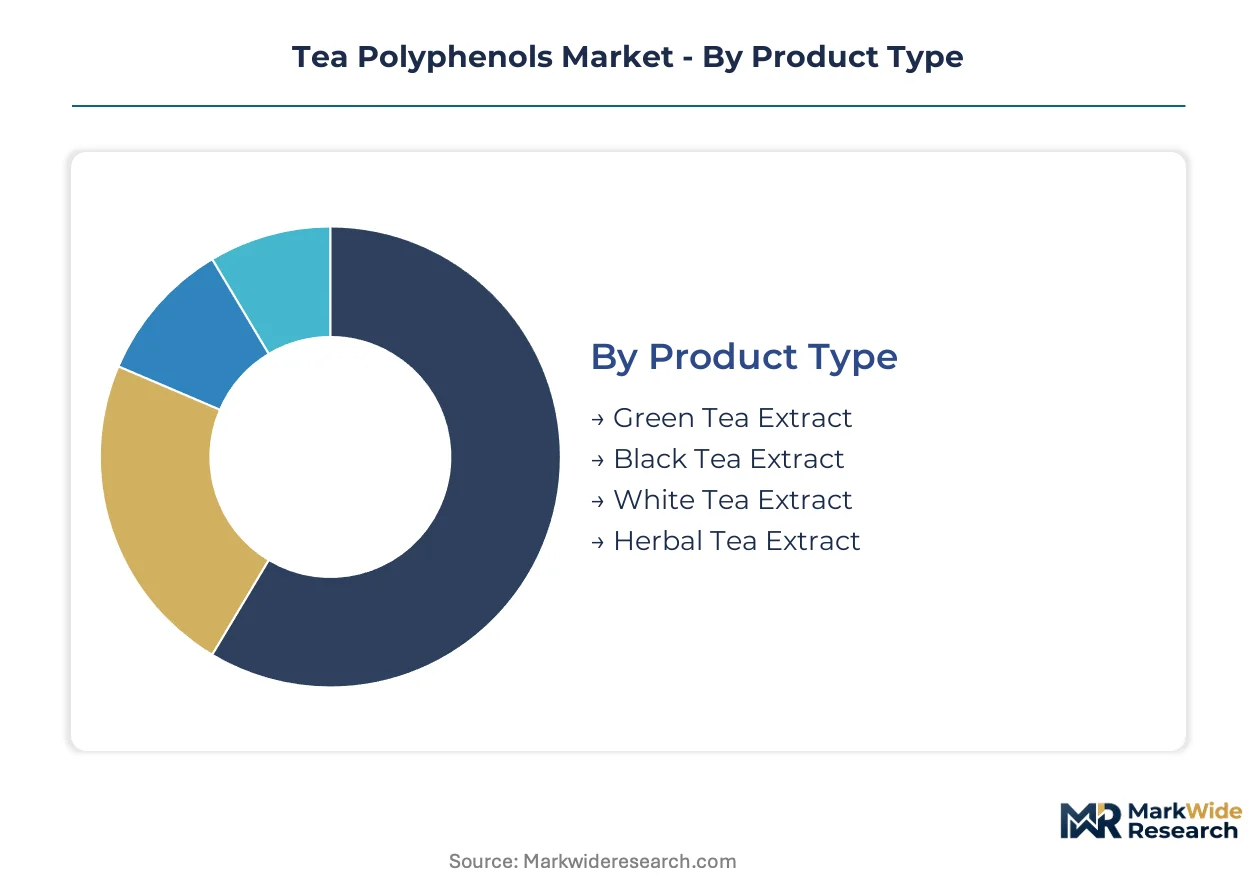
Segmentation in the tea polyphenols market reveals distinct margin pools and regulatory pathways. Product chemistry, end-use application, and extraction source each create separate competitive arenas with divergent purity requirements and customer procurement behaviors.
Product Type:
Polyphenol composition varies dramatically across tea oxidation levels, creating four distinct supply chains with separate standardization protocols and customer bases.
- Green Tea Extract:Dominates catechin-standardized supply with EGCG concentrations typically ranging 50-98%. German and French nutraceutical manufacturers prioritize this format for EFSA-substantiated antioxidant claims, though supply concentrates in Zhejiang and Fujian provinces with climate exposure.
- Black Tea Extract:Theaflavin and thearubigin content differentiates cardiovascular-positioned formulations. Italian beverage brands increasingly specify black tea polyphenols for functional drink differentiation where synthetic antioxidant replacement drives procurement.
- White Tea Extract:Higher catechin preservation from minimal processing commands premium positioning in dermocosmetic channels.
- Herbal Tea Extract:Non-Camellia botanicals serve niche allergen-free and caffeine-free formulation requirements.
Established volume favors Green Tea Extract; emerging adoption favors Black Tea Extract.
End User:
Customer procurement patterns split between formulation-driven specification and commodity-scale volume purchasing.
- Food & Beverage:Italian and Spanish functional drink manufacturers drive clean-label reformulation demand. EFSA health claim substantiation requirements compress supplier qualification timelines while beverage brands audit organic-certified supply chains for label permissibility.
- Nutraceuticals:Supplement brands shift from synthetic vitamins to plant-standardized actives with clinical dossiers. DSM and Givaudan supply networks serve German contract manufacturers seeking GRAS-self-affirmed or Novel Food-approved inputs.
- Pharmaceuticals:Drug-grade polyphenol specifications require pharmacokinetic study documentation for bioavailability claims.
- Cosmetics:K-beauty and J-beauty formulators specify oxidative stress mitigation actives for premium skincare positioning.
Volume concentration sits with Food & Beverage; steepest expansion trajectory belongs to Nutraceuticals.
Source:
Raw material provenance determines regulatory classification, caffeine content, and extraction yield economics.
- Camellia Sinensis:Standardized leaf sourcing from certified organic cultivation dominates European procurement. Martin Bauer Group and similar specialists anchor supply through multi-year cultivation contracts displacing spot-market purchasing.
- Herbal Sources:Rooibos, hibiscus, and other botanicals serve caffeine-free and novel food positioning requirements.
- Decaffeinated Sources:Supercritical CO2 decaffeination creates dual-output economics for caffeine-sensitive formulations.
- Others:Fermentation-derived alternatives from DSM complement traditional leaf extraction with batch-to-batch consistency advantages.
Supply security concentrates with Camellia Sinensis; regulatory differentiation favors Herbal Sources.
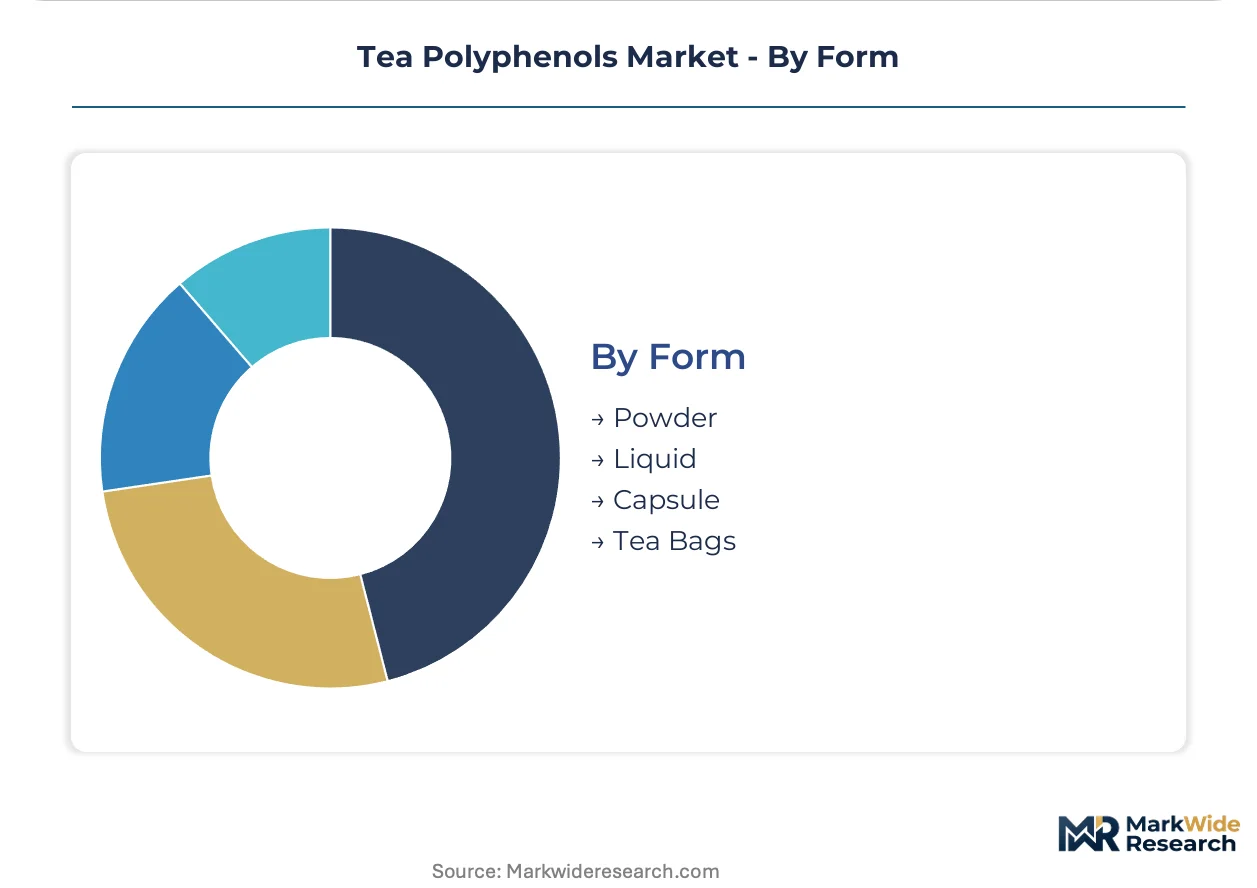
Form:
Delivery format selection reflects end-use processing constraints and consumer administration preferences.
- Powder:Spray-dried extracts dominate industrial-scale beverage and supplement manufacturing for solubility and dosing precision.
- Liquid:Ready-to-drink formulation compatibility drives adoption in functional beverage bottling operations.
- Capsule:Direct-to-consumer supplement brands specify gelatin or vegetable-based encapsulation for unit-dose convenience.
- Tea Bags:Whole-leaf and extract-impregnated formats serve traditional consumption channels with minimal processing claims.
Manufacturing throughput favors Powder; consumer convenience positioning favors Capsule.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German nutraceutical contract manufacturers and French functional beverage brands anchor procurement demand for EGCG-standardized extracts. Italian clean-label reformulators and Spanish bottling operations drive secondary volume. Chinese leaf processors supply raw material, though climate volatility concentrates risk in Zhejiang and Fujian provinces.
Germany
Frankfurt and Hamburg host nutraceutical contract manufacturers expanding green tea extract procurement for EFSA-substantiated antioxidant supplements. The country's Federal Office of Consumer Protection and Food Safety enforces strict Novel Food documentation requirements. Martin Bauer Group anchors supply through certified-organic cultivation contracts serving German formulators.
France
Paris-based beverage brands audit leaf-to-extract chain of custody for clean-label functional drink portfolios. ANSM and DGCCRF coordinate novel food safety assessments with EFSA alignment timelines. Lyon and Strasbourg processing clusters specialize in organic-certified extract standardization for premium positioning.
Italy
Milan and Bologna beverage manufacturers reformulate with Camellia sinensis-derived extracts replacing synthetic preservatives. The Ministry of Health's novel food notifications compress supplier qualification windows. Piedmont and Lombardy bottling corridors concentrate demand for liquid extract formats in ready-to-drink operations.
China
Zhejiang and Fujian provinces concentrate Camellia sinensis cultivation supplying global extract processors. The National Health Commission's food safety standards govern export-grade polyphenol specifications. Hangzhou and Fuzhou extraction clusters face climate-driven harvest volatility and freight cost spikes affecting European formulators.
United States
New Jersey and California dietary supplement brands drive GRAS self-affirmation demand for concentrated extract formats. FDA NDI notification requirements govern entry for polyphenol levels above traditional food use. Chicago and Los Angeles distribution hubs handle import logistics for catechin-standardized powders.
Tea Polyphenols Market Vendor Landscape
Channel-controlling players compete with product-specialist players across four distinct archetypes. Integrated botanical houses with captive Asian sourcing networks face fermentation-derived alternative suppliers and certified-organic specialists. The structure splits between fragrance-flavor conglomerates leveraging extraction expertise, nutraceutical ingredient pure-plays, and mid-scale organic processors. Dominant competitive moves include multi-year cultivation contract lock-ups and supercritical CO2 equipment leasing programs displacing solvent-based legacy capacity.
Within the integrated botanical tier, Givaudan and DSM exemplify divergent sourcing strategies—one through captive leaf networks, the other through fermentation-derived batch consistency. Martin Bauer Group occupies a position as the certified-organic specialist serving European contract manufacturers with multi-year chain-of-custody documentation. Sensient Technologies Corporation and International Flavors & Fragrances sit within the flavor-house extraction segment, leveraging existing botanical processing infrastructure for polyphenol standardization.
| Leading Market Players |
|---|
| Givaudan |
| Symrise |
| Sensient Technologies Corporation |
| International Flavors & Fragrances |
| Amax NutraSource |
| Indena |
| DSM |
| Martin Bauer Group |
| Layn Natural Ingredients |
| Others |
Supply Flow & Price Mechanics
Zhejiang and Fujian provinces concentrate Camellia sinensis leaf processing capacity, and their harvest volatility directly transmits to European formulators' procurement costs. Supercritical CO2 extraction equipment leasing spreads capital burden, but raw material indexation clauses in multi-year contracts tie pricing to climate-driven yield fluctuations.
Pricing Analysis
Cost-plus contracts with leaf-indexed pricing dominate procurement between Chinese processors and German nutraceutical contract manufacturers. Three-tier pricing structure across organic-certified, conventional, and commodity-grade extracts reflects EFSA Novel Food dossier investment and chain-of-custody documentation depth. Pricing pressure stems from synthetic antioxidant substitution in mass-market food preservation, where butylated hydroxytoluene retains cost advantage. Beverage brands exhibit highest price sensitivity due to clean-label reformulation volume scale; pharmaceutical-grade specifications command least sensitivity given pharmacokinetic study requirements.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for catechin-standardized extract shipments. Raw material sourcing draws from Zhejiang and Fujian cultivation clusters, with enzymatic processing aids and supercritical CO2 equipment representing critical input dependencies. Single-source vulnerability concentrates in certified organic leaf supply, where Martin Bauer Group and similar specialists lock multi-year cultivation contracts. Distribution runs through Rotterdam and Hamburg port clusters for European nutraceutical contract manufacturers, with secondary consolidation at Lyon and Strasbourg processing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tea polyphenols function as a platform chemistry where extraction technology interoperability unlocks cross-sector formulation value. EFSA health claim substantiation creates ecosystem lock-in for suppliers with validated clinical dossiers.
For Market Incumbents: Harden supply security through backward integration into certified organic cultivation in Yunnan province, displacing spot-market leaf procurement. Lock multi-year supercritical CO2 equipment leases to freeze manufacturing cost structures against enzymatic extraction specialists. Prioritize pharmacokinetic study investment to defend against fermentation-derived alternatives from DSM threatening bioavailability positioning.
For New Entrants and Emerging Players: India's functional beverage white space offers first-mover positioning before FSSAI standards fully crystallize. Target dermocosmetic channels in South Korea and Japan where K-beauty formulators seek oxidative stress mitigation actives with minimal EFSA-equivalent regulatory burden. Pursue white tea extract specialization for premium skincare positioning, leveraging higher catechin preservation claims.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EFSA Novel Food approval timelines and GRAS self-affirmation dossiers create durable barriers against commodity entrants. Acquisition targets should display integrated analytical capabilities with digital quality assurance systems and established CRO relationships for human bioavailability trials. Monitor FSSAI's evolving standards for plant-based actives as the signal for India market entry inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Secures label permissibility for EGCG-standardized supplements in German and French markets. |
| Supercritical CO2 Equipment Leasing | Eliminates residual solvent concerns while compressing EFSA compliance timelines for mid-scale processors. |
| Certified Organic Cultivation Contracts | Locks chain-of-custody documentation required by French beverage brands auditing leaf-to-extract provenance. |
| Pharmacokinetic Study Partnerships | Addresses qualified CRO capacity scarcity in Switzerland and Netherlands for bioavailability claims. |
| Spent-Leaf Valorization Infrastructure | Captures EU Green Deal circular processing subsidies for secondary polyphenol recovery economics. |
Methodological Framework
Initial hypotheses were tested against primary input from extraction technology specialists, nutraceutical contract manufacturing procurement leads, EFSA regulatory affairs consultants, and dermocosmetic formulators, and refined through secondary validation. Primary fieldwork combined structured interviews with plant managers at Zhejiang and Fujian processing clusters, category buyers at German and French beverage brands, and technical R&D directors at enzymatic extraction specialists. Secondary sources included EFSA Novel Food assessment databases, REACH registration filings for extraction solvents, customs trade data for Camellia sinensis leaf imports, and SEC 10-K disclosures from fragrance-flavor conglomerates. Bottom-up volume modeling triangulated against top-down market sizing from ingredient supplier revenue allocations.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included tea oxidation level, end-use application channel, extraction technology type, and regional regulatory cluster. CAGRs derived from iterative convergence between volume build-ups and value chain margin analysis. Industry-specific forecast inputs incorporated EFSA assessment pipeline timelines and FSSAI standard evolution trajectories for plant-based actives.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by fermentation-derived alternative suppliers or accelerated FSSAI liberalization would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Detox Tea Market
Tea
White Tea Market
Tea
Asia-Pacific Green Tea Market
Tea
Camellia Sinensis Leaf Extract Market
Tea
Out of Home Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Smart Tea Maker Market
Tea
Tea Subscription Market
Tea
Green Tea Bag Market
Tea
Europe Green Tea Market
Tea
Organic Tea Market
Tea
Probiotic Tea Market
Tea
Herbal Tea Market
Tea
Instant Tea Premixes Market
Tea
Spray-Dried Tea Products Market
Tea
Matcha Market