
 Agarwood Essential Oil Market | 2026-2036
Agarwood Essential Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Agarwood Essential Oil Market Analytics
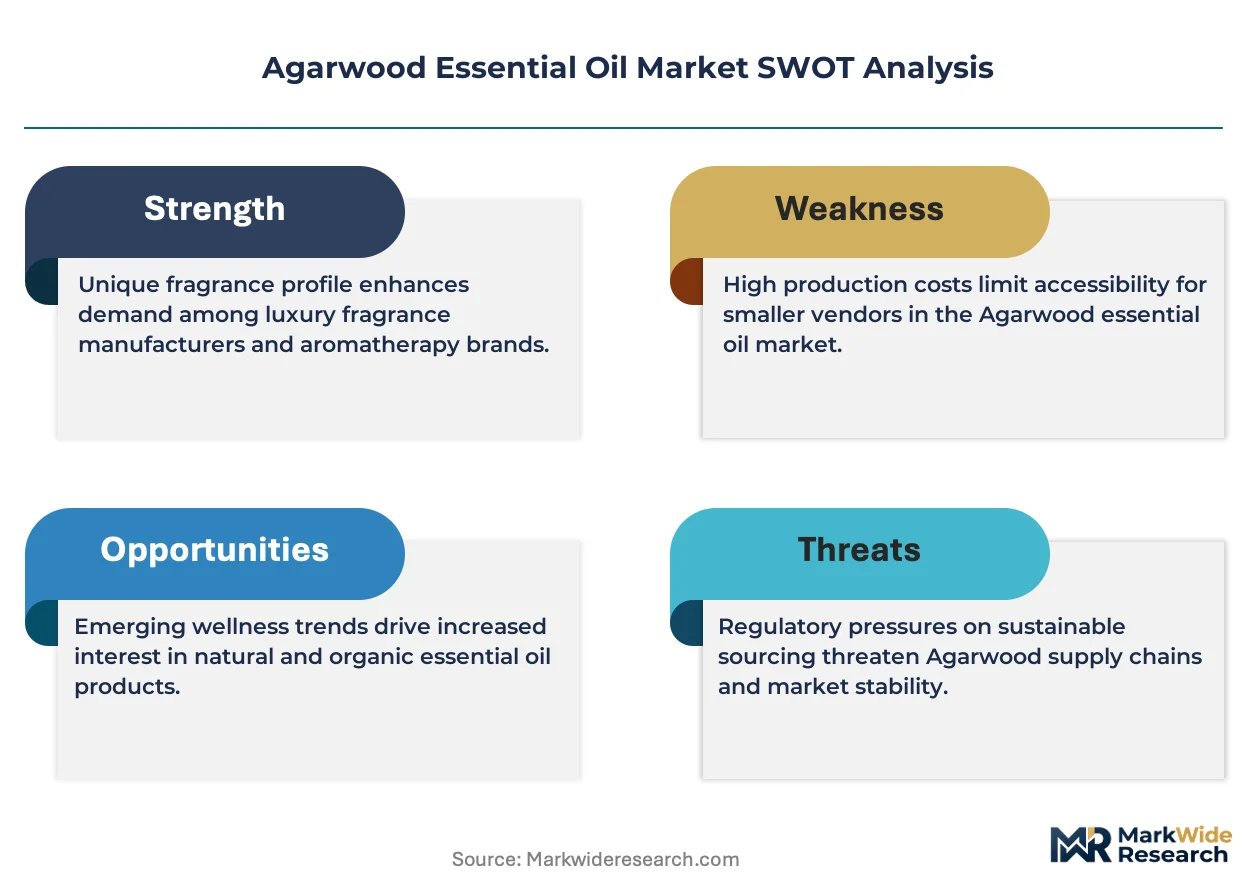
CITES Appendix II regulation is expanding compliance burdens for distillers sourcing wild Aquilaria species. Hoang Giang Agarwood Ltd. leverages plantation-scale cultivation in Vietnam to secure captive supply of resinous heartwood. Givaudan International AG sustains R&D intensity in molecular reconstruction of oud accords to reduce wild-harvest dependency. Robertet SA anchors its competitive position through controlled partnerships with Southeast Asian extraction facilities.
Agarwood essential oil is a hydrodistilled or steam-distilled volatile concentrate derived from the dark resin-impregnated heartwood of Aquilaria and Gyrinops trees, containing sesquiterpenoids such as agarofuran and nor-ketoagarofuran that impart its characteristic woody-animalic odor profile; perfumers value it as a fixative and base-note material in luxury fragrance compositions. Steam distillation dominates commercial output due to equipment accessibility, though CO2 extraction captures fuller terpene complexity for niche perfumery. Aromatherapy and perfume applications command the deepest margin pools, while incense demand remains structurally price-sensitive across South Asian markets.
USDA and FDA oversight governs import documentation and cosmetic safety labeling for agarwood oil entering American channels, while ECHA REACH compliance shapes formulation restrictions within European fragrance houses. Vietnam's BIS-aligned national standards for cultivated agarwood quality are tightening export certification requirements. Stakeholders must monitor plantation maturation timelines against wild-harvest moratoria to calibrate long-term raw material strategies.
Market Dynamics
CITES Appendix II trade controls have created a structural bifurcation between plantation-cultivated and wild-harvested agarwood supply, forcing distillers to rebuild procurement networks around captive cultivation assets rather than spot-market wild material.
Growth Catalysts
- Plantation maturation cycles:Vietnamese and Thai cultivation investments planted during the 2010-2015 expansion window are now yielding harvestable resinous heartwood, injecting certified supply into previously constrained channels.
- REACH compliance frameworks:European fragrance houses under ECHA oversight are formalizing documented supply chains for natural oud materials, creating preferential procurement relationships with certified plantation operators.
- Molecular reconstruction R&D:Biotech-enabled synthesis of sesquiterpenoid accords is reducing batch-to-batch variability that has historically complicated luxury fragrance formulation work.
Market Restraints
- Input cost volatility:Resinous heartwood from mature Aquilaria trees commands prices that fluctuate with plantation yield cycles and weather-induced fungal infection rates.
- Supply concentration risk:Vietnam and Thailand together account for the dominant share of internationally traded cultivated agarwood, creating geographic vulnerability to regional climate events or export policy shifts.
- Regulatory friction:CITES permit processing delays and Appendix II documentation requirements extend order-to-delivery timelines for distillers sourcing across multiple jurisdictions.
Strategic Opportunities
- Underpenetrated cultivation geographies:Laos and Cambodia present expansion terrain for plantation development, with less mature regulatory frameworks offering earlier-mover positioning for integrated operators.
- Emerging wellness applications:Aromatherapy and functional fragrance segments are developing standardized dosing protocols for agarwood oil in anxiety-reduction and sleep-support formulations.
- Supercritical CO2 technology convergence:Combination of carbon dioxide extraction with in-line terpene profiling is enabling boutique distillers to offer terroir-differentiated products with verified chemical signatures.
Industry Challenges
- Skill gap in resin grading:Plantation-scale operations lack sufficient trained assessors to evaluate heartwood quality against the BIS-aligned standards now governing Vietnamese export certification.
- Capex intensity for compliance infrastructure:In-house gas chromatography-mass spectrometry systems and chain-of-custody documentation platforms require capital outlays that strain mid-scale distillers.
- Integration complexity with legacy fragrance houses:Molecular reconstruction programs must reconcile synthetic accord profiles with established perfumer expectations developed through decades of wild-harvest material use.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agarwood Essential Oil Market |
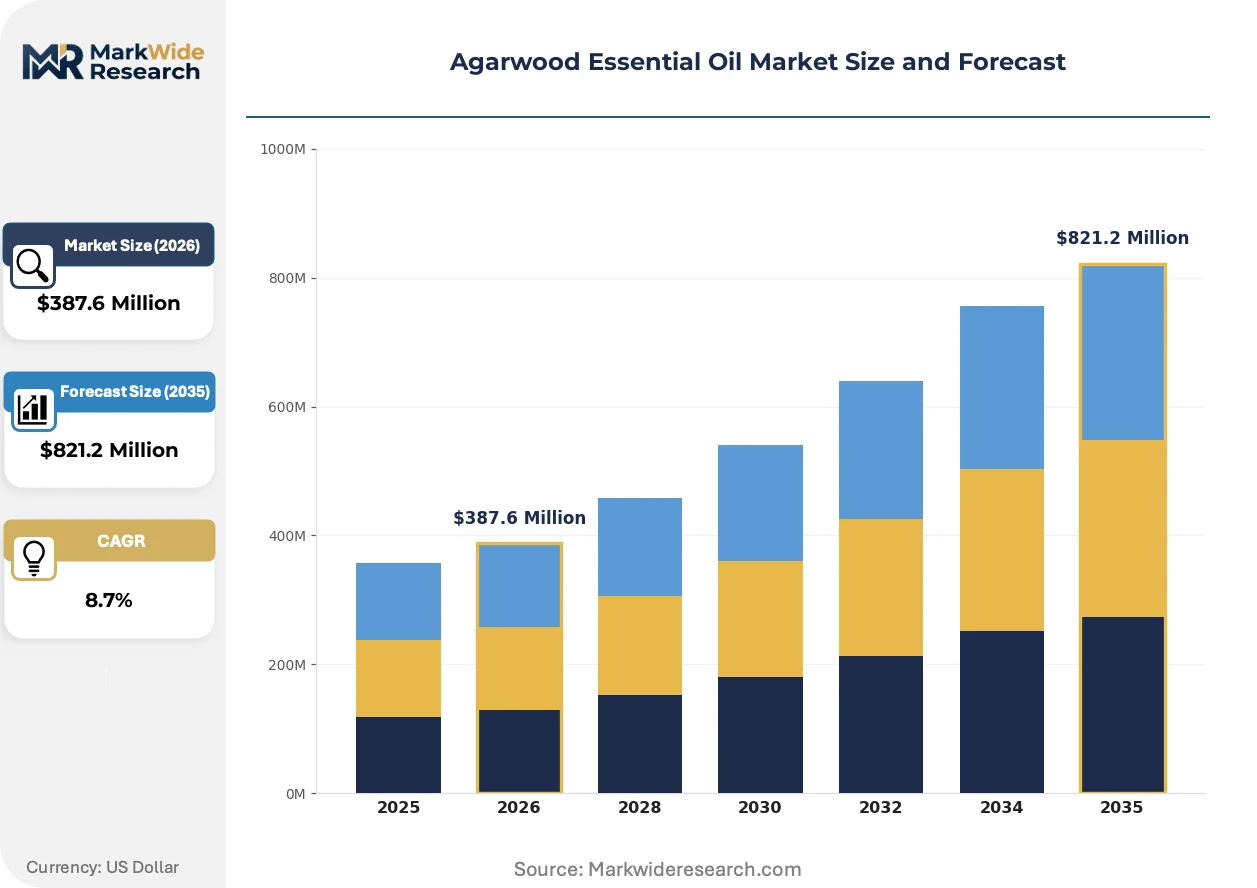
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Extraction Method: Steam Distillation, Hydro Distillation, Solvent Extraction, CO2 Extraction Application: Aromatherapy, Perfumes, Cosmetics, Incense Form: Liquid, Roll-On, Spray, Solid Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Hoang Giang Agarwood Ltd., MANE SA, Firmenich SA, Assam Aromas, Robertet SA, Givaudan International AG, Symrise AG, Takasago International Corporation, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agarwood Essential Oil Market Evolving Landscape
Steam distillation equipment miniaturization combined with portable analytics is redistributing extraction capacity toward plantation-adjacent processing, collapsing the geographic distance between harvest and primary distillation.
Supercritical CO2 extraction systems are decentralizing agarwood oil production by enabling on-site processing at plantation facilities, bypassing the traditional consolidation of raw heartwood at central distilleries. Vietnamese operators with 50-hectare-plus cultivation footprints are installing skid-mounted extraction units to capture value at origin. This technology is decentralizing quality control and shortening the documentation chain for CITES compliance.
ECHA REACH registration requirements for fragrance raw materials are tightening substance documentation obligations for natural oud imports into European formulation facilities. The regulation forces importers to maintain detailed substance identity profiles and safety data sheets across complex botanical extracts. Niche perfumery houses in France are responding by consolidating supplier relationships with plantation operators who can provide batch-level chemical characterization.
Direct contracting between fragrance houses and plantation operators is displacing the layered trader-wholesaler-distributor structure that historically dominated agarwood commerce. Middle Eastern luxury retailers are establishing multi-year offtake agreements with Vietnamese cultivation groups, securing volume commitments in exchange for quality tier guarantees. This pattern is most visible in Dubai and Riyadh, where vertically integrated oud brands are building captive supply networks.
Agarwood Essential Oil Market Segmentation
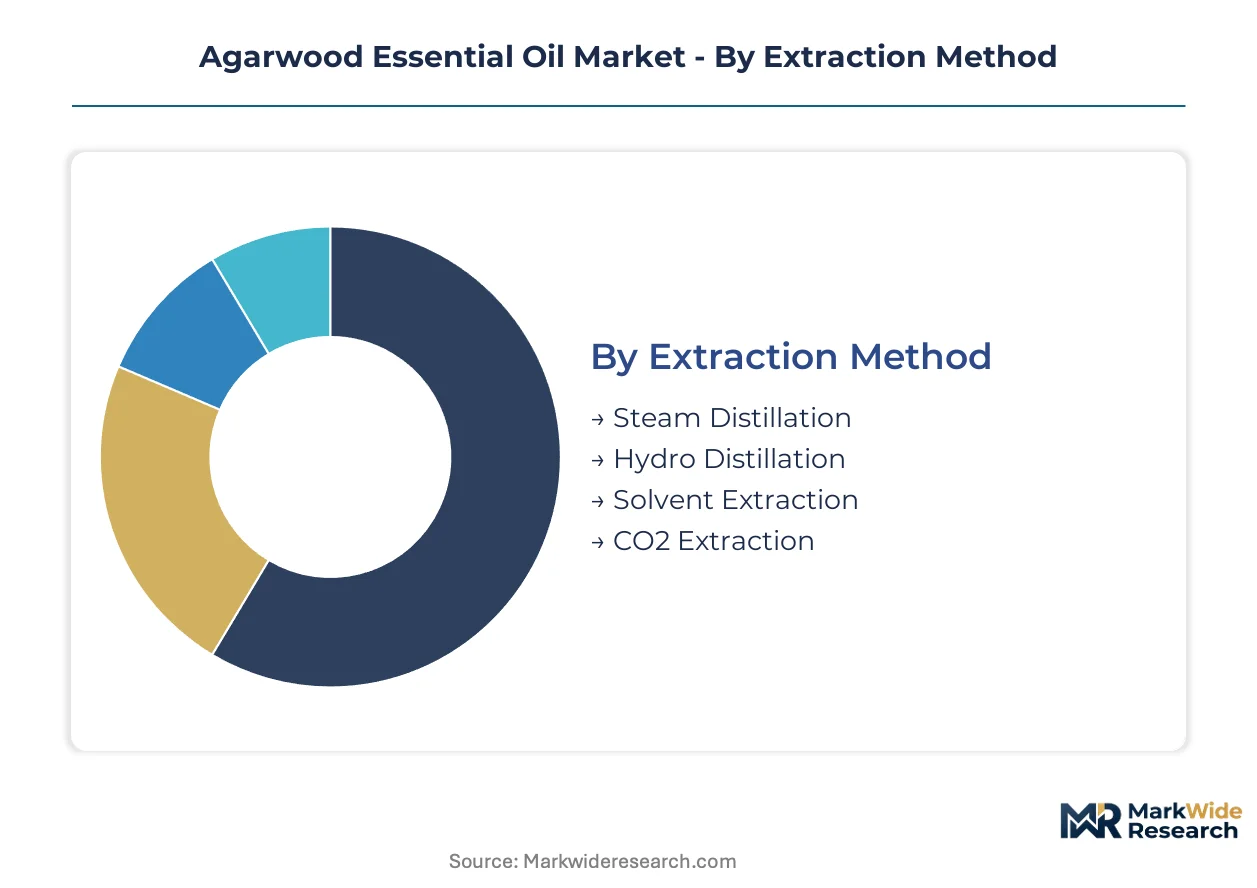
Agarwood essential oil segmentation reflects divergent technical requirements across extraction platforms and end-use specifications. Distillers configure output profiles to match fragrance house formulation protocols, wellness application dosing standards, and retail channel packaging constraints.
Extraction Method:
Standalone extraction systems serve boutique perfumery with batch-level chemical customization, while integrated distillery networks supply standardized volumes to cosmetic manufacturers.
- Steam Distillation:Conventional steam-stripping of resinous heartwood yields sesquiterpenoid-rich fractions with equipment accessibility driving adoption across Vietnamese plantation facilities. Fragrance houses in France specify steam-distilled material for base-note stability in luxury compositions, though batch-to-batch fungal infection variability complicates procurement planning.
- CO2 Extraction:Supercritical carbon dioxide systems capture fuller terpene complexity including heat-labile agarofuran derivatives for niche perfumery applications. Thai operators with 50-hectare-plus cultivation footprints install skid-mounted units to collapse harvest-to-distillation timelines and streamline CITES documentation chains.
- Hydro Distillation:Water-immersion methods predominate in traditional Middle Eastern distillation clusters with established equipment amortization.
- Solvent Extraction:Organic solvent protocols yield absolute extracts for cosmetic formulation work requiring standardized odor intensity.
Steam distillation leads volumes today; CO2 extraction is gaining share fastest.
Application:
Cost tier stratification separates premium fragrance formulation from commoditized incense consumption, with aromatherapy occupying an intermediate value position.
- Perfumes:High-purity sesquiterpenoid fractions function as fixatives and base-note materials in luxury fragrance compositions. Dubai and Riyadh retailers establish multi-year offtake agreements with Vietnamese cultivation groups, securing volume commitments against quality tier guarantees.
- Aromatherapy:Standardized dosing protocols for anxiety-reduction and sleep-support formulations require verified chemical signatures and batch-level consistency. Wellness brands in Switzerland source through plantation operators with in-house gas chromatography-mass spectrometry systems.
- Cosmetics:Low-concentration incorporation into skincare and haircare products demands REACH-compliant documentation for ECHA-registered formulations.
- Incense:Price-sensitive South Asian markets consume resinous heartwood directly or as diluted oil fractions for religious and ceremonial burning.
Perfumes command the steepest margin pools; aromatherapy shows the most rapid application expansion.
Form:
Packaging configuration aligns with distribution channel requirements and end-user application convenience, from professional perfumer bulk handling to consumer portability.
- Liquid:Bulk liquid concentrate in amber glass or aluminum containers supplies formulation laboratories and professional aromatherapy practitioners. Vietnamese exporters ship liquid form under CITES Appendix II permits with BIS-aligned quality certification.
- Spray:Atomized delivery systems target personal fragrance and room application segments with precise dosing control.
- Roll-On:Diluted oil preparations in roller-ball applicators serve wellness retail channels with standardized concentration protocols.
- Solid:Wax or balm matrices enable portable formats for travel and religious pilgrimage markets.
Liquid form dominates professional channel volumes; spray formats are climbing fastest in consumer-direct segments.
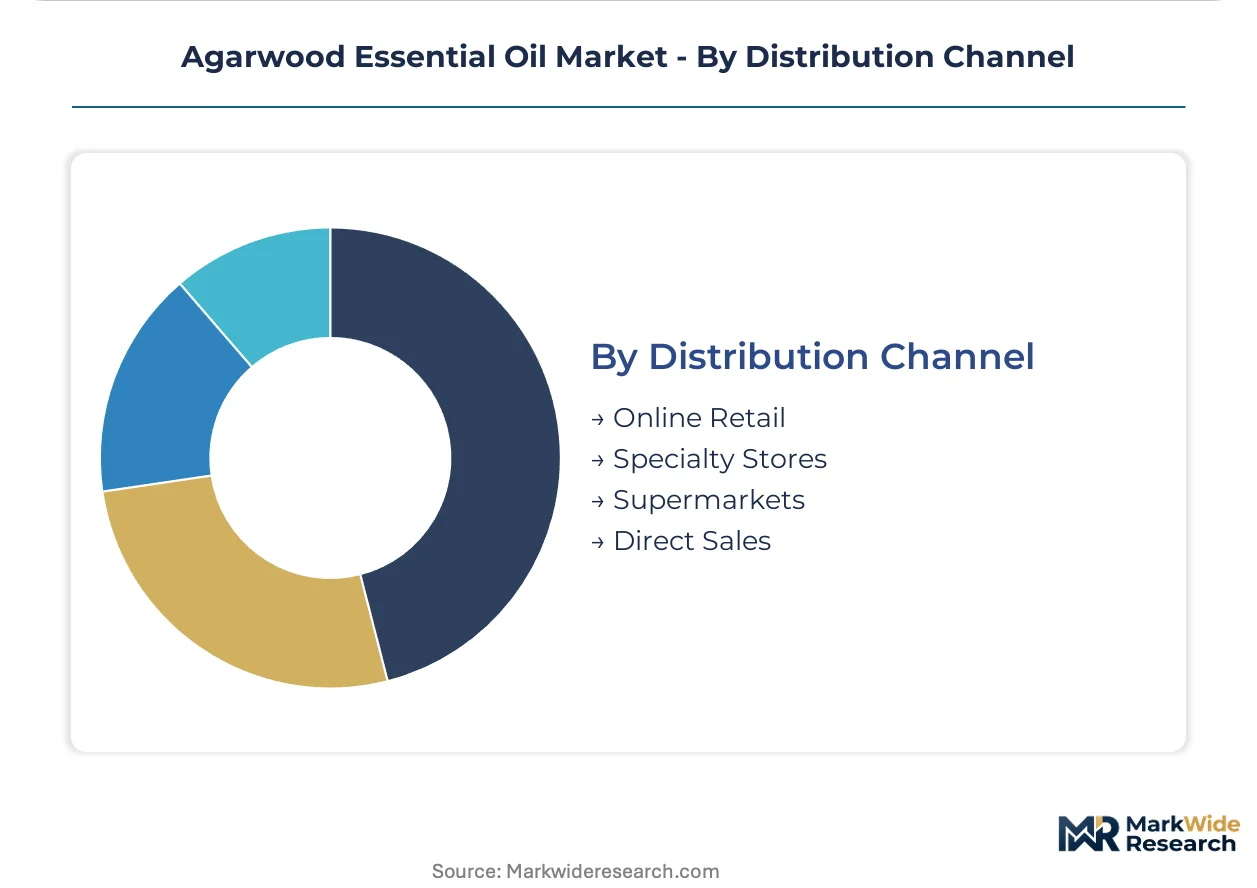
Distribution Channel:
Channel selection determines margin capture and documentation burden, with direct contracting displacing layered trader structures for certified plantation output.
- Direct Sales:Multi-year supply agreements between plantation operators and fragrance houses eliminate intermediary markups while enforcing chain-of-custody documentation. Middle Eastern luxury retailers in Dubai consolidate procurement through vertically integrated oud brands with captive Vietnamese supply networks.
- Specialty Stores:Curated retail environments in Paris and Geneva serve niche perfumery consumers with terroir-differentiated products and verified chemical signatures.
- Online Retail:E-commerce platforms expand geographic reach for standardized aromatherapy and wellness products with simplified regulatory documentation.
- Supermarkets:Mass retail channels distribute diluted and lower-concentration formats to price-sensitive consumer segments.
Direct sales anchor premium tier volumes; online retail is expanding most quickly for mid-market wellness applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese plantation technicians and Thai resin graders anchor the industry's geographic workforce concentration. Their expertise in fungal inoculation techniques and heartwood quality assessment shapes supply reliability. Cultivation investments from the 2010-2015 expansion window now mature across Southeast Asian production belts.
Vietnam
Perfume house procurement teams and wellness brand formulators drive import demand from European and Middle Eastern channels. BIS-aligned national standards for cultivated agarwood quality tighten export certification requirements through the national standards body. The Mekong Delta and Central Highlands host plantation clusters where Hoang Giang Agarwood Ltd. operates integrated cultivation-to-distillation facilities.
Thailand
Domestic incense manufacturers and regional fragrance distributors absorb substantial plantation output for traditional and commercial applications. CITES Appendix II permit processing through the Department of National Parks, Wildlife and Plant Conservation governs cross-border shipments. Chiang Mai and surrounding northern provinces concentrate skid-mounted CO2 extraction units at 50-hectare-plus cultivation footprints.
France
Luxury fragrance house perfumers and niche parfumerie blenders specify high-purity sesquiterpenoid fractions for base-note stability. ECHA REACH registration requirements tighten substance documentation obligations for natural oud imports into European formulation facilities. Grasse and Paris-based ateliers consolidate supplier relationships with plantation operators providing batch-level chemical characterization.
United Arab Emirates
Vertically integrated oud brands and luxury retail groups establish multi-year offtake agreements with Southeast Asian cultivation networks. MOHAP oversight governs cosmetic safety labeling for agarwood oil entering commercial channels. Dubai and Riyadh-based retailers secure volume commitments from Vietnamese cultivation groups against quality tier guarantees.
Switzerland
Wellness brand formulators and aromatherapy practitioners source standardized dosing protocols for anxiety-reduction applications. Swissmedic registration pathways shape import documentation for therapeutic-grade essential oil classifications. Geneva and Basel-based distributors maintain relationships with plantation operators possessing in-house gas chromatography-mass spectrometry systems.
Agarwood Essential Oil Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the agarwood essential oil value chain. Fragrance houses with integrated raw material divisions face independent plantation operators with captive distillation assets. Three archetypes dominate: multinational flavor and fragrance houses with molecular reconstruction capabilities, plantation-integrated distillers with certified supply chains, and boutique extraction specialists with terroir-differentiated positioning. Competitive moves center on backward integration into cultivation assets and technology licensing for portable analytics systems.
Among plantation-integrated operators, Hoang Giang Agarwood Ltd. exemplifies the captive supply archetype with Vietnamese cultivation footprints. Within the fragrance house tier, Givaudan International AG and Robertet SA occupy positions representing contrasting approaches to raw material security—biotech-enabled synthesis versus controlled partnerships with Southeast Asian extraction facilities. These three names anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Hoang Giang Agarwood Ltd. |
| MANE SA |
| Firmenich SA |
| Assam Aromas |
| Robertet SA |
| Givaudan International AG |
| Symrise AG |
| Takasago International Corporation |
| International Flavors & Fragrances Inc. |
| Others |
Value Network & Pricing Analysis
Vietnamese resin graders and Thai fungal inoculation specialists concentrate in the Mekong Delta and Chiang Mai provinces, with labor-cost differentials between these plantation belts spreading pricing tiers from artisanal small-batch distillates to industrial-scale outputs. Their expertise in heartwood quality assessment and controlled infection techniques creates wage premiums that cascade through finished oil pricing structures.
Pricing Analysis
Contract-based long-term offtake agreements separate bundled plantation-to-distillery services from unbundled spot-market resin trading. Price differentiation rests on CITES certification grade and batch-level chemical characterization through gas chromatography-mass spectrometry. Cost compression in standard-grade steam-distilled material is intensifying because Vietnamese plantation maturation cycles are expanding certified supply volumes. Incense manufacturers across South Asian markets exhibit the highest price sensitivity, while French niche perfumery houses demonstrate the lowest.
Supply Chain Analysis
Regional distribution centers in Ho Chi Minh City and Bangkok consolidate plantation output before forwarding to Grasse and Dubai formulation facilities. Raw material supply draws from resinous heartwood of Aquilaria crassna in Vietnam, Aquilaria malaccensis in Thailand, and emerging Gyrinops verstegii cultivation in Laos. Single-source vulnerability concentrates in Vietnamese export certification bottlenecks under BIS-aligned national standards. Distribution runs through direct contracting between plantation operators and fragrance houses, displacing historical trader-wholesaler layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where CITES Appendix II permit processing delays and documentation requirements continuously tighten compliant supply access, with each regulatory milestone in Vietnamese export certification driving preferential procurement relationships.
For Market Incumbents: Lock in captive cultivation assets through multi-year offtake agreements with Vietnamese plantation operators before emerging biotech synthesis alternatives achieve commercial scale. Prioritize in-house gas chromatography-mass spectrometry systems to meet tightening ECHA REACH substance documentation obligations for European fragrance house supply. For New Entrants and Emerging Players: Direct-to-consumer online retail channels for standardized aromatherapy roll-ons offer the most penetrable entry vector, bypassing layered distributor markups and simplified regulatory documentation. Target Swiss wellness brand formulators with anxiety-reduction dosing protocols, leveraging portable analytics systems for batch-level chemical verification as a go-to-market angle. For Investors and Strategic Acquirers: Fragrance houses with molecular reconstruction programs are the most active acquirer in this space, seeking plantation-integrated operators with certified supply chains to reconcile synthetic accord profiles with perfumer expectations. Monitor supercritical CO2 technology convergence at Thai 50-hectare-plus cultivation footprints as the inflection signal for terroir-differentiated product viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Assets | Captive supply of resinous heartwood secures volume commitments against CITES permit volatility. |
| Supercritical CO2 Extraction Deployment | Skid-mounted units at plantation facilities collapse harvest-to-distillation timelines for Dubai retailers. |
| Batch-Level Chemical Characterization Investment | In-house gas chromatography-mass spectrometry systems satisfy ECHA REACH documentation for Grasse formulators. |
| Direct Contracting with Fragrance Houses | Multi-year agreements eliminate intermediary markups while enforcing chain-of-custody compliance. |
| Molecular Reconstruction R&D Expansion | Biotech-enabled sesquiterpenoid synthesis reduces batch-to-batch variability for luxury fragrance formulation. |
Research Methodology
Multiple input streams — primary interviews with plantation operators, fragrance house procurement directors, and wellness brand formulators; secondary validation through CITES trade database records, Vietnamese BIS export certification filings, and ECHA REACH registration disclosures; plus customs documentation from Thai Department of National Parks — were reconciled through bottom-up cultivation footprint modeling and top-down fragrance house demand estimation.
Cross-referencing historical price series for resinous heartwood against expert panel assessments of plantation maturation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include extraction method, application category, and cultivation geography. CAGRs were derived from supply-demand balance equations incorporating fungal infection rate variability and regulatory permit processing lag assumptions.
The model assumes a particular technology adoption path; alternative pathways for supercritical CO2 extraction miniaturization would alter the outlook if portable systems achieve cost parity with conventional steam distillation faster than projected. Forecasts reflect documented assumptions regarding plantation yield cycles and CITES enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Aromatherapy Oils Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Pericarp Waste Market