
 Mangosteen Market | 2026-2036
Mangosteen Market Size, Share, and Industry Trends Forecast 2026-2036
Mangosteen Market Analysis
Skilled agricultural labor for hand-pollination and selective harvesting is redrawing production economics across tropical growing belts. Genesis Today leverages direct farm partnerships in Southeast Asia to secure premium fresh fruit supply chains. Dole Food Company anchors large-scale distribution infrastructure that sustains cold-chain integrity from Indonesian orchards to North American retail channels. Xi'an Greena Biotech specializes in solvent-free extraction protocols that differentiate its xanthone concentrate output for pharmaceutical-grade buyers.
Mangosteen (Garcinia mangostana) is a tropical evergreen tree fruit with a thick purple pericarp rich in xanthones, particularly alpha-mangostin and gamma-mangostin, compounds with documented antioxidant and anti-inflammatory properties; the fruit pulp contains fructose, citric acid, and ascorbic acid, while the rind serves as the primary industrial feedstock for standardized extract production. Fresh Mangosteen dominates premium retail channels in East Asian markets where whole-fruit presentation commands price premiums, while Mangosteen Powder represents the fastest-expanding product type as functional food manufacturers seek shelf-stable, dose-controlled ingredient formats. Nutraceuticals occupies the deepest margin pool among end-use segments, driven by contract manufacturing demand for standardized xanthone extracts in capsule and tablet formulations.
Thailand's Department of Agriculture enforces Good Agricultural Practice certification for export-bound fresh mangosteen, while the FDA evaluates New Dietary Ingredient notifications for xanthone-based supplements entering the United States, creating dual compliance thresholds for vertically integrated suppliers. ISO 22000 food safety management systems and HACCP protocols govern processing facility accreditation for international wholesale buyers. Stakeholders must monitor evolving maximum residue limits for post-harvest fungicides in key import jurisdictions, as regulatory stringency directly shapes cultivar selection and orchard management investment cycles.
Market Dynamics
Fresh mangosteen export eligibility now hinges on Thailand's Good Agricultural Practice certification, tightening raw material access for international nutraceutical processors and reshaping procurement economics across Southeast Asian supply chains.
Growth Catalysts
- Xanthone standardization protocols:ISO 22000-aligned extraction methods enable pharmaceutical-grade xanthone concentrates for antioxidant supplement formulations, expanding contract manufacturing demand from global nutraceutical brands.
- Thailand's GAP mandate:The Department of Agriculture's certification requirement for export-bound fresh fruit elevates quality premiums and consolidates supplier relationships with certified orchard networks.
- Shelf-stable powder formats:Functional food manufacturers drive rapid adoption of dose-controlled mangosteen powder as a replacement for perishable whole-fruit logistics in beverage and confectionery applications.
Market Restraints
- Hand-pollination labor scarcity:Skilled agricultural workers for selective harvesting command rising wages across Indonesian and Vietnamese growing belts, compressing orchard margins.
- Post-harvest fungicide MRL divergence:Maximum residue limit heterogeneity between Japan's PMDA, the US FDA, and EU EFSA forces cultivar-specific treatment protocols that fragment processing batch economics.
- Pericarp supply concentration:Industrial xanthone feedstock depends on fresh fruit processing clusters in Thailand and Vietnam, creating geographic vulnerability to monsoon disruption.
Strategic Opportunities
- Indian nutraceutical import liberalization:FSSAI's evolving dietary supplement notification pathway opens formulation partnerships for standardized xanthone extracts in capsule and tablet formats.
- Solvent-free extraction convergence:Supercritical CO2 technology paired with HACCP-accredited facilities enables clean-label positioning for premium cosmetic and pharmaceutical buyers.
- Direct-to-ingredient procurement:Nutraceutical brands bypass commodity traders through farm-direct partnerships, capturing traceability premiums and shortening quality verification cycles.
Industry Challenges
- New Dietary Ingredient notification timelines:FDA evaluation periods for xanthone-based supplements extend product launch schedules, tying up R&D capital and compressing patent-protected revenue windows.
- Cold-chain integrity capex:Maintaining pericarp bioactive stability from Indonesian orchards to North American processing facilities requires continuous refrigeration infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mangosteen Market |
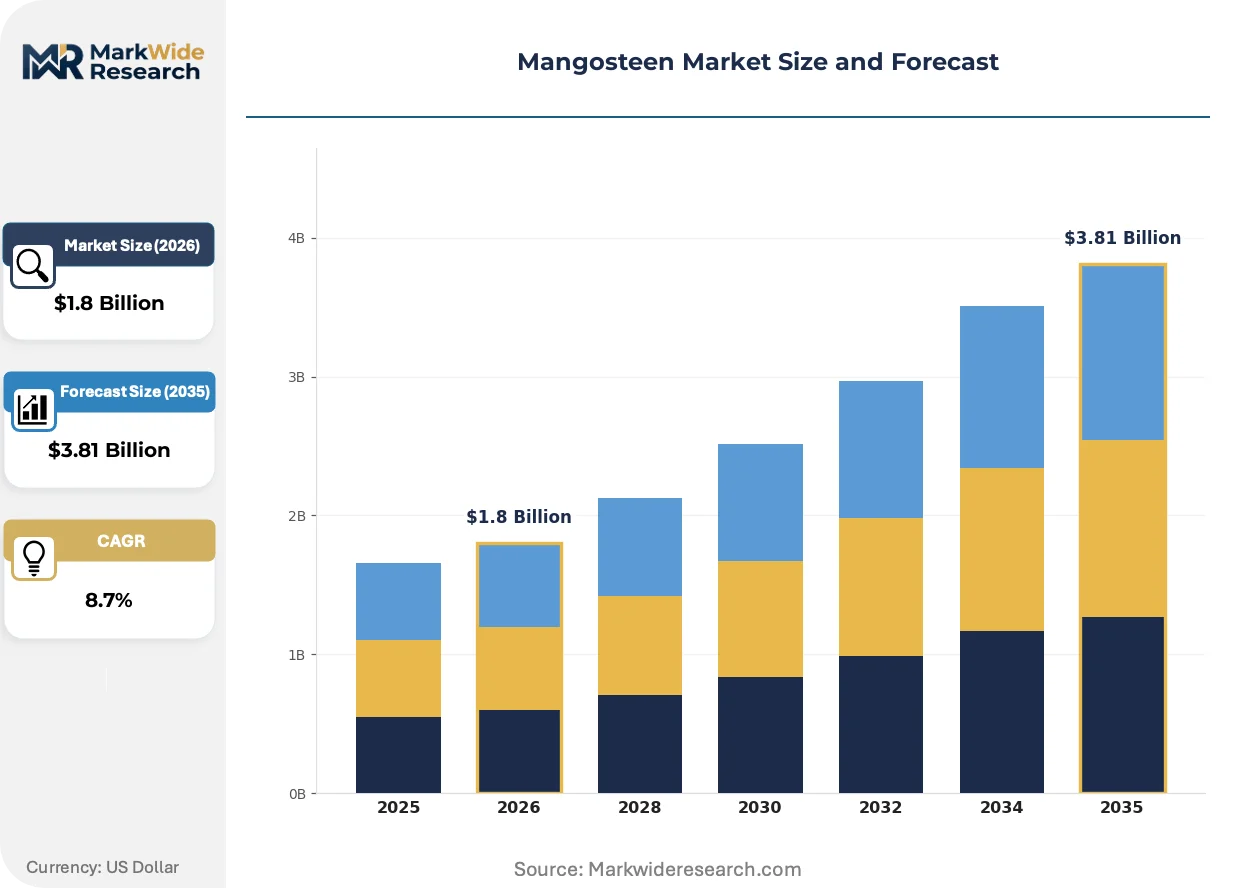
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Mangosteen, Dried Mangosteen, Mangosteen Juice, Mangosteen Powder End Use: Food Industry, Beverage Industry, Nutraceuticals, Cosmetics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Geometric Focus: Health Benefits, Culinary Use, Beauty Applications, Functional Foods |
| Companies Covered | Genesis Today, NutraCargo, LLC, Dole Food Company, Sensient Technologies Corporation, Tropical Fruits LLP, Xi'an Greena Biotech, Elcon Drugs and Formulation Ltd., Bhumija Lifesciences, Best Chain Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mangosteen Market Emerging Trajectories
Technological substitution in extraction methods, regulatory tightening on agricultural residues, and procurement model restructuring are converging to reshape competitive positioning across the mangosteen value chain.
Supercritical CO2 extraction is supplanting conventional solvent-based methods in pharmaceutical-grade xanthone production. Nutraceutical contract manufacturers in Vietnam and Thailand are retrofitting facilities to capture clean-label premiums from US and EU buyers. This shift compresses acceptable residue thresholds and disqualifies legacy hexane-dependent processors from premium supply tiers.
REACH-aligned maximum residue limits for post-harvest agrochemicals are tightening across EU import jurisdictions. Thai exporters must demonstrate compliance through accredited laboratory testing to maintain wholesale contracts with European nutraceutical brands. The pericarp processing segment bears the heaviest adaptation burden, as fungicide traces concentrate in the industrial feedstock stream.
Ingredient buyers now demand batch-level phytochemical assay documentation before contract execution. Functional food manufacturers in East Asia are displacing spot-market purchasing with multi-year supply agreements tied to alpha-mangostin potency guarantees. This behavioral shift is most pronounced in Japan, where METI-registered importers require ISO 22000 certification and third-party xanthone verification for every shipment.
Mangosteen Market Segmentation
Mangosteen's commercial structure fragments across preservation formats, industrial applications, and channel economics. Margin pools concentrate in high-potency extract derivatives and certified fresh fruit supply chains, while commodity-grade products face compression from input cost volatility.
Product Type:
Premium extraction feedstock and perishable whole-fruit logistics command the widest margin spreads within this category.
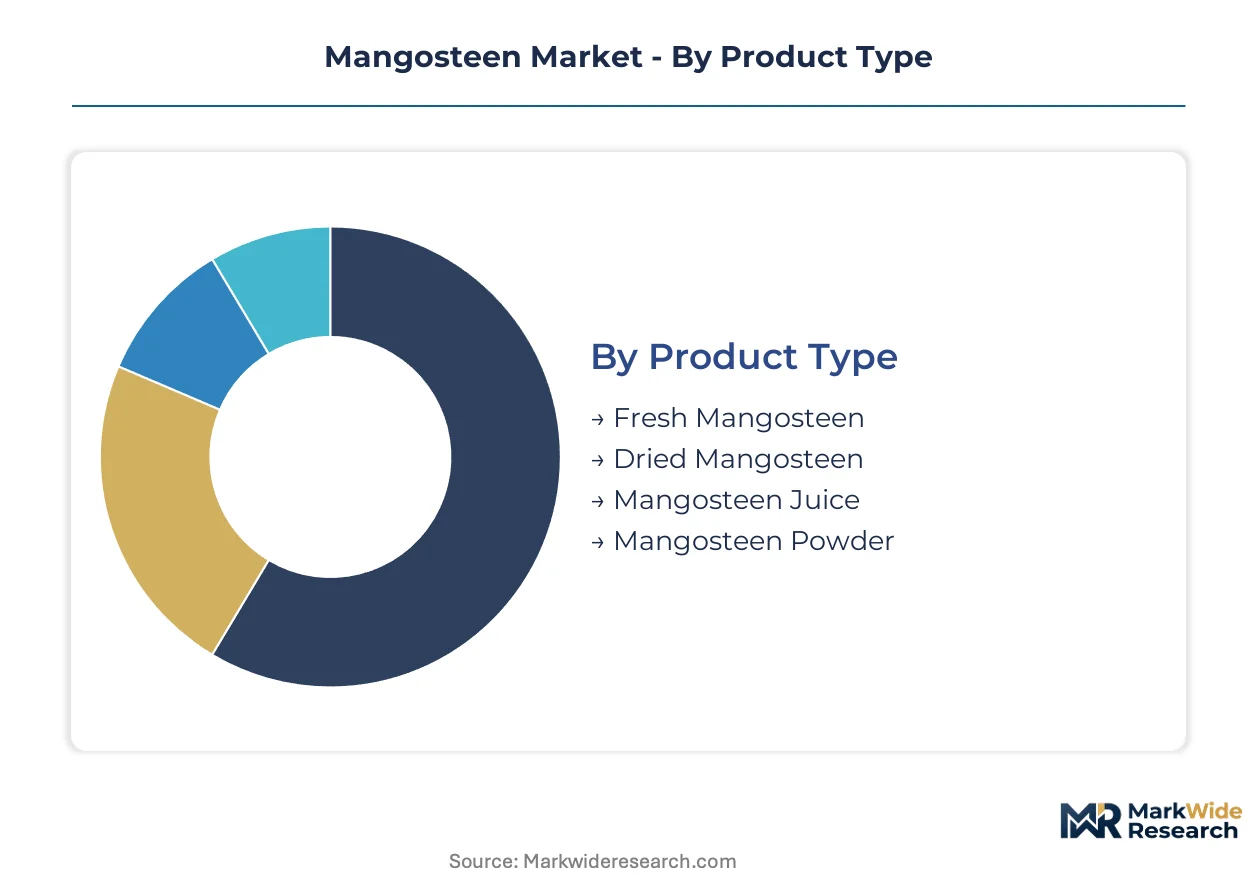
- Fresh Mangosteen:Whole purple pericarp fruit requiring continuous cold-chain maintenance from Thai and Indonesian orchards to East Asian retail channels. Japanese and South Korean importers pay certified-premium prices for GAP-validated shipments with intact calyx and minimal transit bruising.
- Mangosteen Powder:Spray-dried or freeze-dried pulp standardized for alpha-mangostin content, enabling dose-controlled incorporation into functional beverages and supplement matrices. Functional food manufacturers in Japan and the United States are displacing perishable logistics with this shelf-stable format, though potency verification adds procurement overhead.
- Dried Mangosteen:Dehydrated aril segments retaining fructose and citric acid profiles for confectionery and snack applications.
- Mangosteen Juice:Pasteurized liquid extract blended with other tropical fruits for retail beverage positioning.
The dominant share belongs to Fresh Mangosteen, while Mangosteen Powder is closing the gap fastest.
End Use:
Application economics diverge sharply between commodity food processing and high-margin pharmaceutical-grade extraction.
- Nutraceuticals:Standardized xanthone concentrates for antioxidant supplement capsules and tablets, subject to FDA New Dietary Ingredient notification and ISO 22000 facility accreditation. Contract manufacturers in Thailand and Vietnam capture value through alpha-mangostin potency guarantees backed by third-party assay documentation.
- Cosmetics:Pericarp-derived extracts positioned for anti-aging and skin-brightening formulations in South Korean and Japanese personal care markets. Clean-label pressure from EU buyers is accelerating solvent-free supercritical CO2 adoption.
- Food Industry:Pulp incorporation into jams, jellies, and dessert applications with lower bioactive retention requirements.
- Beverage Industry:Juice blending and flavoring applications competing on tropical positioning rather than functional claims.
Nutraceuticals maintains the deepest margin pool, with Cosmetics expanding most quickly on clean-label extraction demand.
Distribution Channel:
Channel selection determines traceability depth and price realization for differentiated versus commodity grades.
- Wholesale:Bulk pericarp supply to nutraceutical processors and industrial extract manufacturers, dominating volume throughput from Thai processing clusters. Batch-level phytochemical documentation is becoming mandatory for contract execution with Japanese METI-registered importers.
- Specialty Stores:Premium whole-fruit positioning in urban East Asian markets where presentation quality commands price multiples over supermarket alternatives.
- Supermarkets:Standard-grade fresh fruit and packaged juice competing on seasonal availability.
- Online Retail:Direct-to-consumer powder and supplement formats with subscription-model potential.
Wholesale captures the largest volume share, though Specialty Stores are gaining fastest on premiumization trends.
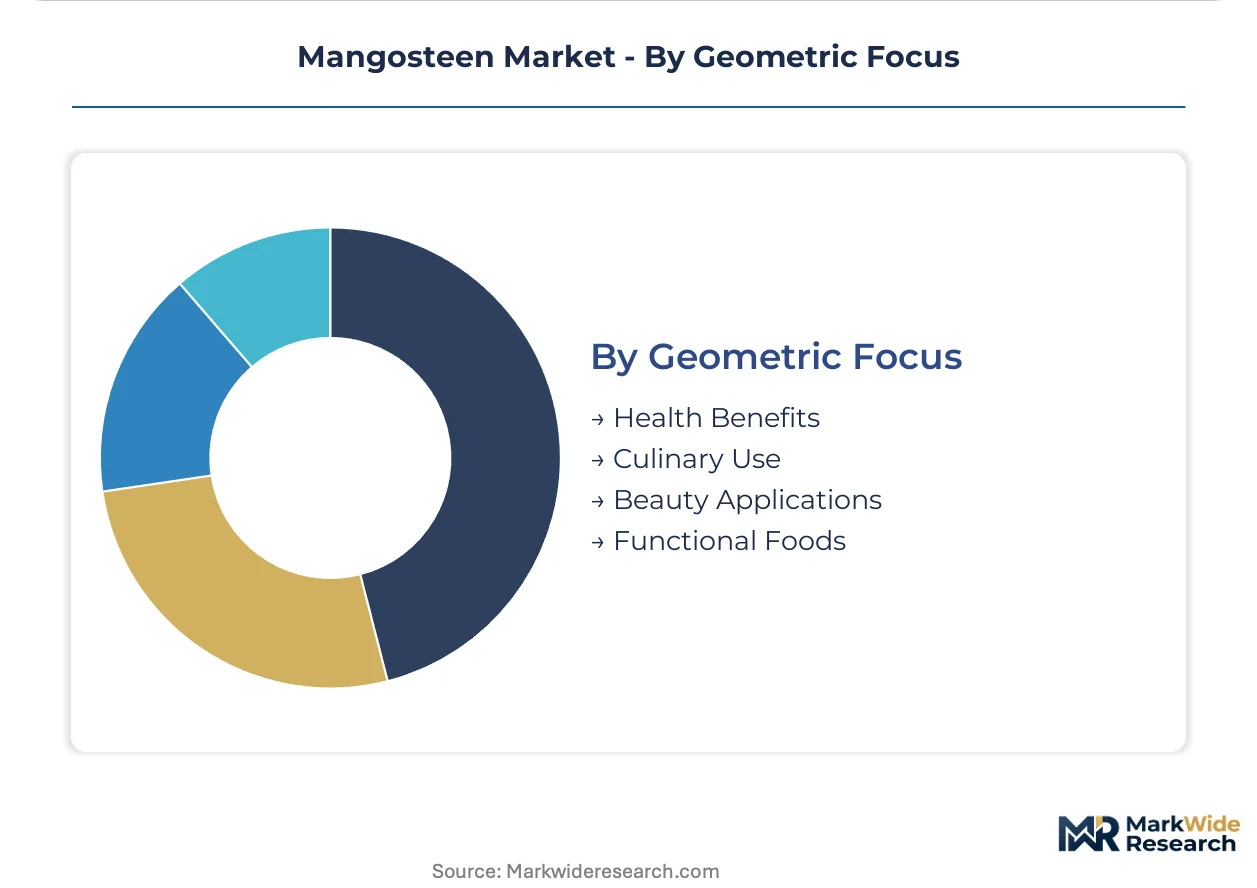
Geometric Focus:
Benefit-positioning strategies segment buyers by willingness to pay for verified bioactive content versus sensory experience.
- Health Benefits:Xanthone-standardized products targeting antioxidant and anti-inflammatory claims, requiring regulatory navigation of FDA, EFSA, and FSSAI notification pathways. This positioning demands the most intensive supply chain documentation.
- Functional Foods:Bioactive-fortified everyday consumption formats bridging wellness and convenience, with Japanese and South Korean manufacturers leading formulation innovation.
- Culinary Use:Fresh fruit and pulp applications emphasizing flavor profile and textural quality.
- Beauty Applications:Topical and ingestible cosmetic positioning with emphasis on skin health outcomes.
Health Benefits anchors the value pool, while Functional Foods shows the steepest expansion trajectory on mainstream wellness integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price realization for Thai GAP-certified fresh fruit runs 40-60% above Indonesian standard-grade exports, creating a two-tier sourcing architecture that shapes procurement strategies across East Asian nutraceutical supply chains.
Thailand
Contract manufacturers for Japanese and South Korean nutraceutical brands drive concentrated demand for alpha-mangostin standardized extracts. The Department of Agriculture enforces Good Agricultural Practice certification for all export-bound fresh mangosteen, elevating compliance costs but securing premium channel access. Processing clusters around Chanthaburi and Rayong provinces coordinate pericarp supply for pharmaceutical-grade xanthone production.
Vietnam
Functional food manufacturers in Ho Chi Minh City and Hanoi accelerate powder format adoption for beverage fortification applications. The Ministry of Agriculture and Rural Development oversees post-harvest treatment protocols aligned with EU REACH residue limits. Mekong Delta orchards near Cần Thơ supply raw material to supercritical CO2 extraction facilities serving clean-label cosmetic buyers.
Indonesia
Hand-pollination labor scarcity in Sumatran and Javanese growing belts compresses orchard margins while sustaining volume leadership in non-certified fresh fruit segments. The national agricultural quality agency maintains voluntary standards below Thai mandatory thresholds. North Sumatra processing hubs around Medan concentrate pericarp collection for regional nutraceutical intermediate supply.
United States
Dietary supplement brands navigate FDA New Dietary Ingredient notification timelines for xanthone-based antioxidant formulations, extending product development cycles. Import procurement concentrates through West Coast distribution infrastructure serving functional food manufacturers. California-based formulation houses source Thai-certified extracts for premium positioning in natural retail channels.
Japan
METI-registered importers enforce batch-level phytochemical assay documentation and ISO 22000 certification for every mangosteen-derived shipment entering pharmaceutical and cosmetic supply chains. Tokyo and Osaka-based nutraceutical contract manufacturers specify alpha-mangostin potency guarantees in multi-year supply agreements. This regulatory stringency filters supplier eligibility to Thai and Vietnamese certified processors exclusively.
Mangosteen Market Vendor Landscape
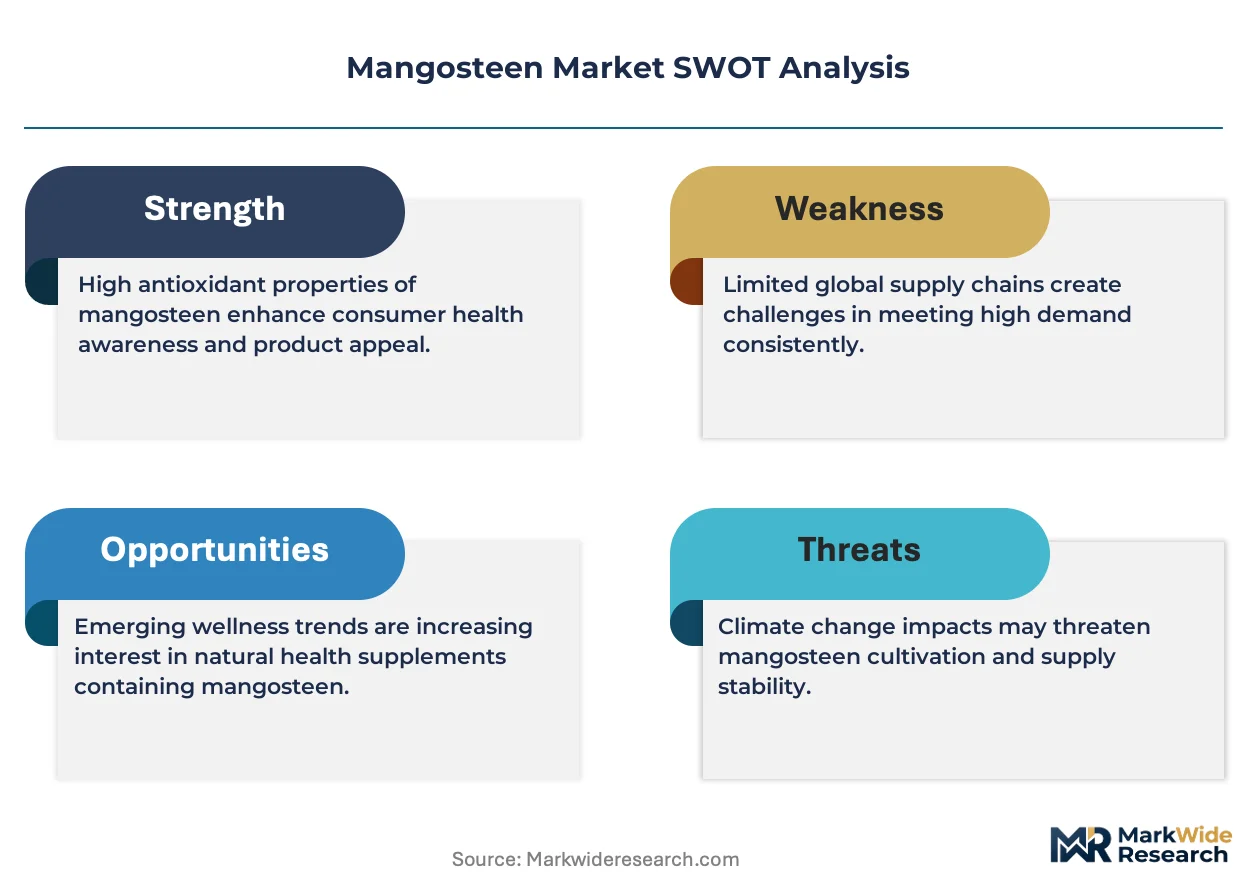
Technology leadership and cost leadership are held by different player archetypes across the mangosteen value chain, with solvent-free extraction specialists commanding premium pricing while commodity-grade processors compete on volume throughput. The market structure fragments across three tiers: certified fresh fruit exporters, standardized extract manufacturers, and functional ingredient formulators. Strategic moves concentrate on backward integration into orchard networks and supercritical CO2 capacity expansion for clean-label positioning.
Within the extraction technology tier, Xi'an Greena Biotech represents pharmaceutical-grade positioning through solvent-free protocol specialization, while Genesis Today anchors direct farm partnership models for premium fresh fruit supply security. Dole Food Company occupies the scale-driven distribution infrastructure segment, sustaining cold-chain integrity across trans-Pacific logistics. These three archetypes illustrate divergent competitive vectors: technology differentiation, supply chain control, and logistics scale.
| Leading Market Players |
|---|
| Genesis Today |
| NutraCargo, LLC |
| Dole Food Company |
| Sensient Technologies Corporation |
| Tropical Fruits LLP |
| Xi'an Greena Biotech |
| Elcon Drugs and Formulation Ltd. |
| Bhumija Lifesciences |
| Best Chain Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Cold-chain capacity utilization in Thai GAP-certified corridors establishes floor pricing for export-grade fresh fruit, while Indonesian standard-grade volumes compete on logistics efficiency rather than quality premiums. Scale economies in pericarp processing clusters concentrate margin capture among solvent-free extraction specialists, compressing spot-market processors into commodity tiers.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade xanthone concentrates from commodity powder grades. Contract manufacturers command potency-guarantee premiums through ISO 22000 certification and third-party alpha-mangostin assay documentation. Cost compression in standard-grade dried fruit intensifies because Vietnamese processors expand spray-drying capacity. Functional food manufacturers exhibit highest price sensitivity, while Japanese METI-registered importers absorb certification premiums for traceability assurance.
Supply Chain Analysis
Thailand and Vietnam anchor pharmaceutical-grade xanthone extraction, while Indonesia feeds regional fresh fruit and intermediate processing. Pericarp supply draws from Thai GAP-certified orchards and Mekong Delta collection networks, with alpha-mangostin content varying by cultivar and harvest timing. Single-source vulnerability concentrates in Thai processing clusters around Chanthaburi and Rayong provinces exposed to monsoon disruption. Distribution runs through East Asian nutraceutical contract manufacturers and North American natural retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction adoption represents a technological inflection disrupting legacy solvent-dependent processors, while FDA New Dietary Ingredient notification timelines compress revenue windows for xanthone-based supplement entrants. These forces reward upstream control and regulatory navigation capability.
For Market Incumbents: Shield certified orchard relationships through multi-year alpha-mangostin supply agreements with Japanese and South Korean nutraceutical brands. Expand solvent-free extraction capacity in Vietnam to capture clean-label premiums from EU cosmetic buyers. The threat of REACH-aligned residue limit tightening favors processors with in-house laboratory testing infrastructure. For New Entrants and Emerging Players: Direct-to-ingredient procurement services represent a service-layer gap where incumbents under-serve small-batch functional food manufacturers seeking traceability documentation. Target Indian FSSAI notification pathway navigation for dietary supplement partnerships. Penetrate through farm-direct quality verification platforms that shorten procurement cycles for mid-tier nutraceutical brands. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Thai GAP-certified extract manufacturers with multi-year Japanese supply contracts. Long-term viability centers on backward integration into orchard networks and supercritical CO2 capacity. Acquisition candidates combine ISO 22000 accreditation with established METI-registered importer relationships. Monitor FDA NDI notification approval velocity as inflection indicator for US market accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Networks | Captures GAP certification premiums and secures pericarp feedstock for extraction capacity. |
| Supercritical CO2 Capacity Expansion | Enables REACH-compliant positioning for EU pharmaceutical and cosmetic ingredient buyers. |
| FSSAI Notification Pathway Investment | Opens formulation partnerships for xanthone-based supplements in India's liberalizing nutraceutical import regime. |
| Direct Farm Partnership Platforms | Shortens quality verification cycles and captures traceability premiums from mid-tier nutraceutical brands. |
| ISO 22000 Certification Acceleration | Qualifies processors for Japanese METI-registered importer supply tiers and multi-year contracts. |
Methodological Framework
The analysis maps fresh fruit logistics, extract manufacturing, and functional ingredient formulation sub-sectors, each validated through orchard managers, nutraceutical procurement leads, and contract manufacturing executives. Primary interviews with Thai Department of Agriculture certification officers, Vietnamese supercritical CO2 facility operators, and Japanese METI-registered importers combined with secondary validation from FDA NDI notification databases, EU REACH residue limit registers, and FSSAI dietary supplement guidelines. Bottom-up orchard yield modeling and top-down nutraceutical demand sizing provided triangulation across data sources.
Consistency checks validated volume and value outputs against customs trade flows, cold-chain logistics capacity disclosures, and extraction facility expansion announcements. Segmentation modeling incorporated preservation format, end-use application, distribution channel depth, and bioactive potency tier dimensions. CAGRs were derived from supply-side capacity buildout trajectories and demand-side contract manufacturing expansion patterns, with alpha-mangostin standardization protocols and GAP certification penetration rates as key forecast inputs across the projection horizon.
Forecasts assume regulatory continuity in FDA NDI evaluation timelines, EU REACH residue limits, and Thai GAP certification requirements; material policy shifts in any regime would require re-modeling supply eligibility and price realization assumptions. Specific risks include hand-pollination labor wage escalation, maximum residue limit divergence between import jurisdictions, and monsoon disruption to Thai processing cluster operations. Recalibration cycles align with material shifts in extraction technology adoption, regulatory notification approvals, and orchard certification penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Tamanu Oil Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Vetiver Oil Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market