
 Customized Nutrient Premixes Market | 2026-2036
Customized Nutrient Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Customized Nutrient Premixes Market Insights
India is reconfiguring its premix manufacturing footprint with new blending facilities near Mumbai and Hyderabad to serve domestic food fortification programs. DSM Nutritional Products anchors European vitamin premix supply through its Netherlands operations. Glanbia Nutritionals leverages dairy-protein integration to dominate sports-nutrition premix formulations. Cargill Incorporated competes on grain-sourced mineral premix scale across North American animal feed channels.
Customized nutrient premixes constitute precisely metered blends of vitamins, minerals, amino acids, and probiotics, typically dosed at 0.1% to 2.0% of finished product weight and manufactured via tumble blending or high-shear mixing to achieve coefficient-of-variation below 5%. Their primary purpose is to deliver uniform micronutrient distribution across processed foods, clinical nutrition, and compound feeds where direct single-ingredient dosing creates unacceptable variability. Powder formulations occupy the dominant share of volume due to superior stability and lower transport costs, though liquid premixes are gaining share in beverage applications where solubility and dispersion speed command premium positioning. The Food & Beverage application segment carries the deepest margin pools as clean-label and free-from positioning justifies ingredient customization premiums.
The FDA's Food Safety Modernization Act mandates preventive controls for human food that elevate documentation burdens on premix suppliers seeking US market access. EFSA's revised dietary reference values for folate and vitamin D are recalibrating formulation targets across European premix portfolios. India's FSSAI fortification standards for edible oil and wheat flour are creating structured demand channels that domestic and multinational premix suppliers must navigate. Stakeholders should monitor evolving maximum permitted levels for bioactive compounds as regulators tighten upper-limit thresholds that could force formula redesigns and inventory write-downs.
Market Dynamics
Precise micronutrient fortification mandates from infant formula manufacturers are compressing formulation cycles and forcing premix suppliers to rebuild blending capabilities around coefficient-of-variation targets below 3%.
Growth Catalysts
- EFSA revised folate thresholds:European premix portfolios require recalibration, creating replacement demand for reformulated vitamin blends across clinical nutrition channels.
- India FSSAI edible oil mandates:Structured procurement channels for wheat flour and oil fortification are institutionalizing premix offtake volumes.
- High-shear mixing platforms:Tumble blending equipment upgrades in German innovation clusters around Cologne are reducing batch-to-batch variability penalties.
Market Restraints
- Vitamin input cost volatility:Feedstock fluctuations in niacin and riboflavin precursors compress margin buffers for standard-grade premix portfolios.
- Netherlands supply concentration:European vitamin premix capacity anchors through a single dominant supplier, creating single-source vulnerability for cross-border buyers.
- FDA FSMA documentation burdens:Preventive control mandates elevate compliance costs for premix suppliers seeking US market access without established quality management systems.
Strategic Opportunities
- Hyderabad blending facilities:New domestic manufacturing capacity positions suppliers to capture wheat flour fortification volumes under India's national nutrition programs.
- Liquid premix beverage penetration:Solubility-optimized formats command premium positioning in functional drinks where dispersion speed determines formulation selection.
- Probiotic-vitamin convergence:Synbiotic premix combinations target gut-health positioning in clinical nutrition with dual-mechanism efficacy claims.
Industry Challenges
- Microencapsulation technician scarcity:Specialized formulation chemists capable of stability-optimized nutrient protection command wage premiums that inflate R&D overhead.
- Clean-label certification timelines:Third-party non-GMO and organic verification processes extend product launch cycles by eight to fourteen months.
- Legacy ERP integration friction:Batch record digitization for FDA compliance conflicts with established manufacturing execution systems in mid-scale blending facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customized Nutrient Premixes Market |
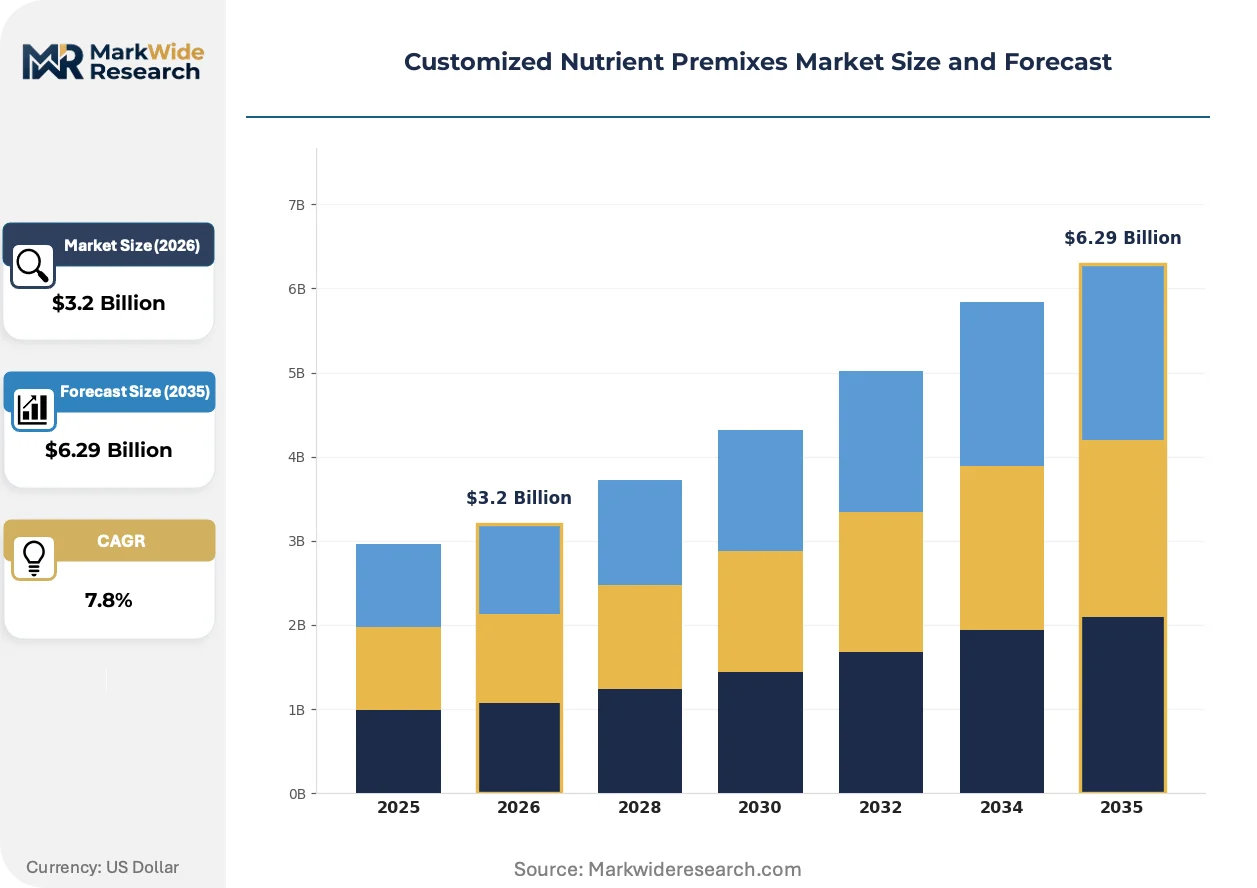
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics Application: Food & Beverage, Animal Feed, Pharmaceutical, Personal Care End User: Manufacturers, Distributors, Retailers, Healthcare Providers Form: Powder, Liquid, Granule, Tablet |
| Companies Covered | DSM Nutritional Products, Glanbia Nutritionals, Cargill Incorporated, Archer Daniels Midland, BASF SE, Prinova Group LLC, Corbion N.V., Vitablend Netherland B.V., SternVitamin GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customized Nutrient Premixes Market Trends and Innovations
Hybrid manufacturing architectures are collapsing the traditional separation between powder stability and liquid solubility performance, enabling format-agnostic premix platforms that serve multiple end-use specifications from unified production lines.
Encapsulation technology is hybridizing vitamin and mineral matrices with lipid-based barrier systems that extend shelf stability in tropical distribution conditions. Infant formula manufacturers in Southeast Asian markets are adopting these formats at accelerated procurement cycles. The structural consequence is compressing regional formulation differentiation into unified global specifications that reduce inventory fragmentation.
REACH substance evaluation protocols are expanding data requirements for vitamin premix additives entering European compound food channels. Industrial consequence includes extended safety dossier preparation periods that delay new ingredient market entry. Sports nutrition premix portfolios face the most acute compliance recalibration as novel bioactive compounds trigger enhanced substance scrutiny.
Direct procurement from blending facilities is displacing layered distributor networks for high-volume food fortification programs. National wheat flour millers in India and edible oil refiners are establishing captive premix supply relationships that bypass traditional ingredient traders. This channel compression is most visible in government-mandated fortification schemes where price transparency requirements expose distributor markups to competitive tender processes.
Customized Nutrient Premixes Market Segmentation
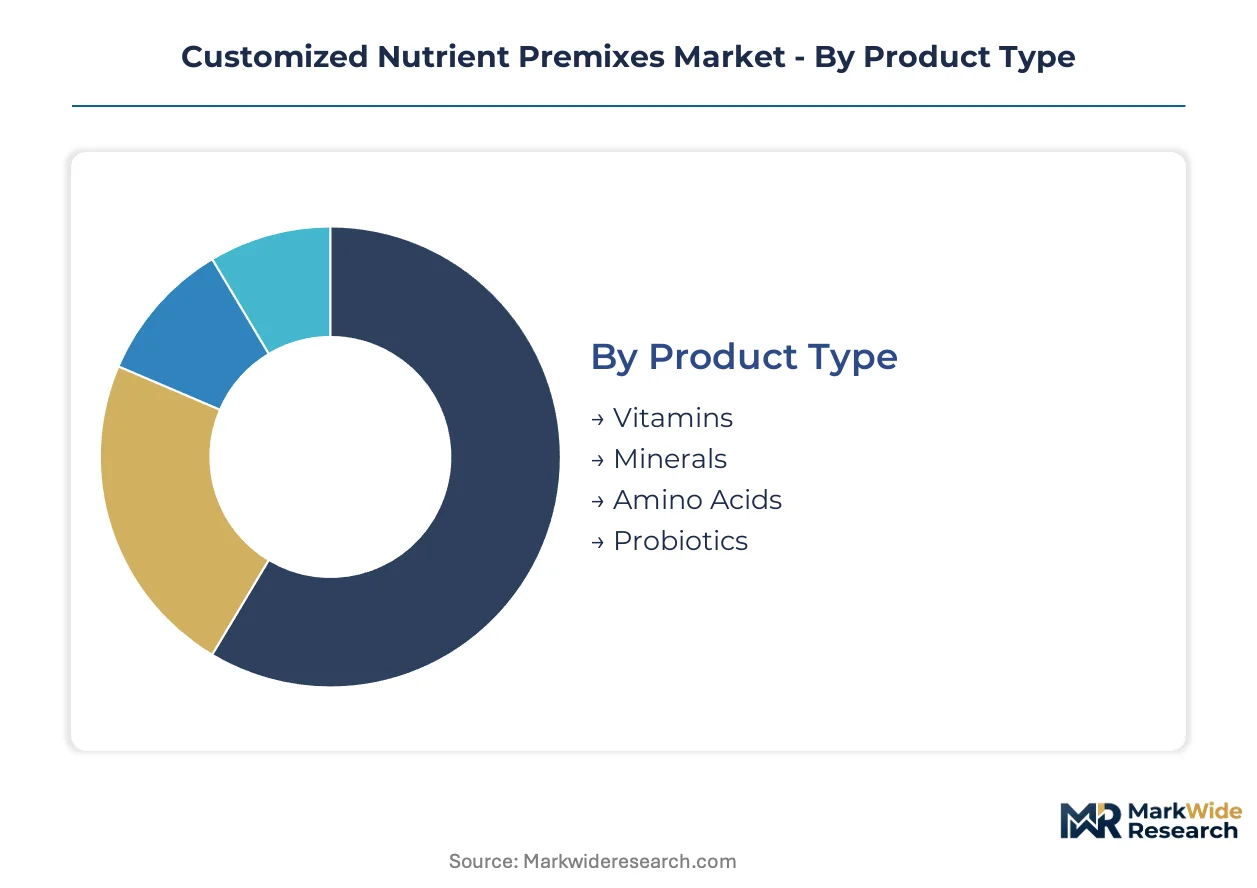
Premix segmentation determines formulation complexity, regulatory pathway, and margin architecture. Product chemistry dictates stability requirements. Application end-use shapes dosage precision and certification burdens.
Product Type:
Cost tier stratification separates commodity mineral inputs from high-value bioactive compounds requiring specialized protection technologies.
- Vitamins:Lipid-soluble and water-soluble variants demand microencapsulation against oxidation and moisture degradation. Infant formula manufacturers in Germany and the Netherlands specify coefficient-of-variation below 3% for vitamin premixes. EFSA's revised folate and vitamin D reference values force portfolio recalibration across European clinical nutrition channels.
- Minerals:Chelated and inorganic salt forms vary in bioavailability and cost position. Grain-sourced mineral premixes dominate North American animal feed procurement through direct mill relationships. Iron and zinc fortification of wheat flour and edible oil drives structured demand under India's FSSAI mandates.
- Amino Acids:Essential and conditionally essential profiles target sports nutrition and clinical recovery segments.
- Probiotics:Viable colony-forming unit stability requires refrigerated distribution chains and moisture-barrier packaging.
Vitamins command the established base. The steepest expansion runs through probiotics as synbiotic combinations gain clinical nutrition positioning.
Application:
End-use maturity separates regulated pharmaceutical channels from price-sensitive commodity feed markets.
- Food & Beverage:Clean-label positioning and free-from claims justify customization premiums. Powder formats dominate bakery and dairy fortification due to superior stability and lower transport economics. Liquid premixes penetrate functional beverages where dispersion speed determines formulation selection.
- Animal Feed:Compound feed manufacturers specify mineral premixes at 0.1% to 2.0% inclusion rates for uniform micronutrient distribution. Cargill Incorporated leverages grain-sourced mineral scale across North American channels.
- Pharmaceutical:Clinical nutrition and enteral feeding demand GMP-certified blending with batch documentation for FDA FSMA compliance.
- Personal Care:Topical nutrient delivery requires solubility-optimized formats with skin-permeation characteristics.
Food & Beverage holds the revenue concentration. Pharmaceutical applications are climbing the fastest as medical nutrition prescriptions expand.
End User:
Customer type determines procurement structure, with direct manufacturer relationships displacing layered distribution in high-volume fortification programs.
- Manufacturers:Infant formula producers and wheat flour millers establish captive premix supply relationships bypassing traditional ingredient traders. DSM Nutritional Products anchors European vitamin supply through Netherlands operations serving manufacturer direct procurement.
- Distributors:Regional ingredient traders face margin compression as government tender processes expose markup structures to price transparency requirements.
- Retailers:Private-label supplement brands source customized premixes for differentiated positioning in pharmacy and mass-market channels.
- Healthcare Providers:Hospital nutrition services and clinical dietitians specify patient-specific micronutrient protocols for enteral and parenteral applications.
Manufacturers represent the procurement volume base. Healthcare providers are gaining share fastest as personalized nutrition protocols expand.
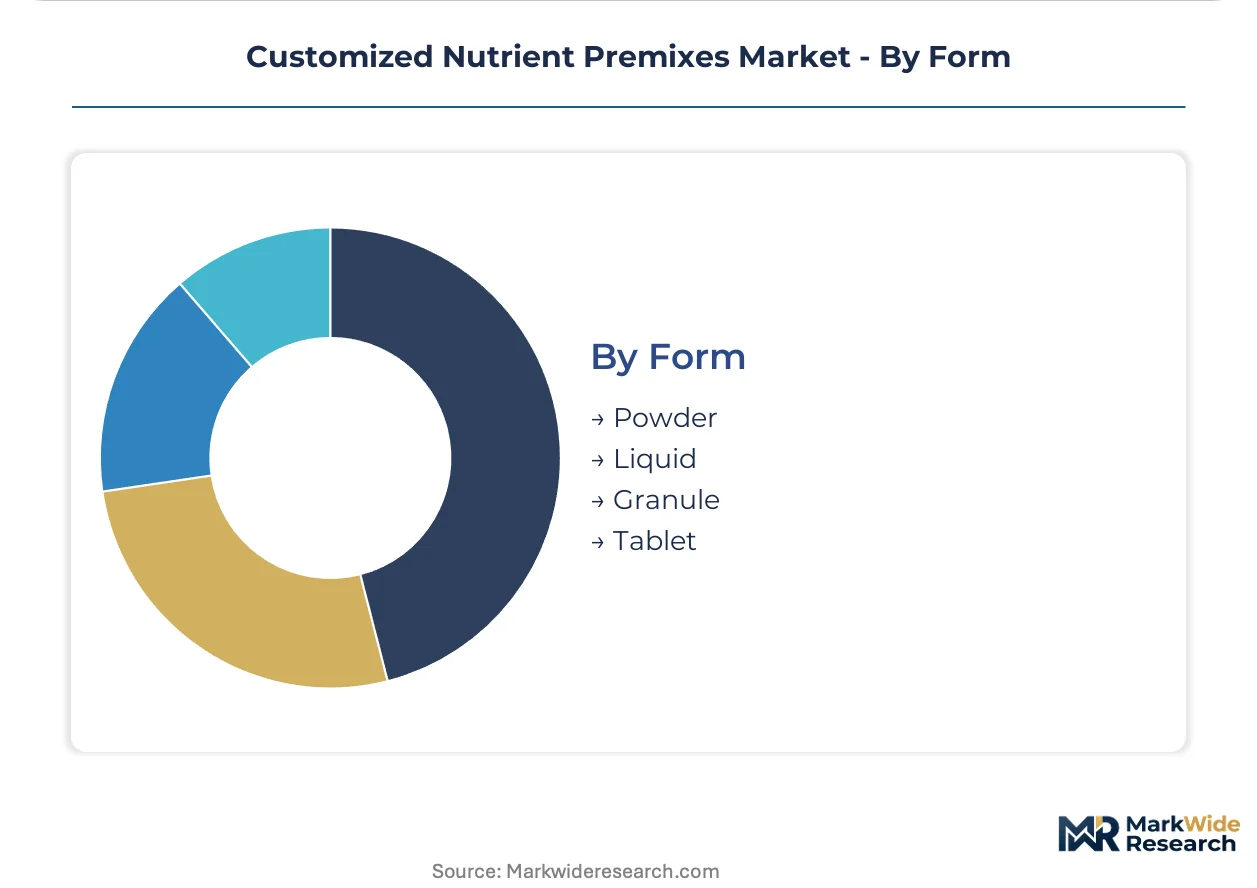
Form:
Physical format governs stability performance, solubility characteristics, and equipment compatibility across blending and dosing operations.
- Powder:Tumble-blended and high-shear mixed formats achieve coefficient-of-variation below 5% for uniform distribution. Superior shelf stability and transport economics sustain volume dominance across food, feed, and pharmaceutical channels.
- Liquid:Solubility-optimized concentrates command premium positioning in beverage applications where dispersion speed determines selection. Hybrid manufacturing architectures now enable format-agnostic production from unified lines.
- Granule:Free-flowing agglomerated forms reduce dust generation and improve handling in high-speed packaging operations.
- Tablet:Direct-compression premixes integrate binders and disintegrants for supplement manufacturing efficiency.
Powder formulations anchor supply volumes. Liquid formats are expanding most quickly as functional beverage applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European vitamin premix capacity concentrates through Netherlands operations, creating single-source vulnerability for cross-border buyers. German ingredient innovation clusters around Cologne and Hamburg drive tumble blending equipment upgrades. Indian domestic manufacturing expansion near Mumbai and Hyderabad targets government-mandated fortification volumes.
United States
Infant formula manufacturers in Illinois and California pursue coefficient-of-variation targets below 3% for precise micronutrient fortification. The FDA's Food Safety Modernization Act mandates preventive controls that elevate documentation burdens on premix suppliers. Chicago-area blending facilities face batch record digitization friction with legacy manufacturing execution systems.
Germany
Clinical nutrition channels require EFSA-aligned folate and vitamin D recalibration across European premix portfolios. The country's national food regulator enforces purity thresholds under the EU's updated Food Supplements Directive. Cologne hosts high-shear mixing platform upgrades that reduce batch-to-batch variability penalties for regional suppliers.
Netherlands
DSM Nutritional Products anchors continental vitamin premix supply through Rotterdam-area operations serving manufacturer direct procurement. REACH substance evaluation protocols extend safety dossier preparation periods for new ingredient market entry. Amsterdam-region logistics hubs manage cross-border distribution to German and Belgian compound food manufacturers.
India
FSSAI fortification standards for wheat flour and edible oil create structured procurement channels for domestic and multinational premix suppliers. New blending facilities near Mumbai and Hyderabad capture volumes under national nutrition programs. Government tender processes expose distributor markups to price transparency requirements, compressing regional trader margins.
China
Sports nutrition premix demand accelerates as functional beverage applications proliferate in Shanghai and Guangzhou. The country's national food regulator enforces GB standards for micronutrient additives in processed foods. Yangtze River Delta manufacturing zones develop hybrid architectures enabling format-agnostic production from unified powder and liquid lines.
Customized Nutrient Premixes Market Competitive Landscape
Specialized nutrition ingredient suppliers and diversified agricultural processors split the market into distinct capability tiers. European chemical conglomerates and North American grain traders anchor opposing ends of the value chain. Three archetypes dominate: micronutrient technology specialists with encapsulation expertise, integrated nutrition platforms leveraging protein-dairy synergies, and commodity-scale mineral premix operators. Competitive moves concentrate on direct procurement relationship capture and high-shear mixing capacity expansion.
Within the technology-specialist tier, DSM Nutritional Products and BASF SE exemplify European chemical heritage applied to vitamin stability engineering. Glanbia Nutritionals occupies a position bridging dairy-protein integration with sports-nutrition formulation depth. Cargill Incorporated anchors the commodity-scale vector through grain-sourced mineral premix operations. These three represent divergent strategic postures: precision micronutrient protection, vertical nutrition platform building, and agricultural supply chain leverage.
| Leading Market Players |
|---|
| DSM Nutritional Products |
| Glanbia Nutritionals |
| Cargill Incorporated |
| Archer Daniels Midland |
| BASF SE |
| Prinova Group LLC |
| Corbion N.V. |
| Vitablend Netherland B.V. |
| SternVitamin GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Cologne and Hamburg innovation clusters anchor European vitamin premix capacity, concentrating high-shear mixing expertise that translates into formulation premium capture for regional suppliers serving cross-border clinical nutrition channels. This geographic concentration of technical capability directly shapes downstream pricing power, as buyers seeking coefficient-of-variation below 3% face limited alternative sourcing for precision-blended infant formula premixes.
Pricing Analysis
EFSA's revised folate and vitamin D reference values dictate the pricing tier structure across European premix portfolios, forcing reformulation investments that stratify pricing across premium-mid-economy levels based on certification grade and micronutrient precision. Price differentiation hinges on GMP compliance depth and batch documentation granularity for FDA FSMA alignment, with vitamin input cost volatility in niacin and riboflavin precursors compressing margins in standard-grade tiers. Wheat flour millers in India exhibit acute price sensitivity under government tender transparency requirements, while infant formula manufacturers in Germany absorb premiums for sub-3% variability guarantees.
Supply Chain Analysis
REACH substance evaluation protocols function as de facto export-control mechanisms limiting novel bioactive compound flows into European compound food channels, extending safety dossier preparation periods. Supply concentrates in the Netherlands for vitamin premixes, India for iron and zinc fortification inputs, and Germany for high-shear mixing equipment, with raw material dependencies on Chinese niacin precursors, Indian riboflavin fermentation stocks, and Brazilian mineral ore. Single-source vulnerability around Rotterdam-area DSM operations creates structural risk for cross-border buyers, while distribution runs through direct manufacturer procurement relationships that displace layered distributor networks in high-volume fortification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists capable of microencapsulation stability engineering command wage premiums that inflate R&D overhead, creating a bottleneck that constrains premix supplier expansion and rewards early capability lock-in.
For Market Incumbents: Insulate margin position by deepening backward integration into vitamin precursor supply through captive fermentation capacity or long-term offtake agreements with Indian and Chinese feedstock suppliers. Expand high-shear mixing capacity in Cologne and Hamburg clusters to capture EFSA-mandated portfolio recalibration demand, while accelerating batch record digitization to preempt FDA FSMA documentation penalties that disadvantage mid-scale blending facilities with legacy ERP systems. For New Entrants and Emerging Players: Build out Hyderabad and Mumbai blending facilities to capture wheat flour and edible oil fortification volumes under India's FSSAI-mandated national nutrition programs, where government tender processes expose incumbent distributor markups to competitive displacement. Target liquid premix beverage penetration in functional drinks, where solubility-optimized formats command premium positioning and dispersion speed requirements favor specialized entrants over commodity-scale mineral operators. For Investors and Strategic Acquirers: Long-term, this sits as a nutrition-platform consolidation play because synbiotic premix combinations and probiotic-vitamin convergence create defendable positioning in clinical nutrition with dual-mechanism efficacy claims. Acquisition focus should center on mid-scale European blending facilities with GMP certification and established EFSA regulatory dossier capabilities. The signal to watch is REACH substance evaluation protocol expansion to additional bioactive categories, which would accelerate compliance-driven consolidation among sub-scale premix formulators lacking dedicated regulatory affairs infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| High-Shear Mixing Capacity Expansion | Cologne facility upgrades reduce batch-to-batch variability penalties for EFSA-aligned premix portfolios. |
| Backward Integration into Vitamin Precursors | Captive niacin and riboflavin feedstock supply buffers margin compression from commodity price swings. |
| Liquid Premix Format Development | Solubility-optimized concentrates penetrate functional beverage applications where dispersion speed determines selection. |
| Direct Procurement Relationship Capture | Bypassing distributor layers in Indian government fortification tenders exposes markup structures to competitive pressure. |
| Synbiotic Premix Portfolio Buildout | Probiotic-vitamin combinations target gut-health positioning in clinical nutrition with dual-mechanism efficacy differentiation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with premix formulation chemists, plant managers at blending facilities, procurement leads at infant formula manufacturers, and FSSAI regulatory affairs specialists; and secondary validation through EFSA guidance documents, FDA FSMA preventive control records, FSSAI fortification standards, and customs trade data on vitamin precursor imports. Bottom-up volume triangulation across product type, application, and form segments was cross-checked against top-down value estimates derived from manufacturer revenue disclosures and industry association aggregates.
Forecast inputs considered coefficient-of-variation precision tiers, regulatory recalibration timelines, and channel structure evolution across the projection horizon. Segmentation dimensions modeled include vitamin-mineral-probiotic-amino acid chemistry, food-beverage-feed-pharmaceutical application end-use, powder-liquid-granule-tablet physical form, and manufacturer-distributor-retailer-healthcare provider procurement structure. CAGRs were derived from slope analysis of segment-level volume trajectories adjusted for input cost elasticity and compliance burden intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by commodity-scale mineral operators or accelerated REACH protocol expansion would shift outcomes. Material shifts in EFSA maximum permitted level thresholds or FSSAI fortification mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Aromatherapy Oils Market
Specialty Ingredients
Mango Butter Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Abies Alba (Fir) Leaf Oil Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Mangosteen Market