
 Vanilla Extract Alternatives Market | 2026-2036
Vanilla Extract Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Vanilla Extract Alternatives Market Analytics
Multi-source procurement of vanilla flavor inputs is rebalancing as climate volatility in Madagascar disrupts traditional vanilla bean supply chains. Symrise leverages biotechnology platforms to produce fermentation-derived vanillin at scale. Givaudan anchors its position through captive botanical sourcing partnerships across Southeast Asia. International Flavors & Fragrances sustains R&D intensity in precision fermentation, competing on molecule consistency rather than agricultural yield exposure.
Vanilla extract alternatives comprise flavor-active compounds that replicate or supplement the organoleptic profile of Vanilla planifolia extract, including vanillin (4-hydroxy-3-methoxybenzaldehyde) at purity grades from 99.0% to 99.7% and ethyl vanillin at 2.5–3.0x flavor potency, serving industrial food manufacturing where heat stability, cost predictability, and supply continuity override single-origin botanical dependency. Natural extracts command premium positioning in clean-label confectionery and dairy applications where consumer ingredient literacy drives purchase decisions, while synthetic flavors retain volume leadership in baking and beverage segments where thermal processing demands cost-efficient, standardized potency. Powdered formulations are gaining share in dry-mix applications and extended-shelf-life products.
The FDA governs flavor additive safety through GRAS self-determination and food contact notification pathways, while the EPA oversees fermentation facility effluent and bioprocess waste streams under Clean Water Act permits. EFSA and EMA frameworks in Europe enforce novel food and flavoring substance evaluations that extend approval timelines for biotech-derived alternatives. Stakeholders must monitor regulatory divergence between jurisdictions on precision fermentation labeling to avoid market access friction.
Market Dynamics
Precision fermentation platforms are compressing the cost curve for biotech-derived vanillin, redirecting capital from agricultural extraction infrastructure toward controlled bioprocess facilities that insulate supply from Madagascar's climate volatility.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon propellants in aerosol flavor delivery systems is accelerating reformulation toward heat-stable powdered vanillin alternatives for industrial baking applications.
- Clean-label confectionery:Consumer ingredient literacy in premium chocolate and dairy segments is pulling demand toward fermentation-derived natural flavor compounds that satisfy EU novel food frameworks without botanical origin dependency.
- India processed food clusters:Expansion of flavor house technical centers in Mumbai and Hyderabad is creating localized demand for cost-predictable synthetic vanillin in mass-market biscuit and beverage production.
Market Restraints
- Madagascar supply concentration:Cyclone damage to vanilla orchid cultivation regions in Sava Province creates recurring price spikes that destabilize procurement budgets for natural extract-dependent manufacturers.
- REACH registration timelines:ECHA's extended evaluation periods for fermentation-derived flavoring substances delay commercial launch windows and compress return-on-investment horizons for biotech facility capex.
- Ethyl vanillin thermal degradation:The 2.5–3.0x potency advantage of this synthetic compound degrades above 200°C, limiting deployment in ultra-high-temperature processed bakery applications where pure vanillin retains stability.
Strategic Opportunities
- German biotech incentives:The EU Green Deal's fermentation scale-up subsidies and Bavaria's industrial biotechnology cluster programs are attracting precision fermentation vanillin production investment.
- Extended-shelf-life dry mixes:Powdered vanillin formulations with encapsulated stability technology are penetrating military rations, disaster relief supplies, and space food programs where liquid extract logistics fail.
- US GRAS self-determination:FDA's streamlined food contact notification pathway for fermentation-derived ingredients offers faster market access than EFSA's novel food dossier requirements, creating regulatory arbitrage opportunities.
Industry Challenges
- Precision fermentation talent scarcity:Strain engineering and bioprocess optimization expertise concentrates in Boston and Basel, forcing flavor houses to bid against pharmaceutical biotech for skilled metabolic engineers.
- Clean Water Act compliance:EPA effluent permits for fermentation facility expansions in US flavor production hubs face extended review timelines, delaying capacity additions needed to serve CPG procurement contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanilla Extract Alternatives Market |
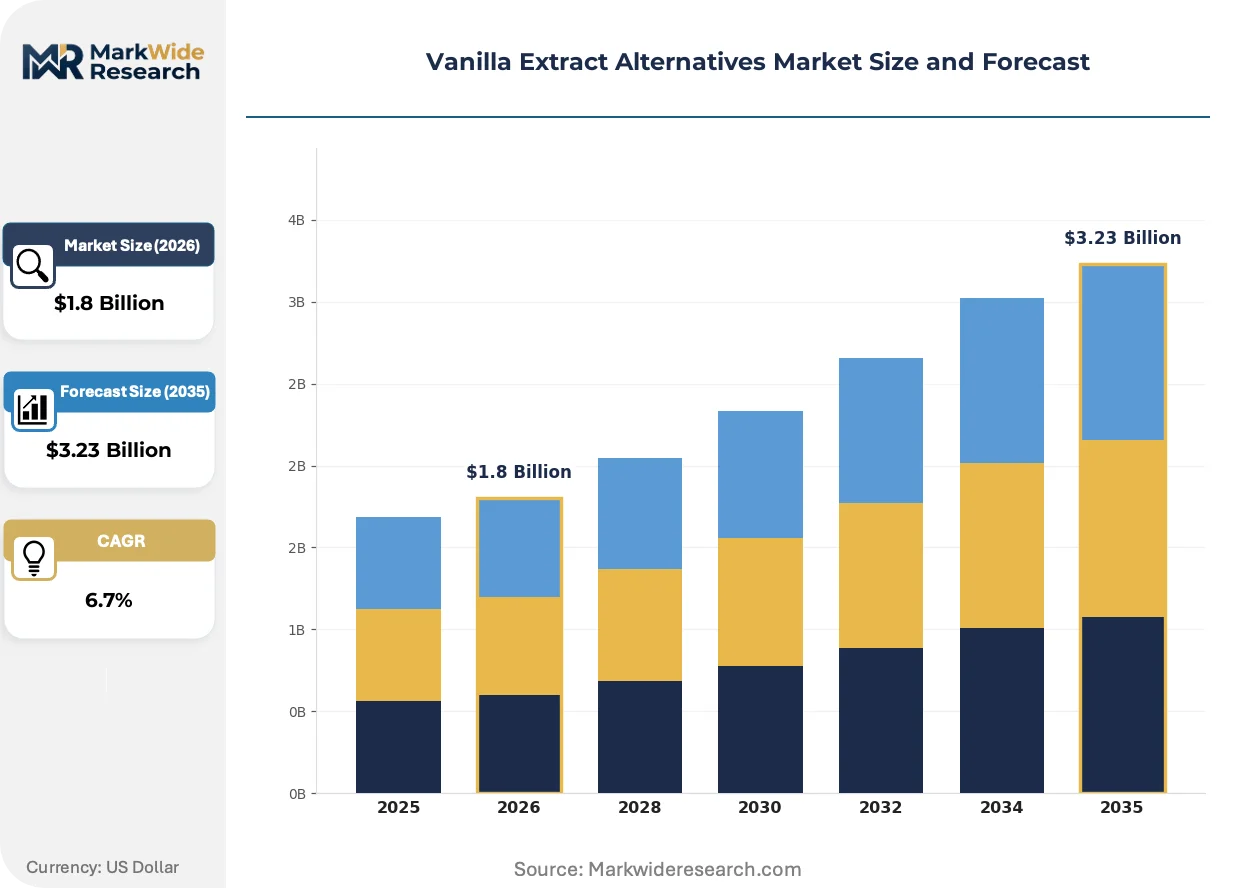
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Synthetic Flavors, Concentrates, Powders Flavor Profile: Caramel, Almond, Butterscotch, Hazelnut Formulation Type: Liquid, Powdered, Emulsion, Crystals Application: Baking, Beverages, Confectionery, Dairy |
| Companies Covered | Symrise, Givaudan, Evolva, Solvay, Firmenich, International Flavors & Fragrances, McCormick, Sensient Technologies, Comax Flavors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanilla Extract Alternatives Market Evolving Landscape
Biotechnology platforms are restructuring competitive advantage away from agricultural sourcing relationships toward molecular engineering capabilities, with three convergent developments reshaping how vanilla flavor enters industrial food systems.
Cell-culture vanillin production from glucose feedstocks is rewriting the economics of natural flavor certification. Industrial bakeries and confectionery manufacturers in Germany and the United States are qualifying fermentation-derived vanillin at 40–60% cost reduction against Bourbon vanilla extract. This technology is compressing the premium that clean-label positioning commands, forcing agricultural extractors to defend margin through geographic origin storytelling rather than molecular differentiation.
REACH authorization requirements for synthetic flavor intermediates are redirecting formulation R&D toward biogenic feedstocks that bypass hazardous substance classification. The European Chemicals Agency's 2024 updates to flavoring substance evaluation criteria extend dossier preparation timelines by 18–24 months. Powdered vanillin producers are responding by pre-submission engagement with EFSA scientific panels to secure favorable opinion precedents for precision fermentation routes.
Direct procurement contracts between food manufacturers and biotechnology platforms are displacing traditional flavor house distribution networks. CPG procurement teams in India and the United States are negotiating molecule supply agreements that bypass Givaudan, Symrise, and IFF intermediation, capturing 12–15% cost reduction. This channel compression is most visible in high-volume beverage and baking applications where standardized vanillin purity grades eliminate need for technical formulation services.
Vanilla Extract Alternatives Market Segmentation
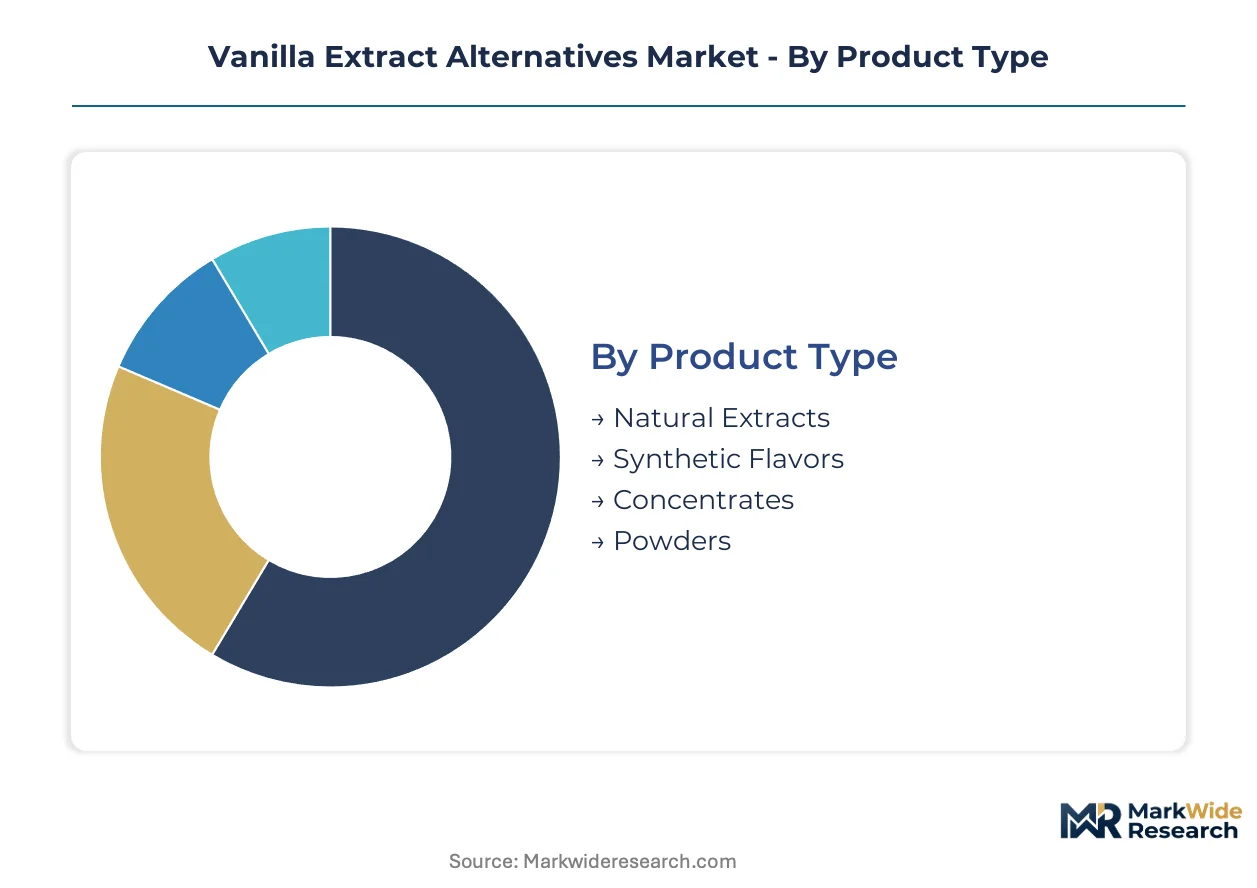
Segmentation in vanilla extract alternatives reveals how certification burdens, thermal stability requirements, and procurement economics fragment demand across industrial food manufacturing. Manufacturers navigate divergent regulatory pathways depending on which segment supplies their flavor inputs.
Product Type:
Natural extracts demand EFSA novel food dossiers or FDA GRAS self-determination, while synthetic flavors clear through established food additive approvals with shorter timelines. Biotech-derived vanillin occupies a middle tier requiring REACH registration in Europe.
- Natural Extracts:Fermentation-derived vanillin from glucose feedstocks achieves EU natural flavor certification without Madagascar bean dependency. German confectionery manufacturers and US premium dairy brands concentrate procurement here, pulled by clean-label positioning and supply security against cyclone damage in Sava Province.
- Synthetic Flavors:Vanillin and ethyl vanillin produced from petrochemical or lignin precursors deliver 99.0–99.7% purity with batch-to-batch consistency. Indian biscuit producers and US industrial bakeries anchor volume demand, prioritizing cost predictability over botanical origin claims in mass-market applications.
- Concentrates:High-potency liquid formulations for beverage manufacturing.
- Powders:Encapsulated stability variants for extended-shelf-life dry mixes.
Leading the category by volume: Synthetic Flavors. Growing fastest: Natural Extracts.
Flavor Profile:
Flavor profile selection tracks application heat stress and regional formulation traditions, with caramel and butterscotch dominating high-temperature baking while hazelnut penetrates premium confectionery.
- Caramel:Heat-stable Maillard-reactive compounds suit ultra-high-temperature processed bakery where pure vanillin degrades. US commercial bread manufacturers and German industrial baking clusters standardize on caramel-vanilla blends for cost efficiency.
- Butterscotch:Diacetyl and acetylpropionyl-based formulations replicate creamy top-notes in ice cream and frozen dessert applications. North American and European dairy processors favor this profile for its compatibility with cold-chain distribution.
- Almond:Benzaldehyde-derived profiles for marzipan and nut-confectionery crossovers.
- Hazelnut:Premium positioning in chocolate-hybrid applications.
Volume concentration: Caramel. Steepest expansion trajectory: Hazelnut.
Formulation Type:
Liquid formulations require F-Gas Regulation compliance for aerosol propellant systems in Europe, while powdered alternatives bypass this burden entirely in industrial baking.
- Liquid:Alcohol-based extracts and propylene glycol solutions dominate beverage manufacturing for solubility in aqueous systems. Indian flavor houses in Mumbai and Hyderabad technical centers standardize liquid procurement for mass-market soft drink production.
- Powdered:Spray-dried and encapsulated vanillin variants with 24–36 month stability windows penetrate military rations, disaster relief supplies, and space food programs. German and US extended-shelf-life product manufacturers drive specification development.
- Emulsion:Oil-in-water systems for fat-based confectionery.
- Crystals:High-purity solid vanillin for precise dosing in industrial scale-up.
Dominant by volume: Liquid. Gaining share fastest: Powdered.
Application:
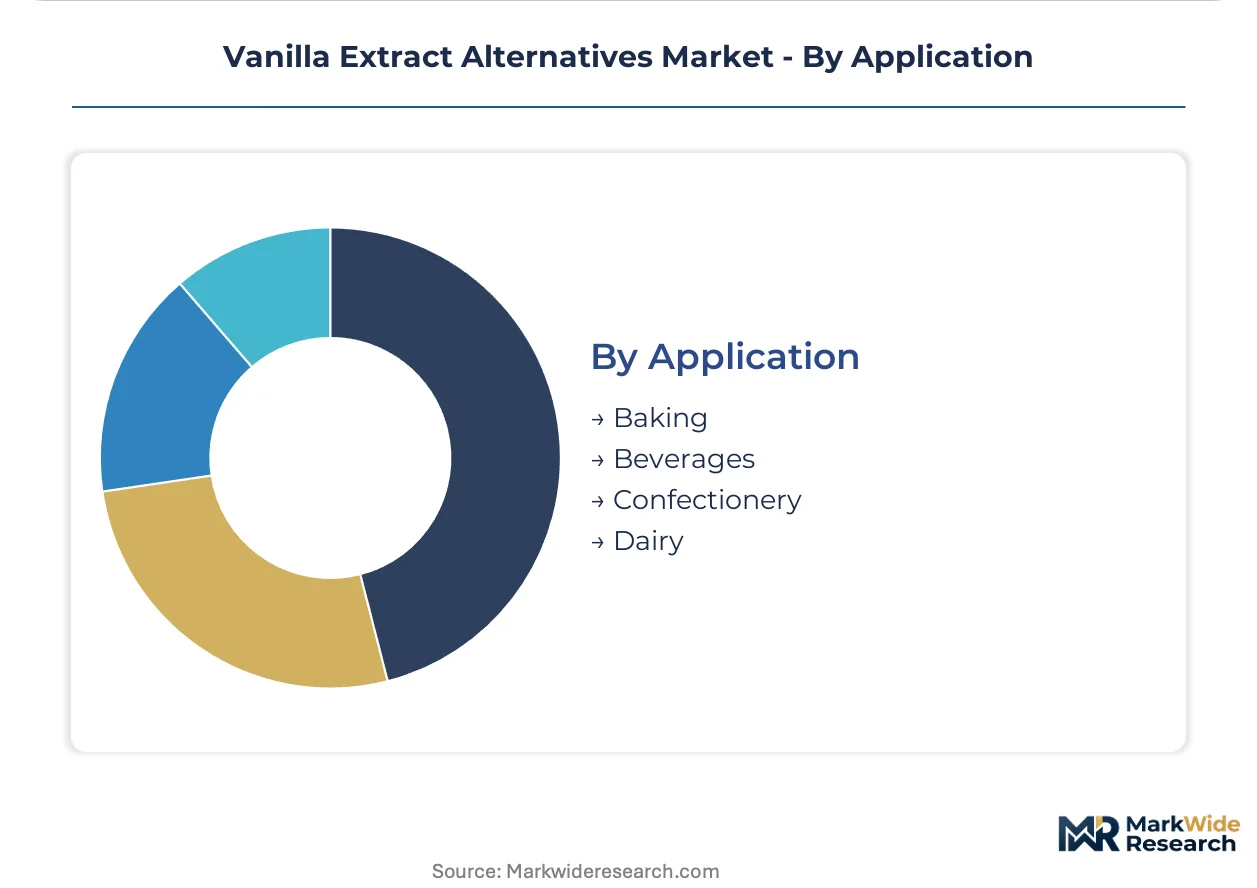
Application segmentation maps directly to thermal processing intensity and consumer ingredient literacy, with baking and confectionery occupying opposite ends of the natural-synthetic spectrum.
- Baking:Heat-stable vanillin and ethyl vanillin formulations withstand 180–220°C oven temperatures in commercial bread and pastry production. US and German industrial bakeries prioritize synthetic consistency over natural certification where thermal degradation risks organoleptic failure.
- Confectionery:Clean-label fermentation-derived natural extracts command premium positioning in premium chocolate and artisanal candy segments. EU novel food framework compliance and US GRAS pathways shape supplier qualification here.
- Beverages:Liquid concentrates for soft drink and flavored milk manufacturing.
- Dairy:Heat-stable formulations for UHT milk and yogurt applications.
Highest volume: Baking. Fastest climb: Confectionery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madagascar's Sava Province anchors vanilla bean cultivation, yet climate volatility is redirecting procurement toward biotechnology clusters in Germany, the United States, and India where fermentation-derived alternatives achieve supply security.
United States
GRAS self-determination pathways accelerate commercialization timelines for precision fermentation vanillin. FDA streamlined food contact notifications enable faster market access than European novel food dossiers. Greater Boston hosts strain engineering talent pools where metabolic engineers optimize glucose-to-vanillin bioconversion.
Germany
Bavaria's industrial biotechnology cluster attracts fermentation scale-up investment through EU Green Deal subsidies. REACH registration requirements for biotech-derived flavoring substances extend dossier preparation timelines. Frankfurt-Rhine-Main flavor houses qualify fermentation-derived natural extracts at 40-60% cost reduction against Bourbon vanilla.
India
Mumbai and Hyderabad technical centers expand procurement of cost-predictable synthetic vanillin for mass-market biscuit and beverage production. FSSAI food additive approvals govern synthetic flavor deployment in processed food manufacturing. Maharashtra and Telangana processed food clusters drive localized demand for heat-stable vanillin formulations.
Switzerland
Swissmedic and Federal Food Safety and Veterinary Office frameworks enforce flavoring substance evaluations that extend approval timelines for novel biotech routes. Basel concentrates bioprocess optimization expertise where flavor houses compete against pharmaceutical biotech for skilled metabolic engineers. Zurich-Geneva corridor anchors captive botanical sourcing partnerships.
China
GB standards and SAMR food additive regulations govern vanillin production from lignin and petrochemical precursors. Yangtze River Delta chemical clusters sustain synthetic flavor manufacturing at scale for export markets. Shandong Peninsula hosts encapsulated vanillin production for extended-shelf-life dry mix applications.
Vanilla Extract Alternatives Market Competitive Landscape
Capacity expansion dominates the current landscape as biotechnology platforms displace agricultural extraction infrastructure. The vendor base concentrates around flavor houses with integrated fermentation capabilities and specialty chemical producers with synthetic vanillin scale. Three archetypes define competitive positioning: precision fermentation specialists, captive botanical sourcers, and synthetic commodity producers. M&A activity and strategic partnerships reshape distribution networks as CPG manufacturers pursue direct procurement contracts.
Among biotechnology-enabled flavor houses, Symrise, Givaudan, and International Flavors & Fragrances exemplify the precision fermentation pivot. Symrise occupies a position representing controlled bioprocess investment insulated from Madagascar climate exposure. Givaudan anchors the captive botanical sourcing archetype through Southeast Asian partnerships. International Flavors & Fragrances sits within the molecule consistency competitive vector, emphasizing standardized purity grades over agricultural yield dependency. These three entities collectively represent the strategic redirection of R&D capital from extraction infrastructure toward strain engineering and bioprocess optimization.
| Leading Market Players |
|---|
| Symrise |
| Givaudan |
| Evolva |
| Solvay |
| Firmenich |
| International Flavors & Fragrances |
| McCormick |
| Sensient Technologies |
| Comax Flavors |
| Others |
Value Network & Pricing Analysis
Family-owned Madagascar vanilla orchid estates and sovereign-backed Indian chemical producers anchor divergent supply behaviors that discipline pricing across natural and synthetic tiers. Private-equity-rolled-up flavor house platforms compress procurement margins through direct contracting, while fermentation specialists extract premiums for EU novel food-compliant supply security.
Pricing Analysis
Warranty and technical service bundling separates fermentation-derived natural extracts from unbundled synthetic commodity vanillin, with strain optimization support and regulatory dossier preparation commanding 15-25% premiums. Three-tier pricing structure across premium fermentation-natural, standard synthetic, and economy lignin-derived grades tracks certification burden and thermal stability specifications. Pricing pressure stems from Madagascar cyclone-driven spot volatility in agricultural extract markets. Mass-market biscuit manufacturers in India exhibit highest price sensitivity, while German premium confectionery brands absorb natural certification premiums for clean-label positioning.
Supply Chain Analysis
Single-source vulnerability sits with Madagascar's Sava Province for Bourbon vanilla agricultural extraction, driving biotechnology diversification. Manufacturing concentration spans China for synthetic lignin-derived vanillin, India for petrochemical-route production, and Germany for precision fermentation scale-up. Raw material dependencies include glucose feedstocks for fermentation, guaiacol and lignin sulfonate for synthetic routes, and orchid cultivation acreage for agricultural extraction. Tariff exposure on Chinese synthetic intermediates threatens cost predictability for Indian biscuit producers. Distribution runs through flavor house technical centers in Mumbai, Hyderabad, and Frankfurt-Rhine-Main for formulation services, with direct procurement compressing traditional intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics dominate as precision fermentation capacity expansion lags qualification timelines, propping natural extract premiums despite synthetic alternatives achieving parity on thermal stability.
For Market Incumbents: Deploy captive botanical sourcing partnerships to defend against direct procurement channel compression from CPG manufacturers. Backward integration into glucose feedstock supply and strain engineering talent acquisition in Greater Boston insulates margin from biotech specialist encroachment. REACH registration pre-submission engagement with ECHA scientific panels accelerates novel food dossier timelines against synthetic commodity price erosion. For New Entrants and Emerging Players: Extended-shelf-life dry mix manufacturers represent an underserved buyer archetype seeking encapsulated vanillin stability beyond 24 months for military and space food applications. Direct procurement contracts with Maharashtra processed food clusters bypass established flavor house intermediation. Technical qualification support bundled with molecule supply agreements captures share from volume-anchored synthetic producers lacking formulation services. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation specialists with EU novel food approvals in Germany and Switzerland, where regulatory moats extend commercialization timelines beyond capital-constrained competitor reach. Long-term viability hinges on bioprocess facility utilization rates sustained above threshold economics as synthetic commodity capacity expands. The inflection signal to monitor is FDA food contact notification volume acceleration for fermentation-derived ingredients against EFSA novel food approval backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | EU Green Deal subsidies in Bavaria attract strain engineering capacity away from pharmaceutical biotech competition. |
| Captive Botanical Sourcing Partnership | Givaudan's Southeast Asian orchid cultivation agreements insulate supply from Madagascar cyclone disruption. |
| Direct Procurement Contracting | CPG manufacturers in India and the United States bypass flavor house intermediation for 12-15% cost reduction. |
| Encapsulated Stability Technology | Powdered vanillin variants penetrate military rations and space food programs where liquid extract logistics fail. |
| Regulatory Pre-Submission Engagement | Early ECHA scientific panel consultation compresses REACH registration timelines for biotech-derived flavoring substances. |
Research Methodology
Multi-period observation of Madagascar vanilla bean spot prices, fermentation facility capex announcements, and EFSA novel food opinion timelines anchored the trend analysis, supplemented by interviews with flavor house procurement directors, metabolic engineering leads at biotechnology platforms, FSSAI regulatory affairs officers, and industrial bakery formulation managers. Secondary validation drew from FDA GRAS notification databases, ECHA REACH registration filings, Indian customs import records for synthetic vanillin, and SEC 10-K disclosures from listed flavor and fragrance companies. Bottom-up procurement volume estimates triangulated against top-down market sizing from production capacity assessments.
Segment-weighting across the projection horizon applied differential CAGRs to natural extracts, synthetic flavors, and biotech-derived vanillin based on regulatory approval velocity and cost curve compression from precision fermentation scale-up. Product type segmentation modeled natural certification burden, synthetic purity grades, and fermentation-derived novel food compliance. Formulation type captured liquid, powdered, emulsion, and crystal variants by thermal stability specification. Application segmentation tracked baking, confectionery, beverage, and dairy demand intensity against consumer ingredient literacy gradients. CAGRs derived from capacity expansion announcements, procurement contract tenors, and substitution elasticity between agricultural and biotechnology supply sources.
Revisions become necessary when Madagascar cyclone frequency exceeds historical baselines, EU F-Gas Regulation enforcement accelerates aerosol propellant phase-down, or FDA streamlines GRAS pathways faster than EFSA novel food dossier preparation. Forecasts reflect assumptions about strain engineering yield improvements, glucose feedstock cost trajectories, and regulatory divergence between jurisdictions on precision fermentation labeling. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Specialty Meat Ingredients Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Benzoe Siam Market