
 Specialty Carbohydrates Market | 2026-2036
Specialty Carbohydrates Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Carbohydrates Market Outlook
Pharmaceutical formulators is unwinding the historical dominance of conventional food processors in specialty carbohydrate procurement. Cargill Incorporated leverages its corn wet-milling infrastructure to anchor supply security for North American pharmaceutical clients. Südzucker AG competes through beet-sourced inulin specialization, while Roquette Frères differentiates via pea-derived oligosaccharide platforms that bypass allergen labeling triggers in EU markets.
Specialty carbohydrates comprise structurally modified saccharides engineered for specific physiological or functional outcomes, including prebiotic fermentation resistance, controlled glycemic response, or enhanced encapsulation stability in active delivery systems. Hydrolysis and fermentation processing methods predominate in high-purity segments, with spray drying commanding premium positioning for thermolabile bioactive preservation. Oligosaccharides lead product-type value pools due to infant nutrition and gut-health positioning, while maltodextrin volume concentrates in sports nutrition and clinical enteral feeding applications where rapid gastric emptying proves clinically desirable.
FDA GRAS notifications and EFSA novel food authorizations shape market access timelines for new molecular entities, with China's NMPA dietary supplement registration adding a third compliance gate for Asia-bound exporters. ISO 22000 and FSSC 22000 certifications function as non-negotiable operational baselines rather than differentiators in pharmaceutical and infant-grade procurement. Stakeholders must monitor evolving microbiome health claim substantiation standards across FDA, EFSA, and China's SAMR to preempt reformulation cycles and label restriction risks.
Market Dynamics
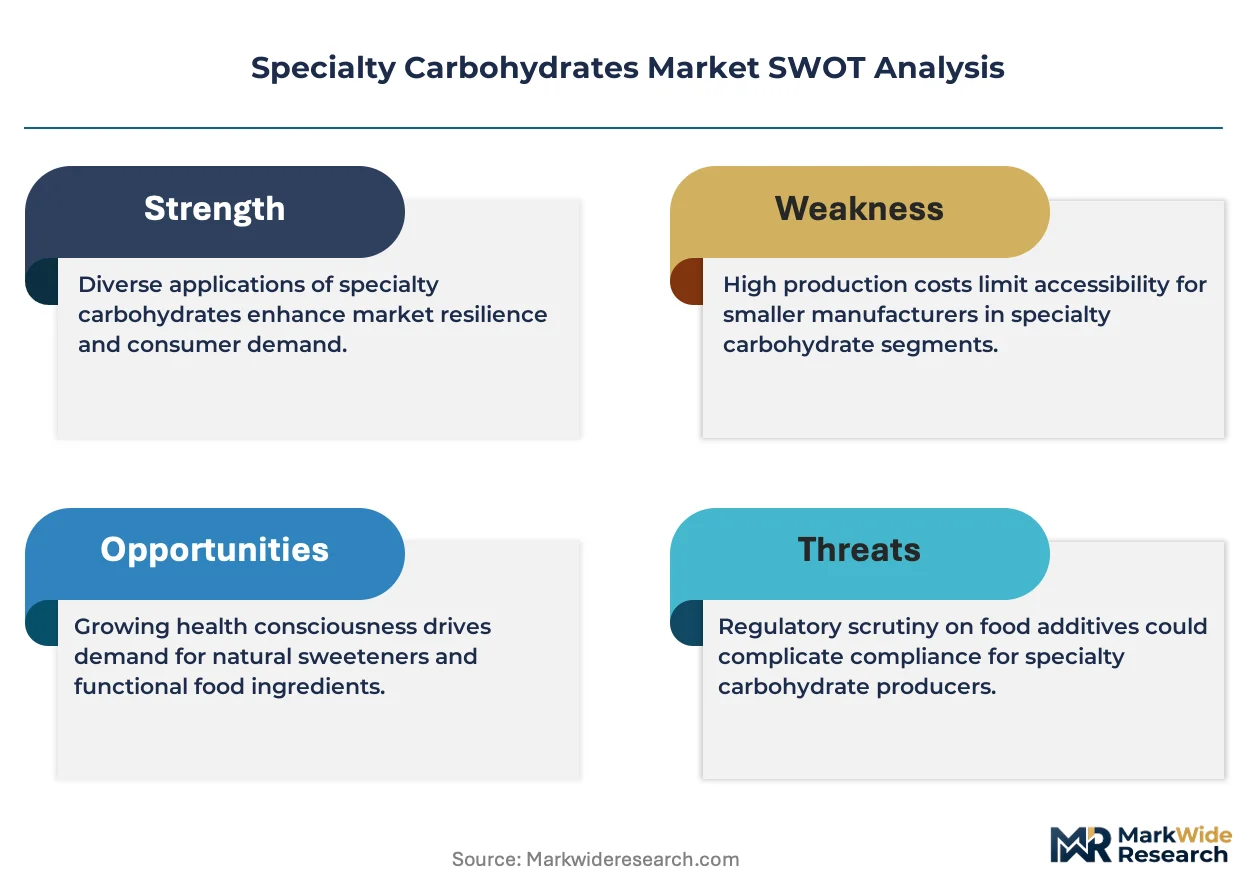
Pharmaceutical formulators are accelerating procurement of pharmaceutical-grade oligosaccharides and resistant starches, displacing conventional food processors as the dominant demand node and forcing upstream suppliers to reconfigure purity benchmarks and batch traceability protocols.
Growth Catalysts
- EFSA Novel Food authorizations:Accelerated approval pathways for prebiotic fibers in infant nutrition applications are expanding addressable markets for gut-health positioned ingredients.
- Clinical enteral feeding protocols:Hospital nutrition departments are standardizing rapid gastric emptying formulations, pulling maltodextrin volumes into medical-grade supply chains.
- Pea-protein fermentation platforms:Allergen-free oligosaccharide production methods are unlocking EU clean-label positioning without mandatory allergen declarations.
Market Restraints
- Corn wet-milling concentration:North American supply security depends on a limited number of heartland processing facilities, creating geographic vulnerability to climate-driven crop yield volatility.
- EU F-Gas Regulation compliance costs:Process emissions thresholds for fermentation-derived saccharides are elevating capital requirements for spray-drying operations.
- Enzymatic hydrolysis yield ceilings:Thermolabile bioactive preservation during oligosaccharide extraction imposes hard technical limits on unit economics.
Strategic Opportunities
- China NMPA dietary supplement registration:Formalized pathways for gut-health claims are creating a third compliance gate for exporters able to navigate SAMR microbiome substantiation standards.
- Sports nutrition direct-to-consumer channels:E-commerce platforms are compressing traditional ingredient distributor margins while enabling premium positioning for certified-clean maltodextrins.
- ISO 22000 plus FSSC 22000 dual certification:Pharmaceutical and infant-grade procurement baselines are becoming competitive differentiators for mid-tier processors investing in integrated quality systems.
Industry Challenges
- Microbiome health claim substantiation:Evolving FDA, EFSA, and SAMR evidentiary standards are forcing reformulation cycles before label restrictions crystallize.
- Batch-level traceability infrastructure:Pharmaceutical-grade procurement demands are requiring capital-intensive serialization and blockchain-anchored documentation systems.
- Cross-jurisdictional IP licensing:Enzyme platform patents for resistant starch production are fragmenting technology access across geographic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Carbohydrates Market |
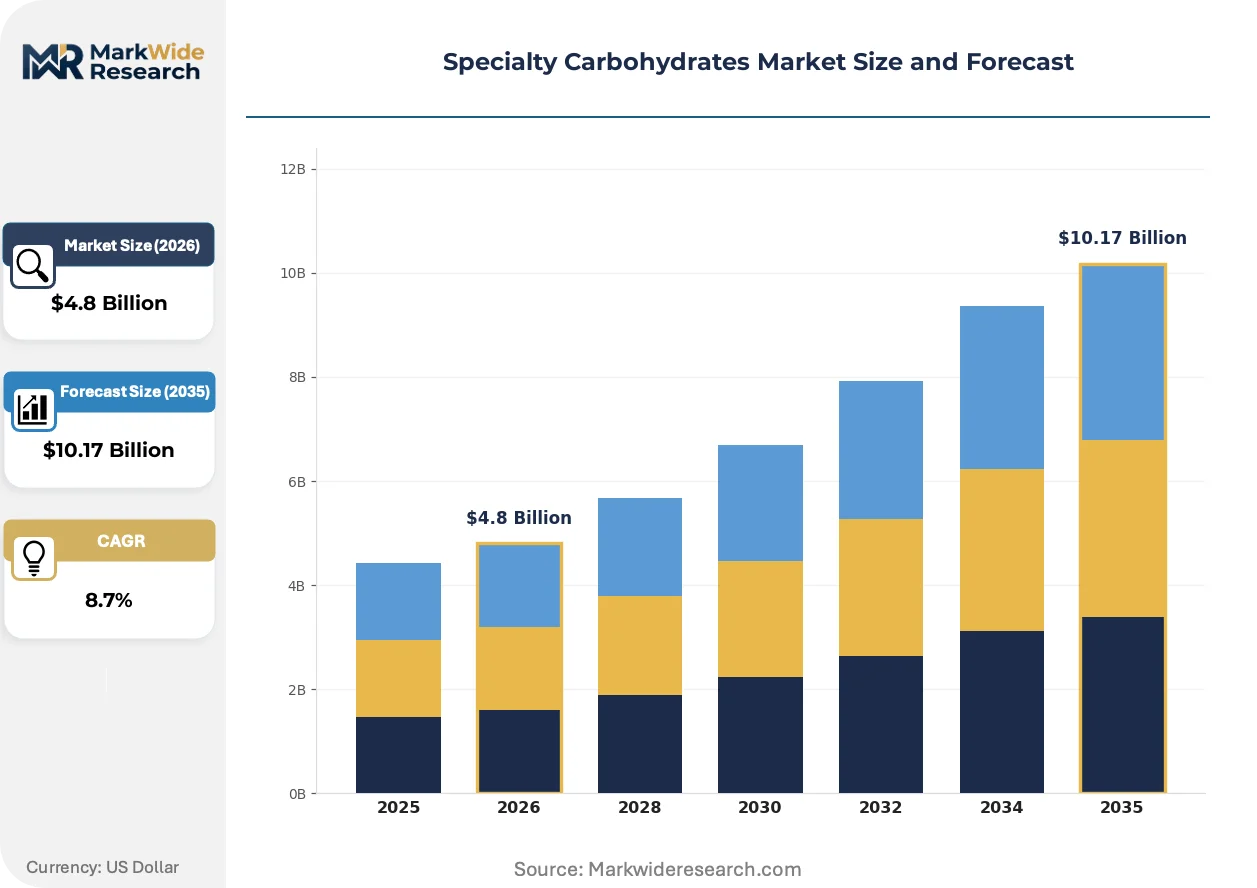
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligosaccharides, Maltodextrin, Dextrins End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Animal Feed Processing Method: Hydrolysis, Fermentation, Precipitation, Spray Drying Form: Powder, Liquid, Granule, Syrup |
| Companies Covered | Tate & Lyle, Südzucker AG, Cargill Incorporated, SunOpta, DuPont, Roquette Frères, Ingredion Incorporated, Grain Processing Corporation, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Carbohydrates Market Strategic Shifts
Continuous bioprocessing technologies are compressing fermentation cycle times for high-purity oligosaccharides while regulatory jurisdictions race to codify microbiome health claim standards. These forces are reshaping competitive positioning around speed-to-approval and manufacturing flexibility rather than scale alone.
Membrane filtration systems with nanofractionation capabilities are enabling selective molecular weight cutoff for prebiotic fiber standardization. Infant formula manufacturers in Germany and the Netherlands are adopting these systems at pilot scale. The technology is miniaturizing downstream purification footprints while preserving bioactive integrity through reduced thermal exposure.
China's SAMR issued draft guidelines for gut-microbiome related health claims in dietary supplements during 2024, creating a compliance template likely to influence ASEAN harmonization efforts. Domestic processors are accelerating clinical trial investments to secure first-mover advantage in substantiation dossiers. Pharmaceutical-grade oligosaccharide exporters targeting China now face expanded stability testing requirements.
Ingredient buyers in sports nutrition and clinical nutrition are consolidating supplier relationships around dual-certified processors capable of pharmaceutical and food-grade production. Traditional commodity distributors are losing share to direct manufacturer relationships. This concentration is most visible in Germany, where enteral feeding formulators are bypassing intermediaries for maltodextrin procurement.
Specialty Carbohydrates Market Segmentation
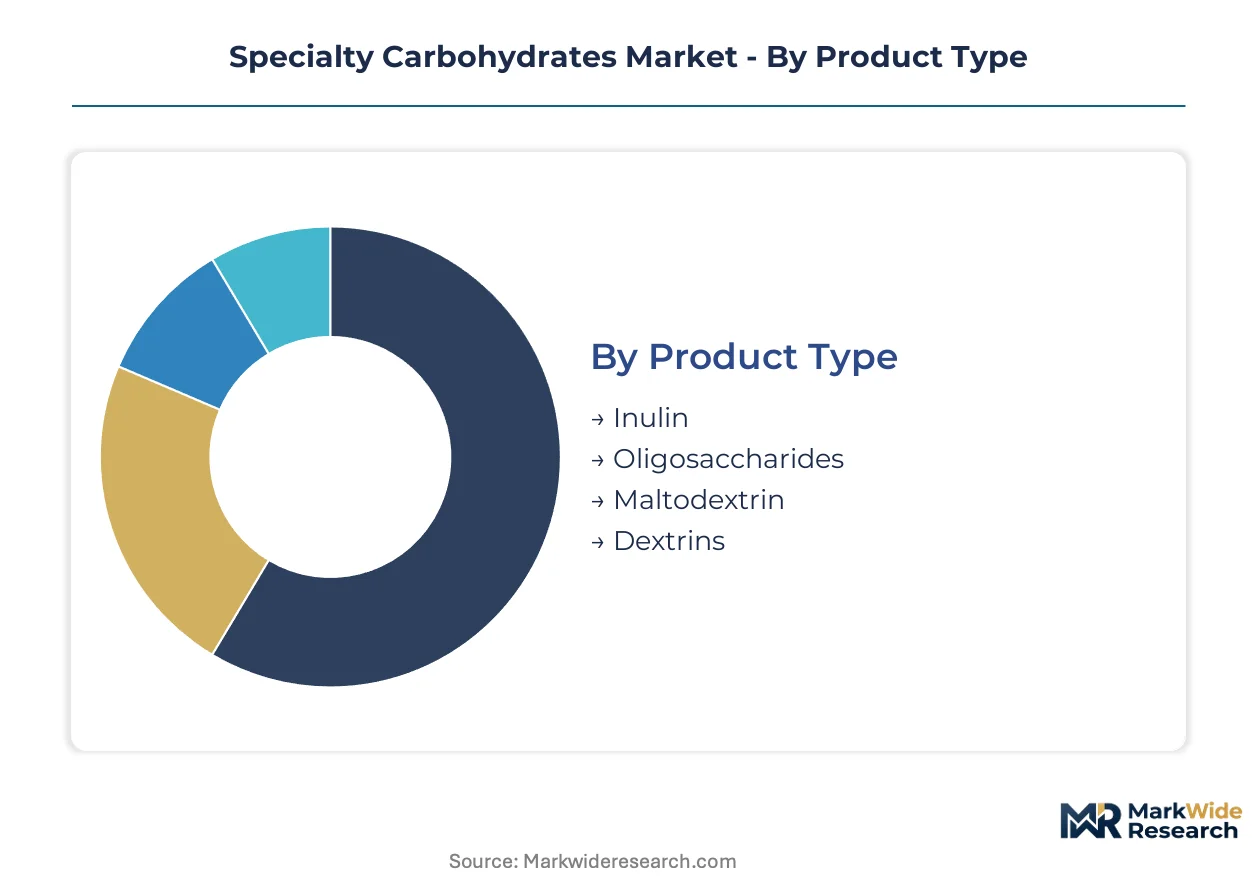
Specialty carbohydrate buyers segment procurement by functional specification rather than commodity grade. Pharmaceutical formulators demand molecular precision that food processors rarely require.
Product Type:
Oligosaccharides face the most acute substitution pressure from resistant starch blends in infant nutrition applications.
- Oligosaccharides:Short-chain saccharides engineered for prebiotic fermentation selectivity. Gut-health positioned infant formula manufacturers in Germany and the Netherlands concentrate procurement here, though EFSA novel food authorization timelines constrain new entrant supply.
- Maltodextrin:Partially hydrolyzed starch polymers with controlled dextrose equivalence. Clinical enteral feeding protocols in US hospital systems standardize rapid gastric emptying formulations, pulling volumes into medical-grade supply chains with batch-level traceability mandates.
- Inulin:Beta-2,1 fructan fiber extracted from chicory root or synthesized from beet sucrose. Südzucker AG anchors European supply through beet-sourced specialization.
- Dextrins:Branched glucose oligomers produced through pyrolysis or enzymatic conversion. Sports nutrition encapsulation applications in direct-to-consumer channels drive specification tightening.
Maltodextrin anchors the volume base while oligosaccharides gain share at the steepest rate.
End Use Industry:
Cost tier stratification separates pharmaceutical-grade premiums from commodity food applications.
- Pharmaceuticals:Active pharmaceutical ingredient carriers and prebiotic excipients with USP-NF monograph compliance. FDA GRAS notifications and NMPA dietary supplement registrations shape market access timelines for exporters targeting multiple jurisdictions.
- Food & Beverage:Clean-label texture modification and reduced-sugar formulation. EU allergen labeling triggers push formulators toward pea-derived alternatives that bypass mandatory declarations.
- Cosmetics:Humectant and film-forming polysaccharides in dermal delivery systems. Stability testing requirements from China's SAMR draft microbiome guidelines are expanding documentation burdens.
- Animal Feed:Prebiotic gut health promoters in livestock and aquaculture. Regulatory divergence between EU feed additive authorizations and US FDA veterinary feed directive compliance fragments formulation strategies.
Food and beverage commands absolute volume while pharmaceuticals expand most quickly.
Processing Method:
Supply concentration in enzymatic hydrolysis creates margin pressure on fermentation-derived alternatives.
- Hydrolysis:Acid or enzyme-catalyzed glycosidic bond cleavage for molecular weight control. Cargill Incorporated leverages corn wet-milling infrastructure across North American heartland facilities to anchor supply security.
- Fermentation:Microbial conversion of simple sugars to complex oligosaccharides. EU F-Gas Regulation emissions thresholds for process gases elevate capital requirements for new capacity.
- Spray Drying:Atomization and thermal dehydration for thermolabile bioactive preservation. Premium positioning depends on nitrogen blanketing and low-temperature inlet configurations.
- Precipitation:Solvent-induced crystallization or selective aggregation for purity enhancement. Solvent recovery economics determine regional cost competitiveness.
Hydrolysis retains volume dominance while fermentation climbs the fastest.
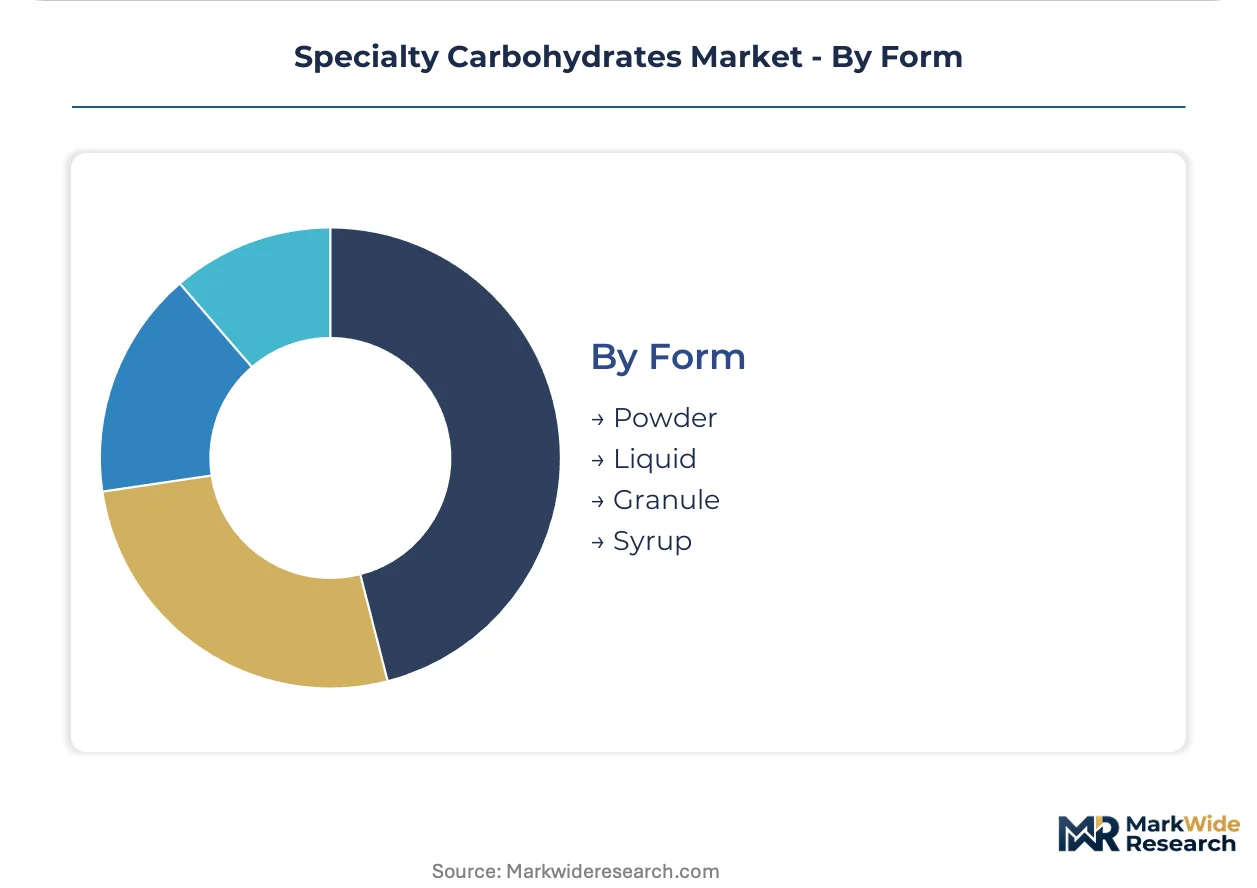
Form:
Customer type bifurcation separates bulk industrial buyers from precision-dose pharmaceutical formulators.
- Powder:Free-flowing particulate with specified particle size distribution and moisture content. Infant formula manufacturers specify tight agglomeration parameters for wet-mix solubility.
- Liquid:Aqueous solutions or suspensions with preserved bioactive stability. Clinical nutrition enteral feeding systems in Germany bypass traditional distributors for direct manufacturer relationships.
- Granule:Agglomerated particles for controlled release or direct compression tableting. Pharmaceutical excipient specifications require dissolution profile validation.
- Syrup:High-solids aqueous preparations for beverage and confectionery applications. Viscosity control through solids concentration determines handling equipment compatibility.
Powder forms anchor the volume base while liquid preparations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heartland processing infrastructure in the United States and concentrated fermentation clusters in Germany anchor supply-side leverage. China's NMPA registration pathways and expanding clinical nutrition demand are redrawing procurement flows. Regulatory divergence between FDA GRAS notifications, EFSA novel food authorizations, and SAMR microbiome guidelines fragments compliance strategies across jurisdictions.
United States
Pharmaceutical-grade maltodextrin procurement from hospital nutrition departments and sports nutrition direct-to-consumer channels drives demand concentration. FDA GRAS notification pathways shape market access timelines for prebiotic fiber entrants. Corn wet-milling infrastructure across Iowa and Illinois processing corridors anchors North American supply security for resistant starch and oligosaccharide outputs.
Germany
Infant formula manufacturers in the Netherlands-Germany corridor concentrate oligosaccharide procurement for gut-health positioned products. EFSA novel food authorizations and F-Gas Regulation emissions thresholds constrain new fermentation capacity expansion. Enteral feeding formulators in North Rhine-Westphalia bypass traditional distributors for direct maltodextrin manufacturer relationships.
China
Domestic processors accelerate clinical trial investments to secure NMPA dietary supplement registrations for gut-microbiome health claims. SAMR draft guidelines issued during 2024 create compliance templates influencing ASEAN harmonization efforts. Yangtze River Delta fermentation clusters scale pharmaceutical-grade oligosaccharide capacity to serve Asia-bound export demand.
Japan
Functional food and cosmetic applications for humectant polysaccharides sustain steady demand from dermal delivery system manufacturers. METI industrial standards and PMDA pharmaceutical regulations govern dual-use ingredient classifications. Kanto region formulators integrate membrane filtration systems for prebiotic fiber standardization at pilot commercial scale.
India
Infant nutrition and clinical enteral feeding applications expand addressable markets for imported specialty carbohydrate grades. FSSAI food safety standards and CDSCO pharmaceutical regulations create parallel compliance frameworks for excipient and active ingredient classifications. Maharashtra-based formulators invest in ISO 22000 certification to access pharmaceutical-grade procurement channels.
Specialty Carbohydrates Market Competitive Environment
Concentration sits with diversified agribusiness conglomerates controlling wet-milling infrastructure and specialized fermentation houses with novel food authorization expertise. Tiered competitive structure separates pharmaceutical-grade purity specialists from commodity food-grade processors. Strategic archetypes include corn wet-milling anchors, beet-sourced inulin specialists, and pea-derived oligosaccharide platform operators. Dominant competitive moves encompass capacity expansion in low-emission fermentation facilities and strategic partnerships for cross-jurisdictional regulatory navigation.
Within the wet-milling anchor tier, Cargill Incorporated exemplifies supply security positioning through heartland infrastructure control. Südzucker AG represents beet-sourced specialization archetype with European regulatory pathway fluency. Roquette Frères occupies the plant-derived alternative protein and carbohydrate convergence space, exemplifying allergen-free positioning strategies for clean-label procurement demands.
| Leading Market Players |
|---|
| Tate & Lyle |
| Südzucker AG |
| Cargill Incorporated |
| SunOpta |
| DuPont |
| Roquette Frères |
| Ingredion Incorporated |
| Grain Processing Corporation |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
FDA GRAS notification pathways and EFSA novel food authorizations simultaneously gate supply qualification and stratify price tiers across pharmaceutical-grade, food-grade, and feed-grade procurement channels. These dual certification requirements force processors to absorb compliance costs upfront while capturing premiums through batch-level traceability and USP-NF monograph alignment.
Pricing Analysis
EFSA novel food authorizations dictate the pricing tier structure across European markets, separating infant-nutrition-grade oligosaccharides from commodity maltodextrins through substantiation dossier investments. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade levels reflects purity benchmarks and documentation depth. Cost compression in standard-grade maltodextrins is intensifying because hospital nutrition departments consolidate direct manufacturer relationships. Sports nutrition direct-to-consumer channels exhibit the highest price sensitivity, while pharmaceutical excipient buyers prioritize supply security over unit cost.
Supply Chain Analysis
Strategic stockpiling of corn and pea protein feedstocks dominates inventory strategy among North American wet-milling operators facing climate-driven yield volatility. Supply concentrates in the United States, Germany, and China, with heartland processing corridors in Iowa and Illinois anchoring resistant starch output. Raw material dependencies center on corn, chicory root, and pea protein isolates. Single-source vulnerability runs through concentrated fermentation clusters in the Yangtze River Delta. Distribution runs through direct manufacturer relationships in pharmaceutical and infant nutrition segments, bypassing traditional commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing technologies and evolving microbiome health claim standards are disrupting incumbent scale advantages, creating first-mover windows for substantiation-ready entrants. Regulatory jurisdictions are racing to codify evidentiary thresholds faster than manufacturing flexibility can adapt.
For Market Incumbents: Consolidate around low-emission fermentation capacity in EU markets ahead of F-Gas Regulation enforcement thresholds. Secure backward integration into pea protein supply chains to defend against allergen-free positioning by specialized fermentation houses. Anchor pharmaceutical-grade relationships through dual ISO 22000 and FSSC 22000 certification investments that mid-tier processors cannot replicate. For New Entrants and Emerging Players: Differentiate on China NMPA dietary supplement registration readiness, where domestic clinical trial investments have created temporary capability gaps for Asia-bound exporters. Target sports nutrition direct-to-consumer channels in Germany and the United States, where e-commerce platforms compress distributor margins and enable premium positioning for certified-clean maltodextrins. Pursue membrane filtration technology partnerships with infant formula manufacturers seeking wet-mix solubility specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-derived oligosaccharide segments as EU emissions compliance and spray-drying nitrogen blanketing requirements escalate facility costs. Five-to-ten-year viability favors processors with existing novel food authorization expertise and integrated quality systems. Acquisition targets should demonstrate SAMR microbiome guideline alignment and pilot-scale membrane filtration deployment. The signal to watch is batch-level traceability infrastructure adoption rates among pharmaceutical formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Emission Fermentation Capacity Expansion | EU F-Gas Regulation compliance secures operating licenses for German and Dutch processing clusters. |
| Pea-Derived Oligosaccharide Platform Development | Allergen-free positioning bypasses mandatory EU declaration requirements for clean-label procurement. |
| China NMPA Registration Investment | SAMR microbiome substantiation standards create first-mover advantage in Asia-bound export channels. |
| Membrane Filtration System Integration | Nanofractionation capabilities preserve bioactive integrity for infant formula manufacturers in the Netherlands. |
| Direct Manufacturer Relationship Cultivation | Bypassing commodity distributors captures margin compression in sports nutrition e-commerce channels. |
Study Parameters
The analysis maps oligosaccharide, maltodextrin, inulin, and dextrin sub-sectors, each validated through interviews with pharmaceutical formulators, infant nutrition procurement leads, fermentation plant managers, and sports nutrition brand managers. Primary fieldwork combined with secondary validation from FDA GRAS notifications, EFSA novel food authorization databases, NMPA dietary supplement registries, and FSSC 22000 certification records. Bottom-up capacity assessments and top-down demand triangulation anchored volume and value estimates.
Outputs were validated against external benchmarks including customs trade flows, corn wet-milling capacity utilization reports, and hospital nutrition procurement database trends. The forecast framework spans product type, processing method, end-use industry, and geographic regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers and input cost trajectories. Microbiome health claim substantiation timelines and continuous bioprocessing adoption curves informed scenario weightings.
Decision-makers should treat outputs as directional under stable regulatory authorization timelines and intact corn supply chains; material deviation in EFSA or SAMR evidentiary standards would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Customized Nutrient Premixes Market