
 South Africa Real Time Payments Market | 2026-2036
South Africa Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Real Time Payments Market Analytics
Merchant settlement fee revenue is reconfiguring toward instant-clearing value propositions as interchange economics shift. BankservAfrica leverages its national switch infrastructure to sustain real-time clearing dominance across interbank rails. Peach Payments anchors its position through API-first integration for e-commerce platforms. Ozow (Pty) Ltd. specializes in account-to-account instant transfers that bypass traditional card networks.
Real time payments denote funds transfer systems where transaction processing, clearing, and settlement occur within seconds rather than days, operating on ISO 20022 messaging standards with 24/7 availability. These systems eliminate settlement risk for merchants while reducing liquidity requirements for financial institutions. Mobile payments and QR code payments within the payment method dimension command the dominant transaction volume, reflecting South Africa's high mobile penetration and informal merchant density. Open banking and API integration within the technology dimension represent the fastest structural expansion, enabling third-party fintech access to core banking infrastructure. Cloud computing deployments among service providers concentrate margin pools through operational scale rather than capital-intensive on-premise systems.
The South African Reserve Bank governs systemic payment infrastructure through the National Payment System Act, mandating interoperability standards that shape market access for new entrants. The Financial Sector Conduct Authority and Payment Association of South Africa enforce consumer protection and participant conduct rules that directly determine product design requirements. The Information Regulator applies POPIA compliance obligations to transaction data flows, constraining cloud architecture choices for providers. Stakeholders must monitor how the South African Reserve Bank's retail fast payment program evolves against open banking licensing timelines to calibrate platform investment priorities.
Market Dynamics
The South African Reserve Bank's retail fast payment program is compressing settlement windows from T+2 to real-time, forcing incumbent processors to rebuild core infrastructure around ISO 20022 messaging standards.
Growth Catalysts
- SARB Instant Settlement Mandate:The central bank's directive for 24/7 clearing availability eliminates batch-processing bottlenecks and unlocks liquidity for smaller financial institutions.
- Small Business Digital Migration:Informal merchants in Gauteng and Western Cape provinces are abandoning cash handling for QR-code acceptance rails, expanding addressable transaction volume.
- Mobile Penetration Infrastructure:Smartphone density above 90% enables USSD and app-based payment initiation without dedicated POS hardware.
Market Restraints
- Interbank Switch Concentration:BankservAfrica's dominance over national clearing infrastructure creates single-point-of-failure risk for new entrants seeking direct participation.
- POPIA Compliance Architecture:The Information Regulator's data localization requirements impose cloud deployment constraints that inflate operational expenditure for foreign-hosted platforms.
- Cash Handling Cost Parity:Persistent informal banking habits in rural Eastern Cape and Limpopo provinces sustain paper-based alternatives that undercut digital fee structures.
Strategic Opportunities
- Open Banking Licensing Timeline:The South African Reserve Bank's phased API access framework creates entry paths for fintech account-to-account providers previously excluded from core banking systems.
- Cross-Border SADC Integration:Underpenetrated corridors into Botswana, Namibia, and Eswatini offer white-space for instant remittance products bypassing correspondent banking delays.
- Merchant Acquiring Consolidation:Fragmented ISO networks in secondary cities present acquisition targets for platforms with unified API stacks.
Industry Challenges
- ISO 20022 Talent Scarcity:Domestic engineering pools lack depth in message schema implementation, forcing reliance on expensive international contractors.
- Legacy Core Banking Integration:Tier-2 and Tier-3 banks operate on decades-old mainframe architectures that resist real-time API connectivity without multimillion-rand overhaul programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Real Time Payments Market |
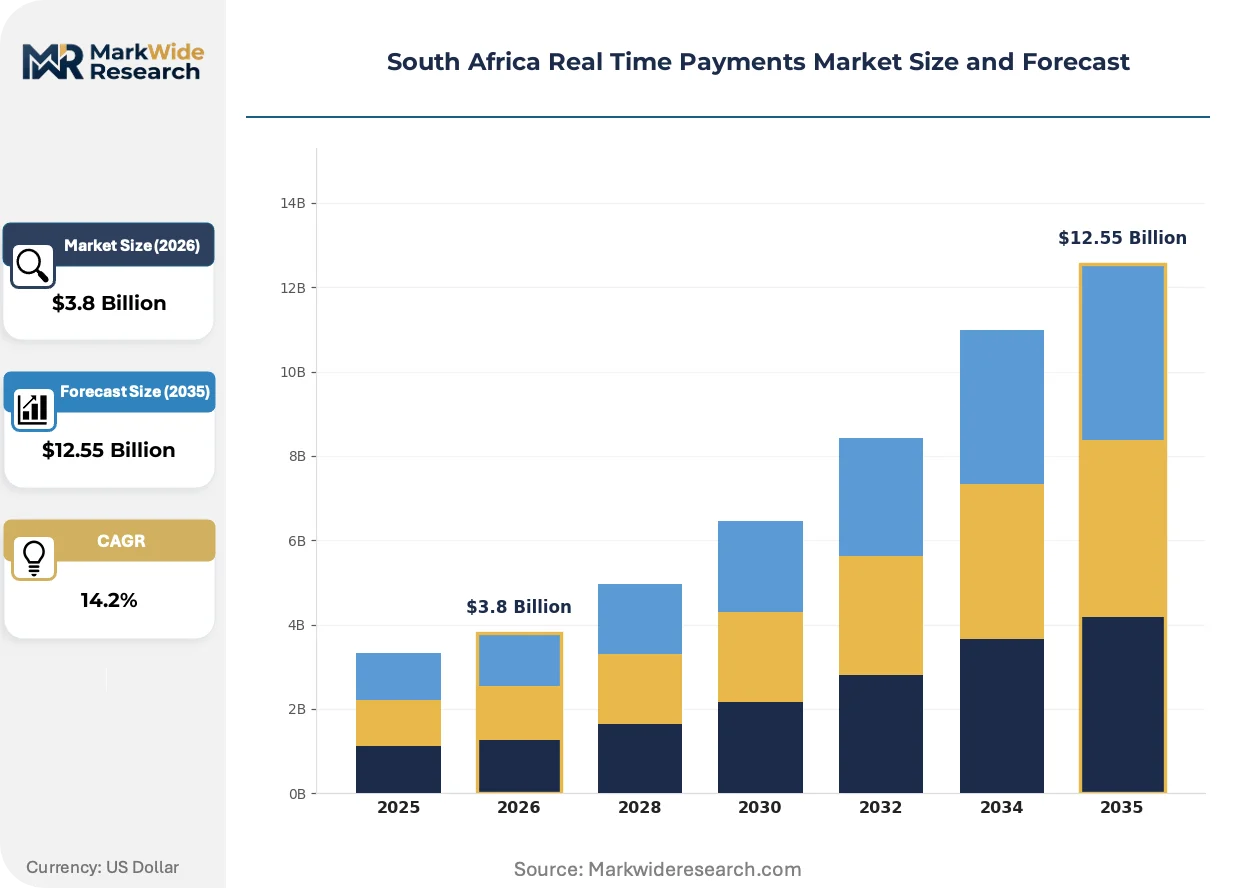
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Mobile Payments, Instant Transfers, Digital Wallets, QR Code Payments User Type: Consumers, Small Businesses, Corporations, Government Entities Technology: Blockchain, Open Banking, API Integration, Cloud Computing Service Provider: Payment Processors, Banks, Fintech Companies, Telecom Operators |
| Companies Covered | BankservAfrica, Peach Payments, PayU South Africa, Ozow (Pty) Ltd., iVeri Payment Technologies, Fiserv Inc., Electrum Payments, PayFast (DPO Group), Yoco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Real Time Payments Market Evolving Landscape
Payment orchestration is fragmenting as specialized providers unbundle functions previously monopolized by retail banks, with API-first architectures enabling direct merchant-processor relationships.
Cloud-native transaction processing is migrating from on-premise data centers to distributed African cloud regions, reducing latency for Johannesburg and Cape Town merchants. Mid-sized payment service providers are adopting containerized deployments to bypass capital-intensive hardware refresh cycles. This shift is compressing time-to-market for new payment products from quarters to weeks.
The South African Reserve Bank's National Payment System Act amendments are mandating tiered participation fees that favor high-volume processors. Smaller fintech entrants face escalating compliance costs that threaten standalone viability. The regulatory friction is driving consolidation among account-to-account specialists seeking scale economies.
Merchant procurement of payment acceptance is fragmenting from bundled bank relationships toward unbundled best-of-breed selections. E-commerce platforms now integrate multiple instant payment rails alongside traditional card acquiring. Gauteng-based online retailers are piloting this multi-rail approach to optimize authorization speed and failure-rate performance.
South Africa Real Time Payments Market Segmentation
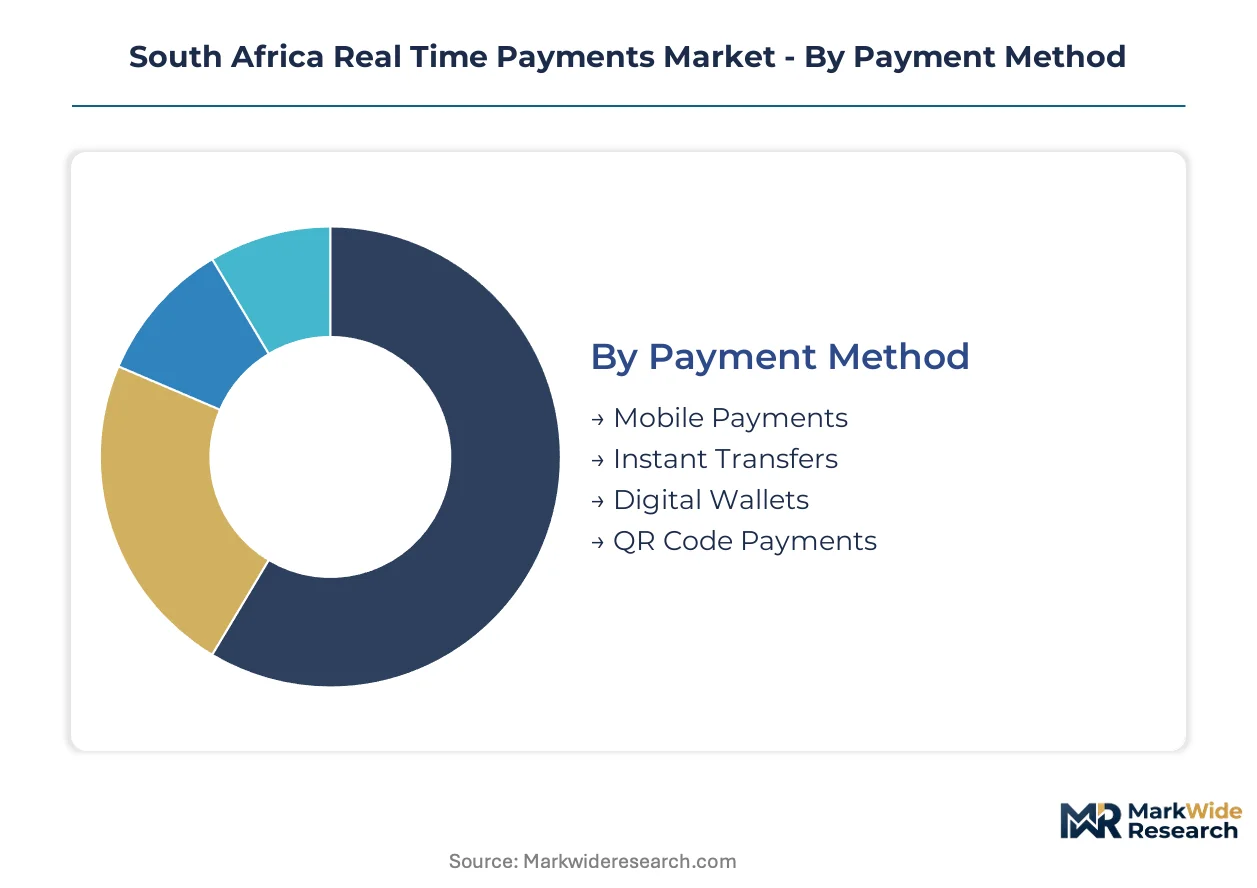
Segmentation in South Africa's real-time payments market reveals how infrastructure investments, regulatory mandates, and merchant adoption patterns concentrate value across distinct rails. Each dimension exposes divergent growth trajectories and margin structures that shape provider strategy.
Payment Method:
After-sales service intensity varies sharply across payment rails, with QR-code and mobile-first platforms demanding continuous merchant onboarding support while instant transfers require minimal ongoing intervention.
- Mobile Payments:USSD and smartphone-app initiation dominate transaction volume in Gauteng and Western Cape townships where POS hardware penetration remains low. Small merchants in informal trade corridors drive adoption as cash-handling costs escalate.
- Instant Transfers:Account-to-account rails bypass card networks entirely, settling through BankservAfrica's real-time clearing. Demand concentrates among e-commerce platforms seeking reduced interchange exposure and faster merchant liquidity.
- Digital Wallets:Stored-value instruments linked to mobile network operators.
- QR Code Payments:Static and dynamic codes enabling smartphone-to-smartphone settlement.
Mobile payments holds the largest share; momentum sits with instant transfers.
User Type:
Cost tier segmentation separates high-volume corporate treasuries with dedicated integration teams from small businesses reliant on off-the-shelf solutions.
- Consumers:Individual users initiating peer-to-peer transfers and retail purchases.
- Small Businesses:Informal merchants and township traders migrating from cash to digital acceptance. Gauteng-based spaza shops and Western Cape street vendors represent the fastest-expanding addressable base as SARB instant settlement mandates reduce clearing friction.
- Corporations:Large enterprises with complex treasury operations and multi-bank relationships. Supply chain payment automation in Johannesburg's manufacturing and logistics clusters drives demand for API-integrated real-time disbursement.
- Government Entities:Municipal and provincial agencies distributing social grants and procurement payments.
Small businesses command transaction volume growth; corporations anchor revenue per transaction.
Technology:
Application architecture determines which providers capture margin pools, with cloud-native stacks displacing on-premise deployments among mid-tier processors.
- Blockchain:Distributed ledger pilots for cross-border SADC corridors remain experimental. Regulatory uncertainty from the South African Reserve Bank constrains production deployment despite technical viability for remittance settlement.
- Open Banking:API frameworks enabling third-party access to core banking infrastructure. The SARB's phased licensing timeline is accelerating fintech account-to-account product development ahead of formal authorization deadlines.
- API Integration:REST and SOAP connectivity for merchant platform embedding.
- Cloud Computing:Containerized transaction processing reducing latency for Johannesburg and Cape Town merchants.
Open banking represents the steepest expansion trajectory; cloud computing underpins operational scale.
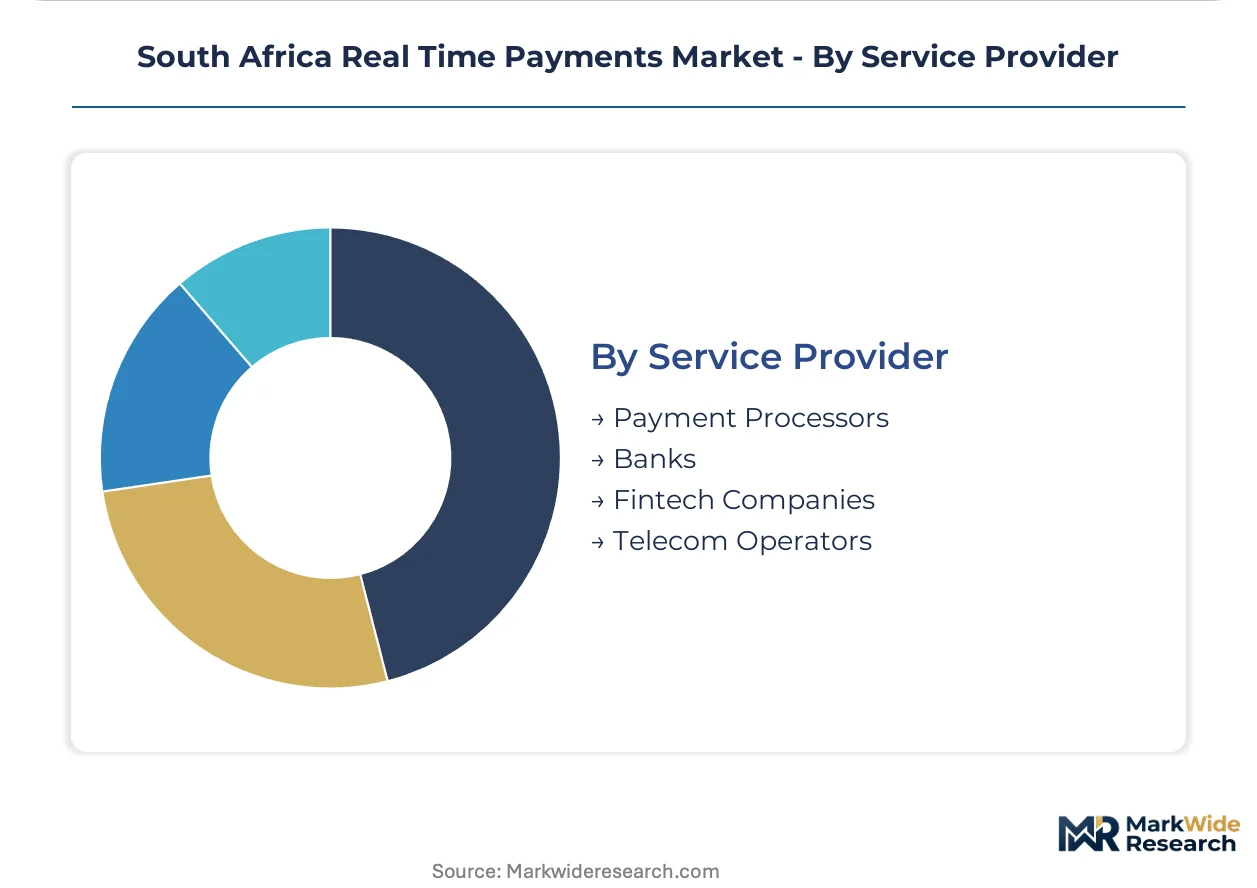
Service Provider:
Supply concentration among national switch operators creates asymmetric margin capture, with direct clearing participants extracting premium economics over indirect aggregators.
- Payment Processors:Technical intermediaries routing transactions through national switches. Specialist providers in secondary cities face consolidation pressure as tiered participation fees under National Payment System Act amendments escalate compliance burdens.
- Banks:Licensed deposit-taking institutions with direct clearing access. Tier-2 and Tier-3 institutions struggle with legacy mainframe integration costs that resist real-time API connectivity without multimillion-rand overhaul programs.
- Fintech Companies:Unlicensed technology providers leveraging bank partnerships.
- Telecom Operators:Mobile network operators with USSD infrastructure and subscriber bases.
Banks retain clearing dominance; fintech companies are gaining share fastest through unbundled service delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng and Western Cape provinces deploy real-time payments for informal merchant settlement, while Eastern Cape and Limpopo retain cash-dominant corridors due to infrastructure gaps and banking access limitations.
Gauteng
Johannesburg's township spaza shops and Pretoria's logistics hubs drive QR-code adoption for instant settlement. The South African Reserve Bank's retail fast payment program mandates 24/7 clearing availability that eliminates batch-processing delays for small merchants. Sandton's fintech cluster hosts API-first payment orchestrators rebuilding merchant acquiring around ISO 20022 standards.
Western Cape
Cape Town's e-commerce platforms and Stellenbosch wine route merchants accelerate account-to-account instant transfers to bypass card interchange fees. The Payment Association of South Africa enforces interoperability standards that shape product design for new entrants. The Cape Town CBD hosts cloud-native processors deploying containerized architectures to compress product launch timelines.
KwaZulu-Natal
Durban's port logistics operators and Pietermaritzburg manufacturing clusters demand real-time disbursement for supply chain automation. The Information Regulator's POPIA compliance obligations constrain cloud architecture choices for transaction data flows. The Dube TradePort special economic zone attracts payment processors seeking reduced latency through distributed African cloud regions.
Eastern Cape
Rural municipalities and informal trade corridors sustain cash-handling habits that undercut digital fee structures despite mobile penetration above 90%. The South African Reserve Bank's National Payment System Act amendments impose tiered participation fees that threaten standalone viability for smaller fintech entrants. Port Elizabeth's automotive manufacturing belt generates corporate treasury demand for API-integrated real-time payment rails.
Limpopo
Polokwane's agricultural supply chains and Bushbuckridge's grant distribution points remain underpenetrated by instant settlement infrastructure. The Financial Sector Conduct Authority's consumer protection rules determine product design requirements for rural market entry. The Musina border corridor with Zimbabwe presents white-space for cross-border instant remittance products bypassing correspondent banking delays.
South Africa Real Time Payments Market Competitive Landscape
Capability concentration sits with national switch operators holding direct clearing access; scale advantage sits with API-first fintechs unbundling merchant acquiring from traditional banking relationships. BankservAfrica anchors infrastructure dominance through its position as the national switch operator, while specialist processors fragment across secondary cities facing consolidation pressure. Three archetypes define competitive positioning: switch-backed incumbents with clearing privileges, API-native fintechs embedding into e-commerce platforms, and telecom-linked wallet providers leveraging USSD infrastructure. M&A activity targets fragmented ISO networks in secondary cities, while strategic partnerships between fintechs and Tier-2 banks accelerate core banking modernization.
Within the switch-backed tier, BankservAfrica exemplifies infrastructure-centric positioning through its control of national real-time clearing rails. Among API-first specialists, Peach Payments and Ozow (Pty) Ltd. occupy positions representing the unbundling of merchant acquiring from traditional banking relationships, with Peach Payments anchoring e-commerce platform integration and Ozow (Pty) Ltd. exemplifying account-to-account transfer specialization that bypasses card networks entirely.
| Leading Market Players |
|---|
| BankservAfrica |
| Peach Payments |
| PayU South Africa |
| Ozow (Pty) Ltd. |
| iVeri Payment Technologies |
| Fiserv Inc. |
| Electrum Payments |
| PayFast (DPO Group) |
| Yoco |
| Others |
Value Network & Pricing Analysis
Underutilized cloud capacity in Johannesburg and Cape Town data centers is forcing payment processors to compete aggressively on transaction fees while simultaneously driving infrastructure consolidation among regional hosting providers.
Pricing Analysis
Contract structures in South Africa's real-time payments market favor per-transaction SaaS tiers over long-term offtake commitments, with merchants selecting between volume-scaled interchange models and flat-rate subscription bundles. Price differentiation hinges on ISO 20022 certification tier and geographic latency optimization for Gauteng versus Western Cape corridors. Pricing pressure intensifies as Ozow and Peach Payments compress margins on account-to-account rails. Small businesses in informal trade corridors exhibit highest price sensitivity; corporate treasuries in Sandton prioritize authorization speed over cost.
Supply Chain Analysis
Export-control regimes on advanced semiconductor components constrain supply flows from Taiwan and South Korea into South African payment hardware manufacturing. Cloud infrastructure draws from hyperscaler regions in Ireland, Germany, and emerging Johannesburg nodes. Supply chain risk centers on single-source vulnerability for BankservAfrica's national switch monopoly. Distribution runs through API-first platform integrations and direct merchant-processor relationships, bypassing traditional banking intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from account-to-account instant transfer rails that bypass card networks entirely, as SARB's open banking licensing timeline accelerates fintech access to core infrastructure.
For Market Incumbents: Harden clearing dominance by securing direct participation status under National Payment System Act amendments before tiered fees escalate. Acquire fragmented ISO networks in secondary cities to consolidate merchant acquiring scale. ISO 20022 talent scarcity in domestic engineering pools presents the critical vulnerability; vertical integration into specialized training partnerships mitigates contractor dependency. For New Entrants and Emerging Players: Build out API-first orchestration layers targeting e-commerce platforms in Cape Town's Stellenbosch wine route and Durban's port logistics clusters. The Eastern Cape and Limpopo cash-dominant corridors offer underpenetrated white-space for QR-code merchant onboarding. Go-to-market leverage rests on partnerships with Tier-2 banks seeking core banking modernization without multimillion-rand mainframe overhaul programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native payment processors as containerized deployments displace on-premise hardware refresh cycles. Long-term viability favors platforms with direct BankservAfrica switch access and ISO 20022 implementation depth. Acquisition targets should display unified API stacks with proven merchant onboarding velocity. The signal to watch is SARB retail fast payment program authorization timelines against open banking license issuance rates.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Infrastructure Migration | SARB mandates eliminate batch-processing bottlenecks and unlock 24/7 clearing availability for smaller institutions. |
| API-First Platform Integration | Direct merchant-processor relationships bypass traditional banking intermediaries and compress product launch timelines. |
| Cloud-Native Architecture Deployment | Containerized processing reduces latency for Johannesburg and Cape Town merchants while avoiding capital-intensive hardware cycles. |
| Cross-Border SADC Corridor Development | Instant remittance products into Botswana, Namibia, and Eswatini bypass correspondent banking delays and capture white-space volume. |
| Tier-2 Bank Core Modernization Partnership | Legacy mainframe integration programs accelerate real-time API connectivity without standalone multimillion-rand overhaul investments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SARB payment system directives, POPIA compliance frameworks, and BankservAfrica infrastructure disclosures. Primary interviews engaged payment platform CTOs, merchant acquiring heads at Tier-2 banks, fintech product directors, and Payment Association of South Africa regulatory leads. Secondary validation drew from National Payment System Act amendments, Information Regulator guidance documents, and regional cloud provider capex announcements. Bottom-up transaction volume modeling triangulated against top-down addressable merchant base estimates.
Forecast inputs incorporate payment method adoption curves, technology deployment timelines, and provincial merchant density differentials across the analysis window. Segmentation dimensions modeled include payment method type, user archetype, application architecture, and service provider category. CAGRs derived from trend extrapolation against SARB regulatory milestone schedules and mobile penetration saturation patterns. Industry-specific inputs include ISO 20022 implementation velocity and open banking license issuance trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by account-to-account specialists or hyperscaler cloud entrants would shift outcomes. Material shifts in SARB instant settlement mandates, POPIA data localization requirements, or cross-border SADC regulatory harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
North America Payments Market
Payments
United States Payments Market
Payments
Hungary POS Terminal Market
Payments
Saudi Arabia Mobile Payments Market
Payments
Germany POS Terminal Market
Payments
US Buy Now Pay Later Services Market
Payments
North America POS Terminal Market
Payments
Online Charging System (OCS) Market
Payments
Digital Transfer Services Market
Payments
Direct Carrier Billing Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Biometric Payment Market
Payments
France Payments Market
Payments
Voice-Based Payments Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
UK Virtual Cards Market