
 Middle East & North Africa Digital Payments Market | 2026-2036
Middle East & North Africa Digital Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & North Africa Digital Payments Market Insights
Software-defined acquiring services is restructuring how payment revenue gets captured across the Middle East & North Africa. Network International leverages its multi-country processor licenses to dominate merchant acquiring in Egypt and the UAE. Payfort anchors online payment gateway services for regional e-commerce platforms. STC Pay competes through its mobile wallet super-app strategy tied to Saudi Arabia's national digital transformation agenda.
Digital payments encompass electronic fund transfers executed through card networks, mobile applications, and real-time clearing systems, typically settling within seconds to two business days depending on rail type and regulatory jurisdiction. The primary commercial purpose is to displace cash handling costs while enabling transaction traceability for tax compliance and anti-money-laundering monitoring. Mobile wallet adoption is outpacing card growth across the Middle East & North Africa as underbanked populations skip traditional banking infrastructure. QR code acceptance is expanding fastest among small merchants due to minimal hardware requirements and lower merchant discount rates. Payment gateway services capture concentrated margin pools as e-commerce platforms demand integrated fraud management and multi-currency settlement.
SAMR in Saudi Arabia and the UAE's central bank fintech licensing framework are tightening capital reserve and data localization requirements for non-bank payment providers. Egypt's central bank mandates interoperability standards between mobile wallets and traditional banking channels, reshaping product architecture decisions for platform operators. Stakeholders must monitor how Gulf Cooperation Council monetary coordination on cross-border real-time settlement affects national licensing strategies and partnership structures.
Market Dynamics
Real-time payment infrastructure deployment across Saudi Arabia and the UAE is compressing settlement windows from days to seconds, forcing merchant acquirers and wallet operators to rearchitect core systems around instant clearing rails rather than batch processing.
Growth Catalysts
- QR Code Merchant Acceptance:Egypt's central bank interoperability mandates are binding mobile wallets to traditional banking channels, expanding formal payment acceptance among micro-merchants previously excluded from card networks.
- Contactless Checkout Integration:E-commerce platforms across the Gulf Cooperation Council are embedding one-click payment flows, reducing cart abandonment and accelerating online transaction velocity.
- SAMR Licensing Framework:Saudi Arabia's tightened capital reserve requirements for non-bank payment providers are filtering out undercapitalized competitors and consolidating market access around licensed operators.
Market Restraints
- Data Localization Costs:UAE central bank mandates requiring domestic server infrastructure for fintech operators are elevating fixed costs for cross-border payment providers entering the market.
- Cash Handling Infrastructure:Remittance corridors serving Egyptian and Moroccan labor populations maintain deep cash-out network dependencies that resist digitization due to recipient preference and last-mile banking gaps.
- Interoperability Technical Debt:Fragmented wallet standards across Jordan, Lebanon, and North African markets force providers to maintain multiple API integrations, elevating engineering overhead.
Strategic Opportunities
- Underpenetrated Iraqi Market:Baghdad and Basra merchant corridors lack integrated payment acceptance infrastructure, creating first-mover advantage for acquirers willing to deploy QR and soft-POS solutions.
- Cross-Border GCC Settlement:Gulf Cooperation Council monetary coordination on real-time cross-border rails will enable wallet operators to offer seamless remittance and merchant payments across member states.
- Biometric Authentication Convergence:Facial recognition and voiceprint verification layered atop mobile wallets is reducing fraud rates and enabling higher-value transaction limits for underbanked users.
Industry Challenges
- Compliance Talent Scarcity:AML and sanctions-screening expertise specific to Middle East correspondent banking relationships commands premium compensation, constraining provider scaling.
- Legacy Core Banking Integration:Tier-2 banks in Morocco and Tunisia operate on decades-old mainframe architectures that resist real-time API connectivity, delaying wallet-to-account interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & North Africa Digital Payments Market |
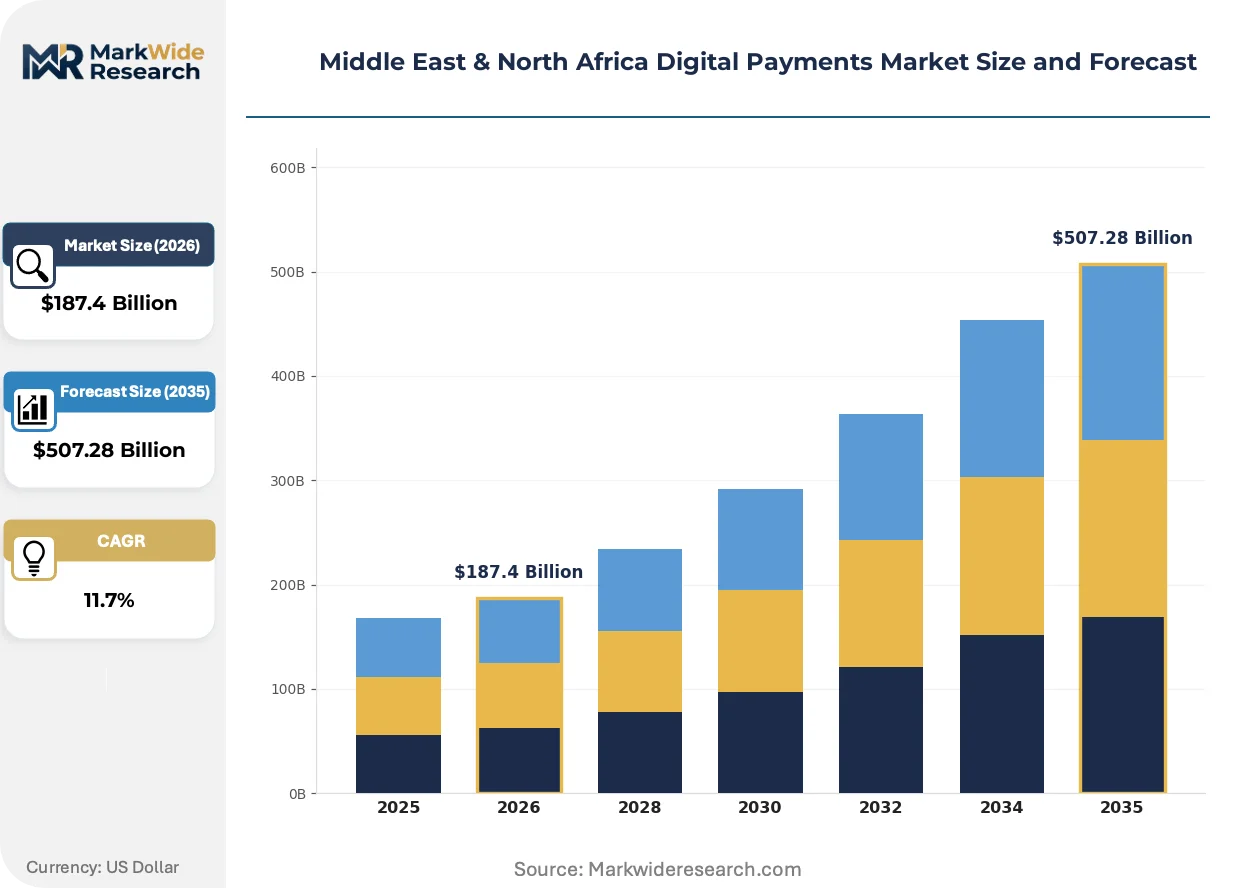
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Card, Debit Card, Mobile Wallet, Bank Transfer End User: Retail, E-Commerce, Hospitality, Travel Technology: Contactless, NFC, QR Code, Blockchain Service Provider: Payment Gateway, Processor, Acquirer, Others |
| Companies Covered | Network International, Payfort, HyperPay, Tap Payments, Fawry, STC Pay, Visa, Mastercard, PayPal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & North Africa Digital Payments Market Trends and Innovations
Artificial intelligence is embedding fraud detection and personalized financial services directly into payment flows, compressing the traditional separation between transaction processing and value-added banking.
Machine learning risk scoring is automating real-time transaction monitoring for merchant acquirers across Saudi Arabia and the UAE. Large e-commerce platforms and digital marketplaces are adopting these systems fastest, replacing rules-based fraud filters that generated excessive false declines. The technology is automating compliance cost structures that previously required manual analyst review of flagged transactions.
SAMR's operational risk management guidelines and the UAE central bank's stored value facility regulations are tightening governance requirements for payment service providers. These frameworks mandate segregated customer fund protection and operational resilience testing that elevates barriers to market entry. Fintech operators in both jurisdictions are responding by deepening partnerships with licensed banks rather than pursuing standalone licenses.
Small merchants are consolidating payment relationships around super-app ecosystems that bundle acceptance, working capital, and customer analytics. Traditional standalone point-of-sale terminal distributors are losing ground to mobile-first acquirers offering software-defined checkout experiences. This pattern concentrates most visibly among Dubai and Riyadh retail corridors where merchant churn between providers has accelerated.
Middle East & North Africa Digital Payments Market Segmentation
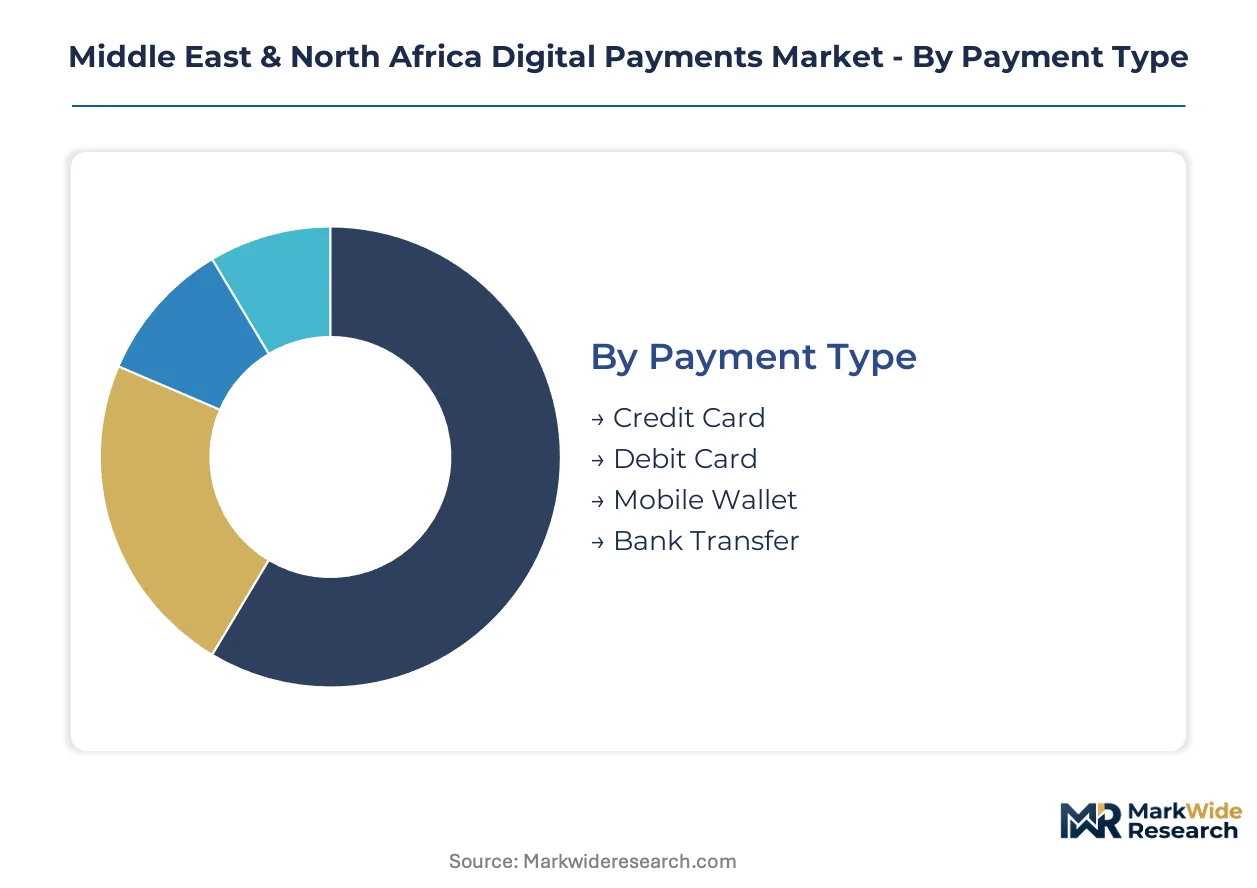
Payment infrastructure across the Middle East & North Africa fragments across rails, user contexts, and service layers. Each segmentation axis reveals distinct competitive dynamics and capital deployment priorities for providers building regional scale.
Payment Type:
Technology specifications determine settlement velocity and merchant acceptance economics across Saudi Arabia, the UAE, and Egypt.
- Credit Card:Revolving credit products tied to international schemes dominate high-value hospitality and travel corridors in Dubai and Riyadh. Issuers compete on loyalty programs and installment conversion features as interchange compression pressures margins.
- Debit Card:Direct-account-linked instruments anchor payroll disbursement and government benefit distribution across Egypt and Morocco. Central bank mandates for salary digitization are accelerating issuance velocity.
- Mobile Wallet:Smartphone-based stored value systems are gaining share fastest among underbanked populations in Iraq and Jordan.
- Bank Transfer:Account-to-account rails serve B2B settlement and high-value real estate transactions with lower fraud exposure than card networks.
Mature deployment sits with Credit Card. Newer deployment is concentrated in Mobile Wallet.
End User:
Customer context shapes fraud tolerance, checkout friction requirements, and integration complexity for payment providers.
- Retail:Physical merchant acceptance spans hypermarkets in Riyadh to informal souks in Cairo. QR code and soft-POS solutions are displacing traditional terminals due to lower hardware costs and faster onboarding.
- E-Commerce:Online marketplaces demand one-click checkout flows and multi-currency settlement across Gulf Cooperation Council corridors. Gateway providers capture premium margins for integrated fraud management and local payment method aggregation.
- Hospitality:Hotels and restaurants in Dubai and Jeddah prioritize contactless guest experiences and pre-authorization capabilities.
- Travel:Airlines and booking platforms require cross-border settlement and dynamic currency conversion for inbound tourism from Europe and Asia.
Volume concentration favors Retail. Margin expansion is steepest in E-Commerce.
Technology:
Interface specifications determine hardware requirements, merchant training burden, and interoperability complexity across fragmented national standards.
- Contactless:Tap-to-pay card and device interfaces dominate urban retail in the UAE and Saudi Arabia. Terminal upgrade cycles accelerated during pandemic-era hygiene concerns and remain embedded in merchant expectations.
- NFC:Near-field communication enables peer-to-peer transfers and transit fare collection. Deployment concentrates in Riyadh and Dubai metro systems with government-backed standardization.
- QR Code:Visual scan-to-pay systems are expanding most quickly among Egyptian micro-merchants due to zero hardware requirements and central bank interoperability mandates.
- Blockchain:Distributed ledger settlement remains experimental for cross-border remittance corridors serving South Asian labor populations in the Gulf.
Regulatory clarity favors Contactless. Technical innovation concentrates in QR Code.
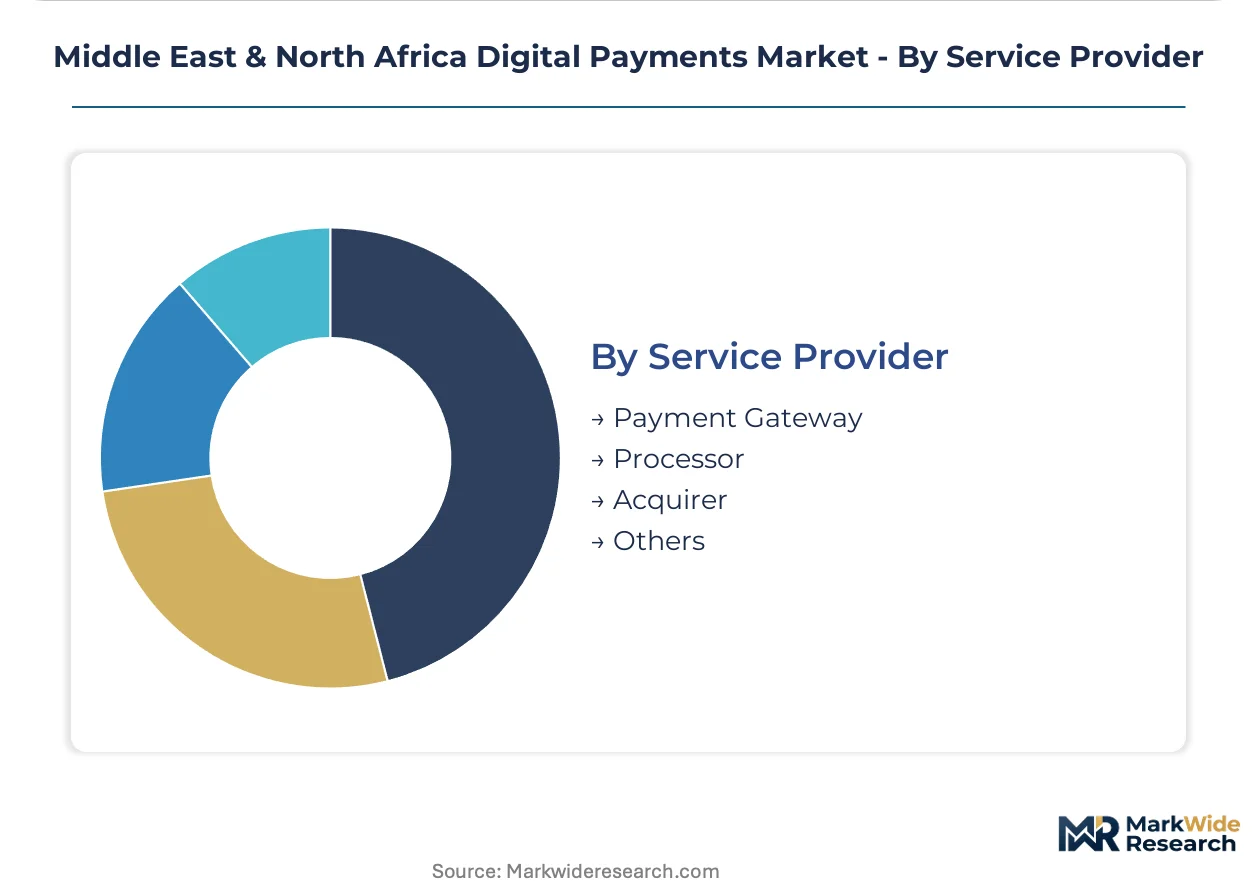
Service Provider:
Value chain position determines capital intensity, regulatory licensing requirements, and customer ownership depth.
- Payment Gateway:E-commerce front-end integration specialists capture recurring SaaS revenue from merchant platforms. Product differentiation centers on fraud scoring sophistication and local payment method coverage.
- Processor:Transaction routing and authorization infrastructure operators serve acquirers and issuers across multiple countries. Scale economies concentrate volume with regional specialists holding multi-country licenses.
- Acquirer:Merchant-facing entities managing settlement and chargeback risk face SAMR capital reserve requirements in Saudi Arabia and UAE central bank governance mandates.
- Others:Independent sales organizations and value-added resellers extend reach into tier-2 merchant segments with limited direct sales capacity.
Consolidation pressure is highest on Acquirer. Partnership dependency defines Others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure investment concentrates in Gulf Cooperation Council economies while North African markets lag in real-time rail deployment. Consumption growth outpaces domestic processing capacity in Egypt and Morocco. Regulatory divergence between Saudi Arabia's SAMR framework and Egypt's central bank mandates shapes cross-border operator strategies.
Saudi Arabia
STC Pay and mobile wallet operators drive merchant acceptance expansion in Riyadh and Jeddah retail corridors. SAMR licensing requirements filter undercapitalized competitors while mandating operational resilience testing. The Eastern Province oil services sector accelerates B2B payment digitization through account-to-account rails.
United Arab Emirates
Dubai's hospitality and tourism clusters demand contactless guest experiences with dynamic currency conversion. The central bank's dual-track fintech authorization elevates capital reserve requirements for non-bank payment providers. Abu Dhabi sovereign wealth deployment backs national real-time payment infrastructure scaling.
Egypt
Fawry anchors bill payment digitization while micro-merchants adopt QR code acceptance fastest in Cairo and Alexandria informal commerce zones. The central bank mandates interoperability standards between mobile wallets and traditional banking channels. Remittance corridors serving Gulf labor populations resist full digitization due to last-mile cash-out dependencies.
Iraq
Baghdad and Basra merchant corridors lack integrated payment acceptance infrastructure, creating first-mover positioning for QR and soft-POS deployers. The central bank's gradual modernization of clearing systems lags regional peers by several years. Kurdish Regional Government banking infrastructure operates with limited connectivity to federal rails.
Morocco
Tier-2 banks in Casablanca and Rabat operate on legacy mainframe architectures resisting real-time API connectivity. The central bank's salary digitization mandates accelerate debit card issuance velocity. Remittance cash-out networks in Tangier and Agadir maintain deep dependencies resistant to wallet substitution.
Middle East & North Africa Digital Payments Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light platform developers across merchant acquiring and gateway services. Market structure consolidates around licensed processors holding multi-country regulatory coverage while fragmenting among specialized e-commerce enablers. Three archetypes dominate: regional processors with sovereign licensing, mobile wallet super-apps tethered to telecom balance sheets, and international scheme networks with localized compliance operations. Competitive dynamics center on strategic partnerships with licensed banks and geographic expansion through regulatory arbitrage.
Among regional infrastructure specialists, Network International exemplifies the multi-license processor archetype spanning Egypt and UAE merchant acquiring. Payfort occupies a position within the e-commerce gateway tier serving regional marketplace platforms. STC Pay anchors the telecom-originated super-app model tied to Saudi Arabia's national digital transformation agenda.
| Leading Market Players |
|---|
| Network International |
| Payfort |
| HyperPay |
| Tap Payments |
| Fawry |
| STC Pay |
| Visa |
| Mastercard |
| PayPal |
| Others |
Pricing and Supply Chain Analysis
Gulf Cooperation Council hospitality merchants and Saudi government procurement programs anchor demand concentration, binding pricing power to software-defined acquiring tiers and real-time rail access fees across Riyadh and Dubai corridors.
Pricing Analysis
Margin tightening in merchant acquiring reflects SAMR capital reserve mandates and interoperability engineering costs. Three-tier pricing structure across enterprise, mid-market, and micro-merchant levels segments by transaction volume and fraud management bundling. Cost-down pressure on payment gateways accelerates as e-commerce platforms demand multi-currency settlement without fee premiums. Micro-merchants in Egyptian informal commerce zones exhibit highest price sensitivity; enterprise hospitality operators in Dubai show lowest.
Supply Chain Analysis
Cross-border data center provisioning and undersea cable capacity shape logistics cost structures for UAE-based fintech operators serving Saudi and Egyptian markets. Hardware manufacturing concentrates in China, Taiwan, and South Korea for POS terminals and secure element chips. Cloud infrastructure draws from hyperscaler regions in UAE, Ireland, and Singapore. Single-source vulnerability sits with SWIFT correspondent banking relationships for dollar settlement. Distribution runs through licensed bank partnerships rather than direct-to-merchant sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time payment rails are displacing batch-based legacy infrastructure across the Middle East & North Africa, compressing settlement windows and forcing core system reinvestment.
For Market Incumbents: Extend super-app ecosystem bundling to capture merchant churn from standalone terminal distributors. Deepen API integration with SAMR-licensed banks to deflect standalone licensing costs. Build captive fraud scoring capabilities to offset margin compression from interchange regulation.
For New Entrants and Emerging Players: Begin with QR code and soft-POS deployment in Baghdad and Basra corridors where integrated acceptance infrastructure remains absent. Target Iraqi micro-merchants through telecom partnerships for subscriber acquisition cost efficiency. Lead with zero-hardware onboarding to bypass legacy distributor relationships.
For Investors and Strategic Acquirers: The window for entry favors multi-license processors with Egypt-UAE regulatory coverage and proven central bank relationships. Long-term viability hinges on GCC cross-border settlement coordination enabling seamless remittance rails. Watch Gulf Cooperation Council monetary authority announcements on real-time interoperability as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Rail Integration | STC Pay and Network International are rearchitecting core systems around Saudi Arabia's instant clearing infrastructure. |
| Biometric Authentication Layer | Facial recognition deployment reduces fraud rates and unlocks higher transaction limits for underbanked Egyptian users. |
| Cross-Border GCC Partnership | Wallet operators leveraging Abu Dhabi sovereign wealth backing gain first-mover positioning on remittance corridors. |
| QR Code Merchant Acquisition | Fawry's zero-hardware onboarding captures Cairo informal commerce zones excluded from traditional card networks. |
| Banking License Partnership | Payfort's deepening ties with UAE central bank licensed entities deflect standalone stored value facility requirements. |
Research Methodology
Central bank regulatory filings, fintech operator license disclosures, and Gulf Cooperation Council monetary coordination announcements formed the secondary backbone. Primary interviews with payment gateway CTOs, merchant acquiring heads, SAMR compliance officers, and hospitality procurement managers validated operational assumptions. Customs data on POS terminal imports and hyperscaler capex disclosures anchored hardware supply chain modeling. Bottom-up transaction volume estimates triangulated against top-down GDP electronic payment penetration benchmarks.
Historical trendline analysis of real-time rail deployment velocity and mobile wallet adoption curves informed projection parameters across the analysis window. Segmentation dimensions modeled include payment rail type, end-user context, merchant size tier, and regulatory jurisdiction cluster. CAGRs derived from logistic diffusion curves fitted to wallet penetration data and e-commerce growth trajectories. Forecast inputs incorporated SAMR licensing timeline assumptions and Egypt central bank interoperability mandate implementation pacing.
Underlying measurement precision varies by segment; mobile wallet transaction volumes carry tighter precision than blockchain remittance corridor estimates due to regulatory reporting requirements. Forecasts reflect documented assumptions on GCC monetary coordination progress and Egyptian banking channel modernization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
GCC Payment Gateway Market
Payments
US Gift Card and Incentive Card Market
Payments
Vietnam E-Wallet Market
Payments
Europe Virtual Cards Market
Payments
Canada Gift Card and Incentive Card Market
Payments
Indonesia Prepaid Cards Market
Payments
Bill Splitting Apps Market
Payments
Voice-Based Payments Market
Payments
China Real Time Payments Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Global Point of Sale Terminals Market
Payments
North America Mobile Payments Market
Payments
Global Real-Time Payments Market
Payments
Singapore Remittance Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Crypto Payment Gateway Market