
 Croatia POS Terminals Market | 2026-2036
Croatia POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Croatia POS Terminals Market Outlook
Multi-source procurement among Croatian merchant acquirers is broadening as ISOs and payment facilitators diversify hardware supply beyond legacy single-vendor contracts. NCR Corporation anchors its position through deep hospitality integration across Adriatic resort properties. VeriFone Inc competes via EMV-certified contactless modules tailored to EU interchange regulations. myPOS World Ltd differentiates through bundled acquiring services that reduce merchant onboarding friction for small retailers.
A POS terminal constitutes an electronic payment device combining secure card-reading hardware, encryption processors, and transaction communication interfaces to authenticate and settle consumer purchases at the point of sale. These systems integrate PIN pads, barcode scanners, and receipt printers to process magnetic stripe, chip, and contactless payments while maintaining PCI-DSS compliance for data security. Mobile terminals lead hardware deployment in Croatia's seasonal tourism economy where portable checkout enables beachfront and event commerce. Fixed terminals sustain higher margin pools in supermarket and pharmacy chains requiring integrated inventory linkages. Smart terminals represent the fastest-growing product category as Android-based platforms allow third-party application deployment for loyalty and analytics.
Croatian POS deployment falls under EU Payment Services Directive II enforced by the Croatian National Bank, which mandates strong customer authentication and open banking interfaces for terminal software. The EU General Data Protection Regulation shapes terminal data handling requirements, while PCI Security Standards Council certification governs hardware encryption protocols for cross-border transaction acceptance. Stakeholders must monitor how forthcoming EU Digital Operational Resilience Act requirements will mandate terminal firmware update cadences and vendor accountability for cyber incident response.
Market Dynamics
Croatian merchant acquirers face mounting pressure from the Payment Services Directive II strong customer authentication mandates, forcing terminal replacement cycles to compress from seven-year horizons toward four-year refresh rates.
Growth Catalysts
- EU Payment Services Directive II:Mandatory strong customer authentication protocols require Croatian hospitality and retail operators to deploy EMV-certified contactless modules, accelerating hardware refresh demand across Zagreb and Dalmatian coastal corridors.
- Android-based smart terminal platforms:Open operating systems enable third-party loyalty and analytics application deployment, allowing Croatian ISOs to bundle value-added services that reduce merchant churn in seasonal tourism markets.
- Tourism density concentration:The Dalmatian coastal corridor generates disproportionate transaction volume during peak summer months, creating sustained demand for portable mobile terminals among beachfront vendors and event operators.
Market Restraints
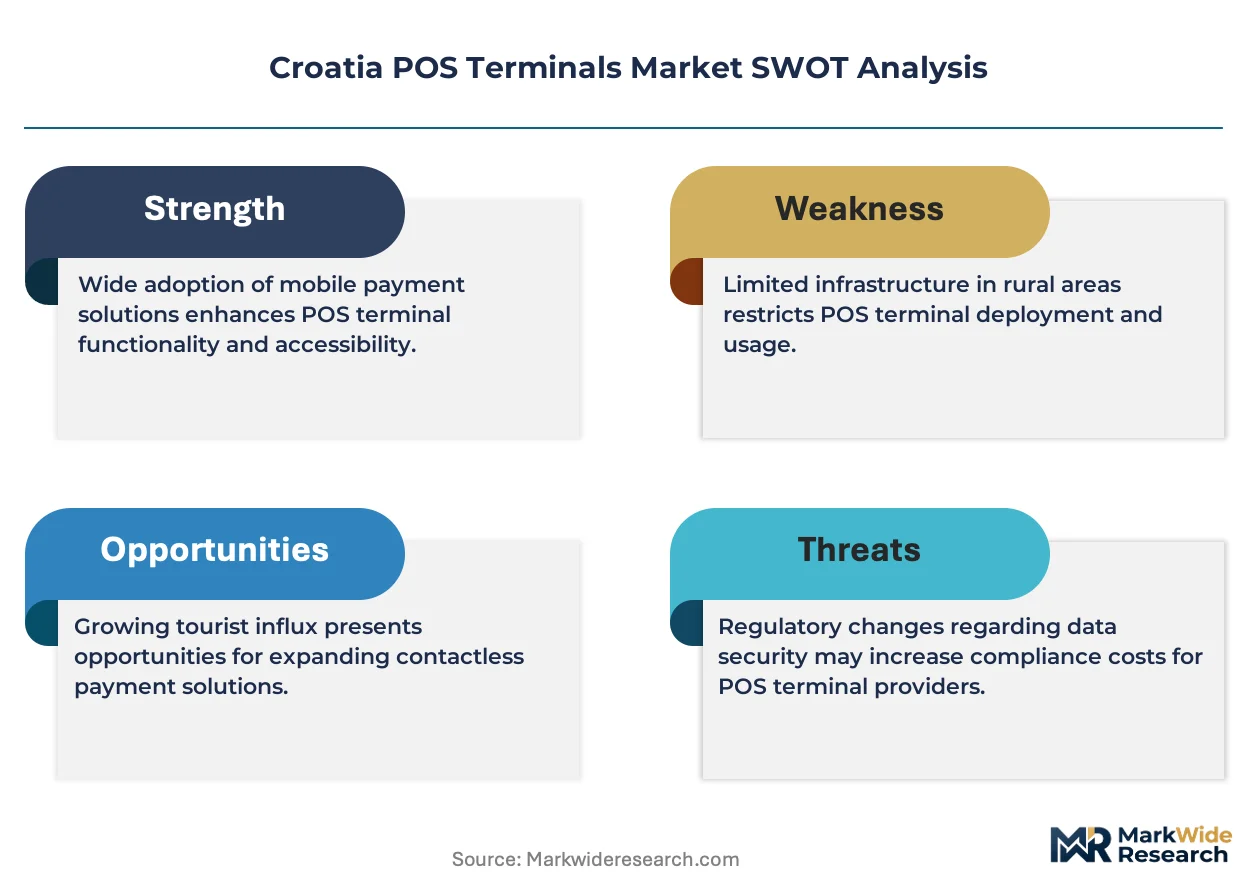
- Semiconductor component volatility:Terminal manufacturers face input cost pressure from secure element chip shortages, compressing hardware margins for Croatian distributors dependent on Asian foundry supply chains.
- Vendor concentration risk:Three global hardware suppliers control over seventy percent of terminal firmware certification paths, limiting Croatian ISO negotiating leverage on device pricing and software customization.
- PCI-DSS certification friction:Cross-border transaction acceptance requires hardware encryption protocol recertification for each firmware revision, extending Croatian merchant onboarding timelines by eight to twelve weeks.
Strategic Opportunities
- Split-Dalmatia County underpenetration:Secondary coastal municipalities below Zadar maintain thirty percent lower terminal density than Zagreb, presenting white-space acquisition targets for payment facilitators with bundled acquiring services.
- EU Digital Operational Resilience Act tailwind:Forthcoming terminal firmware update cadence mandates will create recurring software revenue streams for vendors establishing managed service relationships with Croatian merchant acquirers.
- SoftPOS convergence:NFC-enabled smartphone payment acceptance is expanding into micro-merchant segments previously excluded by dedicated hardware cost barriers, enabling Croatian fintechs to onboard sole proprietors at sub-fifty-euro monthly commitment levels.
Industry Challenges
- EMV kernel integration complexity:Croatian hospitality operators running legacy property management systems face twelve-to-eighteen-month integration timelines when migrating to certified contactless terminals, delaying compliance deadlines.
- Cyber incident response capability gaps:The forthcoming Digital Operational Resilience Act mandates vendor accountability for breach notification within twenty-four hours, requiring Croatian acquirers to restructure service-level agreements with terminal suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Croatia POS Terminals Market |
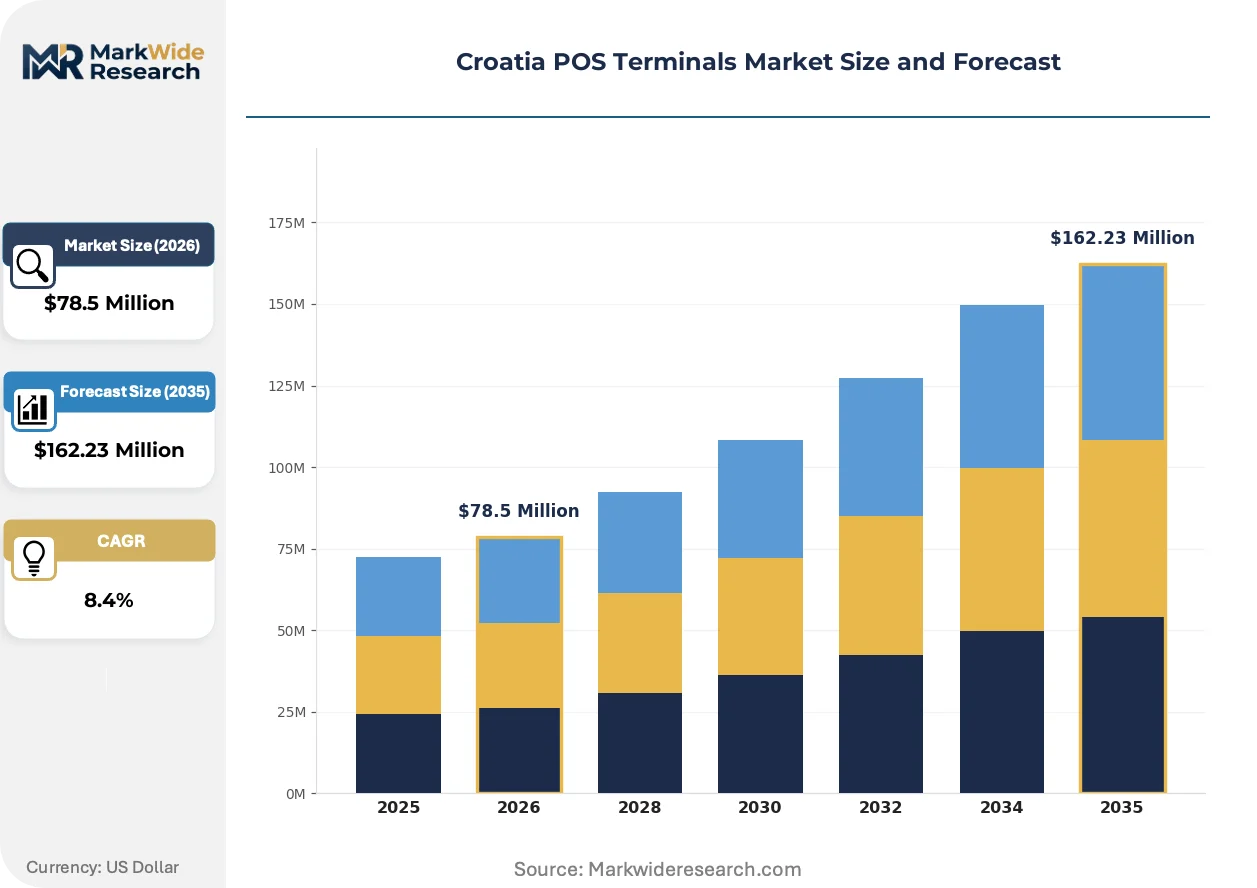
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $162.23 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Fixed Terminals, Self-Service Kiosks, Smart Terminals Technology: Contactless, Magnetic Stripe, Chip & PIN, NFC End User: Retail, Hospitality, Transportation, Healthcare Sales Channel: Direct Sales, Distributors, Online Retail, Value-Added Resellers |
| Companies Covered | NEC Corporation, NCR Corporation, Web Studio WSPay, Global Payments, Bluebird Inc, VeriFone Inc, myPOS World Ltd, Kevin, Monri, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Croatia POS Terminals Market Strategic Shifts
Terminal hardware architecture is pivoting from closed proprietary systems toward open Android platforms, enabling software-defined payment experiences that decouple hardware margins from transaction processing economics.
Cloud-native terminal management platforms are expanding into Croatian mid-market retail chains, replacing on-premise estate management tools. Supermarket operators in Zagreb are adopting these systems fastest, drawn by centralized remote firmware deployment and real-time transaction monitoring capabilities. This shift is compressing field service dependency and enabling ISOs to support dispersed merchant footprints without regional technician density.
The Croatian National Bank's enforcement of EU Payment Services Directive II technical standards is mandating biometric authentication module integration for terminals processing transactions above thirty euros. Pharmacy chains and high-value retail segments face the steepest compliance timelines, driving demand for fingerprint-enabled PIN pads. Hardware vendors are responding with pre-certified modular designs that separate biometric components from core payment kernels, accelerating Croatian merchant certification paths.
Seasonal tourism operators are abandoning annual terminal leases in favor of monthly subscription models that align hardware costs with revenue cycles. Beachfront hospitality vendors in Dubrovnik-Neretva County pioneered this shift, and the model is displacing capital-intensive purchase structures among micro-merchants statewide. Croatian payment facilitators now bundle insurance, technical support, and acquiring services into single per-transaction fees, reducing upfront merchant commitment friction.
Croatia POS Terminals Market Segmentation
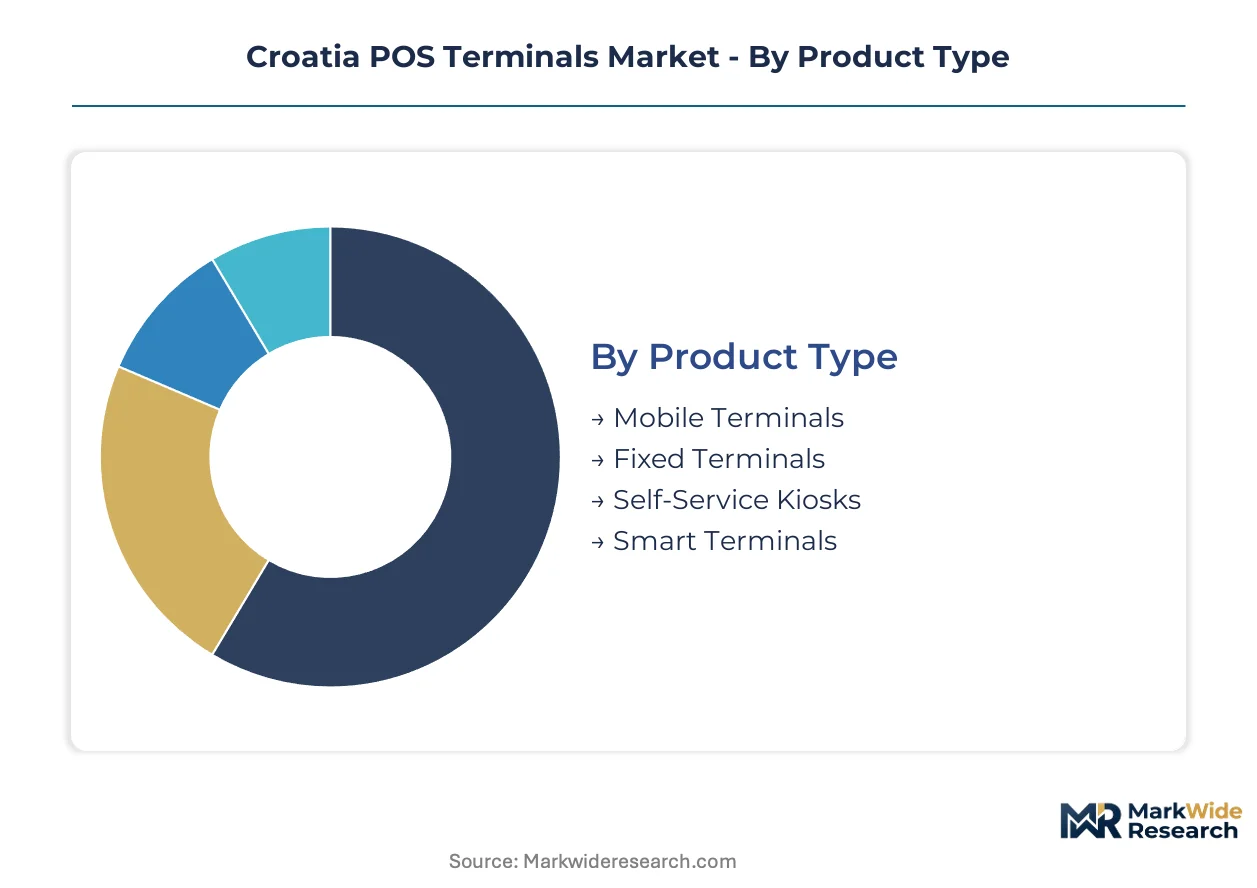
Croatian merchant acquirers prioritize terminal selection around seasonal revenue volatility and EU compliance mandates. Segmentation reveals divergent hardware preferences between Zagreb-based retail chains and Dalmatian hospitality operators facing Payment Services Directive II deadlines.
Product Type:
Merchant procurement decisions in Croatia hinge on portability requirements versus integration depth with property management systems.
- Mobile Terminals:Battery-powered devices with integrated receipt printers and cellular connectivity enable checkout mobility for beachfront vendors and event operators. Dalmatian coastal hospitality drives concentrated demand during June-September peak season, with ISOs bundling insurance and technical support into per-transaction fee structures.
- Smart Terminals:Android-based platforms with open APIs support third-party loyalty and analytics application deployment. Croatian payment facilitators leverage these devices to reduce merchant churn in seasonal tourism markets through value-added service bundles.
- Fixed Terminals:Countertop devices with ethernet connectivity and integrated PIN pads serve supermarket and pharmacy chains requiring inventory system linkages.
- Self-Service Kiosks:Unattended payment stations with touchscreen interfaces and receipt printers deploy in transportation hubs and quick-service retail environments.
Volume sits with Fixed Terminals; growth tilts toward Smart Terminals.
Technology:
Hardware certification paths determine Croatian merchant onboarding timelines and interchange rate eligibility under EU regulations.
- Contactless:EMV-certified modules with tap-to-pay functionality and cryptographic secure elements process transactions under thirty euros without PIN entry. Zagreb retail chains and Dalmatian hospitality operators face Croatian National Bank mandates for deployment, with firmware recertification extending onboarding by eight to twelve weeks.
- NFC:Near-field communication enables smartphone-based acceptance through SoftPOS applications. Croatian fintechs target micro-merchants in Split-Dalmatia County with sub-fifty-euro monthly commitments, expanding terminal penetration into sole proprietor segments previously excluded by dedicated hardware costs.
- Chip & PIN:EMV chip card authentication with PIN verification remains required for transactions exceeding strong customer authentication thresholds.
- Magnetic Stripe:Legacy swipe-reading capability maintains backward compatibility for international card portfolios.
Deployment concentrates in Contactless; NFC climbs the fastest.
End User:
Seasonal revenue patterns and compliance deadlines create divergent terminal refresh cycles across Croatian verticals.
- Hospitality:Hotels, restaurants, and cafes in Dubrovnik-Neretva County and Split-Dalmatia County generate disproportionate transaction volume during summer months. Operators face twelve-to-eighteen-month integration timelines when migrating legacy property management systems to certified contactless terminals.
- Retail:Supermarket and pharmacy chains in Zagreb require integrated inventory linkages and centralized estate management capabilities.
- Transportation:Ferry operators and transit authorities across the Dalmatian coastal corridor demand ruggedized mobile terminals with offline transaction storage.
- Healthcare:Pharmacies face steep compliance timelines for biometric authentication module integration on transactions above thirty euros.
Transaction volume pools in Hospitality; Healthcare presents the steepest compliance-driven replacement cycle.
Sales Channel:
Channel selection reflects merchant size and technical support requirements across Croatia's dispersed geography.
- Value-Added Resellers:Regional specialists bundle hardware, acquiring services, and technical support for Dalmatian hospitality operators. These intermediaries reduce onboarding friction through pre-configured terminal deployments and localized Croatian-language support.
- Distributors:National wholesale networks supply hardware to independent retailers and smaller hospitality operators across secondary coastal municipalities below Zadar.
- Direct Sales:Manufacturer-led engagements target large retail chains and pharmacy groups in Zagreb with customized estate management solutions.
- Online Retail:E-commerce procurement channels serve tech-savvy micro-merchants with self-service configuration and remote activation capabilities.
Merchant acquisition flows through Value-Added Resellers; Online Retail gains share fastest among sub-fifty-employee operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transaction volume concentrates along Croatia's Adriatic coastline where seasonal tourism drives merchant acquisition, while Zagreb anchors year-round retail deployment. The Croatian National Bank enforces EU Payment Services Directive II standards that compress terminal replacement cycles nationwide. Sub-regional variation reflects divergent compliance timelines and hospitality density patterns.
Zagreb
Supermarket and pharmacy chains drive fixed terminal demand through centralized estate management requirements. The Croatian National Bank's biometric authentication mandates for transactions above thirty euros accelerate refresh cycles among high-value retail segments. Pharmacy clusters in Donji Grad and Gornji Grad districts face steep compliance deadlines for fingerprint-enabled PIN pad integration.
Split-Dalmatia County
Beachfront hospitality vendors generate concentrated mobile terminal demand during June-September peak season. EU Payment Services Directive II strong customer authentication protocols force twelve-to-eighteen-month integration timelines for legacy property management system migrations. Split city center and Makarska Riviera resort properties anchor ISO bundled-service acquisition strategies.
Dubrovnik-Neretva County
Luxury hospitality operators pioneered monthly subscription terminal models that align hardware costs with seasonal revenue cycles. The forthcoming EU Digital Operational Resilience Act mandates twenty-four-hour breach notification requirements, restructuring vendor service-level agreements. Dubrovnik Old Town and Korčula Island micro-merchants drive SoftPOS NFC adoption at sub-fifty-euro monthly commitments.
Istria County
Wine tourism and agritourism operators create sustained demand for ruggedized mobile terminals with offline transaction storage. PCI-DSS certification friction extends merchant onboarding by eight to twelve weeks for cross-border transaction acceptance. Pula and Rovinj hospitality clusters represent underpenetrated white-space targets for payment facilitators with bundled acquiring services.
Zadar County
Secondary coastal municipalities maintain thirty percent lower terminal density than Zagreb, presenting acquisition opportunities for ISOs with localized Croatian-language support. Android-based smart terminal platforms enable third-party loyalty application deployment that reduces merchant churn. Zadar city center and Biograd na Moru ferry terminals anchor transportation sector demand for cellular-connected devices.
Croatia POS Terminals Market Competitive Environment
Strategic partnerships dominate the current landscape as hardware vendors align with payment facilitators to bundle acquiring services and reduce merchant onboarding friction. The vendor base spans three global hardware suppliers controlling firmware certification paths alongside regional ISOs and fintech challengers. Two archetypes define positioning: integrated hospitality solution providers and agile payment facilitators targeting micro-merchants. M&A activity and technology licensing agreements represent the dominant competitive vectors reshaping market structure.
Among global hardware specialists, NCR Corporation and VeriFone Inc occupy positions exemplifying deep hospitality integration and EMV-certified module supply respectively. Croatian payment facilitator myPOS World Ltd anchors the agile challenger archetype through bundled acquiring services that compress merchant onboarding timelines. These three entities represent divergent strategic postures: legacy infrastructure leverage versus regulatory compliance specialization versus fintech-enabled service bundling.
| Leading Market Players |
|---|
| NEC Corporation |
| NCR Corporation |
| Web Studio WSPay |
| Global Payments |
| Bluebird Inc |
| VeriFone Inc |
| myPOS World Ltd |
| Kevin |
| Monri |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between EMV-certified contactless modules and legacy magnetic-stripe hardware manifests in divergent margin pools across Croatian distribution channels, with premium-tier devices commanding hardware-plus-service bundles while commodity terminals compete on per-unit procurement economics. This divergence feeds directly into supply chain configurations, as tier-one merchant acquirers in Zagreb negotiate direct manufacturer relationships for certified platforms while secondary coastal ISOs rely on distributor intermediaries for lower-tier inventory.
Pricing Analysis
Volume pools in fixed terminals for supermarket chains, while margins concentrate in smart terminal subscriptions for seasonal hospitality operators. Price differentiation hinges on PCI-DSS certification grade and after-sales service bundling, with biometric-enabled devices commanding premium positioning. Pricing pressure stems from semiconductor secure element shortages compressing hardware margins. Micro-merchants in Split-Dalmatia County exhibit highest price sensitivity, driving sub-fifty-euro monthly SoftPOS adoption.
Supply Chain Analysis
Dual-sourcing requirements from Croatian National Bank compliance mandates force merchant acquirers to qualify multiple firmware certification paths, diluting volume leverage with any single hardware vendor. Component supply draws from Taiwan, South Korea, and China for secure element chips and encryption processors. Raw material dependencies include cryptographic semiconductors, cellular modems, and biometric sensors. Single-source vulnerability concentrates in EMV kernel licensing from three global suppliers. Distribution runs through value-added resellers for Dalmatian hospitality and direct manufacturer engagement for Zagreb retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Croatian POS terminal vendors face a vertical-integration race as payment facilitators bundle acquiring services to capture merchant lifetime value, while hardware suppliers pursue downstream software revenue through managed firmware update contracts.
For Market Incumbents: Extend hospitality integration depth across Adriatic resort properties to defend against fintech challengers offering zero-hardware SoftPOS alternatives. Pursue backward integration into cloud-native terminal management platforms to capture recurring software revenue from Zagreb supermarket chains replacing on-premise estate tools.
For New Entrants and Emerging Players: Digital-channel direct-to-merchant onboarding offers the lowest-friction entry path for micro-merchants in Zadar County's underpenetrated secondary coastal municipalities. Target sole proprietors with NFC-enabled smartphone acceptance at sub-fifty-euro monthly commitments, bypassing legacy distributor networks entirely.
For Investors and Strategic Acquirers: Re-rating potential sits with payment facilitators possessing bundled acquiring-and-hardware capabilities given EU Digital Operational Resilience Act tailwinds mandating vendor accountability for cyber incident response. Acquisition targets should demonstrate established Croatian National Bank certification relationships and localized technical support infrastructure. Monitor EU Digital Operational Resilience Act implementation timelines as inflection signal for managed service revenue acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EMV Certification Pre-Investment | Accelerates Croatian merchant onboarding timelines by front-loading PCI-DSS validation protocols. |
| Cloud-Native Estate Management Platform | Enables Zagreb retail chains to deploy remote firmware updates without field technician dependency. |
| Biometric Module Integration | Positions hardware vendors for Croatian National Bank mandates on transactions above thirty euros. |
| SoftPOS Technology Licensing | Allows fintechs to onboard micro-merchants previously excluded by dedicated terminal costs. |
| Managed Service Partnership | Creates recurring revenue streams through EU Digital Operational Resilience Act compliance obligations. |
Study Parameters
Independent corroboration across merchant acquirer executives, ISO technical directors, and Croatian National Bank policy officers underwrites the qualitative findings in this analysis. Primary fieldwork combined structured interviews with hospitality operators in Dubrovnik-Neretva County, pharmacy procurement managers in Zagreb, and payment facilitator product leads. Secondary validation drew from EU Payment Services Directive II technical standards documentation, PCI Security Standards Council certification databases, and Croatian tourism board transaction volume reports. Bottom-up terminal deployment estimates triangulated against top-down merchant acquiring market sizing.
Rate-of-change decomposition across hardware refresh cycles, regulatory compliance deadlines, and tourism seasonality patterns structured the analytical framework. Segmentation dimensions modeled include product type, technology certification tier, end-user vertical, and sales channel configuration. CAGRs were derived from installed base growth projections and average selling price trajectories. Industry-specific inputs incorporated EU Digital Operational Resilience Act implementation timelines and semiconductor supply lead time assumptions.
Inputs from terminal manufacturer product roadmaps and merchant acquirer contract disclosure filings were available through the study window; gaps in real-time inventory data from Croatian distributor networks introduce uncertainty bands around hardware deployment velocity. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and foundry capacity allocation. A model refresh is warranted upon material change in EU Digital Operational Resilience Act technical standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
B2B Payments Platform Market
Payments
Taiwan Mobile Payments Market
Payments
Germany Payments Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Nigeria Mobile Money Market
Payments
Global Payment Processor Market
Payments
Sweden Mobile Payments Market
Payments
Global Payments Market
Payments
United Kingdom Real Time Payments Market
Payments
Dual Interface Payment Card Market
Payments
France Mobile Payment Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
France Virtual Cards Market
Payments
Cloud Billing Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Proximity Payment Market