
 Europe Clearing Houses and Settlements Market | 2026-2036
Europe Clearing Houses and Settlements Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Clearing Houses and Settlements Market Insights
Asset-light utility models and shared-service platforms is reconfiguring capital deployment across European post-trade infrastructure. Euroclear leverages its cross-border securities settlement network to anchor pan-European bond clearing. LCH Group competes through interest-rate swap specialization, sustaining deep liquidity pools in euro-denominated derivatives.
Europe clearing houses and settlements comprise regulated financial utilities that interpose themselves between trading parties to guarantee performance, manage counterparty risk, and finalize asset transfers through novation and net settlement processes. These entities operate under strict capital requirements and default fund structures designed to absorb losses during member failures. Securities settlement services dominate transaction volumes across the continent, while distributed ledger technology segments attract the fastest-growing investment as operators pilot tokenized collateral mobility. Real-time gross settlement systems occupy the core infrastructure layer, processing high-value payments with immediate finality.
ESMA, the ECB, and national competent authorities under MiFID II shape European clearing house mandates through capital buffer rules, interoperability requirements, and third-country recognition frameworks. The EU's Digital Operational Resilience Act imposes incident reporting deadlines and stress-testing protocols that directly affect technology budgets. Stakeholders must monitor how incoming DLT interoperability standards alter competitive boundaries between incumbent settlement utilities and emerging blockchain-native platforms.
Market Dynamics
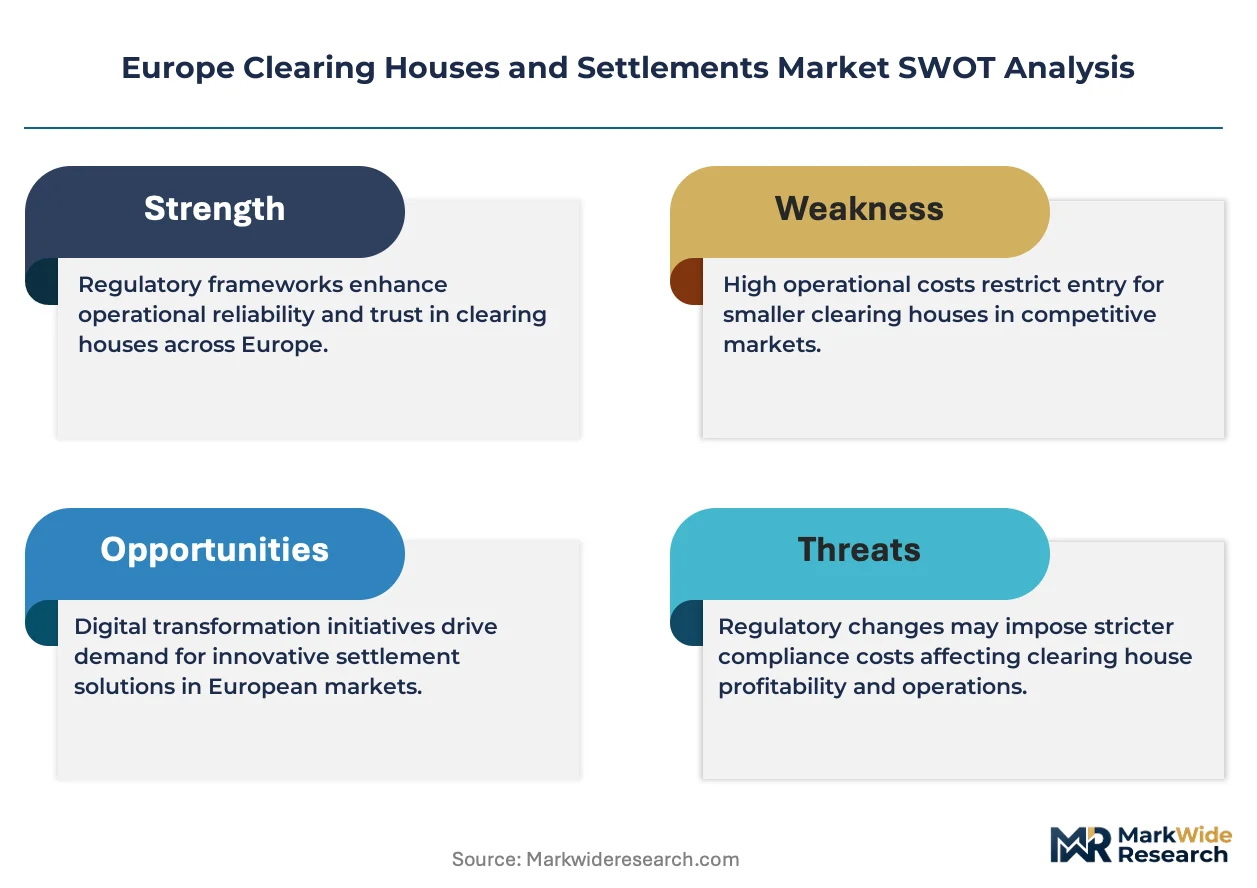
Capital requirements under the EU's Digital Operational Resilience Act are forcing clearing houses to restructure technology budgets and default fund mechanisms. This regulatory compression is accelerating consolidation among smaller settlement utilities while deepening moats for incumbent pan-European networks.
Growth Catalysts
- Derivatives clearing mandates:Asset managers are expanding central counterparty usage for post-trade workflow compression. Eurex Clearing in Germany is deepening processing capabilities for euro-denominated interest rate products.
- DLT interoperability standards:The European Securities and Markets Authority is piloting frameworks for tokenized collateral mobility. Distributed ledger pilots are attracting infrastructure investment from incumbent settlement operators.
- Cross-border securities netting:Euroclear's pan-European bond clearing network is anchoring demand for multi-currency settlement services. Asset-light utility models are reconfiguring capital deployment across post-trade infrastructure.
Market Restraints
- Concentrated liquidity pools:Interest rate swap clearing concentrates in euro-denominated products at LCH Group. New entrants face prohibitive costs to establish competing liquidity depth.
- Capital buffer escalation:Default fund contributions and skin-in-the-game requirements under MiFID II are compressing returns for clearing members. Smaller participants are exiting or consolidating.
- Legacy system integration costs:Real-time gross settlement systems require continuous maintenance of core infrastructure layers. Technology debt accumulates in mainframe-dependent settlement engines.
Strategic Opportunities
- Tokenized securities settlement:France and Germany are piloting blockchain-native platforms for digital bond issuance. Regulatory sandboxes are permitting experimentation outside incumbent utility frameworks.
- Carbon derivatives clearing:The EU Green Deal is creating demand for emissions trading scheme contract processing. New product categories are opening beyond traditional rates and credit.
- Third-country recognition:ESMA's equivalence frameworks for UK and Swiss clearing houses are creating cross-border service expansion pathways. Regulatory arbitrage opportunities exist in margin requirement differentials.
Industry Challenges
- Cyber resilience certification timelines:The Digital Operational Resilience Act imposes strict incident reporting deadlines and stress-testing protocols. Compliance certification is consuming technology leadership bandwidth.
- Interoperability protocol fragmentation:Competing distributed ledger standards between incumbent utilities and fintech platforms are delaying settlement finality improvements. Technical committees are struggling to converge on common messaging formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Clearing Houses and Settlements Market |
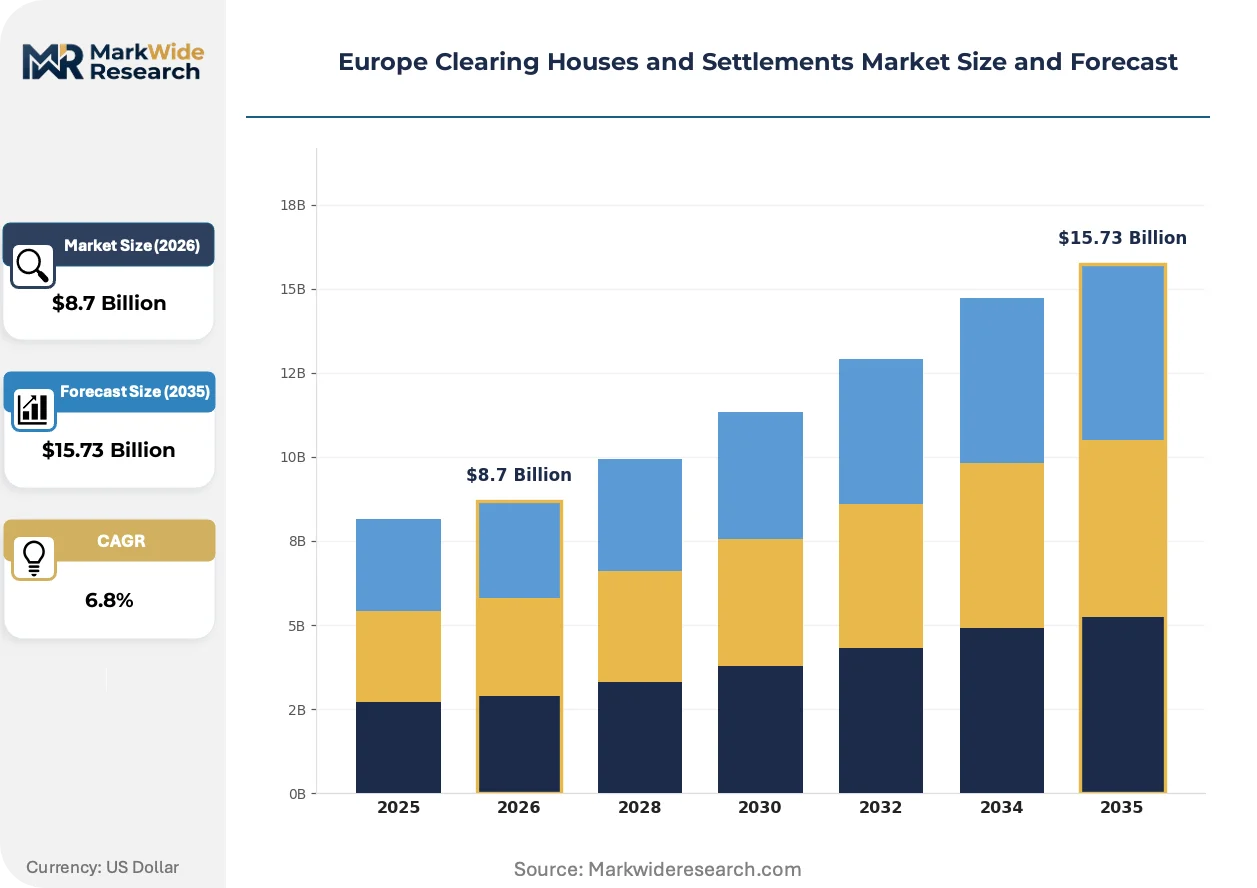
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Central Counterparty, Securities Settlement, Derivatives Clearing, Trade Matching Technology: Distributed Ledger, Blockchain, Real-Time Gross Settlement, Electronic Funds Transfer Client Type: Investment Banks, Asset Managers, Hedge Funds, Retail Brokers Transaction Size: High Value, Low Value, Small Scale, Large Scale |
| Companies Covered | Euroclear, Clearstream, LCH Group, Eurex Clearing, SIX x-clear, Euronext Clearing, BME Clearing, Cboe Clear Europe, Nasdaq Clearing, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Clearing Houses and Settlements Market Trends and Innovations
Post-trade infrastructure is undergoing platform modernization as regulatory mandates and distributed ledger pilots converge. Settlement utilities are repositioning around data services and collateral optimization rather than pure transaction processing.
Distributed ledger technology is digitizing collateral mobility through tokenized asset representations on permissioned networks. Major clearing houses are piloting atomic settlement for repo transactions. The structural consequence is compressing settlement cycles from T+2 toward T+0 while reducing intraday liquidity requirements.
The EU's Digital Operational Resilience Act is mandating incident reporting within strict timeframes and comprehensive stress-testing for critical financial infrastructure. Clearing houses must now maintain operational continuity under severe cyber attack scenarios. German and French regulators are enforcing the tightest compliance timelines, accelerating technology procurement cycles.
Buyers are consolidating vendor relationships around integrated post-trade service bundles rather than fragmented best-of-breed solutions. Asset managers are demanding unified collateral management across cash and derivatives portfolios. This concentration is most visible among Dutch and Scandinavian pension funds seeking to reduce operational counterparty counts.
Europe Clearing Houses and Settlements Market Segmentation
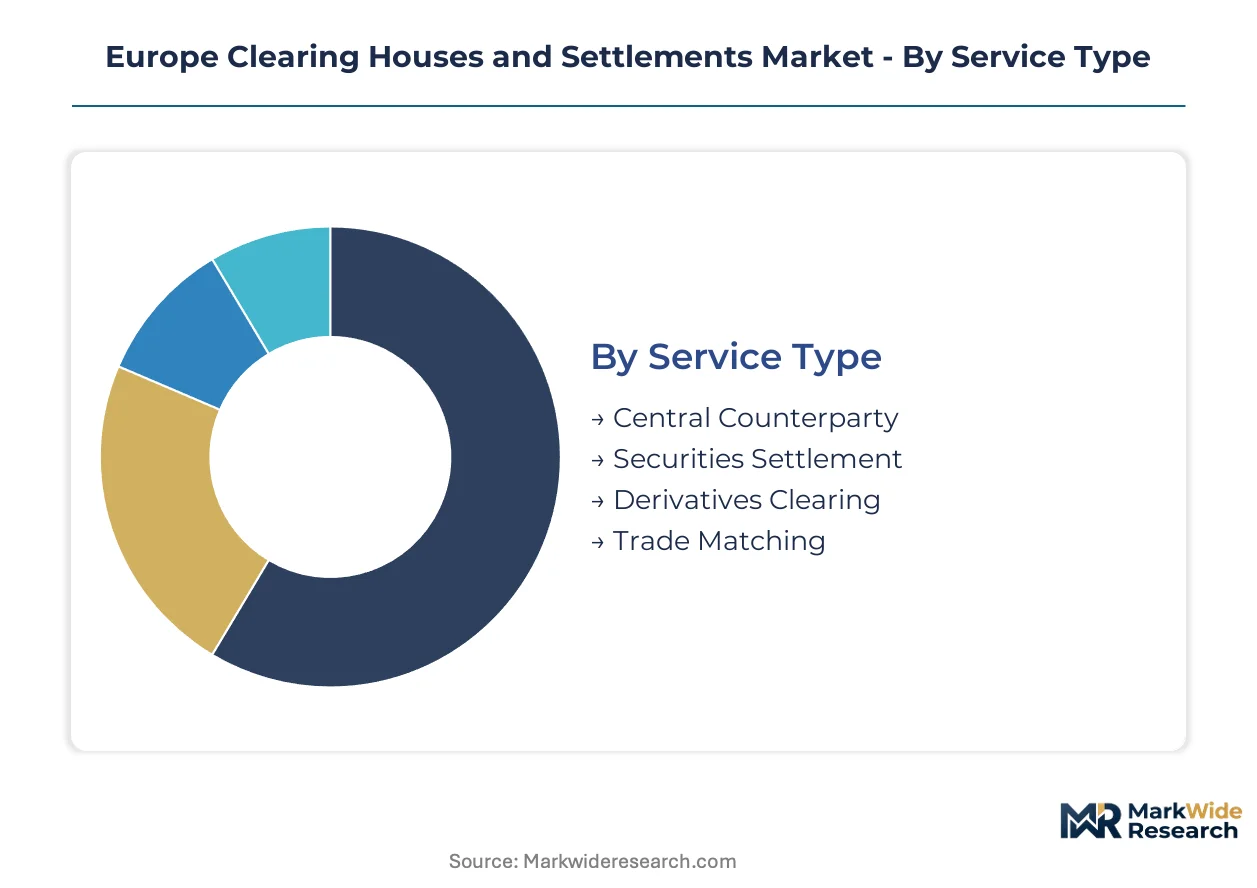
Segmentation in European clearing and settlement infrastructure reveals how service specialization, technology adoption curves, and client sophistication tiers determine capital allocation and regulatory compliance burdens across the post-trade value chain.
Service Type:
Post-trade service intensity varies dramatically by function, with novation and default fund management demanding continuous operational engagement long after trade execution.
- Central Counterparty:Interposes itself between trading parties through contract novation, absorbing counterparty risk into mutualized default funds. German asset managers are expanding CCP usage for euro-denominated interest rate compression, driven by Eurex Clearing's deepening liquidity pools.
- Securities Settlement:Finalizes legal ownership transfer through delivery-versus-payment mechanisms, operating Euroclear's pan-European bond clearing network with multi-currency capabilities. Dutch and Scandinavian pension funds are consolidating vendor relationships around these utility models.
- Derivatives Clearing:Manages margin collection and variation payments for futures and options contracts.
- Trade Matching:Confirms trade details between counterparties prior to settlement finality.
Securities Settlement holds the largest share; momentum sits with Central Counterparty as derivatives volumes expand.
Technology:
Technology cost tiers separate incumbent utilities maintaining legacy mainframe stacks from challengers building cloud-native distributed infrastructure.
- Distributed Ledger:Enables tokenized collateral mobility on permissioned networks, compressing settlement cycles toward atomic finality. French and German regulators are permitting sandbox experimentation outside incumbent frameworks.
- Real-Time Gross Settlement:Processes high-value payments with immediate finality, forming the core infrastructure layer for TARGET2 and national central bank systems. The ECB's operational continuity mandates are accelerating procurement cycles for cyber resilience upgrades.
- Blockchain:Supports digital bond issuance pilots with immutable transaction records.
- Electronic Funds Transfer:Handles retail and commercial payment flows through automated clearing houses.
Real-Time Gross Settlement dominates transaction volumes; Distributed Ledger is climbing the fastest as infrastructure investment redirects toward tokenization.
Client Type:
Client sophistication determines service bundling complexity, with integrated collateral management demands concentrating among the largest institutional players.
- Investment Banks:Require comprehensive clearing membership across multiple CCPs and asset classes, maintaining direct default fund contributions and skin-in-the-game capital. MiFID II buffer requirements are compressing returns and forcing consolidation among smaller participants.
- Asset Managers:Drive demand for unified post-trade workflows across cash and derivatives portfolios. Buy-side consolidation of vendor relationships is most visible among Dutch and Scandinavian institutions seeking operational counterparty reduction.
- Hedge Funds:Prioritize margin efficiency and cross-product netting opportunities.
- Retail Brokers:Rely on sponsored clearing arrangements with indirect CCP access.
Investment Banks generate the highest revenue per client; Asset Managers represent the steepest expansion trajectory as CCP usage broadens.
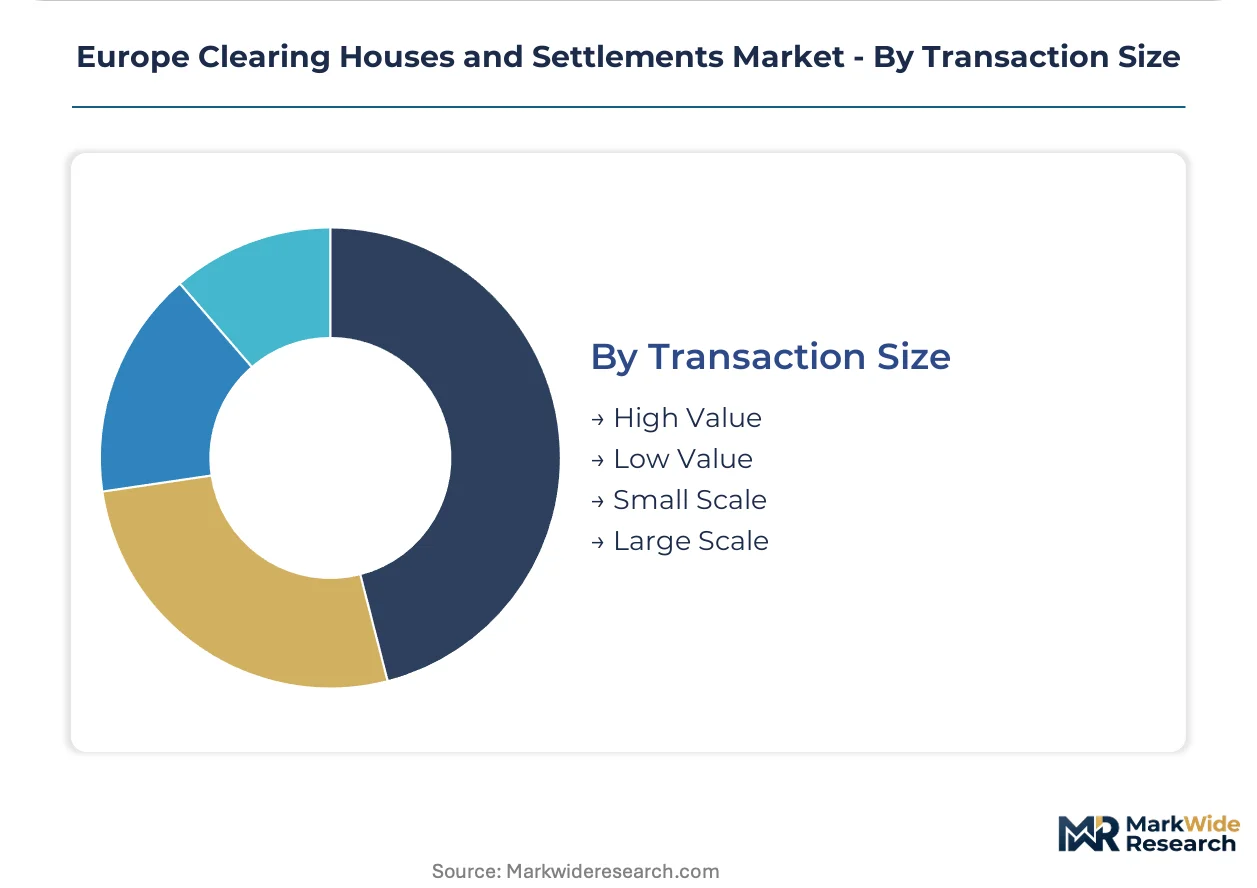
Transaction Size:
Transaction scale dictates infrastructure requirements, with high-value flows demanding real-time finality and low-value batches tolerating deferred net settlement.
- High Value:Exceeds thresholds requiring immediate settlement finality through RTGS systems, subject to strict Digital Operational Resilience Act incident reporting deadlines. German and French regulators are enforcing the tightest compliance timelines for these systemically critical flows.
- Large Scale:Encompasses institutional block trades and wholesale market transactions with compressed settlement cycles. The shift from T+2 toward T+0 is reducing intraday liquidity requirements for repo and securities lending markets.
- Low Value:Processes retail payments through automated batch settlement.
- Small Scale:Handles fragmented retail securities orders and micro-payments.
High Value commands infrastructure investment priority; Large Scale is gaining share fastest as institutional workflow compression accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border clearing flows within Europe generate substantial intra-regional service exports, with settlement utilities in core markets processing instruments issued across peripheral jurisdictions. Import dependency concentrates in specialized derivatives clearing where liquidity pools determine access rather than geography.
Germany
Eurex Clearing anchors euro-denominated interest rate derivatives processing, drawing asset managers from across the continent into its liquidity pools. BaFin enforces the Digital Operational Resilience Act's strictest operational continuity timelines for Frankfurt-based infrastructure operators. The Frankfurt financial cluster concentrates clearing technology development and default fund management operations.
United Kingdom
LCH Group sustains deep liquidity in sterling and euro interest rate swaps despite post-Brexit third-country recognition constraints. The Bank of England and FCA maintain equivalence assessments for EU clearing house access under EMIR refit negotiations. London's City cluster retains specialized repo clearing and securities lending infrastructure serving European institutional clients.
France
Euronext Clearing processes equity and commodity derivatives for continental European exchanges. The Autorité des Marchés Financiers permits distributed ledger experimentation through regulatory sandboxes for tokenized bond settlement pilots. Paris La Défense hosts post-trade innovation labs developing atomic settlement protocols for repo markets.
Netherlands
Euroclear's headquarters in Brussels coordinates pan-European securities settlement with substantial Dutch operational presence. De Nederlandsche Bank supervises TARGET2 payment flows and real-time gross settlement system resilience under ECB mandates. Amsterdam's financial district concentrates collateral management services for Scandinavian and Benelux pension funds.
Belgium
Euroclear Bank operates the international central securities depository anchoring cross-border bond settlement across 60 markets. The National Bank of Belgium enforces ESMA guidelines on settlement discipline and cash penalties for failed trades. Brussels hosts the primary technical infrastructure for Euroclear's multi-currency settlement engine processing high-value institutional flows.
Europe Clearing Houses and Settlements Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in risk management and collateral optimization modules. The market structures around three pan-European utilities with interoperating national subsidiaries, creating tiered access based on clearing membership depth. Strategic archetypes include multi-asset central counterparties, international central securities depositories, and national settlement utilities with specialized asset-class focus. Competitive moves concentrate on regulatory technology procurement for Digital Operational Resilience Act compliance and distributed ledger pilot partnerships with national regulators.
Among pan-European platform operators, Euroclear, LCH Group, and Eurex Clearing occupy positions representing distinct archetypes: the cross-border settlement network, the derivatives clearing specialist, and the exchange-integrated central counterparty respectively. These entities exemplify how scale in default fund mutualization and liquidity pool depth create defensive positioning against new entrants. Smaller national utilities such as SIX x-clear and BME Clearing sit within specialized geographic or asset-class niches where regulatory preferences or exchange ownership sustain viable competitive positions.
| Leading Market Players |
|---|
| Euroclear |
| Clearstream |
| LCH Group |
| Eurex Clearing |
| SIX x-clear |
| Euronext Clearing |
| BME Clearing |
| Cboe Clear Europe |
| Nasdaq Clearing |
| Others |
Pricing and Supply Chain Analysis
The Frankfurt-London fiber corridor carries latency-sensitive order flow between Eurex Clearing and LCH Group, with bandwidth costs feeding directly into connectivity pricing tiers for buy-side participants. This infrastructure concentration amplifies pricing power for pan-European settlement utilities while compressing margins for regional challengers dependent on leased network capacity.
Pricing Analysis
Investment banks anchor transaction-based pricing structures across central counterparty services, with clearing fees scaling by notional exposure and default fund contribution requirements. Price differentiation hinges on liquidity pool depth and cross-product netting efficiency rather than pure service bundling. Pricing pressure stems from MiFID II capital buffer escalation forcing members to demand volume discounts for compressed returns. Asset managers exhibit highest price sensitivity due to fee pressure on passive fund structures, while hedge funds prioritize margin efficiency over absolute cost.
Supply Chain Analysis
Technology vendors in Germany, the United Kingdom, and Ireland hold dominant positions in core settlement engine software and cyber resilience certification services. Raw material dependencies center on specialized semiconductor components for mainframe modernization, subsea cable capacity for cross-border data flow, and skilled compliance personnel for DORA implementation. Supply chain risk concentrates in single-source vulnerability for legacy system maintenance where vendor consolidation has eliminated alternative suppliers. Distribution runs through direct enterprise sales teams serving clearing members and sponsored access arrangements for indirect participants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's clearing and settlement infrastructure operates as a regulatory moat business where default fund mutualization and liquidity network effects create near-impregnable barriers against new entrants. Switching costs for clearing members—measured in operational integration, collateral rehypothecation agreements, and regulatory recognition timelines—lock participants into incumbent relationships.
For Market Incumbents: Insulate core derivatives clearing franchises by deepening vertical integration into collateral optimization software and real-time risk analytics. Prioritize DORA compliance certification ahead of regulatory deadlines to capture members exiting smaller utilities unable to absorb technology investment burdens. Threats from blockchain-native settlement platforms and regulatory sandboxes in France and Germany demand pre-emptive pilot partnerships with national authorities. For New Entrants and Emerging Players: Carbon derivatives clearing for EU Emissions Trading Scheme contracts represents the most penetrable entry point, given limited incumbent specialization and Green Deal regulatory tailwinds. Tokenized securities settlement pilots in French regulatory sandboxes offer a second white-space target where incumbent utilities lack deployed infrastructure. A go-to-market angle through specialized buy-side technology partnerships—collateral management APIs for Scandinavian pension funds—circumvents direct liquidity pool competition. For Investors and Strategic Acquirers: National settlement utilities with exchange ownership and specialized asset-class focus offer acquisition targets with embedded regulatory relationships and geographic moats. Long-term viability across the analysis window depends on successfully navigating DORA implementation timelines and DLT interoperability standardization. The signal to watch is ESMA equivalence decision velocity for UK clearing houses, which will determine cross-border service expansion capacity and margin requirement arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Procurement | DORA compliance certification ahead of BaFin and AMF enforcement timelines secures member retention. |
| DLT Interoperability Partnership | Collaboration with ECB and national regulators on tokenized collateral standards shapes competitive boundaries. |
| Carbon Derivatives Product Launch | EU Green Deal regulatory tailwinds create first-mover advantage in emissions contract processing infrastructure. |
| Cross-Border Service Expansion | ESMA equivalence pathway exploitation enables UK and Swiss clearing house margin arbitrage capture. |
| Collateral Optimization Platform Integration | Unified cash and derivatives collateral management addresses Dutch and Scandinavian pension fund consolidation demands. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association disclosures, and infrastructure operator technical documentation. Primary engagement spanned clearing house risk officers, buy-side operational heads at asset managers, compliance leads at investment banks, and national competent authority supervisors. Secondary validation drew from ESMA consultation papers, ECB payment system reports, EMIR refit legislative texts, and Euroclear Group annual disclosures. Bottom-up transaction volume modeling triangulated against top-down market sizing from pan-European utility revenue aggregation.
Forecast inputs incorporate service type adoption curves, technology migration timelines, and regulatory implementation schedules across the projection horizon. Segmentation dimensions modeled include service type intensity, technology cost tier, client sophistication band, and transaction scale threshold. CAGRs derive from historical volume trajectories adjusted for derivatives clearing mandate expansion and DLT pilot scaling assumptions. Industry-specific inputs include TARGET2 payment flow growth and tokenized securities issuance pipeline data from French and German regulatory sandboxes.
Practitioners should monitor ESMA equivalence determinations, DORA enforcement variance across national regulators, and DLT interoperability standard convergence for early signals of competitive boundary shifts. Forecasts embed assumptions regarding regulatory timeline adherence and technology adoption S-curves that material divergence could invalidate. Quarterly review of clearing member default fund contribution trends and sandbox licensing velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Malta POS Terminal Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Brazil POS Terminal Market
Payments
India Forex Cards Market
Payments
Fingerprint Payment Market
Payments
Germany Payments Market
Payments
Denmark POS Terminals Market
Payments
Global Master Card Market
Payments
Mexico Payments Market
Payments
Medical Payment Fraud Detection Market
Payments
Global Virtual Payment (POS) Terminals Market
Payments
Canada Real Time Payments Market
Payments
Payment Analytics Software Market
Payments
India Payment Gateway Market
Payments
Global Payment Monitoring Market
Payments
Biometric Payment Market