
 Household Finances Market | 2026-2036
Household Finances Market Size, Share, and Industry Trends Forecast 2026-2036
Household Finances Market Analysis
The gap between premium wealth-management tiers and commodity transactional banking is rebalancing as automated robo-advisors compress advisory fees while high-net-worth clients demand bespoke hybrid services. JPMorgan Chase leverages its private banking infrastructure to sustain white-glove offerings across multiple wealth brackets. Ally Financial competes through digital-first savings products with minimal overhead. Capital One Financial differentiates via data-driven credit monitoring and personalized financial coaching embedded in mobile channels.
Household finances encompass the full spectrum of consumer monetary management, including liquidity planning, debt instruments, risk-transfer vehicles, and capital accumulation vehicles governed by interest-rate benchmarks, credit-scoring algorithms, and regulatory capital requirements. The primary purpose is to optimize intertemporal resource allocation across income volatility, life-stage transitions, and unexpected expenditures. Personal loans and mortgages within the product-type dimension command the deepest margin pools due to interest-income duration and collateral backing, while budgeting tools and investment platforms across service-type and channel dimensions are capturing the fastest growth as mobile-app penetration displaces in-person advisory relationships.
The Consumer Financial Protection Bureau enforces disclosure standards and fair-lending protocols that shape product design and marketing practices for deposit and credit products in the United States. The Securities and Exchange Commission governs investment-platform offerings, mandating fiduciary standards and suitability frameworks that influence fee structures and advisory hybridization. Stakeholders must monitor evolving open-banking rulemakings and embedded-finance regulatory clarifications to anticipate where data-sharing permissions and partnership liability will redistribute competitive advantage.
Market Dynamics
Open banking frameworks are dismantling data monopolies held by incumbent deposit institutions, forcing a wholesale reconfiguration of how consumer financial data flows between aggregators, lenders, and advisory platforms.
Growth Catalysts
- EU PSD2 and Open Banking Standards:Mandatory account-access APIs in the European Union have normalized real-time data portability, lowering customer acquisition costs for fintech challengers and enabling embedded finance partnerships between non-bank retailers and licensed credit providers.
- Artificial Intelligence in Underwriting:Machine-learning models trained on alternative data streams—utility payments, rental history, gig-economy income—are expanding credit access to thin-file borrowers previously excluded by FICO-centric scoring.
- Mobile-First Households in Southeast Asia:Indonesia, Vietnam, and the Philippines exhibit smartphone penetration above 75% alongside minimal legacy branch infrastructure, creating greenfield conditions for super-app financial services.
Market Restraints
- Core Banking System Modernization Costs:Tier-2 and Tier-3 institutions face capital requirements exceeding $50 million to replace COBOL-based ledger architectures with cloud-native cores capable of supporting open API ecosystems.
- Concentrated Cloud Infrastructure:Amazon Web Services, Microsoft Azure, and Google Cloud collectively host over 80% of fintech workloads, creating systemic resilience risks and vendor lock-in that complicates multi-cloud strategies.
- State-Level Licensing Fragmentation:Money Transmitter Licenses in the United States require 50-state compliance, with New York's BitLicense and California's DFPI frameworks imposing particularly burdensome capital and examination requirements.
Strategic Opportunities
- Embedded Insurance in Latin America:Brazil's regulatory sandbox under the Central Bank of Brazil permits non-insurers to distribute micro-policies through e-commerce and ride-hailing platforms, opening distribution channels previously captive to traditional agencies.
- Convergence of Buy-Now-Pay-Later and Credit Building:Point-of-sale installment providers are integrating with Experian, TransUnion, and Equifax to report repayment history, transforming deferred payment products into credit-score building tools for subprime segments.
- Wealth Transfer to Female-Led Households:Demographic projections indicate women will control the majority of investable assets in the United States by 2030, yet advisory platforms remain optimized for male decision-making patterns in risk profiling and communication cadence.
Industry Challenges
- Quantitative Risk Modeling Talent Scarcity:Demand for data scientists with expertise in survival analysis and credit risk stress-testing exceeds supply by approximately 40% in major financial centers, inflating compensation packages and slowing model deployment timelines.
- ISO 20022 Migration Complexity:Payment processors must reconcile legacy MT messaging formats with the XML-based standard for cross-border remittances, requiring simultaneous upgrades to correspondent banking relationships and treasury workstation integrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Finances Market |
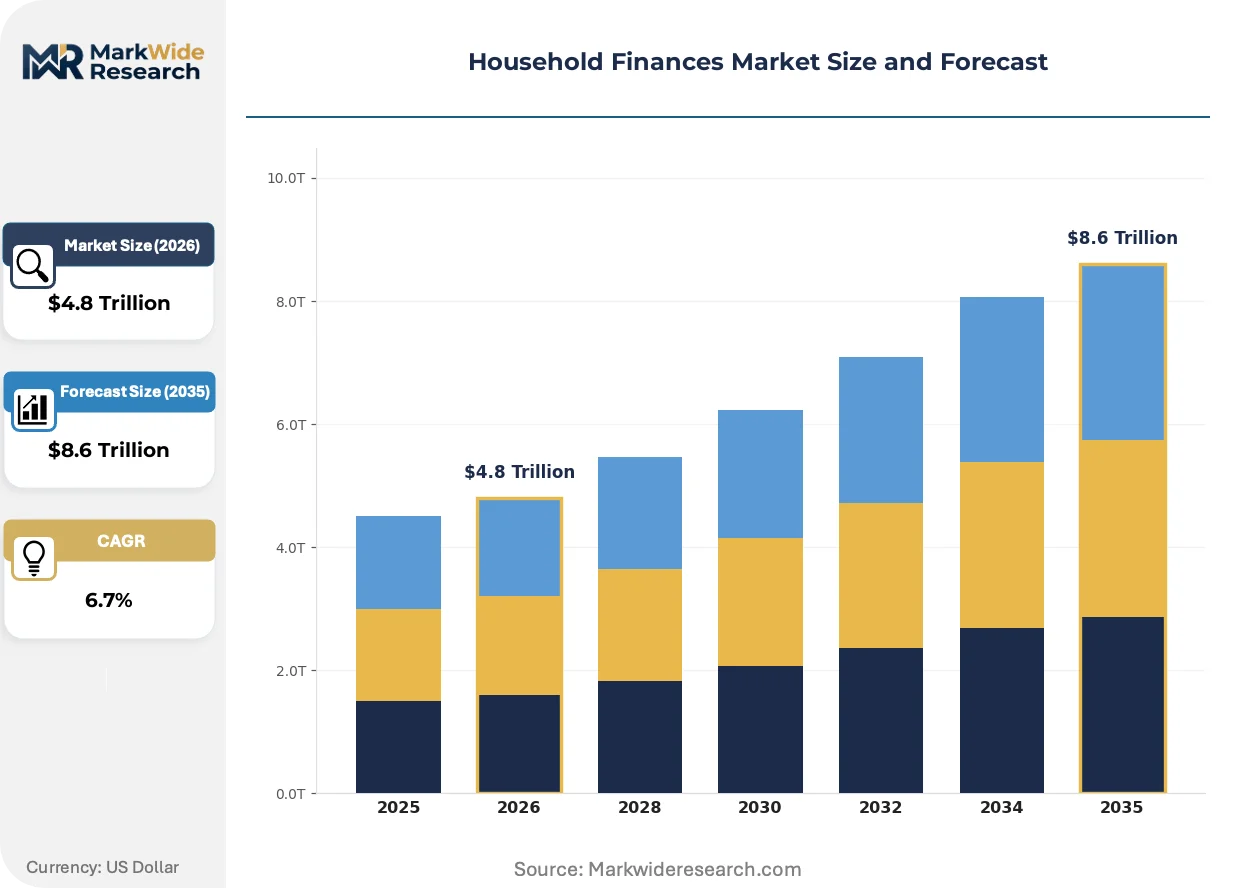
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $8.6 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Millennials, Gen X, Baby Boomers, Single Parents Service Type: Budgeting Tools, Investment Platforms, Savings Accounts, Credit Monitoring Product Type: Personal Loans, Mortgages, Insurance Products, Credit Cards Channel: Online Banking, Mobile Apps, Financial Advisors, In-Person Services |
| Companies Covered | JPMorgan Chase, Bank of America, Wells Fargo, Citigroup, U.S. Bancorp, PNC Financial Services, Truist Financial, Capital One Financial, Ally Financial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Finances Market Emerging Trajectories
Household financial management is undergoing platform unification as disparate budgeting, lending, and investment functions consolidate into integrated super-apps, compressing the addressable market for standalone point solutions.
Embedded finance infrastructure is integrating banking-as-a-service APIs directly into non-financial software ecosystems. Payroll platforms like Gusto and e-commerce backends like Shopify now offer native business checking accounts and revenue-based financing. This convergence is collapsing the distinction between financial and non-financial software procurement decisions for small-business owners.
The Consumer Financial Protection Bureau's Section 1033 rulemaking in the United States will mandate standardized data-sharing formats for deposit and credit card accounts, mirroring PSD2's European precedent. Banks must build consent-management frameworks and liability protocols for third-party data recipients. Mid-tier institutions lacking dedicated compliance technology are outsourcing these functions to specialized regtech vendors.
Subscription-based financial advisory is displacing traditional assets-under-management fee structures among mass-affluent households. Flat monthly pricing—typically $20 to $200—appeals to younger investors with lower portfolio balances but complex planning needs around student debt, equity compensation, and tax-loss harvesting. This model is gaining traction fastest in coastal United States metropolitan areas with high concentrations of technology-sector employees.
Household Finances Market Segmentation
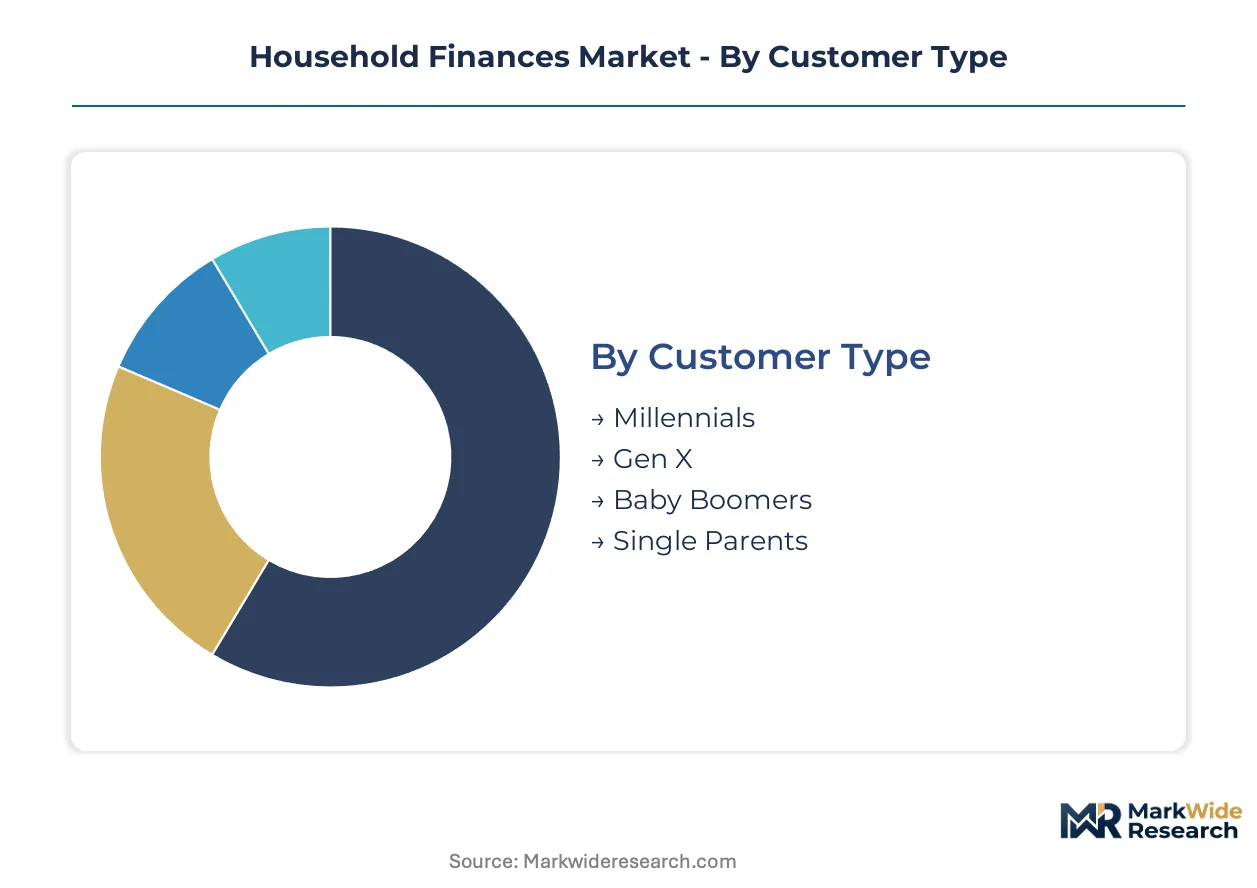
Household finances fragment across demographic cohorts, delivery mechanisms, and product architectures, each dimension commanding distinct margin profiles and technology requirements. Understanding where supply concentrates within these boundaries reveals where fintech challengers can displace incumbents versus where legacy infrastructure retains durable advantage.
Customer Type:
Provider infrastructure and customer acquisition economics concentrate heavily around digitally native cohorts, while regulatory compliance burdens shape service delivery to protected segments.
- Millennials:Digital-first households aged 28-43 drive super-app adoption for integrated budgeting, lending, and investment functions. Demand clusters in United States coastal metropolitan areas where employer-sponsored equity compensation creates complex tax-planning needs alongside student debt management.
- Gen X:Sandwich-generation households balance dependent care with retirement accumulation, generating demand for hybrid advisory models that blend automated portfolio management with human consultation on college funding and eldercare costs. This cohort commands the deepest fee pools per household.
- Baby Boomers:Wealth decumulation phase requires specialized annuity and long-term care product distribution through trusted advisory relationships.
- Single Parents:Income volatility and time constraints create demand for automated savings triggers and emergency liquidity products with streamlined underwriting.
Gen X absorbs the bulk of installed advisory capacity; Millennials are expanding most quickly across digital-native platforms.
Service Type:
Margin structure varies dramatically across service categories, with data-intensive offerings capturing recurring revenue streams while transactional tools face commoditization pressure.
- Budgeting Tools:Aggregated transaction categorization and cash-flow forecasting software that links multiple accounts through open banking APIs. Demand concentrates among United Kingdom and European Union households where PSD2 mandates enable seamless data portability between institutions.
- Investment Platforms:Self-directed brokerage and robo-advisory services with fractional share trading and automated rebalancing. This segment commands the highest customer lifetime value through assets-under-management fee structures.
- Savings Accounts:High-yield deposit products competing on annual percentage yield with minimal balance requirements.
- Credit Monitoring:Real-time score tracking and identity protection services with subscription-based pricing models.
Investment Platforms generate the dominant share of service-type revenue; Budgeting Tools show the steepest expansion trajectory as open banking penetration deepens.
Product Type:
Capital intensity and regulatory burden determine which product categories attract fintech entry versus incumbent defense.
- Personal Loans:Unsecured installment credit for debt consolidation and major purchases, underwritten through alternative data models. Demand concentrates in Germany and France where bank branch density historically limited credit access for thin-file borrowers.
- Mortgages:Long-duration secured lending with complex documentation requirements and servicing infrastructure. This category retains the highest barriers to fintech disruption due to regulatory capital requirements and escrow management complexity.
- Insurance Products:Term life, property, and micro-policies distributed through embedded finance partnerships.
- Credit Cards:Revolving credit with rewards programs and merchant interchange economics.
Mortgages lock up the majority of balance-sheet capacity; Personal Loans are gaining share fastest through algorithmic underwriting expansion.
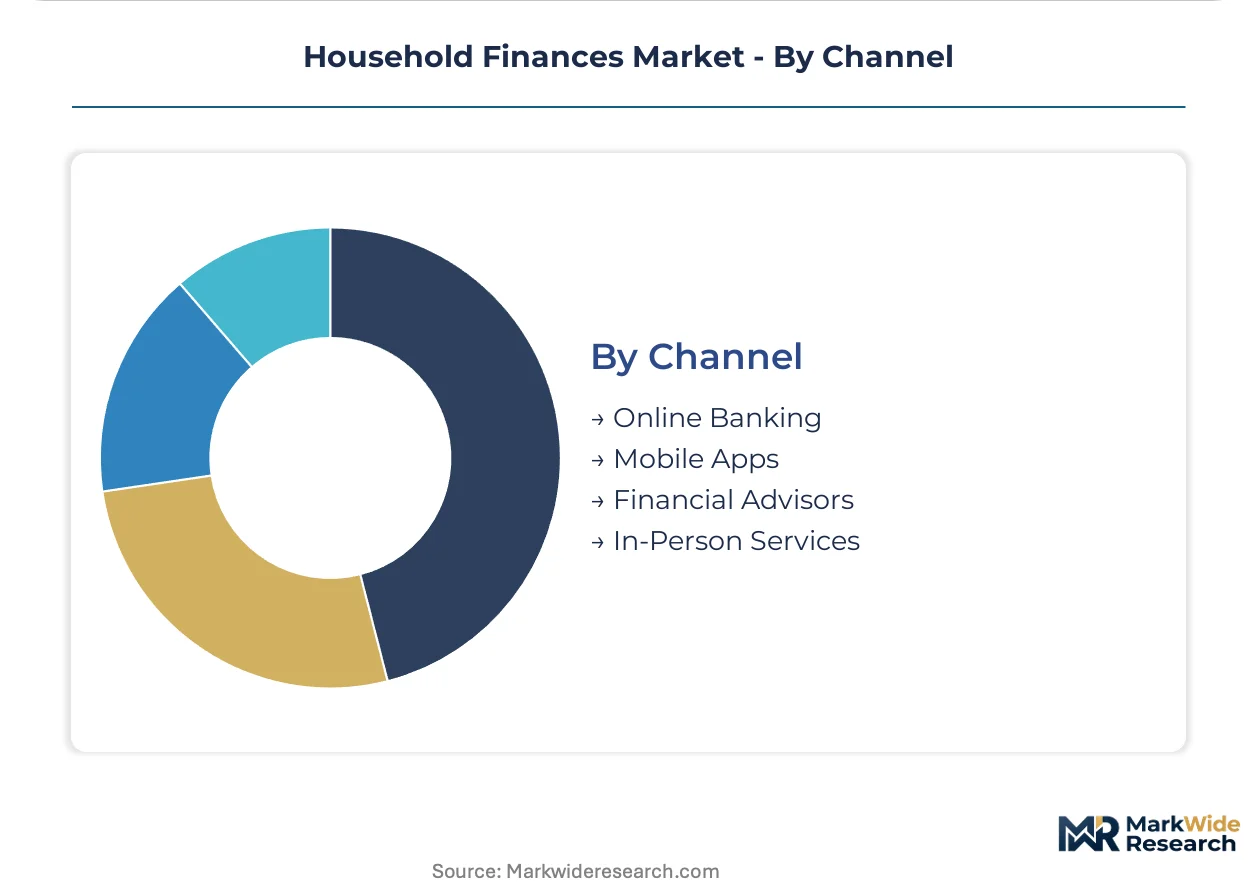
Channel:
Distribution economics have inverted as mobile infrastructure collapses the cost advantage of physical networks for routine transactions.
- Online Banking:Browser-based account management and bill payment through desktop interfaces. Demand persists among small-business owners and households managing complex multi-account relationships requiring spreadsheet export functionality.
- Mobile Apps:Native smartphone applications with biometric authentication and push-notification alerts. This channel captures the fastest-growing transaction volume as Southeast Asian and Latin American markets bypass legacy desktop infrastructure entirely.
- Financial Advisors:Licensed professionals providing holistic planning across tax, estate, and investment domains.
- In-Person Services:Branch-based consultation for complex product origination and dispute resolution.
Online Banking retains the largest active user base; Mobile Apps are climbing the fastest as smartphone penetration saturates emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors household fintech innovation density, with venture deployment clustering around digital wealth and credit infrastructure startups. Regulatory divergence across major economies is fragmenting data-sharing protocols and reshaping competitive entry costs.
United States
Employer-sponsored equity compensation and student debt burdens drive demand for integrated planning tools among coastal technology workers. The Consumer Financial Protection Bureau's Section 1033 rulemaking mandates standardized deposit account data portability, accelerating open banking adoption. New York and San Francisco metro areas concentrate robo-advisory and subscription-based financial coaching platform headquarters.
United Kingdom
PSD2-mature open banking APIs enable seamless account aggregation and cash-flow forecasting applications. The Financial Conduct Authority enforces consumer duty standards on investment platform disclosures and fee transparency. London's fintech corridor hosts incumbent bank innovation labs alongside challenger neobanks competing on savings yield and credit access.
Germany
Thin-file borrower segments and historically restrictive bank branch networks create demand for algorithmic personal loan underwriting. BaFin supervises embedded finance partnerships and banking-as-a-service licensing frameworks. Berlin and Munich clusters concentrate insurtech and automated savings trigger product development.
Brazil
Pix instant payment infrastructure and super-app financial services penetration drive mobile-first household money management adoption. The Central Bank of Brazil's regulatory sandbox permits non-insurers to distribute micro-policies through e-commerce platforms. São Paulo anchors embedded finance partnership activity between fintech infrastructure providers and retail distribution networks.
India
Jan Dhan-Aadhaar-Mobile stack penetration and UPI transaction volume growth enable digital credit scoring for previously unbanked households. The Reserve Bank of India governs account aggregator frameworks for consent-based financial data sharing. Mumbai and Bangalore clusters concentrate neobank licensing and wealth-tech platform development targeting mass-affluent millennials.
Household Finances Market Vendor Landscape
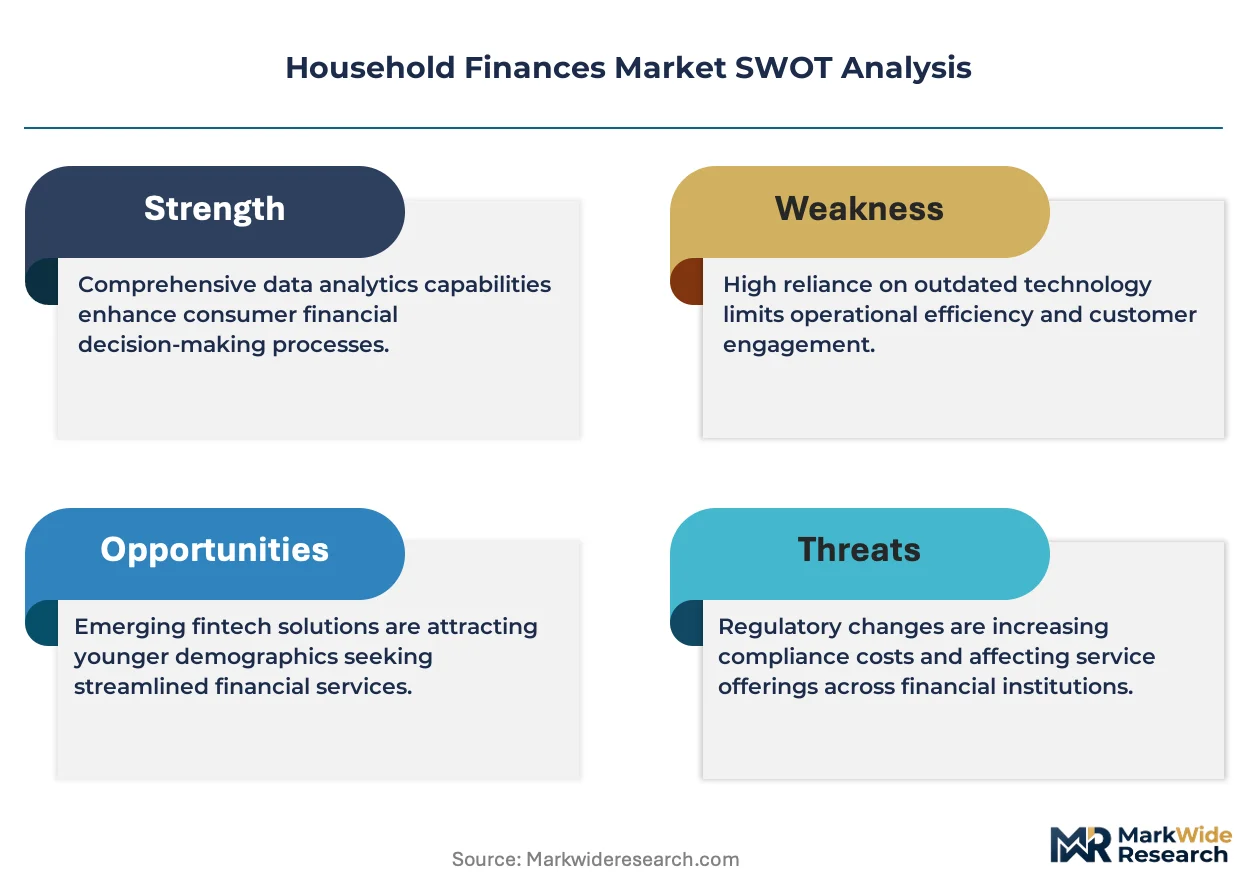
Premium-margin players sit above commodity-margin players across advisory service tiers, with white-glove private banking commanding sustained fee structures while automated platforms compress mass-market pricing. The vendor base stratifies into three tiers: universal banks with integrated wealth and deposit franchises, digital-native specialists competing on customer acquisition efficiency, and infrastructure providers enabling embedded finance distribution. Consolidation pressure operates through strategic technology acquisitions and API partnership expansion rather than horizontal merger activity.
Within the universal banking tier, JPMorgan Chase and Bank of America occupy positions spanning private wealth through mass-market digital channels, exemplifying hybrid service delivery across wealth brackets. Capital One Financial and Ally Financial represent the digital-native specialist archetype, competing through mobile-first product design and minimized physical infrastructure overhead. These four entities anchor the competitive structure, with remaining market share distributed across regional banks and emerging fintech challengers.
| Leading Market Players |
|---|
| JPMorgan Chase |
| Bank of America |
| Wells Fargo |
| Citigroup |
| U.S. Bancorp |
| PNC Financial Services |
| Truist Financial |
| Capital One Financial |
| Ally Financial |
| Others |
Supply Flow & Price Mechanics
Millennial demand for subscription-based financial coaching is compressing legacy assets-under-management fee structures and forcing providers toward flat-rate SaaS pricing models with embedded API costs. This procurement shift squeezes margin pools at traditional institutions while rewarding cloud-native challengers with lower fixed-cost bases.
Pricing Analysis
Outcome-linked pricing tied to credit-score improvement or debt-reduction targets anchors value-based fee structures in household financial services. Three-tier pricing separates white-glove hybrid advisory from automated robo-portfolios and self-directed brokerage tools. Price differentiation rests on certification depth—fiduciary advisors command 40-60 basis point premiums over suitability-standard platforms. Cost compression in mass-market tiers is intensifying because embedded finance APIs commoditize basic budgeting functionality. Small-balance households exhibit highest price sensitivity; ultra-high-net-worth segments tolerate bespoke fee arrangements.
Supply Chain Analysis
Reverse-logistics flows for physical payment cards and check stock are diminishing as digital issuance displaces plastic fulfillment networks. Core banking infrastructure concentrates in the United States, United Kingdom, and Germany where legacy COBOL modernization demands capital deployment. Cloud compute, open-banking middleware, and alternative data feeds constitute critical input dependencies. Single-source vulnerability pervades cloud infrastructure with hyperscaler concentration creating systemic resilience exposure. Distribution runs through mobile app stores and embedded finance API marketplaces rather than branch networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The household finances sector is becoming a vertical-integration race as providers pursue captive control over data infrastructure and distribution endpoints to defend margin pools.
For Market Incumbents: Deepen proprietary data asset development through first-party transaction graph construction rather than third-party aggregator dependence. Acquire consent-management technology to retain customer relationship ownership under open-banking frameworks. JPMorgan Chase's private banking infrastructure exemplifies how white-glove service layering preserves pricing power against robo-advisory compression. For New Entrants and Emerging Players: Enter via embedded finance partnerships in Latin American e-commerce and Southeast Asian super-app ecosystems where legacy branch infrastructure remains underdeveloped. Target thin-file borrower segments in Germany and France where algorithmic underwriting bypasses traditional credit scoring. White-label banking-as-a-service distribution offers lowest customer acquisition cost pathways. For Investors and Strategic Acquirers: The window for entry favors infrastructure providers with regulatory technology capabilities and alternative data sourcing networks. Long-term viability hinges on compliance automation and consent-framework ownership rather than consumer-facing brand equity. Monitor CFPB Section 1033 implementation velocity and EU PSD3 rulemaking trajectory as inflection signals for data-sharing economics redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Development | PSD2-mature European frameworks establish data portability standards that reshape competitive entry costs. |
| Embedded Finance Partnership | Non-bank retailers distributing credit through licensed provider APIs collapse traditional distribution economics. |
| Alternative Data Integration | Machine-learning models trained on utility and rental histories expand addressable borrower pools beyond FICO-centric scoring. |
| Subscription Advisory Launch | Flat monthly pricing captures mass-affluent millennials with complex planning needs around equity compensation. |
| Regulatory Technology Acquisition | Consent-management and liability-protocol automation addresses CFPB Section 1033 compliance burdens for mid-tier institutions. |
Methodological Framework
Document review covered SEC 10-K filings, CFPB enforcement actions, and EU PSD2 implementation reports, complemented by interviews with retail banking executives, fintech product managers, regulatory compliance officers, and open-banking infrastructure providers. Secondary validation drew from central bank statistical releases, venture capital deployment databases, and mobile app analytics platforms. Bottom-up customer cohort sizing and top-down macroeconomic anchoring were triangulated against disclosed AUM flows and deposit growth rates.
Market size outputs reflect segment-level modeling across customer type, service type, product type, and channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical fintech penetration curves against smartphone adoption saturation and open-banking regulatory implementation timelines. Forecast inputs incorporated interest rate scenario sensitivity and credit cycle positioning.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid regulatory harmonization or systemic cloud infrastructure disruption scenarios. Practitioners should monitor CFPB rulemaking velocity, EU PSD3 proposal advancement, and hyperscaler concentration policy developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Finance and Financial Planning
Global Personal Loans Market
Personal Finance and Financial Planning
Global Financial Planning Software Market
Personal Finance and Financial Planning
Account Planning Tool Market
Personal Finance and Financial Planning
Global Personal Finance Tools and Market
Personal Finance and Financial Planning
Debt Settlement Market
Personal Finance and Financial Planning
Global Financial Wellness Software Market
Personal Finance and Financial Planning
Personal Finance Software Market
Personal Finance and Financial Planning
China Financial Planning Software Market
Personal Finance and Financial Planning
Credit Scores, Credit Reports and Credit Check Services Market
Personal Finance and Financial Planning
Renters Insurance Market
Personal Finance and Financial Planning
Financial Calculators Market