
 North America Trade Finance Market | 2026-2036
North America Trade Finance Market Size, Share, and Industry Trends Forecast 2026-2036
North America Trade Finance Market Insights
Supply chain finance origination is reconfiguring margin pools away from traditional letter-of-credit issuance toward dynamic discounting and payables finance platforms. JPMorgan Chase & Co. leverages its corporate treasury relationships to anchor large-enterprise invoice financing volumes across the United States. Wells Fargo & Co. sustains dominant positioning in SME-focused documentary credit products through its branch network density in the Southwest and Midwest.
Trade finance encompasses structured instruments—letters of credit, bank guarantees, supply chain finance, and factoring—that mitigate counterparty risk and bridge payment timing gaps in international and domestic goods transactions, typically governed by Uniform Customs and Practice for Documentary Credits or Uniform Commercial Code Article 5 protocols. Its primary commercial purpose is to substitute bank creditworthiness for buyer credit risk, enabling sellers to ship goods before receiving payment while preserving buyer leverage to inspect documents. Supply chain finance now leads product-type revenue generation as buyers extend payment terms and suppliers seek early liquidity without degrading balance-sheet ratios. Invoice financing within service-type categories captures the fastest expansion, driven by API-enabled platform integration with enterprise resource planning systems that automate receivables verification.
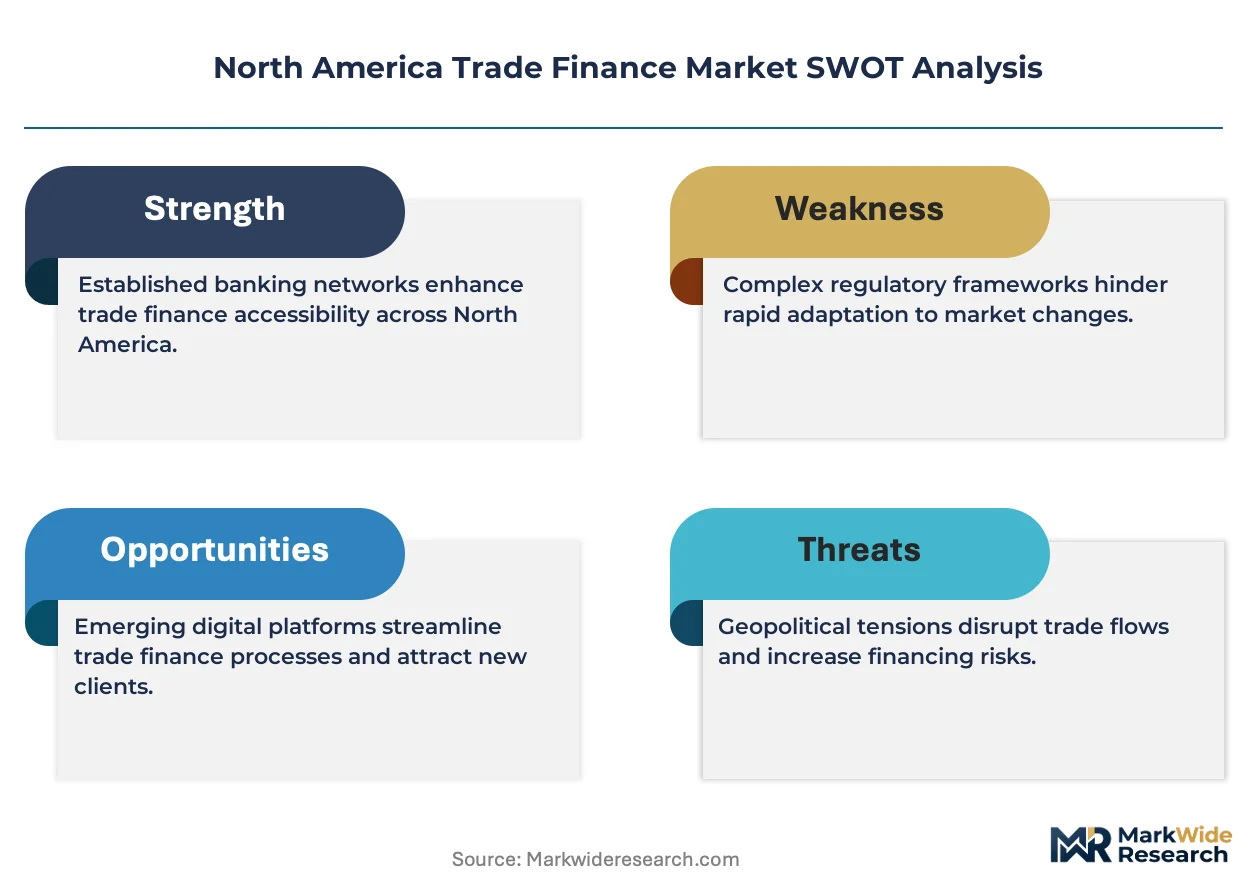
The Office of the Comptroller of the Currency supervises national bank trade-finance capital reserves, while the Financial Crimes Enforcement Network enforces anti-money-laundering documentation standards that lengthen onboarding cycles for new trade clients. The Uniform Commercial Code's Article 5 variations across US states create compliance fragmentation that elevates legal costs for multi-jurisdictional programs. Stakeholders must monitor whether proposed Basel III endgame revisions recalibrate risk-weighted asset treatments for off-balance-sheet trade exposures, as this would directly alter pricing economics for banks competing in documentary credit and guarantee issuance.
Market Dynamics
Supply chain finance platforms are digitizing receivables verification through ERP-integrated APIs, compressing origination timelines from weeks to hours and reconfiguring margin pools away from traditional documentary credit instruments.
Growth Catalysts
- USMCA Rules-of-Origin Updates:The revised trade agreement's stricter regional content requirements are generating fresh documentary demand as manufacturers requalify supply chains across the United States, Mexico, and Canada.
- Reshoring Manufacturing Clusters:Semiconductor and automotive production expansion in Texas and California is concentrating working-capital needs among mid-market suppliers seeking invoice financing.
- API-Enabled Receivables Automation:Real-time data exchange between enterprise resource planning systems and finance platforms is accelerating supplier onboarding and reducing verification costs.
Market Restraints
- Basel III Endgame Uncertainty:Proposed risk-weighted asset recalibrations for off-balance-sheet trade exposures threaten to elevate capital charges and compress bank pricing power in guarantee issuance.
- Fragmented UCC Article 5 Compliance:State-by-state variations in documentary credit law create legal friction that elevates multi-jurisdictional program costs for national lenders.
- AML Documentation Burden:FinCEN's enhanced customer due diligence requirements lengthen onboarding cycles and raise compliance overhead for new trade relationships.
Strategic Opportunities
- Mexican Nearshoring Corridors:Industrial park development in Nuevo León and Baja California is creating concentrated demand for cross-border supply chain finance among first-time exporters.
- Dynamic Discounting Platforms:Early-payment programs embedded within procurement systems offer white-space expansion beyond traditional bank-led supply chain finance.
- Canadian SME Digitization:Underpenetrated documentary credit usage among Atlantic Canada and Prairie region exporters presents platform-led acquisition potential.
Industry Challenges
- Trade Finance Talent Scarcity:Documentary credit specialists with Uniform Customs and Practice expertise are retiring faster than apprenticeship programs replenish the pipeline.
- Legacy System Integration:Core banking infrastructure at regional lenders lacks API compatibility with emerging supply chain finance platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Trade Finance Market |
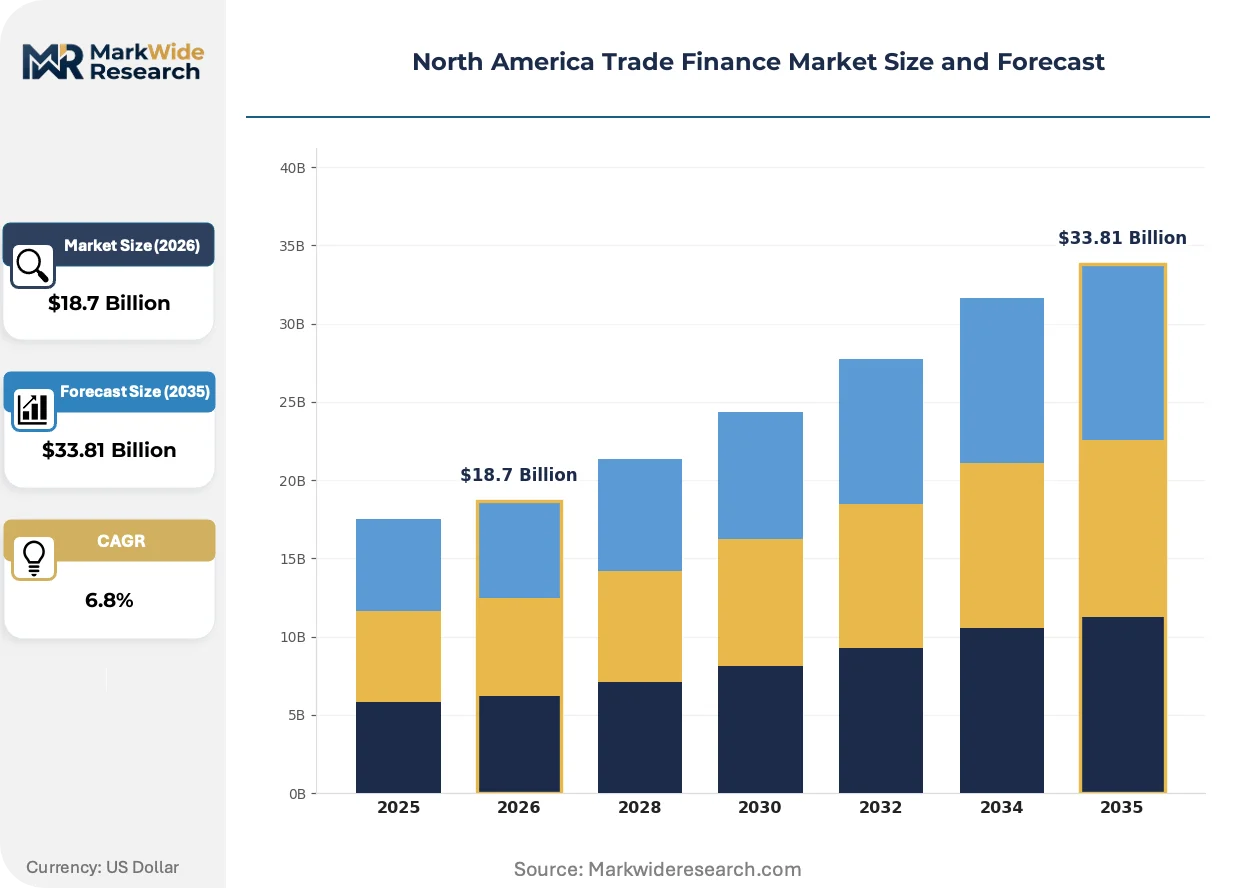
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Letter of Credit, Bank Guarantees, Supply Chain Finance, Factoring Service Type: Documentary Credit, Risk Mitigation, Payment Services, Invoice Financing Customer Type: SMEs, Large Enterprises, Corporations, Governments Transaction Size: Small Value, Medium Value, Large Value, High-Value |
| Companies Covered | Wells Fargo & Co., BNP Paribas S.A., JPMorgan Chase & Co., Santander Bank, TD Bank Group, Bank of America Corporation, HSBC Holdings plc, Deutsche Bank AG, Citigroup Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Trade Finance Market Trends and Innovations
Distributed ledger and artificial intelligence applications are compressing verification timelines and automating compliance checks across the trade finance value chain.
Blockchain-based trade documentation is digitizing letter-of-credit processing through immutable bill-of-lading and invoice records. Large commodity importers in the United States are piloting smart-contract settlement to reduce documentary discrepancy rates. This technology is digitizing the multi-party verification workflow that previously required sequential manual checks across banks, shippers, and insurers.
The Office of the Comptroller of the Currency is scrutinizing bank-fintech partnership models for trade finance origination. National banks must now demonstrate operational control over customer identification and sanctions screening when leveraging third-party platforms. Mid-sized regional lenders in the Southwest are responding by building captive technology capabilities rather than outsourcing to unregulated vendors.
Buyers in automotive and electronics verticals are unbundling payment terms from purchase orders to capture supplier discounts. Procurement teams now negotiate early-payment programs separately from base pricing, treating finance as a distinct spend category. This behavior is most visible among Fortune 500 manufacturers with centralized treasury operations in Michigan and Ohio.
North America Trade Finance Market Segmentation
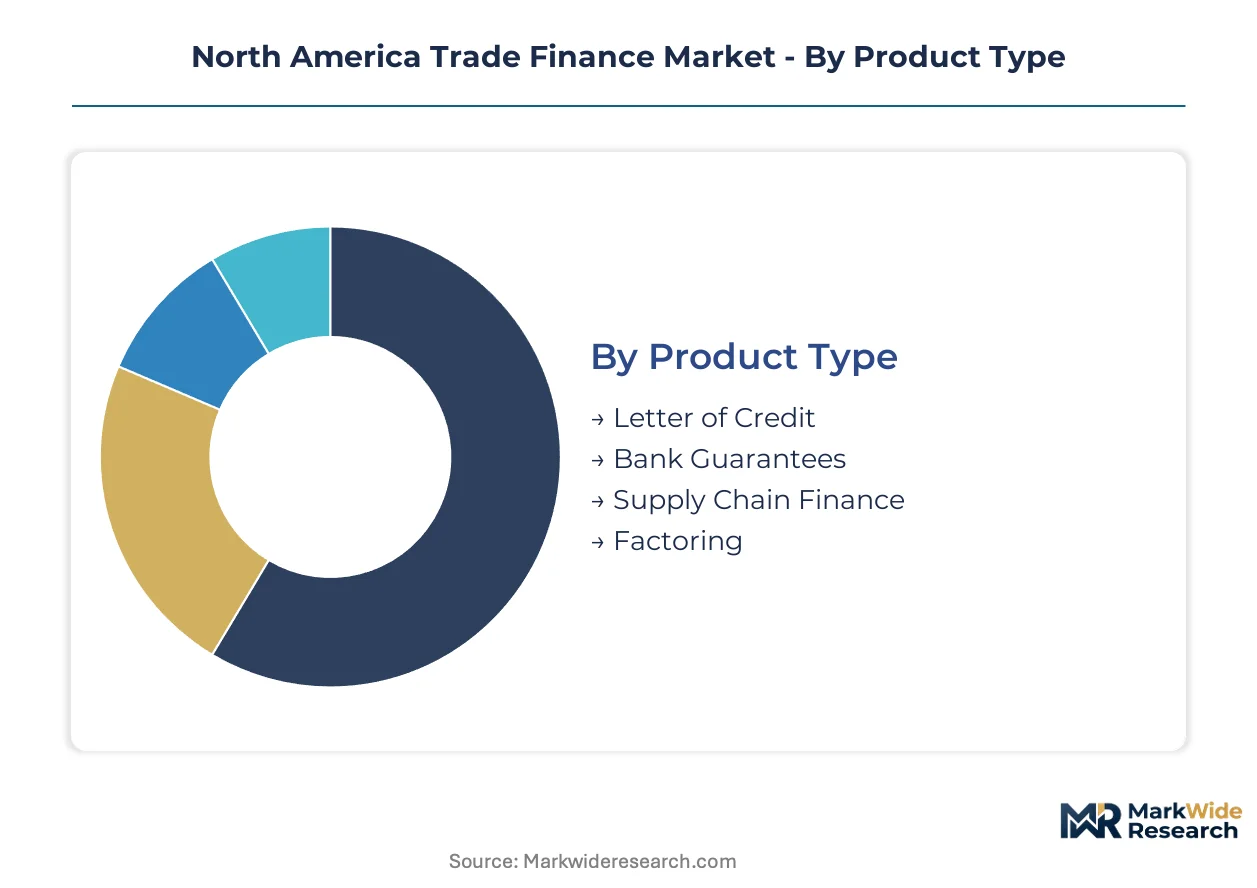
Trade finance instruments vary dramatically in origination velocity and documentation burden. Segment-level cycle times determine working capital efficiency for buyers and liquidity access for suppliers across North American supply chains.
Product Type:
Supply chain finance compresses origination to hours while letters of credit retain multi-week documentary cycles.
- Letter of Credit:Documentary instruments governed by UCP 600 protocols require sequential verification across issuing banks, advising banks, and shipping agents. Automotive and heavy machinery exporters in Michigan and Ohio anchor demand as they manage counterparty risk across extended production timelines.
- Supply Chain Finance:Reverse-factoring platforms integrate directly with enterprise procurement systems, enabling buyers to extend payment terms while suppliers capture early liquidity. Texas-based semiconductor manufacturers and California electronics assemblers are concentrating adoption as reshoring accelerates component sourcing cycles.
- Bank Guarantees:Standby instruments backing performance obligations in construction and energy projects carry longer tenors and infrequent drawdown events.
- Factoring:True-sale receivables purchases by specialized finance companies serve SME freight carriers and agricultural distributors with rapid documentation turnaround.
Letter of credit anchors the volume base while supply chain finance gains share at the steepest rate.
Service Type:
Cost tiers separate premium advisory services from standardized payment processing.
- Invoice Financing:API-enabled verification against ERP data is compressing onboarding from weeks to days. Mid-market suppliers in Nuevo León industrial corridors and Baja California maquiladoras are driving cross-border adoption as Mexican nearshoring accelerates.
- Documentary Credit:Traditional LC issuance and negotiation services command premium pricing due to specialized UCP expertise requirements. Large commodity traders in Houston and Vancouver sustain volume concentration despite margin compression from digitization.
- Risk Mitigation:Political risk insurance and credit default protection products carry higher advisory fees and longer structuring timelines.
- Payment Services:Standardized wire and draft processing operate at thin margins with high velocity and minimal human intervention.
Payment services anchor the volume base while invoice financing climbs the fastest.
Customer Type:
Application intensity varies across entity scale and treasury sophistication.
- Large Enterprises:Centralized procurement and treasury operations at Fortune 500 manufacturers embed supply chain finance into ERP workflows. Automotive OEMs in Detroit and technology hardware assemblers in Austin are unbundling payment terms from purchase orders to capture supplier discounts.
- SMEs:Fragmented credit needs and limited collateral access drive reliance on factoring and government-backed guarantee programs. Southwestern US agricultural exporters and Prairie region Canadian manufacturers face onboarding friction from FinCEN documentation requirements.
- Corporations:Multi-divisional entities with decentralized purchasing require customized program structures across business units.
- Governments:Sovereign and municipal procurement operates under distinct bidding and payment protocols with extended settlement cycles.
SMEs anchor the volume base while large enterprises expand program adoption most aggressively.
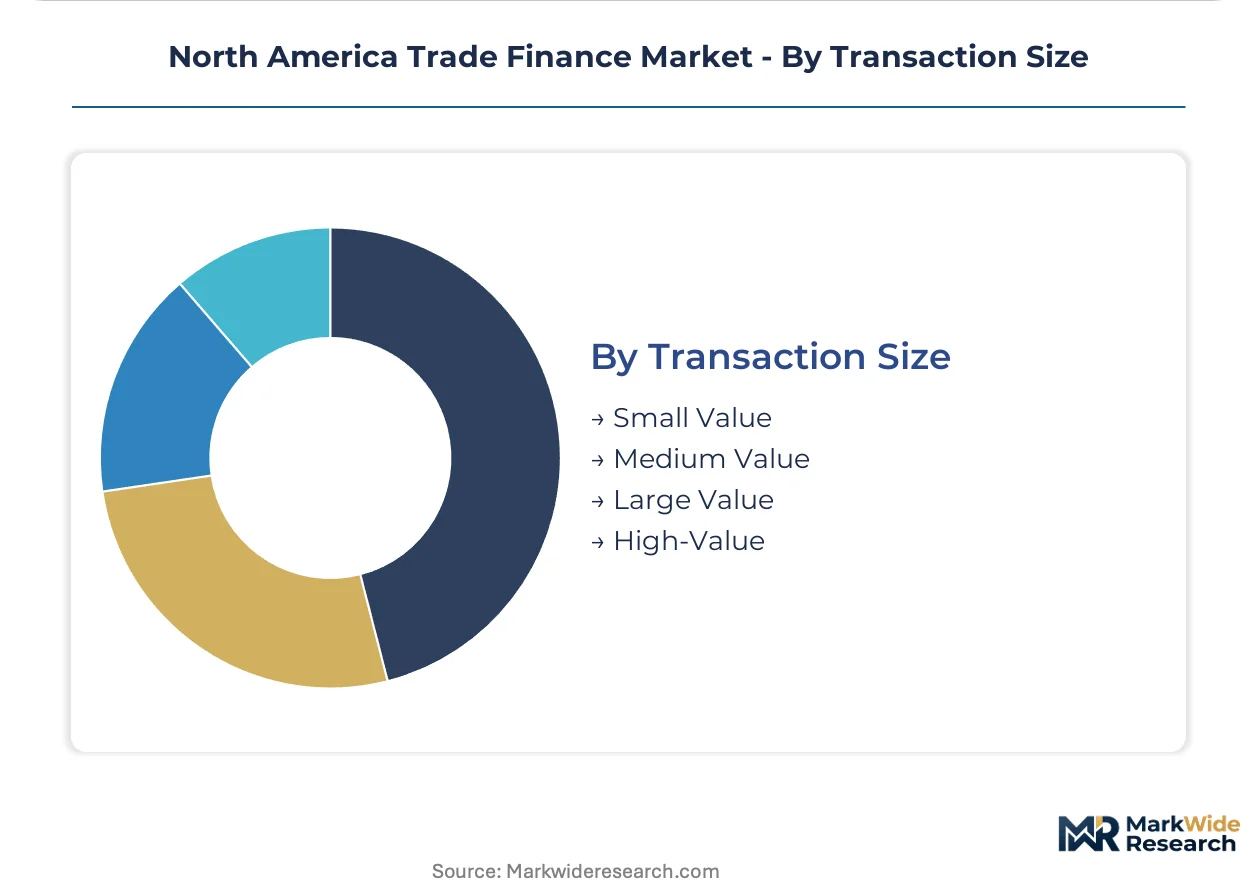
Transaction Size:
Margin structures stratify across value thresholds and operational complexity.
- Large Value:Transactions exceeding ten million dollars in underlying goods value attract concentrated bank competition and bespoke structuring. Energy sector importers in Houston and mining equipment exporters in Vancouver sustain this tier through commodity-linked trade flows.
- Medium Value:One-to-ten million dollar ranges balance standardization with relationship-based pricing. Mid-market automotive suppliers in Ontario and electronics contract manufacturers in Tijuana concentrate demand as USMCA rules-of-origin compliance intensifies.
- Small Value:Sub-million dollar transactions face unit-cost constraints that platform automation is beginning to address.
- High-Value:Specialized aircraft, maritime vessel, and infrastructure equipment financing operates on multi-year tenors with complex collateral structures.
Medium value transactions anchor the volume base while large value transactions capture the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade finance consumption patterns diverge sharply across the tri-national region: United States buyers prioritize supply chain finance platforms integrated with ERP systems, while Mexican and Canadian counterparts maintain heavier reliance on traditional documentary credit instruments for cross-border risk mitigation.
United States
Semiconductor reshoring in Texas and automotive production expansion in Michigan are concentrating working-capital demand among mid-market suppliers. The Office of the Comptroller of the Currency supervises national bank capital reserves for trade exposures, creating compliance uniformity absent in other jurisdictions. Houston energy traders and Los Angeles electronics importers sustain large-value letter-of-credit volume despite accelerating platform adoption elsewhere.
Mexico
Nearshoring industrial corridors in Nuevo León and Baja California are generating first-time exporter demand for cross-border supply chain finance. Mexico's central bank, Banco de México, maintains foreign exchange stability mechanisms that reduce hedging costs for peso-denominated trade settlements. Maquiladora operators in Tijuana and Monterrey manufacturing parks are transitioning from open-account terms to structured receivables financing as USMCA compliance intensifies.
Canada
Atlantic Canada and Prairie region exporters show underpenetrated documentary credit usage relative to Ontario and Quebec peers, presenting platform-led acquisition opportunities. Export Development Canada provides government-backed guarantee programs that compete with private bank offerings for SME segments. Vancouver mining equipment exporters and Toronto commodity traders anchor the large-value transaction tier through commodity-linked trade flows.
California
Port volumes at Los Angeles and Long Beach are generating concentrated invoice financing demand among freight forwarders and customs brokers. California's Department of Financial Protection and Innovation maintains distinct fintech licensing requirements that lengthen third-party platform deployment timelines. Technology hardware assemblers in Silicon Valley and Central Valley agricultural exporters exhibit divergent instrument preferences—platform finance versus traditional documentary credit.
Texas
Manufacturing reshoring in Austin and Dallas-Fort Worth is driving supply chain finance adoption among electronics and defense contractors. The Texas Department of Banking regulates state-chartered institutions offering trade finance products, creating dual-track compliance for national bank competitors. Houston energy sector importers sustain bespoke guarantee structuring for multi-year equipment procurement contracts.
North America Trade Finance Market Competitive Landscape
Capability concentration sits with global money-center banks possessing corporate treasury relationships; scale advantage sits with regional lenders leveraging branch density for SME documentary credit origination. The market structures around three tiers: universal banks anchoring large-enterprise supply chain finance, superregional banks dominating mid-market letter-of-credit issuance, and specialized factors serving freight and agricultural distributors. Consolidation pressure is intensifying through technology partnerships and captive platform development rather than outright acquisition.
Among universal bank operators, JPMorgan Chase & Co., Wells Fargo & Co., and Citigroup Inc. exemplify divergent strategic positioning within the North American trade finance architecture. JPMorgan Chase & Co. occupies a position anchored by corporate treasury relationships that generate large-enterprise invoice financing volume. Wells Fargo & Co. represents the branch-density archetype, sustaining documentary credit market presence through physical network coverage in the Southwest and Midwest. Citigroup Inc. sits within the international connectivity tier, leveraging correspondent banking infrastructure for cross-border guarantee issuance.
| Leading Market Players |
|---|
| Wells Fargo & Co. |
| BNP Paribas S.A. |
| JPMorgan Chase & Co. |
| Santander Bank |
| TD Bank Group |
| Bank of America Corporation |
| HSBC Holdings plc |
| Deutsche Bank AG |
| Citigroup Inc. |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure under USMCA rules-of-origin recalibration determines both pricing tier spreads and supply chain shape across North American trade finance origination. Buyers extending payment terms through dynamic discounting platforms capture supplier discounts that compress traditional documentary credit margins, while regional concentration in Texas and California manufacturing clusters amplifies working-capital pricing power for platform-integrated lenders.
Pricing Analysis
Long-term offtake contracts anchor large-value guarantee structuring for Houston energy importers and Vancouver mining equipment exporters, while spot transactional pricing dominates SME factoring and freight-forwarder invoice financing. Price differentiation hinges on UCP 600 certification tier and API-enabled ERP integration depth, with premium advisory services commanding spreads above standardized payment processing. Cost compression in mid-market supply chain finance is intensifying because JPMorgan Chase and Wells Fargo compete for corporate treasury relationships through embedded procurement system partnerships. SME agricultural exporters in the Prairie regions exhibit highest price sensitivity due to fragmented collateral access, while Fortune 500 automotive OEMs in Detroit demonstrate lowest sensitivity given centralized treasury sophistication.
Supply Chain Analysis
Contract-manufacturing concentration among Nuevo León industrial park operators and Baja California maquiladoras anchors cross-border receivables origination capacity. Geographic supply concentration rests on Mexico for nearshoring assembly, the United States for semiconductor fabrication reshoring, and Canada for Prairie region agricultural distribution. Raw material dependencies draw from Texas petrochemical feedstocks, California rare-earth component inflows, and Ontario automotive steel inputs. Single-source vulnerability runs through ERP-integrated platform providers that intermediate bank-fintech partnerships under OCC supervision. Distribution runs through Los Angeles and Long Beach port corridors for Pacific Rim electronics, Houston energy trading hubs for commodity-linked guarantees, and Detroit-Toronto automotive supplier networks for USMCA-compliant documentary cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent banks must defend against fintech platform substitution that disintermediates traditional documentary credit relationships through API-enabled receivables automation. The threat of unregulated vendor capture in supply chain finance origination demands preemptive capability investment.
For Market Incumbents: Pre-empt fintech encroachment by building captive ERP-integrated platforms rather than outsourcing to third-party vendors under OCC scrutiny. Fortify UCP 600 specialist talent pipelines through apprenticeship programs that address documentary credit expertise attrition. Vertical integration into dynamic discounting procurement systems represents the critical defensive lever against platform-led margin compression in large-enterprise segments.
For New Entrants and Emerging Players: Atlantic Canada and Prairie region SME exporters present the most penetrable white-space for platform-led documentary credit acquisition given underpenetrated adoption relative to Ontario peers. Mexican first-time exporters in Nuevo León industrial corridors offer concentrated cross-border supply chain finance demand as USMCA compliance intensifies. A go-to-market angle anchored in Spanish-language onboarding and peso-denominated settlement mechanisms through Banco de México partnerships differentiates against incumbent branch-network dependency.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technology-enabled regional lenders with captive platform capabilities over legacy documentary credit specialists. Long-term viability across the five-to-ten year window hinges on API infrastructure investment and regulatory compliance automation rather than balance-sheet scale alone. Acquisition targets should demonstrate OCC-supervised operational control over customer identification and sanctions screening. The signal to watch is Basel III endgame risk-weighted asset recalibration for off-balance-sheet trade exposures, which would alter pricing economics for guarantee issuance.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Enabled Platform Integration | OCC-supervised ERP connectivity accelerates supplier onboarding while reducing FinCEN documentation friction for mid-market segments. |
| Dynamic Discounting Program Launch | Procurement-embedded early payment captures supplier discounts that displace traditional bank-led supply chain finance margins. |
| UCP 600 Certification Investment | Documentary credit expertise retention addresses talent scarcity as specialist retirements outpace apprenticeship replenishment. |
| Nearshoring Corridor Expansion | Nuevo León and Baja California industrial park presence captures first-time exporter demand under USMCA rules-of-origin compliance. |
| Captive Technology Development | In-house platform capabilities avoid third-party vendor operational control scrutiny from the Office of the Comptroller of the Currency. |
Research Methodology
Desk research of Uniform Customs and Practice for Documentary Credits protocol documentation, OCC supervisory guidance releases, and FinCEN anti-money-laundering enforcement actions preceded structured interviews with trade finance product heads at national banks, documentary credit operations specialists, corporate treasury managers at Fortune 500 manufacturers, and compliance officers overseeing sanctions screening programs. Secondary validation drew from SEC 10-K trade finance revenue disclosures, Banco de México foreign exchange stability reports, and USMCA rules-of-origin regulatory filings. Bottom-up origination volume estimates by product type and customer segment were triangulated against top-down market sizing derived from bank regulatory capital filings.
Assumptions regarding USMCA implementation continuity, Basel III endgame finalization trajectory, and API platform adoption curves were held fixed across baseline scenarios while stress-testing incorporated alternative regulatory capital treatment and fintech partnership model disruption. Segmentation modeling spanned product type, service type, customer type, transaction size, and regional regulatory cluster dimensions. CAGRs were derived from logistic diffusion curves fitted to historical origination velocity data and projected ERP integration penetration rates across automotive and electronics verticals. Forecast inputs incorporated semiconductor reshoring capital expenditure announcements and Mexican nearshoring industrial park development pipelines.
Practitioners should monitor OCC guidance on bank-fintech partnership operational control, FinCEN documentation requirement amendments, and Basel III endgame risk-weighted asset calibrations for early signals of forecast revision. Quarterly review of port volume data from Los Angeles and Long Beach, USMCA rules-of-origin qualification rates, and regional bank trade finance capital reserve disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Global Financial Consulting Software Market
Financial Services
China Factoring Services Market
Financial Services
Silver Economy Market
Financial Services
Saas Escrow Services Market
Financial Services
Factoring Services Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
ATM Software Market
Financial Services
United States Payroll Services Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Online Sports Betting Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Islamic Finance Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
North America B2C Legal Services Market
Financial Services
Global Alternative Data Market
Financial Services
India Trade Finance Market