
 Africa Virtual Cards Market | 2026-2036
Africa Virtual Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Virtual Cards Market Analytics
Market Context
Subscription-based card provisioning is shifting how virtual card revenue gets captured across African fintech ecosystems. Visa leverages its tokenization infrastructure to anchor digital payment rails in multiple markets. Flutterwave competes through localized API stacks that embed virtual issuance into merchant workflows. Safaricom dominates mobile-money-linked card distribution through its M-Pesa ecosystem in East Africa.
Technical Definition and Segments
Africa virtual cards are digitally generated payment credentials with 16-digit PANs, CVV codes, and expiration dates delivered via mobile application or API, designed for single-use or limited-duration transactions without physical plastic production. Their primary commercial purpose centers on reducing fraud exposure for e-commerce merchants and enabling financial inclusion for populations lacking traditional banking access. Prepaid virtual cards lead transaction volume among unbanked consumers, while corporate virtual cards capture expanding B2B transaction flows as enterprises seek spend-control tools. Wallet integration technology anchors the fastest-growing deployment channel, though QR code acceptance still lags merchant infrastructure in Francophone markets.
Regulatory Environment
Nigeria's Central Bank enforces tiered KYC requirements that shape virtual card issuance limits and customer onboarding flows. South Africa's Financial Sector Conduct Authority and Kenya's Central Bank govern electronic money licensing, directly determining which fintechs may issue payment credentials. Stakeholders must monitor how cross-border data localization mandates and open banking frameworks alter platform economics for card orchestration services.
Market Dynamics
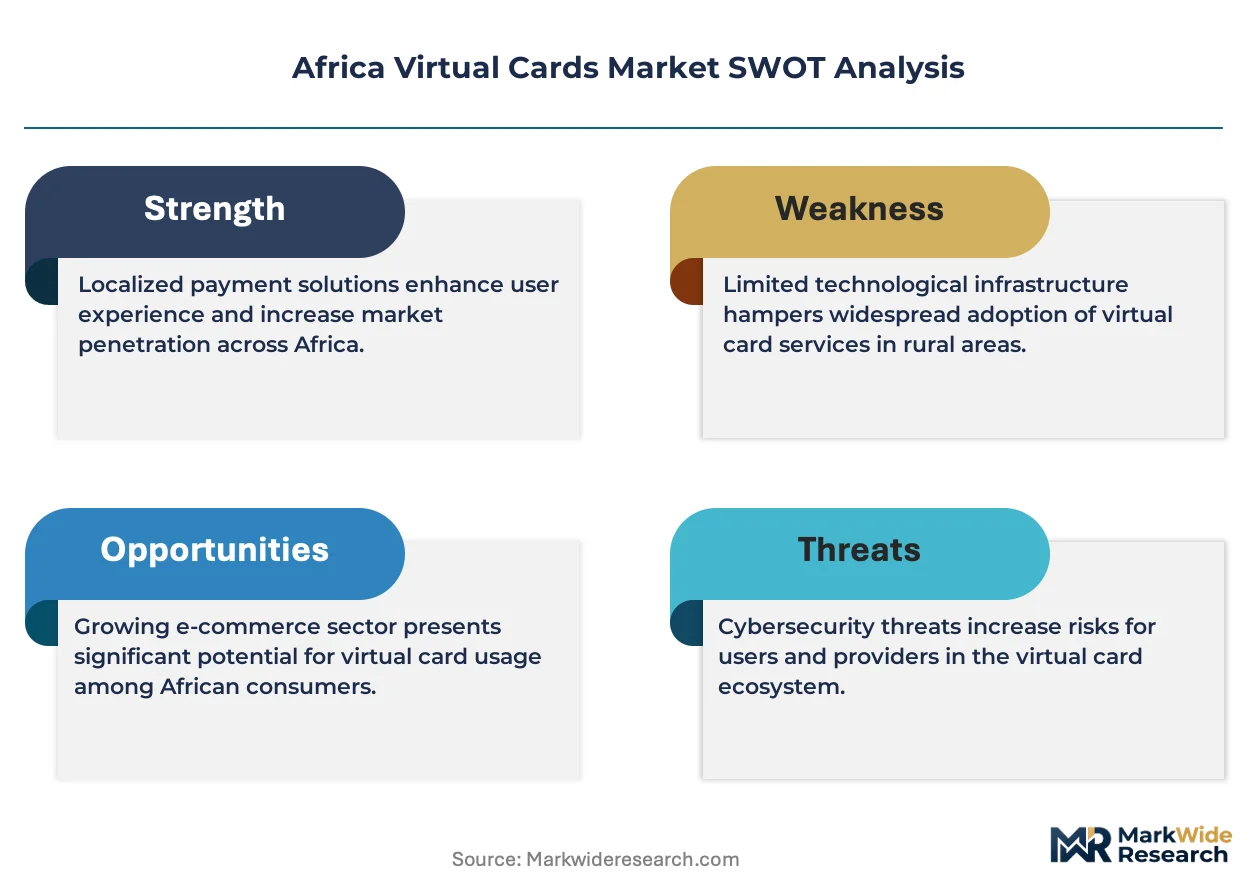
Mobile wallet integration is concentrating virtual card distribution through platform-specific ecosystems, locking in unbanked users via M-Pesa-style closed-loop architectures that reshape issuer economics across the continent.
Growth Catalysts
- Nigeria's Central Bank cashless policy:Tiered KYC requirements accelerate formal financial inclusion by lowering onboarding barriers for virtual issuance. Merchant acceptance infrastructure expands in Lagos and Abuja commercial corridors.
- Prepaid credential technology:Single-use PAN generation reduces fraud exposure for e-commerce transactions. Unbanked consumers in Kenya access cross-border payments without traditional account relationships.
- Wallet-linked distribution channels:API-based provisioning embeds virtual cards directly into mobile money applications. South African fintechs leverage this integration for real-time salary disbursement products.
Market Restraints
- Merchant infrastructure gaps:QR code acceptance networks remain underdeveloped in Francophone West African markets. Côte d'Ivoire and Senegal lag Anglophone peers in point-of-sale digitization.
- Foreign exchange volatility:Naira and Rand depreciation compresses cross-border transaction margins. Issuers absorb currency conversion costs that plastic card networks historically passed to consumers.
- Data localization mandates:Nigeria's central bank requires domestic server hosting for transaction records. Pan-African platforms face fragmentation costs from divergent national storage requirements.
Strategic Opportunities
- Ethiopian market opening:Telebirr mobile money platform creates virgin territory for virtual card overlay products. The central bank's liberalization of digital payments invites first-mover positioning.
- B2B spend control tools:Corporate virtual cards capture enterprise procurement workflows. Nigerian and South African multinationals seek programmable credential limits for departmental budgets.
- Open banking frameworks:Kenya's API standards for account aggregation enable card orchestration services. Third-party providers can now initiate payments across previously siloed banking infrastructure.
Industry Challenges
- Tokenization certification timelines:Visa and Mastercard compliance audits delay product launches by 8-14 months for new African entrants. Technical integration costs disproportionately burden mid-tier fintechs.
- Legacy core banking integration:Traditional institutions resist API connectivity that would enable virtual card issuance. Their COBOL-based infrastructure requires expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Virtual Cards Market |
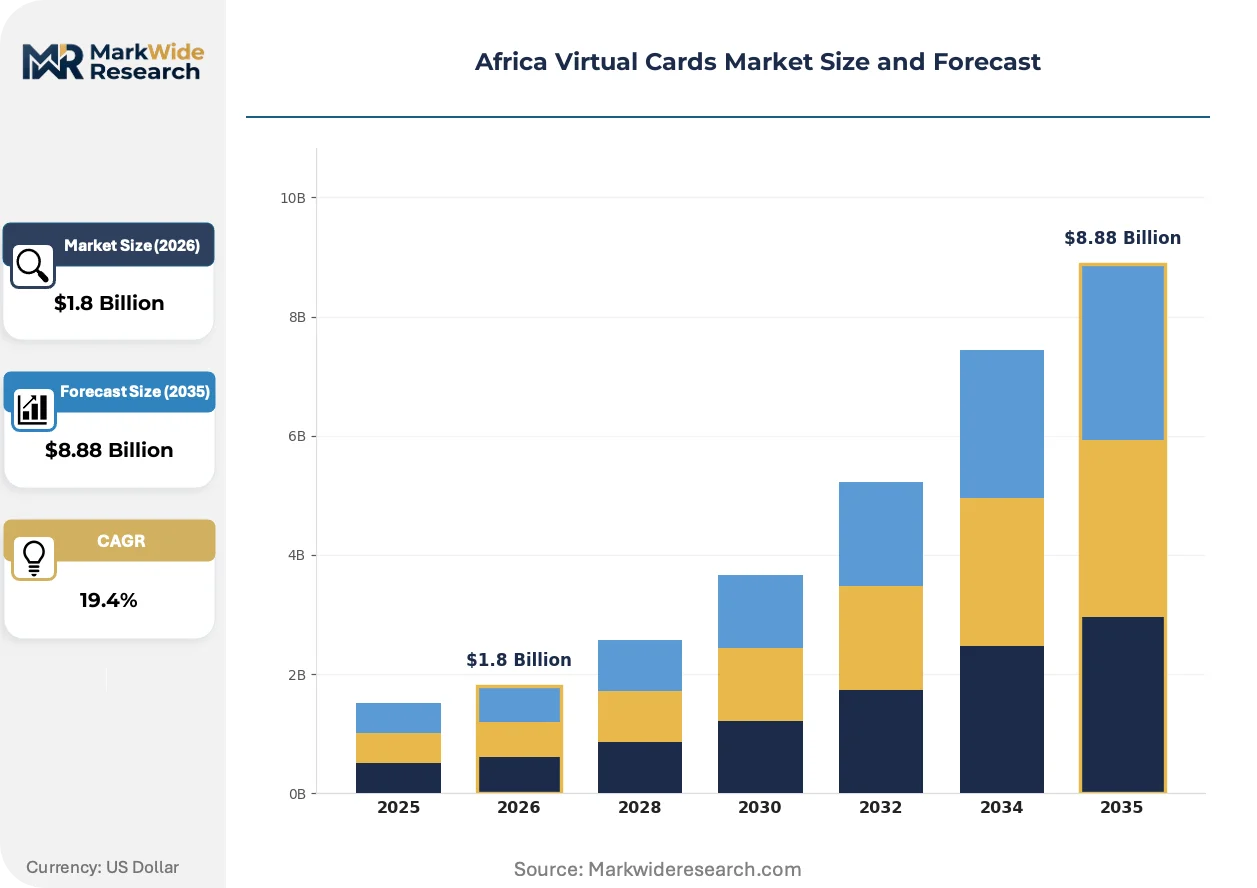
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Prepaid, Debit, Corporate, Gift Application: E-commerce, Subscription Services, Travel, B2B Transactions Customer Type: Individuals, Small Businesses, Enterprises, Startups Technology: Wallet Integration, QR Code, NFC, Mobile App |
| Companies Covered | Visa, Mastercard, UnionPay International, Interswitch, Flutterwave, MTN, Safaricom, Airtel Africa, Fawry, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Virtual Cards Market Evolving Landscape
Tokenization infrastructure is reshaping how payment credentials circulate across African digital economies, compressing fraud vectors while enabling new issuer-audience relationships previously blocked by physical distribution costs.
Dynamic CVV generation is expanding into high-velocity e-commerce merchant categories as a fraud mitigation layer. Nigerian online retailers adopt this technology to reduce chargeback rates on cross-border transactions. The structural consequence is that single-use credential providers are capturing merchant processing fees that static virtual card issuers previously dominated.
South Africa's Financial Sector Conduct Authority licensing requirements for electronic money institutions now mandate segregated customer fund protection. This regulatory architecture forces virtual card providers to restructure treasury operations around ring-fenced liquidity pools. B2B corporate issuers face the steepest compliance adaptation costs as they retrofit spend-management platforms to meet custody rules.
Subscription-based provisioning models are displacing per-transaction fees among East African fintechs. Kenyan M-Pesa ecosystem partners now bundle virtual card access into monthly wallet premium tiers. This behavioral shift concentrates revenue predictability for issuers while reducing per-credential economics visibility for consumers in Nairobi and Mombasa merchant networks.
Africa Virtual Cards Market Segmentation
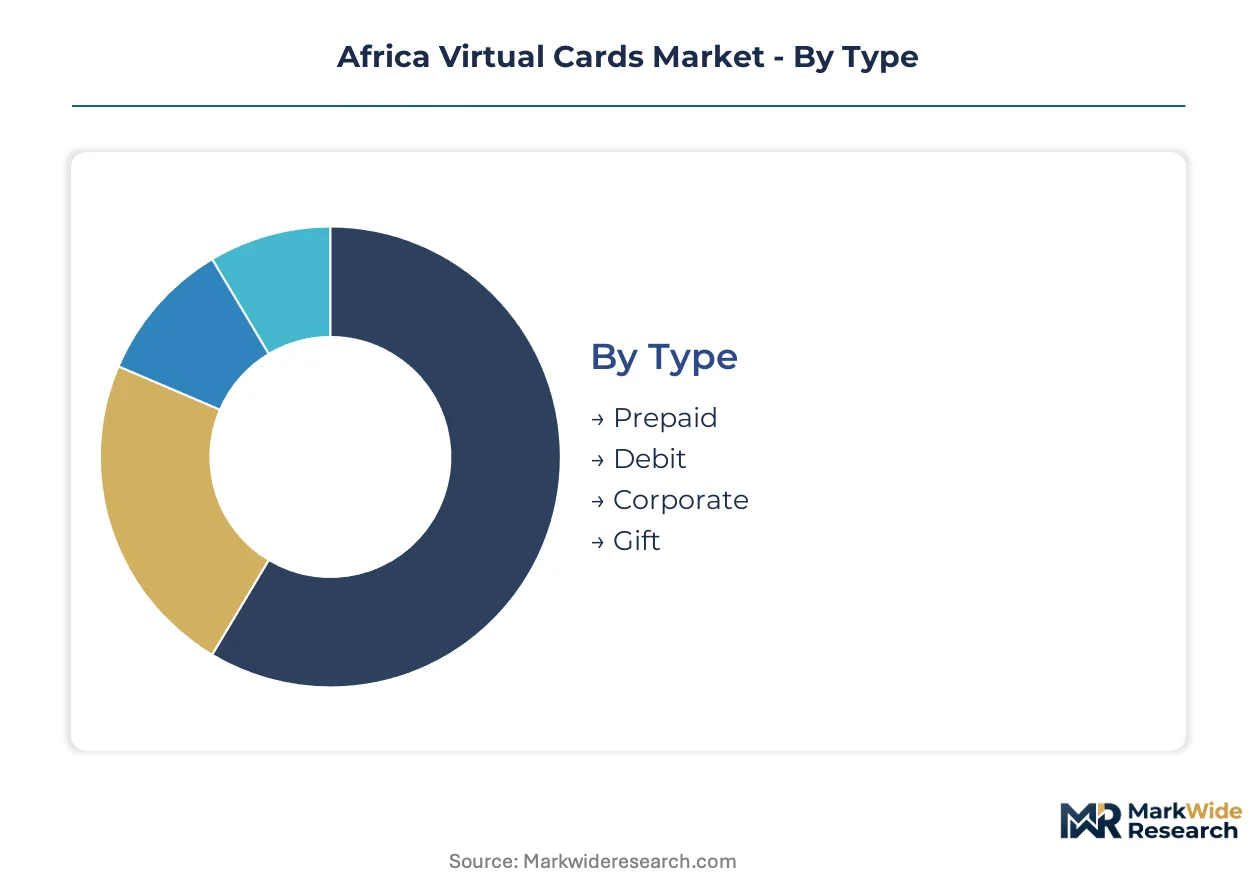
Virtual card segmentation across Africa reveals how issuance economics shift dramatically across credential types and delivery technologies. Regulatory licensing burdens from Nigeria's Central Bank and Kenya's Central Bank fragment market entry requirements by segment.
Type:
Nigeria's Central Bank tiered KYC mandates impose stricter certification thresholds on debit-linked credentials than prepaid products, reshaping which fintechs can compete in each tier.
- Prepaid:Single-use or reloadable credentials without underlying bank account linkage dominate transaction volume among unbanked populations. Demand concentrates in Kenya's M-Pesa ecosystem and Nigeria's informal merchant corridors, driven by lower onboarding friction and minimal documentation requirements.
- Debit:Credentials tied to traditional deposit accounts carry higher regulatory scrutiny under South Africa's Financial Sector Conduct Authority licensing. Nigerian fintechs absorb extended compliance timelines to access salary disbursement and recurring payment use cases.
- Corporate:Programmable spend-control tools for enterprise procurement workflows require segregated fund protection compliance.
- Gift:Limited-duration promotional credentials face merchant acceptance constraints in Francophone markets.
Prepaid sits at the top of the volume ranking, with Corporate climbing the fastest.
Application:
Merchant infrastructure maturity varies sharply across use cases, with e-commerce corridors in Lagos and Nairobi outpacing travel and B2B digitization.
- E-commerce:Single-use PAN generation reduces fraud exposure for online retailers. Nigerian merchants adopt dynamic CVV technology to compress chargeback rates on cross-border transactions.
- Subscription Services:Recurring credential provisioning locks in predictable revenue streams for East African fintechs bundling virtual access into monthly wallet premiums.
- Travel:Cross-border transaction margins suffer from Naira and Rand depreciation volatility.
- B2B Transactions:Programmable departmental budgets capture enterprise procurement workflows in South African and Nigerian multinationals.
E-commerce commands the largest transaction base, while B2B Transactions expand most quickly.
Customer Type:
Wallet-linked distribution channels reshape acquisition economics across demographic tiers, with mobile money integration favoring individual and small business onboarding.
- Individuals:Unbanked consumers access cross-border payments through prepaid credentials without traditional account relationships. Kenya's API standards for account aggregation enable third-party providers to initiate payments.
- Small Businesses:API-based provisioning embeds virtual issuance directly into merchant workflows. Lagos and Abuja commercial corridors show concentrated demand for invoice payment and supplier settlement tools.
- Enterprises:Spend-management platforms retrofit to meet South Africa's ring-fenced liquidity pool requirements.
- Startups:Limited compliance resources delay tokenization certification timelines with Visa and Mastercard networks.
Individuals generate the highest credential volume, with Small Businesses gaining share fastest.
Technology:
Delivery channel selection determines fraud architecture and merchant acceptance reach, with wallet integration anchoring the fastest deployment velocity.
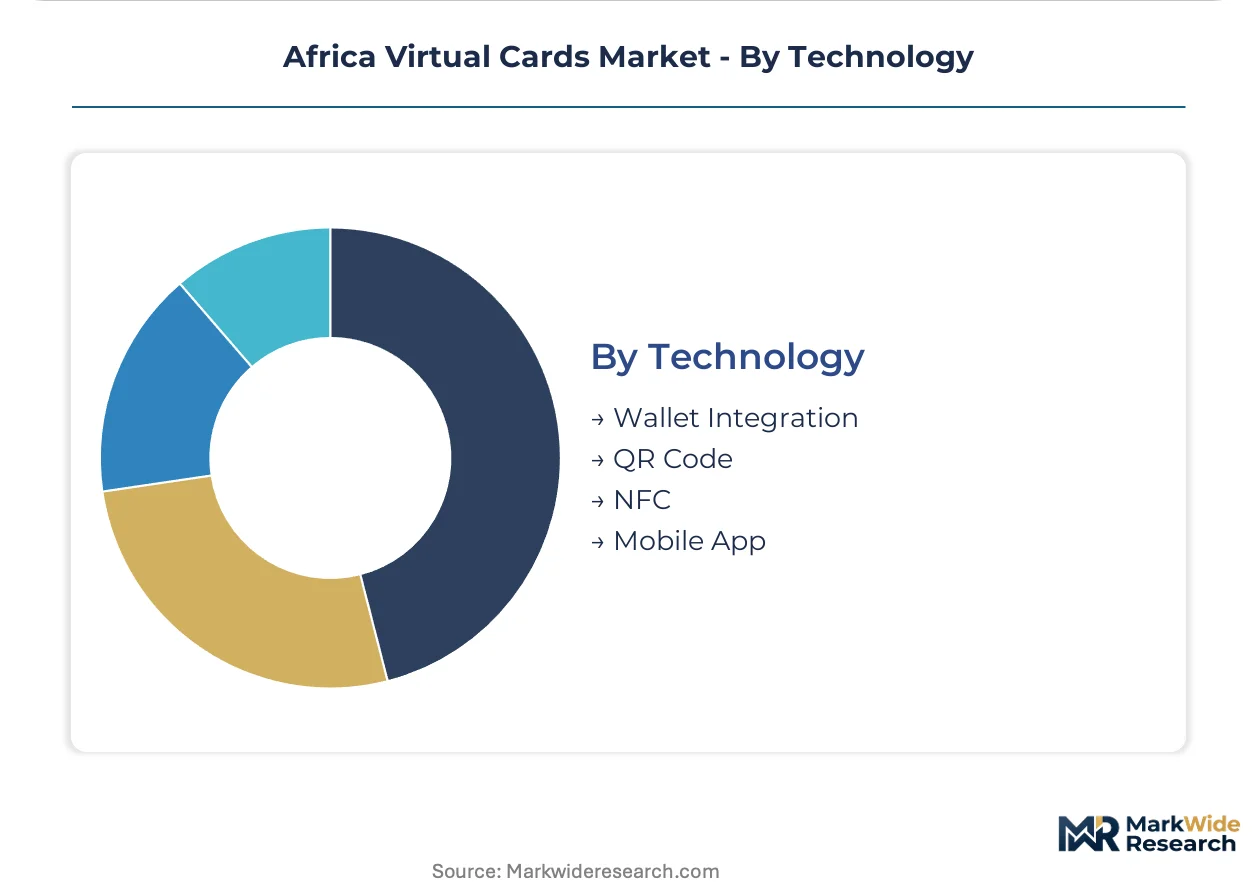
- Wallet Integration:API-based provisioning embeds credentials directly into mobile money applications. Safaricom's M-Pesa ecosystem locks in unbanked users through closed-loop architectures.
- QR Code:Acceptance networks remain underdeveloped in Côte d'Ivoire and Senegal relative to Anglophone peers.
- NFC:Contactless credential delivery requires point-of-sale terminal upgrades concentrated in South African urban centers.
- Mobile App:Standalone provisioning faces customer acquisition costs that wallet-linked channels avoid.
Wallet Integration leads deployment scale, with NFC showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's cashless policy acceleration contrasts with Ethiopia's recent market liberalization, revealing how regulatory maturity shapes virtual card deployment timelines across African economies.
Nigeria
Tiered KYC requirements and merchant acceptance expansion in Lagos commercial corridors drive prepaid credential volume. The Central Bank of Nigeria enforces domestic server hosting mandates for transaction records. Abuja fintech clusters absorb compliance costs to access salary disbursement use cases.
Kenya
Mobile money wallet integration through M-Pesa ecosystem partners locks in unbanked user acquisition. The Central Bank of Kenya governs electronic money licensing for credential issuers. Nairobi and Mombasa merchant networks show concentrated API-based provisioning demand for invoice settlement tools.
South Africa
Corporate spend-control tools capture enterprise procurement workflows among multinationals. The Financial Sector Conduct Authority mandates segregated customer fund protection for electronic money institutions. Johannesburg fintechs retrofit treasury operations around ring-fenced liquidity pools.
Ethiopia
Telebirr mobile money platform expansion creates first-mover positioning for virtual card overlay products. The National Bank of Ethiopia's digital payment liberalization invites foreign fintech entry. Addis Ababa commercial corridors lag Anglophone peers in point-of-sale digitization infrastructure.
Egypt
Government payroll digitization and e-commerce merchant fraud mitigation drive credential demand. The Central Bank of Egypt oversees electronic money licensing frameworks. Cairo fintech clusters focus on cross-border remittance-linked virtual issuance for diaspora payments.
Africa Virtual Cards Market Competitive Landscape
Top-tier vendors anchor payment network infrastructure, while mid-tier fintechs compete through localized API stacks and wallet-linked distribution channels. The market exhibits tiered concentration around tokenization-certified networks and mobile money ecosystem partners. Three archetypes dominate: global payment networks with tokenization infrastructure, African fintechs with merchant-embedded issuance APIs, and mobile network operators leveraging subscriber bases for wallet integration. Competitive moves center on strategic partnerships with mobile money platforms and geographic expansion into newly liberalized markets.
Among global payment networks, Visa and Mastercard occupy positions as tokenization infrastructure providers, while Flutterwave exemplifies the localized API stack archetype within African fintechs. These entities represent contrasting approaches to market penetration—network-level certification authority versus merchant workflow embedding.
| Leading Market Players |
|---|
| Visa |
| Mastercard |
| UnionPay International |
| Interswitch |
| Flutterwave |
| MTN |
| Safaricom |
| Airtel Africa |
| Fawry |
| Others |
Value Network & Pricing Analysis
Nigeria's Central Bank cashless policy mandates and South Africa's ring-fenced liquidity requirements are forcing virtual card providers to restructure treasury operations and absorb compliance costs that reshape how credential pricing gets set across issuance tiers.
Pricing Analysis
Capacity additions in Kenyan fintech infrastructure are reshaping price floors for wallet-integrated virtual card provisioning. Subscription-based SaaS-tiered pricing dominates East African markets, with premium-mid-economy pricing differentiation anchored by tokenization certification levels and API integration complexity. Cost compression in prepaid credential tiers is intensifying because Flutterwave-style localized API stacks reduce merchant acquisition friction. Small businesses in Lagos commercial corridors show highest price sensitivity, while South African multinational enterprises demonstrate lowest sensitivity due to programmable spend-control requirements.
Supply Chain Analysis
Tokenization infrastructure supply rests on Visa and Mastercard network certification hubs concentrated in the United States, United Kingdom, and Singapore. Provisioning technology draws from cloud computing services, API middleware layers, and mobile wallet integration platforms. Single-source vulnerability concentrates around network-level compliance audits that delay product launches for new African entrants. Distribution runs through mobile network operator partnerships and fintech API marketplaces rather than traditional banking channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Africa's virtual cards market functions as a stable compounder, with mobile wallet integration driving steady penetration among unbanked populations that locks in recurring revenue predictability for credential issuers.
For Market Incumbents: Deepen control over M-Pesa-style closed-loop distribution architectures to defend against emerging API-first fintech challengers. Invest in tokenization certification capacity additions in Kenya and Nigeria to maintain network-level pricing power. Lock in exclusive mobile money platform partnerships before Ethiopian market liberalization accelerates. For New Entrants and Emerging Players: Launch via Telebirr overlay products in Ethiopia's newly liberalized digital payments environment. Target B2B spend-control tools for Nigerian and South African multinationals as the most penetrable segment. Pursue open banking API integration in Kenya as the primary go-to-market angle to bypass legacy core banking resistance. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier fintechs possessing localized merchant-embedded issuance capabilities and pending tokenization certification. Long-term viability over a multi-year horizon favors platforms with demonstrated wallet integration traction and regulatory licensing across multiple African markets. Watch for Ethiopian central bank foreign fintech licensing announcements as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Tokenization Certification Investment | Visa and Mastercard compliance audits anchor network-level pricing power for credential issuers. |
| Mobile Money Platform Partnership | Safaricom's M-Pesa ecosystem locks in unbanked user acquisition through closed-loop architectures. |
| Open Banking API Integration | Kenya's account aggregation standards enable third-party payment initiation across siloed banking infrastructure. |
| B2B Spend-Management Platform Development | South Africa's ring-fenced liquidity requirements force treasury operation restructuring for enterprise issuers. |
| Geographic Expansion into Ethiopia | Telebirr mobile money platform creates virgin territory for virtual card overlay products. |
Research Methodology
Bottom-up credential volume modeling reconciled against top-down fintech infrastructure tracking forms the analytical core of this study. Primary interviews with virtual card product managers, mobile money platform engineers, central bank regulatory officers, and merchant payment integration specialists combined with secondary validation from Nigeria's Central Bank policy circulars, Kenya's electronic money licensing frameworks, South Africa's Financial Sector Conduct Authority guidance notes, and Visa tokenization certification documentation. Triangulation across these sources ensures segmentation outputs reflect actual deployment patterns rather than modeled assumptions.
Historical trendline analysis of prepaid credential issuance velocity and corporate virtual card adoption rates established baseline growth parameters across the projection horizon. The analytical framework models segmentation dimensions including credential type, application use case, customer tier, and delivery channel technology, with CAGRs derived from regression analysis of mobile wallet penetration curves and merchant acceptance infrastructure buildout. Industry-specific forecast inputs incorporate Nigeria's tiered KYC implementation timelines and Ethiopia's digital payment liberalization trajectory.
Forecast precision tightens around the base case; tail outcomes carry wider variance under naira depreciation volatility and cross-border data localization mandate fragmentation. Forecasts reflect assumptions about regulatory licensing continuity and network certification processing speeds. A small set of named triggers—Ethiopian foreign fintech entry permits, Kenyan open banking API standard revisions, and South African liquidity pool compliance enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Digital Remittance Service Market
Payments
Germany Real Time Payments Market
Payments
Japan Virtual Cards Market
Payments
UK Prepaid Cards Market
Payments
Global Accounts Payable Automation Market
Payments
Sweden POS Terminals Market
Payments
Nigeria Mobile Money Market
Payments
United Kingdom Payment Gateway Market
Payments
In Vehicles Payment Market
Payments
E-Commerce Payments Market
Payments
Mobile POS Market
Payments
MENA Digital Payments Market
Payments
Finland Payments Market
Payments
Saudi Arabia Mobile Payments Market
Payments
Southeast Asia POS Terminal Market
Payments
Electronic Cash Register Market