
 Global Hardware Wallets Market | 2026-2036
Global Hardware Wallets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hardware Wallets Market Analysis
Security-grade certification tiers is collapsing the distinction between consumer and enterprise hardware wallet segments. Ledger SAS leverages its custom secure element architecture to sustain dominance across European and North American channels. SatoshiLabs anchors its competitive position through open-source firmware transparency and long-standing community trust. SafePal competes aggressively on price while extending distribution reach through integrated exchange partnerships.
Hardware wallets are physical electronic devices that generate and store private cryptographic keys in isolated secure elements, typically employing EAL5+ or higher certified chips with air-gapped or USB-connected transaction signing protocols to protect digital asset holdings from remote extraction. Cold storage wallets command the highest margin pools as institutional custody mandates drive demand for fully offline key generation and multi-signature configurations. Bluetooth wallets represent the fastest-growing product type as mobile-native investors prioritize wireless convenience without sacrificing secure element isolation. Multi-signature technology adoption accelerates among institutional end users seeking quorum-based governance structures for treasury management.
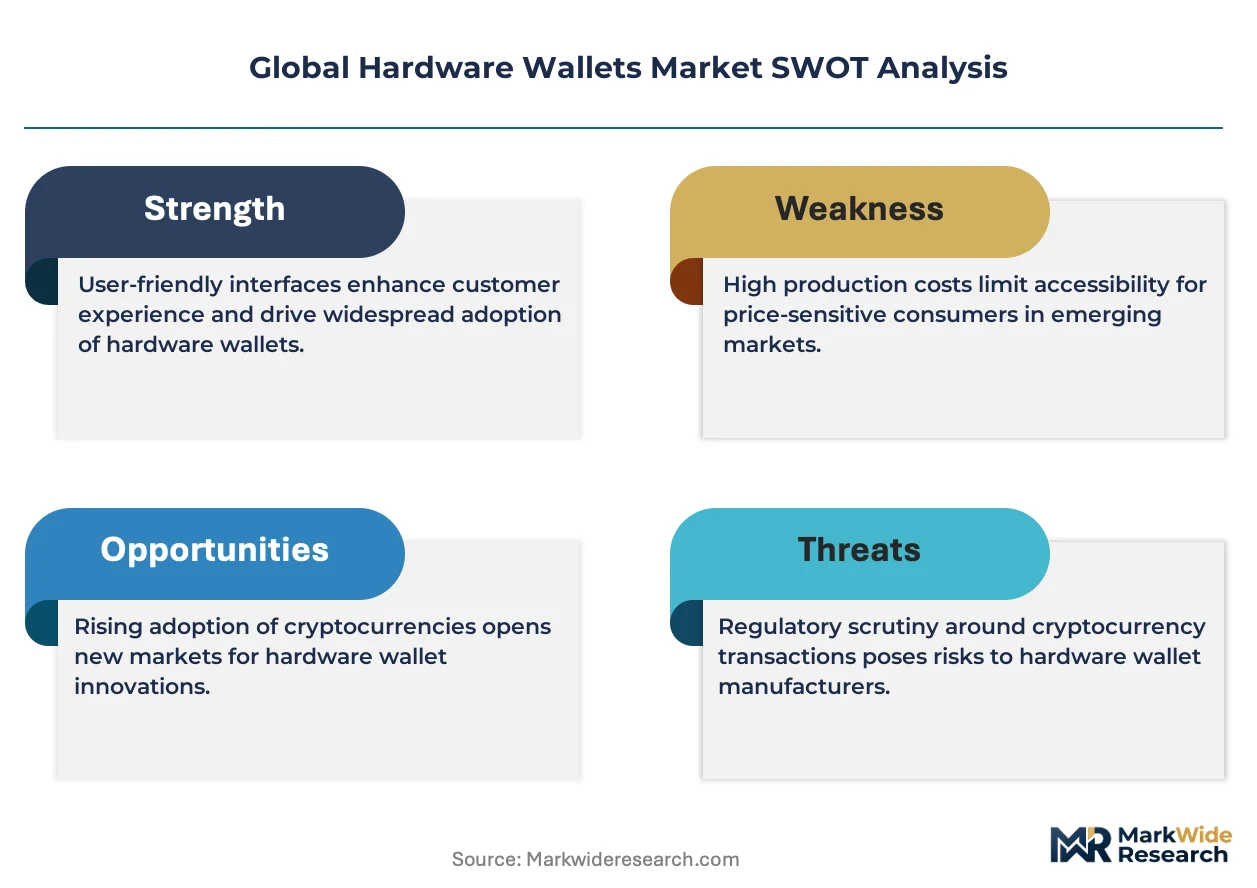
The EU's Markets in Crypto-Assets Regulation and the US SEC custody rule proposals reshape compliance requirements for wallet providers serving institutional clients. France's ANSM-aligned financial conduct standards and Singapore's Monetary Authority technology risk management guidelines further fragment certification obligations across jurisdictions. Stakeholders must monitor evolving custody rule definitions that determine whether hardware wallet architectures qualify as qualified custodians under emerging regulatory frameworks.
Market Dynamics
Institutional custody mandates are compressing product development cycles as treasury managers demand EAL5+-certified secure elements with multi-signature governance support. This structural pull from enterprise buyers is forcing hardware wallet architectures toward bank-grade compliance tiers previously reserved for HSM infrastructure.
Growth Catalysts
- MiCA Framework Compliance:The EU's Markets in Crypto-Assets Regulation creates mandatory certification benchmarks that institutional clients now require as table stakes for vendor selection.
- Air-Gapped Signing Protocols:Fully offline transaction authorization is displacing USB-connected workflows among family offices managing multi-generational digital asset holdings.
- Singapore MAS Guidelines:The Monetary Authority of Singapore's technology risk management standards accelerate enterprise procurement across ASEAN financial centers.
Market Restraints
- Secure Element Supply Concentration:EAL5+ certified chip fabrication concentrates among three European and East Asian foundries, creating input bottlenecks during demand surges.
- Bluetooth Attack Surface Expansion:Wireless connectivity protocols introduce side-channel vulnerabilities that penetration testing firms actively exploit, constraining mobile-first product roadmaps.
- Qualified Custodian Definition Uncertainty:The US SEC's evolving custody rule proposals create compliance friction for wallet providers serving registered investment advisors.
Strategic Opportunities
- Brazil ANVISA-Aligned Financial Standards:Latin America's largest economy lacks mature hardware wallet penetration, creating first-mover advantages for certified entrants.
- Biometric-Seed Phrase Convergence:Fingerprint-authenticated key recovery is merging with traditional mnemonic backup systems, opening premium-tier positioning.
- Integrated Exchange Distribution:Direct-to-wallet fiat on-ramps through trading platform partnerships bypass traditional retail electronics channels.
Industry Challenges
- Firmware Security Engineering Talent Scarcity:Secure boot implementation and side-channel resistance require specialized embedded systems expertise concentrated among semiconductor veterans.
- Multi-Jurisdiction Certification Timelines:Parallel ANSM, BSI, and FIPS 140-3 validation processes extend product launch windows by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hardware Wallets Market |
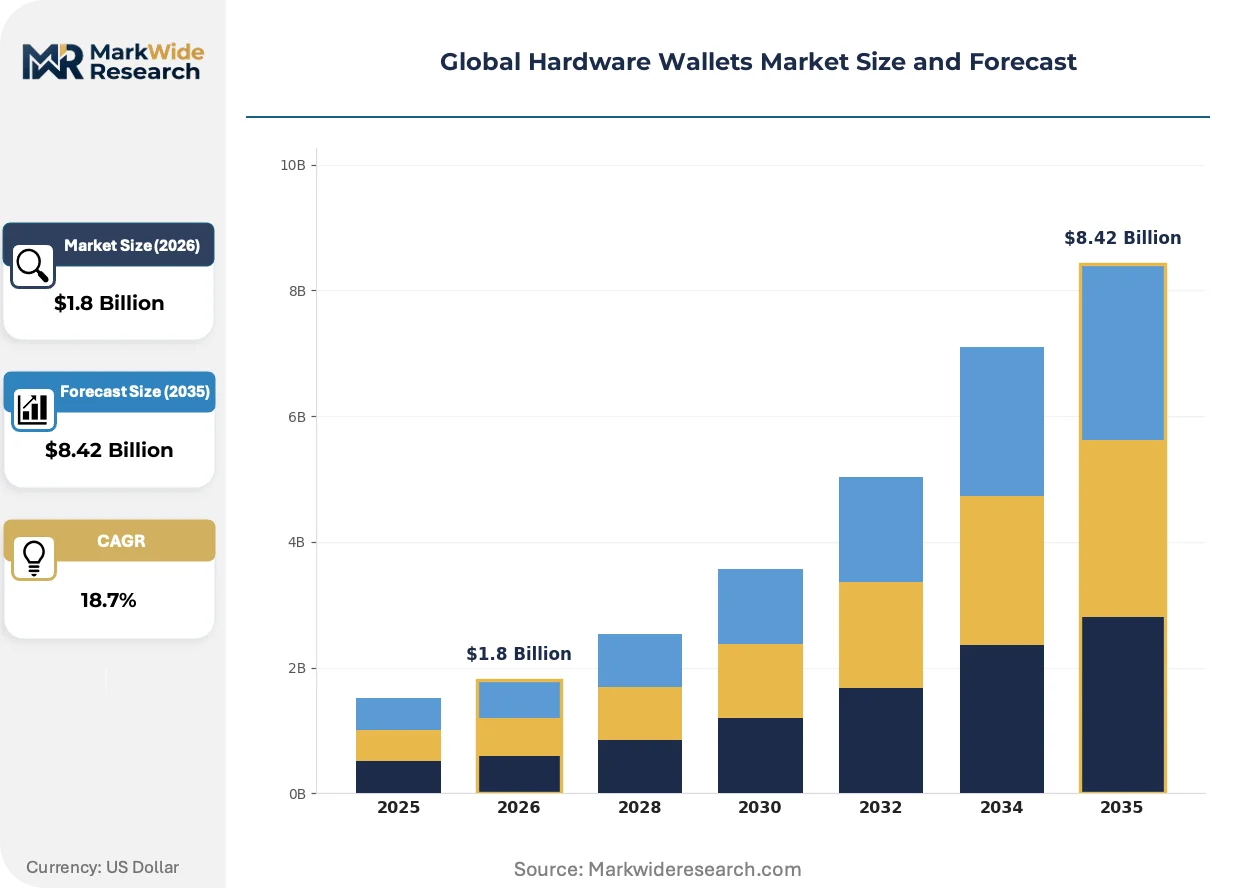
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Wallets, Bluetooth Wallets, Multi-Currency Wallets, Cold Storage Wallets End User: Individual Investors, Institutional Investors, Crypto Exchanges, Developers Technology: Single-Signature, Multi-Signature, Open Source, Proprietary Distribution Channel: Online Retail, Offline Retail, Direct Sales, Resellers |
| Companies Covered | Ledger SAS, SatoshiLabs, KeepKey, CoolWallet, Coinkite, ELLIPAL, SafePal, Shift Crypto AG, BitLox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hardware Wallets Market Emerging Trajectories
Secure element architectures are fragmenting into application-specific configurations as institutional demands diverge from retail convenience priorities. This technical divergence is spawning parallel certification tracks and supply chain specializations.
System-in-package (SiP) modules integrating secure elements with wireless radios are miniaturizing hardware wallet form factors below credit-card dimensions. Mobile-native investors in South Korea and Vietnam are driving volume adoption of these compact designs. The technology is compressing the traditional trade-off between physical security and portability that previously forced buyers into distinct product categories.
The EU AI Act's risk classification framework is extending to financial hardware with embedded machine learning for transaction pattern recognition. Device manufacturers must now document algorithmic transparency for biometric authentication modules. Cold storage wallet providers serving EU institutional clients are responding by segregating AI-enabled features into optional firmware branches.
Self-custody education initiatives from decentralized finance protocols are shortening replacement cycles among retail holders. First-time buyers now upgrade devices every 18-24 months rather than treating wallets as decade-long investments. This behavioral shift is most visible in Turkey and Nigeria, where currency instability drives rapid onboarding and subsequent hardware refresh demand.
Global Hardware Wallets Market Segmentation
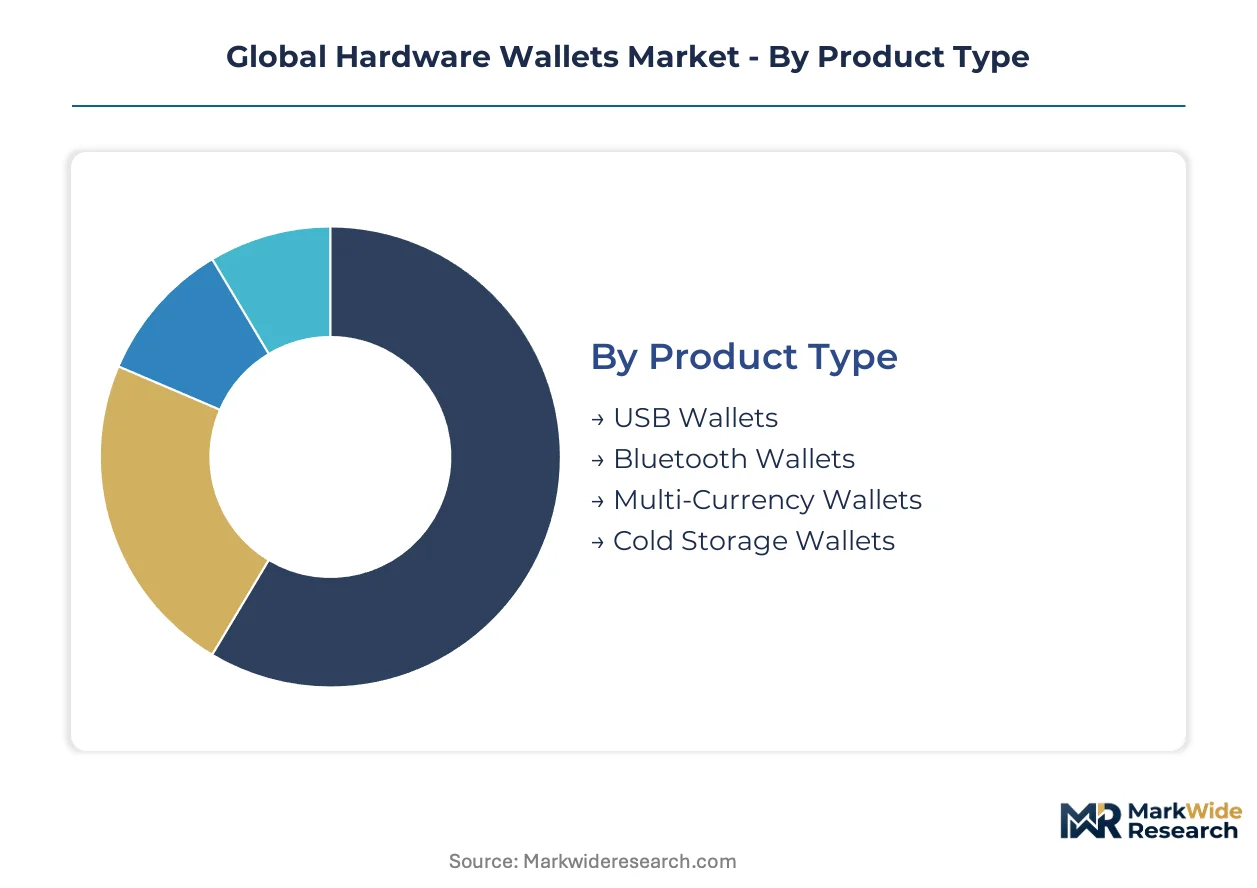
Hardware wallet segmentation reflects divergent security architectures and procurement pathways. Institutional buyers prioritize certified secure elements and multi-signature governance, while retail investors trade off wireless convenience against attack surface exposure. Distribution channel choices increasingly determine margin capture and compliance exposure for manufacturers.
Product Type:
EU AI Act risk classifications and SEC custody rule proposals are fragmenting certification requirements across product architectures. Cold storage wallets face the most stringent qualified custodian scrutiny, while Bluetooth-enabled devices navigate wireless protocol security attestations.
- Cold Storage Wallets:Fully air-gapped devices with EAL5+ certified secure elements generate private keys in electromagnetically isolated environments. Demand concentrates among family offices in Switzerland and Singapore managing multi-generational digital asset holdings, driven by regulatory mandates for qualified custodian compliance.
- Bluetooth Wallets:System-in-package modules integrate secure elements with wireless radios for mobile-native transaction signing. South Korean and Vietnamese investors are expanding volume fastest, prioritizing portability without sacrificing secure element isolation.
- USB Wallets:Wired connectivity protocols with hardened firmware stacks remain the baseline institutional standard.
- Multi-Currency Wallets:Unified key management for heterogeneous blockchain assets reduces device proliferation for active traders.
Established volume favors Cold Storage Wallets; emerging adoption favors Bluetooth Wallets.
End User:
Procurement authority and compliance obligations diverge sharply across buyer categories. Institutional mandates reshape product roadmaps more decisively than retail preferences.
- Institutional Investors:Treasury managers require multi-signature quorum structures, HSM-grade secure elements, and audit trails meeting ANSM-aligned financial conduct standards. The European Union's MiCA framework accelerates enterprise procurement cycles as compliance departments demand certified vendor shortlists.
- Individual Investors:Self-custody education from decentralized finance protocols shortens replacement cycles to 18-24 months in Turkey and Nigeria, where currency instability drives rapid onboarding and subsequent hardware refresh demand.
- Crypto Exchanges:Integrated custody services demand white-label hardware with custom firmware branding and direct fiat on-ramp connectivity.
- Developers:Open-source firmware transparency and SDK accessibility enable custom application layer integration.
Margin concentration sits with Institutional Investors; volume expansion centers on Individual Investors.
Technology:
Signature architecture and source code availability determine security auditability and institutional eligibility. Proprietary firmware faces heightened scrutiny under emerging algorithmic transparency mandates.
- Multi-Signature:Quorum-based key distribution requires M-of-N signature schemes with geographically distributed signing ceremonies. Institutional custody mandates in the United States and Germany drive specification demands for treasury governance structures.
- Open Source:Publicly auditable firmware repositories enable community penetration testing and vulnerability disclosure. SatoshiLabs anchors competitive positioning through long-standing transparency commitments.
- Single-Signature:Simplified key management suits retail holders with straightforward holding patterns.
- Proprietary:Closed-source implementations protect intellectual property but face regulatory friction in EU jurisdictions.
Security validation favors Open Source; institutional procurement favors Multi-Signature.
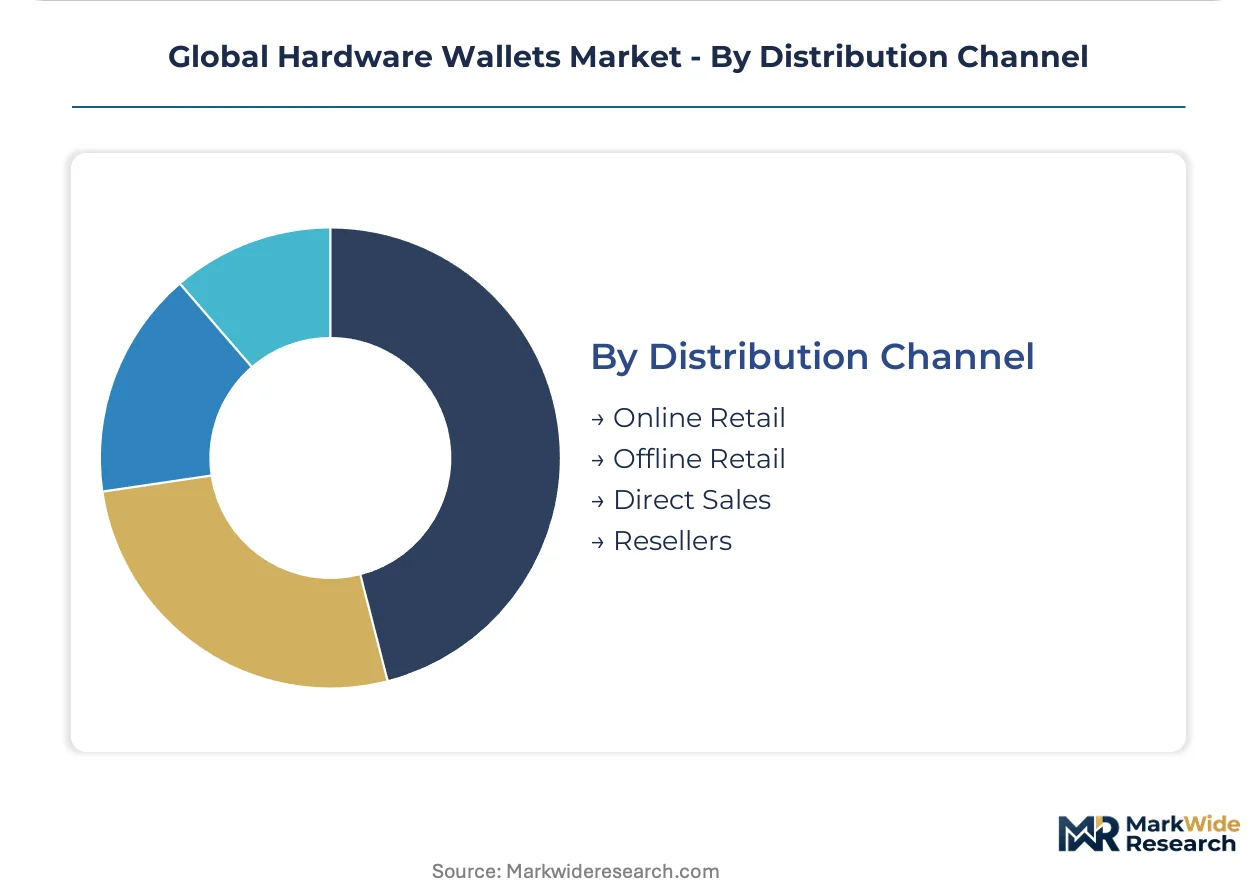
Distribution Channel:
Channel selection determines compliance exposure, margin retention, and customer acquisition cost structures. Direct relationships with regulated entities reduce counterparty risk.
- Direct Sales:Enterprise procurement teams negotiate custom firmware configurations and bulk pricing with manufacturers. Singapore's MAS technology risk management guidelines accelerate direct engagement for ASEAN financial institutions.
- Online Retail:E-commerce platforms enable global reach with standardized SKUs and rapid inventory turnover. SafePal extends distribution through integrated exchange partnerships bypassing traditional electronics channels.
- Offline Retail:Physical presence in consumer electronics stores supports first-time buyer education and device setup assistance.
- Resellers:Authorized distribution networks provide local language support and warranty servicing in fragmented markets.
Margin capture favors Direct Sales; volume scaling favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail buyers in Turkey and Nigeria exhibit extreme price elasticity, upgrading devices every 18-24 months amid currency instability. Institutional purchasers in Switzerland and Singapore show minimal price sensitivity, prioritizing EAL5+ certification and multi-signature governance regardless of cost premium.
United States
Enterprise treasury managers at technology firms and family offices drive procurement of HSM-grade secure elements with multi-signature quorum structures. The SEC's evolving custody rule proposals create compliance friction for wallet providers serving registered investment advisors. Demand concentrates in New York and San Francisco, where regulated institutional custody frameworks accelerate enterprise procurement cycles.
Switzerland
Multi-generational family offices managing digital asset holdings require fully air-gapped cold storage with qualified custodian compliance. FINMA guidelines align with ANSM-aligned financial conduct standards for institutional-grade hardware. The Zug crypto valley cluster anchors European demand for premium-tier security architectures.
Singapore
ASEAN financial institutions accelerate direct procurement of certified hardware following MAS technology risk management guidelines. The Monetary Authority mandates audit trails and secure element certification for institutional custody services. Enterprise demand clusters in the central business district, where treasury diversification into digital assets gains sustained traction.
Germany
Treasury governance structures at Mittelstand industrial firms specify M-of-N signature schemes with geographically distributed signing ceremonies. BaFin interpretations of MiCA framework compliance reshape vendor certification requirements. Berlin and Frankfurt host concentrated procurement teams negotiating custom firmware configurations.
South Korea
Mobile-native investors prioritize wireless convenience without sacrificing secure element isolation, driving volume adoption of system-in-package modules. The Financial Services Commission monitors technology risk standards for retail custody products. Seoul anchors demand for miniaturized form factors below credit-card dimensions.
Global Hardware Wallets Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Secure element architecture specialists command premium positioning through EAL5+ certification and proprietary chip designs. Open-source firmware providers anchor community trust through transparency commitments. Exchange-integrated distributors compete aggressively on price while extending reach through trading platform partnerships. Dominant competitive moves include strategic partnerships for integrated fiat on-ramps and portfolio diversification into biometric-authenticated key recovery systems.
Among European secure element specialists, Ledger SAS exemplifies the proprietary architecture archetype with custom chip designs sustaining dominance across premium channels. SatoshiLabs occupies a position within the transparency-focused tier, representing long-standing open-source commitments that anchor community trust. SafePal sits within the distribution-integrated segment, exemplifying aggressive price positioning and exchange partnership strategies that bypass traditional retail electronics channels.
| Leading Market Players |
|---|
| Ledger SAS |
| SatoshiLabs |
| KeepKey |
| CoolWallet |
| Coinkite |
| ELLIPAL |
| SafePal |
| Shift Crypto AG |
| BitLox |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-twenty-two-month certification timelines for parallel ANSM, BSI, and FIPS 140-3 validation processes concentrate pricing power among incumbents with established foundry relationships and deferred cost absorption capacity. Inventory carrying costs for EAL5+ certified secure elements amplify margin pressure on smaller manufacturers lacking volume commitments with European and East Asian fabrication facilities.
Pricing Analysis
After-sales revenue from firmware update subscriptions and extended warranty tiers drives lifetime value capture beyond initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and multi-signature capability, with institutional procurement showing minimal price sensitivity compared to retail investors in Turkey and Nigeria. Cost compression in economy-tier Bluetooth wallets intensifies as exchange-integrated distributors compete on device subsidies. Price differentiation hinges on secure element certification tier and geographic delivery logistics rather than brand premium alone.
Supply Chain Analysis
France and Germany anchor EAL5+ certified secure element fabrication for institutional-grade hardware, while Taiwan and South Korea supply system-in-package modules integrating wireless radios for mobile-native form factors. Raw material dependencies center on silicon wafers, electromagnetic shielding substrates, and biometric sensor components. Single-source vulnerability concentrates in European foundries qualified for ANSM-aligned financial conduct standards. Distribution runs through direct enterprise procurement teams for institutional buyers and integrated exchange partnerships for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as institutional custody mandates diverge from retail convenience priorities, creating parallel certification tracks and specialized supply chain configurations. The EU's MiCA framework and SEC custody rule proposals fragment compliance requirements across buyer archetypes.
For Market Incumbents: Fortify secure element supply commitments through captive allocation agreements with European and East Asian foundries facing capacity constraints. Deepen backward integration into firmware security engineering talent pools concentrated among semiconductor veterans. Prioritize ANSM-aligned certification maintenance as regulatory fragmentation accelerates vendor qualification timelines. For New Entrants and Emerging Players: White-label institutional custody infrastructure for crypto exchanges lacking in-house hardware capabilities offers the most penetrable service-layer gap. Target Brazil's underdeveloped certified hardware penetration with ANVISA-aligned financial standards positioning. Pursue integrated fiat on-ramp partnerships as the primary go-to-market angle, bypassing traditional retail electronics channel establishment costs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-signature governance hardware as institutional procurement demands HSM-grade secure elements and audit trail infrastructure. Long-term viability centers on acquisition of firmware security engineering specialists with side-channel resistance expertise. Watch for SEC qualified custodian definition finalization as the signal indicating regulatory clarity inflection for enterprise-facing wallet architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Element Supply Agreement | Captive allocation with EAL5+ certified foundries insulates against 14-22 month certification bottlenecks. |
| Multi-Jurisdiction Certification Investment | Parallel ANSM, BSI, and FIPS 140-3 validation opens institutional procurement in Germany and Singapore. |
| Biometric-Seed Phrase Convergence Development | Fingerprint-authenticated key recovery merges with mnemonic backup systems for premium-tier positioning. |
| Integrated Exchange Partnership | Direct-to-wallet fiat on-ramps through trading platforms bypass traditional retail electronics distribution costs. |
| Open-Source Firmware Transparency Commitment | Publicly auditable repositories enable community penetration testing and anchor trust in EU jurisdictions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC custody rule dockets, EU MiCA regulatory filings, and secure element certification databases from BSI and ANSM. Primary interviews engaged hardware wallet product managers, institutional custody officers at crypto exchanges, secure element procurement leads at semiconductor foundries, and regulatory compliance directors at financial services firms. Secondary validation drew from customs trade data for hardware wallet imports, EAL certification registries, and hyperscaler treasury diversification disclosures. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product architecture type, end-user procurement authority, signature scheme technology, and distribution channel structure. Volume and value outputs reflect reconciliation of institutional procurement cycle data with retail replacement frequency observations across currency-unstable economies. CAGRs were derived from regression analysis of certified hardware shipment volumes against regulatory milestone timelines. Industry-specific forecast inputs incorporate MiCA implementation phase transitions and MAS technology risk management guideline adoption rates.
Underlying assumptions cover stable secure element foundry capacity expansion, with deviation risk concentrated in SEC qualified custodian definition uncertainty and Bluetooth protocol vulnerability disclosures. Recalibration cycles align with material shifts in EU AI Act risk classification enforcement and institutional custody mandate expansion into ASEAN financial centers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
GCC Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
US Cryptocurrency Payment Apps Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Investor ESG Software Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market