
 Global Telecom Billing and Revenue Management Market | 2026-2036
Global Telecom Billing and Revenue Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecom Billing and Revenue Management Market Foresight
ISO 9001 certification for telecom software quality management is collapsing as a baseline gatekeeper, forcing vendors to pursue ISO 27001 and PCI DSS attestations to remain eligible for operator RFPs. CSG International Corporation leverages its prepaid billing heritage to sustain North American operator relationships. Amdocs Limited anchors its position through end-to-end BSS/OSS integration across tier-one carriers. Huawei Technologies Co Ltd. competes aggressively on 5G charging infrastructure in markets where geopolitical restrictions do not apply.
Telecom billing and revenue management encompasses the software systems, mediation engines, and financial workflows that translate network usage events into invoices, revenue recognition, and partner settlements. These platforms process call detail records, data session logs, and IoT telemetry through real-time rating engines that apply tariff rules, tax calculations, and discount policies before generating subscriber bills or inter-carrier chargebacks. Cloud-based deployment now leads solution type preferences as operators shed capital-intensive on-premise estates, while convergent billing—unifying prepaid and postpaid wallets—captures the fastest growth within application segments due to subscriber demand for single-account flexibility. Fraud management and revenue assurance retain concentrated margin pools because operators treat leakage prevention as non-discretionary spend.
GDPR in Europe and the EU AI Act impose algorithmic transparency requirements on automated credit scoring and churn prediction modules embedded in billing suites. The FCC in the United States enforces truth-in-billing rules that mandate line-item clarity, directly shaping product roadmap priorities for vendors serving American operators. Stakeholders must monitor how TRAI in India and SAMR in China evolve data localization mandates, as these will determine whether multinational vendors can operate centralized cloud instances or must fragment their architectures into country-specific deployments.
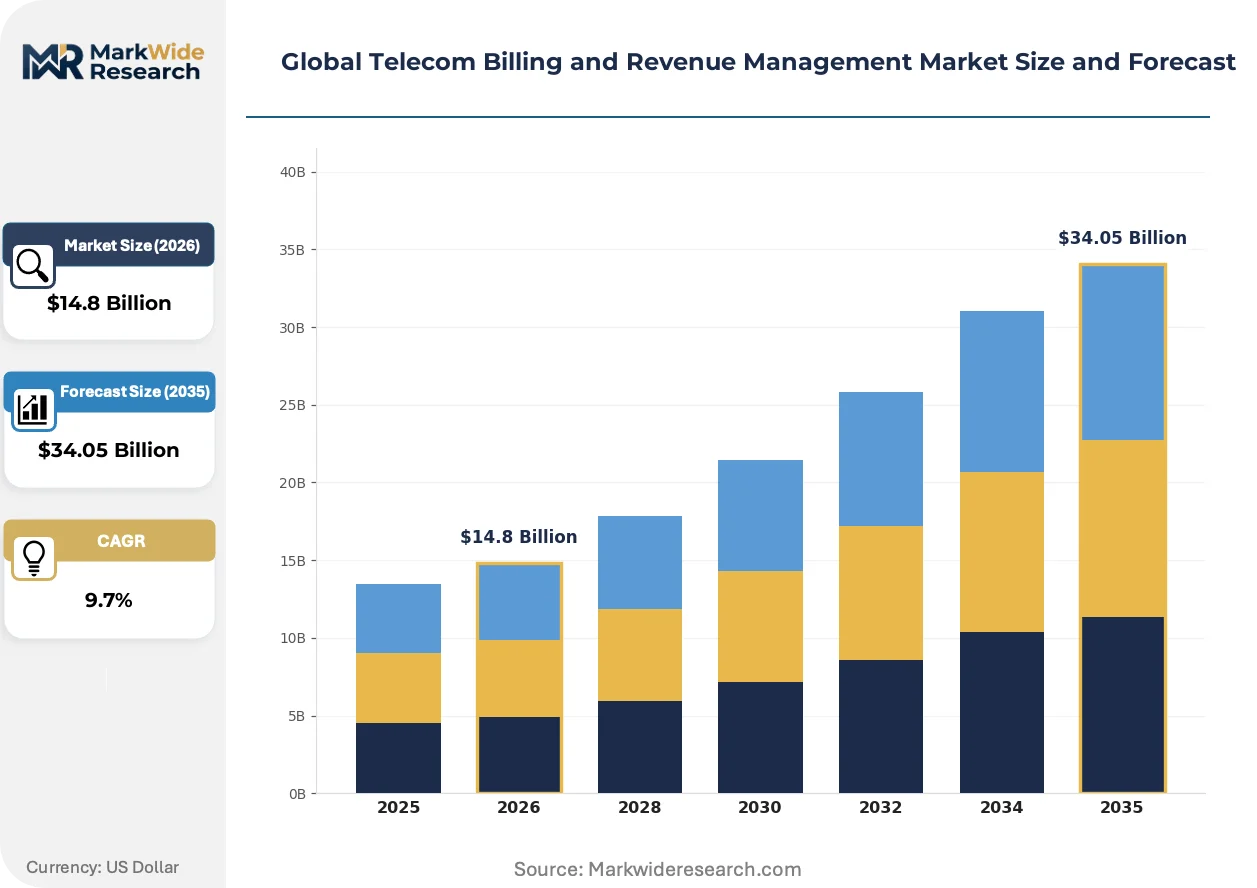
Market Dynamics
Cloud-native billing architectures are decomposing legacy BSS estates as mobile operators shed monolithic stacks for microservices-based rating engines. This structural shift compresses deployment timelines from years to months while fragmenting vendor lock-in patterns across procurement cycles.
Growth Catalysts
- 5G Standalone Core Deployments:Operators in India, Germany, and South Korea are procuring convergent charging functions that unify prepaid and postpaid mediation. TRAI mandates in India accelerate this procurement wave.
- GDPR Algorithmic Transparency:The EU AI Act forces vendors to expose automated credit-scoring logic within billing suites. European operators now require audit trails for churn prediction modules.
- IoT Telemetry Proliferation:Connected vehicle fleets and industrial sensors generate event volumes that legacy rating engines cannot process. Machine-to-machine billing now demands real-time mediation at scale.
Market Restraints
- Geopolitical Procurement Friction:Huawei's exclusion from US, UK, and Australian RFPs fragments vendor competition. Operators in restricted markets face elevated switching costs when migrating from sanctioned suppliers.
- Data Localization Mandates:SAMR in China and TRAI in India require subscriber records to reside within national boundaries. Multinational vendors must architect country-specific cloud instances rather than centralized regional hubs.
- Skill Scarcity in Cloud-Native Engineering:Kubernetes orchestration and event-driven architecture expertise concentrates in Bangalore, Tel Aviv, and Stockholm. Billing vendors compete for the same finite talent pool.
Strategic Opportunities
- Revenue Assurance White Space:Fraud management modules retain concentrated margins as operators treat leakage prevention as non-discretionary spend. Southeast Asian markets underinvest in this capability relative to subscriber growth.
- Convergent Wallet Convergence:Unified prepaid-postpaid accounts appeal to gig-economy workers and migrant populations. Brazil and Indonesia present underpenetrated demand for flexible account structures.
- Embedded Finance Integration:Billing platforms are extending into micro-lending and airtime-backed credit. Kenyan mobile money ecosystems demonstrate the model's viability for emerging market replication.
Industry Challenges
- ISO 27001 Certification Timelines:Vendors pursuing PCI DSS and information security attestations face 12-18 month audit cycles. ISO 9001 no longer satisfies operator procurement gates.
- Mediation Engine Migration Complexity:Decades of tariff rule accumulation in legacy systems resist automated extraction. Manual recoding introduces revenue leakage risks during platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecom Billing and Revenue Management Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Managed Services Solution Type: Billing Systems, Revenue Assurance, Customer Care, Mediation, Fraud Management Application: Prepaid, Postpaid, Convergent Billing, Roaming, Partner Settlement Customer Type: Mobile Network Operators, Fixed Line Providers, Virtual Network Operators, Wholesale Providers |
| Companies Covered | SAP SE, CSG International Corporation, Amdocs Limited, Comarch SA, Cerillion PLC, Huawei Technologies Co Ltd., Accenture PLC, Telefonaktiebolaget LM Ericsson, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecom Billing and Revenue Management Market Shifts & Advancements
Containerized billing functions are fragmenting traditional vendor monopolies as operators assemble best-of-breed components through API marketplaces. This architectural shift rewards specialized rating engine providers while compressing margins for full-stack incumbents.
Microservices-based charging infrastructure is decomposing the integrated BSS stack into discrete, swappable functions. Tier-one carriers in Germany and Japan are piloting Kubernetes-orchestrated rating engines that scale elastically with traffic spikes. This decomposition enables operators to swap individual components without forklift upgrades, compressing vendor switching costs from multi-year lock-in to quarterly contract terms.
The EU AI Act imposes explainability requirements on automated decision systems embedded in billing platforms. Vendors serving European operators must now document algorithmic logic for credit scoring and promotional targeting. This regulatory pressure is diverting R&D resources toward audit-interface development rather than core rating performance.
Subscription fatigue among consumers is compressing billing cycle experimentation across prepaid markets. Operators in Nigeria and the Philippines are testing hourly and daily passes rather than monthly bundles. This behavioral shift demands real-time rating engines capable of micro-transaction processing at volumes traditional mediation architectures cannot sustain.
Global Telecom Billing and Revenue Management Market Segmentation
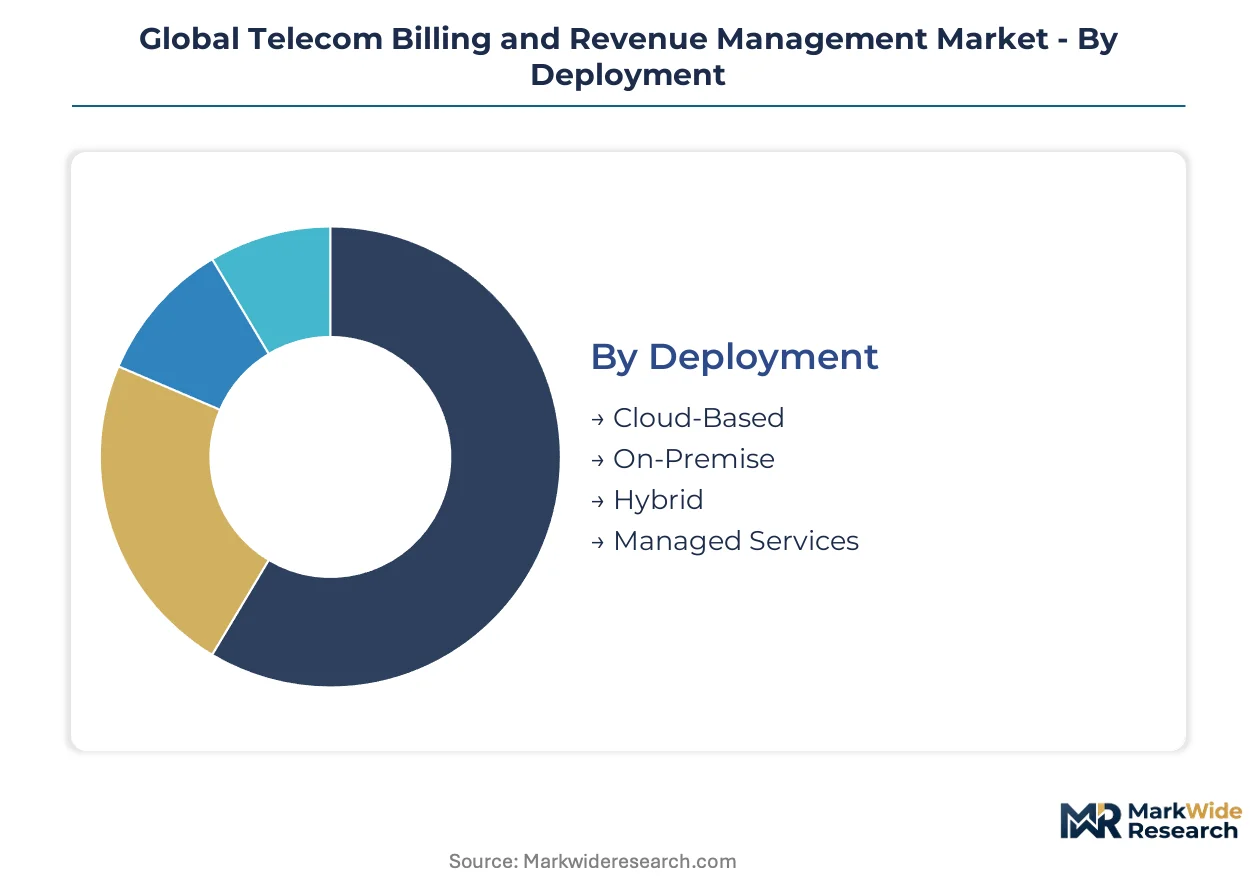
Segmentation reveals how procurement priorities diverge across operator archetypes. Cloud migration intensity, regulatory pressure on data residency, and 5G charging complexity create distinct margin pools that vendors must navigate separately.
Deployment:
Margin concentration follows operational complexity rather than deployment scale alone.
- Cloud-Based:Microservices architectures enable elastic scaling for traffic spikes during promotional campaigns. Indian operators under TRAI modernization mandates are retiring on-premise estates fastest, compressing deployment timelines from years to quarters.
- On-Premise:Legacy hardware persists where data localization laws prohibit cross-border data flows. Chinese operators under SAMR requirements maintain captive infrastructure despite higher total cost of ownership.
- Hybrid:Sensitive rating functions remain on-premise while customer-facing portals migrate to cloud. German operators favor this architecture for GDPR-compliant AI explainability.
- Managed Services:Outsourced operations appeal to tier-two operators lacking Kubernetes expertise. Southeast Asian markets show rising appetite for operational handoff.
The dominant share belongs to Cloud-Based, while Hybrid is closing the gap fastest as operators balance agility against compliance.
Solution Type:
Functional specialization determines vendor stickiness and renewal pricing power.
- Billing Systems:Core rating engines process call detail records and data sessions into subscriber invoices. Convergent prepaid-postpaid unification drives replacement cycles in Brazil and Indonesia.
- Revenue Assurance:Leakage detection modules command premium pricing due to direct ROI visibility. Fraud management integration amplifies procurement priority in African markets.
- Customer Care:Self-service portals and automated dispute resolution reduce call center load. Tier-one carriers in Japan prioritize omnichannel integration.
- Mediation:Real-time event collection from 5G core networks demands protocol adapters for network function virtualization. South Korean operators lead NFV mediation adoption.
- Fraud Management:Machine learning models detect SIM-box and international revenue share fraud patterns. Nigerian operators face acute pressure from subscription fraud proliferation.
Billing Systems retains the largest revenue base, though Revenue Assurance is expanding most quickly as operators quantify leakage exposure.
Application:
Subscriber behavior shifts are fragmenting traditional account structures.
- Prepaid:Wallet-based accounts dominate emerging market subscriber bases. Hourly and daily pass experimentation in Nigeria and the Philippines strains legacy rating throughput.
- Postpaid:Contract billing with credit scoring integration remains standard in developed markets. EU AI Act explainability requirements now govern automated credit decisions.
- Convergent Billing:Unified prepaid-postpaid wallets serve gig-economy workers and migrant populations. Brazilian operators report strongest uptake among informal labor segments.
- Roaming:Inter-carrier settlement complexity intensifies with 5G standalone core deployments. European operators pilot blockchain-verified roaming records.
- Partner Settlement:OTT revenue sharing and content bundling demand granular usage attribution. Indian operators negotiate aggressively with streaming platforms.
Convergent Billing claims the steepest expansion trajectory as operators pursue account simplification, while Prepaid maintains volume dominance.
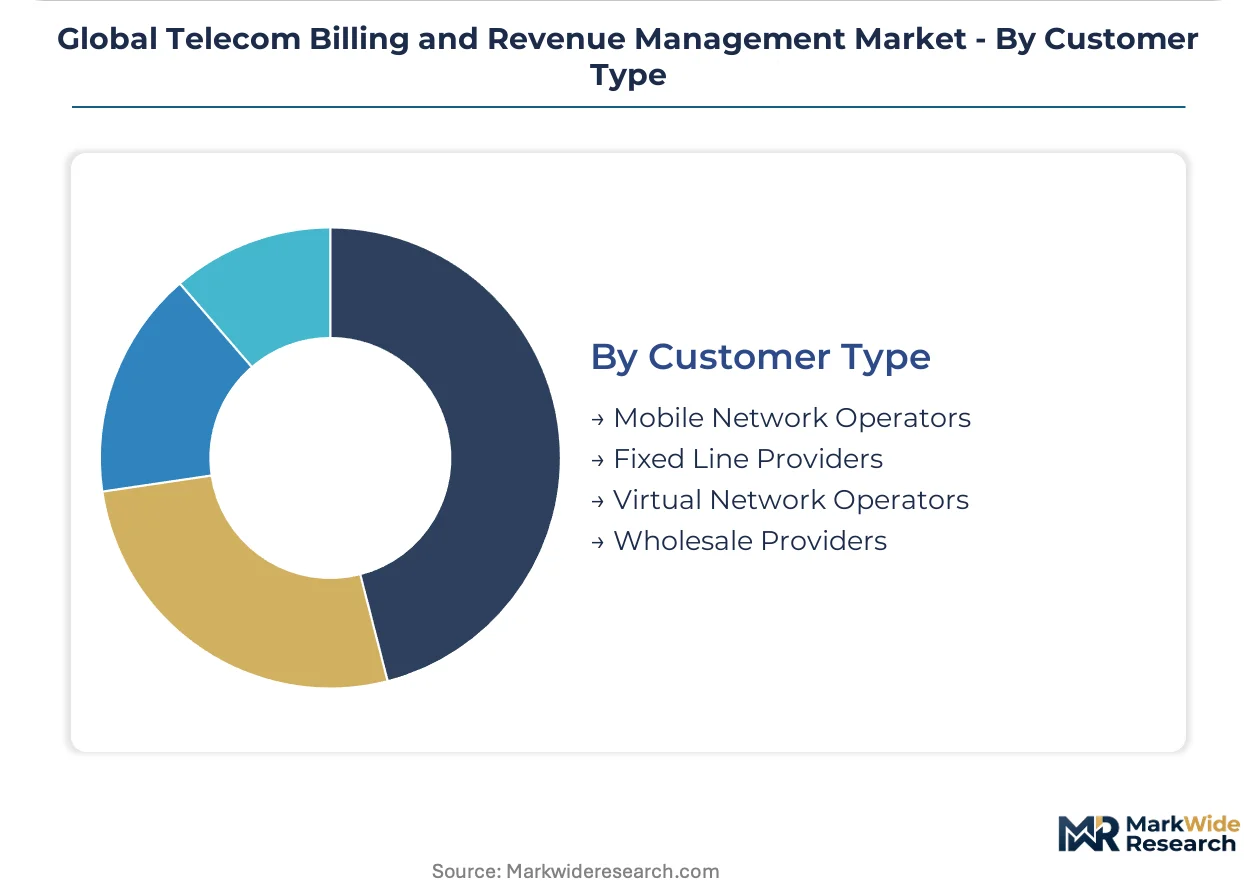
Customer Type:
Procurement sophistication varies sharply across operator business models.
- Mobile Network Operators:Full-stack BSS/OSS replacements consume the largest vendor resources. Tier-one carriers in Germany and Japan drive Kubernetes-native architecture requirements.
- Fixed Line Providers:Broadband and IPTV billing integration lags mobile convergence. Copper-to-fiber migration in rural US markets creates upgrade windows.
- Virtual Network Operators:MVNOs rely on wholesale host platforms with limited customization. European regulatory caps on wholesale pricing compress their IT budgets.
- Wholesale Providers:Capacity resale and infrastructure sharing demand granular usage metering. Tower companies in India expanding into edge compute need event-based charging.
Mobile Network Operators command the deepest vendor relationships, while Virtual Network Operators are gaining procurement sophistication fastest through platform standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile network operators in India, Germany, and South Korea drive procurement volumes for convergent billing platforms. Tier-one carriers prioritize cloud-native architectures as TRAI mandates accelerate digital modernization. Vendor competition fragments across data localization requirements and 5G standalone core deployment timelines.
India
TRAI's digital billing modernization mandates force operators to retire legacy prepaid mediation stacks. The regulator's push for transparent tariff disclosure reshapes vendor selection criteria around real-time rating transparency. Bangalore hosts the densest cluster of cloud-native engineering talent, where Amdocs and Accenture operate captive development centers for Kubernetes-orchestrated deployments.
Germany
Deutsche Telekom and Vodafone Deutschland pilot microservices-based charging infrastructure for 5G standalone cores. GDPR and the EU AI Act impose algorithmic explainability requirements on automated credit scoring modules embedded in billing suites. Munich and Berlin concentrate vendor engineering presence for hybrid cloud deployments that keep sensitive rating functions on-premise.
United States
FCC truth-in-billing rules mandate line-item clarity, directly shaping product roadmaps for vendors serving AT&T and Verizon. Tier-one carriers sustain relationships with CSG International for prepaid billing heritage while migrating postpaid estates to cloud-native stacks. Dallas and Seattle anchor the largest concentrations of BSS/OSS integration specialists.
South Korea
SK Telecom and KT Corporation lead NFV mediation adoption for 5G network function virtualization. The Korea Communications Commission enforces strict data residency for subscriber records, favoring domestic vendors for core charging functions. Seoul's Pangyo Techno Valley clusters the highest density of real-time rating engine startups targeting Asian operator exports.
Brazil
Convergent billing demand concentrates among gig-economy workers and informal labor segments served by Vivo and Claro. Anatel's consumer protection rules shape promotional transparency requirements for prepaid-postpaid wallet unification. São Paulo anchors vendor delivery centers for Portuguese-language support across Latin American operator rollouts.
Global Telecom Billing and Revenue Management Market Competitive Landscape
Player mix skews toward full-stack systems integrators with heritage BSS/OSS portfolios. Tier-one carrier procurement favors end-to-end vendors capable of unified prepaid-postpaid mediation, while emerging market operators fragment spend across specialized rating engine providers. Two strategic archetypes dominate: heritage telecom software vendors with decades of tariff rule accumulation, and cloud-native challengers offering API-first microservices. Competitive moves concentrate on M&A to acquire Kubernetes expertise and strategic partnerships with hyperscale cloud providers for managed service offerings.
Within the heritage systems tier, SAP SE and Oracle Corporation exemplify database-centric vendors extending enterprise resource planning architectures into telecom verticals. CSG International Corporation occupies a distinct position anchored in prepaid billing heritage that sustains North American operator relationships. Huawei Technologies Co Ltd. represents the infrastructure-integrated archetype, competing aggressively on 5G charging infrastructure in markets where geopolitical procurement restrictions do not apply. Ericsson and Amdocs Limited sit within the end-to-end integration tier, serving tier-one carriers with convergent BSS/OSS portfolios spanning mediation through customer care.
| Leading Market Players |
|---|
| SAP SE |
| CSG International Corporation |
| Amdocs Limited |
| Comarch SA |
| Cerillion PLC |
| Huawei Technologies Co Ltd. |
| Accenture PLC |
| Telefonaktiebolaget LM Ericsson |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month ISO 27001 certification timelines compress vendor cash conversion cycles while amplifying pricing power for pre-certified incumbents serving Indian and German operators under TRAI and GDPR mandates. This lead-time band concentrates procurement decisions on audit-ready suppliers, fragmenting price competition across compliance tiers rather than functional performance alone.
Pricing Analysis
Cost-plus contracts with annual CPI indexation dominate managed services engagements for tier-two Southeast Asian operators lacking Kubernetes expertise. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified full-stack vendors from PCI DSS-attested specialists and uncertified challengers. Pricing pressure stems from hyperscale cloud providers bundling basic rating functions into infrastructure contracts. MVNOs exhibit highest price sensitivity due to wholesale host platform dependencies, while tier-one carriers in Germany and Japan prioritize architectural control over unit cost.
Supply Chain Analysis
India and Ireland anchor cloud-native engineering talent clusters where Amdocs and Accenture operate captive development centers for Kubernetes-orchestrated billing deployments. Software supply chains draw from Bangalore's microservices expertise and Tel Aviv's event-driven architecture specialists, with mediation engine components sourced from South Korean NFV vendors. Single-source vulnerability concentrates in real-time rating engine IP held by heritage telecom software vendors. Distribution runs through direct enterprise sales for tier-one carriers and hyperscale marketplace listings for specialized API-first challengers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
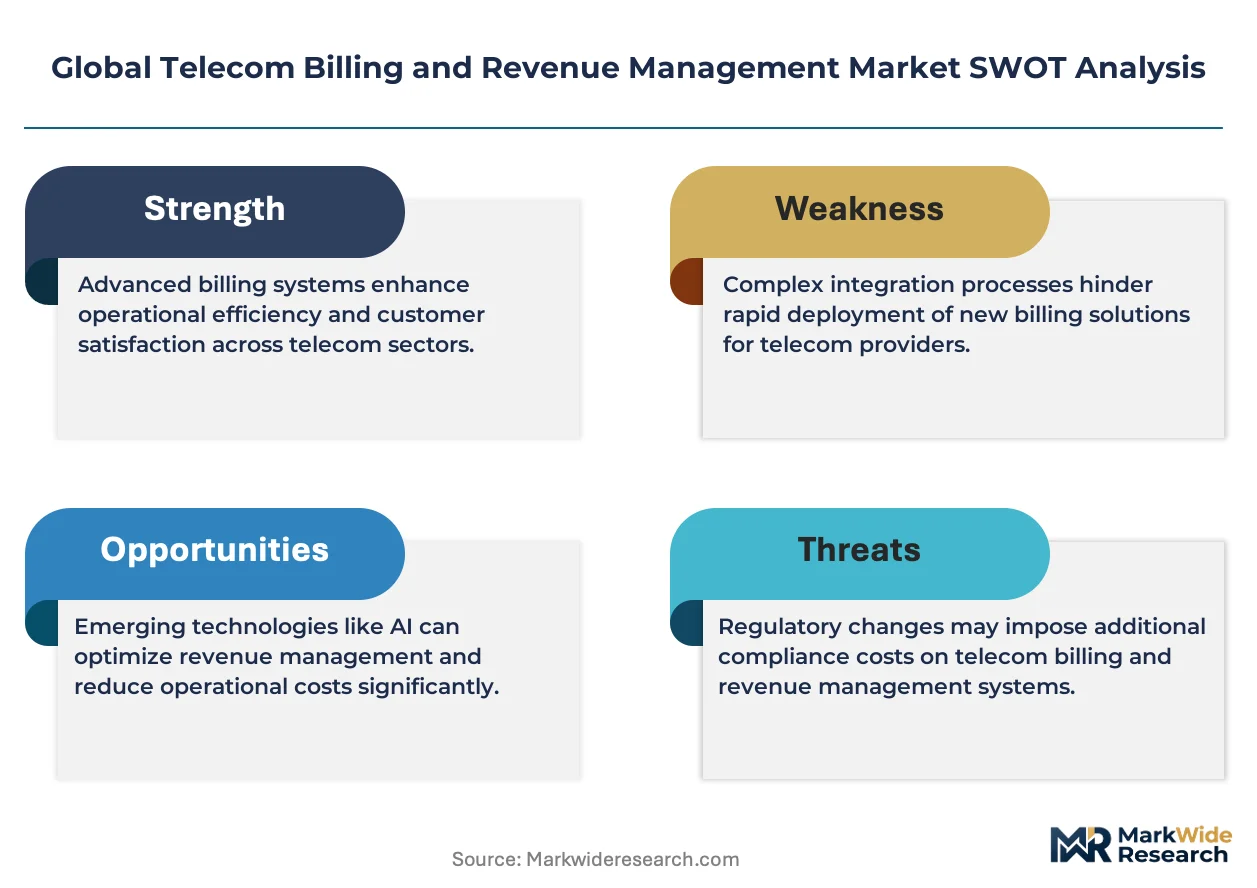
Buyer power is concentrating as tier-one carriers in Germany and Japan consolidate procurement around end-to-end BSS/OSS integrators, fragmenting vendor relationships from multi-year lock-in to quarterly contract terms.
For Market Incumbents: Secure Kubernetes orchestration expertise through targeted capability acquisition in Bangalore and Tel Aviv talent markets. Defend position by accelerating ISO 27001 and PCI DSS attestation pipelines ahead of TRAI-mandated procurement gates in India, while embedding AI explainability interfaces for EU AI Act compliance in German deployments. Cloud-native challengers threaten margin compression through API-first microservices that enable operator component swapping. For New Entrants and Emerging Players: Revenue assurance white space in Southeast Asian markets offers the most penetrable entry point, where fraud management module investment lags subscriber growth velocity. Target Indonesian and Brazilian operators pursuing convergent wallet unification for gig-economy segments. Go-to-market traction requires Kubernetes-certified engineering credentials and rapid PCI DSS attestation to bypass procurement disqualification. For Investors and Strategic Acquirers: Carve-out targets emerge from hyperscale cloud providers divesting vertical-specific billing assets that conflict with platform neutrality positioning. Five-to-ten-year viability hinges on regulatory compliance automation as GDPR and EU AI Act requirements proliferate across European operator estates. Monitor TRAI enforcement intensity in India as the inflection signal for convergent billing replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Kubernetes expertise acquisition in Bangalore compresses deployment timelines for Indian operators under TRAI mandates. |
| Strategic Partnership | Hyperscale cloud alliances enable managed service offerings for Southeast Asian tier-two operators lacking internal expertise. |
| Platform Integration | AI explainability interface development satisfies EU AI Act audit trail requirements for German carrier deployments. |
| Geographic Expansion | Brazilian delivery center establishment captures Portuguese-language convergent billing demand across Latin America. |
| Product Launch | Hourly and daily pass rating engines address subscription fatigue experimentation in Nigerian and Philippine prepaid markets. |
Research Methodology
Initial hypotheses were tested against primary input from BSS/OSS procurement directors, cloud platform engineers, regulatory compliance officers, and tier-one carrier IT architects and refined through secondary validation against TRAI circulars, GDPR implementation guidance, EU AI Act technical standards, SEC 10-K disclosures from listed vendors, and hyperscale cloud provider service documentation. Bottom-up deployment sizing across Indian, German, and Brazilian operator estates triangulated against top-down market aggregation from vendor revenue disclosures.
Variance decomposition across deployment models, solution types, application segments, and customer archetypes structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated 5G standalone core deployment timelines, data localization mandate enforcement patterns, and cloud-native engineering talent availability by geography.
Material uncertainties — geopolitical procurement restrictions on infrastructure-integrated vendors, TRAI and SAMR data residency rule evolution, and Kubernetes skill scarcity concentration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and operator cloud migration velocity. Recalibration cycles align with material shifts in 5G core deployment schedules and certification mandate effective dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Portugal POS Terminals Market
Payments
Africa Virtual Cards Market
Payments
Recurring Payments Market
Payments
Germany Real Time Payments Market
Payments
Enterprise Payment Software Market
Payments
Remittance Market
Payments
Contactless Payment Ring Market
Payments
UK Prepaid Cards Market
Payments
Smart Payment Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
France Mobile Payment Market
Payments
North America POS Terminal Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
France Buy Now Pay Later Services Market
Payments
North America Payment Gateway Market
Payments
Buy Now Pay Later (BNPL) Services Market