
 In Vehicles Payment Market | 2026-2036
In Vehicles Payment Market Size, Share, and Industry Trends Forecast 2026-2036
In Vehicles Payment Market Foresight
Fleet management services are pivoting toward embedded vehicle payment architectures that eliminate driver-mediated transactions. BMW dominates European premium deployments through its ConnectedDrive commerce layer, while Ford Motor Company leverages its FordPass ecosystem to anchor North American fleet integrations. Hyundai Motor competes in Asia-Pacific through partnerships with regional digital wallet providers.
In-vehicle payment systems integrate secure element hardware, tokenization protocols, and automotive-grade connectivity modules to enable fuel, parking, toll, and retail transactions without physical card presentation. These systems typically operate through Near Field Communication or cloud-based architectures with PCI DSS compliance and EMVCo certification as baseline requirements. Payment method segmentation shows digital wallet integrations expanding fastest as OEMs embed Apple Pay, Google Pay, and proprietary wallets into center-stack interfaces, while contactless payment maintains maturity in European markets where fuel retailers pre-installed compatible readers. Vehicle type segmentation reveals electric vehicles leading software-defined payment innovation due to their native connectivity stacks and over-the-air update capabilities.
EMVCo sets tokenization and authentication standards that shape hardware requirements for payment-enabled vehicles across major markets. The Federal Trade Commission monitors data privacy practices in connected car commerce under Section 5 authority, while the EU AI Act imposes risk classification requirements on automated transaction decision systems. Stakeholders must monitor regulatory divergence between EMVCo's global specifications and emerging national data localization mandates that could fragment cloud-based payment architectures.
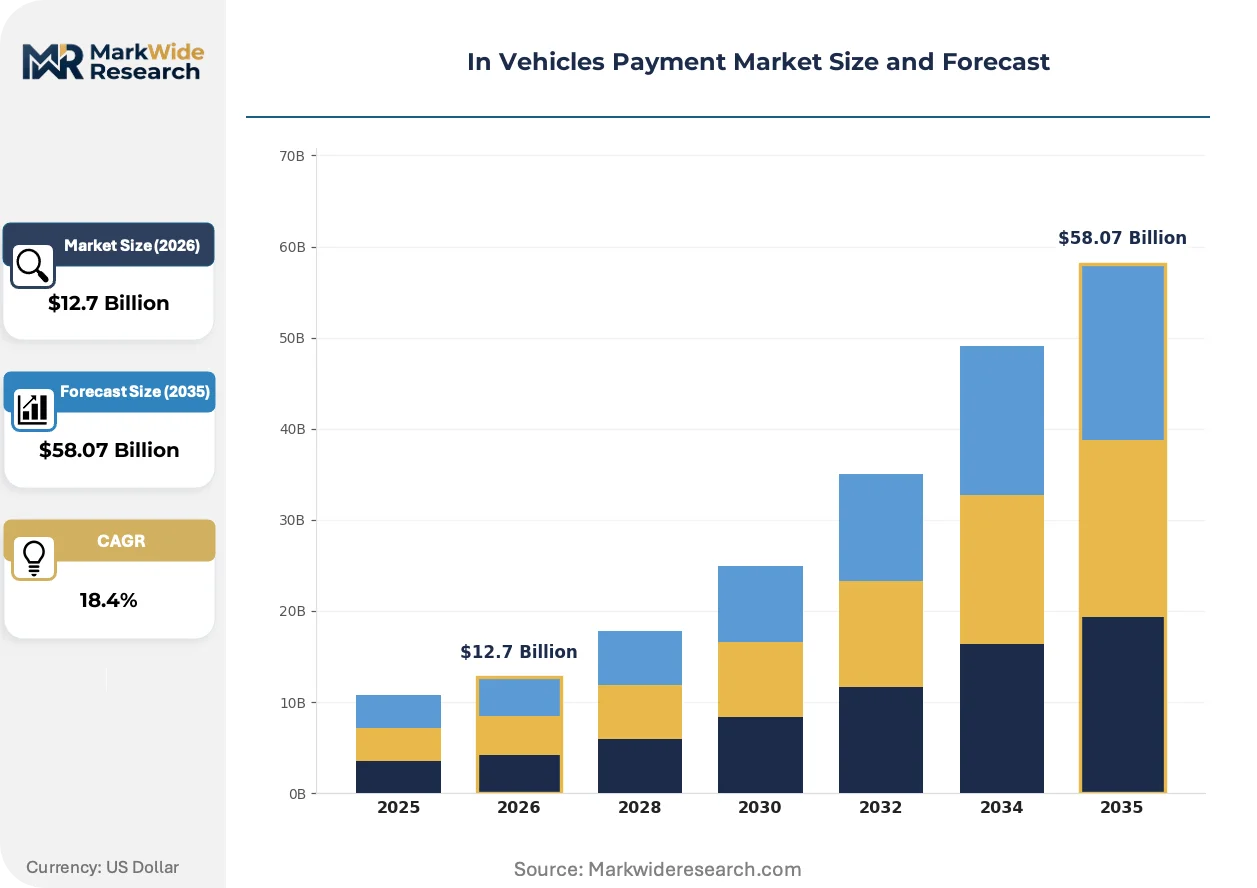
Market Dynamics
Embedded secure element hardware is consolidating transaction authentication directly into vehicle operating systems, eliminating smartphone-tethered architectures and compressing the payment stack into automotive-grade silicon.
Growth Catalysts
- ISO 15118-20:This international standard mandates bidirectional vehicle-grid communication protocols that natively support plug-and-charge payment authentication, accelerating OEM adoption across electric vehicle platforms.
- Fuel retailer infrastructure:Major petroleum chains in Germany and Japan are deploying contactless-enabled pumps that recognize vehicle-embedded credentials, removing manual card insertion from refueling workflows.
- Cloud-native architectures:Over-the-air update capabilities in software-defined vehicles enable continuous payment feature expansion without hardware replacement, extending system lifecycles.
Market Restraints
- Secure element supply concentration:Automotive-grade embedded SIM and secure microcontroller production concentrates in Taiwanese and South Korean foundries, creating single-source vulnerability for payment-enabled vehicles.
- EMVCo certification timelines:Hardware validation cycles for contactless payment modules extend 18-24 months, delaying model-year integrations and compressing revenue recognition windows.
- Smartphone payment stickiness:Established digital wallet ecosystems on iOS and Android platforms create substitution pressure against proprietary vehicle-native payment interfaces.
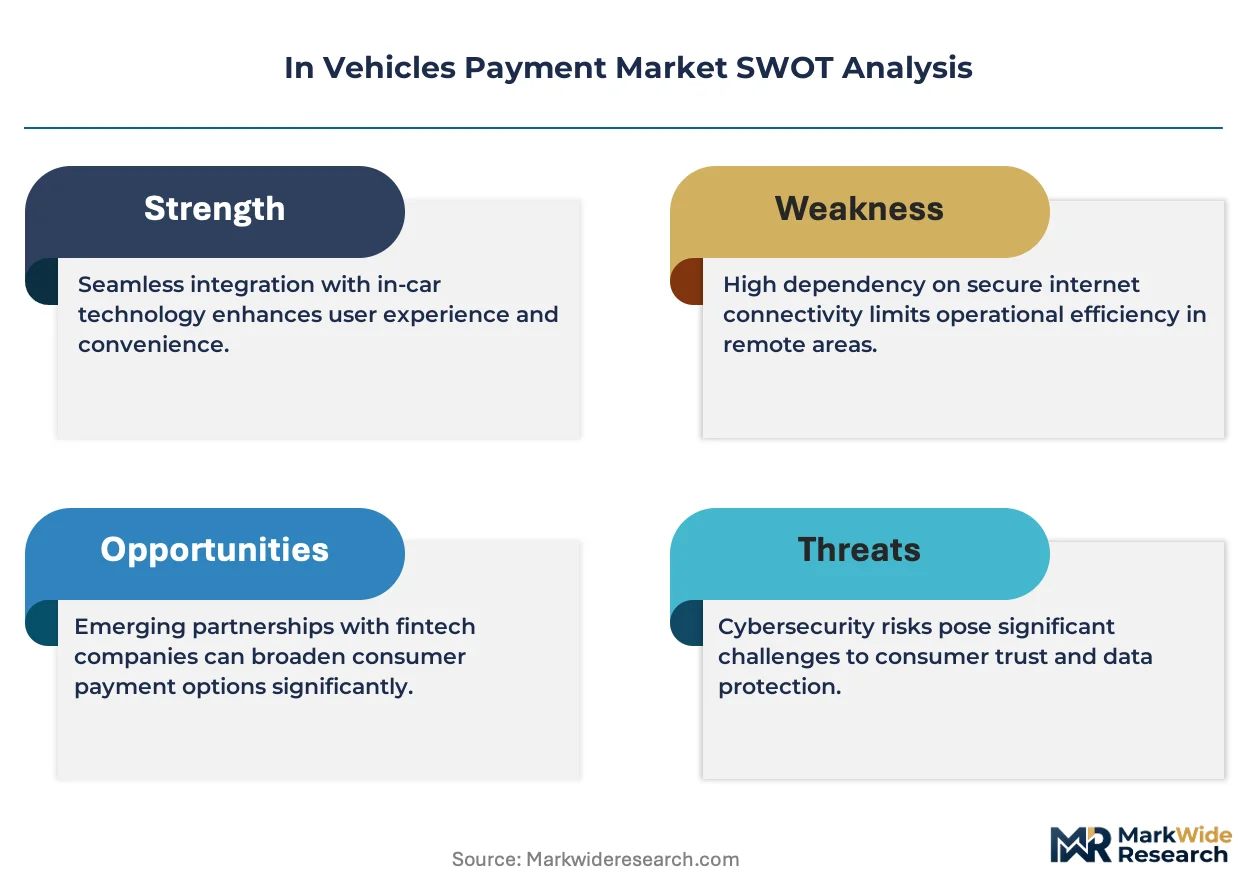
Strategic Opportunities
- India vehicle payment infrastructure:The country's central bank digital currency pilot and FASTag tolling saturation create conditions for unified transport payment systems spanning fuel, parking, and congestion charging.
- Subscription commerce integration:Recurring billing for charging, insurance, and maintenance through embedded vehicle wallets opens recurring revenue streams distinct from one-time transactions.
- EU Data Act interoperability:Mandated data portability requirements force OEMs to open vehicle-generated payment data to third-party financial service providers, fragmenting captive ecosystem control.
Industry Challenges
- Automotive cybersecurity talent scarcity:Payment system architects with dual expertise in PCI DSS compliance and ISO 26262 functional safety remain concentrated in Germany and Japan, constraining development velocity elsewhere.
- Multi-stakeholder liability frameworks:Disputes between OEMs, payment networks, and insurers over transaction fraud attribution create legal complexity that slows deployment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vehicles Payment Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Digital Wallet, Mobile Payment, Contactless Payment Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles End User: Fleet Operators, Individual Users, Ride-Hailing Services, Rental Agencies Technology: Near Field Communication, Blockchain, QR Code Payment, Cloud-Based Payment System |
| Companies Covered | Honda Motor, Ford Motor Company, Hyundai Motor, BMW, Volkswagen, General Motors, Daimler, Jaguar Land Rover Automotive, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vehicles Payment Market Shifts & Advancements
Payment credential virtualization is collapsing hardware differentiation between vehicle classes, while regulatory pressure on data localization fragments cloud architectures that previously enabled seamless cross-border transactions.
Biometric driver authentication is consolidating identity verification into steering wheel capacitive sensors and cabin-facing cameras, replacing PIN entry and smartphone proximity checks. Premium electric vehicle platforms in Germany and California are deploying these systems as standard equipment. This convergence is consolidating payment authorization into continuous driver state monitoring rather than discrete transaction events.
The EU AI Act imposes risk classification requirements on automated transaction decision systems that use machine learning for fraud detection or spending limit adjustments. Automotive OEMs must now document algorithmic transparency and human oversight protocols for in-vehicle payment engines. Electric vehicle fleets operating across EU member states face the most complex compliance burden as they process cross-border transactions subject to divergent national interpretations.
Fleet procurement officers are demanding unbundled payment system pricing separate from telematics and infotainment packages, reversing prior bundled SaaS models. This disaggregation pressures tier-1 suppliers to certify payment modules independently rather than as integrated cockpit systems. The shift is most pronounced in United States commercial fleet channels where procurement teams negotiate payment functionality as a distinct line item against fuel card incumbents.
In Vehicles Payment Market Segmentation
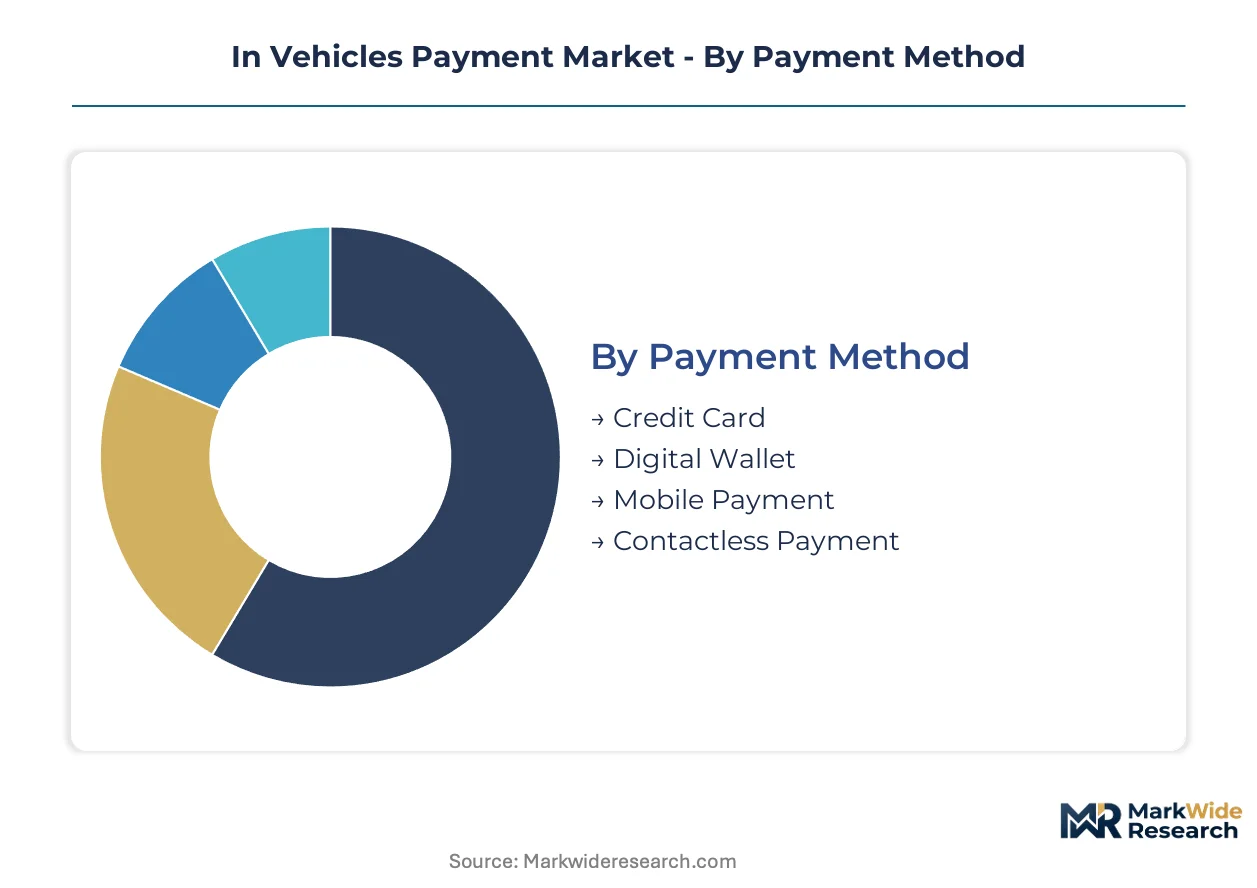
Payment system architectures diverge sharply across vehicle classes and transaction modalities, forcing OEMs to certify multiple hardware configurations. Each segment carries distinct EMVCo compliance requirements and cybersecurity risk profiles that shape procurement decisions.
Payment Method:
Upgrade cycles for in-vehicle payment interfaces accelerate as infotainment systems migrate toward software-defined architectures with over-the-air credential updates.
- Credit Card:Legacy EMV contactless protocols embedded in secure element hardware dominate European fuel retail integrations. German petroleum chains prioritize vehicle-present credential authentication over smartphone-tethered alternatives.
- Digital Wallet:Apple Pay and Google Pay integrations into center-stack displays capture premium electric vehicle deployments. California-based OEMs embed these interfaces as standard equipment to align with consumer smartphone preferences.
- Mobile Payment:Proprietary OEM wallet applications tethered to vehicle operating systems enable subscription billing for charging and maintenance services.
- Contactless Payment:ISO 14443-compliant readers at fuel pumps and parking infrastructure recognize vehicle-embedded credentials without driver interaction.
Contactless Payment sits at the top of the volume ranking, with Digital Wallet climbing the fastest.
Vehicle Type:
Cost tier differentiation separates software-defined payment stacks from legacy CAN-bus tethered systems requiring hardware retrofit.
- Passenger Cars:Mid-market sedans and crossovers integrate payment functionality through infotainment module upgrades rather than dedicated secure elements. Japanese OEMs concentrate deployment in domestic market vehicles first.
- Commercial Vehicles:Fleet procurement specifications increasingly mandate unbundled payment system pricing separate from telematics packages. United States fleet operators negotiate payment functionality as a distinct line item against fuel card incumbents.
- Electric Vehicles:Native connectivity stacks and ISO 15118-20 plug-and-charge protocols position EVs as the primary platform for bidirectional vehicle-grid payment authentication.
- Luxury Vehicles:Biometric steering wheel sensors and cabin-facing cameras consolidate continuous driver authentication into premium segment standard equipment.
Passenger Cars anchor current deployment volumes, though Electric Vehicles are expanding most quickly as OEMs prioritize software-defined architectures.
End User:
Application-specific transaction patterns shape hardware certification priorities across stakeholder groups with divergent fraud liability tolerances.
- Fleet Operators:Centralized payment reconciliation and fuel spend controls drive demand for vehicle-native credential management with real-time telematics integration.
- Individual Users:Consumer preference for smartphone wallet continuity creates substitution pressure against proprietary vehicle payment interfaces.
- Ride-Hailing Services:High-frequency transaction volumes with driver rotation require robust multi-user authentication protocols and automated expense allocation.
- Rental Agencies:Temporary credential provisioning and automated toll reconciliation prioritize cloud-based payment architectures over embedded secure elements.
Fleet Operators command the largest transaction volume share, with Ride-Hailing Services gaining share fastest due to platform-scale deployment mandates.
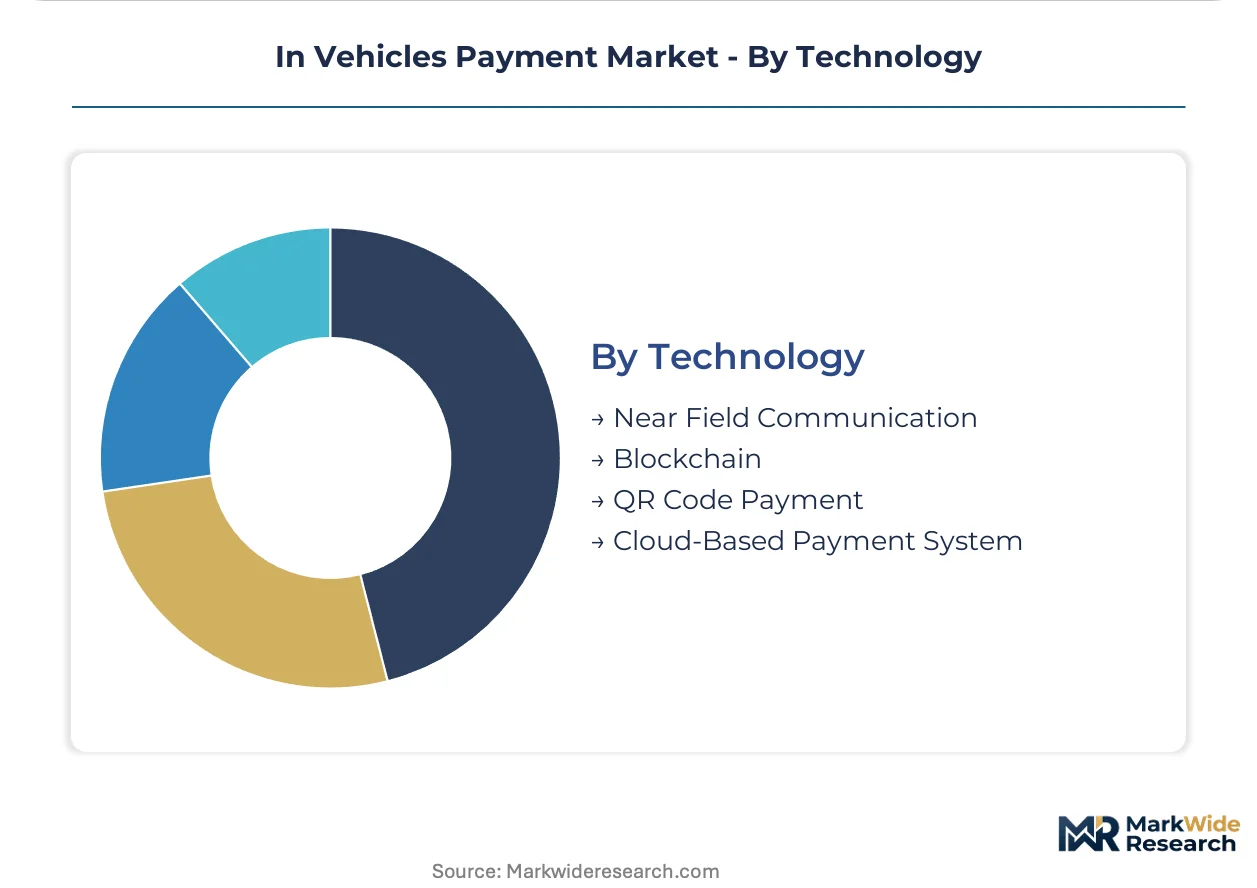
Technology:
Maturity curves separate field-proven proximity protocols from emerging distributed ledger architectures still awaiting automotive-grade certification.
- Near Field Communication:ISO and EMVCo standards govern short-range vehicle-to-infrastructure authentication at fuel pumps, parking terminals, and toll plazas. Hardware certification cycles extend 18-24 months for automotive-grade modules.
- Blockchain:Distributed ledger credential verification remains in pilot phase for peer-to-peer vehicle sharing and cross-border fleet reconciliation applications.
- QR Code Payment:Camera-based transaction initiation dominates emerging market deployments where smartphone penetration exceeds embedded secure element availability.
- Cloud-Based Payment System:Over-the-air credential provisioning enables continuous feature expansion without hardware replacement, extending system lifecycles across software-defined vehicle platforms.
Near Field Communication maintains volume leadership, while Cloud-Based Payment System shows the steepest expansion trajectory as OEMs prioritize software-defined architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor from Stuttgart to Munich anchors embedded payment hardware certification, with OEMs integrating secure elements directly into vehicle operating systems for fuel and toll authentication.
Germany
Fuel retailer infrastructure upgrades and fleet management digitization drive demand for vehicle-native payment stacks. The KBA enforces automotive cybersecurity standards for connected commerce modules. Stuttgart-based OEMs deploy ISO 15118-20 plug-and-charge protocols across electric vehicle platforms, eliminating manual authentication at charging stations.
United States
Fleet procurement unbundling and smartphone wallet continuity preferences shape competitive dynamics. The FTC monitors data privacy practices in connected car commerce under Section 5 authority. Detroit automakers and California-based electric vehicle manufacturers compete through FordPass and proprietary center-stack payment interfaces.
Japan
Contactless fuel pump deployment and domestic OEM prioritization of infotainment-integrated wallets accelerate adoption. METI coordinates standards alignment between automotive and financial sectors. Tokyo-Nagoya industrial corridor hosts concentrated secure element foundry partnerships for automotive-grade silicon production.
India
Central bank digital currency pilots and FASTag tolling saturation create unified transport payment opportunities spanning fuel, parking, and congestion charging. The RBI governs digital wallet interoperability and data localization requirements for vehicle-embedded financial services. Maharashtra and Karnataka host emerging telematics integration hubs for fleet payment reconciliation.
South Korea
Electric vehicle software-defined architectures and over-the-air update capabilities position domestic OEMs for continuous payment feature expansion. The MFDS and financial regulators coordinate on automotive-grade secure element certification. Seoul Capital Area concentrates semiconductor foundry capacity for embedded SIM and secure microcontroller production serving payment-enabled vehicles.
In Vehicles Payment Market Competitive Landscape
Strategic partnerships dominate the current landscape as OEMs embed payment stacks into vehicle operating systems rather than relying on smartphone-tethered architectures. The market structure concentrates around integrated automotive groups with captive infotainment platforms, tier-1 electronics suppliers, and technology licensors. Three archetypes define positioning: full-stack OEMs controlling hardware and software layers, module specialists certifying secure elements independently, and platform aggregators bridging vehicle credentials with retail payment networks. Portfolio diversification and technology licensing represent the primary competitive vectors as stakeholders navigate EMVCo certification timelines.
Among Germany-based integrated automotive groups, BMW and Daimler exemplify full-stack OEM archetypes with proprietary commerce layers, while ZF Friedrichshafen occupies a position among tier-1 module specialists certifying payment hardware independently of complete cockpit systems. These entities anchor distinct strategic postures: captive ecosystem control versus unbundled component supply to competing vehicle manufacturers.
| Leading Market Players |
|---|
| Honda Motor |
| Ford Motor Company |
| Hyundai Motor |
| BMW |
| Volkswagen |
| General Motors |
| Daimler |
| Jaguar Land Rover Automotive |
| ZF Friedrichshafen |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic transparency requirements gate qualified supply for payment-enabled vehicles and premium-tier pricing access, forcing OEMs to document human oversight protocols before securing EMVCo certification for center-stack transaction modules.
Pricing Analysis
Distributor margins on secure element hardware compress as tier-1 suppliers certify payment modules independently of complete cockpit systems. Three-tier pricing structure across premium, standard, and economy levels separates biometric-authenticated luxury platforms from mid-market infotainment upgrades and fleet-specification base configurations. Cost compression in mid-market passenger cars intensifies because Japanese OEMs prioritize domestic market deployment before export qualification. Fleet procurement officers exhibit highest price sensitivity, negotiating payment functionality as unbundled line items against fuel card incumbents, while luxury electric vehicle buyers accept biometric sensor premiums for continuous authentication.
Supply Chain Analysis
India's domestic-content mandates for financial data localization reshape sourcing patterns for cloud-based payment architectures serving vehicle-embedded wallets. Automotive-grade secure microcontroller production concentrates in Taiwan, South Korea, and Germany, drawing from silicon wafer feedstock subject to foundry capacity constraints. Single-source vulnerability pervades embedded SIM manufacturing where Seoul Capital Area foundries anchor global supply. Distribution runs through tier-1 electronics suppliers certifying hardware independently before OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The In Vehicles Payment Market functions as a stable compounder where ISO 15118-20 plug-and-charge protocol standardization drives steady replacement demand across electric vehicle platforms.
For Market Incumbents: Acquire specialized automotive cybersecurity talent pools concentrated in Germany and Japan to defend against smartphone wallet substitution pressure. Secure EMVCo certification for independent payment modules before bundled SaaS models fully disaggregate. Expand backward integration into secure element foundry partnerships in Taiwan and South Korea to mitigate single-source supply risk.
For New Entrants and Emerging Players: The mid-tier price-point gap between BMW ConnectedDrive premium deployments and economy fleet specifications offers white-space entry. Target United States commercial fleet channels where procurement teams negotiate payment functionality as distinct line items. Pursue cloud-native payment architectures with over-the-air credential provisioning to bypass 18-24 month hardware certification timelines.
For Investors and Strategic Acquirers: Roll-up economics work for tier-1 module specialists because EMVCo certification barriers fragment supply and create captive customer relationships with multi-year model-year commitments. Platform consolidation among secure element certifiers offers 5-10 year viability as software-defined vehicle architectures extend payment system lifecycles. Monitor biometric authentication deployment rates in California and Germany as inflection indicators for premium-tier adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo Hardware Certification Investment | Accelerates model-year integration timelines for payment-enabled vehicles. |
| Cloud-Native Payment Architecture Migration | Enables continuous feature expansion through over-the-air credential updates. |
| Biometric Authentication Partnership | Consolidates continuous driver verification into steering wheel sensors. |
| Fleet Procurement Channel Expansion | Captures unbundled payment system demand from United States commercial operators. |
| Regional Digital Wallet Integration | Aligns center-stack interfaces with Apple Pay and Google Pay consumer preferences. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-1 supplier procurement leads, fleet management operators, and EMVCo certification specialists alongside secondary validation. SEC filings from automotive electronics suppliers, EMVCo hardware certification databases, vehicle production registries, and customs trade records anchored bottom-up and top-down triangulation.
Segment-weighting approaches distributed value and volume across payment method, vehicle type, end user, and technology dimensions throughout the forecast period. CAGRs derived from installed base penetration curves for connected infotainment systems and electric vehicle production forecasts. Modeled inputs included ISO 15118-20 adoption timelines and secure element foundry capacity utilization.
Caveats apply where EMVCo certification delays or data localization mandate divergence could materially shift the outlook. Forecasts reflect assumptions about smartphone wallet continuity preferences and automotive cybersecurity talent availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
France Virtual Cards Market
Payments
Indonesia Prepaid Cards Market
Payments
India Forex Cards Market
Payments
Mobile Payment Data Protection Market
Payments
France Payments Market
Payments
Denmark POS Terminals Market
Payments
Norway POS Terminals Market
Payments
India Payment Gateway Market
Payments
QR Codes Payment Market
Payments
Transit Cards Market
Payments
Singapore Payments Market
Payments
Germany Real Time Payments Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Norway Payments Market
Payments
Contactless Payment Terminals Market