
 South Africa Gift Card and Incentive Card Market | 2026-2036
South Africa Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Gift Card and Incentive Card Market Analytics
Supermarket and hypermarket distribution is tilting toward integrated digital redemption platforms across South Africa's major retail chains. Shoprite Holdings Ltd leverages its extensive store network to anchor physical gift card availability in underserved townships and secondary cities. Pick 'n' Pay Stores Ltd competes through its mobile app ecosystem, linking in-store purchases to digital wallet credits. Woolworths Holdings Ltd (South Africa) differentiates via premium positioning in the personal gifting segment, sustaining higher average transaction values.
South Africa gift cards and incentive cards are stored-value instruments encoded with magnetic stripes, barcodes, or NFC chips that carry predetermined monetary value for redemption at designated merchants or networks. These instruments function as closed-loop or open-loop payment tools, with digital variants relying on tokenization and API integrations for real-time balance verification. The retail gift card category dominates transaction volume through supermarket chains and fashion retailers, while the digital gift card segment records the fastest growth trajectory as smartphone penetration deepens and mobile banking adoption accelerates. The prepaid incentive card category captures concentrated margin pools within corporate channels, where bulk procurement and customized branding command premium pricing.
The Financial Sector Conduct Authority and the South African Reserve Bank govern stored-value facility licensing and payment system integrity, while the Protection of Personal Information Act imposes strict data handling protocols on card issuers processing consumer information. Compliance with these frameworks elevates operational costs for new entrants but reinforces trust barriers that protect established retail banking partnerships. Stakeholders must monitor evolving central bank directives on e-money issuance and assess whether regulatory clarity on cross-border digital redemption will unlock regional expansion into neighboring Southern African Development Community economies.
Market Dynamics
Corporate HR departments are expanding prepaid incentive card adoption for employee recognition programs, while the Protection of Personal Information Act imposes strict data governance requirements on digital wallet and card data handling. This regulatory pressure is compressing operational timelines for new entrants and elevating compliance costs across issuance platforms.
Growth Catalysts
- Protection of Personal Information Act compliance:The regulation mandates stringent consumer data handling protocols, forcing established issuers to upgrade infrastructure and creating trust barriers that protect incumbent retail banking partnerships.
- Smartphone penetration deepening:Mobile banking adoption accelerates digital gift card redemption velocity, with tokenization and API integrations enabling real-time balance verification across supermarket and fashion retail networks.
- Gauteng province concentration:Johannesburg and Pretoria host the densest corporate headquarters and retail infrastructure, anchoring bulk procurement demand for closed-loop and open-loop payment instruments.
Market Restraints
- Stored-value facility licensing costs:The South African Reserve Bank and Financial Sector Conduct Authority compliance requirements elevate capital barriers for new entrants seeking to issue e-money instruments.
- Cross-border redemption uncertainty:Regulatory clarity gaps on digital redemption into neighboring Southern African Development Community economies limit regional expansion potential for domestic issuers.
- Magnetic stripe legacy infrastructure:Physical card encoding systems require sustained maintenance investment even as NFC chip and barcode adoption accelerates, creating dual-platform cost burdens.
Strategic Opportunities
- Western Cape secondary cities:Cape Town and surrounding metropolitan areas show underpenetrated corporate incentive card adoption relative to Gauteng, presenting whitespace for specialized B2B issuers.
- Integrated digital redemption platforms:Supermarket chains are consolidating physical and mobile app ecosystems, enabling issuers to capture township and secondary city markets through single-integration partnerships.
- Corporate bulk procurement channels:Customized branding and premium pricing in prepaid incentive cards command concentrated margin pools within HR recognition program budgets.
Industry Challenges
- API integration complexity:Real-time balance verification systems require specialized technical talent scarce in South Africa's fintech labor market, extending deployment timelines for digital-first issuers.
- Data governance audit cycles:Protection of Personal Information Act compliance necessitates recurring third-party assessments, creating operational friction for issuers processing consumer transaction histories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Gift Card and Incentive Card Market |
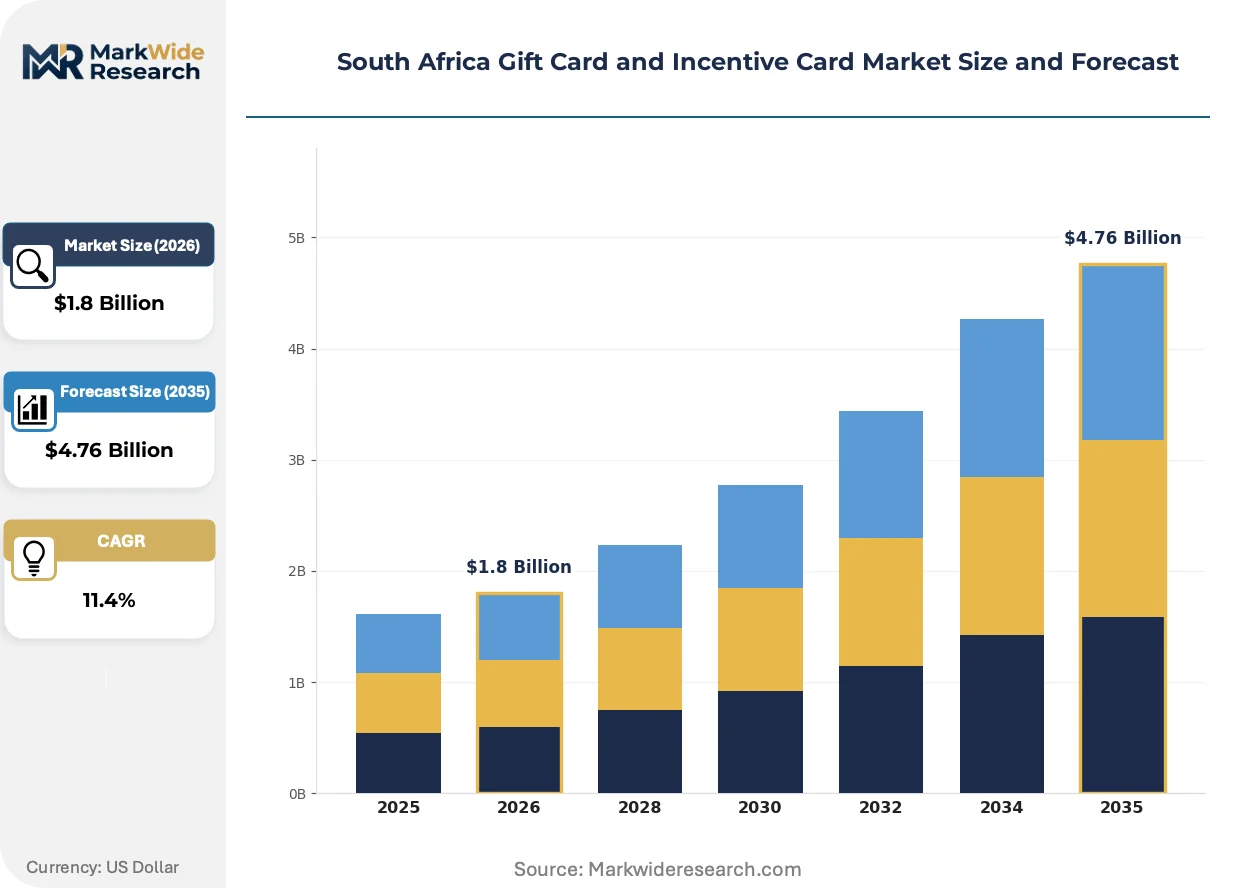
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Retail Gift Card, Restaurant Gift Card, Prepaid Incentive Card, Digital Gift Card Usage Purpose: Employee Incentives, Customer Loyalty, Event Promotion, Personal Gifting Distribution Channel: Online Retail, Physical Stores, Mobile Apps, Corporate Channels Denomination: Low Value, Medium Value, High Value, Custom Amounts |
| Companies Covered | Internationale Spar Centrale BV, Takealot, Shoprite Holdings Ltd, Cape Union Mart, Checkers, Pick 'n' Pay Stores Ltd, Walmart Stores Inc, Creative Incentives, Woolworths Holdings Ltd (South Africa), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Gift Card and Incentive Card Market Evolving Landscape
Digital wallet architectures are converging with retail loyalty ecosystems, compressing the distinction between stored-value instruments and programmable payment credentials. This convergence is forcing issuers to replatform around API-first infrastructure.
Tokenization technology is hybridizing gift card security models. The protocol replaces static magnetic stripe data with dynamic, single-use credentials. Major retail chains are adopting this standard to reduce fraud exposure in high-volume supermarket redemption environments. This hybridization is compressing differentiation between physical and digital issuance channels.
The Protection of Personal Information Act is reshaping data architecture requirements for card issuers. The regulation mandates encryption standards and breach notification protocols that elevate operational costs. Digital gift card segments face the steepest compliance burden due to real-time consumer data processing across mobile banking integrations.
Buyer concentration in corporate procurement is fragmenting issuer revenue models. HR departments are unbundling bulk incentive card purchases from single-vendor relationships, instead adopting multi-issuer programs that optimize redemption flexibility. This pattern is most visible in Gauteng province, where Johannesburg-based headquarters pilot multi-platform recognition systems before national rollout.
South Africa Gift Card and Incentive Card Market Segmentation
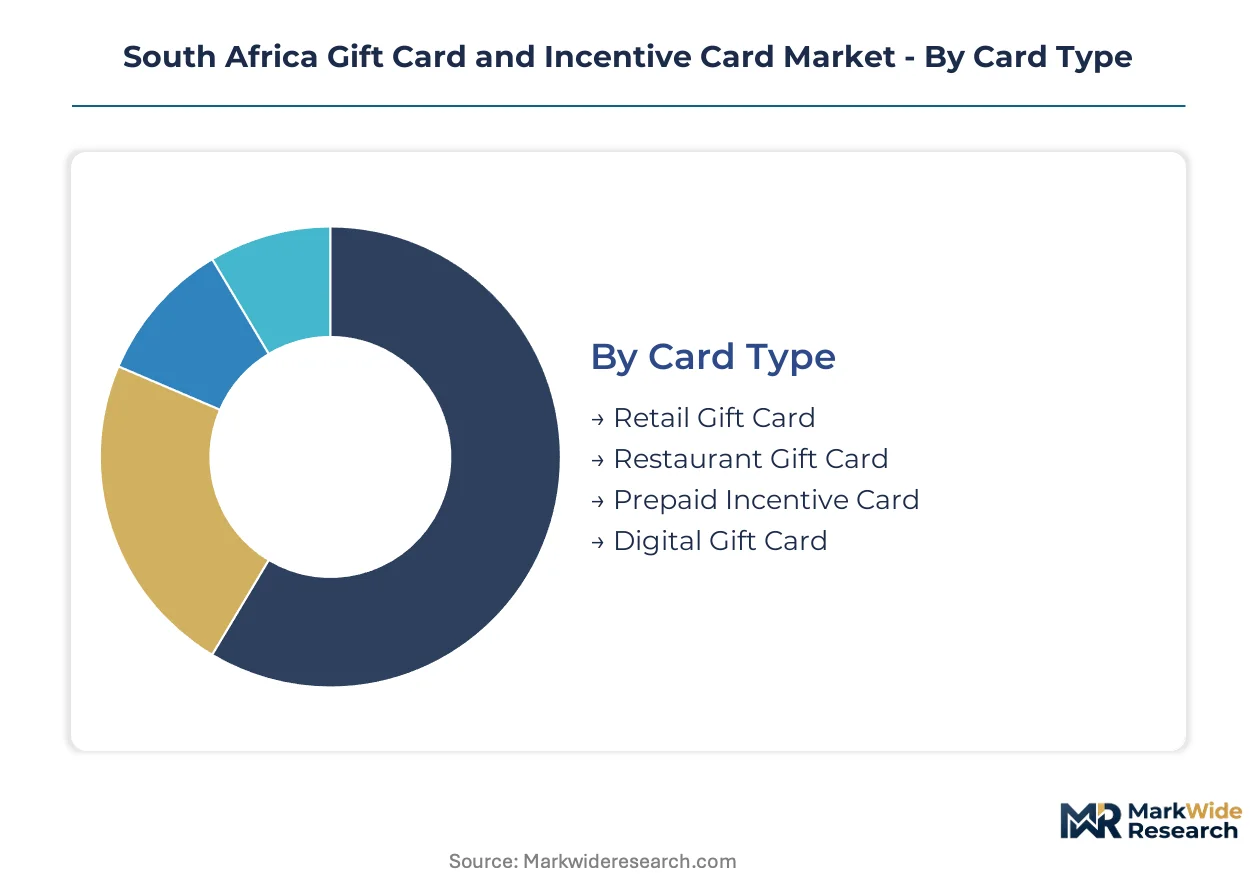
Segmentation in South Africa's gift card market reveals divergent service intensity requirements across issuance channels. Corporate bulk procurement demands dedicated account management, while digital-first segments prioritize API reliability over human touchpoints.
Card Type:
After-sales service intensity varies sharply across physical versus digital encoding formats, with magnetic stripe systems requiring field maintenance networks that NFC-enabled alternatives have largely displaced.
- Retail Gift Card:Closed-loop instruments encoded with magnetic stripes or barcodes, redeemable exclusively at designated merchant networks. Shoprite Holdings Ltd anchors volume through township store penetration, though legacy infrastructure demands sustained technical support. These cards dominate transaction volume through supermarket and fashion retail chains.
- Digital Gift Card:Tokenized credentials delivered via SMS, email, or mobile app integrations, with real-time balance verification through API connections. Smartphone penetration deepening in Gauteng province accelerates redemption velocity, compressing the distinction between stored-value instruments and programmable payment credentials. This segment climbs the fastest as mobile banking adoption accelerates.
- Prepaid Incentive Card:Open-loop or restricted-network instruments deployed through corporate HR recognition programs. Bulk procurement and customized branding command premium pricing, with concentrated margin pools in Johannesburg and Pretoria headquarters.
- Restaurant Gift Card:Sector-specific closed-loop instruments tied to quick-service or full-service dining chains. Distribution concentrates in urban centers with dense commercial office employment.
Retail Gift Card holds the largest share; momentum sits with Digital Gift Card.
Usage Purpose:
Cost tier stratification separates enterprise-grade corporate deployments from consumer-facing personal gifting, with Employee Incentives commanding 3-4x per-unit economics over mass-market segments.
- Employee Incentives:Structured recognition programs administered through HR departments, featuring customized branding and bulk fulfillment workflows. Gauteng province corporate headquarters drive procurement concentration, with multi-issuer programs fragmenting traditional single-vendor relationships.
- Personal Gifting:Individual purchase occasions including birthdays, holidays, and celebrations. Woolworths Holdings Ltd sustains premium positioning here, capturing higher average transaction values through quality positioning.
- Customer Loyalty:Retention-focused issuance tied to retail membership programs and purchase-triggered rewards. Pick 'n' Pay Stores Ltd links these to mobile app ecosystems.
- Event Promotion:Time-bound campaigns including product launches, brand activations, and sponsorship integrations. Shorter redemption windows compress customer service requirements.
Employee Incentives captures the highest margin tier; Personal Gifting shows steadiest volume expansion.
Distribution Channel:
Volume concentration tilts toward integrated platforms that consolidate physical and digital touchpoints, reducing issuer integration overhead.
- Physical Stores:Card-present purchase and redemption through supermarket, hypermarket, and specialty retail locations. Shoprite Holdings Ltd leverages extensive network coverage to anchor availability in underserved secondary cities and townships.
- Corporate Channels:Direct B2B procurement relationships with HR departments and procurement offices. Bulk ordering workflows and customized fulfillment elevate service intensity requirements.
- Online Retail:Browser-based purchase portals with email or SMS delivery of digital credentials. Lower touchpoint density reduces per-transaction support costs.
- Mobile Apps:In-app issuance and wallet integration through retailer or banking applications. API-first infrastructure demands specialized technical talent scarce in South Africa's fintech labor market.
Physical Stores retains dominant transaction share; Mobile Apps gain share fastest through platform consolidation.
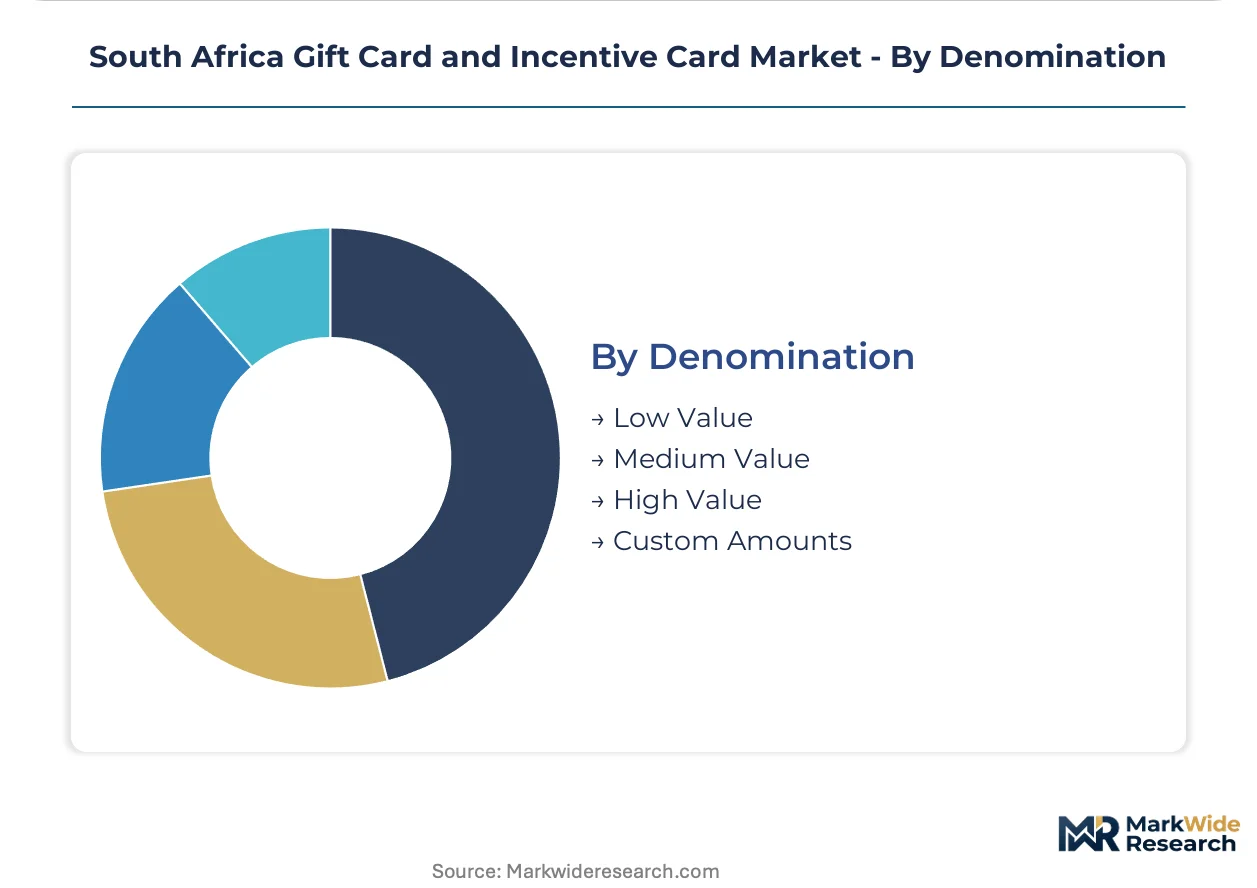
Denomination:
Customer type stratification separates standardized low-value instruments from negotiated enterprise custom amounts, with procurement scale determining pricing flexibility.
- Custom Amounts:Flexible-value issuance configured at point of purchase or through corporate procurement specifications. HR recognition programs favor these for precise budget alignment and recipient personalization.
- High Value:Premium-tier instruments typically exceeding mid-range thresholds, concentrated in executive gifting and senior employee recognition.
- Medium Value:Standardized mid-range denominations balancing perceived generosity with procurement efficiency. Corporate bulk procurement optimizes around these tiers.
- Low Value:Entry-level denominations for mass-market promotional campaigns and small-scale personal gifting. Highest redemption velocity compresses margin per unit.
Medium Value dominates procurement volume; Custom Amounts show steepest expansion in corporate channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The South African Reserve Bank anchors monetary governance across the country's stored-value facility licensing framework. Provincial economic concentration drives divergent adoption patterns for gift card and incentive card instruments.
Gauteng
Johannesburg and Pretoria host the densest corporate headquarters and retail infrastructure in South Africa. The Financial Sector Conduct Authority mandates strict compliance protocols for issuers operating in this economic hub. Bulk procurement demand for closed-loop and open-loop payment instruments concentrates here, with HR departments piloting multi-platform recognition systems.
Western Cape
Cape Town and surrounding metropolitan areas show underpenetrated corporate incentive card adoption relative to Gauteng. The Protection of Personal Information Act imposes encryption standards on digital wallet architectures processing consumer data in this region. Specialized B2B issuers target whitespace opportunities in secondary city markets.
KwaZulu-Natal
Durban anchors retail distribution networks serving coastal consumer bases with supermarket and hypermarket gift card availability. The South African Reserve Bank's e-money directives shape issuance compliance costs for regional operators. Township store penetration by major retail chains extends physical card accessibility.
Eastern Cape
Port Elizabeth and surrounding industrial zones generate moderate demand for employee incentive programs in manufacturing sectors. Data governance audit cycles under POPIA create operational friction for issuers processing transaction histories. Secondary city infrastructure gaps limit digital-first platform deployment.
Free State
Bloemfontein's centralized location supports logistics networks distributing prepaid instruments to interior markets. Regulatory clarity gaps on cross-border digital redemption constrain expansion into neighboring Southern African Development Community economies. Legacy magnetic stripe infrastructure requires sustained maintenance investment.
South Africa Gift Card and Incentive Card Market Competitive Landscape
Retail conglomerates and specialized incentive providers split the market between mass-volume distribution and premium corporate channels. The vendor base tilts toward integrated supermarket-hypermarket networks with extensive physical footprints. Three archetypes dominate: nationwide retail chains with proprietary card programs, dedicated incentive management specialists, and international retail operators with localized adaptation. Competitive moves center on mobile app ecosystem integration and corporate bulk procurement relationship consolidation.
Among South Africa-based retail conglomerates, Shoprite Holdings Ltd and Pick 'n' Pay Stores Ltd exemplify the mass-volume archetype through extensive township and secondary city penetration. Woolworths Holdings Ltd (South Africa) occupies a premium positioning tier in personal gifting segments. Internationale Spar Centrale BV represents international retail operator adaptation to local market conditions. Creative Incentives anchors the specialized B2B incentive management segment.
| Leading Market Players |
|---|
| Internationale Spar Centrale BV |
| Takealot |
| Shoprite Holdings Ltd |
| Cape Union Mart |
| Checkers |
| Pick 'n' Pay Stores Ltd |
| Walmart Stores Inc |
| Creative Incentives |
| Woolworths Holdings Ltd (South Africa) |
| Others |
Value Network & Pricing Analysis
Single-source dependency on NFC chip suppliers from East Asian manufacturing hubs compresses margin structures across both premium customized issuance and standardized digital credential tiers, forcing South African issuers to absorb currency volatility while maintaining competitive redemption economics.
Pricing Analysis
The customization-premium spread separates bulk corporate incentive programs from mass-market retail instruments. Three-tier pricing structure across premium, standard, and economy levels captures differentiated service intensity, with Employee Incentives commanding premium positioning through bespoke branding and dedicated account management. Price differentiation hinges on API integration complexity and after-sales support bundling. Cost compression in entry-level digital segments is intensifying because tokenization infrastructure costs are amortizing across higher issuance volumes. Mass-market personal gifting shows highest price sensitivity, while corporate procurement demonstrates lowest sensitivity due to budget allocation flexibility.
Supply Chain Analysis
Supplier-financing facilities from East Asian semiconductor manufacturers extend payment terms for South African issuers purchasing NFC chips and magnetic stripe encoding equipment. Component sourcing draws from China, Taiwan, and South Korea for secure element chips, card substrates, and POS terminal hardware. Raw material dependencies include polyvinyl chloride card stock, electromagnetic shielding films, and cryptographic security modules. Single-source vulnerability concentrates in advanced NFC controller supply. Distribution runs through integrated retail conglomerates with proprietary logistics networks spanning township and secondary city markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API engineering talent scarcity in South Africa's fintech labor market constrains deployment velocity for digital-first issuers, elevating acquisition premiums for teams with proven tokenization and real-time balance verification expertise.
For Market Incumbents: Entrench market position through backward integration into card personalization facilities and captive supply of NFC chip inventory buffers against East Asian supply volatility. Defensive consolidation should prioritize exclusive API integration partnerships with Shoprite Holdings Ltd and Pick 'n' Pay Stores Ltd to lock out emerging digital entrants from supermarket redemption networks. For New Entrants and Emerging Players: Western Cape secondary cities represent the most penetrable entry point for specialized B2B incentive issuers, with Cape Town corporate headquarters showing underpenetrated adoption relative to Gauteng saturation. Township store networks through independent retail distributors offer alternative channel access circumventing incumbent supermarket exclusivity. Go-to-market execution should anchor on POPIA compliance certification as a trust-building credential against established banking partnerships. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors acquirers with existing retail banking relationships and regulatory licensing infrastructure. Long-term viability over the coming decade hinges on digital wallet convergence with programmable loyalty ecosystems. Acquisition target archetype: mid-scale incentive specialists with proven corporate HR procurement relationships and POPIA-compliant data architectures. The signal to watch is central bank clarity on cross-border e-money issuance into Southern African Development Community markets.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables real-time balance verification across Shoprite and Pick 'n' Pay redemption networks. |
| POPIA Compliance Certification | Creates trust barriers protecting incumbent data architectures from new entrant disruption. |
| Corporate Channel Expansion | Captures concentrated margin pools in Johannesburg and Pretoria HR recognition budgets. |
| Tokenization Infrastructure Deployment | Reduces fraud exposure in high-volume supermarket redemption environments. |
| Western Cape Geographic Penetration | Addresses whitespace in Cape Town corporate incentive adoption relative to Gauteng. |
Research Methodology
Desk research of South African Reserve Bank e-money directives, Financial Sector Conduct Authority licensing records, and Protection of Personal Information Act compliance frameworks preceded structured interviews with prepaid card program managers, digital wallet architects, corporate procurement officers, and retail loyalty platform directors. Primary fieldwork combined with secondary validation against supermarket chain annual reports, mobile banking adoption statistics, and customs data on card substrate imports. Bottom-up issuance volume estimates triangulated against top-down payment instrument flow data from the central bank.
Assumptions held fixed include current POPIA enforcement intensity and existing stored-value facility licensing thresholds, while smartphone penetration trajectories and corporate HR digitization rates were varied across sensitivity scenarios. Segmentation modeling incorporated card type, usage purpose, distribution channel, and denomination tier dimensions alongside regional provincial adoption patterns. CAGRs were derived from fitted growth curves calibrated to historical issuance velocity and mobile banking correlation coefficients.
Macroeconomic conditions sit as an overlay; deviation in rand exchange rate volatility, central bank e-money policy shifts, or cross-border regulatory harmonization would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Contactless Payment Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Enterprise Payment Software Market
Payments
Japan Payments Market
Payments
Global Digital Wallets Market
Payments
New Zealand Payments Market
Payments
Latin America Subscription and Billing Management Market
Payments
Global Gift Card Market
Payments
Global Smart Payment Systems Market
Payments
Global Real-Time Payments Market
Payments
GCC Payment Gateway Market
Payments
Middle East and Africa Prepaid Card Market
Payments
Face-Swiping Payment Market
Payments
Direct Carrier Billing Platform Market
Payments
China Mobile Payments Market
Payments
Denmark Mobile Payments Market