
 Embedded Banking Market | 2026-2036
Embedded Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Banking Market Analysis
The premium banking stack is decoupling from commodity payment rails as enterprise clients demand dedicated ledger infrastructure and custom compliance workflows. Stripe Inc. leverages its dual-issuing and acquiring architecture to capture complex treasury use cases. Marqeta Inc. anchors the card-programming layer with processor-agnostic APIs that sustain margin pools for high-velocity fintech issuers. Solaris SE competes through its full banking license coverage across multiple European jurisdictions, differentiating where regulatory breadth itself becomes a product feature.
Embedded banking denotes the integration of regulated financial services—lending, account provisioning, payment execution, and insurance placement—directly into non-bank software platforms via API or white-label orchestration, typically requiring sponsor bank partnerships or direct chartering to settle funds in fiat. API integration dominates transaction volume by enabling real-time data exchange between platform front ends and core banking systems, while white label solutions capture margin in sectors where brand continuity outweighs speed-to-market. Lending services within the service-type dimension are expanding fastest as platforms embed revenue-based financing and buy-now-pay-later structures at the point of sale.
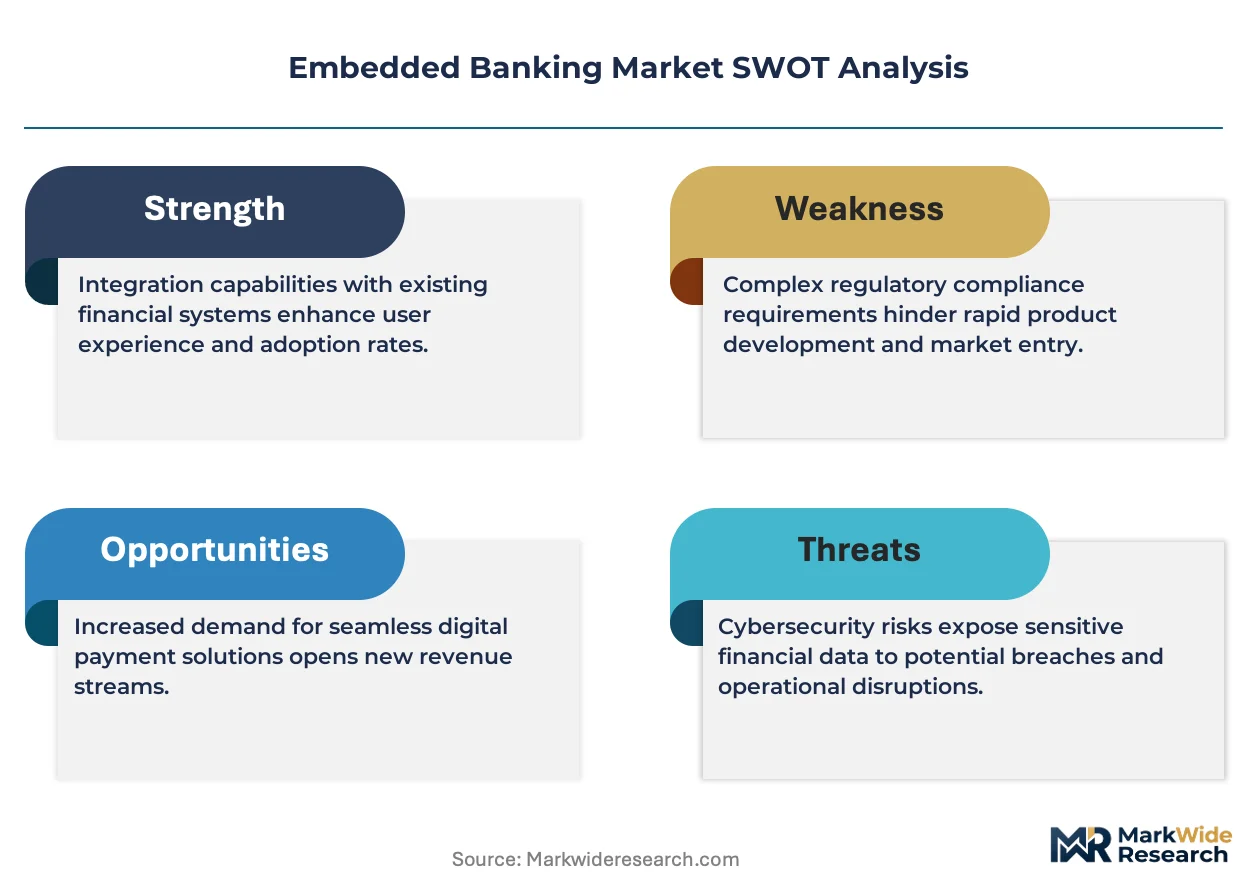
The Federal Reserve's oversight of bank-fintech partnerships through its third-party risk management guidance shapes US market access conditions, while the EU's Payment Services Directive and incoming AI Act constrain how automated underwriting engines operate across member states. The UK's Financial Conduct Authority and the EU's European Banking Authority both scrutinize embedded deposit products for consumer harm, tightening sponsor bank due diligence requirements. Stakeholders must monitor whether charter acquisition or partnership dependency becomes the sustainable path as capital requirements and compliance costs escalate.
Market Dynamics
API-first infrastructure providers are compressing the traditional sponsor bank layer, forcing legacy core banking vendors to modularize their stacks or lose platform relationships entirely.
Growth Catalysts
- Open Banking Mandates:The EU's Payment Services Directive and equivalent frameworks in Brazil and Australia compel incumbent banks to expose account data via standardized APIs, lowering entry barriers for non-bank platforms seeking to embed lending and treasury services.
- E-commerce Checkout Integration:Merchant platforms embed buy-now-pay-later and revenue-based financing at the point of sale, converting transaction data into real-time credit underwriting signals without redirecting customers to external banking interfaces.
- Real-time Payment Rails:The Federal Reserve's FedNow service and equivalent instant settlement systems in the UK, India, and Singapore eliminate float-based revenue models, pushing providers toward fee-based orchestration and data monetization.
Market Restraints
- Capital Requirements:Direct chartering demands compliance with Basel III tiering and local deposit insurance mandates, constraining balance sheet growth for neobanks unwilling to accept dilutive equity raises.
- Sponsor Bank Concentration:US market access depends on relationships with a finite pool of chartered institutions willing to absorb compliance liability, creating dependency risk as regulatory scrutiny intensifies.
- Technical Debt in Core Systems:Legacy mainframe architectures at incumbent banks resist real-time API integration, forcing middleware layers that add latency and failure points to embedded finance stacks.
Strategic Opportunities
- Regulatory Arbitrage in License Passporting:Lithuania's specialized bank charter and similar lightweight regimes in Singapore enable cross-border EU and ASEAN service provision without full banking license overhead.
- Convergence of Embedded Insurance:Parametric risk products and usage-based coverage integrate with payment flows, allowing platforms to capture premium economics alongside lending spreads.
- Vertical SaaS Penetration:Industry-specific software for construction, healthcare, and logistics remains underbanked, offering first-mover advantage to providers configuring treasury and payroll APIs for sector-specific workflows.
Industry Challenges
- Compliance Engineering Talent Scarcity:Demand for engineers fluent in BSA/AML protocols and multi-jurisdiction licensing requirements outstrips supply, inflating compensation and slowing product iteration cycles.
- Fragmented KYC Standards:Inconsistent identity verification requirements across US states and EU member states force redundant data collection, degrading onboarding conversion and inflating operational costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Banking Market |
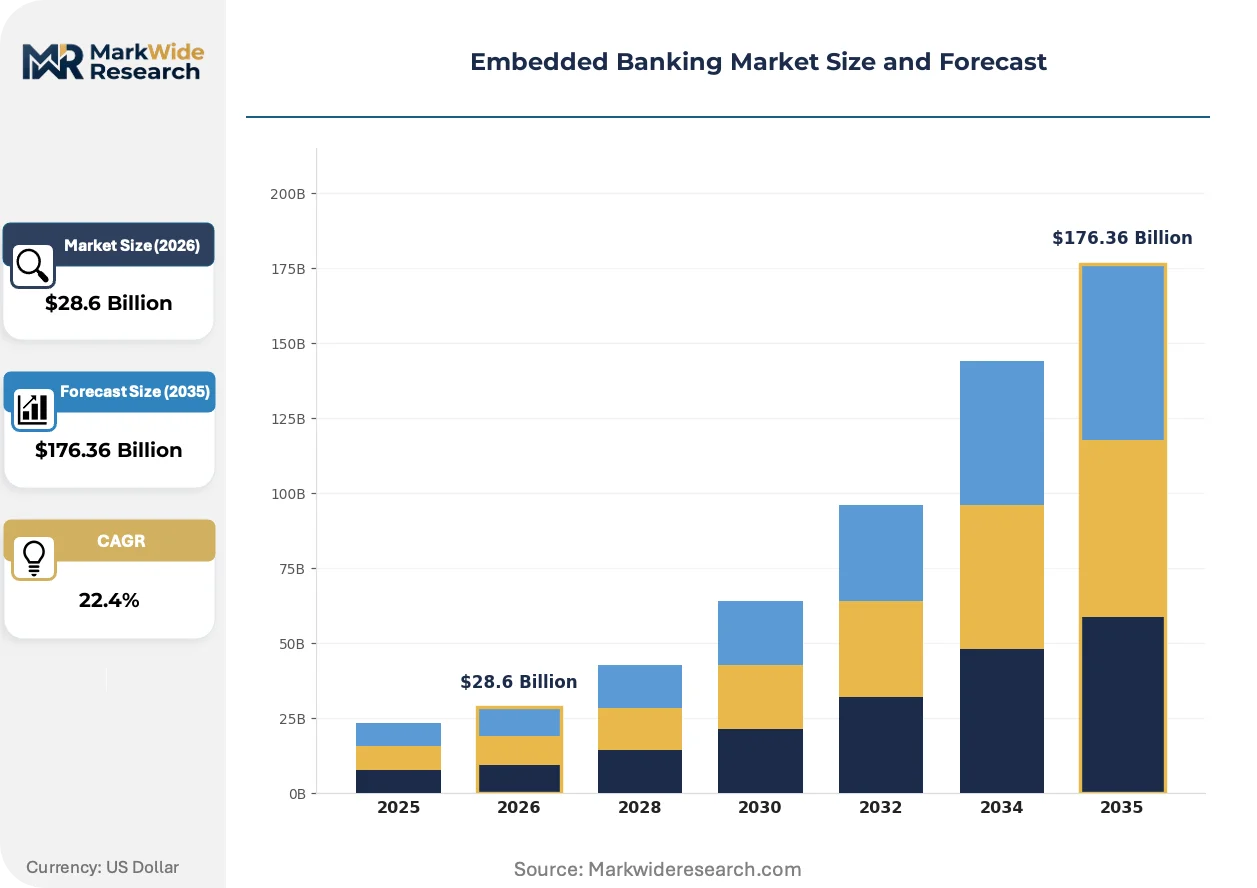
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $176.36 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Lending Services, Account Management, Insurance Services Client Type: E-commerce Platforms, Financial Institutions, Retailers, Fintech Startups Integration Method: API Integration, White Label Solutions, SDK Provisioning, Direct Partnerships Technology: Blockchain, AI-Powered Solutions, Cloud Computing, Data Analytics |
| Companies Covered | Stripe Inc., Marqeta Inc., Galileo Financial Technologies LLC, Unit Finance Inc., Solaris SE, Synctera Inc., Treasury Prime Inc., Adyen NV, Plaid Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Banking Market Emerging Trajectories
Embedded banking infrastructure is bifurcating between full-stack charter holders and thin orchestration layers, with competitive advantage migrating toward data velocity and compliance automation rather than balance sheet scale.
Real-time ledger virtualization is expanding into corporate treasury management by decoupling cash position tracking from physical account structures. Mid-market enterprises adopt these tools to consolidate multi-bank visibility without core banking replacements. This compression of treasury tech stacks is expanding into adjacent spend management and procurement automation markets.
The EU AI Act constrains automated underwriting engines by mandating human oversight for credit decisions affecting consumers, forcing embedded lenders to architect explainability layers and audit trails. This regulatory friction disproportionately impacts buy-now-pay-later providers operating across member states. Affected platforms are responding by localizing decision engines and acquiring regulatory technology vendors.
Merchant platforms now demand revenue-share pricing over flat SaaS subscriptions for embedded finance modules, aligning provider incentives with loan performance and payment volume. This shift displaces traditional per-seat licensing in vertical software categories. The transition is most visible in US and UK e-commerce ecosystems where platform consolidation has concentrated bargaining power.
Embedded Banking Market Segmentation
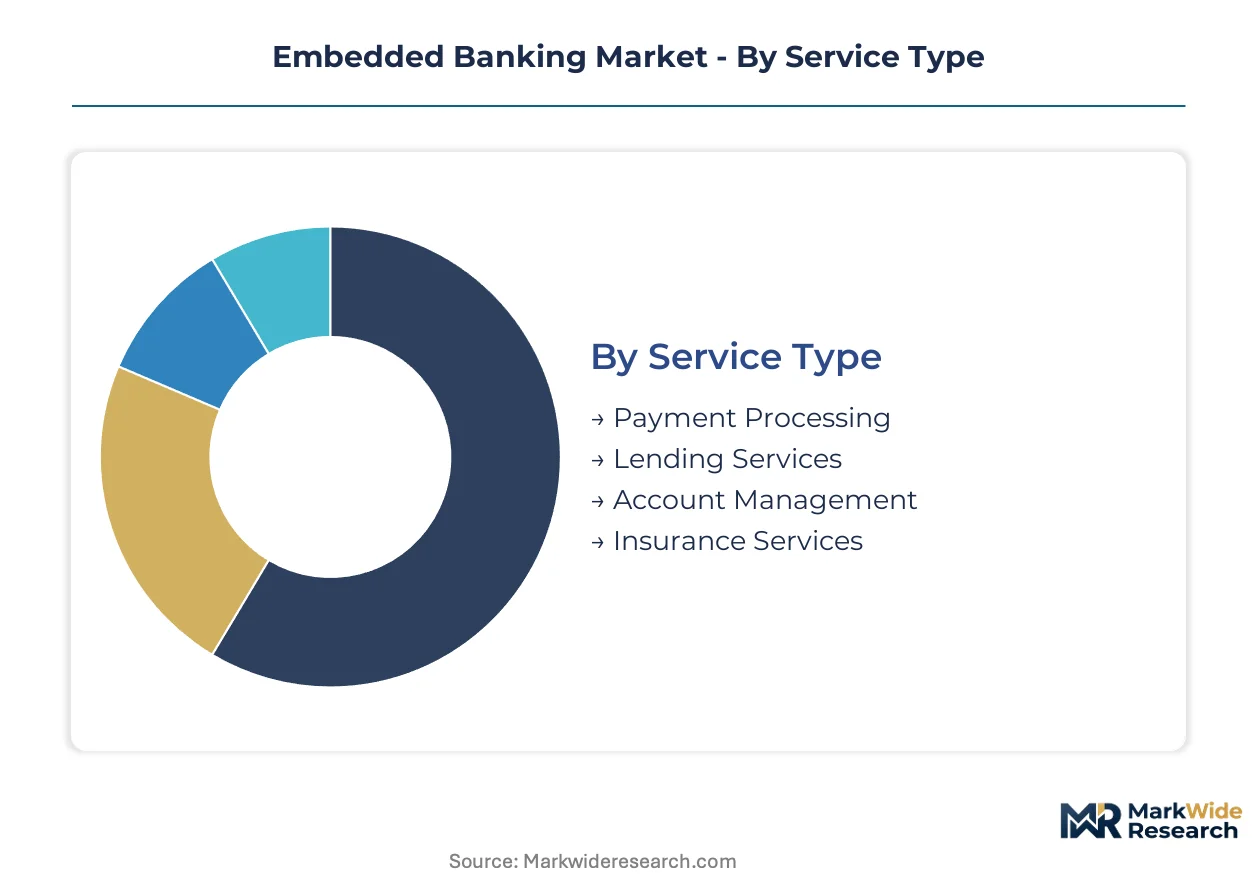
Embedded banking providers configure their service architectures around distinct operational layers, each demanding specialized compliance frameworks and technical integration patterns. Segment boundaries increasingly blur as full-stack platforms absorb multiple service types and client verticals.
Service Type:
Volume concentrates in payment orchestration, while lending commands premium margins through risk-based pricing.
- Payment Processing:Real-time settlement rails handle the highest transaction throughput, with merchants in the United States and United Kingdom driving demand for instant confirmation. FedNow and equivalent instant payment systems eliminate float revenue, pushing providers toward subscription and data monetization models.
- Lending Services:Revenue-based financing and buy-now-pay-later structures embed at e-commerce checkout, converting transaction history into underwriting signals. The EU AI Act mandates human oversight for automated credit decisions, forcing architectural investments in explainability layers.
- Account Management:Virtual ledger infrastructure consolidates multi-bank visibility for mid-market treasury operations.
- Insurance Services:Parametric risk products integrate with payment flows, capturing premium economics alongside core banking spreads.
Today's leader: Payment Processing. Tomorrow's challenger: Lending Services.
Client Type:
Application patterns diverge sharply between platform-native deployments and legacy institutional retrofits.
- E-commerce Platforms:Checkout-embedded finance dominates adoption, with merchants embedding lending and treasury services directly into customer journeys. Real-time data exchange between platform front ends and banking cores enables instant credit decisions without external redirects.
- Financial Institutions:Incumbent banks leverage embedded infrastructure to modernize legacy core systems, purchasing API layers rather than rebuilding mainframe architectures.
- Retailers:Point-of-sale financing and branded stored-value programs deepen customer engagement metrics.
- Fintech Startups:Venture-backed issuers demand processor-agnostic card programming and rapid sponsor bank onboarding.
E-commerce Platforms anchor current deployment scale. Fintech Startups show the steepest expansion trajectory as charter acquisition costs decline.
Integration Method:
Speed-to-market requirements favor API-first approaches, though brand-sensitive sectors retain white-label demand.
- API Integration:Real-time data exchange between platform front ends and core banking systems dominates transaction volume. Standardized interfaces lower entry barriers for non-bank platforms seeking to embed regulated services.
- White Label Solutions:Sectors where brand continuity outweighs technical velocity—particularly retail and insurance—capture margin through full visual customization.
- SDK Provisioning:Mobile-native platforms embed pre-configured code libraries for rapid deployment.
- Direct Partnerships:Sponsor bank relationships remain essential for fiat settlement in jurisdictions lacking open banking mandates.
API Integration commands deployment frequency. Direct Partnerships face regulatory pressure as third-party risk management guidance tightens.
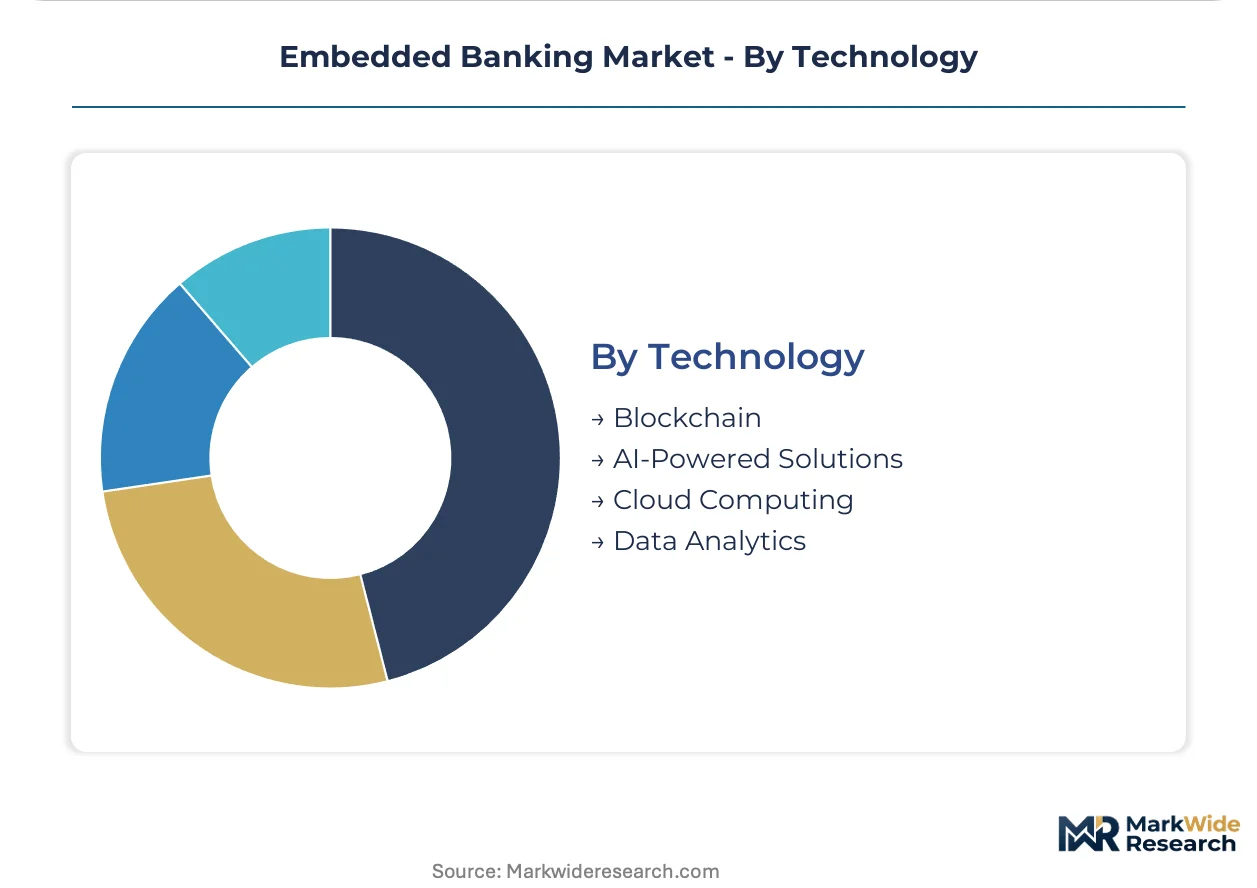
Technology:
Infrastructure investments concentrate on compliance automation and data velocity rather than balance sheet scale.
- AI-Powered Solutions:Automated underwriting engines require architectural redesign under EU oversight mandates, with explainability layers becoming product features. Talent scarcity for engineers fluent in BSA/AML protocols inflates compensation and slows iteration cycles.
- Cloud Computing:Modular core banking stacks displace legacy mainframe dependencies, enabling real-time ledger virtualization for corporate treasury management.
- Blockchain:Distributed ledger applications focus on cross-border settlement and programmable compliance.
- Data Analytics:Transaction pattern recognition converts behavioral signals into credit risk assessments.
Cloud Computing underpins current infrastructure migration. AI-Powered Solutions face regulatory friction but promise the deepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers fluent in BSA/AML protocols and multi-jurisdiction licensing requirements cluster disproportionately in the United States, the United Kingdom, Germany, and Singapore, anchoring regional competitive positioning.
United States
Venture-backed infrastructure providers and chartered neobanks drive platform adoption across e-commerce and fintech verticals. The Federal Reserve's third-party risk management guidance tightens sponsor bank due diligence requirements. New York and San Francisco host the deepest partner ecosystems for API-first banking orchestration.
United Kingdom
Mid-market enterprises adopt real-time ledger virtualization for multi-bank treasury consolidation. The Financial Conduct Authority scrutinizes embedded deposit products for consumer harm. London anchors the deepest concentration of compliance engineering talent outside North America.
Germany
Industrial software platforms embed payment and lending modules into sector-specific workflows for manufacturing and logistics. BaFin enforces strict oversight of automated underwriting engines under incoming EU AI Act provisions. Berlin and Frankfurt sustain competing clusters of full-stack charter holders and thin orchestration layers.
Singapore
Cross-border ASEAN service provision attracts providers seeking lightweight licensing regimes without full banking charter overhead. The Monetary Authority of Singapore governs digital payment token and e-money issuance frameworks. The city-state's regulatory sandbox enables rapid pilot deployment for revenue-based financing products.
Brazil
Open banking mandates compel incumbent institutions to expose account data via standardized APIs, lowering entry barriers for platform-native lenders. Banco Central do Brasil enforces Pix instant payment integration requirements. São Paulo concentrates fintech startup density and sponsor bank partnership activity.
Embedded Banking Market Vendor Landscape
Top-tier vendors anchor the full-stack charter holder tier, while thin orchestration layers compete on API velocity and compliance automation. The vendor base stratifies between balance-sheet-heavy operators and modular infrastructure specialists. Dual-issuing and acquiring architectures represent one dominant archetype; processor-agnostic card programming layers represent another. Competitive moves concentrate on sponsor bank partnership expansion and regulatory technology acquisition.
Within the infrastructure provider tier, Stripe Inc. and Marqeta Inc. exemplify contrasting architectural approaches to embedded financial services. Solaris SE occupies a position representing the full banking license coverage archetype across multiple European jurisdictions. These three entities collectively illustrate the market's bifurcation between charter-dependent and partnership-dependent operating models.
| Leading Market Players |
|---|
| Stripe Inc. |
| Marqeta Inc. |
| Galileo Financial Technologies LLC |
| Unit Finance Inc. |
| Solaris SE |
| Synctera Inc. |
| Treasury Prime Inc. |
| Adyen NV |
| Plaid Inc. |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure cost indices cascade through embedded banking supply chains, compressing margins for API-first orchestrators while amplifying pricing power for full-stack charter holders with captive ledger infrastructure. This asymmetry stratifies the vendor base between commodity payment rails and premium compliance-automation tiers.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive pricing architecture in embedded banking. Full-stack providers package payment processing, lending origination, and treasury management under subscription SaaS tiers, while thin orchestration layers charge per-unit transactional fees that erode as volume scales. Price differentiation rests on regulatory coverage breadth and real-time settlement capability, with EU-licensed operators commanding premiums over sponsor-bank-dependent US counterparts. Pricing pressure intensifies as merchant platforms shift from flat SaaS subscriptions to revenue-share models, squeezing provider margins in high-volume e-commerce verticals. Mid-market fintech startups exhibit acute price sensitivity, whereas enterprise treasury clients prioritize compliance automation over unit economics.
Supply Chain Analysis
Domestic-content mandates in data residency regulations across Germany, Singapore, and Brazil are reshaping sourcing patterns for core banking infrastructure. Supply concentration clusters in the United States, the United Kingdom, and Germany, where compliance engineering talent pools anchor development centers. Raw material dependencies include cloud compute capacity from hyperscalers, specialized banking-as-a-service middleware, and regulatory technology modules for automated KYC processing. Single-source vulnerability pervades sponsor bank relationships in the US market, where a finite pool of chartered institutions controls fiat settlement access. Distribution runs through API marketplaces and direct enterprise sales channels, with vertical SaaS platforms emerging as critical downstream aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded banking functions as a stable compounder, with open banking mandates and real-time payment rail expansion providing durable structural tailwinds across regulatory jurisdictions.
For Market Incumbents: Anticipate sponsor bank consolidation and compliance cost escalation by acquiring regulatory technology vendors with multi-jurisdiction licensing expertise. Charter-dependent operators face existential pressure as the Federal Reserve tightens third-party risk management guidance, making direct licensing or partnership diversification essential defensive maneuvers. Vertical integration into proprietary ledger infrastructure preserves margin pools against commodity API pricing.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in corporate treasury virtualization offers white-space entry for modular providers. Vertical SaaS penetration in underbanked sectors—construction, healthcare logistics, agricultural supply chains—presents the most penetrable beachhead. A partnership-first go-to-market strategy with established sponsor banks accelerates time-to-revenue without charter acquisition overhead.
For Investors and Strategic Acquirers: Asymmetric upside sits with full-stack charter holders possessing EU passporting rights and automated compliance engines. Long-term viability favors operators with diversified funding sources beyond venture capital, including revenue-based financing and strategic corporate backing. Monitor sponsor bank exit announcements as an inflection indicator for partnership-model distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Acquisition | Automated KYC engines reduce compliance costs under EU AI Act human-oversight mandates. |
| Vertical SaaS Integration | Construction and healthcare platforms embed payroll APIs for sector-specific workflow capture. |
| Charter Passporting Expansion | Lithuania and Singapore licenses enable cross-border EU and ASEAN service provision. |
| Real-time Ledger Virtualization | Mid-market enterprises consolidate multi-bank visibility without core banking replacements. |
| Revenue-share Model Transition | Merchant platforms align provider incentives with loan performance and payment volume. |
Methodological Framework
Direct dialogue with embedded banking infrastructure executives, sponsor bank compliance officers, fintech product managers, and vertical SaaS platform engineers grounded the qualitative foundation. Secondary validation drew from Federal Reserve guidance documents, EU Payment Services Directive regulatory filings, Banco Central do Brasil open banking disclosures, and cloud infrastructure provider capex reports. Bottom-up transaction volume estimates and top-down market sizing triangulated across API gateway traffic data and sponsor bank partnership announcements.
Bottom-up modeling segmented volume by service type, client vertical, integration method, and regional regulatory cluster across the projection horizon. Top-down validation cross-referenced venture capital deployment patterns, charter application filings, and neobank balance sheet growth. CAGRs derived from historical adoption curves in payment orchestration and lending origination, adjusted for FedNow rollout velocity and EU AI Act compliance friction. Industry-specific inputs included sponsor bank concentration ratios and compliance engineering salary inflation indices.
Caveats apply where sponsor bank exit events, abrupt regulatory reinterpretations, or hyperscaler pricing shocks could materially shift the outlook. Forecasts embed assumptions regarding open banking mandate enforcement consistency and real-time payment rail interoperability timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Asia-Pacific Machine Learning in Banking Market
Banking
Payment Bank Solutions Market
Banking
Cybersecurity in Banking Market
Banking
Global Neobanking Market
Banking
Digital LED Retail Banking Market
Banking
Retail Banking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Blockchain in Retail Banking Market
Banking
Performance Bank Guarantee Market
Banking
North America Challenger Banks Market
Banking
Global Banking Systems Software Market
Banking
Investment Banking Market
Banking
Corporate Banking Market
Banking
Cloud Billing in Banking Market
Banking
ATM Market
Banking
Latin America Data Analytics in Banking Market