
 Canada Real Time Payments Market | 2026-2036
Canada Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Real Time Payments Market Outlook
Canadian payment infrastructure is shifting from batch-based clearing toward continuous settlement rails. Interac Corporation leverages its domestic network dominance to anchor real-time debit capabilities across financial institutions. Mastercard Incorporated competes through its Vocalink acquisition, extending global instant payment protocols into Canadian corridors. Royal Bank of Canada sustains institutional leadership by integrating real-time capabilities into commercial treasury platforms.
Canada real time payments denote electronic fund transfers settled within seconds through always-on clearing infrastructure, typically operating on ISO 20022 messaging standards with 24/7 availability and irrevocable finality. These systems eliminate float periods, reduce counterparty risk, and enable immediate liquidity confirmation for payers and recipients. Among payment types, instant transfers dominate transaction volume while QR code payments represent the fastest-growing acceptance format at merchant points of sale. On the service provider dimension, traditional banks occupy the majority share of transaction value, though fintech companies capture disproportionate growth in small business onboarding and user experience innovation.
Payments Canada governs the national clearing and settlement framework, while the Department of Finance advances open banking regulations that mandate standardized data sharing between incumbents and third-party providers. The Office of the Superintendent of Financial Institutions imposes operational risk requirements that shape how banks architect real-time payment security and resilience. Stakeholders must monitor how forthcoming consumer protection rules and liability allocation standards will reshape competitive dynamics between established banks and emerging payment platforms.
Market Dynamics
Canada's real-time payments infrastructure is pivoting from batch-based clearing to continuous settlement rails, driven by the Bank of Canada's Lynx system modernization and the Department of Finance's open banking mandate. This structural shift compresses settlement windows from days to seconds, forcing financial institutions to rebuild core systems around ISO 20022 messaging standards.
Growth Catalysts
- Small business cash flow optimization:Canadian SMEs are abandoning check-based receivables for instant settlement to eliminate payment float and working capital gaps.
- Payments Canada's Real-Time Rail (RTR):The national infrastructure upgrade mandates 24/7 availability and irrevocable finality, creating technical obligations that accelerate bank modernization.
- QR code merchant acceptance:Retail point-of-sale systems in Ontario and British Columbia are rapidly deploying scan-to-pay interfaces, expanding real-time payment touchpoints beyond traditional banking channels.
Market Restraints
- Core banking system replacement costs:Legacy mainframe architectures at major Canadian banks require capital-intensive overhauls to achieve real-time processing capability.
- Interoperability fragmentation:Competing technical standards between Interac's domestic network and Mastercard's Vocalink protocols create integration complexity for multi-rail merchants.
- Fraud liability uncertainty:The Office of the Superintendent of Financial Institutions has not finalized consumer protection rules for irrevocable real-time transactions, chilling some institutional deployment.
Strategic Opportunities
- Underpenetrated Prairie provinces:Manitoba and Saskatchewan exhibit lower fintech density and slower enterprise digitization, creating whitespace for platform expansion beyond Ontario and British Columbia concentration.
- Request-to-pay (R2P) services:The ISO 20022 messaging standard enables invoice-presentment-with-payment, opening B2B use cases currently dominated by electronic funds transfer.
- Department of Finance open banking framework:Mandated data-sharing between incumbents and third-party providers will lower onboarding friction for fintech payment platforms.
Industry Challenges
- ISO 20022 migration complexity:Financial institutions face multi-year transformation timelines to replace legacy messaging formats, risking service disruption during parallel operation periods.
- Real-time fraud detection capability gaps:Batch-based risk scoring systems require complete reconstruction for sub-second transaction monitoring, demanding scarce machine learning engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Real Time Payments Market |
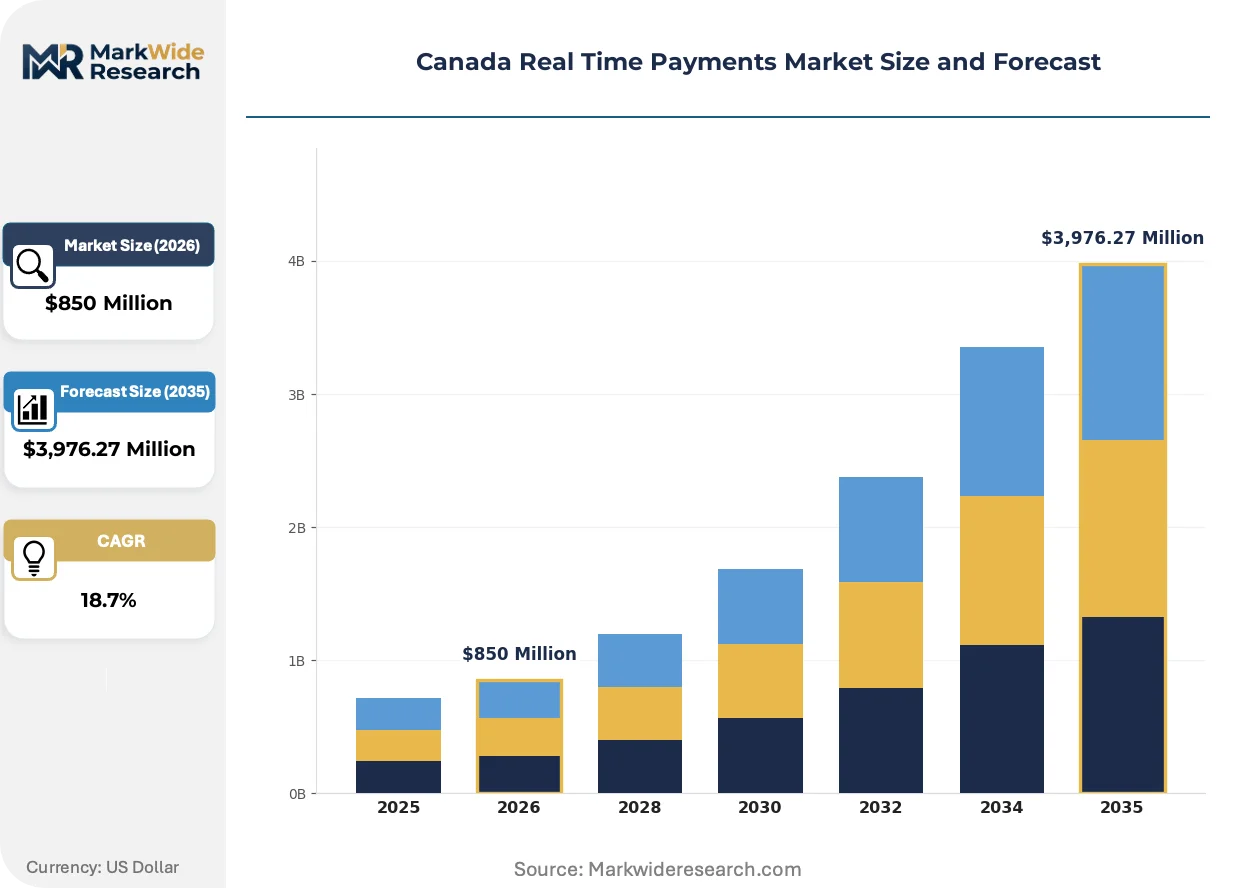
| Market Size in 2026 | $850 Million |
| Market Size in 2035 | $3,976.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Instant Transfers, ACH Payments, Mobile Payments, QR Code Payments Service Provider: Traditional Banks, Fintech Companies, Credit Unions, Payment Platforms End User: Consumers, Small Businesses, Enterprises, Government Agencies Transaction Value: Low Value, Medium Value, High Value, Others |
| Companies Covered | Interac Corporation, Mastercard Incorporated, Visa Inc., ACI Worldwide Inc., FIS (Fidelity National Information Services, Inc.), Fiserv, Inc., PayPal Holdings, Inc., Moneris Solutions Corporation, Royal Bank of Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Real Time Payments Market Strategic Shifts
Canadian payment infrastructure is experiencing convergent pressures from regulatory modernization, technical standardization, and merchant demand for instant liquidity confirmation. These forces are compressing development cycles and reshaping competitive positioning between incumbent banks and specialized fintech platforms.
Cloud-native core banking platforms is expanding into the real-time payments stack, displacing decades-old on-premise mainframe architectures. Mid-tier Canadian credit unions and regional banks are adopting these systems most aggressively, drawn by faster deployment timelines and lower capital requirements. This technology shift is expanding into previously inaccessible market segments, enabling smaller institutions to offer instant settlement parity with national banks.
The Department of Finance's open banking regulations are mandating standardized API access between financial institutions and third-party providers. This policy framework compels banks to expose customer-permissioned transaction data, eroding proprietary data moats that historically protected payment revenues. Fintech onboarding platforms in Ontario are responding by building compliance-ready interfaces that accelerate credential verification and account linking.
Merchant procurement of payment acceptance is rotating toward integrated software vendors over standalone hardware terminals. Canadian retailers, particularly in British Columbia's hospitality sector, are consolidating point-of-sale, inventory, and payment functions into single-platform subscriptions. This consolidation is most visible among mid-market chains seeking to reduce vendor management overhead and unify transaction data analytics.
Canada Real Time Payments Market Segmentation
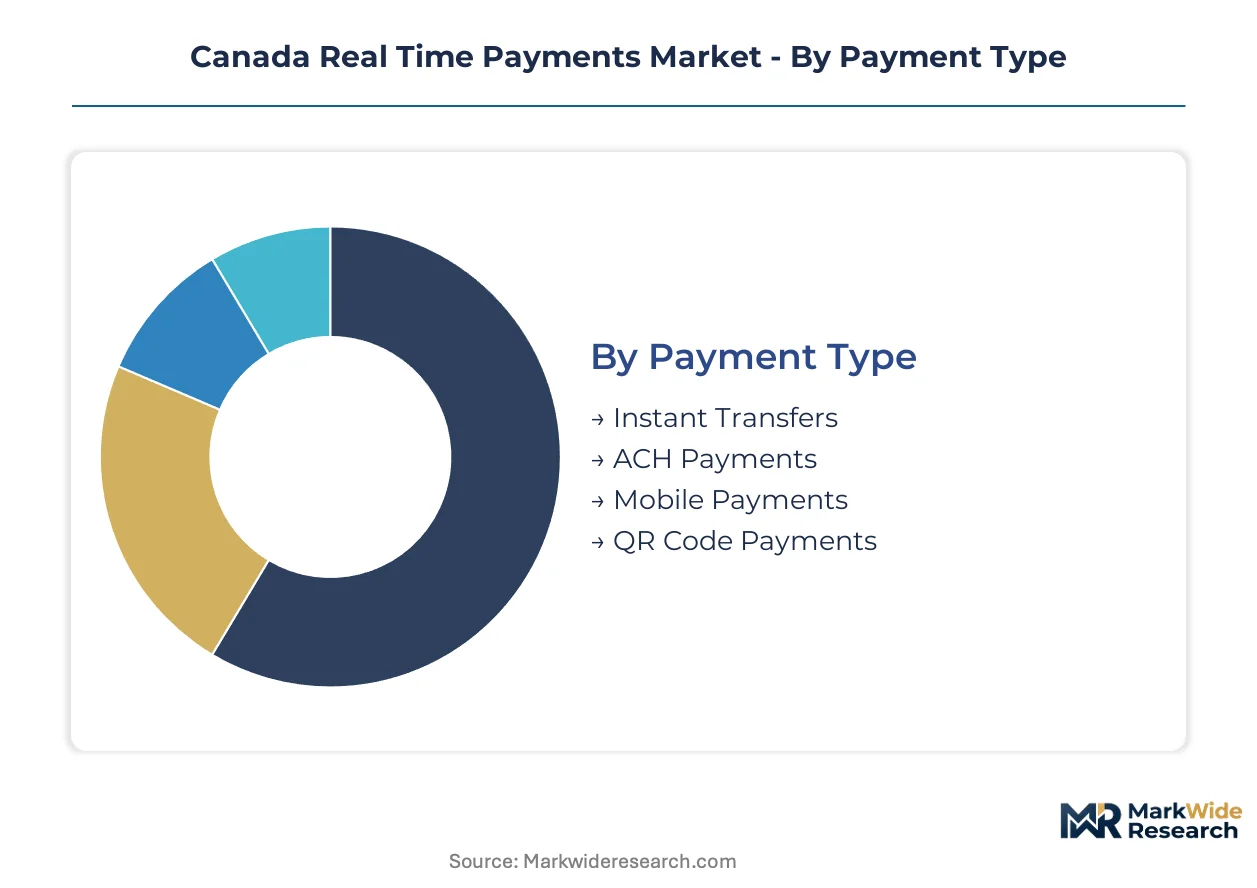
Canada's real-time payments market fragments across four structural dimensions that determine infrastructure requirements, regulatory exposure, and competitive dynamics. Payment type and service provider categories shape capital intensity and certification burdens, while end user and transaction value segments dictate risk management protocols and pricing architectures.
Payment Type:
Certification requirements vary sharply across payment modalities, with QR code deployments facing merchant onboarding standards from Payments Canada and instant transfers governed by Lynx system operational risk mandates from the Office of the Superintendent of Financial Institutions.
- Instant Transfers:These transactions settle through the Lynx system with irrevocable finality within seconds, operating on ISO 20022 messaging standards. Demand concentrates in Ontario's commercial banking corridors, where enterprise treasury departments prioritize working capital velocity over batch-based alternatives.
- QR Code Payments:Scan-to-pay interfaces at merchant points of sale require integrated software certification and PCI-DSS compliance. British Columbia's hospitality sector drives adoption, with mid-market chains consolidating payment acceptance into unified platform subscriptions.
- ACH Payments:Legacy batch-based clearing persists for scheduled disbursements and payroll, though migration toward real-time rails accelerates.
- Mobile Payments:Smartphone-initiated transfers leverage Interac's domestic network dominance, with fintech platforms capturing small business onboarding.
Instant transfers sit at the top of the volume ranking, with QR code payments climbing the fastest.
Service Provider:
Cost tier stratification separates capital-intensive core banking overhauls at traditional institutions from cloud-native deployments at emerging competitors, with regulatory capital requirements creating divergent entry barriers.
- Traditional Banks:Royal Bank of Canada and Toronto-Dominion Bank maintain institutional leadership through commercial treasury platform integration. Prairie provinces and Atlantic Canada show concentrated branch infrastructure, though legacy mainframe replacement costs constrain real-time capability deployment.
- Fintech Companies:Specialized platforms exploit open banking API mandates to accelerate credential verification and account linking. Ontario's fintech density outpaces national averages, with Toronto-Waterloo corridor hosting disproportionate venture deployment.
- Credit Unions:Mid-tier regional institutions adopt cloud-native core systems aggressively, drawn by faster deployment timelines and lower capital requirements than national bank alternatives.
- Payment Platforms:Interac Corporation anchors domestic network infrastructure, while Mastercard's Vocalink protocols compete for multi-rail merchant integration.
Traditional banks command the highest transaction value share, with fintech companies expanding most quickly in small business segments.
End User:
Application context determines fraud liability frameworks and user experience requirements, with government agencies imposing procurement standards that cascade into private sector specifications.
- Small Businesses:Canadian SMEs abandon check-based receivables for instant settlement, eliminating payment float and working capital gaps. Ontario and British Columbia exhibit highest adoption rates, correlating with fintech platform density and enterprise digitization maturity.
- Enterprises:Corporate treasury departments demand immediate liquidity confirmation and integrated cash forecasting. Manufacturing and logistics sectors in Quebec prioritize B2B request-to-pay capabilities enabled by ISO 20022 messaging.
- Consumers:Retail payment behavior shifts toward mobile-first interfaces, with peer-to-peer transfers gaining share against legacy methods.
- Government Agencies:Federal and provincial procurement modernization mandates 24/7 disbursement capability, with Payments Canada's Real-Time Rail creating technical obligations for vendor qualification.
Enterprises generate the highest average transaction values, with small businesses demonstrating the steepest adoption trajectory.
Transaction Value:
Volume concentration and margin structure correlate inversely across value tiers, with low-value transactions requiring scale economics and high-value transfers demanding enhanced authentication protocols.
- Low Value:Micropayments and retail purchases dominate transaction count, with per-unit margins compressing toward interchange fee floors. Quick-service restaurants and convenience retail in urban Ontario deploy QR acceptance most aggressively.
- High Value:Commercial real estate transactions and capital equipment purchases require multi-factor authentication and enhanced fraud monitoring. Alberta's energy sector procurement drives concentrated demand for irrevocable settlement finality.
- Medium Value:B2B trade payments and professional services invoices occupy the middle tier, with request-to-pay services gaining traction.
- Others:Variable-value use cases including charitable donations and peer-to-peer transfers span authentication requirement thresholds.
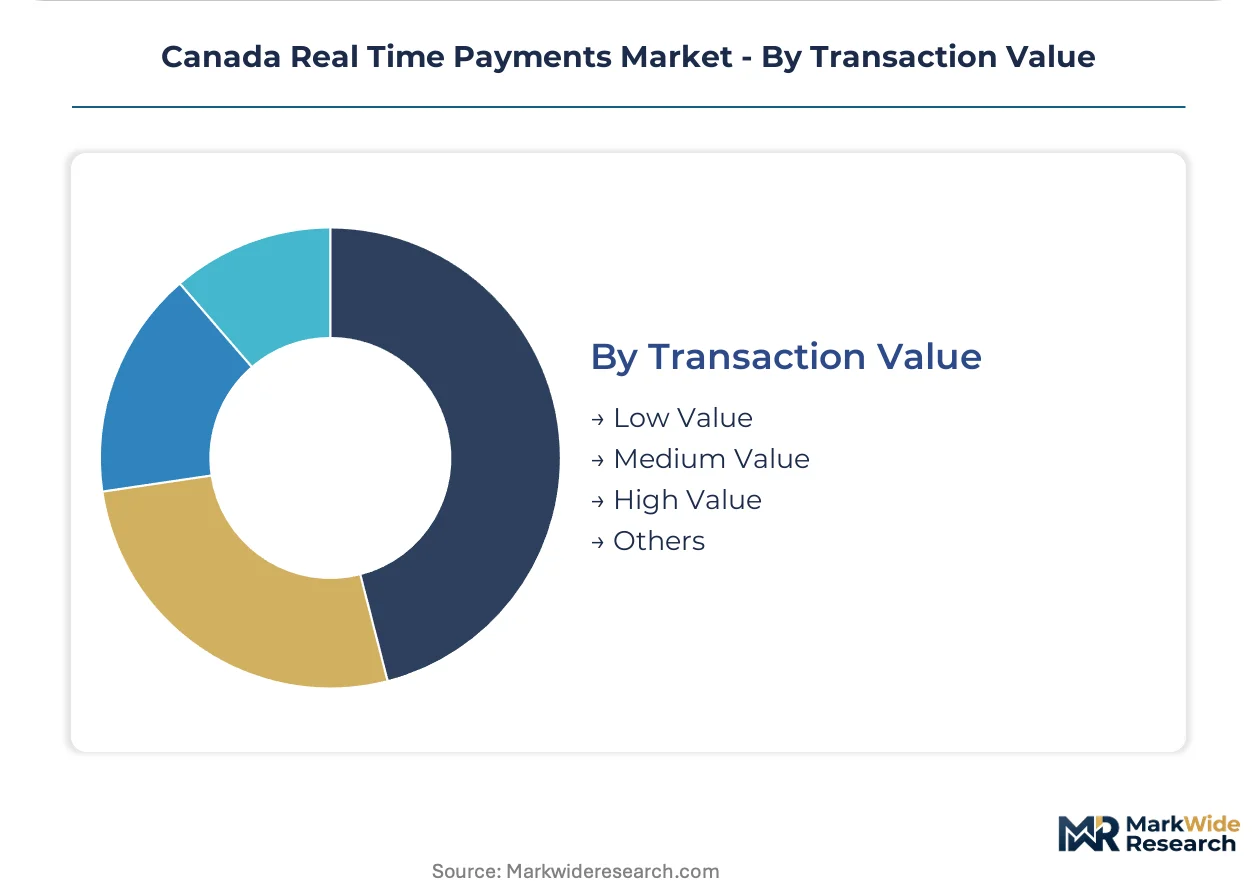
Low value transactions anchor total volume, with high value transfers commanding disproportionate revenue concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's real-time payments infrastructure outpaces Mexico's adoption curve but trails the United States in merchant penetration density. Provincial fragmentation creates divergent deployment timelines across the federation.
Ontario
Toronto-Waterloo corridor fintech density drives SME onboarding velocity for instant settlement platforms. Payments Canada's Real-Time Rail technical obligations cascade through provincial procurement standards. Manufacturing and logistics clusters in Mississauga prioritize B2B request-to-pay capabilities enabled by ISO 20022 messaging.
British Columbia
Hospitality sector consolidation into unified platform subscriptions accelerates QR code merchant acceptance. The Department of Finance open banking framework mandates API standardization that Vancouver-based platforms exploit for credential verification. Vancouver and Victoria host disproportionate venture deployment in cloud-native payment infrastructure.
Quebec
Corporate treasury departments in Montreal demand immediate liquidity confirmation for cross-border trade settlements. The Office of the Superintendent of Financial Institutions operational risk requirements shape how Quebec institutions architect real-time security protocols. Quebec City government procurement modernization mandates 24/7 disbursement capability for vendor qualification.
Alberta
Energy sector procurement drives concentrated demand for irrevocable settlement finality in high-value commercial transactions. The Bank of Canada's Lynx system modernization compresses settlement windows for Calgary-based commodity traders. Edmonton and Calgary exhibit accelerating cloud-native core banking adoption among mid-tier credit unions.
Prairie Provinces
Manitoba and Saskatchewan exhibit lower fintech density and slower enterprise digitization, creating whitespace for platform expansion. Regional banks face core banking system replacement costs that constrain real-time capability deployment. Winnipeg and Saskatoon agricultural cooperatives represent underpenetrated segments for instant transfer adoption.
Canada Real Time Payments Market Competitive Environment
Toronto-based financial institutions anchor one tier; global payment network specialists hold another through infrastructure licensing arrangements. Market structure consolidates around three strategic archetypes: domestic network operators with regulatory anchoring, global technology licensors extending protocols into Canadian corridors, and cloud-native challengers exploiting open banking API mandates. Dominant competitive moves include strategic partnerships between incumbent banks and fintech platforms, plus portfolio diversification into request-to-pay and QR code acceptance formats.
Within the domestic network tier, Interac Corporation exemplifies regulatory-anchored infrastructure dominance through its clearing and settlement positioning. Among global technology licensors, Mastercard Incorporated and Visa Inc. occupy positions extending instant payment protocols across Canadian merchant corridors. These three entities represent divergent competitive approaches: domestic network depth versus global protocol standardization versus dual-network hedging strategies.
| Leading Market Players |
|---|
| Interac Corporation |
| Mastercard Incorporated |
| Visa Inc. |
| ACI Worldwide Inc. |
| FIS (Fidelity National Information Services, Inc.) |
| Fiserv, Inc. |
| PayPal Holdings, Inc. |
| Moneris Solutions Corporation |
| Royal Bank of Canada |
| Others |
Value Chain & Pricing Dynamics
Small business procurement consolidation into unified platform subscriptions is compressing merchant acquirer margins and forcing payment processors to absorb ISO 20022 compliance costs within bundled SaaS offerings rather than pass-through pricing.
Pricing Analysis
Merchant acquirer markup layers dominate revenue capture, with ISO 20022 certification tier and transaction volume scale serving as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels segments by fraud liability coverage and settlement speed guarantees. Pricing pressure stems from cloud-native fintech challengers undercutting legacy bank interchange-plus models. Small businesses exhibit highest price sensitivity, while enterprise treasury departments prioritize irrevocable finality over per-transaction cost.
Supply Chain Analysis
Regional distribution centers in Toronto and Vancouver anchor hub-and-spoke patterns for payment terminal hardware and POS software deployment. Core banking technology draws from the United States, Ireland, and India for cloud infrastructure and software development. ISO 20022 messaging standard compliance, PCI-DSS certification hardware, and real-time fraud detection algorithms constitute critical input dependencies. Single-source vulnerability concentrates in Lynx system gateway access controlled by Payments Canada. Distribution runs through direct-to-bank channels for core infrastructure and ISV-aggregated routes for merchant-facing solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's real-time payments market functions as a geographic-arbitrage play where Prairie province underpenetration offers expansion runway at lower customer acquisition cost than saturated Ontario and British Columbia corridors.
For Market Incumbents: Extend cloud-native core banking partnerships to Prairie credit unions before fintech platforms establish merchant lock-in. Defend position by accelerating ISO 20022 migration timelines to outpace emerging competitors lacking legacy mainframe replacement burdens. Vertical integration into request-to-pay software development protects against disintermediation by specialized B2B fintech vendors. For New Entrants and Emerging Players: Enter via Manitoba and Saskatchewan agricultural cooperative segments where incumbent bank branch density masks real-time capability gaps. Target underpenetrated Prairie provinces through mobile-first onboarding that bypasses traditional merchant acquirer relationships. Leverage open banking API mandates from the Department of Finance to accelerate credential verification and reduce compliance friction. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native payment infrastructure specialists serving mid-tier credit unions. Long-term viability hinges on sustained open banking regulatory momentum and successful ISO 20022 standardization across the forecast horizon. Acquisition target archetype: regional fintech platforms with Prairie province merchant networks and compliant API interfaces. Monitor Payments Canada Real-Time Rail deployment milestones as the critical inflection signal for infrastructure monetization timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Migration Acceleration | Payments Canada mandates compel banks to modernize legacy messaging infrastructure or face exclusion from Real-Time Rail access. |
| Open Banking API Development | Department of Finance regulations enable fintech platforms to bypass traditional credential verification friction and accelerate onboarding. |
| Cloud-Native Core Banking Adoption | Mid-tier credit unions in Alberta and Prairie provinces deploy faster-deployment systems to achieve real-time parity with national banks. |
| Request-to-Pay Platform Launch | ISO 20022 messaging enables invoice-presentment-with-payment functionality that displaces legacy EFT in B2B use cases. |
| QR Code Merchant Acceptance Expansion | British Columbia hospitality sector consolidation into unified platform subscriptions drives scan-to-pay touchpoint density growth. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with payment technology executives, commercial banking treasury leads, fintech platform founders, and Payments Canada regulatory staff alongside secondary validation. Primary sources included real-time payment system operators, merchant acquirer product managers, and cloud banking infrastructure vendors. Secondary data drew from Payments Canada regulatory filings, Bank of Canada Lynx system disclosures, Department of Finance open banking consultations, and Office of the Superintendent of Financial Institutions operational risk guidelines. Bottom-up transaction volume modeling and top-down infrastructure investment triangulation anchored market size estimation.
Historical reference periods spanning pre- and post-Real-Time Rail announcement established baseline adoption curves and infrastructure deployment velocity benchmarks across the projection horizon. Segmentation dimensions modeled include payment type, service provider category, end user archetype, and transaction value tier alongside geographic adoption pattern. CAGRs were derived from infrastructure investment run-rates and merchant onboarding velocity curves. Forecast inputs incorporated ISO 20022 migration timelines, open banking regulatory phase-in schedules, and cloud-native core banking deployment trajectories at regional credit unions.
Inputs from Payments Canada and Bank of Canada regulatory disclosures were available through the study window; gaps in private fintech transaction volume data introduce uncertainty bands around small business segment estimates. Forecasts reflect documented assumptions regarding Real-Time Rail technical obligation timelines and open banking API standardization adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Ghana Mobile Money Market
Payments
Netherlands POS Terminal Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Fuel Cards Market
Payments
Fingerprint Payment Market
Payments
Wireless POS Terminals Market
Payments
Australia Mobile Payment Market
Payments
Retail Point of Sale (POS) Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Global Accounts Payable Software Market
Payments
Smart Home Payments Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Sweden Payments Market
Payments
Subscription Billing Management Market
Payments
In-Vehicle Payment Services Market
Payments
Europe Mobile Payment Market