
 Airborne SATCOM Equipment Market | 2026-2036
Airborne SATCOM Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne SATCOM Equipment Market Outlook
A widening capability gap between vertically integrated primes and component-reliant suppliers is unwinding competitive stability in airborne SATCOM. Honeywell International Inc. leverages its integrated avionics ecosystem to bundle SATCOM with flight-management systems, sustaining long-term platform relationships. Thales Group anchors European defense and commercial programs through sovereign manufacturing lines in France and satellite partnerships. Viasat, Inc. competes via direct-to-aircraft broadband services, differentiating through proprietary constellation access rather than hardware margins.
Airborne SATCOM equipment encompasses terminals, antennas, modems, and controllers engineered for Ku-band, Ka-band, K-band, and X-band frequencies, typically operating across 12–40 GHz ranges with phased-array or mechanically steered architectures to maintain link integrity during high-dynamic flight profiles. These systems enable beyond-line-of-sight voice, data, and video transmission for military command networks, commercial passenger connectivity, and unmanned platform telemetry. Terminal hardware leads current revenue pools due to platform-specific integration complexity and military certification requirements, while antenna segments oriented toward flat-panel electronically steered arrays represent the fastest-expanding margin pool as commercial aviation and UAV end users demand lower-drag installations. Modem and controller categories remain more fragmented, with demand splitting between software-defined architectures for military flexibility and purpose-built chipsets for commercial cost efficiency.
FAA airworthiness directives under 14 CFR and EASA certification standards under CS-23/CS-25 shape equipment design cycles, while ITAR and EAR export controls govern cross-border military SATCOM transfers. Frequency coordination through the ITU Radio Regulations and national spectrum allocations by the FCC and Ofcom constrain Ka-band and Ku-band deployment timelines, forcing manufacturers to engineer multi-band flexibility into new platforms. Stakeholders must weigh sovereign content requirements against supply chain concentration in RF component fabrication when positioning for defense procurement windows and commercial fleet retrofit programs.
Market Dynamics
Phased-array antenna architectures are compressing equipment refresh cycles across commercial aviation and defense platforms, forcing suppliers to reconfigure production lines around solid-state electronics rather than mechanically steered legacy systems.
Growth Catalysts
- FAA NextGen mandates:The FAA's 14 CFR airworthiness directives are compelling commercial fleet operators to replace aging Ku-band hardware with multi-band capable terminals, accelerating retrofit demand across narrow-body and wide-body aircraft.
- Military ISR platform expansion:NATO member states are integrating SATCOM into unmanned aerial systems and manned surveillance aircraft, driving sustained procurement of X-band and Ka-band terminals for beyond-line-of-sight command networks.
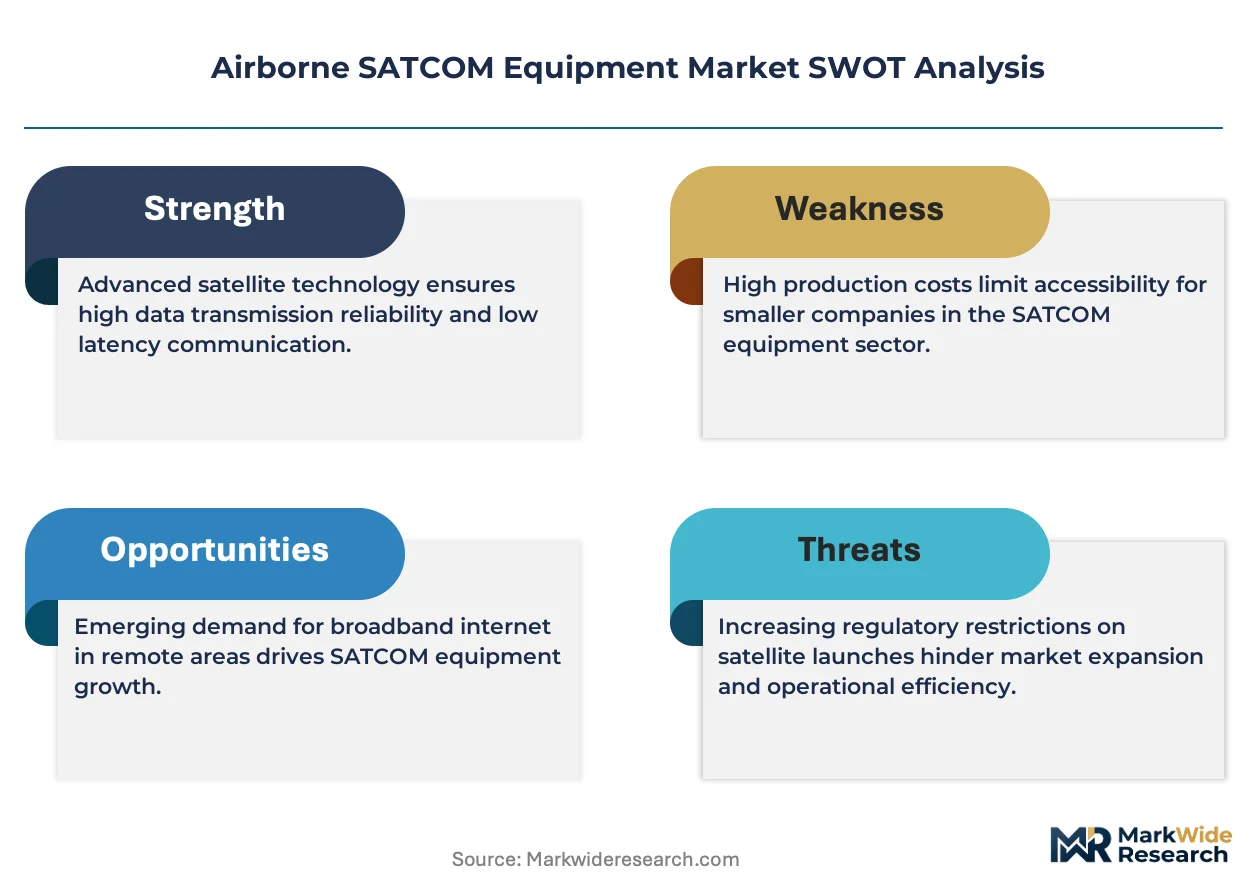
- Low Earth orbit constellation proliferation:Commercial aviation operators are demanding flat-panel antennas compatible with emerging LEO networks, opening new addressable equipment segments distinct from traditional geostationary satellite architectures.
Market Restraints
- Gallium nitride substrate costs:RF power amplifier fabrication depends on specialized GaN-on-SiC substrates concentrated among Japanese and US suppliers, creating input cost volatility that compresses hardware margins.
- ITAR-controlled component concentration:High-frequency MMICs and cryptographic modules for military terminals face US export controls, fragmenting supplier bases and extending lead times for non-US platform integrators.
- Ku-band spectrum congestion:ITU Radio Regulations constrain additional Ku-band allocations in dense North Atlantic and European corridors, forcing premature migration to Ka-band architectures with higher equipment costs.
Strategic Opportunities
- UAV beyond-visual-line-of-sight expansion:Civilian drone operators in Australia and Canada are securing regulatory waivers for SATCOM-controlled long-range flights, creating demand for miniaturized terminals below 10 kg.
- Software-defined modem architectures:Military end users are converging toward reprogrammable waveform processors that accommodate multiple satellite networks, enabling hardware vendors to capture recurring firmware upgrade revenue.
- India's defense indigenization push:The country's PLI scheme for aerospace components is incentivizing local assembly of SATCOM terminals, opening procurement channels previously dominated by imports.
Industry Challenges
- Phased-array thermal management expertise:Solid-state antenna design requires specialized RF engineering talent concentrated among defense contractors, constraining workforce scalability for commercial market entrants.
- DO-160G environmental qualification timelines:Commercial aviation certification demands 12-18 month test cycles for vibration, humidity, and electromagnetic interference, delaying revenue recognition for new product introductions.
- Multi-orbit interoperability integration:Terminal manufacturers must engineer seamless handoff between geostationary and LEO constellations, complicating firmware architecture and antenna control algorithms.
Report Scope
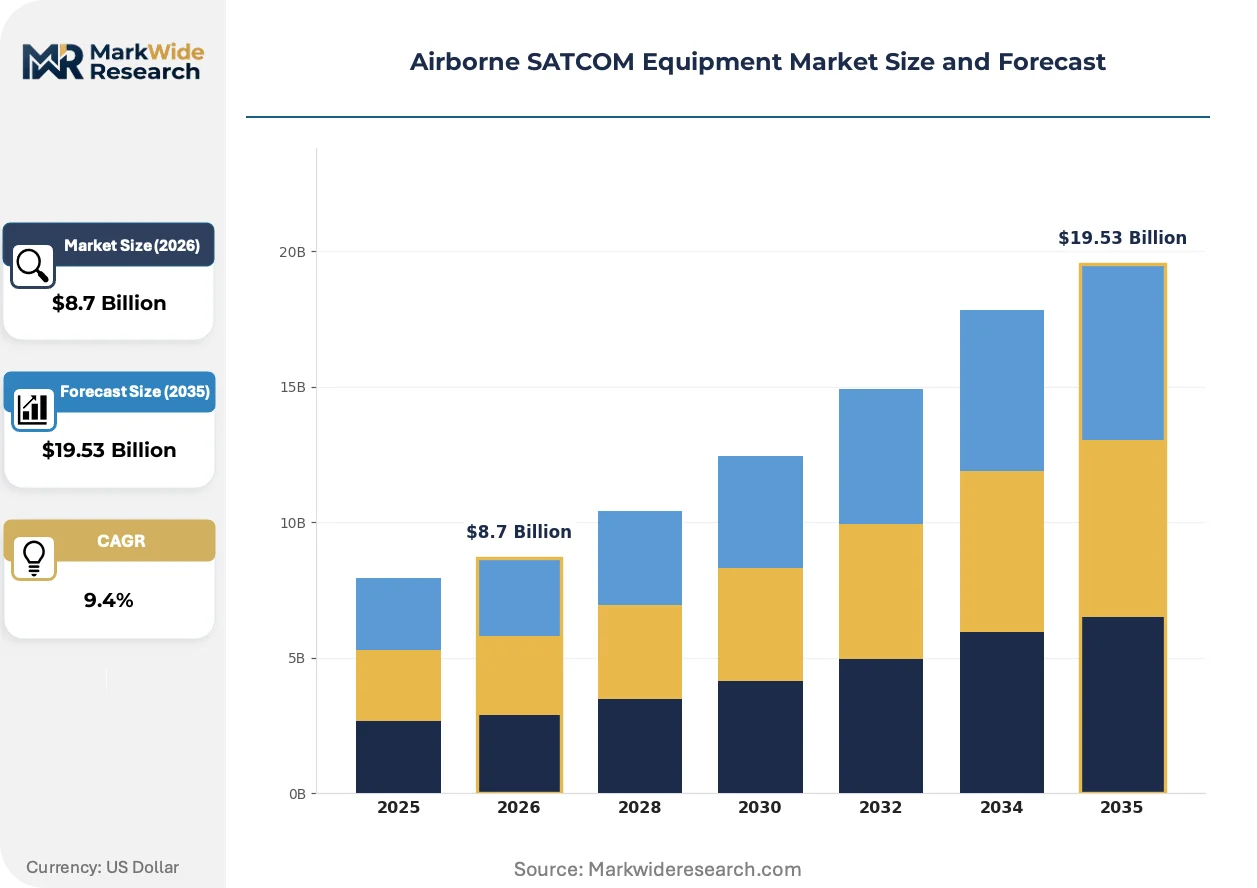
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne SATCOM Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terminal, Antenna, Modem, Controller Installation Type: Fixed, Portable, In-flight, Ground-based End User: Military, Commercial Aviation, Business Jets, UAVs Frequency Band: K-band, Ka-band, Ku-band, X-band |
| Companies Covered | Honeywell International Inc., Thales Group, Viasat, Inc., L3Harris Technologies, Inc., RTX Corporation, General Dynamics Mission Systems, Inc., Collins Aerospace, Israel Aerospace Industries, Hughes Network Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne SATCOM Equipment Market Strategic Shifts
Electronically steered arrays are displacing mechanically actuated antennas across both commercial and defense installations, compressing form factors while expanding operational frequency agility. This architectural shift is redrawing supplier capabilities around semiconductor fabrication rather than precision machining.
Flat-panel active electronically scanned arrays are displacing gimbal-mounted parabolic dishes in commercial aviation retrofit programs. Airlines operating Boeing 737 and Airbus A320 fleets are selecting these installations to reduce drag penalties and fuel burn during transoceanic routes. The technology is displacing legacy hardware vendors whose core competencies center on mechanical steering systems rather than RF semiconductor integration.
EASA's CS-25 certification amendments for connectivity equipment are mandating enhanced electromagnetic interference testing for Ka-band installations above 26 GHz. European commercial operators must now demonstrate coexistence between passenger Wi-Fi systems and flight-critical avionics. Narrow-body aircraft retrofit programs face the most pronounced compliance burden, with integrators extending project timelines to accommodate revised test protocols.
Defense procurement offices are consolidating SATCOM terminal awards under platform-level system integrators rather than awarding discrete hardware contracts. Prime contractors are absorbing subsystem vendors into captive supply chains, compressing the addressable market for standalone terminal manufacturers. This concentration is most visible in US Department of Defense programs, where platform primes now specify antenna and modem architectures as part of airframe delivery contracts.
Airborne SATCOM Equipment Market Segmentation
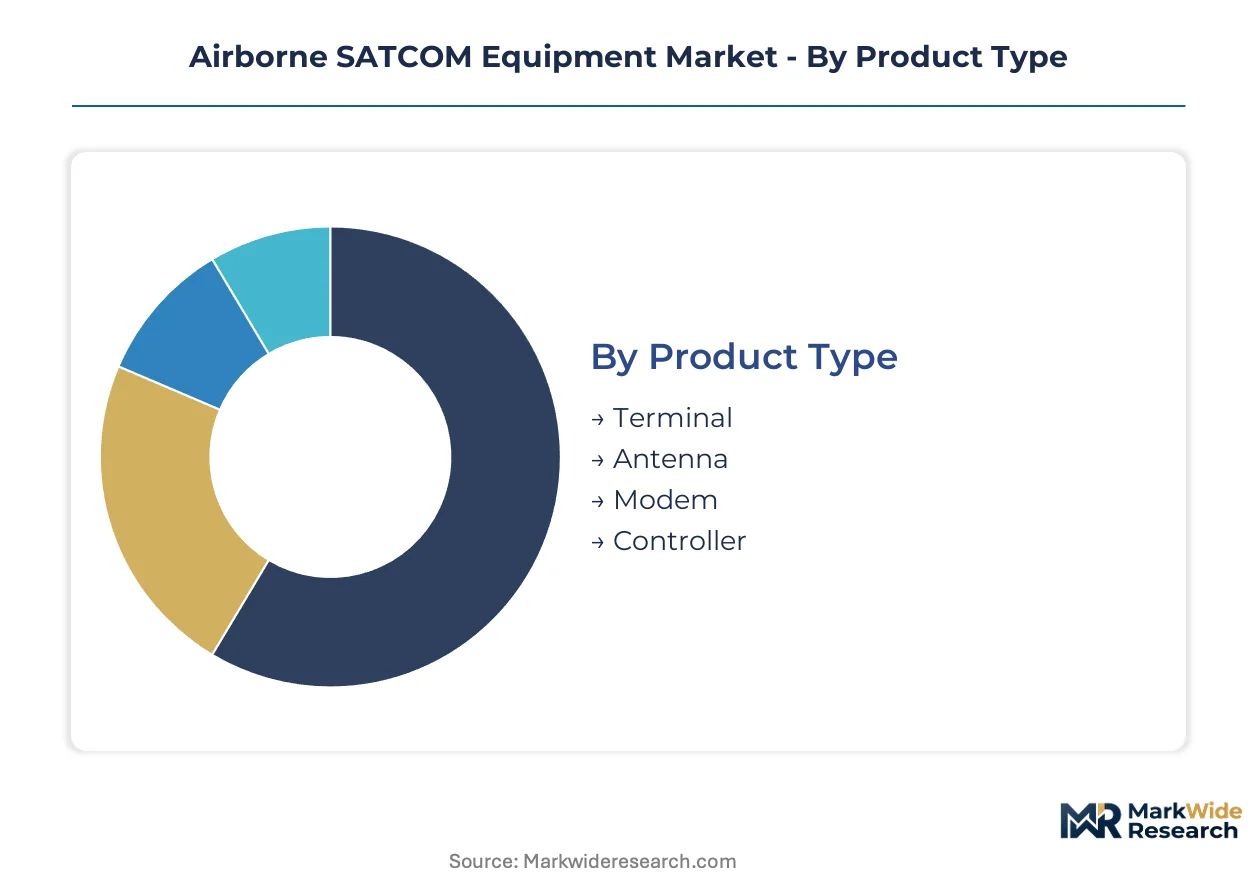
Segmentation in airborne SATCOM equipment reveals distinct procurement channels and technical requirements across defense and commercial aviation. Equipment specifications diverge sharply between military platforms requiring hardened X-band terminals and commercial operators optimizing for passenger connectivity economics. Understanding these segment boundaries helps suppliers align certification investments with addressable contract flows.
Product Type:
Terminal hardware flows primarily through airframe OEM integration contracts and military platform prime awards, while antenna and modem subsystems see heavier aftermarket and retrofit channel activity. Component-level procurement concentrates among RF specialists serving tier-two integrators.
- Terminal:Platform-specific integration units combining RF front-ends, power amplifiers, and environmental sealing for military airworthiness or commercial CS-25 certification. Demand clusters in US Department of Defense programs and European NATO fleet modernization, driven by beyond-line-of-sight command network requirements and FAA NextGen mandate compliance timelines.
- Antenna:Phased-array and mechanically steered architectures operating across 12–40 GHz with beam-steering electronics for high-dynamic flight profiles. Flat-panel electronically steered arrays are expanding most quickly in commercial aviation retrofit programs as airlines seek drag reduction on narrow-body transoceanic routes.
- Modem:Signal processing units encoding voice, data, and video streams for satellite uplink, spanning software-defined military architectures and purpose-built commercial chipsets.
- Controller:Interface modules managing antenna pointing, frequency agility, and network handoff protocols across multi-band installations.
Terminal hardware dominates installed base. Antenna represents where expansion concentrates.
Installation Type:
Cost tier stratification separates fixed military integrations at premium price points from portable commercial solutions and emerging UAV miniaturized formats. Ground-based testing equipment serves a distinct maintenance channel with lower margins but recurring revenue characteristics.
- Fixed:Permanent airframe-integrated installations on military ISR platforms and commercial wide-body aircraft, requiring full DO-160G or MIL-STD-810 qualification cycles. Demand concentrates in NATO member state defense procurement and US carrier fleet renewal programs, constrained by GaN substrate cost volatility and ITAR-controlled component lead times.
- Portable:Rapidly deployable terminals for tactical military units and emergency response aviation, prioritizing field reconfiguration over environmental hardening.
- In-flight:Passenger connectivity systems on commercial narrow-body and regional jets, governed by EASA CS-25 electromagnetic interference amendments above 26 GHz.
- Ground-based:Test and calibration equipment for pre-flight SATCOM system verification and maintenance depot operations.
Fixed installations anchor revenue stability. Portable configurations are climbing the fastest as expeditionary military requirements expand.
End User:
Application-driven demand splits between sovereign defense procurement with classified waveform requirements and commercial aviation connectivity services monetized through passenger fees. Business jet operators occupy a middle tier with mixed owner-operator and charter fleet economics.
- Military:Command network terminals for manned surveillance aircraft and unmanned systems requiring X-band and Ka-band beyond-line-of-sight links. Procurement flows through platform prime integrators in US, UK, and German defense programs, with India's PLI scheme opening indigenized assembly channels previously import-dependent.
- Commercial Aviation:Passenger Wi-Fi and crew communications on narrow-body and wide-body fleets, subject to FAA 14 CFR airworthiness directives and Ku-band spectrum congestion forcing Ka-band migration.
- Business Jets:Owner-operator and fractional ownership fleets demanding compact terminal form factors with premium service tier pricing.
- UAVs:Miniaturized terminals below 10 kg for beyond-visual-line-of-sight civilian operations in Australia and Canada regulatory waiver programs.
Military end users dominate program value. UAV applications represent the steepest expansion trajectory as regulatory frameworks mature.
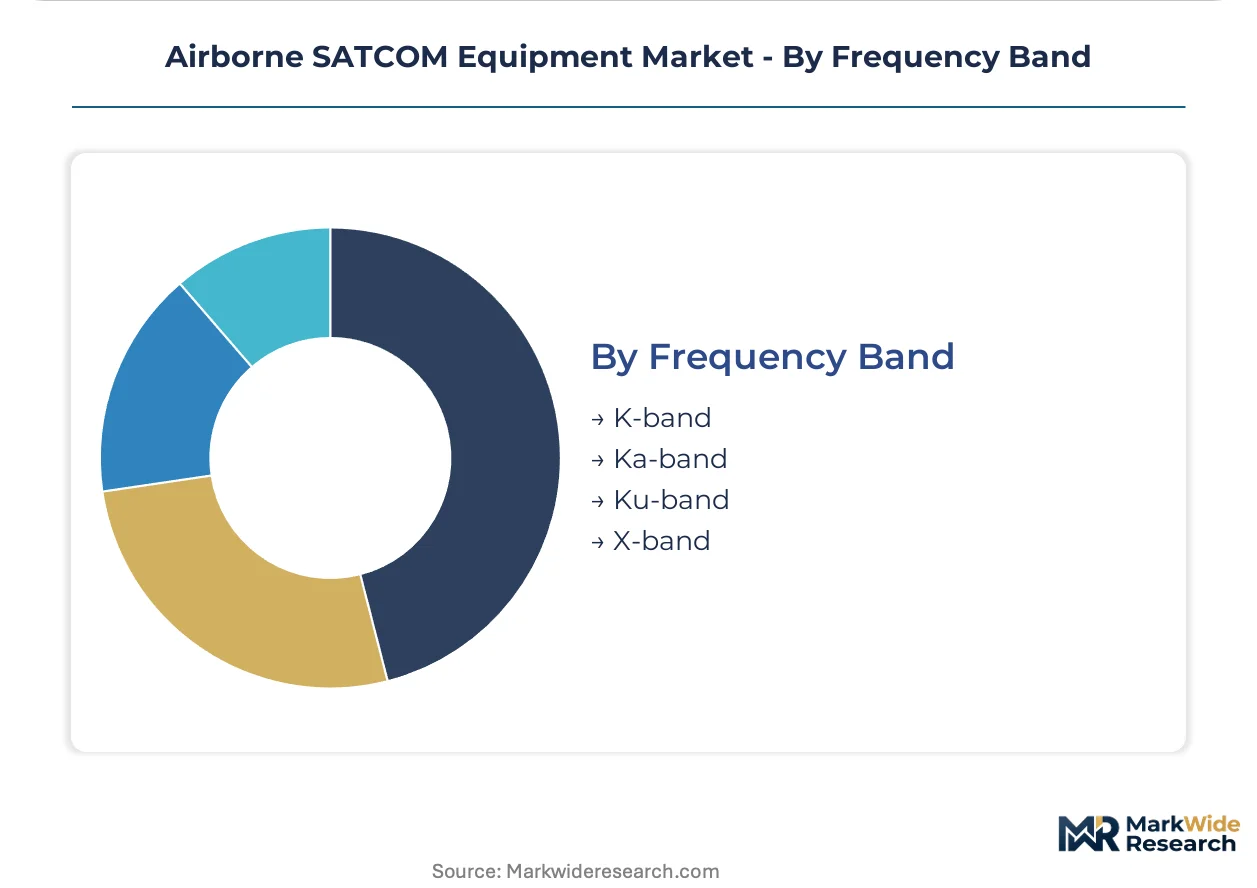
Frequency Band:
Geography and maturity shape band selection, with Ku-band saturation in North Atlantic corridors pushing deployment toward Ka-band architectures despite equipment cost premiums. K-band and X-band serve specialized military and emerging LEO constellation applications.
- K-band:18–27 GHz allocations supporting high-throughput military and experimental commercial links, constrained by atmospheric attenuation and limited satellite availability.
- Ka-band:26.5–40 GHz spectrum enabling broadband commercial passenger connectivity and high-data-rate military ISR feeds. Deployment accelerates in European and North American dense corridors where ITU Radio Regulations constrain additional Ku-band allocation.
- Ku-band:12–18 GHz legacy infrastructure with broad satellite coverage but congested spectrum in high-traffic regions.
- X-band:7–12 GHz military-protected allocations for NATO and allied command networks, resistant to commercial interference but requiring specialized terminal architectures.
Ku-band retains the largest installed footprint. Ka-band is gaining share fastest as commercial operators abandon spectrum-constrained legacy hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment pricing power concentrates in United States defense procurement channels, while European commercial aviation operators face compressed margins from EASA certification burdens and spectrum migration costs.
United States
Defense procurement and commercial fleet modernization overlap to sustain equipment demand. FAA 14 CFR airworthiness directives compel Ku-band hardware replacement across narrow-body and wide-body fleets. Seattle-Tacoma aerospace cluster hosts prime contractors integrating SATCOM terminals into Boeing delivery contracts.
Germany
NATO fleet modernization drives X-band and Ka-band terminal procurement for surveillance aircraft. KBA vehicle certification standards influence military airworthiness protocols adopted by Bundeswehr procurement offices. Bavaria's defense electronics corridor concentrates subsystem vendors serving Airbus Defence and Space programs.
France
Sovereign manufacturing requirements anchor Thales Group production lines for European defense and commercial programs. EASA CS-25 electromagnetic interference amendments above 26 GHz extend certification timelines for narrow-body retrofits. Toulouse aerospace cluster hosts integrated avionics development for Airbus A320 family connectivity solutions.
India
Defense indigenization opens procurement channels previously import-dependent for SATCOM terminals. PLI scheme for aerospace components incentivizes local assembly of RF subsystems. Bengaluru's defense electronics corridor attracts tier-two integrators establishing captive production for military platform programs.
United Kingdom
ISR platform expansion drives sustained procurement of beyond-line-of-sight command network equipment. Ministry of Defence procurement consolidates terminal awards under system integrators rather than discrete hardware contracts. Farnborough aerospace cluster hosts prime contractor facilities specifying antenna architectures for Royal Air Force delivery programs.
Airborne SATCOM Equipment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated avionics primes commanding platform-level relationships while component specialists compete on semiconductor fabrication scale. The market structures around three tiers: integrated system houses with airframe OEM partnerships, RF component specialists with GaN-on-SiC substrate access, and service providers leveraging proprietary constellation access. Consolidation pressures intensify as defense procurement offices absorb subsystem vendors into captive supply chains. Strategic moves center on backward integration into RF semiconductor fabrication and multi-orbit interoperability partnerships.
Among US-based integrated primes, Honeywell International Inc. and L3Harris Technologies, Inc. occupy positions anchoring platform-level system integration contracts. Thales Group exemplifies the European sovereign manufacturing archetype, sustaining defense and commercial program access through domestic production lines and satellite partnerships. Viasat, Inc. represents the service-provider model, differentiating through direct-to-aircraft broadband offerings rather than hardware-centric revenue streams.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Viasat, Inc. |
| L3Harris Technologies, Inc. |
| RTX Corporation |
| General Dynamics Mission Systems, Inc. |
| Collins Aerospace |
| Israel Aerospace Industries |
| Hughes Network Systems |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at GaN-on-SiC substrate foundries in Japan and the United States shapes both supply concentration and price floors for RF power amplifiers, compressing margins for terminal manufacturers unable to secure long-term offtake agreements.
Pricing Analysis
Configured-to-order military terminals command premiums of 40-60% above standard commercial aviation hardware due to ITAR-controlled cryptographic modules and MIL-STD-810 environmental qualification. Three-tier pricing structure across premium, standard, and economy levels separates hardened X-band platforms from narrow-body connectivity retrofits and portable expeditionary units. Price differentiation hinges on certification grade and volume scale, with FAA 14 CFR compliance timelines accelerating contract-based long-term offtake structures. Cost compression in commercial Ku-band retrofits is intensifying because airlines prioritize drag reduction over spectral performance, rendering price-sensitive narrow-body operators unwilling to absorb Ka-band migration premiums.
Supply Chain Analysis
Japan and the United States anchor GaN-on-SiC substrate fabrication for RF power amplifiers, while Taiwan and South Korea concentrate MMIC packaging and testing capacity. The supply chain draws from specialized ceramic substrates, high-purity gallium feedstock, and precision-machined waveguide components. Single-source vulnerability pervades ITAR-controlled cryptographic module sourcing, constraining non-US platform integrators. Distribution runs through airframe OEM integration contracts for fixed installations and tier-two RF specialists for aftermarket antenna retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as multi-orbit interoperability becomes the default procurement specification, with LEO-GEO handoff capability reshaping vendor lock-in dynamics across defense and commercial aviation ecosystems.
For Market Incumbents: Consolidate backward integration into RF semiconductor fabrication to defend against GaN substrate cost volatility and capture margin pools shifting from hardware to firmware. Lock in multi-year offtake agreements with Japanese substrate suppliers before defense procurement offices absorb subsystem vendors into captive supply chains. Certification investment in DO-160G and MIL-STD-810 test infrastructure anchors long-term platform relationships against emerging flat-panel specialists. For New Entrants and Emerging Players: Anchor in Australia's and Canada's regulatory waiver programs for UAV beyond-visual-line-of-sight operations, where miniaturized terminal demand runs ahead of established vendor capacity. Target civil drone operators seeking sub-10 kg SATCOM solutions as the most penetrable segment, bypassing ITAR-controlled military procurement channels. Pursue software-defined modem architectures as the go-to-market angle, capturing recurring firmware upgrade revenue rather than competing on hardware margins. For Investors and Strategic Acquirers: RF component specialists with GaN-on-SiC substrate access and sovereign manufacturing footprints offer the strongest long-term viability as defense procurement consolidates under platform primes. Watch for EASA CS-25 electromagnetic interference test protocol amendments above 26 GHz as the signal indicating which antenna architectures will secure narrow-body retrofit contract flows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Substrate Sourcing | Secures margin pools against Japanese supplier concentration and ITAR export control fragmentation. |
| Multi-Orbit Interoperability Partnership | Enables seamless LEO-GEO handoff for airlines demanding flat-panel antenna flexibility. |
| Software-Defined Modem Architecture Launch | Captures recurring firmware revenue from military end users requiring waveform reprogrammability. |
| Sovereign Manufacturing Footprint Expansion | Positions for India's PLI scheme incentives and European defense procurement domestic content rules. |
| Phased-Array Thermal Management Talent Acquisition | Addresses workforce scarcity constraining commercial market entry against defense contractor incumbents. |
Study Parameters
Desk research of ITU Radio Regulations filings, FAA airworthiness directive databases, and defense procurement contract disclosures preceded structured interviews with SATCOM terminal program managers, RF subsystem procurement leads at airframe OEMs, and electromagnetic compatibility test engineers. Primary fieldwork with GaN-on-SiC substrate suppliers and phased-array antenna design specialists validated secondary estimates of cost structures and lead time dynamics. Bottom-up equipment shipment modeling across terminal, antenna, and modem categories triangulated against top-down defense budget allocation analysis.
Variance decomposition across frequency band, installation type, and end-user segments structured the analytical framework over the projection horizon. Modeled dimensions included platform-specific integration complexity, certification tier, and sovereign content requirements. CAGRs derived from equipment refresh cycle timing, fleet modernization schedules, and regulatory mandate compliance windows. Industry-specific forecast inputs incorporated LEO constellation deployment timelines and ITU spectrum reallocation proceedings.
Decision-makers should treat outputs as directional under assumptions of sustained defense procurement growth and commercial aviation traffic recovery; material deviation in gallium substrate pricing or ITAR regulatory scope would warrant model refresh. Recalibration cycles align with material shifts in FAA NextGen implementation timelines and EASA CS-25 amendment finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Dual Axis Gyro Stabilized Platform Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
High-End Inertial Systems Market
Communication Navigation & Surveillance
Navigational Inertial Systems Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Tactical Radio Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Airborne Laser Obstacle Avoidance Monitoring Systems Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Autonomous Navigation System Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market