
 Space Situational Awareness Sensor and Tracking Performance Test Systems Market | 2026-2036
Space Situational Awareness Sensor and Tracking Performance Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Space Situational Awareness Sensor and Tracking Performance Test Systems Market Insights
EU Space Surveillance and Tracking (SST) framework requirements is expanding procurement obligations for European defense and aerospace entities. Northrop Grumman leverages its heritage in space-based infrared systems to sustain competitive positioning across sensor validation contracts. L3Harris Technologies anchors significant ground-based radar test infrastructure programs for US government customers. Lockheed Martin specializes in integrated electro-optical and radio frequency test architectures that dominate missile defense sensor qualification workflows.
Space situational awareness sensor and tracking performance test systems comprise calibrated instrumentation suites that measure detection range, angular resolution, and track accuracy against simulated orbital targets under controlled electromagnetic conditions. These systems verify that radar, lidar, electro-optical, and infrared sensors meet operational thresholds for debris tracking and collision avoidance missions. Electro-optical and infrared segments command premium positioning due to their critical role in geostationary orbit monitoring where thermal signature discrimination determines tracking reliability. Ground-based sensor type installations represent the mature revenue base, while space-based validation platforms emerge as the fastest-growing category driven by on-orbit demonstration requirements for next-generation constellations.
US Space Force operational requirements and EU SST framework obligations shape procurement standards for collision avoidance and space traffic management applications. FCC orbital debris mitigation rules and NASA sensor certification protocols further constrain market access to vendors demonstrating validated test traceability. Stakeholders must monitor evolving dual-use export control classifications that govern radio frequency and satellite-based test technology transfers between allied defense programs.
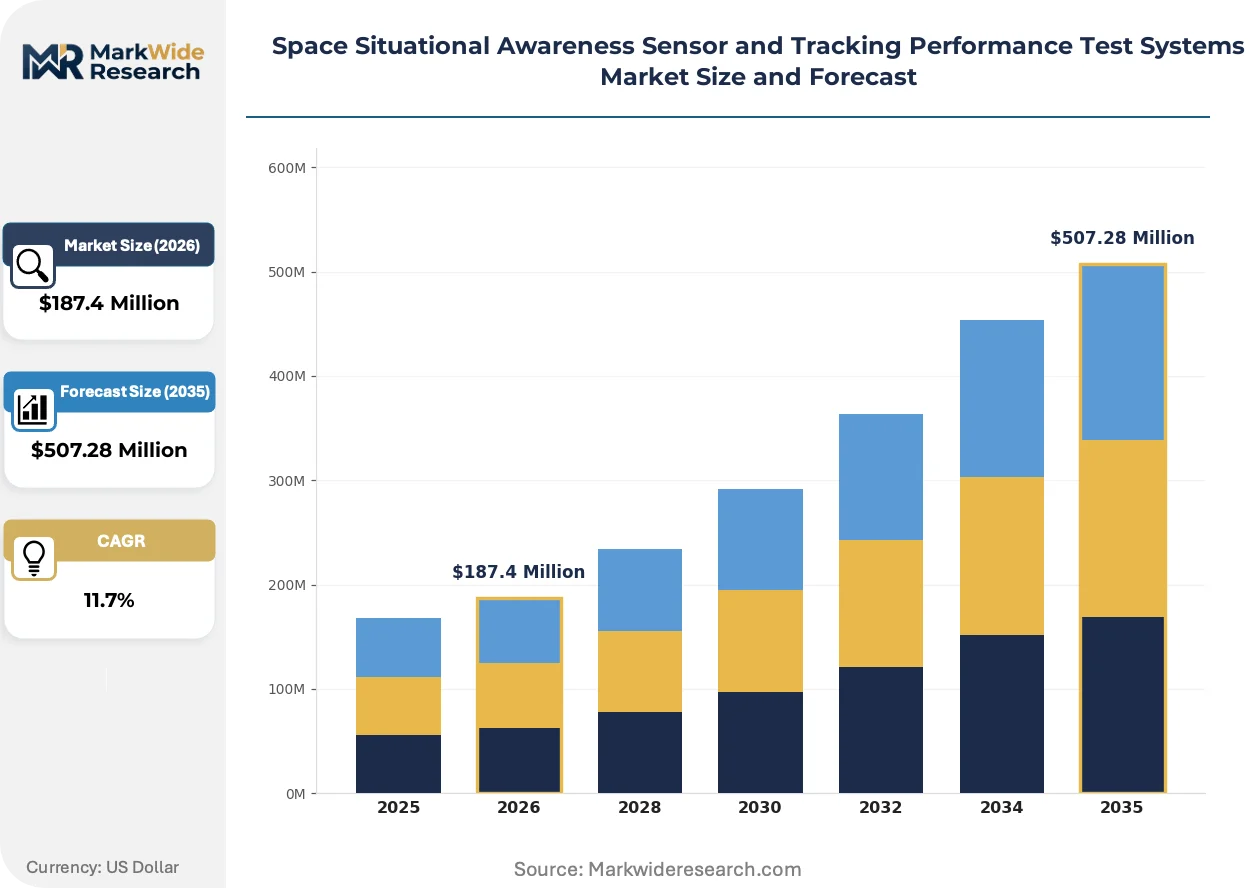
Market Dynamics
The US Space Force's operational requirements for improved orbital tracking accuracy are compressing procurement cycles for radio frequency and lidar calibration systems, forcing defense contractors to accelerate sensor validation capabilities against proliferating satellite constellations.
Growth Catalysts
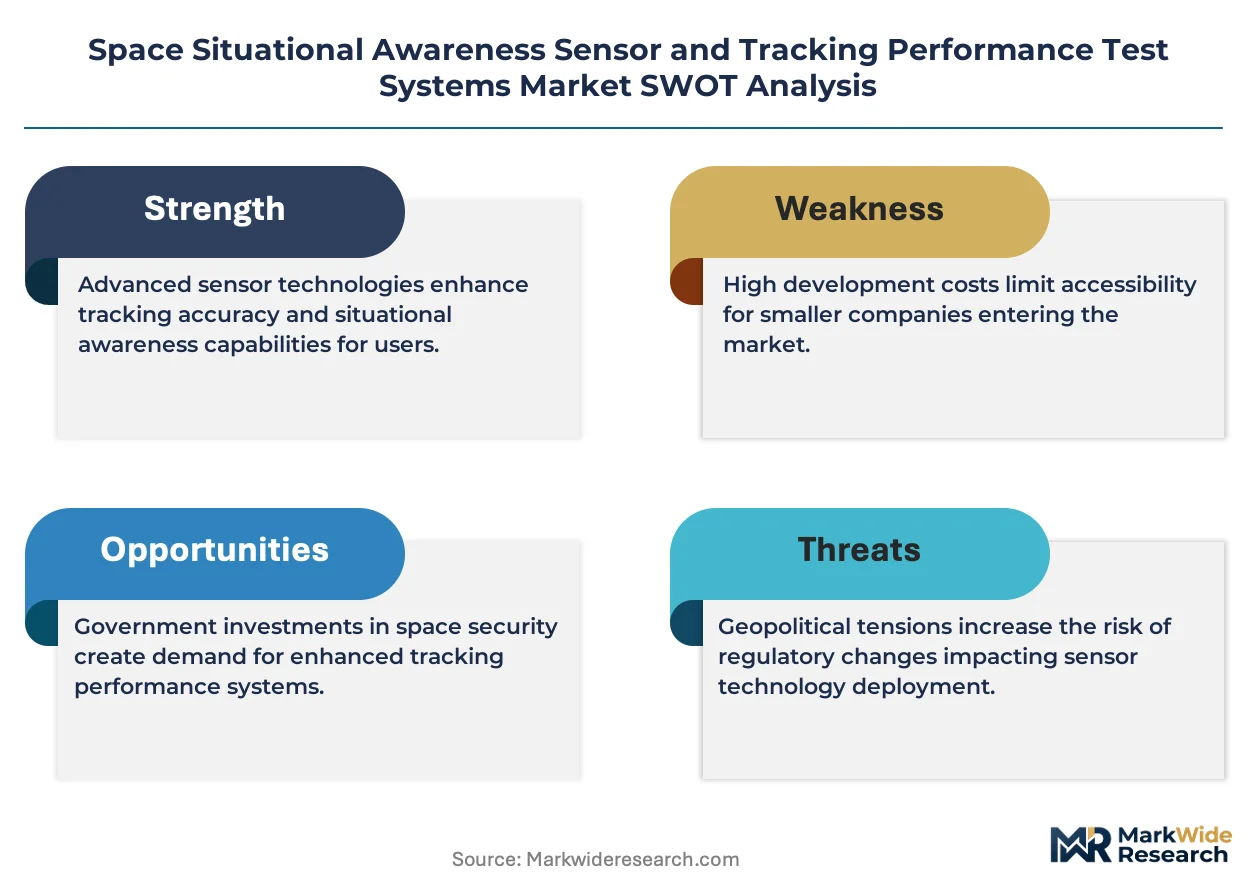
- EU Space Surveillance and Tracking framework:Procurement obligations for European defense and aerospace entities are expanding under mandated collision avoidance protocols. Member states must validate ground-based radar and electro-optical suites against standardized performance thresholds.
- Proliferating commercial constellations:Low Earth orbit satellite deployments by commercial operators are generating demand for continuous sensor validation. Test systems verify detection range and track accuracy against high-velocity orbital targets.
- Dual-use export control alignment:Radio frequency and satellite-based test technology transfers between allied defense programs are streamlining cross-border procurement. NATO standardization is reducing vendor qualification friction.
Market Restraints
- High-purity optical component costs:Precision mirrors and detectors for electro-optical test benches face supply concentration from German and Japanese specialty manufacturers. Input cost volatility constrains margin flexibility for system integrators.
- Electromagnetic spectrum licensing:Radio frequency test operations require coordinated frequency allocation from national regulators. FCC and national spectrum authorities impose transmission power limits that restrict test range scalability.
- Legacy radar substitution pressure:Mechanical steerable antenna test systems face displacement by phased array architectures. Incumbent installed base creates upgrade friction for defense customers with sunk capital.
Strategic Opportunities
- On-orbit demonstration platforms:Space-based validation systems represent emerging white space as next-generation constellations require in-situ sensor verification. Japan's national space agency is advancing orbital test bed procurement.
- Integrated lidar-RF architectures:Convergence of laser ranging with radio frequency tracking is enabling single-platform multi-sensor qualification. This reduces facility footprint for ground-based test ranges.
- India's space surveillance network expansion:The country's national space program is establishing dedicated sensor validation infrastructure. Foreign vendor participation is opening through offset and technology transfer agreements.
Industry Challenges
- Electromagnetic compatibility certification timelines:Test systems must demonstrate non-interference with operational space surveillance networks. Validation protocols from NASA and ESA extend product qualification cycles.
- Multi-sensor fusion algorithm development:Integrating radar, electro-optical, and infrared data streams requires specialized software engineering talent. Workforce scarcity in signal processing and orbital mechanics constrains delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Situational Awareness Sensor and Tracking Performance Test Systems Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar, Lidar, Radio Frequency, Electro-Optical, Infrared, Satellite-Based Sensor Type: Ground-Based, Space-Based, Airborne, Mobile, Fixed Installation Application: Collision Avoidance, Debris Tracking, Satellite Health Monitoring, Space Traffic Management, Missile Defense End User: Government Agencies, Defense Contractors, Aerospace Manufacturers, Research Institutions |
| Companies Covered | Raytheon Technologies, Northrop Grumman, L3Harris Technologies, BAE Systems, Lockheed Martin, Keysight Technologies, Rohde & Schwarz, Teledyne, Hexagon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Situational Awareness Sensor and Tracking Performance Test Systems Market Trends and Innovations
Sensor fusion architectures and on-orbit validation methodologies are compressing traditional ground-based test paradigms, creating structural pressure on facility-based qualification workflows.
Digital twin environments for orbital target simulation are integrating physics-based modeling with real-time sensor feedback. US Space Force test ranges are adopting these virtual-physical hybrid systems to reduce live-sky observation dependencies. This technology is integrating hardware-in-the-loop validation with cloud-based scenario generation, collapsing test campaign durations from months to weeks.
FCC orbital debris mitigation rules are mandating post-mission disposal verification for licensed satellite operators. Commercial constellation providers must demonstrate tracking cooperability with US Space Surveillance Network sensors. Small satellite manufacturers in California and Texas are responding by pre-qualifying payloads against standardized radar cross-section and optical signature databases.
Performance-based service contracts are displacing capital equipment purchases among mid-tier defense contractors. German and Japanese sensor integrators now subscribe to test capacity at shared national facilities rather than maintaining captive calibration infrastructure. This consumption-pattern shift concentrates revenue with facility operators in Munich, Tokyo, and Colorado Springs while reducing equipment vendor direct sales.
Space Situational Awareness Sensor and Tracking Performance Test Systems Market Segmentation
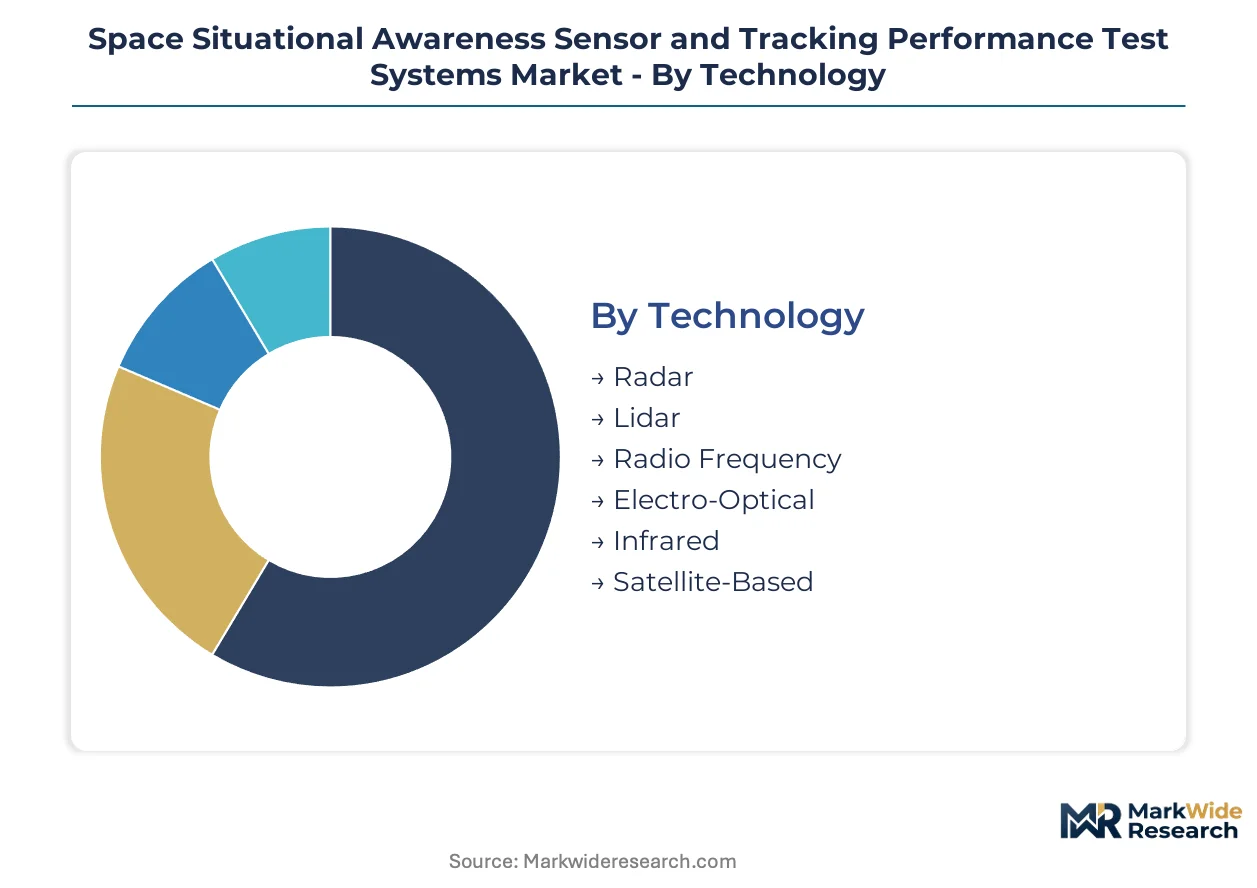
Test system architectures vary dramatically by validation environment, orbital target characteristics, and procurement authority. Segmentation reveals where capital concentrates versus where service-based models are displacing equipment purchases.
Technology:
Customization intensity spans from commodity radio frequency benches to bespoke satellite-based orbital demonstrators requiring years of development.
- Electro-Optical:Precision telescopes and photon-counting detectors measure angular position and thermal signatures against geostationary satellites. US Space Force and EU SST procurement prioritize these systems for high-altitude orbit monitoring where atmospheric distortion compensation determines accuracy thresholds.
- Infrared:Cryogenically-cooled focal plane arrays discriminate spacecraft thermal profiles from background radiation. Demand clusters in Japan's national space surveillance network and German defense research facilities upgrading legacy mid-wave systems.
- Radar:Pulsed and continuous-wave architectures validate detection range against small debris objects. Mechanical steerable systems face phased array substitution pressure.
- Lidar:Laser ranging systems provide centimeter-precision distance measurement for cooperative satellite tracking. Integration with RF platforms is accelerating.
- Radio Frequency:Signal analyzers and spectrum monitors verify transponder emissions and interference characteristics. Commercial constellation operators deploy these for pre-launch payload validation.
- Satellite-Based:On-orbit sensor demonstrators validate performance in actual space environments. Japan's JAXA leads procurement for next-generation constellation verification.
Most installed capacity flows through Radar. Expansion is steepest in Satellite-Based.
Sensor Type:
Volume concentration versus capability frontier tension shapes procurement patterns across fixed facilities and deployable architectures.
- Ground-Based:Permanent test ranges with anechoic chambers and optical laboratories dominate qualification workflows for US Space Force and NATO sensor programs. These installations anchor revenue through long-term service contracts rather than equipment turnover.
- Space-Based:Orbital validation platforms eliminate atmospheric interference for true performance characterization. Development timelines extend procurement cycles but command premium pricing from agencies requiring flight-proven sensor heritage.
- Airborne:High-altitude aircraft carry test payloads above atmospheric distortion layers for stratospheric calibration campaigns. Flexibility trades against payload mass constraints.
- Mobile:Transportable radar and electro-optical suites enable expeditionary validation for deployed military units. Ruggedization requirements inflate unit costs versus fixed equivalents.
- Fixed Installation:Dedicated national facilities in Colorado Springs, Munich, and Tokyo concentrate test capacity through shared-access service models. Mid-tier contractors increasingly subscribe rather than own.
Revenue concentrates in Ground-Based. Space-Based is gaining share fastest.
Application:
Mission-criticality gradients separate statutory compliance-driven procurement from discretionary capability enhancement.
- Collision Avoidance:FCC orbital debris mitigation rules mandate tracking cooperability verification for licensed satellite operators. Commercial constellation providers must demonstrate radar cross-section and optical signature standards before launch authorization.
- Debris Tracking:Detection and cataloging of non-cooperative objects requires validation against high-velocity, low-signature targets. US Space Surveillance Network sensor qualification drives sustained demand for ground-based test infrastructure.
- Satellite Health Monitoring:On-orbit payload performance verification uses standardized telemetry validation suites. Commercial operators in California and Texas deploy these for constellation lifecycle management.
- Space Traffic Management:Multi-operator coordination protocols require interoperable sensor performance standards. EU SST framework mandates standardized validation thresholds across member state facilities.
- Missile Defense:Boost-phase and mid-course tracking sensor qualification demands electromagnetic compatibility with operational warning networks. Lockheed Martin and Northrop Grumman anchor integrated test architecture procurement.
Collision Avoidance commands the largest procurement volume. Space Traffic Management shows the steepest policy-driven expansion trajectory.
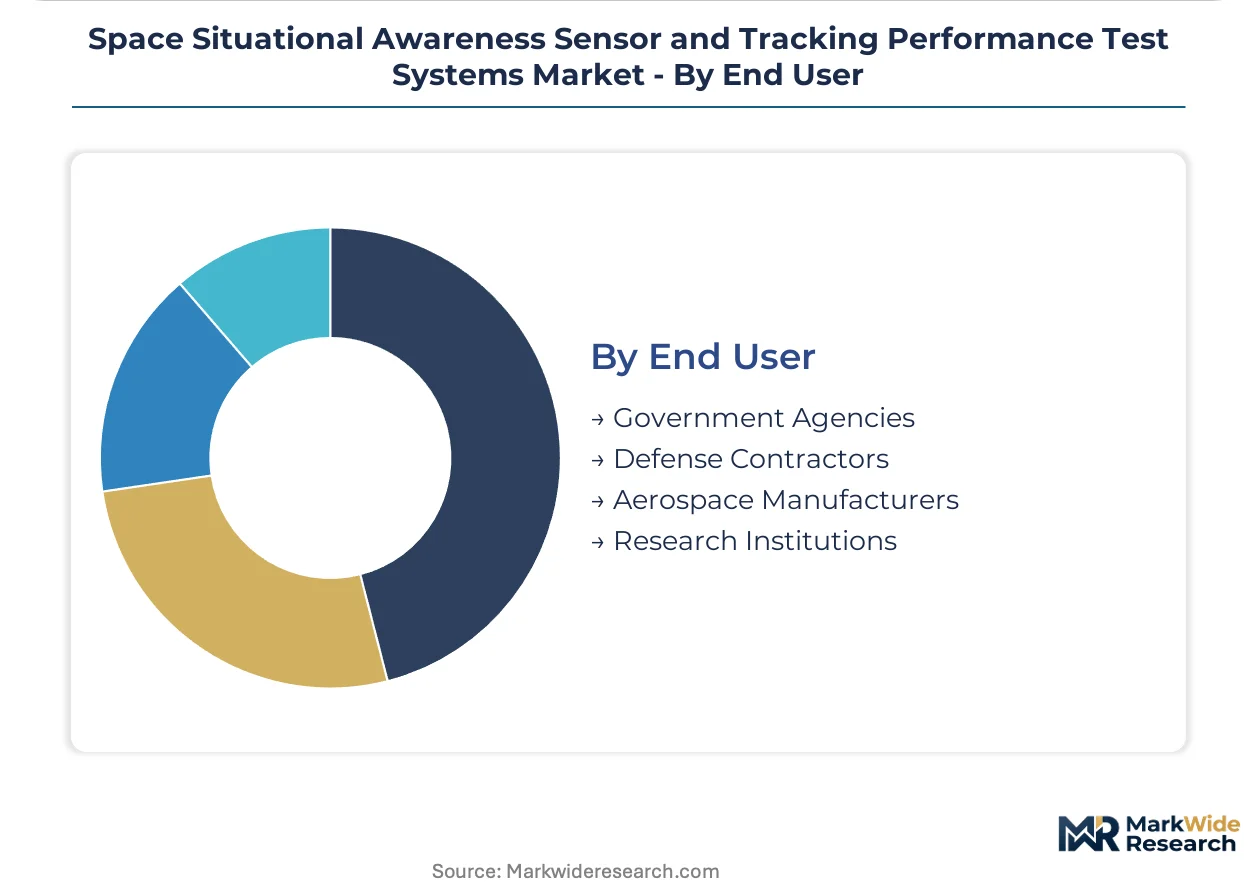
End User:
Budget cycle predictability and technical specification authority divide this landscape between sovereign purchasers and commercial suppliers.
- Government Agencies:US Space Force, EU SST consortium members, and Japan's JAXA operate dedicated procurement channels with multi-year funding horizons. These customers prioritize traceable calibration chains and electromagnetic compatibility certification.
- Defense Contractors:Northrop Grumman, L3Harris, and Lockheed Martin maintain captive test capabilities for classified sensor programs. Performance-based service contracts are displacing capital equipment purchases among mid-tier suppliers.
- Aerospace Manufacturers:Small satellite producers in California and Texas pre-qualify payloads against standardized signature databases to accelerate FCC licensing timelines.
- Research Institutions:German and Japanese university consortia access national shared facilities for algorithm development and sensor fusion research. Grant-funded procurement follows academic budget cycles with extended decision timelines.
Government Agencies account for the dominant share of installed base. Aerospace Manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Space situational awareness test systems originated within US defense research corridors during Cold War satellite tracking programs, then diffused to allied nations establishing sovereign space surveillance networks. Procurement now concentrates where national agencies operate dedicated orbital monitoring infrastructure requiring continuous sensor validation.
United States
The US Space Force compresses procurement cycles for radio frequency and lidar calibration systems at test ranges in Colorado Springs. FCC orbital debris mitigation rules mandate tracking cooperability verification for commercial constellation operators. California and Texas small satellite manufacturers pre-qualify payloads against standardized signature databases to accelerate launch licensing timelines.
Germany
EU Space Surveillance and Tracking framework obligations expand procurement for ground-based radar and electro-optical validation suites. German defense research facilities upgrade legacy mid-wave infrared systems under standardized performance thresholds. Munich anchors shared-access test facility operations where mid-tier contractors subscribe to calibration capacity rather than maintaining captive infrastructure.
Japan
JAXA leads procurement for on-orbit sensor demonstration platforms validating next-generation constellation performance. The national space surveillance network requires continuous electro-optical and infrared sensor verification against geostationary targets. Tokyo concentrates facility operations where government agencies and university consortia access shared test infrastructure for algorithm development.
United Kingdom
UK Space Agency participation in EU SST consortium drives standardized validation threshold adoption across national facilities. British defense contractors maintain electromagnetic compatibility certification chains for classified sensor programs. Harwell Campus clusters aerospace research institutions accessing grant-funded test capacity for orbital mechanics research.
India
The national space program establishes dedicated sensor validation infrastructure through offset and technology transfer agreements. Foreign vendor participation opens as the country expands ground-based radar test architecture. Bengaluru concentrates aerospace manufacturing where small satellite producers seek pre-launch payload qualification against emerging signature databases.
Space Situational Awareness Sensor and Tracking Performance Test Systems Market Competitive Landscape
Capital-heavy defense primes compete with specialized instrumentation houses across contract tiers. The vendor base stratifies between integrated system architects and component specialists. Three archetypes dominate: full-spectrum platform integrators, sensor-specific test bench builders, and software-defined validation suite developers. Competitive dynamics center on strategic partnerships for cross-technology integration and geographic expansion through national facility concessions.
Within the full-spectrum integrator tier, Northrop Grumman, Lockheed Martin, and L3Harris Technologies occupy positions anchored by heritage defense relationships. These entities exemplify platform-level competition where electromagnetic compatibility certification and traceable calibration chains determine contract access. Raytheon Technologies and BAE Systems represent the transatlantic defense prime archetype, sitting within procurement channels shaped by NATO standardization and dual-use export control alignment. Specialized instrumentation houses including Keysight Technologies, Rohde & Schwarz, and Teledyne occupy the test equipment tier, with Hexagon representing the geospatial-technology convergence archetype.
| Leading Market Players |
|---|
| Raytheon Technologies |
| Northrop Grumman |
| L3Harris Technologies |
| BAE Systems |
| Lockheed Martin |
| Keysight Technologies |
| Rohde & Schwarz |
| Teledyne |
| Hexagon |
| Others |
Pricing and Supply Chain Analysis
Captive integration of precision optical component manufacturing anchors supply position and pricing power for electro-optical test bench builders serving US Space Force and EU SST procurement channels. German and Japanese specialty manufacturers control high-purity mirror and detector supply, forcing system integrators to absorb input cost volatility or pursue backward integration into optical fabrication.
Pricing Analysis
Performance-based service contracts now dominate capital equipment purchases across mid-tier defense contractors and commercial constellation operators. Price differentiation rests on electromagnetic compatibility certification tier and traceable calibration chain documentation, with government agencies showing lowest sensitivity due to mission-critical requirements. Cost compression in ground-based radar test systems intensifies as phased array architectures displace mechanical steerable platforms. Small satellite manufacturers in California and Texas exhibit highest price sensitivity, driving subscription models at shared national facilities.
Supply Chain Analysis
Refurbishment flows for cryogenically-cooled infrared focal plane arrays and precision telescope assemblies concentrate in Germany and Japan, with secondary remanufacturing capacity emerging in the United States. Critical inputs include germanium substrates, low-expansion glass ceramics, and super-polished aluminum mirrors. Single-source vulnerability in specialty optical coating processes creates procurement risk for electro-optical test bench builders. Distribution runs through defense prime contractor channels and direct national facility concessions rather than open market commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where FCC orbital debris mitigation rules and EU SST framework obligations are shifting procurement toward premium-tier sensor validation systems with certified traceability chains.
For Market Incumbents: Cement electromagnetic compatibility certification leadership through accelerated NASA and ESA validation protocol engagement. Pursue backward integration into precision optical component fabrication to offset German and Japanese supply concentration. Phased array radar test architectures threaten mechanical steerable installed base; defend through upgrade financing and long-term service contract lock-in. For New Entrants and Emerging Players: Software-defined validation suites with multi-sensor fusion algorithms offer technology-first wedge into workforce-constrained signal processing segments. India's expanding space surveillance network through offset agreements represents most penetrable geography. Target commercial constellation operators in California and Texas with pre-launch payload qualification subscriptions against standardized signature databases. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier contractors lack captive electromagnetic compatibility certification chains and rely on shared national facility access. Long-term viability favors vertically integrated platform architects with heritage defense relationships over pure-play test equipment vendors. Monitor FCC rulemaking on orbital debris mitigation verification timelines as inflection indicator for commercial demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Lidar-RF Architecture Development | Single-platform multi-sensor qualification reduces Colorado Springs facility footprint requirements. |
| On-Orbit Demonstration Platform Procurement | JAXA-led programs validate next-generation constellation performance in actual space environments. |
| Electromagnetic Compatibility Certification Investment | Traceable calibration chains unlock US Space Force and EU SST procurement channel access. |
| Shared National Facility Concession | Munich and Tokyo service subscriptions displace captive infrastructure among mid-tier contractors. |
| Precision Optical Component Backward Integration | German and Japanese supply concentration mitigation secures margin stability for electro-optical benches. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with US Space Force program officers, EU SST consortium technical leads, JAXA procurement directors, commercial constellation operations executives, and electro-optical test bench engineering managers with secondary validation against FCC orbital debris mitigation filings, NASA sensor certification protocols, ESA technical standards documentation, and defense prime contractor SEC disclosures. Bottom-up segment sizing and top-down macro constraint triangulation anchored value estimates.
Comparable-period anchoring to historical procurement cycles across the analysis window informed projection frameworks. Segmentation dimensions modeled include technology type, sensor platform architecture, application mission profile, and end-user budget authority tier. CAGRs derived from fitted growth curves applied to disclosed program funding trajectories and facility capacity expansion announcements. Industry-specific inputs encompassed US Space Force operational requirement documents and EU SST framework procurement obligation schedules.
The model holds under stable dual-use export control alignment and sustained FCC orbital debris enforcement; deviation in electromagnetic spectrum licensing timelines or NATO standardization delays would shift delivery schedules and revenue recognition patterns. Practitioners should monitor ESA and NASA validation protocol revision cycles for early signals of qualification burden changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Flight Tracking System Market
Communication Navigation & Surveillance
Tactical Communications Market