
 US Satellite Connectivity Market | 2026-2036
US Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
US Satellite Connectivity Market Insights
The gap between premium low-latency LEO services and legacy GEO commodity bandwidth is realigning procurement patterns across federal and enterprise buyers. SpaceX leverages its vertically integrated launch-to-terminal stack to dominate price-performance benchmarks in consumer broadband. Viasat anchors government and aviation contracts through specialized high-throughput payloads and dedicated military frequency bands. Hughes Network Systems competes in rural enterprise connectivity with managed-service models that bundle installation and support.
US satellite connectivity encompasses the transmission of voice, video, and data signals between ground terminals and orbiting spacecraft operating across Ku, Ka, and V-band frequencies with latencies ranging from 20 milliseconds for LEO constellations to 500+ milliseconds for geostationary platforms. The primary commercial purpose is to extend broadband coverage to unserved geographic areas and provide resilient backup to terrestrial fiber networks. LEO technology captures the fastest expansion as constellation operators race to deploy interoperable terminals, while GEO retains mature cash flows from video distribution and maritime contracts. Defense applications concentrate margin pools due to encrypted waveform requirements and sustained federal spending on tactical satellite communications.
The FCC governs spectrum licensing and orbital slot coordination, with its recent processing round reforms compressing deployment timelines for non-geostationary systems. The FAA regulates commercial launch operations and reentry safety, directly constraining how quickly operators can orbit new spacecraft. The NTIA manages federal frequency assignments, creating priority access rules that shape military-civilian spectrum sharing. Stakeholders must monitor how the FCC's spectrum auction schedule and the FAA's streamlined launch licensing proposals alter competitive entry costs and constellation scale economics.
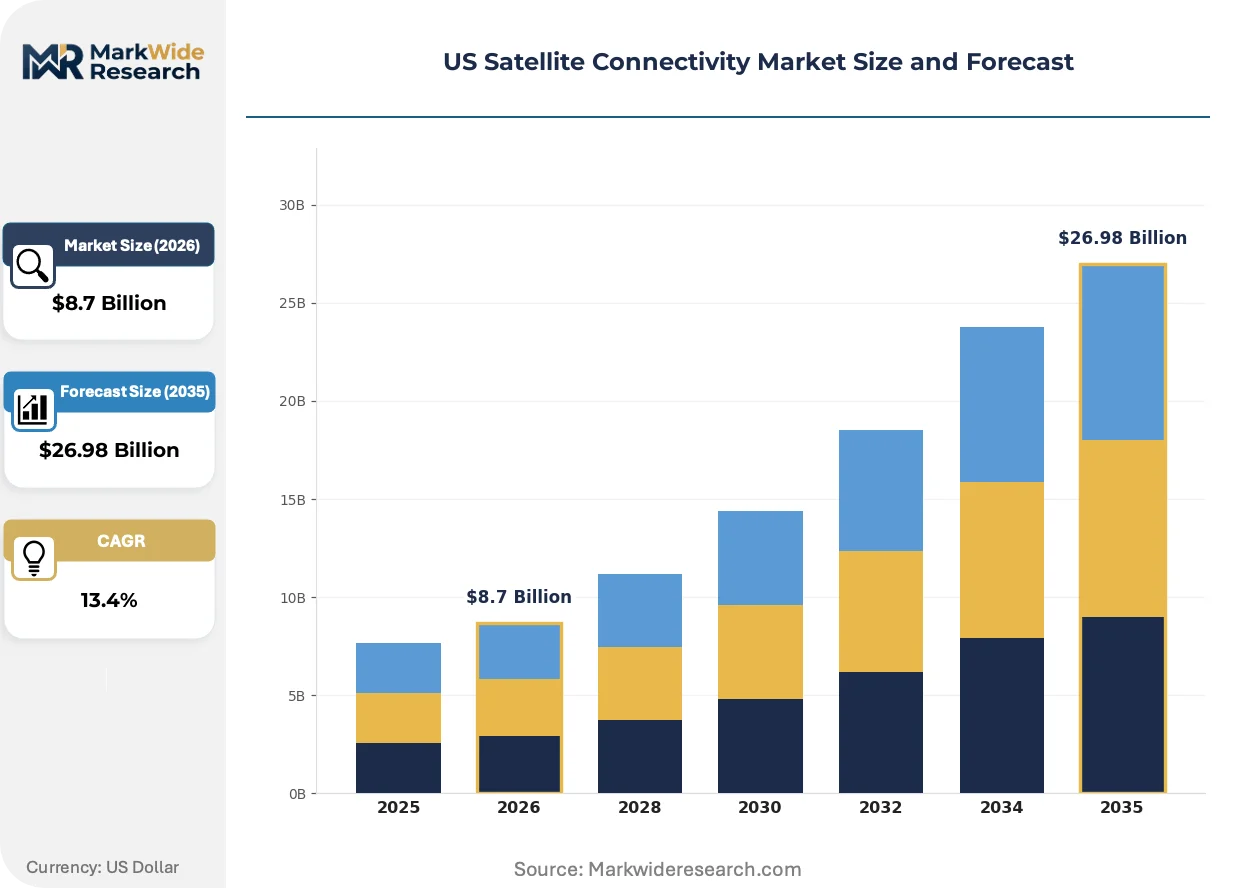
Market Dynamics
The FCC's accelerated spectrum reallocation timeline is compressing deployment schedules for non-geostationary constellations while defense procurement shifts toward resilient tactical communications architectures.
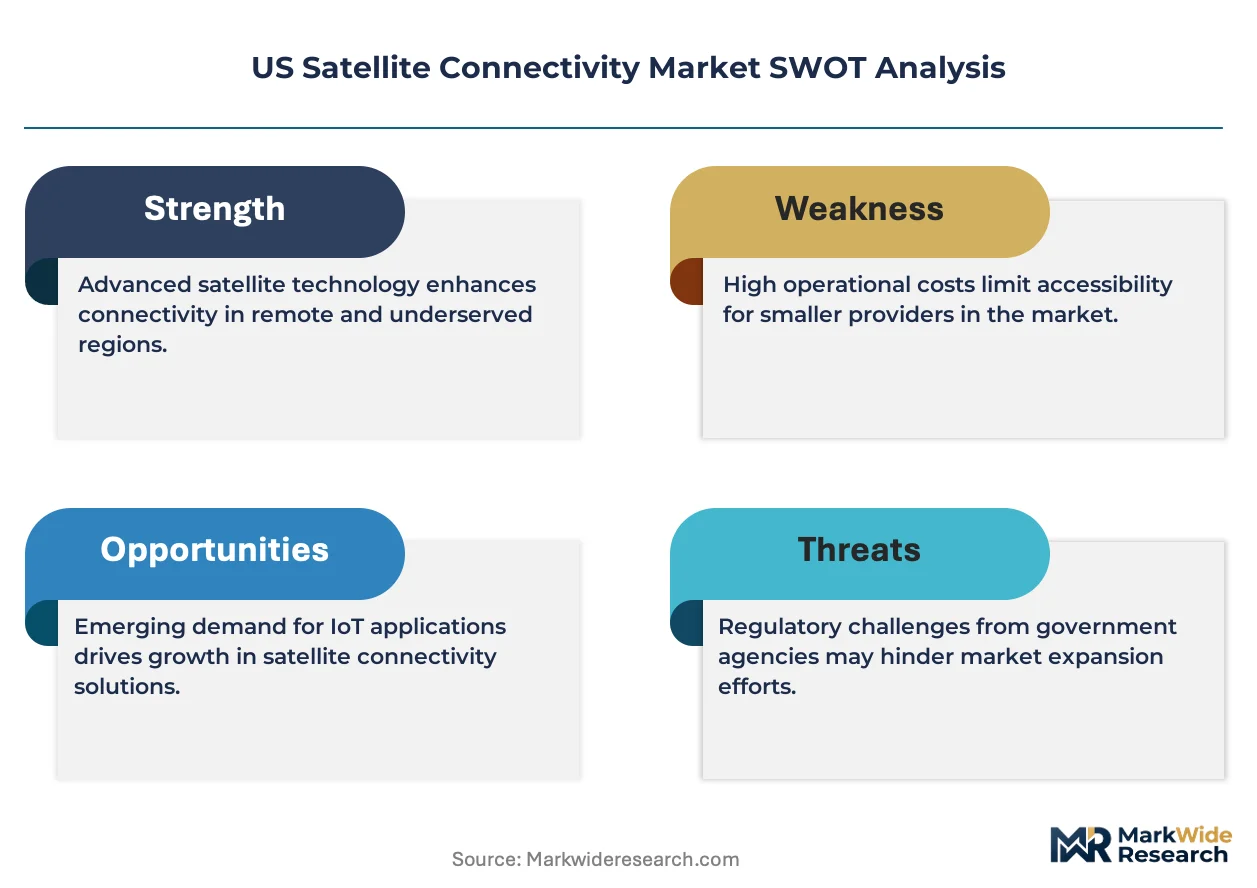
Growth Catalysts
- Defense procurement expansion:Federal agencies are prioritizing encrypted waveform satellite systems for tactical operations, creating sustained demand for specialized military frequency bands and hardened ground terminals.
- LEO constellation race:Orbital slot competition under FCC processing round reforms is driving rapid spacecraft deployment and interoperable terminal development across Ku, Ka, and V-band frequencies.
- Aviation connectivity mandates:Commercial airlines are retrofitting fleets with high-throughput satellite links to meet passenger broadband expectations and operational data requirements.
Market Restraints
- Launch capacity bottlenecks:FAA commercial launch licensing constraints and limited domestic pad availability restrict how quickly operators can orbit new spacecraft.
- Spectrum coordination friction:NTIA priority access rules for federal frequency assignments create complex military-civilian sharing protocols that delay civilian system activation.
- Terminal cost barriers:Phased array antenna production remains concentrated among specialized suppliers, keeping consumer hardware prices elevated relative to terrestrial alternatives.
Strategic Opportunities
- Rural enterprise gaps:Agricultural and extractive operations in the Mountain West and Great Plains lack fiber backhaul, creating addressable demand for managed satellite services.
- Maritime regulatory tailwind:International Maritime Organization safety mandates are accelerating fleet-wide satellite terminal adoption for vessel tracking and crew welfare communications.
- LEO-GEO hybrid architectures:Convergence of low-latency constellations with geostationary video distribution is enabling unified service platforms for broadcast and broadband.
Industry Challenges
- RF engineering talent scarcity:Specialized skills in phased array design and satellite payload integration are concentrated among legacy aerospace employers, constraining startup hiring.
- Legacy system integration:Government buyers require backward-compatible waveforms and interoperable ground segments, complicating pure-play LEO vendor entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Satellite Connectivity Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadband, Mobile, IoT, Data Transmission Technology: VSAT, LEO, GEO, MEO End User: Aerospace, Maritime, Defense, Enterprises Application: Remote Sensing, Telemedicine, Emergency Services, Broadcasting |
| Companies Covered | SpaceX, Viasat, EchoStar Corporation, Iridium Communications, Gilat Satellite Networks, Inmarsat Global Limited, SES, Hughes Network Systems, Amazon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Satellite Connectivity Market Trends and Innovations
Terminal hardware miniaturization and software-defined payload architectures are compressing the cost-performance gap between established geostationary platforms and emerging low-earth orbit networks.
Electronically steered phased array antennas are absorbing functions previously distributed across mechanical gimbals, amplifiers, and modems. Defense integrators and maritime operators are adopting these flat-panel terminals fastest, drawn by conformal mounting options and rapid beam-switching. This consolidation is absorbing subsystem supplier margins and redirecting value toward semiconductor foundries and waveform software developers.
The FCC's streamlined small satellite licensing framework is compressing authorization timelines from 24 months to under 12 months for qualified operators. This regulatory acceleration is enabling constellation operators to iterate spacecraft designs on orbital timelines rather than terrestrial test cycles. Non-geostationary applicants are responding with more aggressive deployment commitments to secure priority spectrum access.
Enterprise buyers are unbundling satellite services from long-term managed network contracts, preferring bandwidth-on-demand purchasing through web portals. This disintermediation is compressing systems integrator margins while expanding direct-to-operator relationships. Energy sector buyers in the Permian Basin and agricultural cooperatives in the Corn Belt are most visible in this shift, driven by seasonal usage variability and capital discipline pressures.
US Satellite Connectivity Market Segmentation
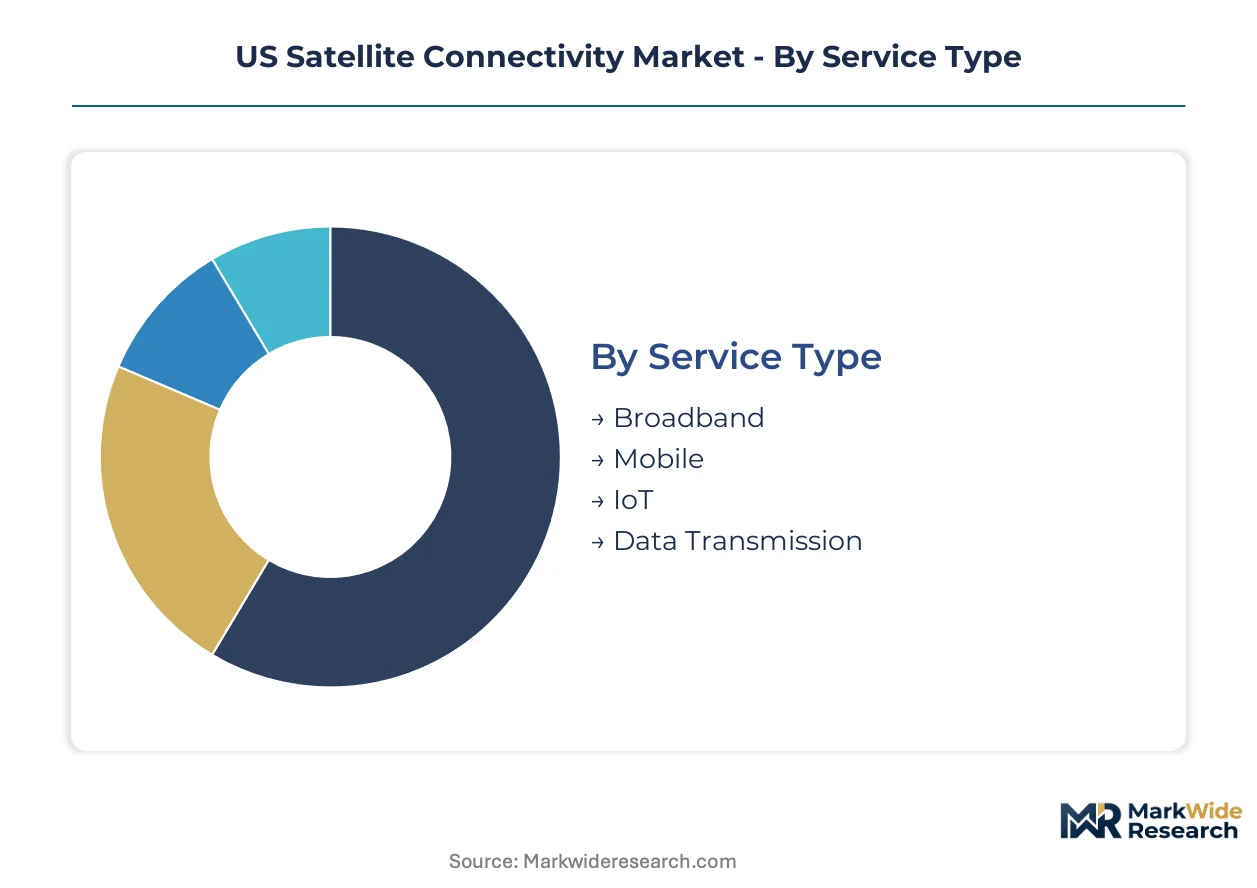
US satellite connectivity procurement patterns diverge sharply across orbital architectures and service tiers. Defense buyers prioritize encrypted waveforms and hardened terminals, while commercial aviation and maritime operators optimize for throughput density and conformal antenna footprints.
Service Type:
Broadband and mobile services anchor revenue concentration, with IoT and data transmission expanding through specialized vertical integrations.
- Broadband:High-throughput Ku and Ka-band links deliver consumer and enterprise internet to unserved rural markets. California's aerospace corridor and Texas energy basins concentrate subscriber growth where fiber backhaul remains uneconomical.
- Mobile:In-motion connectivity for aviation and maritime fleets leverages electronically steered phased arrays. Passenger broadband expectations and crew welfare mandates are accelerating fleet retrofit cycles across US-flagged carriers.
- IoT:Narrowband machine-to-machine links serve agricultural sensor networks and remote asset monitoring in the Mountain West.
- Data Transmission:Enterprise-grade dedicated circuits support financial services backup and government secure communications.
Mature deployment sits with Broadband. Newer deployment is concentrated in IoT.
Technology:
Orbital altitude determines latency profiles, procurement cost structures, and regulatory licensing pathways under FCC processing rounds.
- LEO:Low-earth orbit constellations at 300-1,200 km altitude deliver sub-50 millisecond latency through dense satellite meshes. FCC spectrum reallocation reforms are compressing deployment timelines for non-geostationary applicants seeking priority market access.
- GEO:Geostationary platforms at 35,786 km sustain mature cash flows from video distribution and maritime contracts. Higher latency limits interactive applications but preserves cost advantages for broadcast and one-way data dissemination.
- VSAT:Very Small Aperture Terminal ground systems enable two-way satellite communications through compact dish architectures. Rural enterprise managed services in the Great Plains rely on VSAT infrastructure where terrestrial alternatives fail.
- MEO:Medium-earth orbit systems balance latency and coverage density for specialized government and maritime applications.
Established revenue concentration sits with GEO. Steepest expansion trajectory belongs to LEO.
End User:
Defense procurement commands premium pricing through encrypted waveform requirements, while commercial segments compete on throughput economics.
- Defense:Federal agencies procure resilient tactical satellite communications through dedicated military frequency bands. NTIA priority access rules shape military-civilian spectrum sharing protocols that delay adjacent commercial activations.
- Enterprises:Agricultural cooperatives and extractive operations purchase managed satellite services for seasonal connectivity in fiber-unserved territories. Permian Basin energy operators and Corn Belt farming collectives are disintermediating systems integrators for direct operator relationships.
- Aerospace:Commercial airlines retrofit fleets with high-throughput satellite links to meet passenger broadband expectations and operational data requirements.
- Maritime:International Maritime Organization safety mandates accelerate fleet-wide terminal adoption for vessel tracking and crew welfare.
Margin pool concentration sits with Defense. Volume expansion is accelerating in Enterprises.
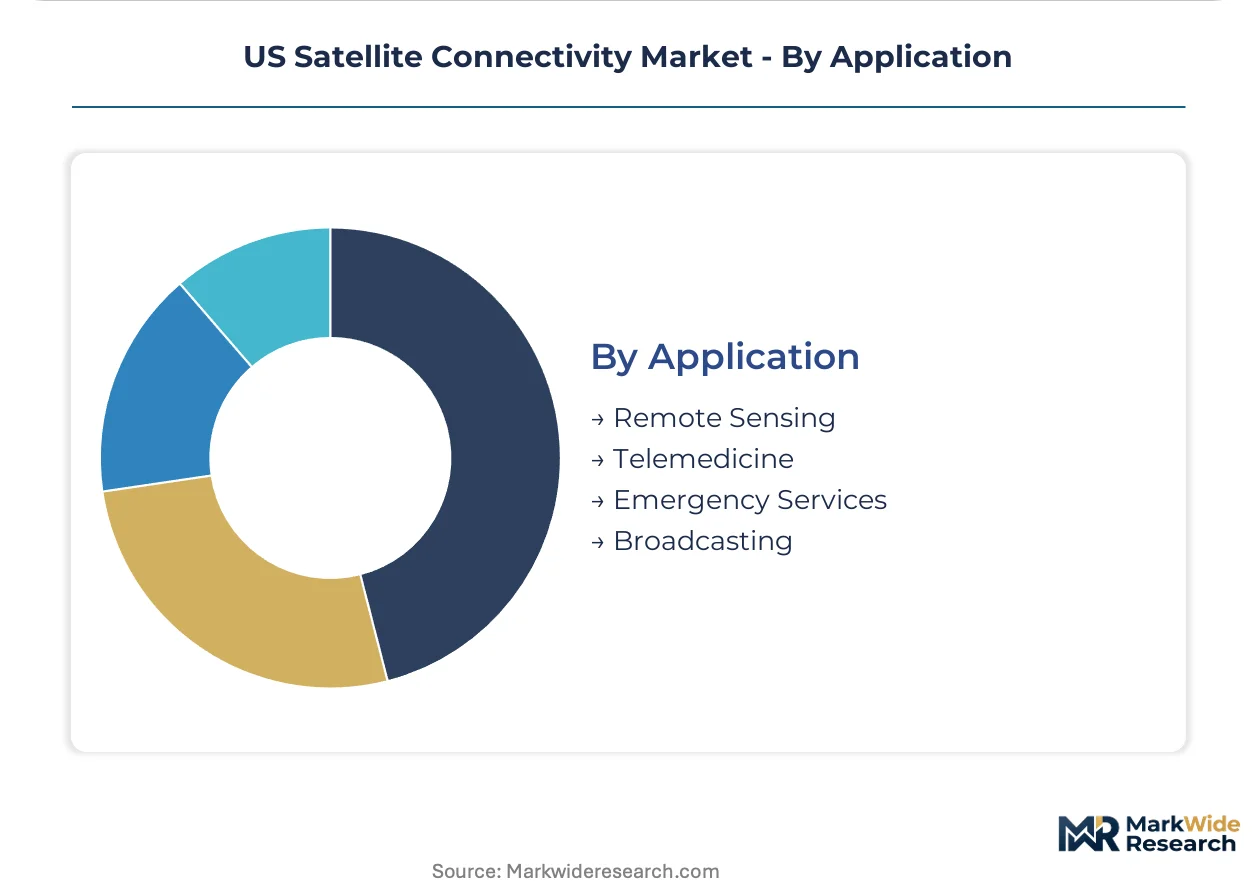
Application:
Use-case specificity determines terminal specifications, service level agreements, and integration complexity with legacy terrestrial networks.
- Remote Sensing:Earth observation data downlink requires high-bandwidth burst capacity and precision ground station coordination. Government weather and agricultural monitoring programs sustain dedicated procurement channels.
- Emergency Services:First responder communications demand hardened equipment and priority network access during terrestrial infrastructure failures. FEMA and state emergency management agencies specify interoperable satellite backup systems.
- Telemedicine:Rural healthcare connectivity enables specialist consultations and remote patient monitoring where broadband infrastructure is absent.
- Broadcasting:Video distribution to cable headends and direct-to-home receivers leverages geostationary capacity for one-to-many transmission economics.
Established infrastructure sits with Broadcasting. Emerging deployment is concentrating in Telemedicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's aerospace corridor anchors US satellite connectivity activity, with launch infrastructure and ground station networks clustering around Hawthorne and San Diego operations.
California
Defense procurement and commercial constellation development drive demand across the state's aerospace corridor. FCC spectrum reallocation reforms accelerate LEO deployment timelines for operators seeking priority market access. SpaceX's vertically integrated operations in Hawthorne and Viasat's specialized payload development in San Diego concentrate engineering talent and manufacturing capacity.
Texas
Energy sector connectivity needs and launch site expansion fuel satellite service adoption in the Permian Basin and Gulf Coast. FAA commercial launch licensing governs spacecraft deployment from Boca Chica and Vandenberg coordination. Houston's Johnson Space Center corridor hosts ground station networks serving maritime and aviation clients.
Colorado
Military satellite communications procurement and weather monitoring programs sustain demand across the Front Range urban corridor. NTIA federal frequency assignment rules shape military-civilian spectrum sharing protocols for operators near Denver. The state's aerospace cluster concentrates payload engineering and ground systems integration in Boulder and Colorado Springs.
Virginia
Intelligence community contracts and maritime terminal manufacturing anchor demand in the Northern Virginia technology corridor. FCC orbital slot coordination requirements govern constellation licensing for operators serving federal clients. The Dulles technology corridor hosts satellite operations centers and government systems integration facilities.
Florida
Commercial launch capacity expansion and cruise line connectivity contracts drive terminal deployment across the Space Coast and Miami-Dade. FAA reentry safety regulations constrain spacecraft landing zone approvals for operators launching from Cape Canaveral. Satellite ground station networks cluster around Patrick Space Force Base and Port Canaveral maritime corridors.
US Satellite Connectivity Market Competitive Landscape
Premium-margin players sit above commodity-margin players across defense and commercial service tiers. Vertically integrated constellation operators capture price-performance advantages through captive launch and terminal manufacturing. Three archetypes dominate: launch-to-service integrators, specialized military payload developers, and managed-service rural connectivity providers. Capacity expansion and strategic spectrum partnerships constitute the dominant competitive moves as operators race FCC deployment deadlines.
Within the launch-integrated tier, SpaceX anchors premium positioning through vertically controlled stack economics. Viasat and Hughes Network Systems occupy established positions across government and rural enterprise segments. These three exemplify how scale and specialization separate margin tiers in procurement cycles.
| Leading Market Players |
|---|
| SpaceX |
| Viasat |
| EchoStar Corporation |
| Iridium Communications |
| Gilat Satellite Networks |
| Inmarsat Global Limited |
| SES |
| Hughes Network Systems |
| Amazon |
| Others |
Pricing and Supply Chain Analysis
FCC spectrum sustainability mandates for orbital debris mitigation and frequency efficiency now gate qualified supplier access and premium-tier pricing authorization for constellation operators. Defense buyers with NTIA priority frequency assignments absorb pricing premiums for encrypted waveforms, while commercial rural enterprises face cost compression from commoditized Ku-band managed services.
Pricing Analysis
Throughput-based value pricing anchors tiered service structures across latency-sensitive and bulk-data segments. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade encrypted links from aviation managed services and rural consumer broadband. Price differentiation rests on certification tier (FCC Part 25 authorization versus experimental licenses) and volume commitment scale. Cost compression in standard-tier rural connectivity is intensifying because SpaceX's captive launch economics force legacy GEO operators into defensive bundling. Agricultural cooperatives in the Corn Belt exhibit highest price sensitivity; intelligence community contractors show least.
Supply Chain Analysis
Dual-sourcing requirements from defense integrators now mandate qualified second-source suppliers for phased array semiconductors and radiation-hardened payloads. Manufacturing concentrates in the United States, Taiwan, and Germany for RF components and ground terminal assemblies. Raw material dependencies center on gallium nitride substrates, rare earth magnets for reaction wheels, and specialized aluminum-lithium alloys. Single-source vulnerability in qualified semiconductor foundries creates supply chain risk for rapid constellation scaling. Distribution runs through direct operator relationships for enterprise buyers and retail channel partners for consumer terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where launch-to-service stack control determines margin capture. Players are pursuing upstream manufacturing leverage through captive semiconductor foundry partnerships and in-house payload integration.
For Market Incumbents: Anchor defense contract renewal rates through backward integration into encrypted waveform software and hardened terminal production. Threat from Amazon's Project Kuiper and emerging LEO constellations demands accelerated FCC deployment commitments to secure priority spectrum access. Capacity addition in Texas launch corridors and certification investment for military frequency bands constitute priority defensive moves. For New Entrants and Emerging Players: FCC streamlined small satellite licensing in the United States opens a window for rapid constellation iteration and orbital slot acquisition ahead of processing round deadlines. White-space targets concentrate in maritime IoT narrowband links and telemedicine rural connectivity where fiber backhaul remains uneconomical. Go-to-market leverage rests on bandwidth-on-demand portal purchasing for seasonal agricultural and energy sector buyers. For Investors and Strategic Acquirers: FAA commercial launch license approval velocity is the leading indicator that capacity expansion timelines will compress or extend constellation deployment economics. Long-term viability favors operators with demonstrated orbital slot coordination success and interoperable terminal ecosystems. Acquisition target archetype: specialized phased array semiconductor designers with defense qualification pathways. Signal to monitor: NTIA federal frequency assignment priority shifts affecting military-civilian spectrum sharing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| LEO Constellation Deployment Acceleration | FCC processing round reforms compress authorization timelines from 24 months to under 12 months for qualified operators. |
| Phased Array Terminal Manufacturing Scale-Up | Electronically steered antennas absorb subsystem margins and redirect value toward semiconductor foundries. |
| Defense Frequency Band Certification | NTIA priority access rules create sustained demand for encrypted waveform systems and hardened ground terminals. |
| Rural Enterprise Direct Channel Expansion | Bandwidth-on-demand portals disintermediate systems integrators for agricultural and energy sector buyers. |
| LEO-GEO Hybrid Service Platform Integration | Unified architectures converge low-latency constellations with geostationary video distribution economics. |
Research Methodology
Document review covered FCC licensing databases, FAA commercial launch records, and NTIA frequency assignment filings, complemented by interviews with constellation program managers, defense procurement officers, and ground systems engineers. Secondary validation drew from SEC filings of publicly traded operators, satellite industry association technical reports, and customs records for terminal hardware imports. Bottom-up subscriber and capacity modeling triangulated against top-down addressable market estimates for rural broadband and defense communications.
Cross-referencing historical deployment patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include orbital architecture (LEO, MEO, GEO), service tier (premium encrypted, standard managed, economy consumer), end-use vertical (defense, aviation, maritime, rural enterprise), and regional regulatory cluster (FCC Part 25, experimental, federal priority). CAGRs were derived from subscriber growth trajectories and average revenue per user trends across service categories. Industry-specific forecast inputs incorporated launch manifest density and phased array production yield rates.
The model assumes a particular technology adoption path; alternative pathways for optical inter-satellite links versus RF crosslinks would alter the outlook for latency performance and constellation capital intensity. Deviation in FAA launch licensing velocity or FCC spectrum auction timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Global LEO Satellite Market
Satellite
Commercial LEO Satellite Market
Satellite
Reconnaissance Satellite Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Satellite Data Service Market
Satellite
France Satellite Imagery Services Market
Satellite
China Satellite Imagery Services Market
Satellite
Asia-Pacific Military Satellite Market
Satellite
Mexico Satellite Connectivity Market
Satellite
Tactical Satellite Market
Satellite
Satellite Communication Equipment Market
Satellite
US Remote Sensing Technology Market