
 Airborne Laser Obstacle Avoidance Monitoring Systems Market | 2026-2036
Airborne Laser Obstacle Avoidance Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Laser Obstacle Avoidance Monitoring Systems Market Insights
Unmanned aerial vehicle demand from military operators is restructuring the airborne laser obstacle avoidance monitoring systems landscape. Lockheed Martin leverages its classified R&D pipeline to dominate directed-energy sensor integration for rotary-wing platforms. Raytheon Technologies anchors the defense contractor tier through captive LiDAR foundry partnerships with domestic semiconductor fabricators.
Airborne laser obstacle avoidance monitoring systems employ pulsed laser or frequency modulated continuous wave emitters paired with time-of-flight receivers to detect terrain, structures, or dynamic obstacles within a defined cone ahead of the aircraft, generating real-time range-azimuth-elevation point clouds for flight-path correction. Their primary purpose is to prevent controlled flight into terrain and wire strikes during low-altitude operations in degraded visual environments. Phase shift technology captures the fastest-growing margin pool as agricultural drones and air ambulances demand sub-centimeter accuracy at shorter standoff distances. Pulsed laser configurations occupy the mature military segment where maximum range and atmospheric penetration outweigh unit cost concerns.
The FAA mandates TCAS-independent obstacle detection for helicopter air ambulance operations under updated Part 135 provisions, while the EASA CS-29 certification framework imposes equivalent sensor redundancy standards across European Union member states. Military procurement channels require ISO 9001 and AS9100 quality traceability for LiDAR subassemblies, effectively filtering non-compliant vendors from defense-tier supply chains. Stakeholders must monitor how emerging JARUS SORA guidelines for specific category drones reshape sensor performance thresholds before committing to next-generation platform integrations.
Market Dynamics
Military procurement from defense ministries is restructuring fleet modernization priorities, while FAA Part 107 waiver expansion for beyond-visual-line-of-sight operations accelerates commercial certification pathways. This dual-track demand evolution is compressing development cycles across sensor manufacturers.
Growth Catalysts
- Army helicopter retrofit programs:The United States Army's fleet modernization mandates are generating sustained demand for directed-energy sensor integration on rotary-wing platforms. These programs prioritize terrain-following and wire-strike avoidance capabilities.
- FAA Part 135 provisions:Updated helicopter air ambulance regulations mandate TCAS-independent obstacle detection, creating immediate retrofit obligations for existing medical transport fleets. Compliance deadlines are accelerating procurement timelines.
- Phase shift LiDAR adoption:Agricultural drone operators and air ambulance services are demanding sub-centimeter accuracy at shorter standoff distances, expanding addressable applications beyond traditional military use cases.
Market Restraints
- Semiconductor foundry concentration:Captive LiDAR foundry partnerships with domestic semiconductor fabricators limit second-source options for defense-tier suppliers, creating single-point vulnerability in photonic component supply.
- Atmospheric attenuation physics:Pulsed laser configurations face inherent range limitations in dust, fog, and precipitation conditions, constraining operational envelopes in degraded visual environments where detection matters most.
- AS9100 certification barriers:ISO 9001 and AS9100 quality traceability requirements for military LiDAR subassemblies filter non-compliant vendors from defense procurement channels, reducing supplier base diversity.
Strategic Opportunities
- JARUS SORA guideline evolution:Emerging specific category drone standards are reshaping sensor performance thresholds, creating first-mover advantage for platforms designed ahead of finalized certification frameworks.
- NASA terrain-mapping contracts:Civilian scientific applications are opening parallel demand streams with less stringent security clearance requirements than defense procurement channels.
- Frequency modulated continuous wave convergence:Integration of FMCW emitters with time-of-flight receivers is enabling simultaneous long-range detection and short-range precision, collapsing dual-sensor architectures into single units.
Industry Challenges
- CS-29 certification timeline compression:EASA's sensor redundancy standards across European Union member states require parallel validation tracks, stretching engineering resources across multiple regulatory submission pathways.
- Directed-energy systems integration:Retrofitting legacy rotary-wing platforms with laser emitters demands airframe modification expertise that sits outside traditional avionics supplier capabilities, creating talent scarcity in structural-mechanical-optical convergence skills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Laser Obstacle Avoidance Monitoring Systems Market |
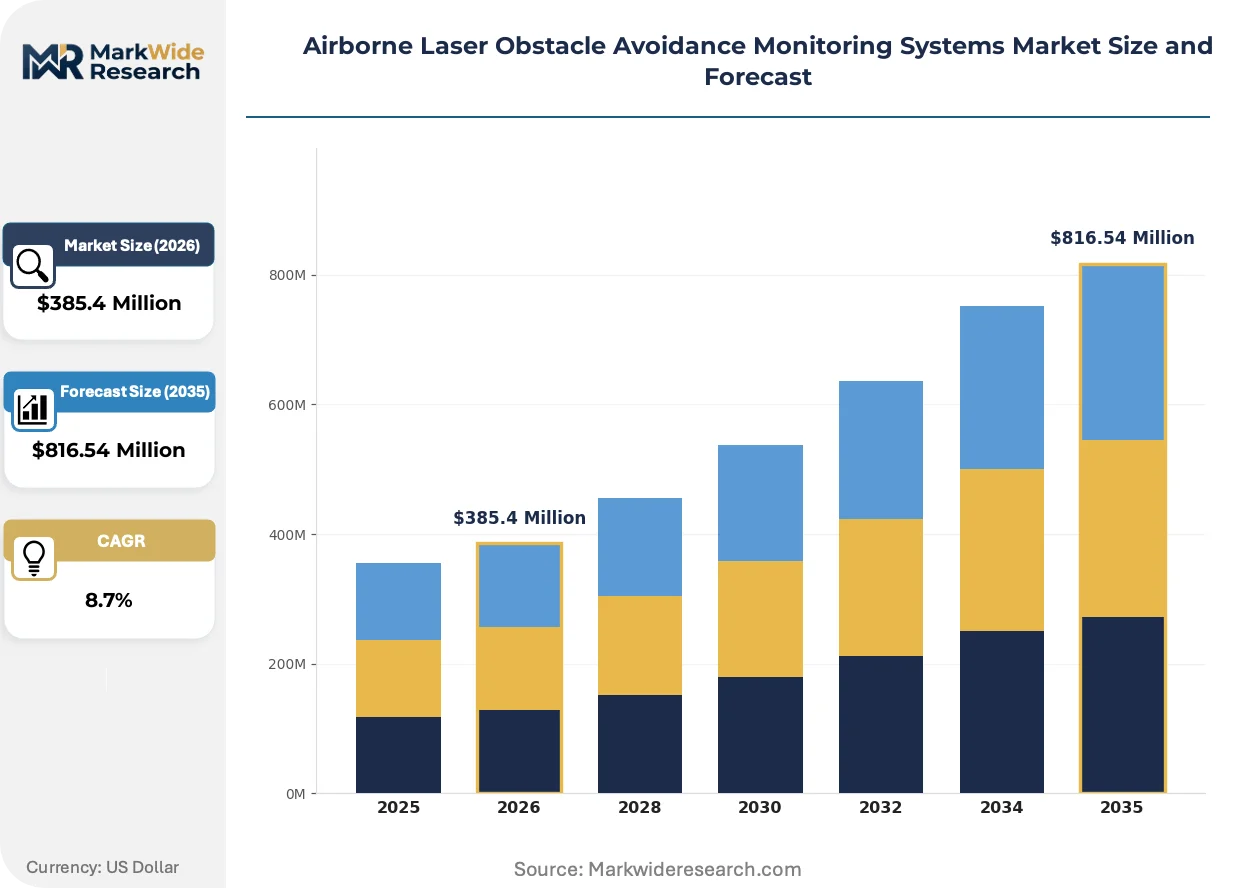
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LiDAR Sensors, Infrared Detectors, Radar Sensors, Ultrasonic Sensors, Optical Cameras Technology: Time-of-Flight, Phase Shift, Frequency Modulated Continuous Wave, Pulsed Laser, Structured Light Application: Unmanned Aerial Vehicles, Helicopters, Air Ambulances, Surveillance Aircraft, Agricultural Drones End User: Military Operators, Emergency Responders, Commercial Airlines, Surveying Companies, Research Institutions |
| Companies Covered | Raytheon Technologies, Lockheed Martin, Honeywell Aerospace, L3Harris Technologies, Northrop Grumman, Leonardo S.p.A., Thales Group, BAE Systems, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Laser Obstacle Avoidance Monitoring Systems Market Trends and Innovations
Electrification of sensor architectures is collapsing power and weight constraints that previously limited deployment on smaller unmanned platforms. This technical trajectory is unlocking airframes previously excluded from laser-based obstacle avoidance.
Solid-state beam steering is electrifying the transition from mechanical gimbal systems to optical phased arrays. Agricultural spraying drone manufacturers in California's Central Valley are adopting these units at three-year replacement cycles. The technology is compressing unit cost curves while expanding field-of-regard coverage beyond mechanical limits.
EASA's CS-29 certification framework revisions are mandating dual-channel sensor redundancy for helicopter operations above certain risk thresholds. Airframe OEMs must now source redundant LiDAR subassemblies from independent design lineages. The commercial air ambulance segment is responding by consolidating procurement around suppliers with pre-validated dual-source architectures.
Acquisition cycles for obstacle avoidance systems are compressing from seven-year platform lifecycles to three-year technology refresh intervals. Fleet operators in Texas and Florida are unbundling sensor upgrades from full avionics overhauls, treating laser detection as modular consumables rather than capital equipment. This pattern is most visible in emergency medical services where operational tempo justifies accelerated depreciation schedules.
Airborne Laser Obstacle Avoidance Monitoring Systems Market Segmentation
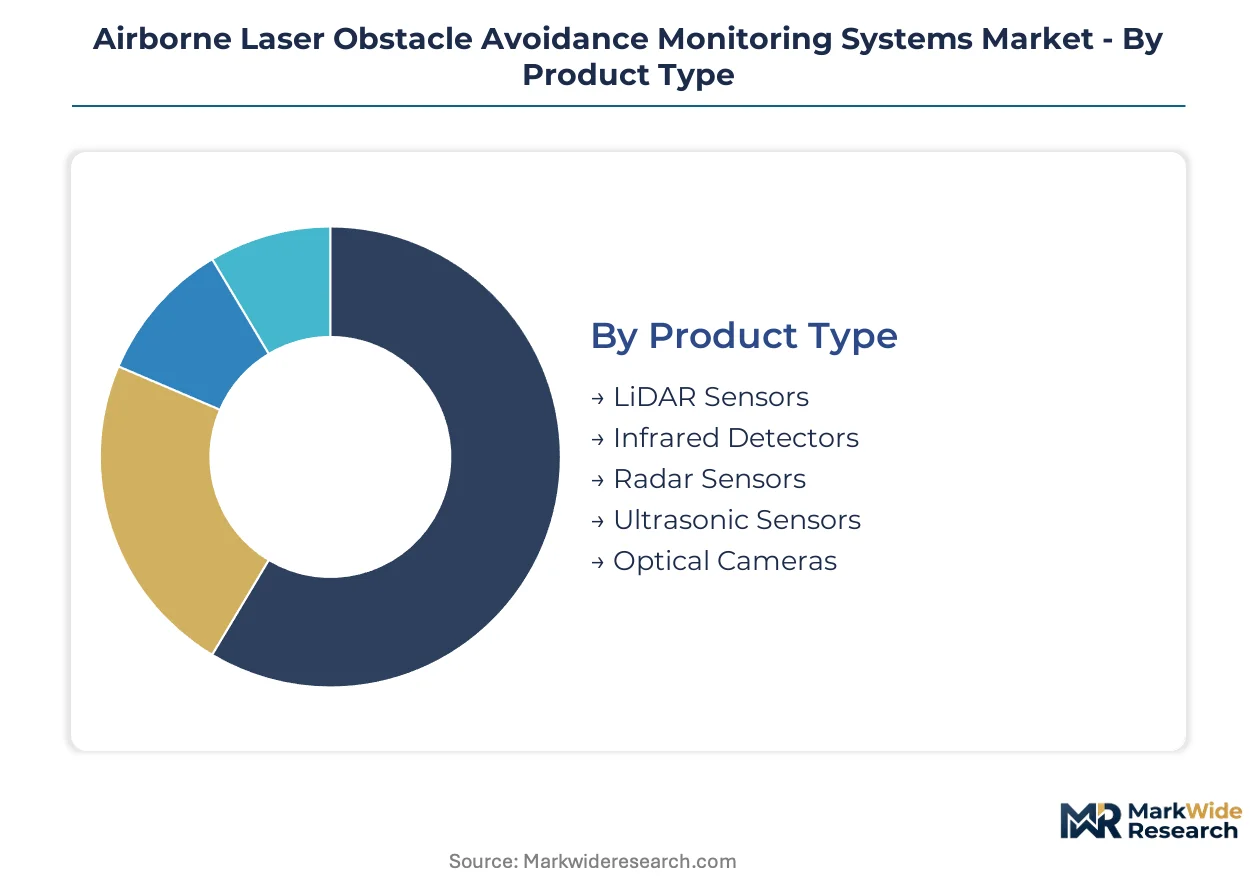
Segmentation in airborne laser obstacle avoidance systems reveals how technical specifications, operational envelopes, and procurement channels fragment demand. Each dimension carries distinct margin profiles and certification burdens that reshape supplier positioning.
Product Type:
Supply concentration in photonic component fabrication tilts competitive advantage toward vendors with captive semiconductor partnerships.
- LiDAR Sensors:Solid-state architectures with optical phased arrays are displacing mechanical gimbal systems. United States Army helicopter retrofit programs and NASA terrain-mapping contracts in California concentrate procurement, though atmospheric attenuation in dust and fog constrains operational envelopes.
- Infrared Detectors:Thermal imaging cores paired with laser rangefinders enable passive-active sensor fusion. Demand clusters in Texas and Florida emergency medical services where night operations in degraded visual environments mandate redundant detection modalities.
- Radar Sensors:Millimeter-wave arrays penetrate precipitation that blinds optical systems.
- Ultrasonic Sensors:Short-range proximity detection for agricultural drone obstacle avoidance in California's Central Valley.
- Optical Cameras:Machine-vision augmentation for classification tasks beyond pure ranging.
LiDAR Sensors absorb the bulk of installed capacity; Infrared Detectors are expanding most quickly.
Technology:
Cost tier differentiation separates military-grade long-range systems from commercial precision platforms.
- Time-of-Flight:Direct measurement of laser pulse return intervals dominates mature military applications. Pulsed configurations from defense contractors prioritize maximum range and atmospheric penetration over unit cost, with ISO 9001 and AS9100 traceability requirements filtering non-compliant vendors.
- Phase Shift:Interferometric measurement achieves sub-centimeter accuracy at shorter standoff distances. Agricultural drone operators and air ambulance services in the United States drive adoption where precision landing and wire-strike avoidance justify premium positioning.
- Frequency Modulated Continuous Wave:Simultaneous long-range detection and short-range precision in single units.
- Pulsed Laser:Maximum range configurations for terrain-following in degraded environments.
- Structured Light:Pattern projection for close-proximity obstacle mapping.
Pulsed Laser retains the largest installed base; Phase Shift shows the steepest expansion trajectory.
Application:
Volume concentration in unmanned platforms is compressing development cycles and accelerating refresh intervals.
- Unmanned Aerial Vehicles:Defense ministry procurement is restructuring fleet modernization priorities. FAA Part 107 waiver expansion for beyond-visual-line-of-sight operations accelerates commercial certification pathways, with JARUS SORA guidelines reshaping sensor performance thresholds.
- Helicopters:FAA Part 135 provisions mandate TCAS-independent obstacle detection for air ambulance operations. EASA CS-29 certification imposes equivalent sensor redundancy standards, stretching engineering resources across multiple regulatory submission pathways.
- Air Ambulances:Retrofit obligations for existing medical transport fleets with compressed compliance deadlines.
- Surveillance Aircraft:Extended-endurance platforms requiring low-power sensor architectures.
- Agricultural Drones:Three-year replacement cycles in California's Central Valley spraying operations.
Helicopters command the dominant share of defense procurement; Unmanned Aerial Vehicles are climbing the fastest.
End User:
Customer type fragmentation creates divergent certification pathways and security clearance requirements.
- Military Operators:Directed-energy sensor integration for rotary-wing platforms requires classified R&D pipelines and AS9100 quality traceability. Army fleet modernization mandates sustain demand for terrain-following and wire-strike avoidance capabilities.
- Emergency Responders:Air ambulance fleets in Texas and Florida unbundle sensor upgrades from full avionics overhauls. Operational tempo justifies accelerated depreciation schedules and modular consumable treatment of laser detection systems.
- Commercial Airlines:TCAS augmentation for low-altitude terminal operations.
- Surveying Companies:Civilian scientific applications with less stringent security clearance requirements than defense channels.
- Research Institutions:NASA terrain-mapping contracts opening parallel demand streams.
Military Operators account for the preponderance of contract value; Emergency Responders are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of airborne laser obstacle avoidance systems concentrates in defense-integrated manufacturing corridors, while consumption splits between military modernization programs and emerging commercial certification pathways. The United States absorbs the dominant procurement volume through Army helicopter retrofits and NASA scientific contracts. European demand follows EASA regulatory timelines, with Asia-Pacific markets developing domestic unmanned platform capabilities.
United States
Army helicopter fleet modernization and FAA Part 107 waiver expansion for beyond-visual-line-of-sight operations drive procurement intensity. The FAA mandates TCAS-independent obstacle detection under updated Part 135 provisions for air ambulance fleets. Texas and Florida emergency medical services clusters treat laser detection as modular consumables with three-year refresh cycles rather than capital equipment.
Germany
EASA CS-29 certification requirements for sensor redundancy shape helicopter operator procurement decisions across the European Union. The country's national aviation regulator enforces parallel validation tracks that stretch engineering resources. Bavaria's aerospace manufacturing corridor hosts system integrators serving both domestic rotorcraft OEMs and export defense contracts.
Israel
Directed-energy sensor development for tactical unmanned platforms benefits from concentrated defense R&D infrastructure. The country's national security establishment prioritizes terrain-following capabilities for low-altitude operations in degraded visual environments. Tel Aviv-area technology clusters bridge military specification systems with dual-use commercial adaptations.
Japan
METI industrial policy supports domestic LiDAR component fabrication for unmanned agricultural and infrastructure inspection platforms. The national aviation regulator maintains stringent certification frameworks that filter non-compliant vendors. Nagoya-area manufacturing networks supply precision optical subassemblies to regional drone OEMs.
Australia
Mining sector unmanned aerial vehicle adoption for remote site inspection creates demand for atmospheric-penetrating sensor configurations. The national civil aviation safety authority adapts JARUS SORA guidelines for specific category drone operations. Western Australia's resource extraction corridors host early deployments of combined LiDAR-radar obstacle detection architectures.
Airborne Laser Obstacle Avoidance Monitoring Systems Market Competitive Landscape
Top-tier vendors anchor defense-integrated supply chains, while specialized component fabricators occupy sub-tier positions. The market structure reflects AS9100 certification barriers that filter non-compliant suppliers from military procurement channels. Three archetypes dominate: captive semiconductor partnerships, airframe-integrated system houses, and modular sensor specialists. Competitive moves concentrate on dual-source architecture pre-validation and FMCW-pulsed laser convergence for collapsed dual-sensor designs.
Within the defense-prime tier, Raytheon Technologies and Lockheed Martin exemplify contrasting integration strategies. Raytheon Technologies occupies a position emphasizing captive foundry relationships with domestic semiconductor fabricators. Lockheed Martin represents the classified-R&D pipeline archetype for directed-energy rotary-wing applications. Honeywell Aerospace sits within the avionics-heritage segment, bridging commercial certification expertise with military specification compliance.
| Leading Market Players |
|---|
| Raytheon Technologies |
| Lockheed Martin |
| Honeywell Aerospace |
| L3Harris Technologies |
| Northrop Grumman |
| Leonardo S.p.A. |
| Thales Group |
| BAE Systems |
| Elbit Systems |
| Others |
Pricing and Supply Chain Analysis
AS9100 quality traceability mandates gate qualified supply access and premium-tier pricing power, filtering non-compliant vendors from defense procurement channels while concentrating margin capture among certified integrators serving Army helicopter retrofit programs and NASA terrain-mapping contracts.
Pricing Analysis
Cost-down pressure on military-grade LiDAR subassemblies accelerates because captive semiconductor foundry partnerships limit second-source competition and compress margin pools for non-integrated suppliers. Three-tier pricing structure across AS9100-certified defense tier, commercial aviation grade, and agricultural drone economy level separates buyers by certification burden and volume scale. Price differentiation hinges on ISO 9001 traceability depth and FAA Part 135 compliance validation, with emergency medical services in Texas and Florida exhibiting highest price sensitivity due to modular consumable treatment of sensor upgrades.
Supply Chain Analysis
Refurbishment flows for legacy mechanical gimbal systems create secondary supply channels as California agricultural operators cycle solid-state optical phased arrays at three-year intervals. Photonic component fabrication concentrates in the United States, Japan, and Germany, drawing from indium phosphide wafers, precision aspheric optics, and rare-earth laser crystals. Single-source vulnerability in domestic semiconductor foundry partnerships threatens defense-tier suppliers, while distribution runs through airframe-integrated system houses and modular sensor specialists serving parallel military and commercial certification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
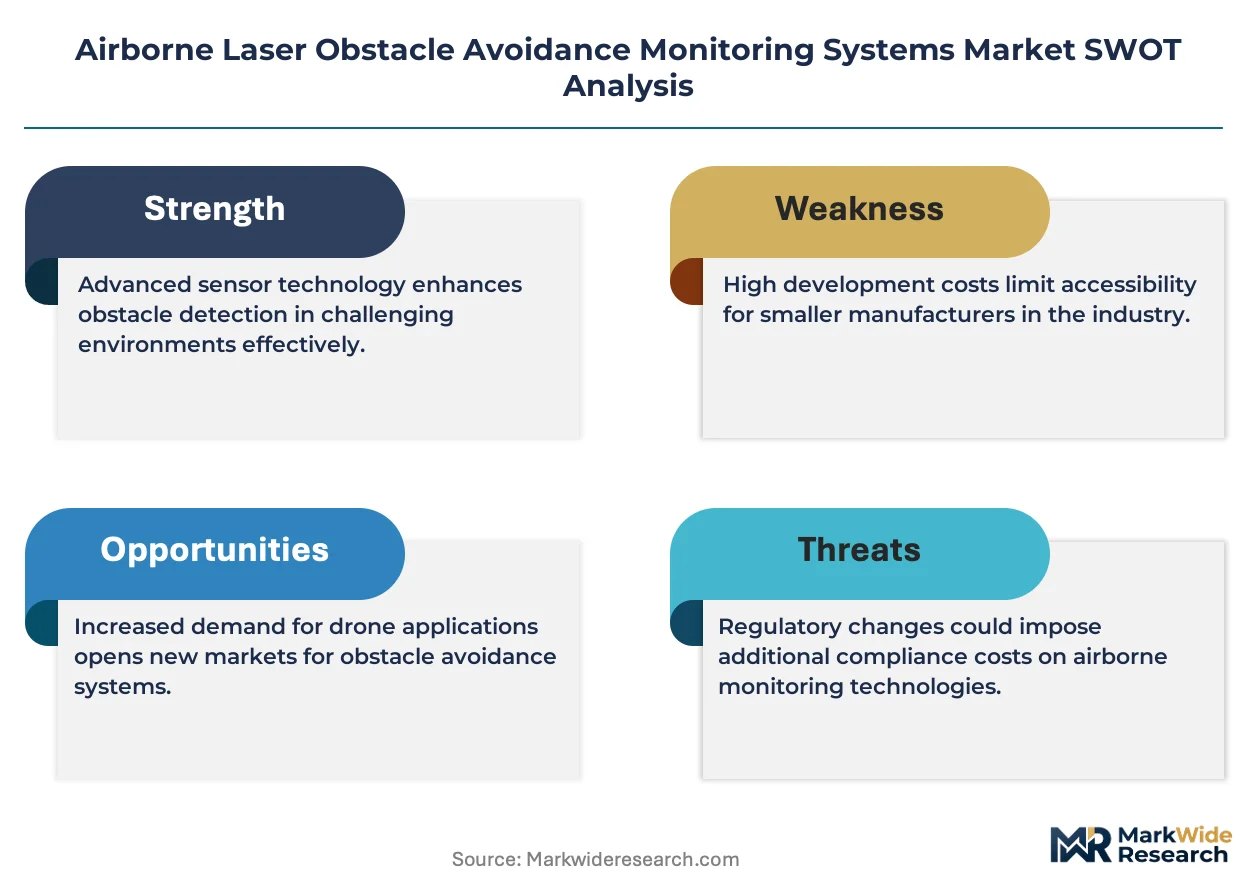
This market consolidates around vendors with pre-validated dual-source architectures, as EASA CS-29 sensor redundancy standards and FAA Part 135 retrofit deadlines force weaker players out of defense and air ambulance procurement channels.
For Market Incumbents: Acquire captive LiDAR foundry capacity or secure exclusive semiconductor fabricator partnerships to defend against single-point vulnerability in photonic component supply. Consolidate procurement relationships with Army helicopter fleet modernization programs and NASA terrain-mapping contractors before compliance deadlines accelerate. Deepen backward integration into precision optical subassembly production to capture margin pools currently leaking to Nagoya-area manufacturing networks. For New Entrants and Emerging Players: Capture JARUS SORA guideline evolution whitespace by designing specific category drone platforms ahead of finalized certification frameworks, securing first-mover advantage in European and Australian unmanned markets. Target agricultural drone operators in California's Central Valley with solid-state optical phased array units priced for three-year replacement cycles, bypassing defense-tier AS9100 barriers entirely. For Investors and Strategic Acquirers: Frequency modulated continuous wave technology convergence announcements from established defense primes signal the leading indicator that dual-sensor architectures will collapse into single-unit designs, reshaping competitive economics. Position for five-to-ten year viability by acquiring modular sensor specialists with validated FMCW-pulsed laser integration pipelines and existing FAA Part 107 waiver relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Foundry Partnership | Secures photonic component supply for Army helicopter retrofit programs against single-source risk. |
| FMCW-Pulsed Laser Convergence R&D | Collapses dual-sensor architectures into single units for simultaneous long-range and precision detection. |
| Dual-Source Architecture Pre-Validation | Meets EASA CS-29 redundancy mandates before competitors complete parallel validation tracks. |
| JARUS SORA-Aligned Platform Design | Captures specific category drone certification pathways ahead of finalized European guidelines. |
| Modular Sensor Consumable Positioning | Aligns with Texas and Florida emergency medical services three-year refresh cycle preferences. |
Research Methodology
Document review covered FAA Part 107 waiver databases, EASA CS-29 certification filings, and Army modernization procurement records, complemented by interviews with rotary-wing platform engineers, LiDAR subsystem procurement leads at defense primes, air ambulance fleet managers, and agricultural drone operators in California's Central Valley. Secondary validation drew from NASA contract award announcements, JARUS SORA guideline drafts, and semiconductor trade flow data. Bottom-up sensor shipment estimates triangulated against top-down defense budget appropriations and commercial aviation retrofit obligations.
Segment-level value outputs across the projection horizon reflect modeled deployment by product type, technology configuration, application platform, and end-user archetype, with CAGRs derived from fitted adoption curves calibrated to regulatory deadline impacts and fleet modernization cycle timing. Forecast inputs incorporated atmospheric attenuation physics constraints on operational envelopes, solid-state beam steering cost compression trajectories, and dual-channel redundancy penetration rates in helicopter air ambulance retrofit programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to JARUS SORA finalization timelines, semiconductor foundry capacity allocation shifts, and EASA-FAA regulatory harmonization progress. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Through the Wall Radar Market
Communication Navigation & Surveillance
3D Radar Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Over the Horizon Radar Market
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
UWB Anchor Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Military Antenna Market
Communication Navigation & Surveillance
Tactical Radio Market