
 Weapon Locating Radar Market | 2026-2036
Weapon Locating Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Weapon Locating Radar Market Insights
Defense procurement channels across NATO allies is tilting toward sole-source and directed-buy contracts for mission-critical radar systems. RTX Corporation leverages its Gallium Nitride transmitter supply chain to sustain cost advantages in active electronically scanned arrays. Lockheed Martin Corporation anchors the US Army's Q-53 radar program through multi-year production contracts. Thales Group competes aggressively in European tenders with its Ground Master family, differentiating through dual-use air-defense and weapon-locating architectures.
A weapon locating radar detects and tracks hostile artillery, mortar, and rocket fire by analyzing projectile trajectories to calculate origin points, typically operating in X-band or C-band frequencies with detection ranges exceeding 50 kilometers against mortar rounds and 100 kilometers against artillery shells. Counter-battery radar systems dominate procurement budgets due to their direct role in force protection and counterfire missions, while phased array configurations command premium positioning as militaries replace legacy mechanically scanned platforms. Firefinder radars retain significant installed bases but face declining new orders as customers prioritize multi-mission flexibility over single-purpose hardware.
US Army Cyber Command and the Defense Information Systems Agency impose stringent encryption and anti-jamming standards that filter vendor eligibility for Pentagon contracts, while NATO's STANAG 4609 requirements for intelligence data interoperability shape product development roadmaps across member nations. The EU's proposed Defence Industrial Readiness Board may introduce consolidated procurement frameworks that alter competitive access for non-European suppliers. Stakeholders must monitor how export control harmonization between the US International Traffic in Arms Regulations and emerging EU defense procurement rules affects cross-border technology transfer timelines.
Market Dynamics
Active electronically scanned array architectures are collapsing cost differentials between counter-battery and air-defense radar platforms, forcing procurement offices across NATO defense ministries to consolidate multi-mission specifications into single-source contracts.
Growth Catalysts
- STANAG 4609 interoperability mandates:NATO standardization for intelligence data exchange compels member states to replace legacy analog radars with digital beamforming systems, creating synchronized replacement cycles across Poland, Germany, and the Baltic states.
- Gallium Nitride transmitter adoption:Wide-bandgap semiconductor technology reduces power consumption and cooling requirements, enabling forward-deployable configurations that expeditionary forces require for rapid emplacement.
- Artillery threat intensification:Russian rocket and mortar barrages in Eastern Ukraine have elevated counter-battery radar to highest-priority procurement categories within Baltic and Polish defense budgets.
Market Restraints
- Gallium Nitride substrate supply concentration:Single-source dependency on Japanese and US substrate manufacturers creates vulnerability to export licensing delays and geopolitical supply interruptions.
- US International Traffic in Arms Regulations:ITAR classification of AESA transmitter modules restricts technology transfer to non-US assembly facilities, fragmenting European supply chain localization efforts.
- Mechanical radar installed base inertia:Legacy Firefinder systems in US and Turkish inventories absorb maintenance budgets that procurement offices cannot redirect toward replacement programs.
Strategic Opportunities
- Dual-use air-defense convergence:Ground Master-class architectures that merge weapon-locating with low-altitude air surveillance open procurement channels to civil defense and border security agencies previously outside military sales pipelines.
- EU Defence Industrial Readiness Board consolidation:Proposed framework for pooled procurement across member states may create preferential access for European radar integrators meeting local content thresholds.
- Cybersecurity certification premiums:US Army Cyber Command encryption mandates position vendors with pre-certified sensor networks to capture sole-source awards bypassing competitive tender processes.
Industry Challenges
- Phased array thermal management engineering:Dense transmitter packaging in mobile configurations demands scarce expertise in compact liquid cooling and heat sink design that defense contractors struggle to staff.
- Legacy analog-digital integration:Field commanders require seamless data fusion between new AESA radars and existing command-and-control networks running proprietary protocols from mechanically scanned predecessors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weapon Locating Radar Market |
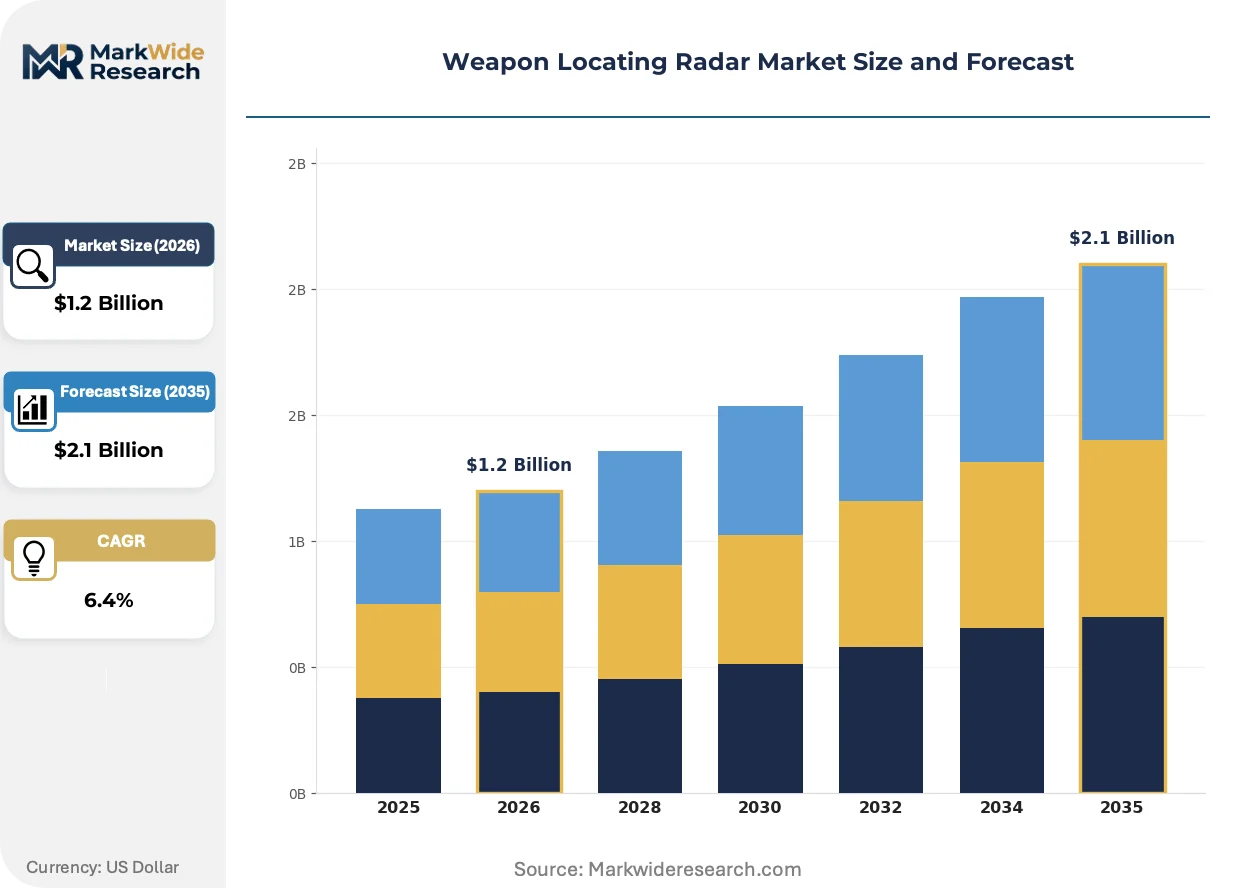
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Counter-battery Radars, Firefinder Radars, Phased Array Radars, Monopulse Radars, Doppler Radars Technology: Pulse-Doppler, Continuous Wave, Frequency Modulated Continuous Wave, Moving Target Indication, Synthetic Aperture Radar Application: Target Acquisition, Mortar Detection, Artillery Tracking, Missile Defense, Troop Movement Surveillance End User: Defense Forces, Border Security Agencies, Coast Guard, Defense Contractors, Intelligence Units |
| Companies Covered | RTX Corporation, Lockheed Martin Corporation, Thales Group, Saab AB, Bharat Electronics Limited, BAE Systems, Northrop Grumman Corporation, Israel Aerospace Industries, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weapon Locating Radar Market Trends and Innovations
Digital beamforming algorithms are compressing hardware differentiation between radar categories, while cybersecurity hardening and procurement consolidation reshape how defense ministries evaluate vendor proposals.
Gallium Nitride monolithic microwave integrated circuits are collapsing the performance gap between solid-state and vacuum tube transmitters. European and US prime contractors now specify GaN MMICs for all new AESA programs, eliminating the power-density advantage that traveling wave tubes previously held in long-range detection. This compression enables single chassis designs to span both counter-battery and air surveillance missions, reducing platform variety that logistics chains must support.
US Department of Defense cybersecurity mandates are filtering vendor eligibility through pre-qualification frameworks. The Defense Information Systems Agency now requires FIPS 140-3 encryption certification and anti-jam waveform diversity as threshold capabilities for Pentagon sensor network contracts. Vendors without pre-existing certified architectures face eighteen-month compliance timelines that exclude them from urgent operational requirements.
Multi-year performance-based sustainment contracts are displacing transactional spare parts purchasing in NATO procurement channels. Defense ministries in Poland and Germany now negotiate availability guarantees rather than component orders, transferring operational risk to contractors. This reconfiguration concentrates aftermarket revenue with original equipment manufacturers possessing integrated logistics databases and forward repair depots.
Weapon Locating Radar Market Segmentation
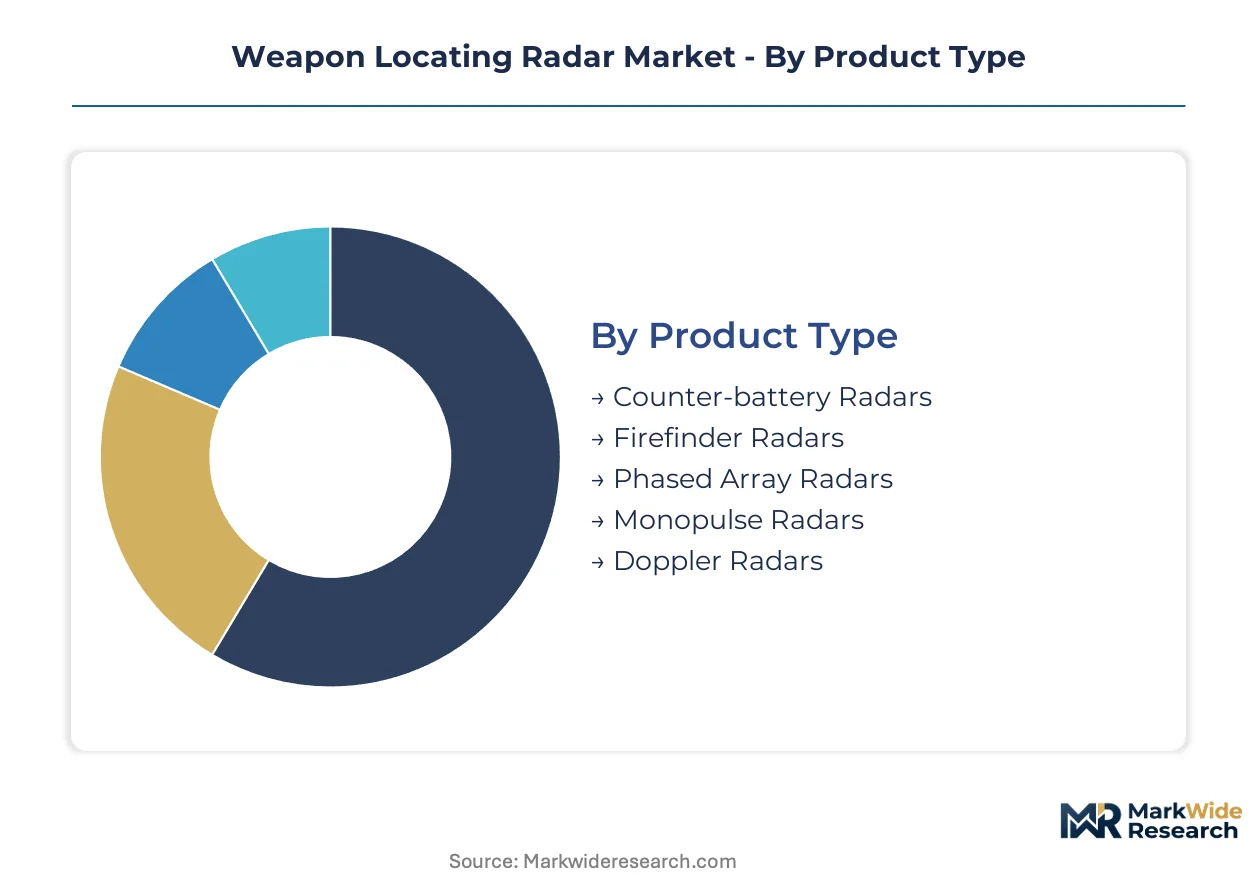
Weapon locating radar procurement splits across mission profiles, transmitter architectures, and operator categories that dictate divergent specification requirements. Defense ministries structure competitive tenders around these dimensions, creating distinct vendor qualification pathways and pricing bands for each segment cluster.
Product Type:
Cost tier stratification separates legacy mechanical systems from solid-state active arrays with divergent sustainment economics and deployment mobility.
- Counter-battery Radars:Active electronically scanned arrays with Gallium Nitride transmitters calculate hostile artillery origin points through trajectory backtracking. Polish and Baltic defense ministries prioritize these for forward-deployed NATO infrastructure, driven by Russian rocket barrage threats in adjacent theaters.
- Phased Array Radars:Electronically steered beams eliminate mechanical rotation latency, enabling simultaneous multi-target tracking. German procurement offices specify these for dual-use air-defense convergence, collapsing separate counter-battery and low-altitude surveillance contracts into single-source awards.
- Firefinder Radars:Mechanically scanned legacy platforms retain substantial US and Turkish installed bases.
- Monopulse Radars:Single-pulse angle measurement architectures serve precision targeting niches.
- Doppler Radars:Velocity-based discrimination systems address specific mortar detection requirements.
Counter-battery configurations command the established base. The steepest expansion runs through phased array platforms.
Technology:
Application demands across target acquisition, mortar detection, and artillery tracking shape waveform selection and processing architecture priorities.
- Pulse-Doppler:Range-velocity measurement through coherent pulse trains enables clutter rejection in contested electromagnetic environments. Defense forces in Eastern Europe specify these for artillery tracking missions where terrain masking complicates line-of-sight geometry.
- Frequency Modulated Continuous Wave:Uninterrupted transmission delivers low probability of intercept signatures critical for survivable forward deployment. Border security agencies in Germany adopt these for troop movement surveillance along extended frontages requiring minimal power signatures.
- Continuous Wave:Sustained carrier transmission supports specific missile defense cueing applications.
- Moving Target Indication:Doppler filtering architectures address ground surveillance requirements.
- Synthetic Aperture Radar:Image-forming processing supports intelligence unit mapping missions.
Pulse-Doppler systems anchor current procurement volumes. Frequency modulated continuous wave architectures are climbing the fastest as expeditionary forces prioritize signature management.
Application:
Customer type differentiation separates military combat formations from paramilitary security services with divergent detection range and mobility specifications.
- Target Acquisition:Precision coordinate generation for counterfire missions demands sub-50 meter circular error probable performance. Defense forces concentrate demand here, with US Army Cyber Command mandating FIPS 140-3 encryption for networked sensor participation.
- Mortar Detection:Short-range, high-angle trajectory analysis requires rapid beam steering against fleeting exposure windows. Baltic states prioritize these for point defense of forward operating bases facing rocket and mortar threats.
- Artillery Tracking:Long-range shell trajectory calculation supports counter-battery fire missions.
- Missile Defense:Early warning cueing for air defense batteries represents integrated architecture demand.
- Troop Movement Surveillance:Ground moving target indication serves border security agency requirements.
Target acquisition commands the established base. Mortar detection is gaining share fastest amid Eastern European threat escalation.
End User:
Volume concentration varies across operator categories with procurement authority resting in defense ministries, interior ministries, or intelligence services with distinct budget cycles.
- Defense Forces:Military procurement offices execute multi-year production contracts with availability-based sustainment terms. NATO member state defense ministries in Poland and Germany consolidate counter-battery and air-defense requirements into unified specifications.
- Border Security Agencies:Paramilitary organizations with interior ministry funding pursue dual-use radar platforms for civil defense applications. These operators in Germany specify Ground Master-class architectures that merge military and border surveillance missions.
- Coast Guard:Maritime perimeter security commands specialized coastal surveillance variants.
- Defense Contractors:Prime integrators acquire subsystems for platform integration programs.
- Intelligence Units:Technical collection agencies specify specialized signal exploitation configurations.
Defense forces command the established base. Border security agencies represent the steepest expansion trajectory as dual-use procurement channels open.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Polish procurement channels where NATO forward-deployment urgency overrides cost sensitivity, while Turkish and Indian defense budgets operate under tighter fiscal constraints that compress vendor margins.
United States
US Army Cyber Command drives AESA radar demand through FIPS 140-3 encryption mandates that filter vendor eligibility for Pentagon sensor networks. The Defense Information Systems Agency imposes eighteen-month compliance timelines that exclude uncertified architectures from urgent operational requirements. Huntsville, Alabama anchors prime contractor engineering clusters where RTX Corporation and Lockheed Martin Corporation sustain multi-year production relationships.
Germany
German defense procurement offices consolidate counter-battery and air-defense requirements into unified specifications that favor dual-use Ground Master-class architectures. The EU's proposed Defence Industrial Readiness Board may introduce consolidated procurement frameworks altering competitive access for non-European suppliers. Bavaria hosts Thales Group engineering facilities where Gallium Nitride transmitter integration advances mobile platform configurations.
Poland
Polish defense ministries prioritize forward-deployed NATO infrastructure replacement cycles amid Russian artillery threat escalation in adjacent theaters. NATO STANAG 4609 interoperability mandates compel digital beamforming system adoption that synchronizes procurement with Baltic state partners. Warsaw defense procurement channels tilt toward sole-source awards for mission-critical radar systems with pre-certified cybersecurity architectures.
Turkey
Turkish defense budgets absorb maintenance costs for legacy Firefinder radar installed bases that procurement offices cannot redirect toward replacement programs. The country's national defense procurement agency balances NATO interoperability requirements with indigenous industrial development priorities. Ankara hosts mechanical radar sustainment clusters where legacy platform expertise delays AESA transition timelines.
India
Indian defense procurement operates through capital acquisition frameworks that emphasize technology transfer and local assembly requirements for foreign radar systems. The country's national defense regulator evaluates counter-battery platforms against Himalayan terrain masking challenges and extended line-of-sight geometries. Bangalore anchors Bharat Electronics Limited manufacturing clusters where phased array subsystem integration advances domestic capability.
Weapon Locating Radar Market Competitive Landscape
US defense primes and European radar integrators split the market along procurement channel boundaries defined by ITAR classification and NATO interoperability mandates. The vendor base concentrates around active electronically scanned array technology leadership and pre-certified cybersecurity architectures. Two strategic archetypes dominate: Gallium Nitride supply chain controllers and dual-use air-defense convergence specialists. Competitive moves center on multi-year performance-based sustainment contracts and sole-source directed-buy awards bypassing competitive tenders.
Within the US prime contractor tier, RTX Corporation and Lockheed Martin Corporation anchor Pentagon procurement relationships through multi-year production contracts. Thales Group occupies a position exemplifying European dual-use convergence strategies that merge weapon-locating with low-altitude air surveillance missions. These three entities represent the archetype boundary between ITAR-restricted AESA transmitter supply chains and NATO STANAG 4609-certified digital beamforming architectures.
| Leading Market Players |
|---|
| RTX Corporation |
| Lockheed Martin Corporation |
| Thales Group |
| Saab AB |
| Bharat Electronics Limited |
| BAE Systems |
| Northrop Grumman Corporation |
| Israel Aerospace Industries |
| Leonardo S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific semiconductor freight corridors from Yokohama to Long Beach transmit Gallium Nitride substrate cost volatility directly into AESA radar module pricing, concentrating margin pressure on European integrators lacking backward integration into wide-bandgap semiconductor supply chains while rewarding Japanese and US substrate controllers with persistent premium capture.
Pricing Analysis
Configured-to-order AESA radar systems command substantial premiums over standard Firefinder replacements, with Polish and Baltic defense ministries absorbing customization costs for STANAG 4609-certified digital beamforming architectures while Turkish maintenance budgets face severe price compression on legacy mechanical platform spares. Three-tier pricing structure across expeditionary-configured, fixed-site, and sustainment-only tiers separates NATO urgent operational requirements from non-priority replacement cycles. Cost compression in standard-tier mechanically scanned radars is intensifying because procurement offices cannot redirect maintenance budgets toward AESA transitions. Border security agencies exhibit highest price sensitivity, lacking military-grade budget flexibility for multi-mission convergence platforms.
Supply Chain Analysis
Tariff exposure between Japanese substrate manufacturers and European assembly facilities dominates supply chain risk calculus for GaN MMIC-dependent AESA programs. Wide-bandgap semiconductor feedstock concentrates in Japan and the United States, with Taiwanese foundry capacity serving secondary processing. Raw material dependencies span high-purity silicon carbide substrates, gold wire bonding materials, and specialized ceramic packaging. Single-source vulnerability in Japanese GaN wafer supply creates procurement timeline uncertainty for non-US prime contractors. Distribution runs through defense ministry sole-source contracting channels that bypass competitive tender processes for pre-certified cybersecurity architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Weapon locating radar procurement is recovering from post-Cold War troughs as Russian artillery barrages in Eastern Ukraine trigger synchronized NATO replacement cycles across forward-deployed infrastructure.
For Market Incumbents: Entrench Gallium Nitride transmitter supply chain control through captive substrate sourcing or long-term offtake agreements with Japanese manufacturers, insulating against export licensing delays that fragment European localization efforts. Consolidate aftermarket revenue through multi-year availability-based sustainment contracts that transfer operational risk to prime contractors possessing integrated logistics databases. Cybersecurity certification investment represents the critical defensive lever against uncertified competitors facing eighteen-month DISA compliance timelines. For New Entrants and Emerging Players: Indian defense procurement channels offer the most penetrable white-space target, with technology transfer mandates and local assembly requirements creating entry pathways for phased array subsystem integrators. Baltic state mortar detection point defense represents a second viable beachhead, with smaller contract values that evade incumbent sole-source dominance. Pursue partnership-based go-to-market positioning with Bharat Electronics Limited or comparable national champions to satisfy domestic content thresholds. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified aerospace parents seeking to monetize non-core radar divisions lacking scale for multi-year Pentagon sustainment contract qualification. Long-term viability centers on dual-use air-defense convergence capabilities that expand addressable market beyond military procurement into civil defense and border security agencies. Watch for EU Defence Industrial Readiness Board consolidation announcements as the inflection signal for preferential European supplier access.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Supply Chain Backward Integration | Captive substrate sourcing insulates RTX Corporation and Lockheed Martin Corporation from Japanese export licensing volatility. |
| Dual-Use Architecture Convergence | Thales Group Ground Master-class platforms merge counter-battery and air surveillance to access border security procurement channels. |
| Cybersecurity Pre-Certification Investment | FIPS 140-3 encryption mandates position pre-certified vendors for sole-source Pentagon awards bypassing competitive tender. |
| Performance-Based Sustainment Contracts | Availability guarantees transfer operational risk to OEMs with integrated logistics databases in Poland and Germany. |
| EU Local Content Threshold Compliance | Defence Industrial Readiness Board frameworks may create preferential access for European integrators meeting assembly requirements. |
Research Methodology
Initial hypotheses were tested against primary input from radar program managers at NATO defense ministries, GaN substrate procurement leads at Japanese manufacturers, AESA engineering directors at US primes, and sustainment contract officers at Polish and German procurement offices, then refined through secondary validation against DISA cybersecurity mandate documentation, NATO STANAG 4609 specification releases, and customs records tracking wide-bandgap semiconductor trade flows, with bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with procurement volume projections segmented by product type across counter-battery, phased array, and legacy mechanical configurations, by technology across pulse-Doppler and frequency modulated continuous wave architectures, by application across target acquisition and mortar detection missions, and by end user across defense forces and border security agencies. CAGRs were derived from replacement cycle synchronization effects and threat escalation intensity modeling, with Gallium Nitride adoption curves and STANAG 4609 compliance timelines serving as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed radar integrators or accelerated EU defense procurement consolidation would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Infrared Search and Track (IRST) System Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Spain Satellite Communications Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market
Communication Navigation & Surveillance
GNSS Smart Antenna Market
Communication Navigation & Surveillance
Global Military Communications Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Military GNSS Anti-Jamming Systems Market
Communication Navigation & Surveillance
UK Autonomous Navigation Market
Communication Navigation & Surveillance
Russia Autonomous Navigation Market