
 Command Fuzes Market | 2026-2036
Command Fuzes Market Size, Share, and Industry Trends Forecast 2026-2036
Command Fuzes Market Insights
Multi-source procurement for critical electronic components is consolidating around a narrower tier of qualified suppliers. L3 Technologies leverages its vertically integrated fuze electronics foundry to sustain delivery schedules for U.S. Army 155mm artillery programs. Northrop Grumman competes through advanced proximity sensing architectures, while JUNGHANS Microtec GmbH anchors European supply with German and allied nation mortar fuzing contracts.
A command fuze is an ordnance initiator that receives and executes firing commands from external fire control systems, typically incorporating microprocessor-based safing and arming logic with redundant firing trains and environmental sensing thresholds. Its primary purpose is to enable variable burst timing against concealed or moving targets without manual fuze setting at the gun line. Electronic and programmable technologies now lead investment flows, as electromechanical platforms face obsolescence in Western arsenals and optical proximity methods remain confined to specialized air defense applications. Point detonating and multi-option types capture the dominant share of current procurement, though height-of-burst configurations for area-effect munitions represent the fastest-growing demand pool.
NATO STANAG 4187 and U.S. DoD insensitive munitions policy shape product qualification pathways, while the U.S. Department of State ITAR regime controls cross-border technology transfer for electronic arming mechanisms. Germany's national explosive safety regulator enforces parallel BGV B5 workplace standards that constrain manufacturing process choices for European suppliers. Stakeholders must monitor evolving cybersecurity mandates for networked fuzing systems as artillery digitization accelerates.
Market Dynamics
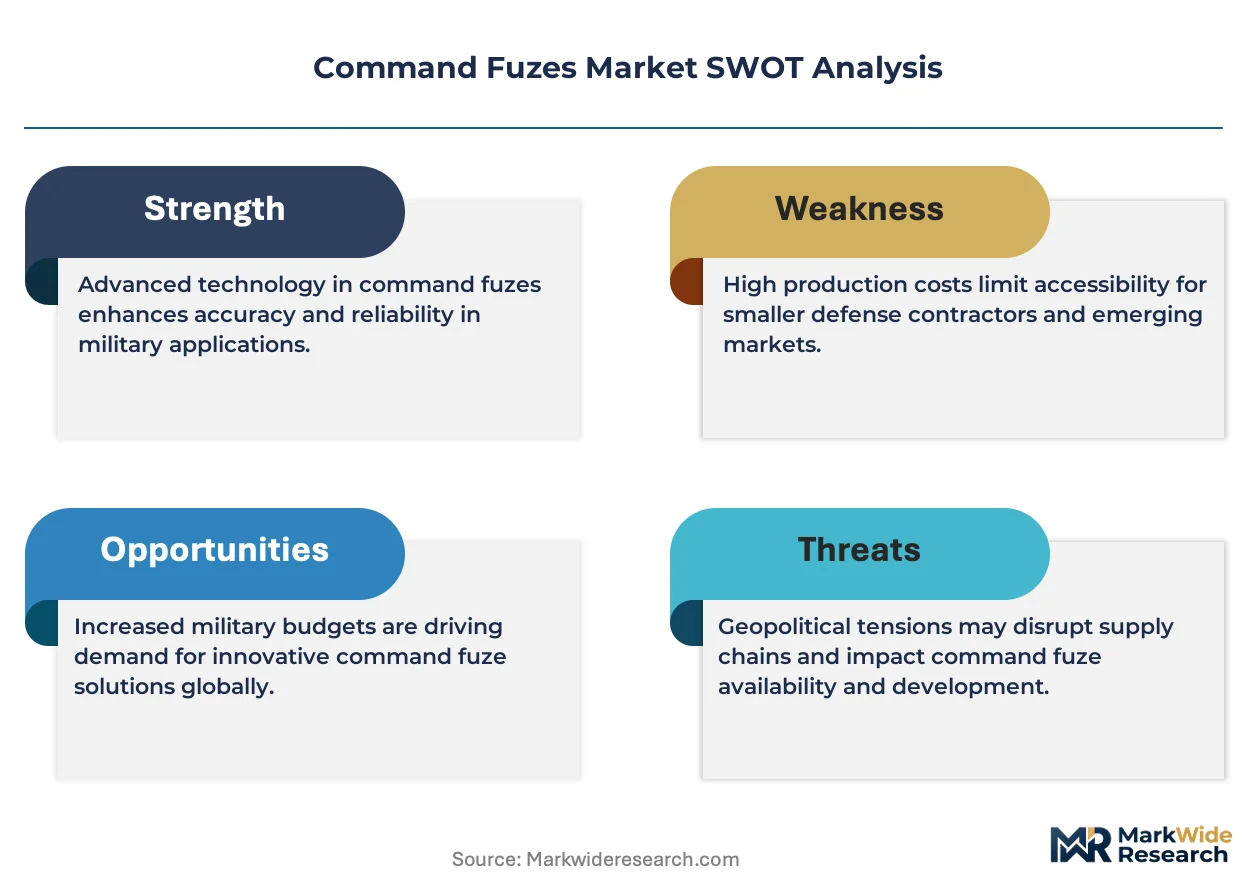
Programmable electronic fuzing architectures are displacing electromechanical platforms across NATO artillery modernization programs, compressing supplier qualification timelines while tightening safety certification requirements under evolving insensitive munitions policies.
Growth Catalysts
- Precision Fire Control Integration:U.S. Army Futures Command mandates networked fuzing compatibility with next-generation artillery digitization, pulling demand for microprocessor-based command initiators.
- NATO STANAG 4187 Modernization:Allied standardization on interoperable electronic safety and arming mechanisms accelerates replacement cycles for legacy mortar and artillery fuzes across member arsenals.
- Insensitive Munitions Policy:The U.S. Department of Defense directive on reduced explosive sensitivity in stored munitions forces redesign of fuze energetic trains and housing materials.
Market Restraints
- Semiconductor Supply Concentration:Qualified radiation-hardened microcontrollers for arming logic concentrate among a handful of U.S. and European foundries, creating single-source vulnerability.
- ITAR Export Controls:The U.S. Department of State regime restricts cross-border transfer of electronic arming mechanisms, fragmenting supplier access for non-U.S. integrators.
- Electromechanical Obsolescence Costs:Maintaining legacy production lines for mechanical time fuzes strains capital allocation as procurement volumes tilt toward electronic platforms.
Strategic Opportunities
- Cybersecurity-Hardened Fuzing:Networked artillery systems create demand for encrypted command links and tamper-resistant arming circuits, opening specialized engineering services.
- Height-of-Burst Configurations:Area-effect munitions for counter-UAS and personnel suppression roles drive fastest-growing demand pool for variable burst timing fuzes.
- European Sovereign Capacity:Germany's BGV B5 workplace standards and parallel national certification pathways incentivize regional production investment to reduce ITAR dependency.
Industry Challenges
- Explosive Safety Engineering Talent:The specialized workforce combining ordnance chemistry with embedded systems design faces generational replacement gaps across Western defense industrial bases.
- Multi-Jurisdiction Certification Overlap:Simultaneous qualification against NATO STANAG, U.S. DoD insensitive munitions policy, and national regulators like Germany's explosive safety authority extends development timelines.
- Legacy System Integration Friction:Backward compatibility requirements with non-digitized artillery fire control systems constrain architecture choices for next-generation fuzing electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Command Fuzes Market |
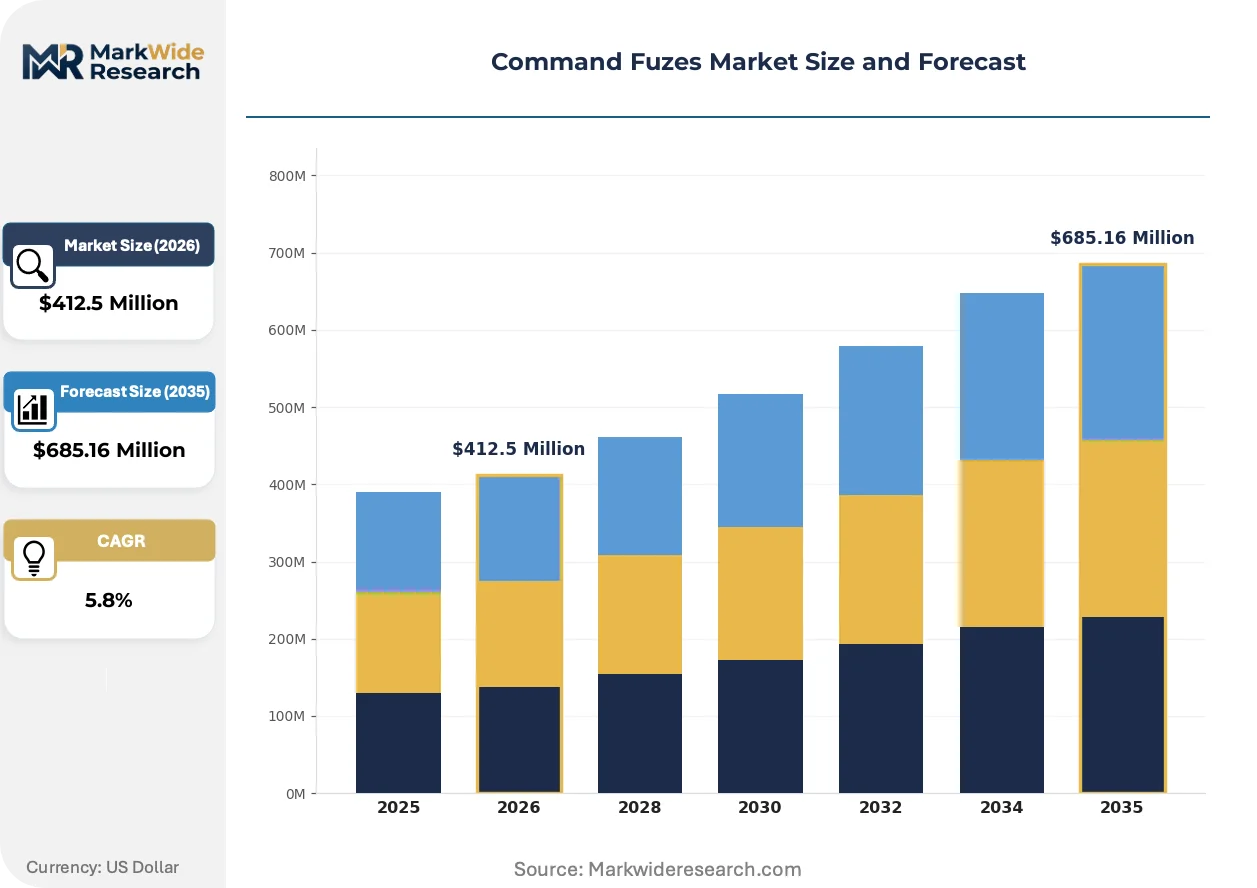
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Point Detonating, Time Delay, Height of Burst, Proximity, Multi-Option Technology: Mechanical, Electronic, Electromechanical, Programmable, Optical Application: Artillery, Mortar, Anti-Tank, Air Defense, Demolition End User: Defense Contractors, Armed Forces, Security Agencies, Defense Integrators |
| Companies Covered | L3 Technologies, Northrop Grumman, Kaman, Expal (Maxam Group), JUNGHANS Microtec GmbH, Action Manufacturing, Anhui Great Wall Military Industry, Reutech Fuchs Electronics, DIXI Microtechniques, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Command Fuzes Market Trends and Innovations
Microelectromechanical systems and solid-state sensing are compressing fuze form factors while expanding functional density, enabling new proximity and height-of-burst capabilities previously confined to larger calibers.
MEMS-based accelerometer and gyroscope integration is rewriting the precision of environmental sensing in artillery fuzes. U.S. and German defense contractors are embedding these sensors for real-time trajectory correction and burst optimization. The technology is compressing the performance gap between mass-produced mortar fuzes and specialized guided munitions.
The EU's evolving defense procurement coordination mechanisms are tightening cross-border interoperability requirements for munitions components. This industrial consequence pressures non-aligned European suppliers to align testing protocols with NATO STANAG frameworks. Artillery fuzing programs in Poland and the Baltic states are responding with accelerated dual-certification investments.
Consolidated multi-year framework agreements are displacing transactional spot procurement for electronic fuzes. Prime contractors are locking in foundry capacity and engineering services through captive supply arrangements spanning entire artillery modernization cycles. This pattern is most visible in U.S. Army 155mm and allied nation mortar program structures.
Command Fuzes Market Segmentation
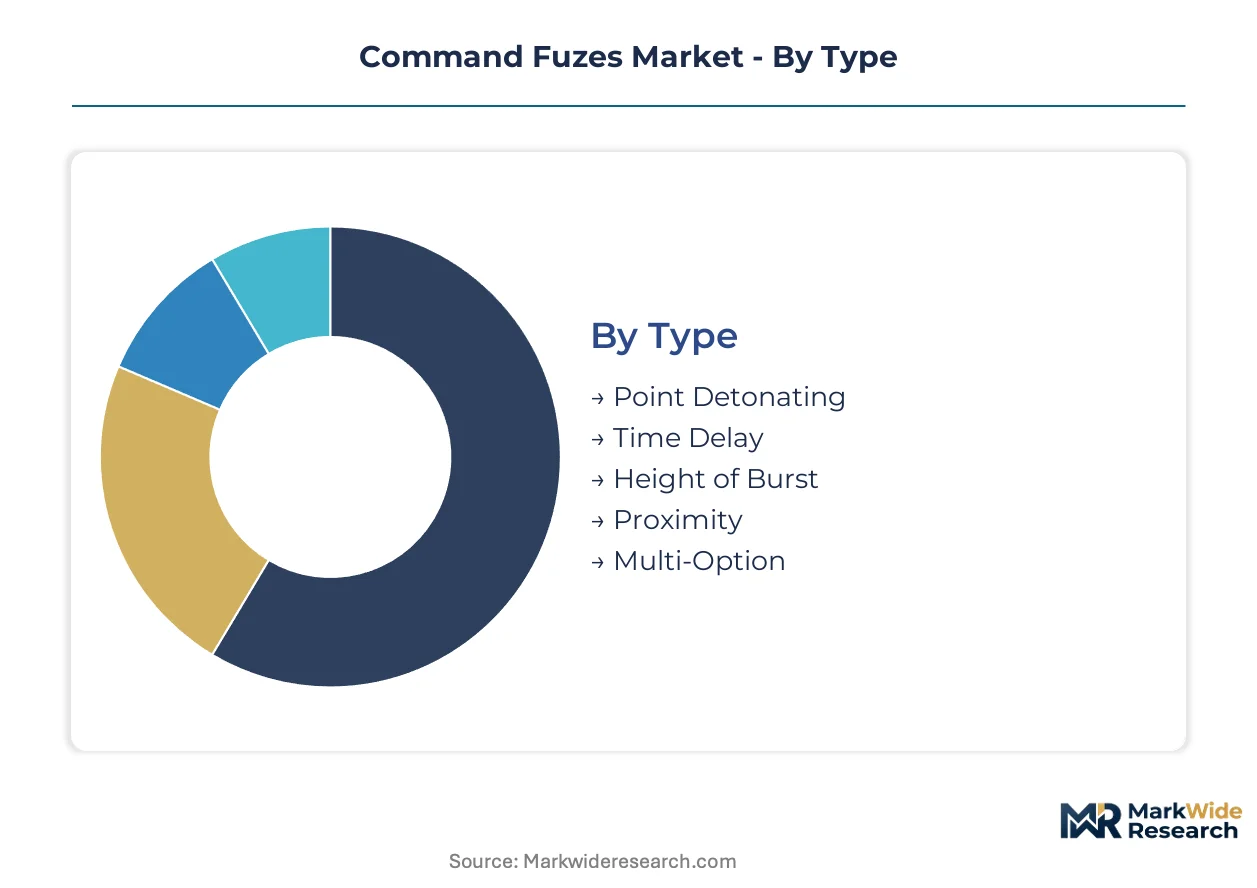
Command fuzes segment across functional type, enabling technology, weapon platform, and procurement channel. Each axis shapes qualification requirements, production economics, and supplier competitive positioning differently.
Type:
Functional classification by detonation trigger mechanism determines compatibility with target profiles and fire control architectures.
- Point Detonating:Surface-contact initiation using crush-switch or piezoelectric sensors. U.S. Army 155mm artillery programs anchor procurement volume, constrained by legacy stockpile drawdown schedules and insensitive munitions recertification timelines.
- Height of Burst:Radar or barometric altitude sensing for airburst fragmentation patterns. Counter-UAS and personnel suppression missions across NATO member arsenals are climbing the fastest, pulling investment from fixed-wing air defense legacy programs.
- Time Delay:Mechanical clockwork or electronic countdown arming for penetration before detonation. Demand concentrates in bunker-defeat and obstacle-clearance roles.
- Proximity:Active radio frequency sensing for target proximity without direct contact. Air defense applications in Poland and Baltic states sustain specialized procurement.
- Multi-Option:Field-selectable fuze modes combining point detonating, delay, and proximity functions. German mortar modernization contracts prioritize this configuration for force flexibility.
Point Detonating leads on scale; Height of Burst leads on momentum.
Technology:
Cost tier and performance specifications stratify across generations of arming and safing mechanisms.
- Electronic:Solid-state logic with microprocessor-controlled firing trains. U.S. Department of Defense insensitive munitions policy mandates dominate procurement specifications, forcing foundry capacity commitments from qualified radiation-hardened suppliers.
- Programmable:Fire-control-linked variable timing with encrypted command reception. NATO STANAG 4187 interoperability requirements in Poland, Germany, and Baltic states are expanding most quickly as artillery digitization accelerates.
- Mechanical:Spring-driven clockwork and setback-armed strikers. Legacy mortar systems in reserve inventories sustain residual demand.
- Electromechanical:Hybrid electric motor and mechanical geartrain combinations. Obsolescence pressure from pure electronic alternatives compresses procurement windows.
- Optical:Laser or infrared proximity detection for specialized air defense. Confined to high-value guided munitions with constrained volume.
Electronic platforms command the dominant procurement share; Programmable architectures are gaining share fastest.
Application:
Weapon system integration requirements dictate form factor, environmental tolerance, and safety certification pathways.
- Artillery:105mm through 155mm cannon systems with high-G setback and spin environments. U.S. Army Futures Command next-generation fire control integration anchors investment scale.
- Mortar:60mm through 120mm smoothbore delivery with lower acceleration profiles. German and allied NATO member programs sustain European demand concentration.
- Anti-Tank:Shaped charge and explosively formed penetrator initiation. Precision timing requirements favor electronic over mechanical platforms.
- Air Defense:Proximity and height-of-burst for missile and gun systems. Polish and Baltic procurement responds to regional threat evolution.
- Demolition:Command-detonated charges with remote firing authorization. Security agency requirements diverge from military specifications.
Artillery applications absorb the largest procurement volume; Mortar programs show the steepest expansion trajectory.
End User:
Customer type shapes contract structure, certification burden, and technology transfer restrictions.
- Armed Forces:National military services with direct procurement authority. U.S. Army and allied NATO member artillery commands concentrate demand for interoperable electronic fuzing.
- Defense Contractors:Prime integrators with multi-year framework agreements. Captive supply arrangements with qualified foundries lock in capacity across modernization cycles.
- Defense Integrators:System-of-systems providers assembling fire control and munitions packages. ITAR compliance requirements fragment supplier access for non-U.S. entities.
- Security Agencies:Domestic law enforcement and counter-terror units with specialized demolition needs. Smaller procurement scale with divergent safety certification pathways.
Armed Forces procurement leads on absolute scale; Defense Contractors procurement leads on contract duration and supply chain captivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as suppliers migrate toward jurisdictions with streamlined insensitive munitions certification pathways and lower compliance overhead. Cost-of-compliance gaps between U.S. ITAR-controlled production and European sovereign capacity are accelerating foundry investment decisions.
United States
Army Futures Command drives demand through next-generation fire control integration mandates. The Department of State ITAR regime restricts cross-border technology transfer for electronic arming mechanisms. Tucson, Arizona and the greater Orlando defense corridor concentrate vertically integrated fuze electronics production for 155mm artillery programs.
Germany
Bundeswehr mortar modernization and allied NATO export contracts sustain procurement volume. BGV B5 workplace standards enforced by national explosive safety regulators constrain manufacturing process choices. JUNGHANS Microtec GmbH anchors production in Baden-Württemberg, supplying German and allied nation mortar fuzing contracts.
Poland
Regional threat evolution accelerates air defense and artillery procurement with NATO STANAG 4187 interoperability requirements. The country's defense procurement agency prioritizes dual-certification investments aligned with allied standardization frameworks. Warsaw and the Łódź industrial cluster host emerging integration partnerships for networked fuzing systems.
France
Fixed-wing air defense legacy programs sustain specialized proximity fuze demand while area-effect munitions gain priority. ANSM and national defense procurement direction shape qualification timelines for insensitive munitions compliance. The Île-de-France aerospace cluster maintains research capacity for optical proximity methods in guided munitions.
South Africa
Regional security requirements and legacy defense industrial capacity sustain niche procurement for electronic fuzing components. National explosive safety regulators enforce parallel certification pathways that extend development timelines. Pretoria and the Gauteng industrial corridor host specialized manufacturing for export-restricted defense electronics.
Command Fuzes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cybersecurity-hardened fuzing and sovereign European capacity. The vendor base stratifies across three tiers: vertically integrated U.S. primes with captive foundry capacity, German specialists anchoring NATO interoperability supply, and emerging Asian producers serving non-aligned defense markets. Three strategic archetypes dominate: radiation-hardened electronics foundries, multi-option fuze integrators, and proximity sensing specialists. Competitive moves concentrate on multi-year framework agreements locking in foundry capacity and regional certification investments reducing ITAR dependency.
Within the vertically integrated tier, L3 Technologies exemplifies foundry-captive supply architecture, while Northrop Grumman occupies a position among proximity sensing specialists. JUNGHANS Microtec GmbH represents the European sovereign capacity archetype, anchoring German and allied nation supply chains. These three entities collectively illustrate the geographic and technological segmentation pressuring mid-tier competitors toward niche specialization or consolidation.
| Leading Market Players |
|---|
| L3 Technologies |
| Northrop Grumman |
| Kaman |
| Expal (Maxam Group) |
| JUNGHANS Microtec GmbH |
| Action Manufacturing |
| Anhui Great Wall Military Industry |
| Reutech Fuchs Electronics |
| DIXI Microtechniques |
| Others |
Pricing and Supply Chain Analysis
U.S. Army multi-year framework agreements and allied NATO artillery procurement programs anchor demand concentration, locking in contract-based long-term offtake pricing with volume-scaled discounts for qualified suppliers. This buyer archetype dominance compresses margin flexibility for mid-tier competitors while rewarding vertically integrated primes with captive foundry capacity.
Pricing Analysis
Prime contractor direct-to-program pricing eliminates distributor margin layers, with three-tier pricing structure across radiation-hardened premium, standard electronic, and residual electromechanical economy levels. Price differentiation hinges on NATO STANAG 4187 certification grade and insensitive munitions compliance tier. Cost compression in mechanical legacy tiers is intensifying because procurement volumes tilt toward programmable platforms. Reserve inventory buyers show highest price sensitivity; next-generation fire control integrators prioritize performance over unit cost.
Supply Chain Analysis
Certification gating under U.S. DoD insensitive munitions policy and Germany's BGV B5 standards restricts qualified production to the United States, Germany, and South Africa. Radiation-hardened microcontroller supply draws from a concentrated tier of U.S. and European foundries, creating single-source vulnerability for arming logic components. Distribution runs through defense prime captive supply arrangements rather than open market channels. Tariff exposure on semiconductor inputs compounds cost pressure for non-integrated assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The command fuzes market represents a late-cycle quality story as NATO artillery digitization mandates pull procurement toward cybersecurity-hardened programmable specifications with premium engineering content.
For Market Incumbents: Hedge against electromechanical obsolescence by accelerating foundry capacity commitments for radiation-hardened electronics while securing dual-certification pathways under NATO STANAG 4187 and Germany's BGV B5 standards. Channel control through multi-year framework agreements locks out emerging competitors from U.S. Army 155mm and Bundeswehr mortar programs. For New Entrants and Emerging Players: Begin with cybersecurity-hardened fuzing engineering services for Polish and Baltic state artillery modernization, where NATO interoperability investments create penetrable demand without ITAR-controlled component barriers. A sovereign European capacity positioning—anchored in German or regional production—reduces technology transfer restrictions for non-U.S. integrators. For Investors and Strategic Acquirers: Defense primes with captive electronics foundries are the most active acquirers in this space, targeting specialized proximity sensing and MEMS trajectory correction capabilities. The long-term viability window favors assets with dual-use potential across artillery and air defense applications. Watch for accelerated EU defense procurement coordination as the inflection signal for cross-border consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captive radiation-hardened production secures U.S. Army 155mm delivery schedules against semiconductor supply concentration. |
| Dual-Certification Investment | Parallel NATO STANAG 4187 and BGV B5 qualification opens Bundeswehr and allied NATO member procurement channels. |
| Cybersecurity Engineering Services | Encrypted command link development addresses networked artillery digitization requirements in Poland and Baltic states. |
| MEMS Sensor Integration | Solid-state accelerometer embedding enables height-of-burst precision for counter-UAS missions across NATO arsenals. |
| European Sovereign Production | Regional manufacturing capacity reduces ITAR dependency for non-U.S. defense integrators serving allied nation programs. |
Research Methodology
Bottom-up artillery and mortar program modeling reconciled against top-down defense procurement budget tracking forms the analytical core of this study. Primary interviews with program managers at Army Futures Command, procurement officers at allied NATO defense agencies, fuze engineering directors at prime contractors, and explosive safety regulators at Germany's federal authority were validated against secondary sources including U.S. DoD budget justification documents, NATO STANAG publication registers, EU defense procurement coordination notices, and national explosive safety regulatory filings.
Historical trendline analysis of electronic fuze adoption rates across Western artillery modernization cycles established baseline penetration assumptions. The forecast framework segments by functional type, enabling technology, weapon platform, and procurement channel, with growth trajectories derived from artillery digitization investment timelines and insensitive munitions policy implementation schedules. Modeled inputs include NATO member state defense expenditure patterns, foundry capacity expansion announcements, and cybersecurity mandate evolution for networked fuzing systems.
Caveats apply where semiconductor supply disruptions, regulatory timeline delays, or threat environment shifts could materially shift the outlook. Forecasts reflect assumptions about allied standardization adherence and procurement budget continuity. A model refresh is warranted upon material change in NATO STANAG 4187 revision schedules or U.S. DoD insensitive munitions policy enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
Cluster Munitions Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Martial Art Weapon Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Space Weapons Market