
 Russia Autonomous Navigation Market | 2026-2036
Russia Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Autonomous Navigation Market Insights
MIL-STD grade inertial measurement specifications is bifurcating the Russia autonomous navigation landscape into defense-certified and commercial-grade supply tiers. Fizoptika leverages fiber-optic gyroscope heritage to anchor high-precision military contracts. Elektropribor JSC sustains deep manufacturing scale in St. Petersburg for accelerometer and gyroscope assemblies. OAO MKB Kompas differentiates through integrated navigation complexes that combine satellite and inertial channels for hardened platforms.
Russia autonomous navigation encompasses self-directed positioning systems that fuse inertial sensors, satellite receivers, and environmental perception algorithms to compute trajectory without human intervention, typically achieving drift rates below 0.01 degrees per hour in strategic-grade implementations. The primary purpose spans weapons guidance, unmanned vehicle autonomy, and geodetic surveying under contested electromagnetic conditions. Inertial navigation occupies the largest installed base within defense aerospace, while computer vision is expanding fastest in robotics and ground unmanned platforms. GPS augmentation solutions command premium pricing in dual-use applications where jamming resilience justifies redundant signal architectures.
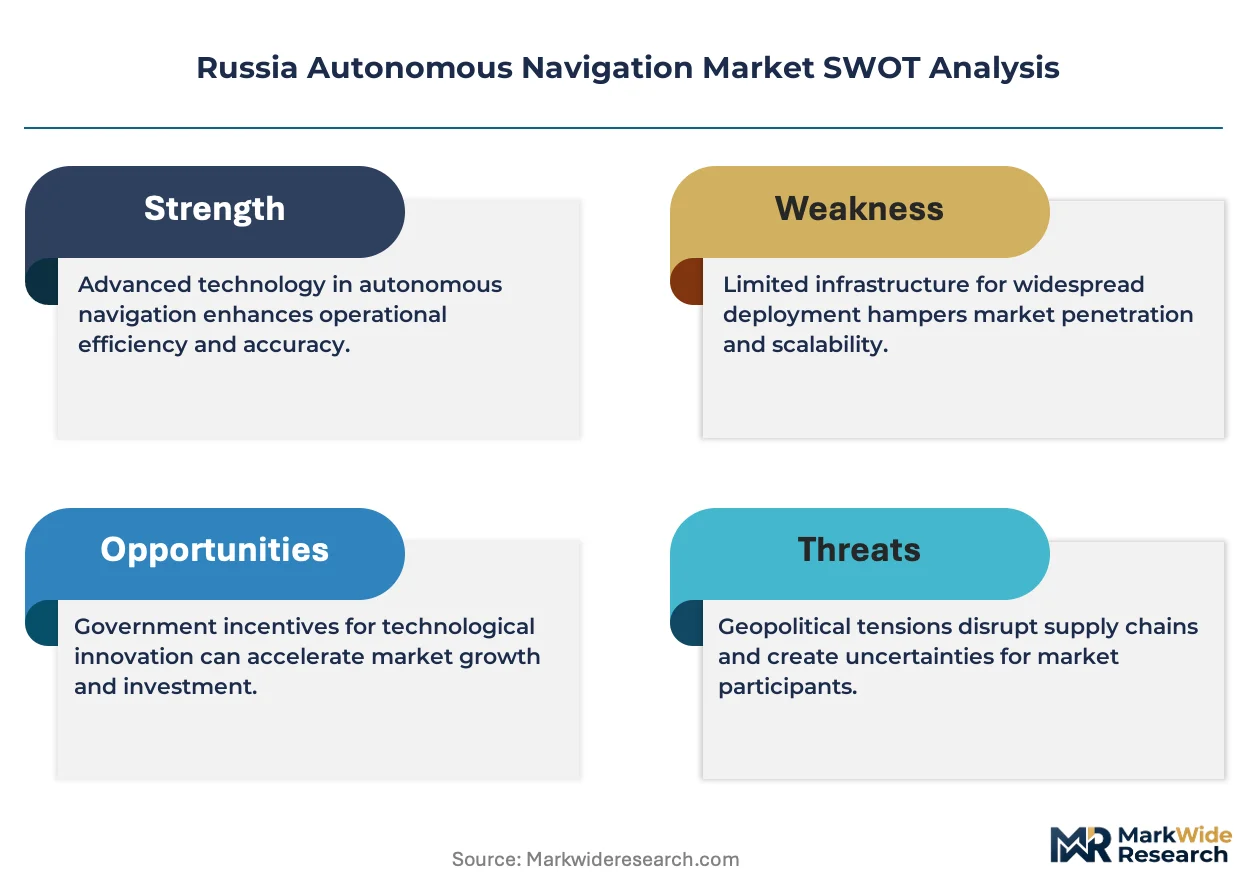
Rosstandart certification requirements and Ministry of Industry and Trade localization quotas shape component sourcing, compelling foreign subsystem replacement with domestic equivalents. The Federal Service for Technical and Export Control imposes cryptographic and frequency restrictions on navigation modules, constraining design flexibility for export-oriented vendors. Stakeholders must monitor procurement rule changes for critical technologies as geopolitical alignment shifts redirect funding between civilian autonomy programs and military modernization tracks.
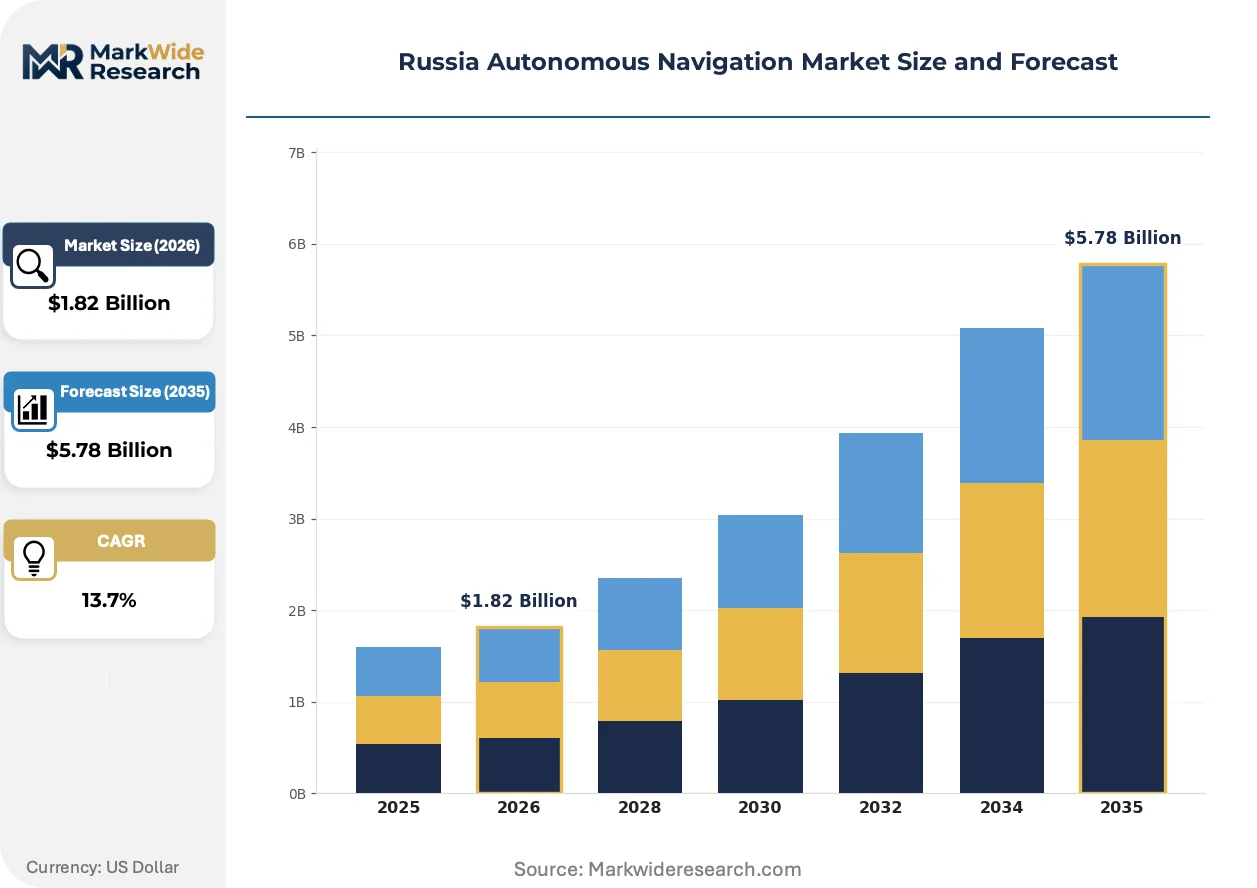
Market Dynamics
Import substitution mandates under the Technological Sovereignty program are restructuring component sourcing across the Russia autonomous navigation value chain, compelling defense integrators to replace foreign inertial sensors with domestic equivalents.
Growth Catalysts
- Defense procurement acceleration:The Ministry of Defense of the Russian Federation is expanding unmanned aerial and ground platform contracts, directly stimulating demand for hardened navigation systems.
- Technological Sovereignty localization quotas:Ministry of Industry and Trade mandates require domestic content thresholds, redirecting R&D funding toward indigenous gyroscope and accelerometer development.
- Satellite-inertial fusion:Multi-sensor integration architectures are enabling navigation continuity under GPS-denied conditions, opening new mission profiles for strategic aerospace applications.
Market Restraints
- Semiconductor input volatility:Precision MEMS fabrication depends on specialty silicon wafers and photolithography equipment subject to trade restriction cascades.
- Supply concentration in St. Petersburg:Accelerometer and gyroscope assembly capacity clusters in a single industrial zone, creating geographic vulnerability to logistical disruption.
- Rosstandart certification timelines:MIL-STD grade qualification protocols extend product validation cycles, compressing effective revenue windows for new entrants.
Strategic Opportunities
- Siberian Arctic unmanned logistics:Remote resource extraction corridors lack reliable satellite coverage, creating demand for terrain-relative navigation and inertial-heavy solutions.
- Dual-use robotics pivot:Agricultural and industrial automation sectors are adopting defense-derived autonomous ground vehicle platforms for civilian deployment.
- Fiber-optic gyroscope convergence:Integration with photonic integrated circuits is reducing size-weight-power constraints for tactical-grade implementations.
Industry Challenges
- Specialized navigation software talent scarcity:Sensor fusion algorithm development requires expertise in Kalman filtering and error-state estimation that outpaces domestic training pipeline output.
- Legacy platform integration friction:Retrofitting Soviet-era airframes and ground vehicles with modern autonomous navigation architectures demands custom mechanical and electrical interface engineering.
- Federal Service for Technical and Export Control cryptographic compliance:Navigation module frequency and encryption restrictions impose design constraints that lengthen development cycles for export-oriented product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Autonomous Navigation Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lidar, Computer Vision, GPS, Inertial Navigation Application: Aerospace, Marine, Automotive, Robotics End User: Government, Commercial, Defense, Research Solution: Autonomous Vehicles, Drones, Shipping Systems, Mapping Services |
| Companies Covered | Fizoptika, Inertial Technologies JSC, MIEA JSC, MRI Progress JSC, OAO RIRT, OAO Izhevskiy Radiozavod, Elektropribor JSC, OAO MKB Kompas, Teknol, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Autonomous Navigation Market Trends and Innovations
Sensor fusion architectures are actively displacing single-modality navigation systems across defense and emerging civilian applications. Three developments are compressing technology refresh cycles.
Photonic inertial measurement technology is fragmenting the traditional mechanical gyroscope market. Fiber-optic gyroscopes achieve drift rates below tactical-grade thresholds without moving parts. The Ministry of Defense is accelerating platform retrofits with these solid-state alternatives. This displacement is compressing maintenance intervals and extending operational availability for deployed unmanned systems.
Rosstandart certification requirements are tightening performance verification protocols for navigation subsystems. The Federal Service for Technical and Export Control has expanded cryptographic and frequency restriction scopes. Defense aerospace integrators are responding by front-loading qualification testing and establishing captive metrology capabilities to accelerate approval timelines.
Defense procurement offices are consolidating vendor relationships around integrated navigation complex suppliers rather than discrete component vendors. Long-term service agreements are displacing transactional hardware purchases in unmanned platform programs. This concentration is most visible in the Moscow-Samara-Togliatti aerospace corridor, where prime contractors are absorbing subsystem risk to secure multi-year platform contracts.
Russia Autonomous Navigation Market Segmentation
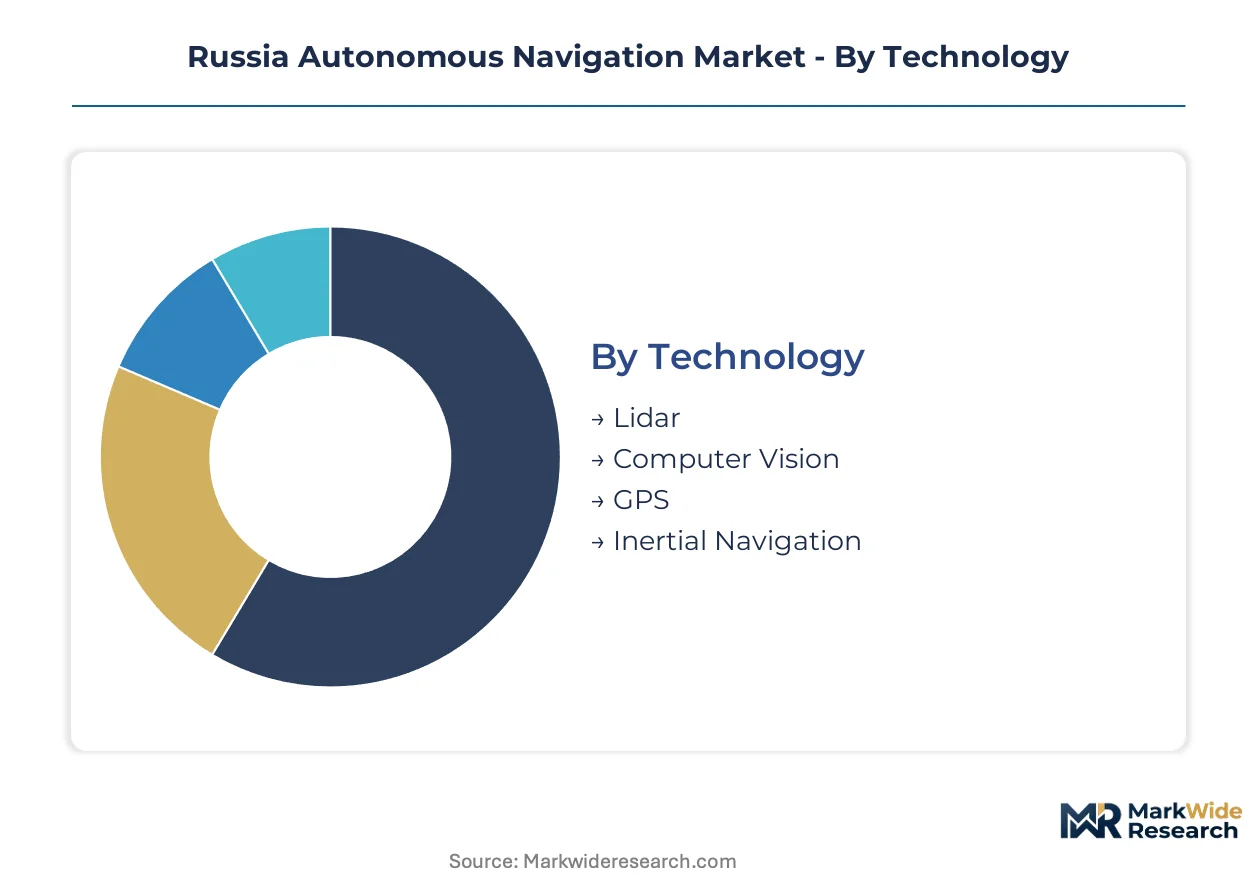
Russia's autonomous navigation market segments reflect the tension between defense-grade certification requirements and civilian application scalability. Procurement flows from the Ministry of Defense of the Russian Federation dominate technology selection, while import substitution mandates reshape supplier eligibility across every category.
Technology:
Rosstandart certification tiers bifurcate the technology landscape into MIL-STD qualified and commercial-grade implementations, with defense integrators facing mandatory domestic sourcing quotas.
- Inertial Navigation:Fiber-optic and MEMS gyroscope assemblies achieve drift rates below 0.01 degrees per hour for strategic-grade platforms. Demand concentrates in the Moscow-Samara aerospace corridor where Elektropribor JSC and Fizoptika anchor military contracts under Technological Sovereignty localization mandates.
- GPS:Multi-constellation receivers with GLONASS integration provide redundant signal architectures for contested electromagnetic environments. The Federal Service for Technical and Export Control imposes frequency and cryptographic restrictions that lengthen qualification timelines for export-oriented variants.
- Computer Vision:Stereo camera and deep learning algorithms enable terrain-relative navigation in GPS-denied conditions. Agricultural automation in Krasnodar Krai and warehouse robotics in Moscow Oblast drive civilian adoption.
- Lidar:Solid-state laser scanning systems map three-dimensional environments for unmanned ground vehicle obstacle avoidance. Domestic manufacturing capacity remains constrained by specialty photodetector import dependencies.
Inertial Navigation handles the majority of defense procurement throughput; Computer Vision is expanding most quickly in civilian robotics applications.
Application:
Cost tier differentiation separates hardened military platforms from commercial implementations, with certification overhead creating a threefold pricing spread between adjacent tiers.
- Aerospace:Manned and unmanned military aircraft require redundant inertial-satellite fusion systems certified to MIL-STD-1553 and GOST R standards. The Ministry of Defense's unmanned aerial platform expansion directly stimulates demand in the Samara-Togliatti industrial cluster.
- Robotics:Autonomous ground vehicles for logistics and perimeter security deploy sensor fusion architectures combining vision, lidar, and inertial channels. Siberian Arctic resource extraction corridors lacking reliable satellite coverage create demand for terrain-relative navigation solutions.
- Automotive:Passenger vehicle advanced driver assistance systems incorporate GLONASS-augmented positioning for highway autonomy. Domestic OEMs face localization quotas for navigation subsystem content under Ministry of Industry and Trade directives.
- Marine:Unmanned surface and underwater vessels require pressure-hardened inertial units for subsea positioning. Icebreaker escort operations in the Northern Sea Route drive specialized demand for jamming-resistant navigation.
Aerospace captures the dominant share of procurement value; Robotics is climbing the fastest as defense-derived platforms pivot to civilian deployment.
End User:
Customer type determines procurement channel access, with defense integrators operating through closed tender processes while commercial buyers navigate Rosstandart conformity assessment procedures.
- Defense:The Ministry of Defense of the Russian Federation and affiliated aerospace primes procure integrated navigation complexes through multi-year platform contracts. Vendor consolidation around OAO MKB Kompas and Elektropribor JSC reflects captive subsystem risk absorption strategies.
- Government:Civilian agencies including Roscosmos and the Ministry of Emergency Situations acquire navigation systems for survey, search-and-rescue, and infrastructure monitoring missions. Budget cycles align with federal target program funding windows.
- Commercial:Agricultural, logistics, and industrial automation sectors adopt defense-derivative autonomous platforms. Dual-use technology transfer friction limits access to hardened navigation architectures.
- Research:Universities and state laboratories develop sensor fusion algorithms under grant funding from the Russian Science Foundation. Kalman filtering and error-state estimation expertise scarcity constrains pipeline output.
Defense channels handle the majority of high-precision system throughput; Commercial end users are gaining share fastest as agricultural automation scales.
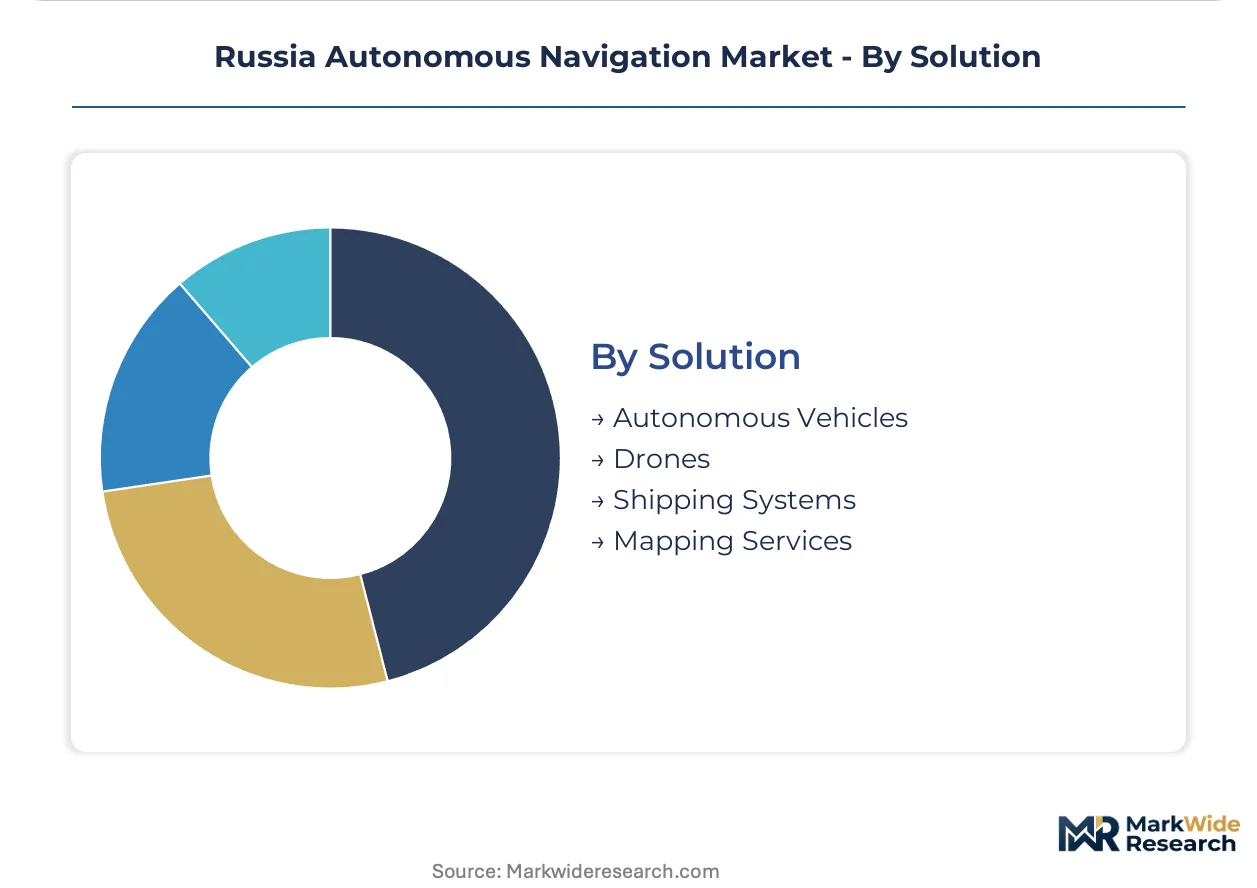
Solution:
Supply concentration in St. Petersburg for accelerometer and gyroscope assembly creates geographic vulnerability that shapes solution-level procurement risk assessment.
- Autonomous Vehicles:Ground-based unmanned platforms integrate multi-sensor navigation stacks for off-road logistics and perimeter patrol. The Siberian Arctic corridor's satellite coverage gaps favor inertial-heavy architectures.
- Drones:Fixed-wing and rotary unmanned aerial systems deploy compact fiber-optic gyroscope units for extended endurance missions. Photonic integrated circuit integration is reducing size-weight-power constraints for tactical-grade implementations.
- Shipping Systems:Autonomous maritime vessels require redundant positioning for collision avoidance in ice-infested waters. Northern Sea Route development stimulates specialized demand.
- Mapping Services:Mobile mapping platforms combine lidar, vision, and satellite positioning for geodetic survey and infrastructure digitization. Rosreestr certification requirements govern data accuracy standards.
Autonomous Vehicles anchor procurement volume in ground platform programs; Drones are advancing most rapidly on share as the Ministry of Defense expands unmanned aerial contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's autonomous navigation sector operates as a net import-substituting market with minimal cross-border component flows. Defense procurement concentrates in domestic industrial corridors while export controls constrain technology transfer.
Central Federal District
Moscow anchors defense procurement command functions and systems integration for unmanned aerial platforms. The Ministry of Industry and Trade administers Technological Sovereignty localization quotas from the capital. The Moscow aerospace corridor houses prime contractors absorbing subsystem risk for multi-year platform contracts.
Northwestern Federal District
St. Petersburg clusters accelerometer and gyroscope assembly capacity for strategic-grade inertial navigation units. Rosstandart certification protocols extend product validation cycles for components manufactured here. Elektropribor JSC sustains deep manufacturing scale for military-grade sensor assemblies in this zone.
Volga Federal District
Samara-Togliatti industrial corridor concentrates unmanned aerial vehicle production and navigation systems integration. The Ministry of Defense expands platform contracts directly stimulating component demand. OAO MKB Kompas anchors integrated navigation complex supply from this manufacturing cluster.
Siberian Federal District
Arctic resource extraction corridors create demand for terrain-relative navigation in GPS-denied conditions. Remote logistics operations favor inertial-heavy architectures for autonomous ground vehicles. Krasnoyarsk and Novosibirsk host emerging robotics development for unmanned logistics applications.
Southern Federal District
Krasnodar Krai drives civilian adoption of computer vision systems for agricultural automation. Dual-use technology transfer from defense programs supports precision farming navigation. Rostov-on-Don anchors industrial automation demand for sensor fusion robotics.
Russia Autonomous Navigation Market Competitive Landscape
Listed leaders compete with private specialists across defense certification tiers, creating a bifurcated supply structure. State-affiliated entities dominate MIL-STD qualified segments while smaller private firms occupy commercial-grade niches. Two archetypes prevail: integrated navigation complex suppliers absorbing subsystem risk, and discrete component specialists focused on gyroscope or accelerometer fabrication. Competitive moves center on captive metrology capability establishment and long-term service agreement displacement of transactional hardware sales.
Within the integrated systems tier, OAO MKB Kompas and Elektropribor JSC exemplify state-affiliated scale players positioned for defense platform contracts. Fizoptika occupies a fiber-optic specialization niche, representing the precision sensor archetype anchored to high-reliability military specifications. These three entities collectively illustrate the vendor consolidation pattern visible across the Moscow-Samara-Togliatti procurement corridor.
| Leading Market Players |
|---|
| Fizoptika |
| Inertial Technologies JSC |
| MIEA JSC |
| MRI Progress JSC |
| OAO RIRT |
| OAO Izhevskiy Radiozavod |
| Elektropribor JSC |
| OAO MKB Kompas |
| Teknol |
| Others |
Pricing and Supply Chain Analysis
Rosstandart certification protocols gate both supplier qualification and price differentiation simultaneously, bifurcating the market into MIL-STD qualified and commercial-grade tiers with threefold pricing spreads between adjacent certification levels. Defense integrators absorb premium positioning costs to secure multi-year platform contracts, while commercial buyers navigate conformity assessment procedures that compress margins on uncertified alternatives.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Moscow-Samara-Togliatti aerospace corridor. Price differentiation separates defense-certified navigation complexes from commercial-grade implementations, with volume scale and after-sales service bundling as secondary tiering mechanisms. Cost compression in commercial-grade tiers is intensifying because import substitution mandates force rapid domestic supplier qualification. State-affiliated defense primes exhibit lowest price sensitivity; agricultural automation OEMs in Krasnodar Krai face acute margin pressure.
Supply Chain Analysis
Container availability constraints on Baltic Sea trade lanes extend inbound logistics timelines for specialty photolithography equipment and precision silicon wafers. Manufacturing concentrates in Russia, with accelerometer and gyroscope assembly anchored in St. Petersburg and integrated navigation complex production in Samara-Togliatti. The supply chain draws from domestic MEMS fabrication, fiber-optic coil winding, and satellite receiver module assembly. Single-source vulnerability in specialty photodetector inputs creates structural risk. Distribution runs through defense procurement channels for certified tiers and Rosstandart conformity assessment for commercial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. Rosstandart certification timelines and Federal Service for Technical and Export Control restrictions create switching costs that protect qualified incumbents from rapid displacement.
For Market Incumbents: Consolidate around integrated navigation complex supply rather than discrete component sales, absorbing subsystem risk to secure multi-year Ministry of Defense platform contracts. Establish captive metrology capabilities in St. Petersburg to accelerate Rosstandart approval timelines and defend against emerging photonic integrated circuit specialists threatening fiber-optic gyroscope incumbency.
For New Entrants and Emerging Players: Lead with terrain-relative navigation solutions for Siberian Arctic unmanned logistics corridors, where satellite coverage gaps favor inertial-heavy architectures over GPS-dependent alternatives. Agricultural automation in Krasnodar Krai offers the most penetrable civilian segment; partner with defense-derivative platform providers to access hardened navigation architectures through dual-use technology transfer channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across photonic integrated circuit integration for tactical-grade implementations, favoring scaled state-affiliated entities over venture-backed specialists. Acquisition targets should display integrated navigation complex capabilities with established Rosstandart certification pipelines. Watch Ministry of Defense procurement rule changes as the primary inflection signal for funding reallocation between civilian autonomy and military modernization tracks.
| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Integration | Fiber-optic gyroscope convergence reduces size-weight-power constraints for tactical-grade unmanned platforms. |
| Captive Metrology Capability Establishment | In-house qualification testing accelerates Rosstandart certification timelines for defense aerospace integrators. |
| Long-term Service Agreement Displacement | Multi-year platform contracts replace transactional hardware sales across Moscow-Samara-Togliatti procurement corridor. |
| Siberian Arctic Terrain-Relative Navigation Development | GPS-denied positioning solutions address remote resource extraction logistics gaps in Krasnoyarsk and Novosibirsk. |
| Dual-Use Robotics Pivot | Defense-derived autonomous ground vehicle platforms transfer to agricultural automation in Krasnodar Krai. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the analysis window, combining primary interviews with platform engineers at Elektropribor JSC and OAO MKB Kompas, procurement officers at Ministry of Defense-affiliated aerospace primes, sensor fusion algorithm researchers at Moscow Institute of Physics and Technology, and agricultural automation OEMs in Krasnodar Krai with secondary validation against Federal Service for Technical and Export Control filings, Rosstandart certification registries, customs data on specialty photodetector imports, and Ministry of Industry and Trade localization quota disclosures. Bottom-up component demand aggregation and top-down defense budget allocation analysis were triangulated to reconcile volume estimates.
Across the projection horizon, the analytical framework modeled technology segments including inertial navigation, GPS augmentation, computer vision, and lidar; application categories spanning aerospace, robotics, automotive, and marine; and end-user channels covering defense procurement, government agencies, commercial buyers, and research institutions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included Ministry of Defense unmanned platform contract announcements and Technological Sovereignty program funding allocations.
Forecasts assume regulatory continuity in Rosstandart certification protocols and Federal Service for Technical and Export Control cryptographic restrictions; material policy shifts would require re-modeling. Semiconductor input trade restriction cascades and Ministry of Defense procurement priority reallocation between civilian autonomy and military modernization tracks represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
High Frequency Military Communications Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Doppler Radar Market
Communication Navigation & Surveillance
Missile Guidance Radar Market
Communication Navigation & Surveillance
Industrial Inertial Systems Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Man-Portable Military Communication Systems Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Airborne SATCOM Equipment Market
Communication Navigation & Surveillance
Defense Communication System Market
Communication Navigation & Surveillance
Integrated 3D Radar Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Naval Tactical Communication Market
Communication Navigation & Surveillance
Airborne SATCOM Market