
 Asia-Pacific Transparent Conductive Films Market | 2026-2036
Asia-Pacific Transparent Conductive Films Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Transparent Conductive Films Market Outlook
GB standards for optoelectronic film transparency is collapsing the supplier base eligible for Chinese OEM contracts. Toyobo Co., Ltd. leverages its polymer substrate expertise to sustain dominance in roll-to-roll flexible film supply. Nitto Denko Corporation anchors its position through adhesive-layer integration that reduces lamination defects for display laminators. Cambrios Technologies Corporation competes on wet-process silver nanowire chemistry that lowers haze values below competing carbon nanotube formulations.
Transparent conductive films are thin, optically clear layers engineered to transmit visible light while conducting electrical current, typically fabricated from metal oxide coatings, nanowire networks, or carbon allotropes deposited via sputtering or solution-based roll-to-roll processing onto polymer substrates. These films serve as the critical electrode interface in capacitive touch sensors, photovoltaic cells, and organic light-emitting diode stacks where optical transmittance above 80 percent must coexist with sheet resistance below 100 ohms per square. Silver nanowires command widening share in flexible display applications where mechanical bending tolerance exceeds indium tin oxide brittleness, while graphene remains confined to premium aerospace segments awaiting manufacturing scale economics. Roll-to-roll processing dominates volume output for touchscreen displays, though sputtering retains margin concentration in solar cell metallization where film uniformity directly correlates with photovoltaic conversion efficiency.
China's MEE enforces volatile organic compound emission ceilings on solvent-based coating lines, compelling migration toward aqueous nanowire inks. Japan's METI mandates circular material content ratios in electronics components, pressuring indium recovery from spent indium tin oxide targets. South Korea's MFDS and KATS coordinate display industry safety certifications that gate market access for automotive display films. Stakeholders must monitor how these regulatory trajectories interact with substrate material transitions before committing to captive coating capacity or merchant supply agreements.
Market Dynamics
China's dual carbon goals and Japan's METI efficiency mandates are compressing the indium tin oxide supply base while accelerating silver nanowire qualification timelines across display manufacturing clusters.
Growth Catalysts
- Automotive Display Certification:South Korea's MFDS and KATS coordinate safety standards that gate market access for curved touchscreen films in vehicle cabins, pulling advanced silver nanowire formulations into qualification pipelines.
- Flexible Form Factor Demand:Rollable smartphone and foldable tablet prototypes from Chinese OEMs are forcing substrate suppliers to validate bending tolerance beyond 100,000 cycles.
- Aqueous Ink Migration:China's MEE volatile organic compound ceilings on solvent coating lines are compelling wet-process nanowire chemistry adoption that reduces haze values.
Market Restraints
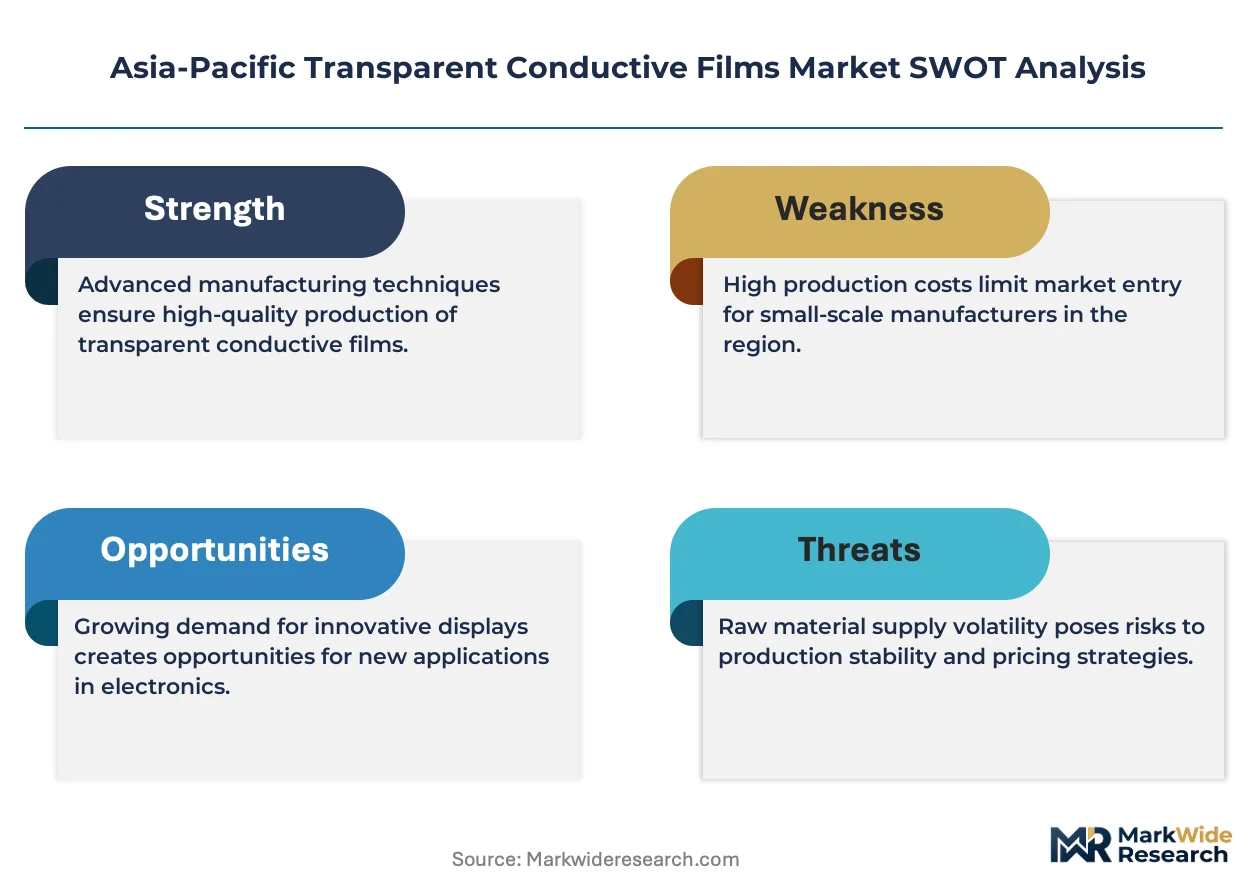
- Indium Supply Concentration:Primary indium refining concentrates in Chinese smelters, exposing indium tin oxide target manufacturers to export quota volatility and price spikes.
- Sheet Resistance Floor:Carbon nanotube networks hit conductivity limits below 50 ohms per square, freezing them out of large-area interactive whiteboard applications.
- Circular Content Mandates:Japan's METI circular material ratios pressure manufacturers to recover indium from spent sputtering targets, adding capital intensity to already thin margins.
Strategic Opportunities
- Photovoltaic Metallization:Heterojunction solar cell architectures in Chinese gigafactories are testing transparent conductive oxide replacements that tolerate higher processing temperatures than polymer substrates.
- Avionics Electromagnetic Shielding:Graphene film stacks are penetrating premium aerospace segments where optical clarity must coexist with radio frequency interference attenuation.
- Medical Device Integration:Australia's TGA is streamlining biocompatibility certification for conductive films in surgical displays, opening a regulated channel with pricing power.
Industry Challenges
- Nanowire Dispersion Expertise:Wet-process coating lines require rheology engineers capable of maintaining silver nanowire ink stability across 1,000-meter roll lengths without aggregation defects.
- Cross-Border Standard Harmonization:Divergent GB transparency specifications, JIS adhesion tests, and KATS flexural standards force manufacturers to maintain three distinct product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Transparent Conductive Films Market |
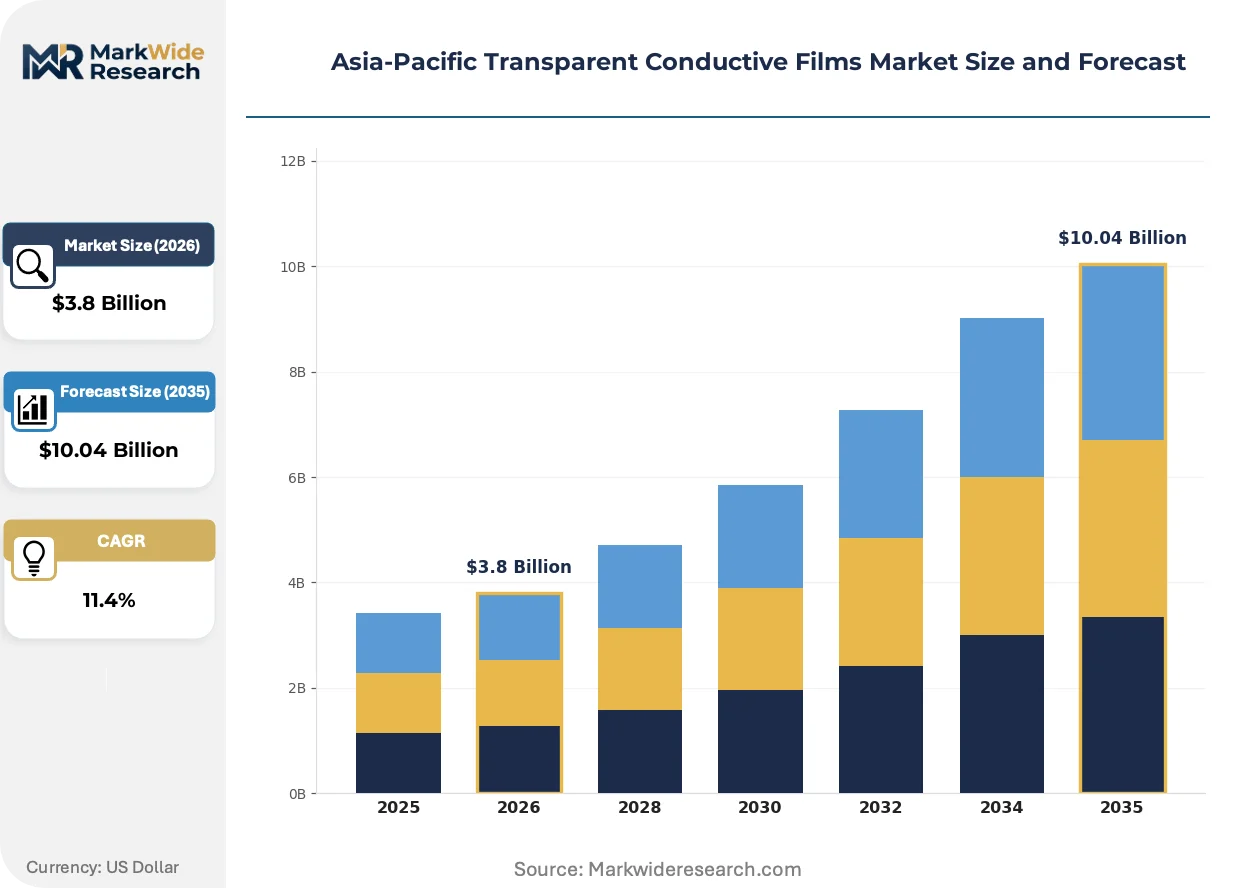
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
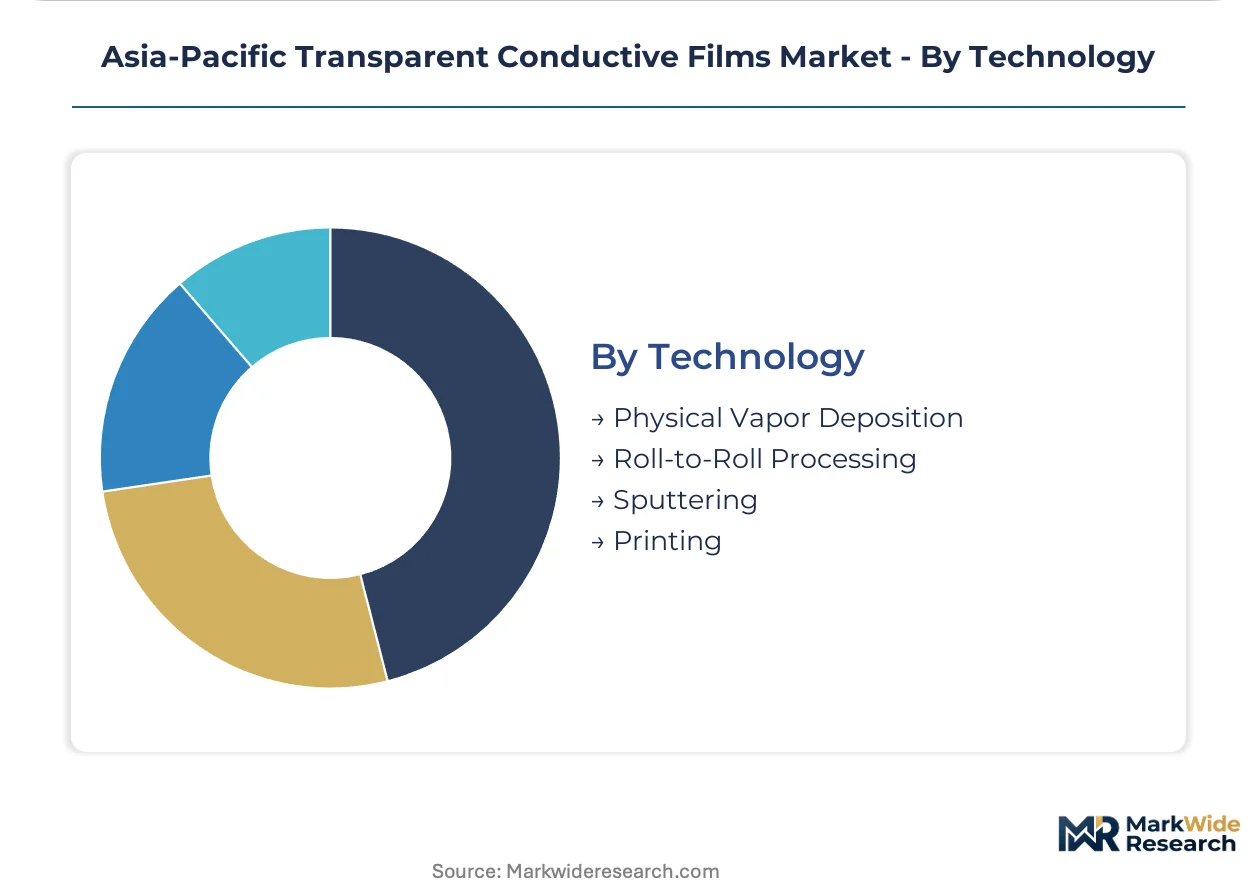
| Segmentation | Product Type: Indium Tin Oxide, Carbon Nanotubes, Silver Nanowires, Graphene Application: Touchscreen Displays, Solar Cells, OLED Displays, Automotive Displays End User: Consumer Electronics, Automotive, Aerospace, Renewable Energy Technology: Physical Vapor Deposition, Roll-to-Roll Processing, Sputtering, Printing |
| Companies Covered | Toyobo Co., Ltd., Cambrios Technologies Corporation, Nitto Denko Corporation, Canatu Oy, C3Nano, Teijin Limited, Gunze Ltd., AGC Inc., TDK Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Transparent Conductive Films Market Strategic Shifts
Silver nanowire chemistry is overtaking metal oxide dominance as display manufacturers prioritize mechanical compliance over optical perfection in next-generation form factors.
Silver nanowire networks transmit electrical current through percolating filament structures that maintain conductivity under tensile strain. Korean display panel makers are integrating these films into foldable OLED stacks at pilot scale. This material transition is supplanting indium tin oxide in applications where radius of curvature falls below 3 millimeters.
China's MEE enforcement of volatile organic compound emission ceilings is shuttering solvent-based coating lines in Guangdong and Jiangsu provinces. Manufacturers are retooling for aqueous nanowire deposition or relocating capacity to inland zones with looser enforcement. Japanese suppliers with established aqueous chemistry expertise are capturing displaced contract volumes from solvent-dependent competitors.
Display laminators are consolidating procurement around adhesive-integrated film stacks that reduce delamination defects during high-temperature autoclave bonding. This specification tightening favors suppliers with in-house polymer substrate and pressure-sensitive adhesive capabilities. The shift is most visible in South Korea's Gyeonggi-do cluster where Samsung Display and LG Display have synchronized incoming material specifications.
Asia-Pacific Transparent Conductive Films Market Segmentation
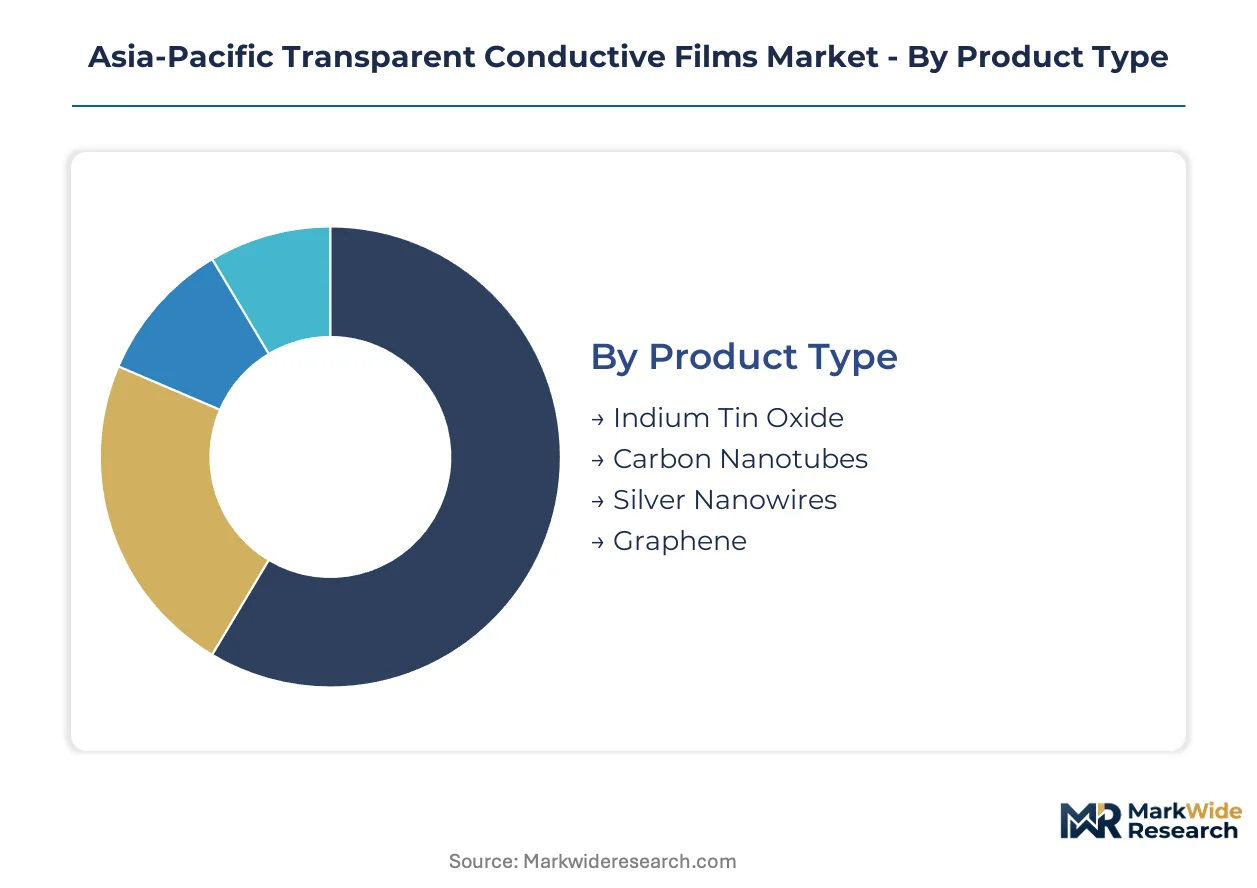
Material chemistry and deposition technology choices in the Asia-Pacific transparent conductive films market determine eligibility for specific OEM qualification pipelines. Segment boundaries are hardening as Chinese GB standards, Japanese JIS adhesion protocols, and Korean KATS flexural certifications diverge.
Product Type:
Domestic consumption across China, Japan, and South Korea favors silver nanowires and graphene for flexible applications, while indium tin oxide maintains export-oriented volume to Southeast Asian assembly operations.
- Indium Tin Oxide:Sputtered metal oxide coatings deliver optical transmittance above 80 percent with sheet resistance below 100 ohms per square. Chinese display manufacturers consume the bulk of regional ITO target volume for rigid touchscreen production, though Japan's METI circular content mandates are forcing indium recovery investments that compress margins.
- Silver Nanowires:Percolating filament networks conduct current under tensile strain exceeding 100,000 bending cycles. Korean panel makers in Gyeonggi-do province are integrating these films into foldable OLED stacks at pilot scale, displacing ITO where curvature radius falls below 3 millimeters.
- Carbon Nanotubes:Randomly oriented nanotube mats hit conductivity floors near 50 ohms per square, freezing them out of large-area interactive whiteboard specifications.
- Graphene:Single-atom carbon layers transmit visible light while attenuating radio frequency interference in premium aerospace applications awaiting manufacturing scale economics.
Indium tin oxide holds the largest share; momentum sits with silver nanowires.
Application:
Volume concentration tracks display manufacturing cluster locations, with margin distribution favoring automotive and solar segments where certification barriers limit supplier competition.
- Touchscreen Displays:Capacitive sensor electrodes in smartphones, tablets, and monitors represent the dominant demand vector. Chinese OEMs in Shenzhen and Dongguan are validating rollable prototypes that force substrate suppliers to certify bending tolerance beyond 100,000 cycles.
- Solar Cells:Heterojunction architectures in Chinese gigafactories are testing transparent conductive oxide replacements that tolerate processing temperatures above polymer substrate limits. Sputtered films dominate where uniformity directly correlates with photovoltaic conversion efficiency.
- OLED Displays:Flexible organic light-emitting diode stacks require electrode interfaces that maintain conductivity under repeated flexure.
- Automotive Displays:Curved touchscreen films for vehicle cabins must satisfy South Korean MFDS and KATS safety certifications that gate market access.
Touchscreen displays generate the highest unit volumes; solar cells are climbing the fastest on capacity expansion in Chinese renewable energy zones.
End User:
Procurement patterns split between high-volume consumer electronics with thin margins and regulated sectors where certification investments sustain pricing power.
- Consumer Electronics:Smartphone and tablet manufacturers in China's Pearl River Delta drive aqueous ink migration as MEE volatile organic compound ceilings shutter solvent-based coating lines in Guangdong province.
- Automotive:Display laminators in South Korea's Gyeonggi-do cluster are consolidating procurement around adhesive-integrated film stacks that reduce delamination defects during autoclave bonding.
- Aerospace:Avionics electromagnetic shielding applications in Japan favor graphene film stacks where optical clarity must coexist with radio frequency interference attenuation.
- Renewable Energy:Photovoltaic manufacturers in Jiangsu and Zhejiang provinces are testing roll-to-roll compatible transparent conductors for heterojunction cell metallization.
Consumer electronics commands the dominant revenue pool; aerospace offers the steepest margin structure.
Technology:
Capital intensity and throughput rates determine geographic distribution, with high-investment sputtering concentrating in Japanese and Korean facilities while roll-to-roll lines proliferate across Chinese coastal provinces.
- Physical Vapor Deposition:Vacuum-based coating delivers atomic-level film uniformity required for solar cell metallization. Japanese equipment suppliers dominate the installed base, though Chinese manufacturers are qualifying domestic alternatives to reduce import dependency.
- Roll-to-Roll Processing:Continuous web coating enables kilometer-scale production of flexible films for touchscreen displays. China's aqueous nanowire ink transition is retooling Guangdong and Jiangsu lines, with Japanese suppliers capturing displaced volumes from solvent-dependent competitors.
- Sputtering:Ionized gas deposition of metal oxides retains margin concentration in photovoltaic applications where thickness uniformity directly impacts cell efficiency.
- Printing:Direct patterning of conductive inks offers cost advantages for large-area applications where feature tolerance permits lower resolution.
Roll-to-roll processing dominates unit output; physical vapor deposition captures the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual carbon targets across China and South Korea are redirecting public procurement toward low-carbon film chemistries, while Japan's METI efficiency mandates compress legacy indium tin oxide margins. These policy vectors are reshaping manufacturing footprints and supplier qualification pipelines throughout the region.
China
Touchscreen OEMs in Shenzhen and Dongguan are validating rollable smartphone prototypes that demand substrate bending tolerance beyond 100,000 cycles. The MEE enforces volatile organic compound ceilings on solvent-based coating lines in Guangdong and Jiangsu provinces, compelling aqueous nanowire ink migration. Display laminators in the Pearl River Delta are consolidating procurement around adhesive-integrated film stacks.
Japan
Automotive and aerospace end-users in Nagoya and Osaka prioritize electromagnetic shielding performance in premium avionics applications. METI mandates circular material content ratios in electronics components, pressuring manufacturers to recover indium from spent sputtering targets. Polymer substrate specialists in the Chubu region leverage roll-to-roll expertise to supply flexible film architectures.
South Korea
Display panel makers in Gyeonggi-do province are integrating silver nanowire films into foldable OLED stacks at pilot scale. The MFDS and KATS coordinate safety certifications that gate market access for curved touchscreen films in vehicle cabins. Samsung Display and LG Display have synchronized incoming material specifications around adhesive-layer integration requirements.
Australia
Medical device manufacturers are qualifying conductive films for surgical display applications where biocompatibility certification sustains pricing power. The TGA is streamlining approval pathways for optoelectronic components in regulated healthcare environments. Procurement concentrates in Sydney and Melbourne medical technology clusters.
Taiwan
Semiconductor packaging specialists are testing transparent conductive oxides for heterojunction solar cell metallization in Hsinchu Science Park facilities. Equipment suppliers qualify domestic alternatives to reduce import dependency on Japanese physical vapor deposition systems. The island's precision manufacturing base supports high-uniformity sputtering applications.
Asia-Pacific Transparent Conductive Films Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with polymer substrate expertise and nanowire chemistry specialists competing on wet-process formulation. Market structure exhibits moderate concentration, with Japanese and Korean incumbents anchoring premium-tier supply and Chinese challengers scaling aqueous ink capacity. Three archetypes dominate: integrated substrate-adhesive suppliers, nanowire ink formulators, and sputtering target recyclers. Competitive moves center on backward integration into captive coating capacity and cross-border qualification partnerships with display laminators.
Within the integrated substrate tier, Toyobo Co., Ltd. and Nitto Denko Corporation exemplify Japanese conglomerates combining polymer film manufacturing with pressure-sensitive adhesive capabilities. Cambrios Technologies Corporation occupies a position among nanowire chemistry specialists focused on wet-process deposition methods. These three entities represent distinct strategic postures: conglomerate diversification, materials science specialization, and process chemistry innovation.
| Leading Market Players |
|---|
| Toyobo Co., Ltd. |
| Cambrios Technologies Corporation |
| Nitto Denko Corporation |
| Canatu Oy |
| C3Nano |
| Teijin Limited |
| Gunze Ltd. |
| AGC Inc. |
| TDK Corporation |
| Others |
Value Chain & Pricing Dynamics
Kilometer-scale roll-to-roll coating lines in Guangdong province generate steep scale economies that compress unit costs for aqueous nanowire inks while simultaneously concentrating procurement leverage among Chinese display laminators. This capacity clustering shapes price floors across the Asia-Pacific transparent conductive films market, as Japanese and Korean suppliers must absorb logistics premiums or localize coating assets to remain contract-eligible.
Pricing Analysis
Certification level (KATS flexural standards versus GB transparency specifications) creates the primary spread between premium Korean automotive display films and economy-tier Southeast Asian assembly inputs. Three-tier pricing structure across premium, standard, and economy levels reflects adhesive-layer integration depth and bending cycle tolerance. Cost compression in standard-tier indium tin oxide films is intensifying because Chinese smelter export quotas inject raw material volatility. Consumer electronics OEMs in Shenzhen exhibit the highest price sensitivity, while aerospace integrators in Nagoya accept substantial premiums for electromagnetic shielding performance.
Supply Chain Analysis
China and South Korea anchor transparent conductive film manufacturing, with Japanese suppliers feeding specialized polymer substrates and pressure-sensitive adhesives. The supply chain draws from indium concentrate refined at Chinese smelters, silver nanowire inks formulated in Gyeonggi-do province, and PET substrates extruded in the Chubu region. Single-source vulnerability concentrates in primary indium refining, where export quota disruptions propagate within one quarter to sputtering target availability. Distribution runs through display laminator consolidation in the Pearl River Delta and Gyeonggi-do cluster, with secondary channels serving Southeast Asian assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transparent conductive films are becoming a platform layer where substrate-adhesive-nanowire interoperability determines ecosystem lock-in, comparable to how display driver IC standardization reshaped panel procurement. Korean and Chinese OEMs are synchronizing incoming material specifications, compressing the vendor base eligible for high-volume contracts.
For Market Incumbents: Secure backward integration into captive aqueous nanowire ink production to offset margin compression from Chinese MEE volatile organic compound enforcement. Defend contract eligibility by qualifying films simultaneously against GB, JIS, and KATS standards, eliminating the cost burden of maintaining three distinct product variants. Carbon nanotube formulations from emerging Korean entrants threaten standard-tier positioning; counter by deepening adhesive-layer integration expertise that reduces delamination defects during autoclave bonding.
For New Entrants and Emerging Players: Anchor in Australia's surgical display segment where TGA biocompatibility certification creates a defensible pricing umbrella with limited incumbent presence. Target heterojunction solar cell metallization in Taiwan's Hsinchu Science Park, where domestic equipment qualification programs reduce dependency on Japanese physical vapor deposition systems. Pursue qualification partnerships with display laminators in South Korea's Gyeonggi-do cluster as the fastest path to foldable OLED stack integration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated substrate-adhesive suppliers with multi-year contracts to Samsung Display and LG Display, as specification synchronization locks in procurement relationships. Long-term viability over the analysis window hinges on aqueous chemistry expertise and circular material recovery capabilities mandated by Japan's METI. Target acquisition archetypes include nanowire ink formulators with proprietary wet-process rheology and roll-to-roll coating assets in Chinese coastal provinces. The signal to watch is qualification timeline acceleration for silver nanowire films in foldable OLED stacks, indicating inflection from pilot to mass production.
| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Ink Migration | Chinese MEE enforcement shutters solvent lines, favoring suppliers with wet-process chemistry expertise. |
| Adhesive-Integrated Film Stacks | Samsung Display and LG Display specifications reduce delamination defects during high-temperature autoclave bonding. |
| Circular Material Recovery | Japan's METI mandates force indium recovery investments from spent sputtering targets, compressing legacy ITO margins. |
| Cross-Border Qualification Partnerships | Display laminators consolidate procurement around vendors certified to GB, JIS, and KATS standards simultaneously. |
| Medical Device Certification | Australia's TGA streamlines biocompatibility pathways for surgical display applications with pricing power. |
Study Parameters
Initial hypotheses were tested against primary input from display laminator procurement directors, aqueous ink formulation chemists, sputtering target recycling operators, and automotive display certification engineers, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of customs records, SEC filings from diversified chemical conglomerates, KATS certification databases, and Chinese environmental compliance disclosures. Bottom-up triangulation across deposition technology capacity installations and top-down reconciliation against end-use demand from smartphone OEMs and solar cell manufacturers anchored volume estimates.
Variance decomposition across material chemistry, application segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type (indium tin oxide, silver nanowires, carbon nanotubes, graphene), application (touchscreen displays, solar cells, OLED displays, automotive), end user (consumer electronics, automotive, aerospace, renewable energy), and technology (physical vapor deposition, roll-to-roll processing, sputtering, printing). CAGRs were derived from elasticity-adjusted demand curves and capacity expansion pipelines. Industry-specific forecast inputs incorporated Chinese dual carbon policy implementation timelines and Korean foldable OLED production ramp schedules.
Decision-makers should treat outputs as directional under assumptions of continued MEE enforcement intensity and stable indium concentrate export flows; material deviation in either driver would warrant model refresh. Specific risks that could revise forecasts include abrupt tariff escalation on Chinese-coated films, breakthrough graphene manufacturing scale economics, or suspension of KATS-MFDS automotive certification reciprocity. Recalibration cycles align with material shifts in regulatory enforcement intensity and display form factor adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Sapphire Substrate Market