
 Gallium Market | 2026-2036
Gallium Market Size, Share, and Industry Trends Forecast 2026-2036
Gallium Market Analysis
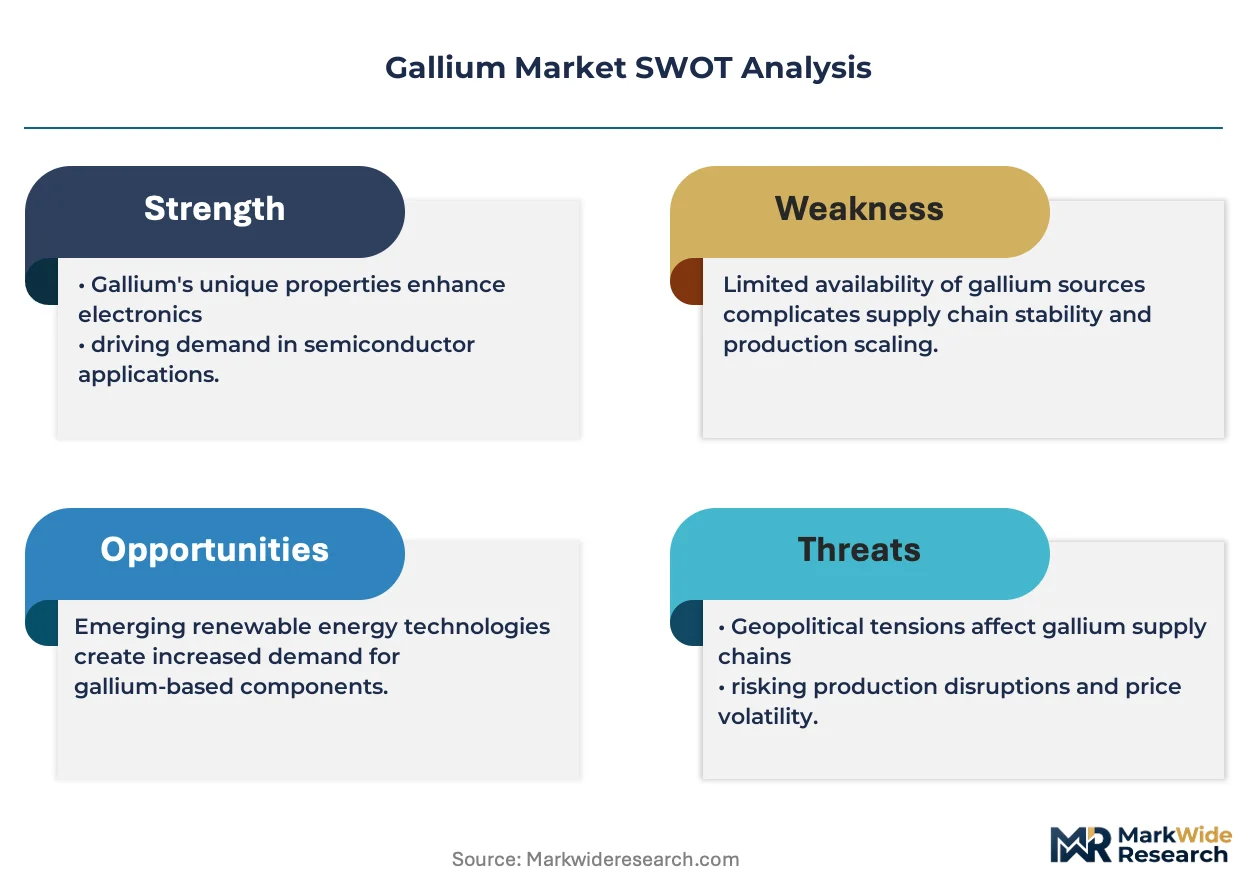
Semiconductor-grade purity thresholds is redrawing competitive boundaries in the gallium market. DOWA Holdings Co. Ltd leverages vertical integration from bauxite residue to high-purity metal, sustaining margin capture across the value chain. Nanjing Jinmei Gallium Co. Ltd anchors Chinese domestic supply through captive refining infrastructure, while Aluminum Corporation of China Limited dominates feedstock access via integrated aluminum smelting operations.
Gallium is a soft, silvery post-transition metal extracted primarily as a byproduct of bauxite and zinc ore processing, typically refined to 4N-7N purity grades for electronic applications where its low melting point and direct bandgap compounds enable high-frequency and optoelectronic devices. Gallium Nitride leads power electronics and RF amplification segments where thermal performance requirements exceed silicon capabilities, while Gallium Arsenide retains mature dominance in satellite and defense optoelectronics despite slower volume expansion. Gallium Oxide emerges as the fastest-growing product category for next-generation power semiconductors targeting electric vehicle inverters and grid infrastructure.
China's MIIT governs strategic mineral stockpiling and export licensing, while the United States leverages IRA provisions and Department of Commerce entity restrictions to reshape supply chain geography for defense-critical gallium compounds. REACH registration requirements in Europe constrain import pathways for unregistered gallium derivatives, compressing market access for non-compliant traders. Stakeholders must monitor export licensing thresholds and regional purity certification standards as procurement patterns fragment across geopolitical blocs.
Market Dynamics
Semiconductor-grade purity thresholds are redrawing competitive boundaries as Gallium Nitride power devices penetrate electric vehicle inverters and 5G infrastructure, forcing feedstock suppliers to upgrade refining capabilities or exit high-margin segments entirely.
Growth Catalysts
- Dual carbon goals:China's MIIT mandates carbon intensity reductions across aluminum smelting, the primary gallium feedstock source, accelerating investment in energy-efficient refining infrastructure that captures previously vented byproduct metal.
- 5G base station deployment:RF amplification requirements in millimeter-wave arrays exceed silicon thermal limits, pulling 6N-7N purity gallium through compound semiconductor foundries serving telecommunications infrastructure buildouts.
- Export licensing regimes:Tightened Department of Commerce entity restrictions on critical minerals processing equipment are prompting defense contractors to qualify alternative gallium arsenide suppliers outside traditional supply corridors.
Market Restraints
- Bauxite residue dependency:Gallium extraction remains tethered to aluminum production economics, with primary smelter curtailments in Henan and Shandong directly compressing feedstock availability regardless of semiconductor demand.
- REACH registration barriers:Unregistered gallium derivatives face compressed market access across EU member states, constraining import pathways for traders lacking ECHA-compliant substance dossiers.
- Silicon carbide substitution:Automotive power electronics suppliers are parallel-qualifying silicon carbide MOSFETs for 800V architectures, creating price ceilings that limit gallium oxide penetration in premium inverter segments.
Strategic Opportunities
- Gallium oxide epitaxy:Next-generation power semiconductors targeting grid infrastructure and heavy-duty electric vehicle inverters represent white space where material properties exceed both silicon and Gallium Nitride thermal performance thresholds.
- Domestic refining capacity:IRA domestic content bonuses for clean energy supply chains are incentivizing North American bauxite residue processing investments that bypass concentrated East Asian refining nodes.
- Optoelectronics convergence:Defense satellite programs are integrating Gallium Arsenide laser diodes with silicon photonics platforms, creating hybrid procurement specifications that favor suppliers with multi-material epitaxy capabilities.
Industry Challenges
- Epitaxial growth technician scarcity:Compound semiconductor fabrication requires specialized MOCVD reactor operators, with training pipelines lagging capacity expansion timelines at new foundry facilities.
- Purity certification timelines:Aerospace and defense qualification protocols for 7N-grade material extend 18-24 months, delaying revenue recognition for upgraded refining investments.
- Legacy substrate integration:Power module manufacturers face thermal expansion coefficient mismatches when bonding Gallium Nitride devices to traditional copper-baseplate architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallium Market |
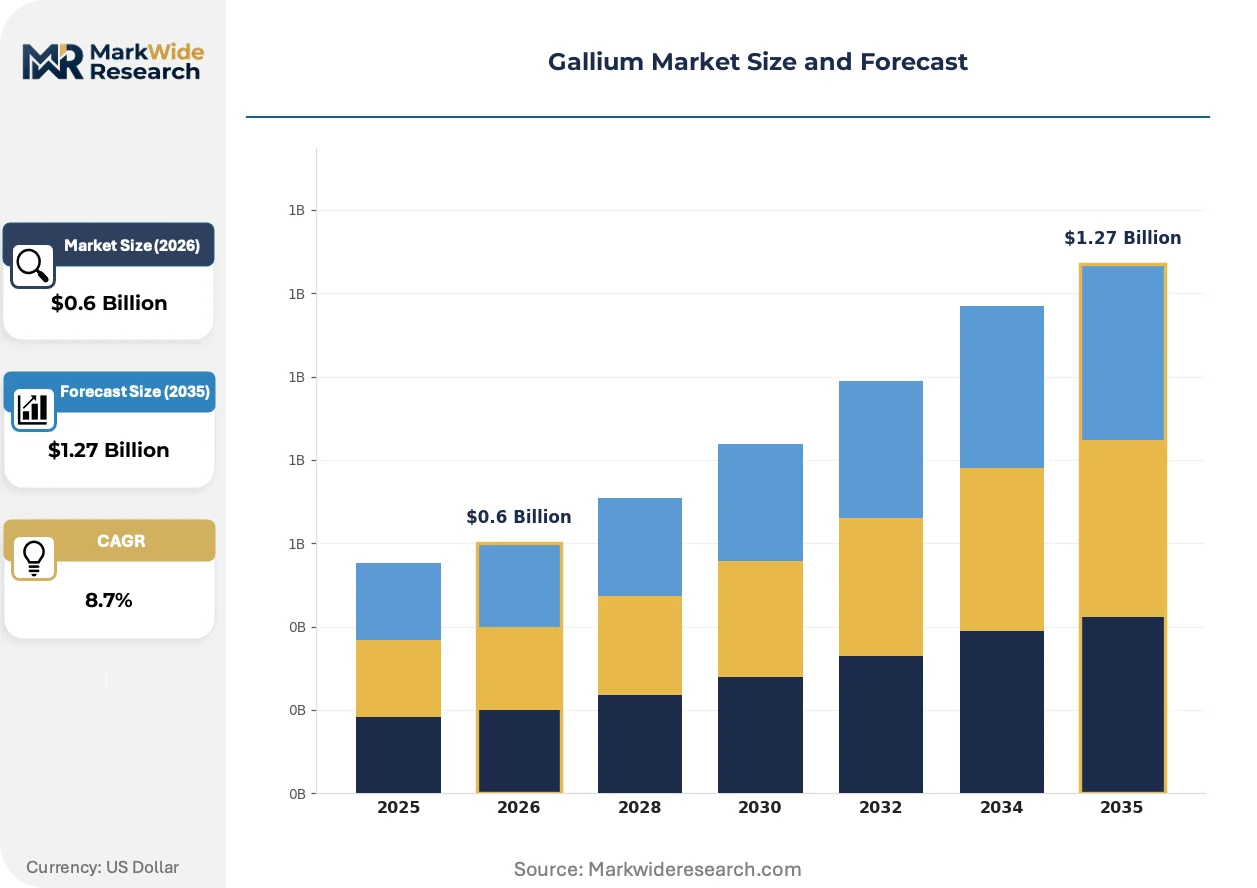
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gallium Metal, Gallium Arsenide, Gallium Nitride, Gallium Oxide Application: Electronics, Optoelectronics, Solar Energy, Pharmaceuticals End User: Aerospace, Automotive Suppliers, Healthcare, Electronics Manufacturers Distribution Channel: Direct Sales, Distributors, E-commerce, Retailers |
| Companies Covered | DOWA Holdings Co. Ltd, Nanjing Jinmei Gallium Co. Ltd, Aluminum Corporation of China Limited, Guizhou Kailin Group Co. Ltd, Zhuzhou Smelter Group Co. Ltd, CMOC Group Limited, East Hope Group, Yunnan Aluminium Co. Ltd, China Minmetals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallium Market Emerging Trajectories
Materials science advances and regulatory fragmentation are simultaneously enabling new application categories and complicating supply chain configuration for compound semiconductor manufacturers.
Gallium Nitride-on-silicon substrates are displacing legacy silicon LDMOS devices in cellular base station power amplifiers, with telecommunications equipment manufacturers in Japan and the United States accelerating design-in cycles for 3.5GHz and 28GHz bands. Base station original equipment manufacturers now specify GaN-on-SiC for macro cells and GaN-on-Si for small cells, creating tiered material demand that splits procurement strategies across purity grades.
China's MIIT export licensing framework for strategic minerals is tightening documentation requirements for gallium compound shipments, forcing non-Chinese importers to establish audited end-use verification protocols or face supply interruption. Defense-critical applications in the United States are responding through Department of Commerce strategic stockpile nominations and accelerated domestic refining partnerships with bauxite residue processors.
Long-term supply agreements are displacing spot market transactions as primary procurement vehicles for semiconductor-grade material, with compound semiconductor foundries in Seoul and Shanghai locking multi-year offtake commitments to secure allocation amid feedstock concentration. This contractual shift compresses trading margins for merchant metal distributors while transferring price volatility risk upstream to aluminum smelters with captive gallium recovery.
Gallium Market Segmentation
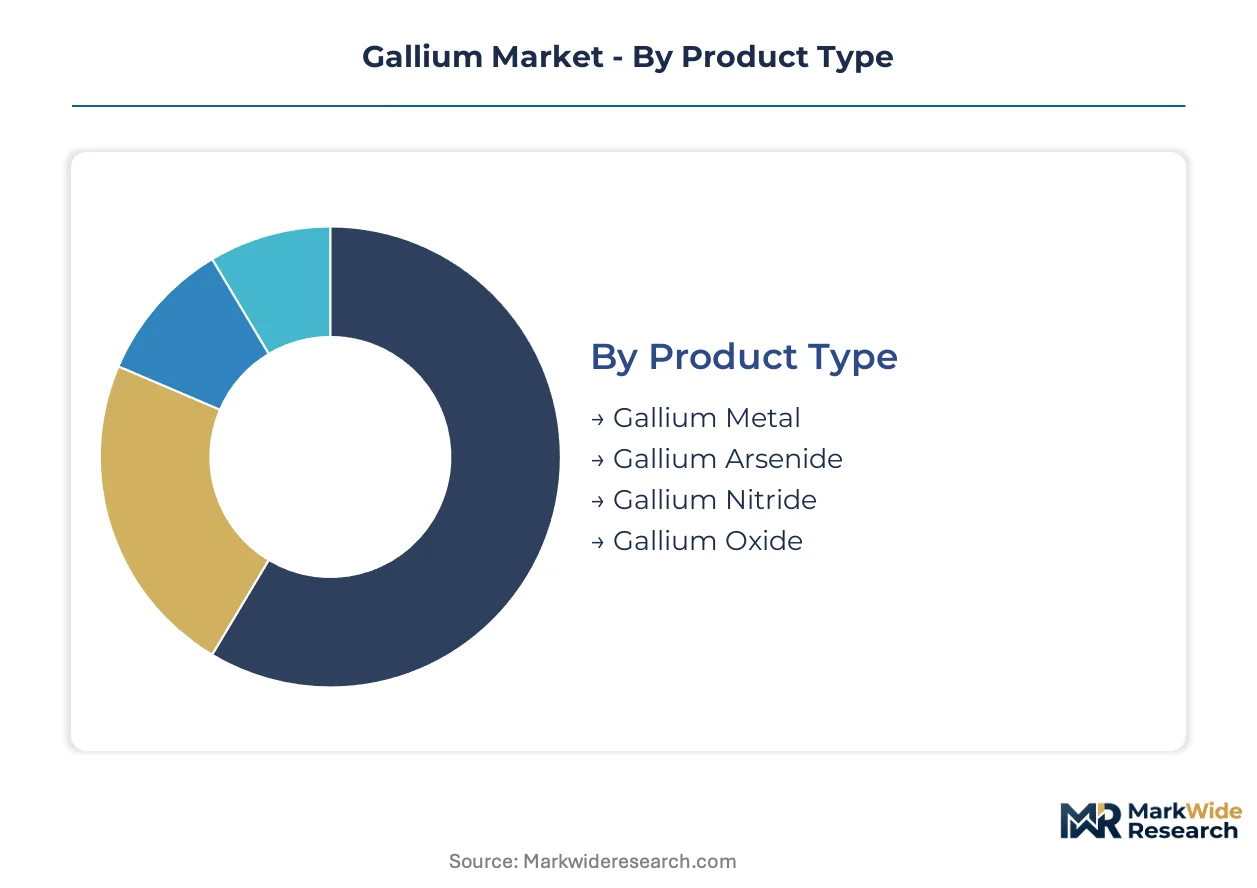
Product chemistry and end-use specifications fragment procurement requirements across the gallium value chain. Purity grades, compound formulations, and application-specific thermal tolerances create distinct supply corridors that resist standardization.
Product Type:
Substitution pressure from silicon carbide and emerging wide-bandgap materials hits hardest at the metal feedstock level, forcing compound producers to differentiate through epitaxial quality rather than commodity metal supply.
- Gallium Metal:Refined to 4N-7N purity grades from bauxite residue streams, serving as the foundational feedstock for all compound semiconductor manufacturing. Demand concentrates in East Asian electronics manufacturing clusters around Shanghai and Seoul, where compound foundries lock multi-year offtake agreements to secure allocation amid feedstock concentration.
- Gallium Arsenide:Direct bandgap III-V compound retaining mature dominance in satellite laser diodes and defense optoelectronics, specified for RF applications through 100GHz. Procurement from defense contractors in the United States is accelerating alternative supplier qualification outside traditional Chinese supply corridors under Department of Commerce entity restrictions.
- Gallium Nitride:Wide-bandgap semiconductor displacing silicon LDMOS in 5G base station power amplifiers and penetrating electric vehicle inverters where thermal performance exceeds silicon limits.
- Gallium Oxide:Ultra-wide-bandgap material emerging for next-generation power semiconductors targeting grid infrastructure and heavy-duty electric vehicle applications where material properties exceed both silicon and Gallium Nitride thermal thresholds.
Gallium Metal retains volume leadership; Gallium Oxide holds the steepest expansion curve.
Application:
Margin capture varies sharply by application tier, with defense and aerospace specifications commanding purity premiums that consumer electronics volumes cannot sustain.
- Electronics:RF amplification and power conversion devices in telecommunications infrastructure and computing hardware, where Gallium Nitride-on-silicon substrates displace legacy silicon across 3.5GHz and 28GHz cellular bands. Japanese and United States base station manufacturers now split procurement between GaN-on-SiC for macro cells and GaN-on-Si for small cells.
- Optoelectronics:Laser diodes, photodetectors, and optical communications components integrating Gallium Arsenide with silicon photonics platforms. Defense satellite programs in the United States are creating hybrid procurement specifications favoring suppliers with multi-material epitaxy capabilities.
- Solar Energy:Concentrated photovoltaic cells employing III-V multi-junction architectures for space and terrestrial high-efficiency installations.
- Pharmaceuticals:Specialized gallium compounds for diagnostic imaging and therapeutic applications, constrained by REACH registration requirements across EU member states.
Electronics commands the revenue base; Optoelectronics delivers the most durable margin premiums.
End User:
Customer concentration in East Asian manufacturing creates procurement asymmetry, with large electronics manufacturers extracting volume discounts that smaller aerospace and healthcare purchasers cannot match.
- Aerospace:Satellite and defense communication systems requiring 7N-grade material with 18-24 month qualification protocols. United States defense contractors are responding to China's MIIT export licensing tightening through Department of Commerce strategic stockpile nominations.
- Automotive Suppliers:Power module manufacturers qualifying Gallium Nitride and parallel silicon carbide MOSFETs for 800V electric vehicle architectures, creating price ceilings that limit gallium oxide penetration.
- Healthcare:Medical imaging equipment and radiopharmaceutical production, facing compressed import pathways for unregistered gallium derivatives under ECHA compliance requirements.
- Electronics Manufacturers:Compound semiconductor foundries in Seoul and Shanghai locking long-term supply agreements to bypass spot market volatility.
Electronics Manufacturers absorb the volume; Aerospace secures the purity premiums.
Distribution Channel:
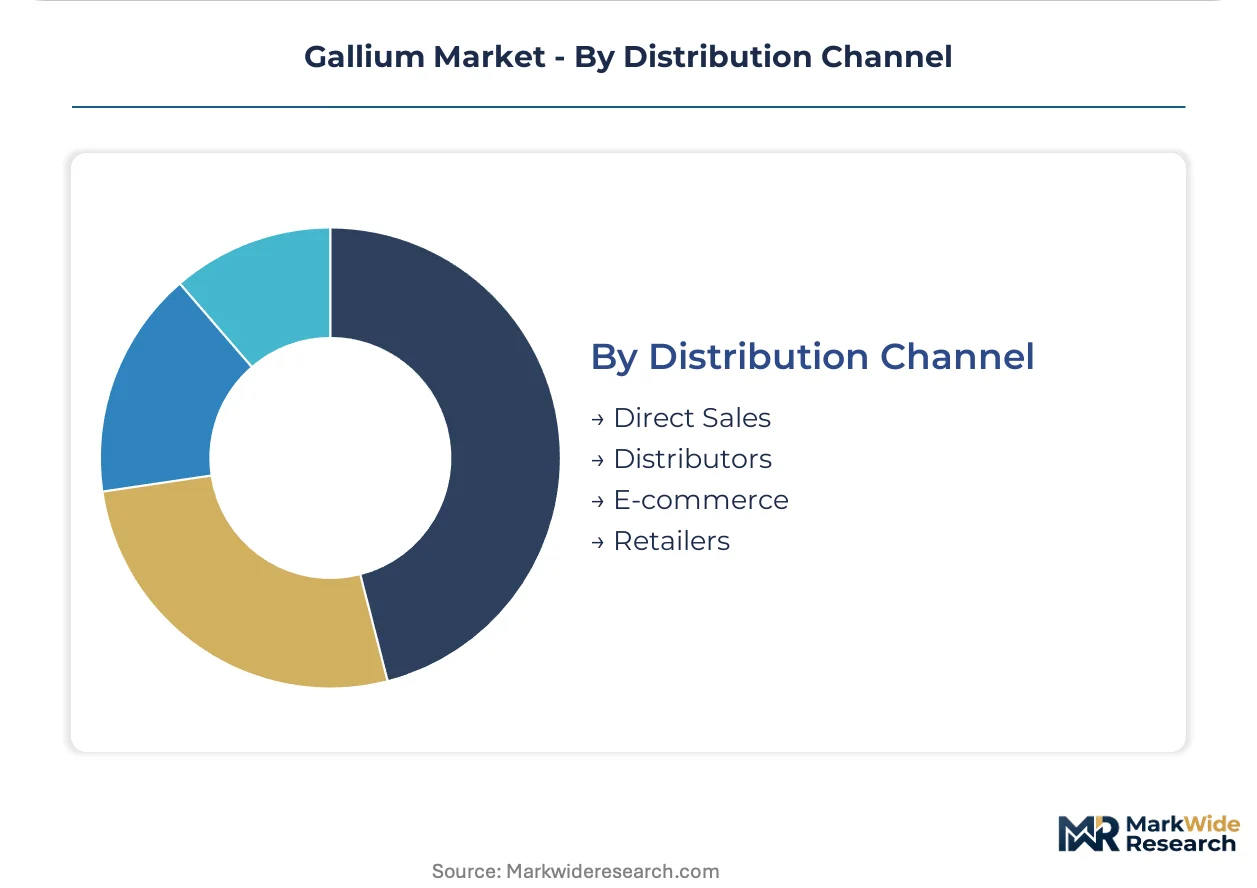
Channel selection tracks transaction scale and technical service requirements, with direct relationships dominating semiconductor-grade supply while distributors handle lower-purity industrial grades.
- Direct Sales:Long-term offtake agreements between aluminum smelters with captive gallium recovery and compound semiconductor foundries, transferring price volatility risk upstream while compressing margins for merchant metal distributors.
- Distributors:Regional metal traders handling 4N-5N purity grades for industrial applications, facing compressed market access across EU member states without ECHA-compliant substance dossiers.
- E-commerce:Small-volume laboratory and research supply transactions, limited by export licensing documentation requirements for strategic mineral shipments.
- Retailers:Minimal presence limited to educational and hobbyist gallium metal products.
Direct Sales anchors the value chain; E-commerce is gaining transaction velocity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary gallium recovery infrastructure clusters around aluminum smelting corridors, with secondary refining capacity concentrating in electronics manufacturing hubs. Feedstock dependency on bauxite processing geography shapes regional supply security calculations.
China
MIIT export licensing governs gallium compound shipments, tightening documentation requirements for semiconductor-grade material. Dual carbon goals mandate carbon intensity reductions across aluminum smelting in Henan and Shandong provinces. Nanjing Jinmei Gallium anchors domestic supply through captive refining infrastructure serving Shanghai-based compound foundries.
Japan
Telecommunications equipment manufacturers accelerate GaN-on-SiC design-in cycles for 5G macro cells and GaN-on-Si for small cells. METI strategic stockpile programs buffer against supply interruption from concentrated East Asian feedstock sources. Tokyo-Osaka electronics corridors host compound semiconductor foundries locking multi-year offtake agreements.
United States
Department of Commerce entity restrictions on critical minerals processing equipment prompt defense contractors to qualify alternative GaAs suppliers outside traditional supply corridors. IRA domestic content bonuses incentivize North American bauxite residue processing investments. Department of Defense strategic stockpile nominations reshape procurement patterns for aerospace-grade 7N material.
South Korea
Seoul-based compound semiconductor foundries concentrate demand for 6N-7N purity gallium through long-term supply agreements bypassing spot market volatility. MFDS pharmaceutical regulations constrain import pathways for diagnostic imaging compounds. Busan-Ulsan industrial clusters integrate gallium arsenide laser diodes with silicon photonics platforms for defense satellite programs.
Germany
ECHA REACH registration requirements compress market access for unregistered gallium derivatives across EU member states. Automotive power module manufacturers in Bavaria and Baden-Württemberg parallel-qualify GaN and SiC MOSFETs for 800V electric vehicle architectures. Frankfurt-Rhine-Main logistics hubs face documentation barriers for strategic mineral shipments from non-compliant traders.
Gallium Market Vendor Landscape
Concentration sits with aluminum smelters possessing captive gallium recovery infrastructure and compound semiconductor foundries with backward integration into high-purity refining. The vendor base splits between feedstock-anchored metal producers and epitaxy-specialized compound manufacturers. Three archetypes dominate: integrated aluminum-gallium operators, independent refiners with semiconductor-grade certification, and compound foundries with captive metal supply. Competitive moves center on capacity expansion in domestic refining corridors and strategic partnerships bypassing export licensing bottlenecks.
Among integrated operators, Aluminum Corporation of China Limited exemplifies feedstock dominance through aluminum smelting scale, while DOWA Holdings Co. Ltd occupies a position spanning bauxite residue to high-purity metal. Nanjing Jinmei Gallium Co. Ltd represents the independent refiner archetype with semiconductor-grade certification serving East Asian electronics clusters.
| Leading Market Players |
|---|
| DOWA Holdings Co. Ltd |
| Nanjing Jinmei Gallium Co. Ltd |
| Aluminum Corporation of China Limited |
| Guizhou Kailin Group Co. Ltd |
| Zhuzhou Smelter Group Co. Ltd |
| CMOC Group Limited |
| East Hope Group |
| Yunnan Aluminium Co. Ltd |
| China Minmetals Corporation |
| Others |
Supply Flow & Price Mechanics
Eighteen-month qualification timelines for 7N-grade aerospace material compress pricing power for merchant refiners while amplifying margin capture for integrated aluminum-gallium operators with captive semiconductor foundry relationships. Spot market liquidity for 4N-5N industrial grades evaporates as compound semiconductor manufacturers in Shanghai and Seoul lock multi-year offtake agreements, transferring price volatility risk upstream to bauxite residue processors.
Pricing Analysis
China's MIIT export licensing framework dictates the pricing tier structure across semiconductor-grade gallium compounds, separating audited end-use verification protocols from standard commercial shipments. Three-tier pricing stratifies across 7N aerospace certification, 6N telecommunications grade, and 4N-5N industrial purity levels, with carbon intensity compliance premiums emerging under dual carbon mandates. Cost compression in 4N feedstock intensifies because primary aluminum smelter curtailments in Henan directly constrain byproduct availability regardless of compound semiconductor demand. Defense contractors exhibit the lowest price sensitivity due to strategic stockpile nominations, while merchant distributors face margin erosion from contractual bypass.
Supply Chain Analysis
China and South Korea anchor gallium refining capacity, with Japan and the United States hosting compound semiconductor foundry demand clusters. Feedstock draws from bauxite residue streams at aluminum smelters in Henan and Shandong provinces, while MOCVD reactor equipment and high-purity chemical precursors rest on concentrated Japanese and German supplier bases. Single-source vulnerability runs through China's MIIT export licensing chokepoint for strategic mineral shipments. Distribution runs through long-term direct sales agreements between captive refiners and foundry customers, compressing spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium compounds are approaching a platform-economics inflection where GaN-on-SiC and GaN-on-Si substrate interoperability determines foundry switching costs and procurement consolidation. Defense-aerospace qualification protocols now function as ecosystem lock-in mechanisms that favor suppliers with multi-material epitaxy capabilities.
For Market Incumbents: Consolidate backward integration into bauxite residue processing corridors in North America to capture IRA domestic content bonuses and bypass MIIT export licensing exposure. Lock multi-year offtake agreements with Seoul and Shanghai foundries before silicon carbide substitution accelerates in 800V automotive architectures. Defensive capacity addition in domestic refining nodes protects margin position against feedstock concentration risk. For New Entrants and Emerging Players: Lead with gallium oxide epitaxy capabilities for grid infrastructure and heavy-duty electric vehicle inverters, where material properties exceed both silicon and GaN thermal thresholds. White space concentrates in North American bauxite residue processing investments serving defense-critical aerospace qualification. Go-to-market angle centers on bypassing traditional East Asian supply corridors through Department of Commerce strategic stockpile partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from aluminum majors with underutilized captive gallium recovery infrastructure and stranded refining assets outside semiconductor-grade certification pathways. Long-term viability frames around 5-10 year defense procurement cycles and clean energy supply chain reconfiguration. Signal to watch: MIIT export licensing threshold adjustments that force end-use verification protocol investments or trigger supply interruption.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Refining Capacity Expansion | IRA domestic content bonuses incentivize North American bauxite residue processing investments bypassing concentrated East Asian nodes. |
| Long-term Supply Agreement | Compound semiconductor foundries in Seoul and Shanghai lock multi-year offtake commitments to secure allocation amid feedstock concentration. |
| Backward Integration into Feedstock | Integrated aluminum-gallium operators capture margin across the value chain from bauxite residue to high-purity metal. |
| Certification Investment | Aerospace and defense qualification protocols for 7N-grade material extend revenue recognition timelines but create ecosystem lock-in. |
| Joint Venture for Epitaxy Capability | Hybrid procurement specifications favor suppliers with multi-material GaAs and silicon photonics epitaxy partnerships. |
Methodological Framework
A standing panel of compound semiconductor foundry procurement directors, aluminum smelter operations managers, MOCVD reactor technicians, and defense contractor supply chain leads provided ongoing calibration across primary fieldwork. Secondary validation drew from MIIT export licensing documentation, ECHA REACH registration databases, Department of Commerce entity restriction filings, and SEC 10-K disclosures from integrated aluminum-gallium operators. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value outputs.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework modeled purity grade tiers, compound chemistry formulations, end-use application specifications, and regional regulatory cluster segmentation. CAGRs derived from capacity expansion timelines, qualification protocol durations, and substitution elasticity parameters for silicon carbide and gallium oxide alternatives. Forecast inputs included aluminum smelter curtailment schedules and telecommunications infrastructure deployment cadence.
Forecasts assume regulatory continuity in China's MIIT licensing regime and United States Department of Commerce entity restrictions; material policy shifts would require re-modeling export pathway availability and domestic content bonus eligibility. Specific risks include REACH registration barrier tightening, silicon carbide MOSFET parallel-qualification acceleration, and epitaxial growth technician scarcity at new foundry facilities. Recalibration cycles align with material shifts in export licensing thresholds and strategic stockpile nomination patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Quartz Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Semiconductor Silicon Material Market