
 Niobium Hydride Market | 2026-2036
Niobium Hydride Market Size, Share, and Industry Trends Forecast 2026-2036
Niobium Hydride Market Insights
The EU Green Deal is restructuring niobium hydride procurement priorities across European aerospace supply chains. CBMM leverages captive niobium ore reserves to anchor its position in hydride precursor supply. Global Advanced Metals competes through R&D intensity in superconductor-grade powder refinement. H.C. Starck Solutions dominates specialty alloy channels with in-house hydrogenation capabilities.
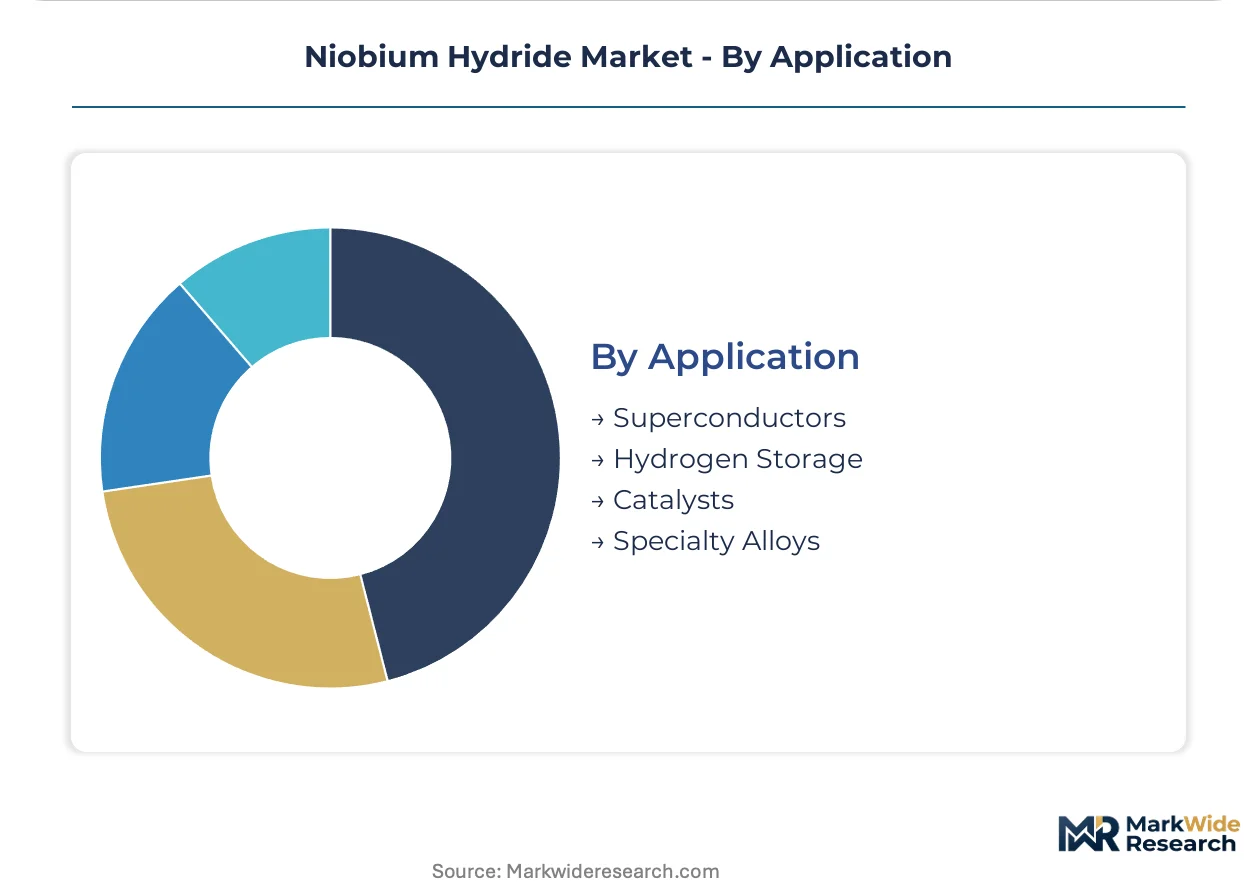
Niobium hydride is an intermetallic compound formed by direct hydrogenation of metallic niobium at elevated temperatures and pressures, typically yielding NbHx where x ranges from 0.7 to 1.0 depending on process conditions; it functions primarily as a hydrogen storage medium and superconductor precursor in advanced material systems. Niobium Hydride Powder leads product type revenue due to its versatility across hydrogen storage and catalyst applications, while Niobium Hydride Coatings represent the fastest-growing product category driven by thermal barrier demand in turbine engines. Superconductors command the largest application share through MRI magnet and particle accelerator procurement, whereas Hydrogen Storage is accelerating fastest as energy transition infrastructure scales.
FDA standards govern niobium hydride incorporation in medical imaging superconductors, REACH compliance dictates chemical handling across European production facilities, and China's GB standards enforce purity thresholds for hydrogen storage materials. Regulatory convergence on material traceability is elevating compliance costs for non-integrated producers. Stakeholders must weigh backward integration into hydrogenation capacity against specialized tolling partnerships as supply security becomes the decisive procurement criterion.
Market Dynamics
Aerospace superconductor procurement is tightening hydrogenation capacity constraints across the supply chain, forcing specialty alloy producers to secure captive niobium ore access or risk allocation shortfalls.
Growth Catalysts
- EU Green Deal restructuring:European aerospace supply chains are reconfiguring procurement priorities toward low-carbon hydrogen storage materials, pulling niobium hydride into strategic mineral lists.
- China's dual carbon goals:GB standards for hydrogen storage purity are tightening, creating compliant-supplier premiums for integrated producers with in-house hydrogenation.
- MRI magnet procurement:Superconductor-grade powder demand from medical imaging OEMs is accelerating as healthcare infrastructure expands in Germany and Japan.
Market Restraints
- Niobium ore concentration:Over 90 percent of global niobium supply originates from Brazilian hard-rock mines, creating single-source vulnerability for hydride precursor production.
- Hydrogenation capex intensity:High-pressure hydrogenation reactors require specialized pressure vessel certification and rare alloy construction, elevating entry barriers.
- REACH compliance friction:ECHA chemical handling mandates across European production facilities impose traceability costs that non-integrated tolling operators struggle to absorb.
Strategic Opportunities
- India hydrogen infrastructure:National hydrogen mission targets under the PLI scheme are creating first-mover openings for storage material suppliers establishing local tolling partnerships.
- Thermal barrier coatings:Niobium hydride coatings are penetrating turbine engine applications as OEMs seek higher-temperature superalloy protection.
- ISO standard convergence:Emerging international standards for superconductor-grade powder are enabling cross-border qualification shortcuts for certified producers.
Industry Challenges
- Superconductor-grade purification talent:The specialized metallurgical expertise required for particle accelerator specification powder remains concentrated in Germany and Japan, creating recruitment bottlenecks.
- FDA certification timelines:Medical imaging superconductor qualification cycles extend 18-24 months, compressing cash conversion for new entrants targeting MRI OEM supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Niobium Hydride Market |
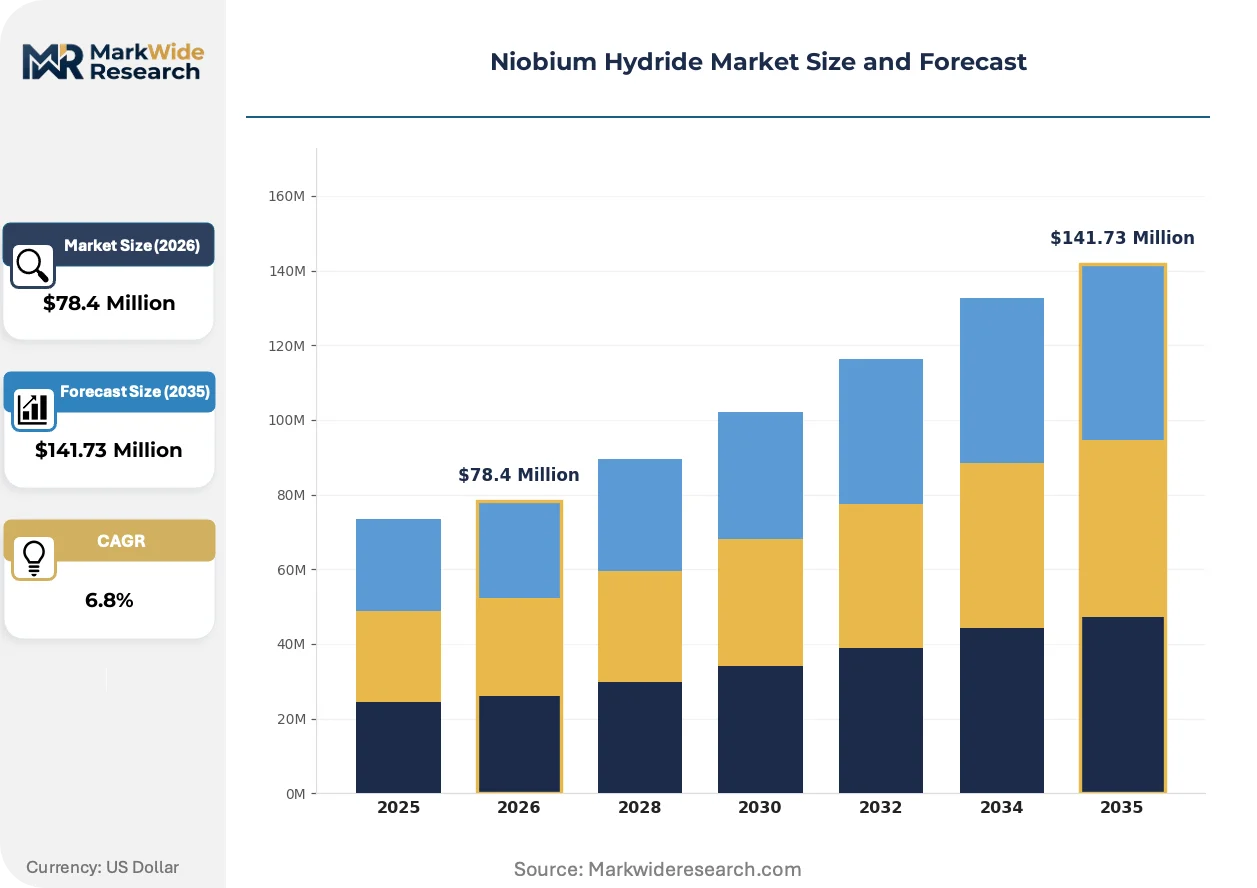
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Niobium Hydride Powder, Niobium Hydride Granules, Niobium Hydride Pellets, Niobium Hydride Coatings End Use Industry: Aerospace, Electronics, Automotive, Military Production Method: Hydrogenation, Reduction, Chemical Vapor Deposition, Synthesis Application: Superconductors, Hydrogen Storage, Catalysts, Specialty Alloys |
| Companies Covered | Global Advanced Metals, Niobec Inc., CBMM, China Minmetals Corporation, Taseko Mines Limited, Jiujiang Tanbre Co., Ltd., H.C. Starck Solutions, Tantalex Resources Corporation, NioCorp Developments Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Niobium Hydride Market Trends and Innovations
Process intensification in hydrogenation and powder refinement is compressing production cycles while regulatory harmonization is reshaping qualification pathways across aerospace and medical verticals.
Plasma-assisted hydrogenation is expanding into superconductor-grade niobium hydride production as an alternative to conventional high-pressure thermal methods. European specialty alloy producers are piloting this technology to reduce cycle times and improve hydrogen distribution uniformity. The process is expanding into applications previously reserved for particle accelerator specifications, enabling tier-2 suppliers to meet MRI magnet purity thresholds.
REACH chemical handling mandates are forcing European production facilities to implement closed-loop hydrogenation systems with real-time purity monitoring. The regulation is compressing tolling partnerships as non-integrated operators face capital requirements beyond their balance sheet capacity. Superconductor-grade powder producers in Germany are responding by consolidating hydrogenation capacity in-house rather than relying on third-party processors.
Long-term offtake contracting is displacing spot procurement in aerospace superconductor supply chains as OEMs seek allocation security. Tier-1 turbine engine manufacturers are locking in multi-year niobium hydride coating supply agreements directly with hydrogenation-capable refiners. This pattern is most visible in Japan, where METI critical mineral stockpiling incentives reinforce preference for contracted over transactional supply relationships.
Niobium Hydride Market Segmentation
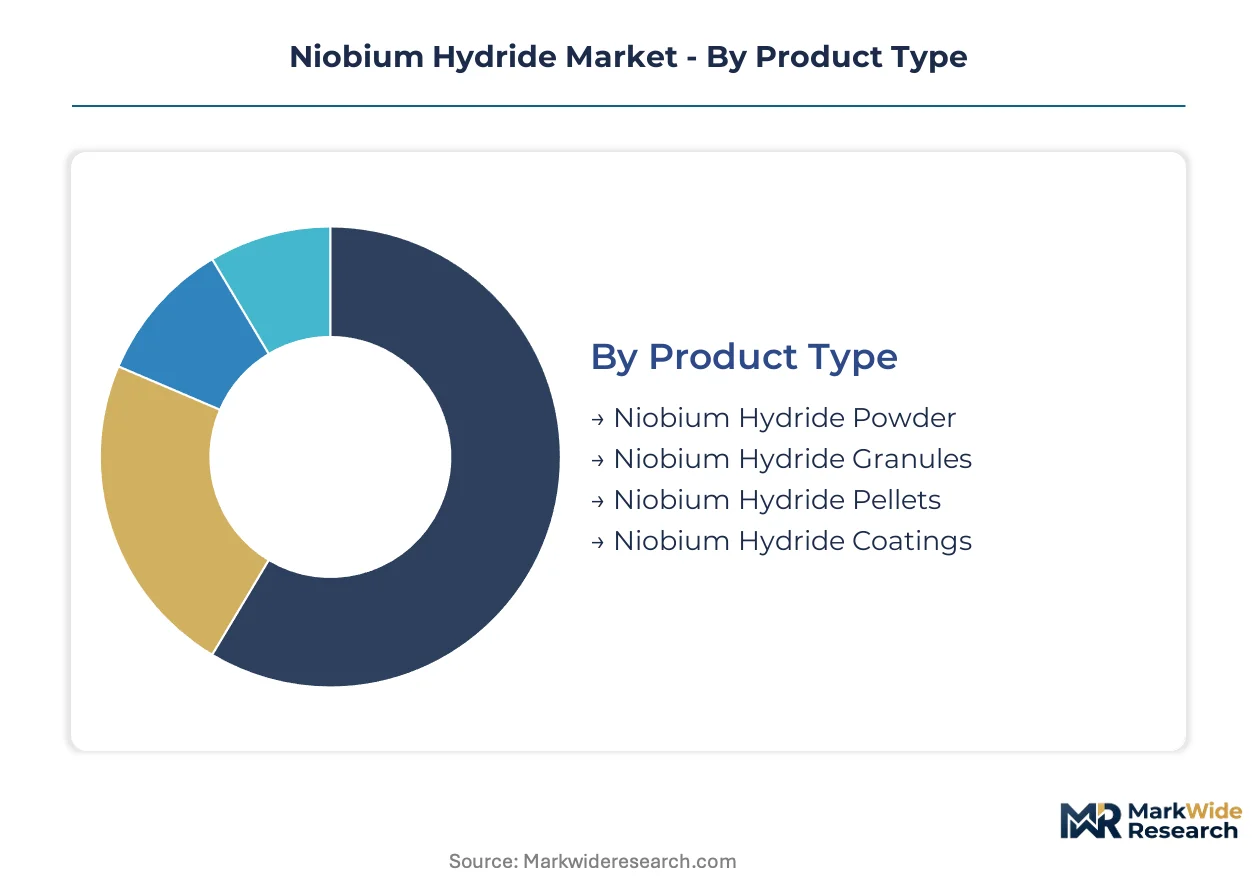
Niobium hydride procurement patterns diverge sharply between bulk material buyers and specification-grade consumers. Aerospace superconductor OEMs prioritize purity thresholds over unit economics, while hydrogen storage deployers optimize for surface area and absorption kinetics. Understanding these trade-offs across four segmentation dimensions clarifies where margin pools concentrate.
Product Type:
Volume applications favor commodity morphologies; premium specifications command powder and coating formats with tighter hydrogen distribution control.
- Niobium Hydride Powder:The dominant revenue format, this fine particulate enables versatile hydrogenation kinetics across catalyst beds and storage vessels. Demand concentrates in German specialty alloy procurement, where REACH-compliant handling infrastructure favors bulk powder tolling over integrated pellet production.
- Niobium Hydride Coatings:Thermal barrier deposition for turbine engine superalloys drives specification-grade demand. Japanese aerospace OEMs are locking in multi-year coating supply agreements directly with hydrogenation-capable refiners, bypassing traditional distributor channels.
- Niobium Hydride Granules:Intermediate particle size suits fixed-bed reactor applications where powder fluidization risks entrainment losses.
- Niobium Hydride Pellets:Compressed morphology optimizes volumetric density for transportable hydrogen storage systems under China's tightening GB purity standards.
Mature deployment sits with Niobium Hydride Powder. Newer deployment is concentrated in Niobium Hydride Coatings.
End Use Industry:
Application maturity determines qualification timelines and contract structures across buyer categories.
- Aerospace:Superconductor magnet procurement for MRI systems and particle accelerators demands 18-24 month FDA certification cycles. Tier-1 turbine manufacturers are displacing spot buying with long-term offtake contracts for thermal barrier coating feedstock.
- Electronics:Thin-film superconductor deposition for quantum computing substrates requires ultra-high-purity hydride precursors. Japanese electronics clusters are consolidating supplier qualifications around METI-critical mineral stockpiling incentives.
- Automotive:Hydrogen storage material demand is accelerating under EU Green Deal low-carbon procurement mandates for fuel cell vehicle components.
- Military:Specialty alloy specifications for aerospace structural applications prioritize domestic hydrogenation capacity over cost optimization.
Contracted volume concentrates in Aerospace. Fastest share gains are emerging in Automotive.
Production Method:
Process selection locks in capital intensity and regulatory exposure for the operating lifespan of hydrogenation assets.
- Hydrogenation:Direct high-pressure thermal reaction of metallic niobium remains the baseline method. European producers are piloting plasma-assisted variants to compress cycle times and improve hydrogen distribution uniformity for superconductor-grade output.
- Reduction:Oxide-to-hydride conversion offers alternative feedstock flexibility where niobium metal availability tightens.
- Chemical Vapor Deposition:Enables conformal coating thickness control for turbine blade thermal barrier applications requiring sub-micron precision.
- Synthesis:Bottom-up molecular assembly approaches are emerging for quantum device precursor materials with atomically defined stoichiometry.
Established capacity sits with Hydrogenation. Emerging qualification activity is concentrating in Chemical Vapor Deposition.
Application:
Performance specifications and regulatory oversight intensity vary dramatically across use cases.
- Superconductors:MRI magnet and particle accelerator procurement commands the largest application share. FDA standards govern medical imaging incorporation, while ISO convergence on powder qualification is enabling cross-border certification shortcuts for German and Japanese producers.
- Hydrogen Storage:Energy transition infrastructure scaling is pulling demand upward fastest. China's dual carbon goals are tightening GB standards for storage material purity, creating compliant-supplier premiums for integrated hydrogenation operators.
- Catalysts:Petrochemical hydrogenation process applications favor powder morphology with optimized surface-area-to-volume ratios.
- Specialty Alloys:Niobium hydride serves as controlled hydrogen source for precipitation-hardened superalloy microstructures in aerospace turbine casting.
Certified volume anchors Superconductors. Steepest expansion trajectory is appearing in Hydrogen Storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Brazilian mining districts while consumption clusters in German specialty alloy foundries and Japanese aerospace manufacturing corridors. This geographic mismatch shapes procurement strategies across the value chain. Regulatory divergence between REACH-mandated European handling protocols and China's tightening GB purity standards is fragmenting supplier qualification pathways.
Brazil
CBMM's captive niobium ore reserves in Minas Gerais anchor global hydride precursor supply. ANVISA chemical handling oversight governs export certification for medical-grade superconductor feedstock. The Araxá mining complex feeds hydrogenation-capable refiners in Germany and Japan through long-term offtake structures.
Germany
Specialty alloy procurement from H.C. Starck Solutions and plasma-assisted hydrogenation pilots drive superconductor-grade powder demand. ECHA REACH mandates enforce closed-loop hydrogenation systems with real-time purity monitoring. The Ruhr industrial corridor concentrates tolling partnerships for aerospace superconductor qualification.
Japan
METI critical mineral stockpiling incentives reinforce multi-year coating supply agreements with turbine engine OEMs. JIS standards govern superconductor-grade powder specifications for MRI magnet procurement. The Nagoya aerospace cluster locks in direct refiner relationships, bypassing traditional distributor channels.
China
Dual carbon goals and GB standards for hydrogen storage purity create compliant-supplier premiums for integrated hydrogenation operators. MIIT oversight enforces traceability for energy transition infrastructure materials. The Yangtze River Delta concentrates hydrogen storage deployment under national hydrogen mission targets.
United States
FDA certification timelines for medical imaging superconductor qualification extend 18-24 months, compressing cash conversion for new entrants. EPA chemical handling protocols intersect with aerospace procurement from domestic specialty alloy channels. The Greater Boston quantum computing cluster drives ultra-high-purity hydride precursor demand for thin-film superconductor deposition.
Niobium Hydride Market Competitive Landscape
The competitive structure tilts toward ore-integrated refiners with captive hydrogenation capacity. Brazilian mining-hydrogenation conglomerates and German-Japanese specialty alloy processors form a two-tier supply base. Strategic archetypes include ore-captive vertical integrators, tolling-dependent refiners, and superconductor-grade purification specialists. Dominant competitive moves center on backward integration into hydrogenation assets and long-term offtake contracting with aerospace OEMs.
Among ore-integrated producers, CBMM exemplifies the captive-supply archetype through its Minas Gerais mining-hydrogenation complex. H.C. Starck Solutions occupies a position within the European specialty alloy tier, representing in-house hydrogenation capabilities. Global Advanced Metals anchors the R&D-intensive refinement segment, sitting within the superconductor-grade powder qualification pathway.
| Leading Market Players |
|---|
| Global Advanced Metals |
| Niobec Inc. |
| CBMM |
| China Minmetals Corporation |
| Taseko Mines Limited |
| Jiujiang Tanbre Co., Ltd. |
| H.C. Starck Solutions |
| Tantalex Resources Corporation |
| NioCorp Developments Ltd. |
| Others |
Pricing and Supply Chain Analysis
Brazilian ferroniobium export price indices cascade through niobium hydride supply chains, compressing margins for non-integrated refiners while ore-captive producers capture value across hydrogenation tiers. Spot volatility in Araxá mining district concentrates pricing power with CBMM and its tolling partners in Germany and Japan.
Pricing Analysis
Superconductor-grade powder purity thresholds anchor value-based pricing for MRI magnet and particle accelerator applications. Three-tier pricing structure across superconductor-grade, specialty alloy-grade, and industrial-grade separates FDA-certified producers from REACH-compliant tolling operators and commodity hydride suppliers. Cost compression in industrial-grade powder is intensifying because Brazilian ore-captive producers are expanding hydrogenation capacity. Hydrogen storage deployers exhibit highest price sensitivity due to GB standard compliance costs, while aerospace OEMs prioritize allocation security over unit economics.
Supply Chain Analysis
Niobium metal feedstock rests on Brazilian hard-rock mining districts, German specialty alloy foundries, and Japanese aerospace manufacturing corridors. Hydrogenation reactor vessels, high-pressure certification systems, and superconductor-grade purification expertise constitute critical input dependencies. Single-source vulnerability pervades the upstream, with over ninety percent of global niobium supply originating from Minas Gerais ore bodies. Distribution runs through long-term offtake contracts directly between hydrogenation-capable refiners and tier-1 turbine engine OEMs, displacing spot procurement and traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma-assisted hydrogenation is displacing conventional high-pressure thermal methods across European and Japanese production facilities, compressing qualification timelines for superconductor-grade output. This technology transition favors integrated producers with balance sheet capacity for reactor retrofitting.
For Market Incumbents: Acquire hydrogenation reactor assets in the Ruhr industrial corridor and Nagoya aerospace cluster to consolidate captive capacity. Secure multi-year coating supply agreements with Japanese turbine engine OEMs before METI stockpiling incentives attract additional qualified suppliers. Invest in closed-loop hydrogenation systems with real-time purity monitoring to absorb REACH compliance costs that tolling-dependent competitors cannot match. Plasma-assisted process patents represent a defendable moat against emerging oxide-to-hydride reduction competitors. For New Entrants and Emerging Players: EU Green Deal low-carbon procurement mandates in Germany open a window for hydrogen storage material suppliers establishing tolling partnerships with REACH-compliant handling infrastructure. Target India's national hydrogen mission under the PLI scheme, where first-mover storage material suppliers can secure local tolling relationships before incumbent Brazilian producers extend hydrogenation capacity. Pursue automotive fuel cell component qualification as the most penetrable segment, leveraging ISO standard convergence for cross-border certification shortcuts. Position as compliant-supplier alternatives to integrated incumbents in China's tightening GB purity environment. For Investors and Strategic Acquirers: The window for entry favors ore-captive vertical integrators with demonstrated superconductor-grade powder qualification pathways. Long-term viability hinges on backward integration into hydrogenation assets rather than tolling-dependent models exposed to REACH capital requirements. Target acquisition archetypes include German specialty alloy processors with in-house hydrogenation and established FDA certification timelines, or Brazilian mining-hydrogenation conglomerates with captive ore reserves. Watch plasma-assisted hydrogenation pilot scale-up rates as the inflection indicator for process economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogenation Assets | Ore-captive producers with in-house high-pressure reactors capture margin pools from tolling-dependent refiners facing REACH compliance barriers. |
| Plasma-Assisted Hydrogenation Scale-Up | European pilot programs in Germany compress cycle times and improve hydrogen distribution uniformity for superconductor-grade powder output. |
| Long-Term Offtake Contracting with Aerospace OEMs | Japanese turbine engine manufacturers lock in multi-year coating supply agreements directly with hydrogenation-capable refiners, bypassing distributors. |
| REACH-Compliant Closed-Loop System Investment | German producers consolidate hydrogenation capacity in-house rather than relying on third-party processors facing ECHA chemical handling mandates. |
| India Tolling Partnership Establishment | National hydrogen mission targets under the PLI scheme create first-mover openings for storage material suppliers before incumbent expansion. |
Research Methodology
Independent corroboration across hydrogenation plant managers, specialty alloy procurement leads at German aerospace OEMs, distribution channel partners in Japanese electronics clusters, and superconductor-grade R&D directors underwrites the qualitative findings. Primary interviews with niobium mining operations executives, REACH compliance officers at European refiners, and MRI magnet procurement managers at medical imaging OEMs combined with secondary validation from ANVISA export certification records, ECHA chemical handling mandate filings, METI critical mineral stockpiling disclosures, and SEC 10-K filings from listed niobium processors. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Rate-of-change decomposition across the analysis window separates volume drivers from price-mix effects in superconductor-grade powder, specialty alloy feedstock, and hydrogen storage material segments. Product type, end-use industry, production method, and application dimensions structured the analytical framework, with regional regulatory clusters overlaying geographic splits. CAGRs derived from segment-level growth rate reconciliation against macro hydrogen infrastructure deployment trajectories and aerospace superconductor procurement cycles. Forecast inputs incorporated plasma-assisted hydrogenation pilot data, FDA certification timeline distributions, and GB standard compliance cost curves.
The model assumes a particular technology adoption path; alternative pathways for solid-state hydrogen storage or high-temperature superconductor wire would alter the outlook. Forecasts reflect assumptions regarding REACH enforcement intensity, METI stockpiling incentive continuity, and Chinese dual carbon goal implementation pace. Regulatory reversal in any major geography, breakthroughs in alternative superconductor materials, or Brazilian mining disruption represent specific risk factors that could revise projections. A small set of named triggers—plasma hydrogenation commercialization rates, India PLI scheme allocation outcomes, and ISO standard convergence timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Indium Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Semiconductor Silicon Wafer Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Barium Titanate Market