
 Infrared Laser Night Vision Devices Market | 2026-2036
Infrared Laser Night Vision Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Laser Night Vision Devices Market Insights
Defense procurement channels is reconfiguring as national security agencies consolidate vendor lists and mandate domestic sourcing quotas. L3Harris Technologies Inc. leverages its vertically integrated supply chain for weapon sights sold to U.S. special operations units. Elbit Systems Ltd. anchors its position in the Middle East through localized production partnerships. Leonardo S.p.A. competes on European tender processes with CE-marked infrared systems.
Infrared laser night vision devices employ near-infrared or short-wave infrared laser illuminators coupled to image intensifier tubes or digital sensors, typically operating at wavelengths between 780 and 1,064 nanometers for covert illumination without visible signature. These systems enable detection, recognition, and identification of targets in zero-ambient-light environments for military, law enforcement, and maritime operators. Rifle-mounted devices dominate procurement volumes among military forces due to squad-level modernization programs, while quantum cascade laser technology represents the fastest-growing segment as manufacturers pursue extended-range identification beyond two kilometers. Fiber laser architectures command premium margins in maritime navigation applications where salt corrosion resistance and beam stability justify higher unit economics.
The U.S. FDA regulates laser eye-safety classifications under 21 CFR 1040.10, directly constraining emitter power thresholds for devices sold to law enforcement and outdoor enthusiasts. European market access requires CE marking under the RoHS directive and compliance with the EU AI Act for digitally fused night vision systems incorporating target recognition algorithms. Military end users must navigate ITAR-controlled export licensing administered by the U.S. State Department and parallel regimes administered by France's DGAC and Germany's BAFA. Stakeholders should monitor divergence between U.S. and European eye-safety standards as this friction threatens interoperability for multinational defense procurement frameworks.
Market Dynamics
Solid-state laser architectures are compressing product development cycles as defense primes abandon legacy diode supply chains for gallium nitride emitters with tighter beam coherence.
Growth Catalysts
- NATO squad modernization:Rifle-mounted device procurement accelerates across member state special operations forces seeking zero-ambient-light target engagement capability.
- RoHS directive compliance:European defense tenders now mandate lead-free solder and restricted substance thresholds, advantaging CE-marked suppliers with pre-certified manufacturing lines.
- Quantum cascade laser maturation:Extended-range identification beyond two kilometers opens maritime navigation and border surveillance applications previously served by thermal imagers.
Market Restraints
- Rare-earth magnet dependency:Neodymium and dysprosium supply chains concentrate in Chinese processing facilities, exposing Western OEMs to export quota volatility.
- ITAR licensing friction:U.S. State Department controls delay re-export authorization for multinational defense frameworks, fragmenting procurement timelines.
- Eye-safety power ceilings:FDA 21 CFR 1040.10 Class 3B limits constrain emitter output for law enforcement devices, compressing effective range versus military variants.
Strategic Opportunities
- Indian paramilitary modernization:Central Reserve Police Force and Border Security Force procurement channels remain underpenetrated by Western suppliers due to domestic preference policies.
- Fiber laser maritime retrofit:Salt-corrosion-resistant beam delivery systems command premium positioning in commercial shipping navigation aids as SOLAS compliance deadlines approach.
- EU AI Act algorithmic fusion:Digitally fused night vision with target recognition features creates compliance-mandated upgrade cycles for legacy analog intensifier tube inventories.
Industry Challenges
- Cleanroom assembly bottleneck:Image intensifier tube manufacturing requires ISO 14644-1 Class 7 environments, constraining capacity expansion to qualified defense contractors.
- Interoperability certification backlog:NATO STANAG 4370 environmental testing queues extend qualification timelines for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Laser Night Vision Devices Market |
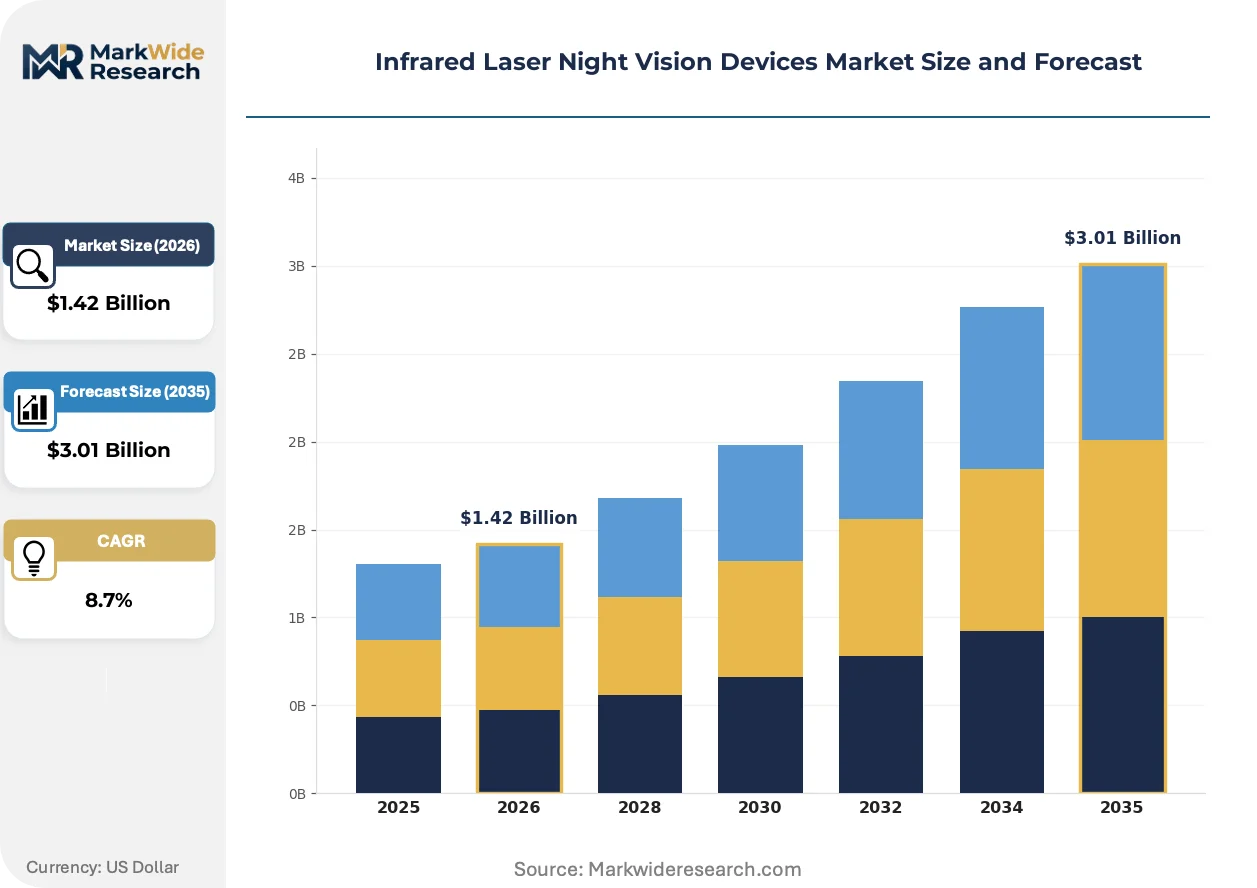
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scopes, Rifle-Mounted Devices, Binoculars, Monoculars, Weapon Sights Technology: Laser Diode, Solid-State, Fiber Laser, Vertical-Cavity Surface-Emitting Laser, Quantum Cascade Laser Application: Surveillance, Border Security, Wildlife Observation, Maritime Navigation, Search & Rescue End User: Military Forces, Law Enforcement, Private Security Firms, Outdoor Enthusiasts, Research Institutions |
| Companies Covered | Teledyne FLIR LLC, L3Harris Technologies Inc., Thales, BAE Systems, Elbit Systems Ltd., RTX, Northrop Grumman Corporation, Leonardo S.p.A., Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Laser Night Vision Devices Market Trends and Innovations
Three concurrent vectors are compressing traditional product lifecycles: emitter technology migration, regulatory algorithm mandates, and procurement channel consolidation toward prime contractors.
Digital sensor fusion is digitizing target engagement workflows by replacing analog image intensifier tubes with CMOS-based short-wave infrared arrays. U.S. special operations units field-test these systems for rapid target handoff to networked fire control. The shift compresses aftermarket tube replacement revenue while enabling software-defined feature upgrades through firmware.
REACH substance restrictions are forcing reformulation of optical coating chemistries across European supply chains. Manufacturers substitute perfluorinated compounds with silicon-based alternatives, extending qualification timelines by twelve to eighteen months. Maritime and aerospace applications face the steepest compliance burdens due to salt-fog and thermal cycling test requirements.
Defense agencies now bundle night vision procurement with multi-year sustainment contracts, displacing transactional spot purchasing. Prime contractors capture lifecycle value through captive repair depots and obsolescence management. This pattern concentrates most visibly in the U.S. defense corridor where Texas and Arizona-based integrators anchor regional supplier ecosystems.
Infrared Laser Night Vision Devices Market Segmentation
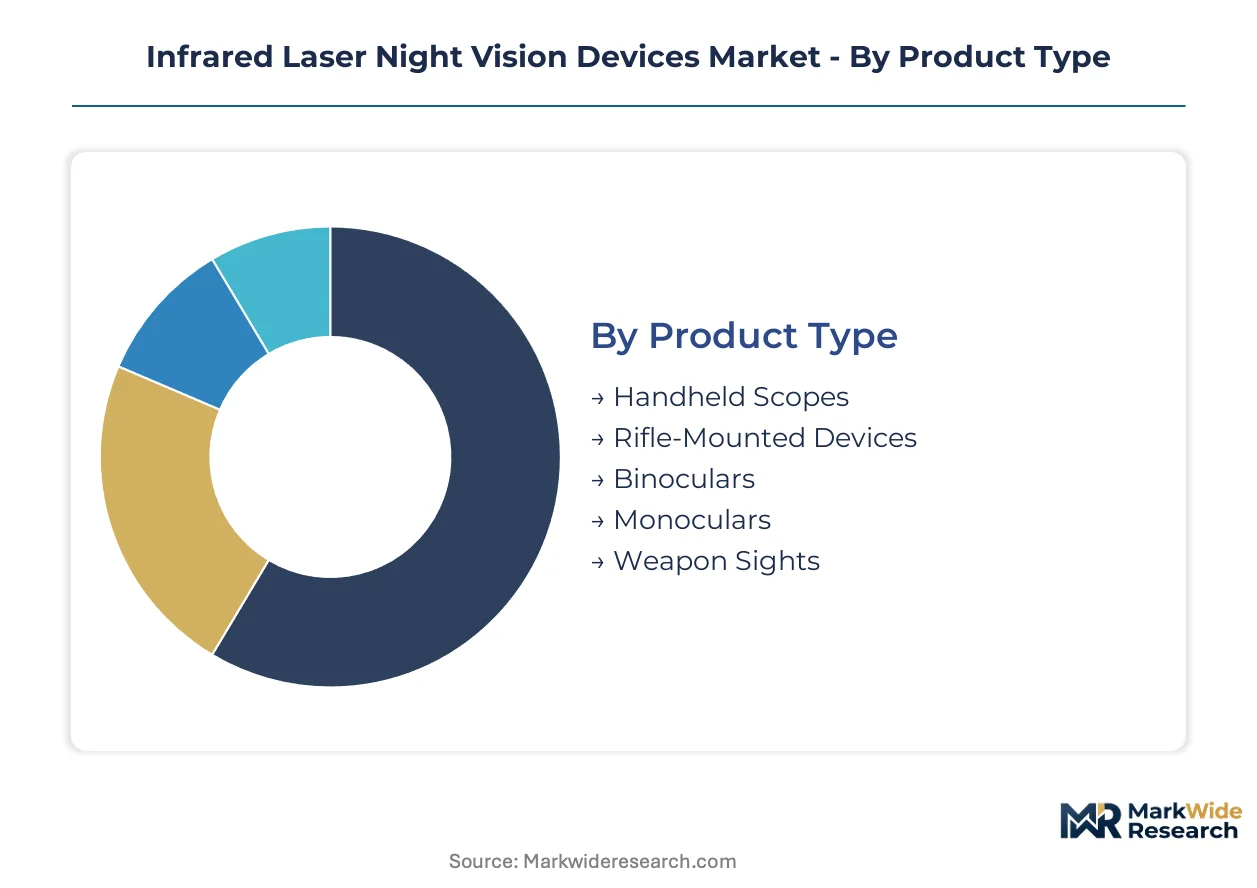
Segmentation in infrared laser night vision devices reveals divergent service lifecycle patterns across product architectures. Rifle-mounted systems demand intensive depot-level maintenance under military contracts, while handheld scopes follow transactional replacement cycles. Understanding these service intensity gradients informs aftermarket revenue capture and channel strategy design.
Product Type:
After-sales-service intensity varies sharply across form factors, with weapon-integrated systems requiring serialized tracking and armorer certification programs.
- Rifle-Mounted Devices:These systems integrate with firearm Picatinny rails and demand zero-retention calibration after each field deployment. U.S. special operations units in Texas and Arizona drive procurement through multi-year sustainment contracts with captive repair depots. NATO squad modernization programs concentrate demand in Germany, France, and Poland.
- Weapon Sights:Compact units with co-aligned laser emitters and ballistic compensation reticles serve designated marksman roles. Law enforcement agencies in Florida and California specify eye-safe Class 3R variants under FDA 21 CFR 1040.10 constraints, compressing effective range versus military Class 3B configurations.
- Handheld Scopes:Standalone observation units serve border patrol and wildlife monitoring with minimal maintenance requirements.
- Binoculars:Dual-tube designs dominate maritime navigation applications requiring depth perception for collision avoidance.
- Monoculars:Single-eyepiece formats reduce weight for extended dismounted patrols in mountainous terrain.
By volume, Rifle-Mounted Devices lead. By growth pace, Weapon Sights is ahead.
Technology:
Cost tier stratification separates legacy diode architectures from premium solid-state and fiber laser systems commanding three-to-five-fold unit price multiples.
- Solid-State:Gallium nitride emitters deliver tighter beam coherence and eye-safety margin under FDA and EU directives. German defense procurement mandates displace legacy diode inventories through RoHS-compliant manufacturing lines.
- Quantum Cascade Laser:Extended-range identification beyond two kilometers opens maritime navigation and border surveillance segments previously served by thermal imagers. Salt-corrosion-resistant packaging commands premium positioning in commercial shipping as SOLAS compliance deadlines approach.
- Fiber Laser:Beam delivery through silica fiber achieves thermal stability for continuous maritime operation.
- Laser Diode:Legacy edge-emitting architectures face phase-out under REACH substance restrictions.
- Vertical-Cavity Surface-Emitting Laser:Wafer-scale manufacturing reduces unit costs for high-volume law enforcement procurement.
By volume, Laser Diode retains installed base dominance. By margin expansion, Solid-State is accelerating most rapidly.
Application:
Customer type concentration shapes procurement channel structure, with defense agencies consolidating vendor lists while outdoor enthusiasts fragment across retail distribution.
- Surveillance:Fixed-site perimeter monitoring employs mast-mounted illuminators with 360-degree pan-tilt mechanisms. U.S. Customs and Border Protection installations across Texas and Arizona specify ITAR-controlled components with serialized chain-of-custody documentation.
- Maritime Navigation:SOLAS-mandated night vision for commercial shipping drives fiber laser adoption where salt-fog corrosion resistance justifies premium unit economics. German and Dutch shipyards anchor European demand clusters.
- Border Security:Mobile patrol units require rapid-deployment tripod systems for temporary observation posts.
- Wildlife Observation:Non-emitting passive observation dominates to avoid species disturbance.
- Search & Rescue:Helmet-mounted monoculars serve alpine and cave rescue teams with hands-free operation.
By volume, Surveillance leads procurement. By upgrade cycle frequency, Maritime Navigation is expanding most quickly.
End User:
Volume concentration among military forces contrasts with margin opportunity in restricted-access law enforcement channels requiring domestic sourcing compliance.
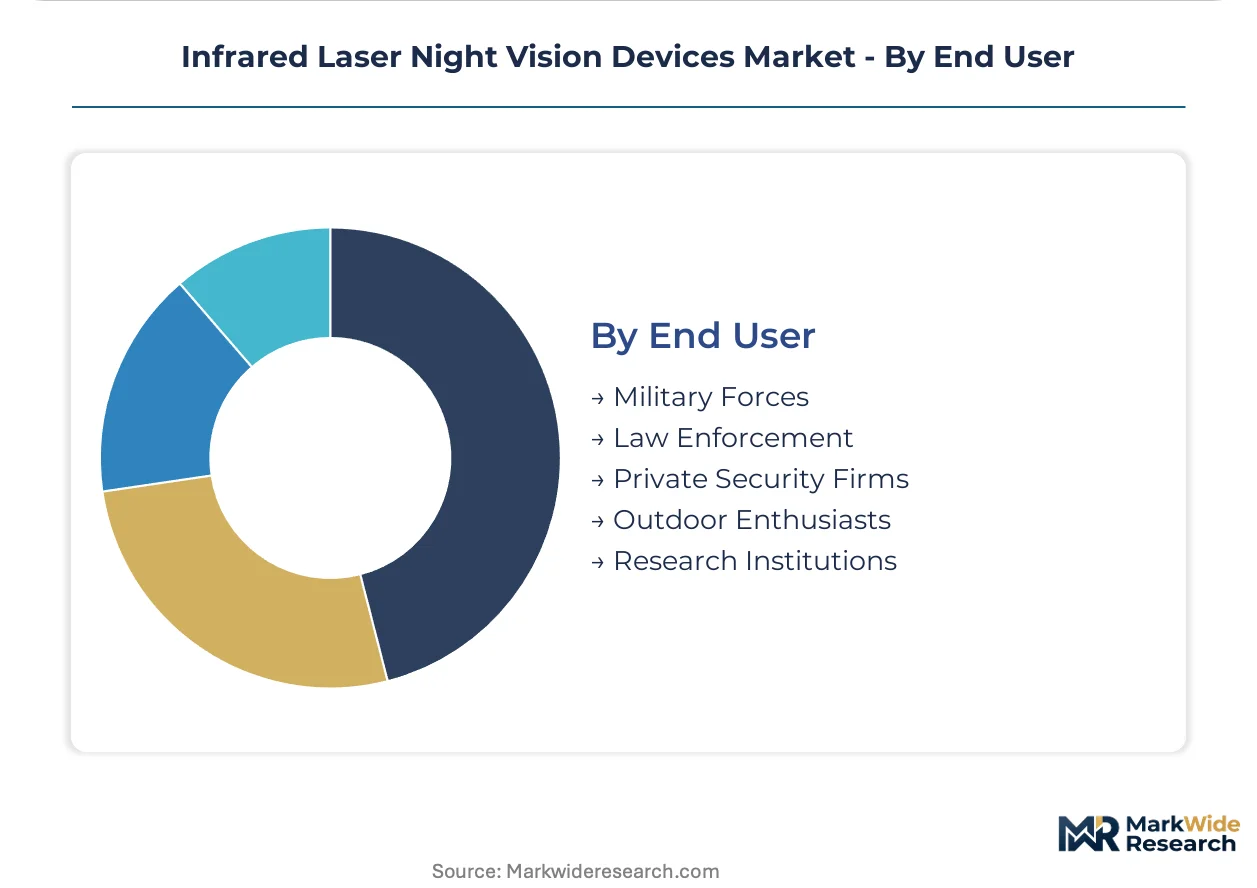
- Military Forces:Squad-level modernization across NATO member states drives rifle-mounted device procurement with multi-year obsolescence management contracts. U.S. Army and Marine Corps units in Texas, Arizona, and Florida anchor the defense corridor supplier ecosystem.
- Law Enforcement:Eye-safety power ceilings under FDA 21 CFR 1040.10 constrain emitter output, forcing closer engagement tactics. German state police procurement through BAFA licensing channels favors CE-marked European suppliers.
- Private Security Firms:Commercial guarding operations adopt refurbished military surplus to minimize capital outlay.
- Outdoor Enthusiasts:Consumer retail channels face price compression from Asian manufacturing imports.
- Research Institutions:Academic observatories require calibrated radiometric performance for atmospheric studies.
By volume, Military Forces dominates procurement. By channel margin, Law Enforcement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Norfolk Southern rail corridor and Port of Savannah logistics spine underpin U.S. defense distribution networks for night vision systems. German autobahn freight networks connect Dutch maritime terminals to Central European assembly plants. These infrastructure assets shape procurement velocity across NATO supply chains.
United States
Texas, Arizona, and Florida host concentrated special operations procurement through multi-year sustainment contracts. FDA 21 CFR 1040.10 eye-safety classifications constrain law enforcement variants while permitting higher-output military configurations. The Dallas-Fort Worth defense corridor anchors L3Harris Technologies Inc. vertically integrated manufacturing for rifle-mounted devices.
Germany
Bundeswehr squad modernization drives gallium nitride emitter adoption under tighter RoHS and REACH substance mandates. BAFA export licensing channels favor CE-marked domestic suppliers for intra-European defense frameworks. The Bavarian optics cluster around Munich hosts precision assembly operations for NATO STANAG-certified systems.
France
DGAC-controlled re-export regimes shape multinational procurement timelines for African and Middle Eastern deployments. The EU AI Act mandates algorithmic compliance for digitally fused target recognition systems entering service after 2025. Thales anchors production in the Île-de-France defense corridor with captive supply chains for image intensifier tubes.
United Kingdom
Strategic Command consolidation of vendor lists compresses supplier margins while extending contract durations. UK Export Control licensing parallels ITAR constraints for transatlantic interoperability programs. The Greater Bristol aerospace cluster hosts BAE Systems night vision integration for maritime navigation applications.
Israel
Border surveillance procurement prioritizes extended-range quantum cascade laser architectures for Negev and Golan Heights monitoring. Localized production partnerships circumvent ITAR friction for Middle Eastern end users. Elbit Systems Ltd. anchors manufacturing in the Central District with captive gallium nitride emitter fabrication.
Infrared Laser Night Vision Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in emitter and optical substrate supply. The vendor base stratifies between prime contractors capturing multi-year sustainment contracts and mid-tier specialists supplying subassemblies under fixed-price arrangements. Three archetypes dominate: vertically integrated defense primes with captive repair depots; regional champions leveraging domestic sourcing quotas; and technology licensors extracting royalties from second-source manufacturing agreements. Competitive moves concentrate on M&A for cleanroom assembly capacity and strategic partnerships for rare-earth magnet supply security.
Among U.S.-based defense primes, L3Harris Technologies Inc. and Northrop Grumman Corporation exemplify the vertically integrated archetype with regional supplier ecosystem control. Elbit Systems Ltd. represents the regional champion model through Middle Eastern production localization. Leonardo S.p.A. occupies a position bridging European tender compliance with CE-marked manufacturing scale.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| L3Harris Technologies Inc. |
| Thales |
| BAE Systems |
| Elbit Systems Ltd. |
| RTX |
| Northrop Grumman Corporation |
| Leonardo S.p.A. |
| Lockheed Martin Corporation |
| Others |
Pricing and Supply Chain Analysis
Cleanroom assembly undercapacity across Bavarian and Texan defense corridors is compressing supplier margins while amplifying pricing power for qualified ISO 14644-1 Class 7 facilities. Gallium nitride emitter fabrication bottlenecks simultaneously constrain volume scaling and sustain premium pricing for solid-state architectures.
Pricing Analysis
Volume-discount tiering separates military procurement lots exceeding ten thousand units from law enforcement spot purchases and outdoor enthusiast retail channels. Three-tier pricing structure across military-specification, agency-certified, and commercial-grade levels reflects ITAR compliance costs and eye-safety certification tiers under FDA 21 CFR 1040.10. Cost compression in commercial-grade segments is intensifying because Asian manufacturing imports flood consumer retail channels. Law enforcement agencies exhibit highest price sensitivity due to municipal budget cycles, while maritime navigation operators accept premium positioning for salt-corrosion-resistant fiber laser systems.
Supply Chain Analysis
Contract manufacturing concentration rests with L3Harris captive facilities in Texas, Thales integrated lines in Île-de-France, and Elbit Systems localized partnerships in Israel's Central District. Rare-earth magnet processing draws from Chinese neodymium and dysprosium facilities, while gallium nitride substrates source from Japanese and German foundries. Single-source vulnerability in rare-earth supply chains exposes Western OEMs to export quota volatility. Distribution runs through prime contractor depot networks rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through NATO procurement consolidation and multi-year sustainment contract bundling, fragmenting vendor access for mid-tier specialists.
For Market Incumbents: Entrench position through backward integration into gallium nitride emitter fabrication and captive cleanroom capacity expansion in Texas or Bavaria. Threat from quantum cascade laser substitutes demands accelerated R&D in extended-range identification algorithms. Certification investment for EU AI Act algorithmic compliance represents the critical defensive lever. For New Entrants and Emerging Players: Build out presence in Indian paramilitary channels where domestic preference policies have kept Western suppliers underpenetrated. The Central Reserve Police Force and Border Security Force procurement pipelines offer white-space opportunity. Go-to-market execution should anchor on localized production partnerships circumventing BAFA and DGAC licensing friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated primes with multi-year sustainment contracts and captive repair depots. Long-term viability across the analysis window favors acquisition targets with ISO 14644-1 Class 7 cleanroom certification and ITAR-compliant manufacturing lines. Signal to monitor: NATO STANAG 4370 environmental testing queue lengths as indicator of qualification backlog pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644-1 Class 7 qualification unlocks image intensifier tube manufacturing for NATO defense contracts. |
| Gallium Nitride Emitter Integration | Backward integration into solid-state laser fabrication reduces dependency on Japanese substrate suppliers. |
| EU AI Act Compliance Certification | Algorithmic validation for digitally fused target recognition systems mandates upgrade cycles across European inventories. |
| Rare-Earth Supply Partnership | Long-term offtake agreements with Australian or Canadian mining ventures mitigate Chinese export quota exposure. |
| Localized Production Joint Venture | Indian or Middle Eastern manufacturing partnerships circumvent ITAR and BAFA licensing delays for regional procurement. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with defense procurement officers, laser systems engineers, and maritime navigation equipment managers; and secondary validation through NATO tender databases, FDA 21 CFR 1040.10 regulatory filings, and EU AI Act implementation guidance. Bottom-up triangulation across product-level bill-of-materials costing and top-down reconciliation against national defense budget appropriations anchored volume estimates.
Forecast inputs considered squad modernization program timelines, RoHS and REACH substance restriction phase-in schedules, and SOLAS maritime compliance deadlines across the projection horizon. Segmentation modeling spanned product architecture, emitter technology tier, application intensity, and end-user procurement channel. CAGRs were derived from fitted growth curves against historical defense procurement cycles and technology substitution patterns.
Stress conditions across rare-earth export quota volatility, ITAR licensing delay scenarios, and cleanroom capacity expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of NATO STANAG 4370 testing queue lengths and BAFA re-export authorization timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Micro Computed Tomography Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Thermal Imaging Systems Market
Imaging
Embedded Smart Cameras Market
Imaging
Digitizer Market
Imaging
Global CMOS Image Sensors Market
Imaging
On-Chip Color Filters Market
Imaging
Handheld Retinal Scanners Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Contact Image Sensor Market
Imaging
Brain Imaging and Neuroimaging Market
Imaging
Camera Accessories Market
Imaging
Global Pathology Imaging Systems Market
Imaging
Gige Camera Market
Imaging
Short-Wave Infrared Imaging Market
Imaging
Wearable IP Camera Market