
 Surveillance Radar System Market | 2026-2036
Surveillance Radar System Market Size, Share, and Industry Trends Forecast 2026-2036
Surveillance Radar System Market Analysis
The gap between premium phased-array platforms and legacy mechanically-scanned systems is repositioning procurement patterns across defense ministries. Raytheon Technologies leverages captive gallium nitride foundry capacity to dominate next-generation active electronically scanned arrays. Thales anchors European maritime surveillance programs through sovereign radar manufacturing lines in France and the Netherlands.
Surveillance radar systems detect, track, and classify airborne, surface, or ground objects by transmitting radio frequency pulses and processing reflected echoes, with modern variants operating across X-band, S-band, and L-band frequencies from 1 GHz to 12 GHz for ranges exceeding 400 nautical miles. Aerospace applications sustain the largest revenue pool as airborne early warning platforms require multi-mode surveillance with simultaneous air-to-air and maritime search capabilities. Ground-based security installations represent the fastest-expanding segment as border agencies deploy counter-drone radar networks against small unmanned aerial system threats.
The FAA mandates Mode S transponder compatibility and ADS-B integration for all new civil surveillance radars entering US airspace, while the EU Green Deal pressures military contractors to reduce radar system power consumption and thermal footprints. NATO's STANAG 4607 standard for ground moving target indicator data exchange shapes coalition interoperability requirements across member procurement specifications. Stakeholders must monitor how dual-use technology export controls under Wassenaar Arrangement protocols affect cross-border subsystem sourcing for phased array antenna modules.
Market Dynamics
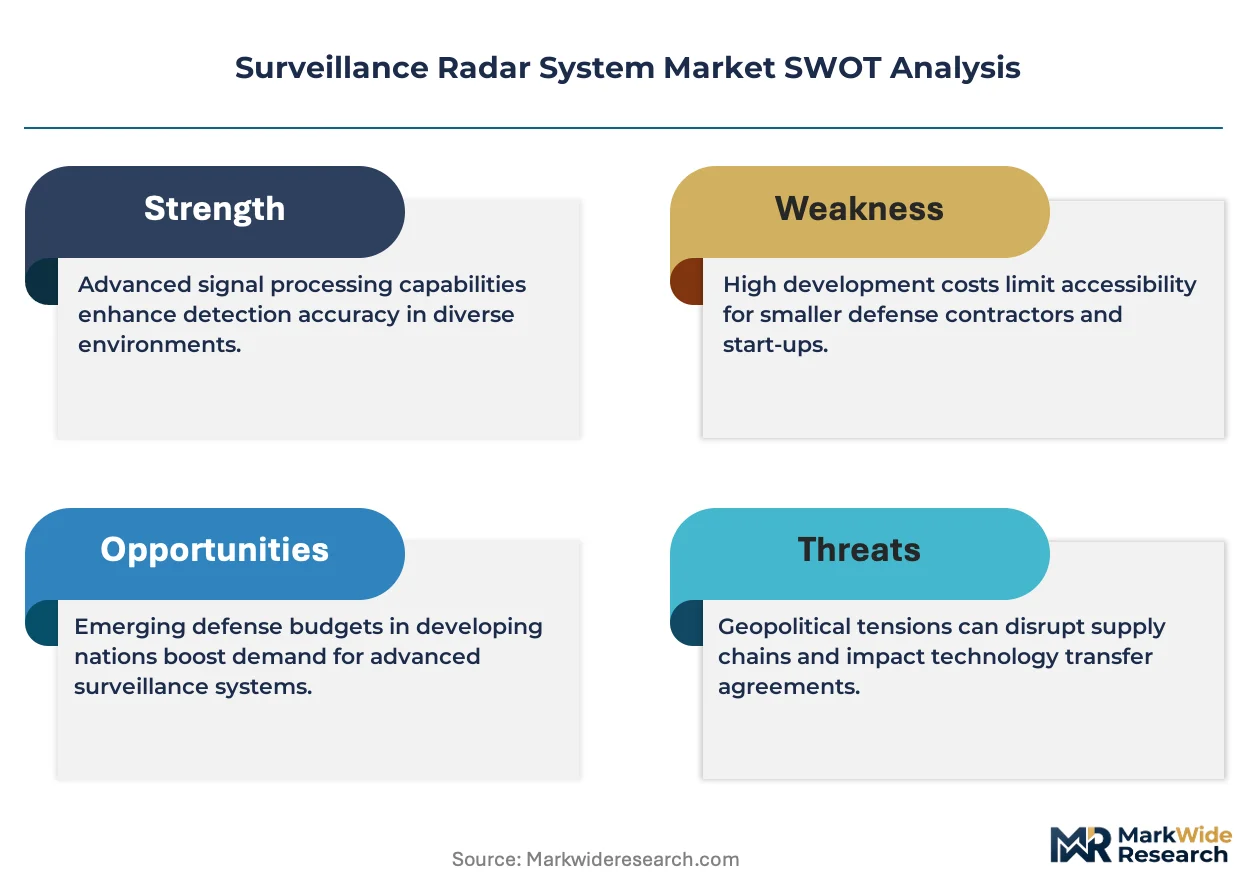
Solid-state gallium nitride transmitters are compressing unit economics while NATO interoperability mandates force architectural standardization across allied procurement programs.
Growth Catalysts
- Five-Eyes Intelligence Frameworks:Australia, the United Kingdom, and the United States mandate cross-compatible radar data formats, creating pooled demand for multi-mode surveillance platforms.
- FAA Mode S Mandates:Civil aviation authorities require ADS-B integration for all new airspace surveillance installations, forcing replacement cycles for aging ground-based radar networks.
- Counter-UAS Border Networks:Ground security agencies deploy short-range X-band systems against small drone threats, expanding the addressable application base beyond traditional military end-uses.
Market Restraints
- Gallium Nitride Substrate Concentration:Foundry capacity for high-purity GaN-on-SiC wafers concentrates among a handful of defense-qualified suppliers, creating input bottlenecks.
- Wassenaar Arrangement Controls:Dual-use technology export protocols restrict phased-array module transfers, fragmenting subsystem sourcing across national boundaries.
- Vacuum Tube Aftermarket Dependency:Legacy mechanically-scanned systems require specialized magnetron replacements, locking some operators into obsolete maintenance ecosystems.
Strategic Opportunities
- Maritime Domain Awareness Gaps:Coastal nations in Southeast Asia lack over-the-horizon radar coverage, creating demand for shore-based L-band installations with integrated AIS correlation.
- EU Green Deal Thermal Requirements:Military contractors can capture procurement preference by demonstrating reduced power consumption and liquid-cooled transmitter architectures.
- Software-Defined Waveform Convergence:Cognitive radar algorithms combined with open-architecture processing hardware enable single-platform multi-mission flexibility.
Industry Challenges
- RF Engineer Scarcity:Specialized expertise in microwave circuit design and antenna pattern optimization remains concentrated among aging workforce cohorts.
- NATO STANAG Certification Timelines:Ground moving target indicator data format validation extends development cycles by 18-24 months for coalition-compatible systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surveillance Radar System Market |
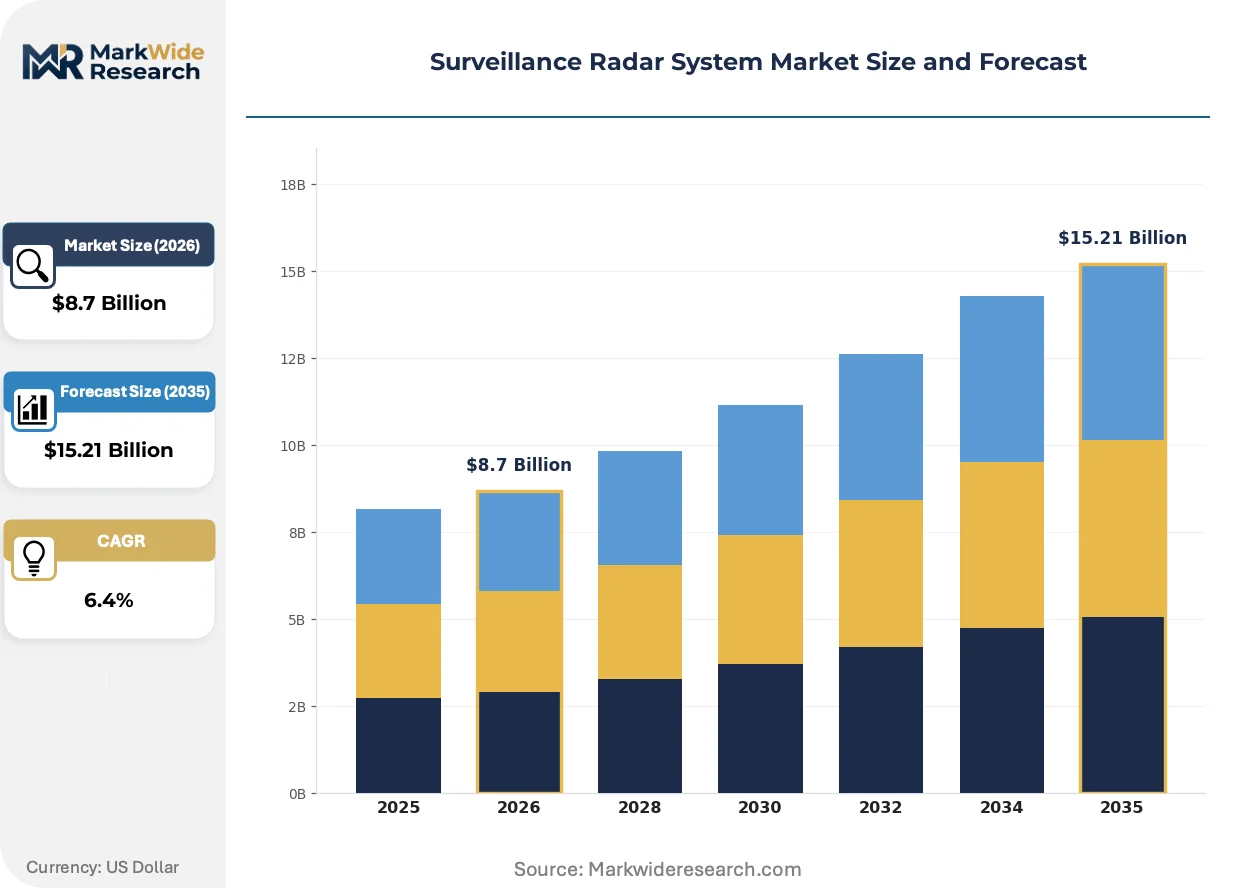
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Maritime, Ground-based, Security Technology: Phased Array, Doppler, Synthetic Aperture, LIDAR Component: Transmitter, Receiver, Antenna, Signal Processor End User: Military, Civil Aviation, Homeland Security, Law Enforcement |
| Companies Covered | Raytheon Technologies Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Group, Leonardo S.p.A., BAE Systems, Hensoldt AG, Israel Aerospace Industries, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surveillance Radar System Market Emerging Trajectories
Active electronically scanned arrays are rewriting platform economics while electromagnetic spectrum regulations and procurement centralization reshape competitive access.
GaN monolithic microwave integrated circuits are consolidating transmitter architectures across airborne and maritime surveillance platforms. Defense procurement agencies in the United States and United Kingdom now specify solid-state designs for all new long-range detection programs. The technology is consolidating supplier tiers by eliminating traveling-wave tube subsystem vendors from next-generation competitions.
The EU Green Deal pressures military contractors to document thermal footprint reductions and power efficiency gains in radar system proposals. France and the Netherlands now require life-cycle energy assessments for naval surveillance radar selections. Maritime platform integrators respond by specifying liquid-cooled GaN arrays that reduce shipboard cooling load.
Border security agencies now bundle counter-drone radar with kinetic and electronic defeat systems under single procurement vehicles. The United States Customs and Border Protection and Australia's Border Force issue integrated requirement documents that favor turnkey detection-to-interdiction packages. This behavior compresses standalone radar vendor access to the fastest-expanding application segment.
Surveillance Radar System Market Segmentation
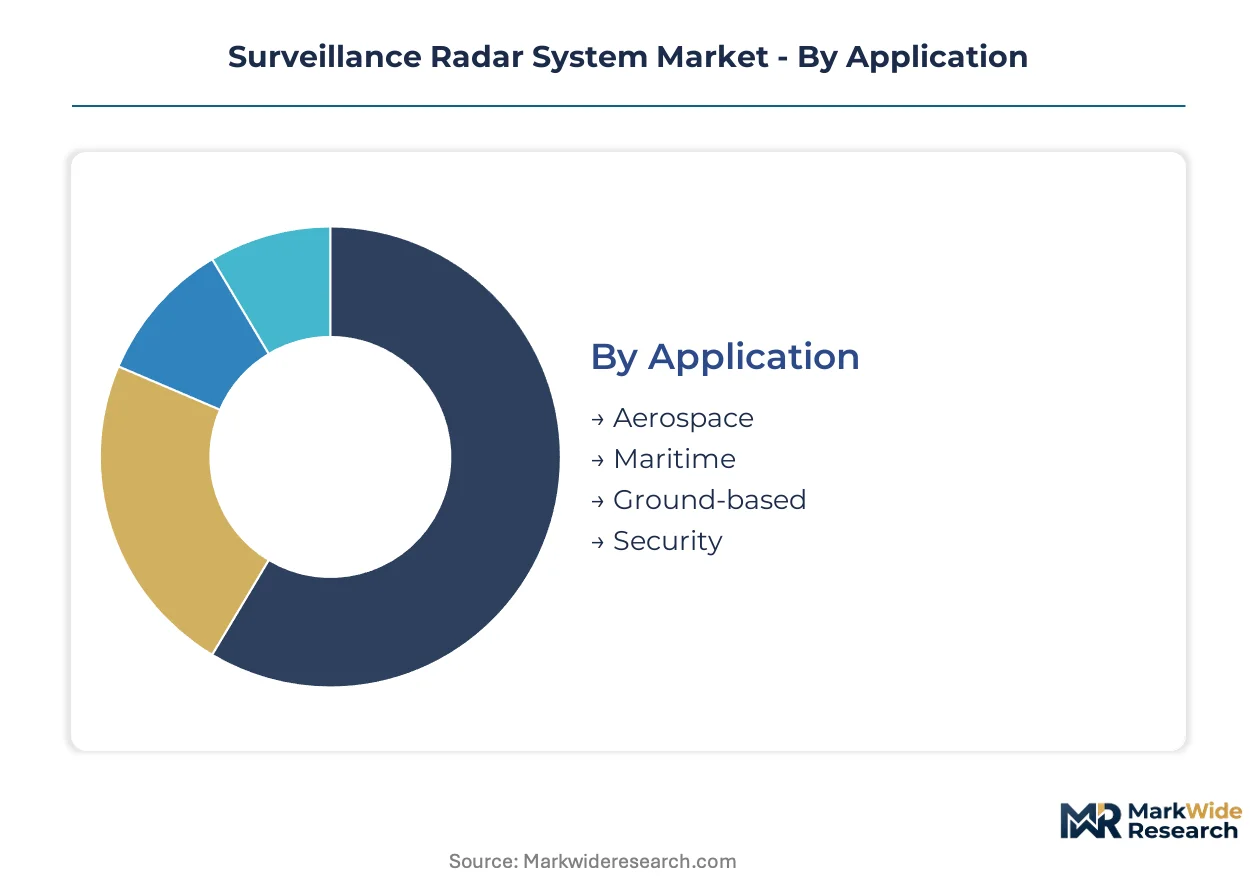
Surveillance radar procurement diverges sharply across mission profiles, with defense ministries prioritizing range and electronic counter-countermeasures while civil operators emphasize spectrum efficiency and regulatory compliance. Component-level sourcing strategies further fragment as gallium nitride transmitter architectures displace legacy vacuum tube supply chains.
Application:
Defense ministries and civil operators select platforms based on detection range requirements, environmental clutter conditions, and integration complexity with existing command networks.
- Aerospace:Airborne early warning platforms integrate multi-mode arrays capable of simultaneous air-to-air tracking and maritime surface search. NATO airborne warning and control system replacements in the United Kingdom and United States sustain demand for X-band active electronically scanned arrays with integrated IFF interrogators.
- Maritime:Naval surveillance radars operate across L-band and S-band frequencies for over-the-horizon detection against low-observable surface targets. France and the Netherlands specify sovereign manufacturing lines for frigate-mounted 3D surveillance systems under EU defense procurement directives.
- Ground-based:Fixed-site installations provide airspace surveillance for en-route air traffic control and ballistic missile early warning. FAA Mode S mandates force replacement cycles for aging airport surveillance radar networks across the United States.
- Security:Short-range X-band systems detect small unmanned aerial systems for border protection and critical infrastructure defense. Australia's Border Force deploys counter-drone radar networks along coastal approaches under integrated detection-to-interdiction procurement frameworks.
Aerospace leads volumes today; security is gaining share fastest.
Technology:
Procurement specifications increasingly favor solid-state architectures as electromagnetic spectrum regulations tighten and maintenance intervals compress operating cost calculations.
- Phased Array:Active electronically scanned arrays eliminate mechanical scanning latency through solid-state beam steering. Gallium nitride monolithic microwave integrated circuits enable higher transmit power density while reducing cooling requirements for naval and airborne platforms.
- Doppler:Pulse-Doppler processing separates moving targets from stationary clutter through frequency shift analysis. Weather radar networks and air traffic control systems in the United States rely on Doppler architectures for precipitation mapping and wind shear detection.
- Synthetic Aperture:SAR systems generate high-resolution imagery through coherent processing of multiple radar returns. Military reconnaissance satellites and unmanned aerial vehicles deploy SAR for all-weather ground mapping independent of daylight conditions.
- LIDAR:Optical detection and ranging supplements radio-frequency systems for short-range precision tracking. Autonomous vehicle developers and perimeter security integrators specify LIDAR for centimeter-level ranging against cooperative and non-cooperative targets.
Phased array dominates new procurement; synthetic aperture climbs fastest in defense reconnaissance applications.
Component:
Subsystem sourcing strategies concentrate around foundry-qualified suppliers as gallium nitride substrate availability constrains transmitter production scaling.
- Transmitter:Solid-state gallium nitride power amplifiers displace traveling-wave tubes across next-generation military programs. High-purity GaN-on-SiC wafer supply concentrates among defense-qualified foundries in the United States and Japan.
- Receiver:Low-noise amplifiers and downconversion chains determine system sensitivity against low radar-cross-section targets. Superheterodyne architectures persist in long-range surveillance while direct-sampling receivers penetrate commercial and dual-use applications.
- Antenna:Aperture design dictates beamwidth, sidelobe suppression, and electronic scan coverage. Slotted waveguide arrays serve maritime applications; patch arrays dominate airborne platforms with severe weight constraints.
- Signal Processor:Digital beamforming and cognitive radar algorithms execute in FPGA and GPU architectures. Open-standards processing hardware enables software-defined waveform convergence across multi-mission platforms.
Transmitter procurement absorbs the largest share of subsystem spending; signal processor content expands most quickly with software-defined architecture adoption.
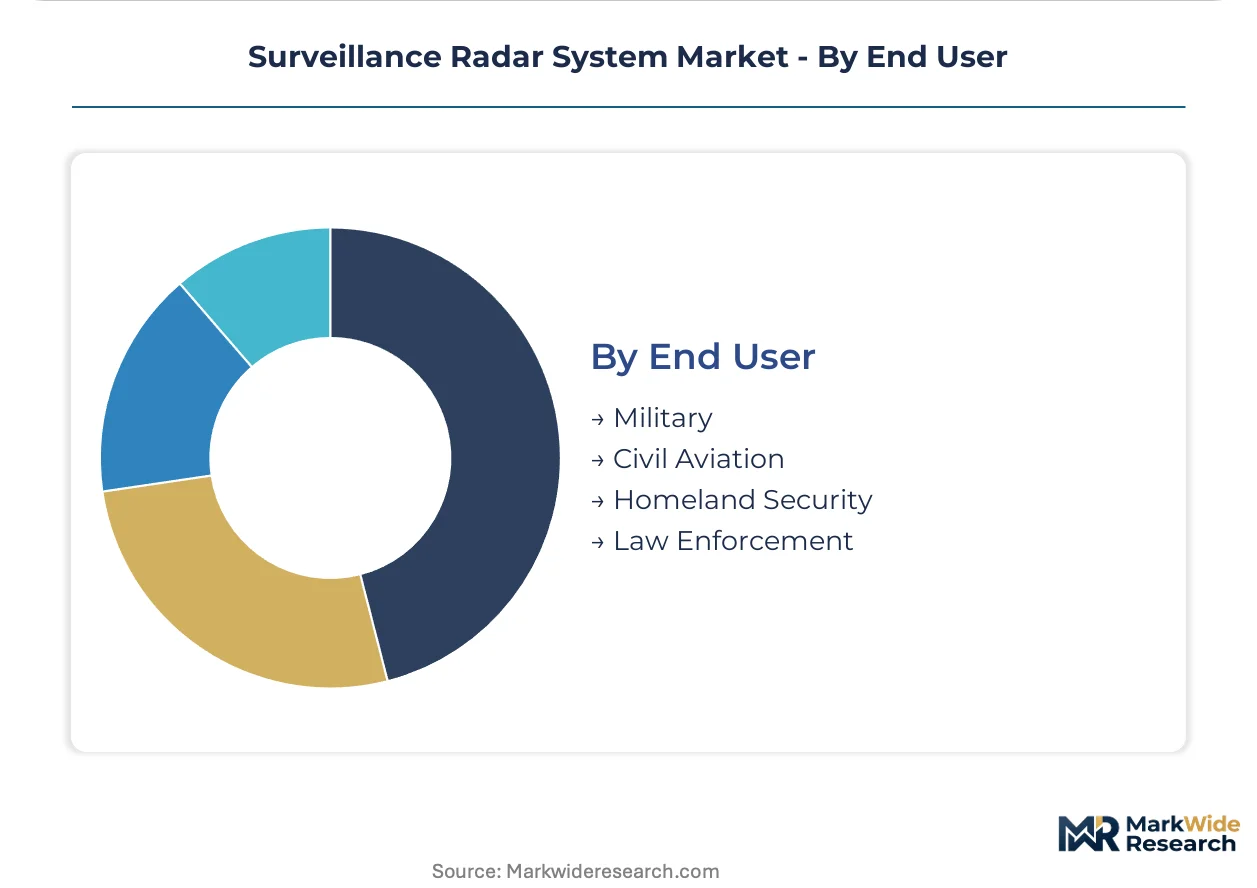
End User:
Budget cycles and regulatory compliance requirements shape procurement timelines, with defense programs spanning multiple fiscal years while civil aviation mandates force accelerated replacement schedules.
- Military:Defense procurement agencies specify long-range detection, electronic counter-countermeasures, and coalition interoperability through NATO STANAG standards. Five-Eyes intelligence-sharing frameworks mandate cross-compatible radar data formats across allied programs.
- Civil Aviation:Air navigation service operators deploy primary and secondary surveillance radar for air traffic management. FAA ADS-B integration requirements and EU SESAR modernization programs drive ground infrastructure replacement.
- Homeland Security:Border protection agencies bundle radar detection with kinetic and electronic defeat systems under single procurement vehicles. United States Customs and Border Protection specifications favor turnkey counter-UAS packages over standalone sensor acquisitions.
- Law Enforcement:Police aviation units and tactical response teams deploy portable radar for perimeter surveillance and search operations. State and municipal budget constraints limit procurement to commercially available systems with reduced classification requirements.
Military end-use commands the largest revenue pool; homeland security procurement expands most rapidly with border modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent clusters in the United States, United Kingdom, and Australia anchor surveillance radar development through Five-Eyes intelligence-sharing frameworks. These nations concentrate microwave circuit design expertise and defense-qualified foundry capacity.
United States
The FAA mandates Mode S transponder compatibility and ADS-B integration for all new civil surveillance radars entering US airspace, accelerating replacement cycles for aging ground-based networks. The Department of Defense specifies solid-state gallium nitride designs for long-range detection programs. Massachusetts and California host concentrated defense electronics clusters where captive foundry capacity supports active electronically scanned array production.
United Kingdom
NATO airborne warning and control system replacements sustain demand for X-band active electronically scanned arrays with integrated IFF interrogators. The UK Ministry of Defence enforces coalition interoperability through STANAG 4607 standard compliance for ground moving target indicator data exchange. Scotland and England's southern coast maintain sovereign radar manufacturing and systems integration facilities serving maritime surveillance programs.
Australia
Border Force agencies deploy counter-drone radar networks along coastal approaches under integrated detection-to-interdiction procurement frameworks. The country's defense procurement aligns with Five-Eids intelligence-sharing mandates for cross-compatible radar data formats. South Australia and Victoria concentrate maritime surveillance radar integration capabilities supporting regional domain awareness initiatives.
France
The EU Green Deal pressures military contractors to document thermal footprint reductions and power efficiency gains in naval surveillance radar selections. France specifies sovereign manufacturing lines for frigate-mounted 3D surveillance systems under EU defense procurement directives. The Provence-Alpes-Côte d'Azur region anchors Thales Group's radar development and maritime systems integration operations.
Netherlands
Naval platform integrators respond to EU Green Deal requirements by specifying liquid-cooled GaN arrays that reduce shipboard cooling load. The country's defense procurement directives favor multi-mode surveillance platforms with reduced life-cycle energy assessments. The Eindhoven region concentrates radar subsystem manufacturing and gallium nitride component sourcing for European maritime programs.
Surveillance Radar System Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the surveillance radar value chain, with foundry-dependent transmitter manufacturers facing distinct economics from software-defined waveform specialists. The market structure concentrates around defense-prime integrators with captive gallium nitride capacity and sovereign manufacturing mandates. Three archetypes dominate: vertically integrated aerospace conglomerates with in-house foundry operations; European defense contractors leveraging national industrial policies; and specialist subsystem vendors focused on antenna or signal processing modules. Competitive moves center on gallium nitride substrate supply agreements and NATO STANAG certification partnerships.
Within the vertically integrated tier, Raytheon Technologies Corporation and Lockheed Martin Corporation represent the capital-intensive archetype with captive gallium nitride foundry capacity. Thales Group occupies a position exemplifying European sovereign manufacturing lines in France and the Netherlands. Northrop Grumman Corporation anchors the specialist subsystem vector with focused positioning in active electronically scanned array development. These three entities collectively illustrate how defense procurement centralization and Five-Eyes interoperability mandates reshape vendor access across allied programs.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Thales Group |
| Leonardo S.p.A. |
| BAE Systems |
| Hensoldt AG |
| Israel Aerospace Industries |
| Saab AB |
| Others |
Supply Flow & Price Mechanics
RF engineering talent concentration in Massachusetts and California anchors labor-cost differentials that widen pricing-tier spreads between premium active electronically scanned arrays and legacy mechanically-scanned alternatives. Defense-qualified foundry specialists command wage premiums that transmit into subsystem pricing, while civil aviation procurement favors standardized configurations with compressed margins.
Pricing Analysis
Bundled detection-to-interdiction packages now dominate border security procurement, displacing standalone radar sales. Three-tier pricing structure across premium, standard, and economy levels separates NATO STANAG-certified platforms from commercial-grade counter-UAS systems and refurbished legacy installations. Pricing pressure stems from gallium nitride substrate bottlenecks that constrain transmitter supply scaling. Military end-users exhibit lowest price sensitivity given sovereign manufacturing mandates, while law enforcement agencies face municipal budget ceilings that favor economy-tier commercial systems.
Supply Chain Analysis
Defense-qualified foundry certification gates concentrate gallium nitride substrate supply among United States, Japan, and select European facilities. High-purity GaN-on-SiC wafers, specialized magnetron replacements, and open-architecture signal processors constitute critical input dependencies. Single-source vulnerability runs through concentrated foundry capacity for defense-grade transmitter components. Distribution runs through prime integrators with captive manufacturing lines rather than component-level vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement agencies prioritize solid-state reliability and coalition interoperability over cost-minimization, with Five-Eyes data-format mandates shifting demand toward premium certified platforms.
For Market Incumbents: Deepen captive gallium nitride foundry capacity to secure transmitter supply against substrate bottlenecks. Lock in NATO STANAG 4607 certification partnerships ahead of coalition replacement cycles. Software-defined waveform convergence threatens hardware-centric positioning; counter through cognitive radar algorithm investments.
For New Entrants and Emerging Players: Capture homeland security counter-UAS procurement as the most penetrable segment, where bundled system integrators seek specialized radar subvendors. Australia's Border Force and United States Customs and Border Protection issue integrated requirement documents favoring turnkey packages. Lead with short-range X-band arrays and open-architecture signal processing to bypass foundry-dependent transmitter barriers.
For Investors and Strategic Acquirers: Defense electronics conglomerates with in-house GaN capacity are the most active acquirer in this space, targeting software-defined waveform specialists to complete multi-mission platform offerings. Long-term viability rests on electromagnetic spectrum regulatory alignment and dual-use export control navigation. Watch for EU Green Deal thermal-efficiency mandates as inflection signal for liquid-cooled array adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Capacity Expansion | Captive substrate supply insulates Raytheon and Lockheed Martin against input bottlenecks. |
| NATO STANAG Certification Partnership | Data-format validation opens coalition procurement pools for UK and US integrators. |
| Software-Defined Waveform Acquisition | Cognitive radar algorithms enable single-platform multi-mission flexibility for maritime applications. |
| EU Green Deal Thermal Compliance | Liquid-cooled architectures secure French and Dutch naval procurement preference. |
| Counter-UAS System Integration | Turnkey detection-to-interdiction packages capture fastest-expanding border security segment. |
Methodological Framework
Direct dialogue with defense procurement officers, radar systems engineers, foundry operations managers, and electromagnetic spectrum regulators grounded the qualitative foundation. Secondary validation drew from NATO standardization documents, FAA ADS-B implementation records, SEC 10-K filings of defense primes, and customs trade data for gallium nitride substrate flows. Bottom-up component demand modeling and top-down defense budget allocation analysis were triangulated to reconcile volume estimates.
Bottom-up unit economics across transmitter, receiver, antenna, and signal processor subsystems were aggregated against top-down procurement budget trajectories. Segmentation dimensions encompassed application profile, technology architecture, component category, and end-user budget cycle. CAGRs were derived from fitted adoption curves for solid-state transmitter displacement and coalition interoperability mandate timelines. Gallium nitride foundry capacity expansion schedules and electromagnetic spectrum regulatory trajectories served as industry-specific forecast inputs.
Defense procurement cycle delays, gallium nitride substrate supply disruptions, and dual-use export control tightening are the dominant revision risks. Forecasts embed assumptions regarding NATO replacement timelines and FAA mandate enforcement. A model refresh is warranted upon material change in Five-Eyes intelligence-sharing framework specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Manportable Radar Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Europe Hydrographic Survey Equipment Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Infrared Anti-Sniper Detection System Market