
 Manportable Radar Market | 2026-2036
Manportable Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Manportable Radar Market Insights
MIL-STD-810 qualification is redrawing competitive boundaries in manportable radar supply. Thales Group leverages its European defense electronics heritage to sustain dual-use product lines spanning military and paramilitary channels. Saab AB anchors Nordic market access through deep integration with Swedish and Finnish territorial defense architectures. Elbit Systems Ltd. specializes in software-defined architectures that compress electronic warfare and surveillance functions into sub-15-kilogram payloads.
Manportable radar denotes ground-mobile detection systems transportable by one or two personnel, typically operating in X-band, Ku-band, or millimeter-wave spectra with detection ranges from 500 meters to 10 kilometers against dismounted targets. These systems synthesize Doppler processing, synthetic aperture imaging, or frequency-modulated continuous-wave modulation to deliver moving-target indication and static-scene mapping for force protection and perimeter security. Pulse Doppler architectures dominate current procurement volumes due to proven performance in clutter-heavy environments, while phased array variants represent the fastest-expanding technology segment as active electronically scanned arrays shrink in cost and thermal footprint. Solid-state transmit chains now command the primary technology lane, displacing tube-based legacy systems across NATO-aligned inventories.
The U.S. Department of Defense imposes MIL-STD-461 electromagnetic compatibility and NSA Type-1 encryption standards that filter non-compliant vendors from federal procurement channels. EUs CE marking and dual-use export control regimes under the EU Green Deal defense adaptation framework shape transatlantic product roadmaps and technology transfer permissions. Stakeholders must monitor convergence between national sovereignty requirements and coalition interoperability mandates as software-defined architectures proliferate.
Market Dynamics
MIL-STD-810 qualification requirements are compressing vendor participation windows, forcing incumbents to revalidate thermal and shock specifications while excluding new entrants lacking defense-aerospace testing infrastructure.
Growth Catalysts
- NSA Type-1 encryption mandates:U.S. federal procurement channels now require certified cryptographic modules, filtering non-compliant suppliers and consolidating contract awards among pre-cleared vendors.
- Indo-Pacific littoral surveillance:Maritime border enforcement agencies across the Philippines, Vietnam, and Indonesia are procuring sub-15-kilogram systems for archipelago perimeter monitoring.
- Solid-state transmit chains:Gallium nitride power amplifiers are displacing traveling-wave tube legacy systems, reducing mean-time-between-failure intervals and field maintenance burdens.
Market Restraints
- Gallium nitride substrate supply:Wolfspeed and Coherent dominate epitaxial wafer production, creating single-source vulnerability for radar transmitter modules.
- EU dual-use export controls:The EU Green Deal defense adaptation framework imposes technology transfer licensing delays that extend sales cycles by 8-14 months for non-EU buyers.
- Millimeter-wave atmospheric attenuation:Rain fade and humidity absorption limit Ku-band and W-band system effectiveness in tropical climates, constraining deployment geography.
Strategic Opportunities
- Swedish-Finnish territorial defense integration:Nordic countries are standardizing on interoperable manportable radar networks for Arctic border surveillance, creating captive demand for NATO-compatible architectures.
- Software-defined radio convergence:Electronic warfare and signals intelligence functions are merging with surveillance radar on common processing backplanes, enabling multi-mission payloads.
- Paramilitary channel expansion:Coast guard and customs agencies in Italy, Spain, and Greece are adopting military-grade perimeter detection for Mediterranean migrant route monitoring.
Industry Challenges
- RF engineer scarcity:Phased array antenna design and thermal management expertise concentrates in defense-aerospace clusters around Toulouse, Stockholm, and Boston, limiting hiring pools for new entrants.
- MIL-STD-461 recertification timelines:Electromagnetic interference testing for platform integration requires 18-24 month validation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manportable Radar Market |
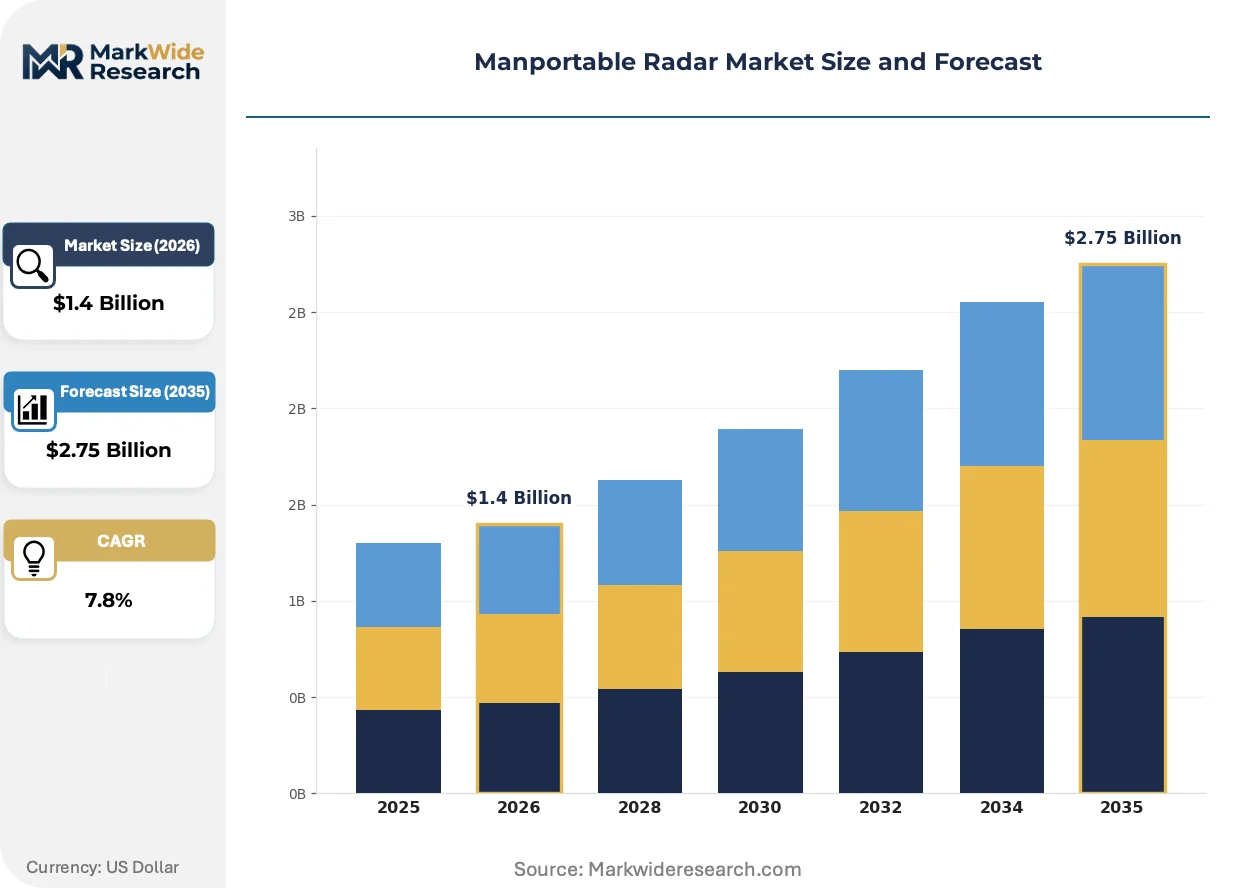
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Doppler Radar, Synthetic Aperture Radar, Continuous Wave Radar, Phased Array Radar, Frequency Modulated Radar Technology: Solid State, GaN, Gallium Arsenide, Software Defined, MEMS Application: Border Surveillance, Maritime Navigation, Search & Rescue, Counter-IED, Threat Detection End User: Military Forces, Law Enforcement Agencies, Border Patrol Units, Security Contractors |
| Companies Covered | Thales Group, Leonardo S.p.A, Saab AB, Telefunken Racoms, FLIR Systems, Elbit Systems Ltd., ASELSAN A.S, BAE Systems PLC, HENSOLDT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manportable Radar Market Trends and Innovations
Active electronically scanned arrays are collapsing cost curves while software-defined architectures enable rapid mission reconfiguration without hardware swaps.
Gallium nitride monolithic microwave integrated circuits are decomposing traditional radar transmitter architectures by integrating power amplification, phase control, and thermal management on single die substrates. Border patrol agencies in Arizona and Texas are fielding GaN-based systems for drone detection at 5-kilometer ranges. This semiconductor transition is decomposing the legacy supply chain separation between tube manufacturers, waveguide fabricators, and cooling system suppliers.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on autonomous target recognition software deployed in European defense procurement. Manufacturers must now document training data provenance and decision-logic interpretability for machine-learning-based moving-target indication. French and German defense ministries are prioritizing vendors with pre-certified ethical AI governance, compressing competitive evaluation timelines for compliant suppliers.
Integrated logistics support contracts are displacing transactional spare-part purchasing across NATO-aligned procurement channels. Danish and Norwegian defense forces now require 10-year availability guarantees with performance-based payment terms tied to operational readiness metrics. This service-model transition is most advanced in Nordic countries, where total-cost-of-ownership calculations dominate source-selection criteria over unit acquisition price.
Manportable Radar Market Segmentation
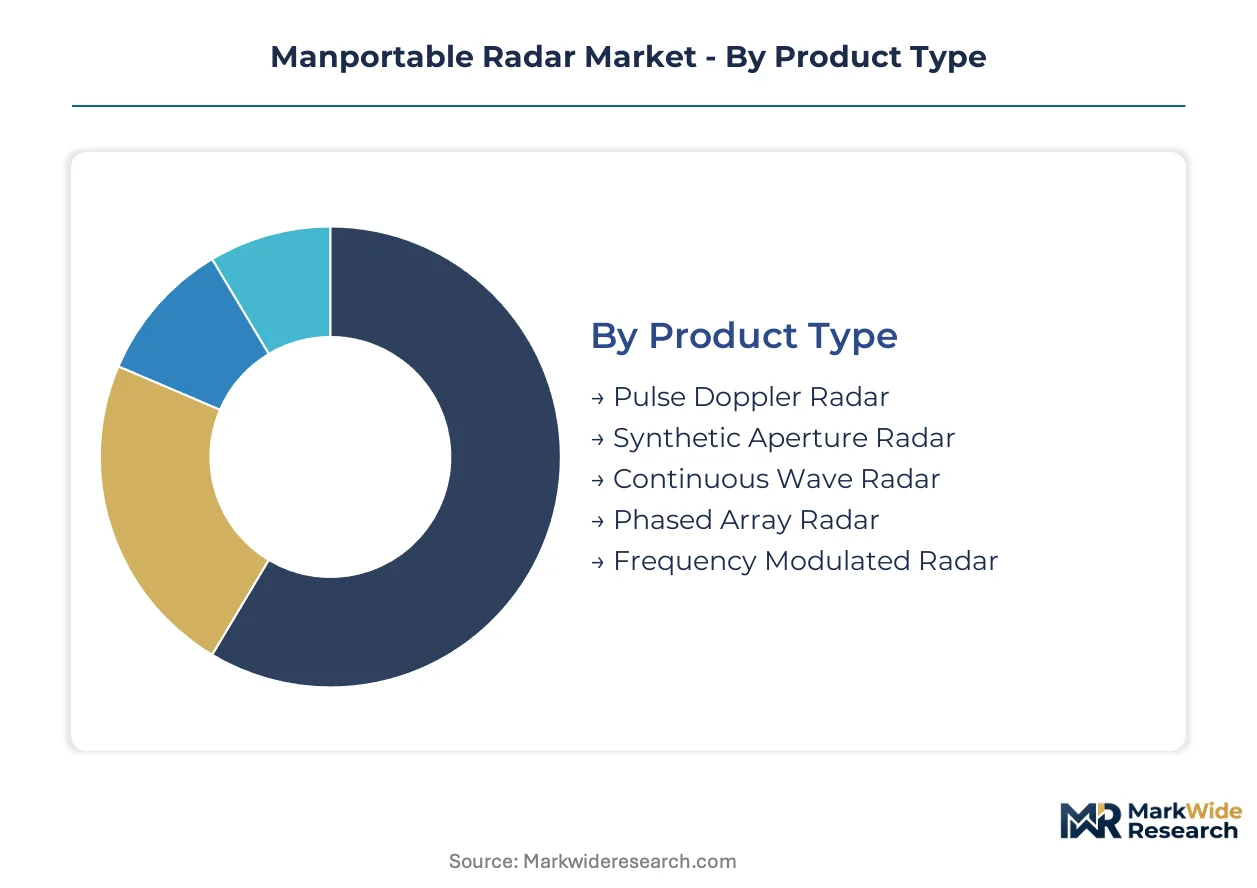
Manportable radar procurement channels fragment across mission profiles and technical specifications that dictate thermal budgets, encryption standards, and platform integration requirements. Each segmentation dimension reveals distinct margin architectures and vendor specialization patterns.
Product Type:
Pulse Doppler architectures command premium pricing in cluttered terrain applications where moving-target discrimination determines mission success.
- Pulse Doppler Radar:Doppler processing filters ground clutter to isolate dismounted personnel and vehicle movement. U.S. Border Patrol units in Arizona and Texas prioritize these systems for desert perimeter monitoring where thermal updrafts create radar interference. MIL-STD-810 shock qualification requirements filter non-compliant vendors from federal procurement.
- Phased Array Radar:Active electronically scanned arrays enable rapid beam steering without mechanical gimbals. Finnish and Swedish territorial defense forces are standardizing on sub-15-kilogram AESA variants for Arctic border surveillance where rapid target acquisition offsets higher unit costs.
- Synthetic Aperture Radar:Coherent processing delivers high-resolution static scene mapping for route reconnaissance.
- Continuous Wave Radar:Unmodulated carrier systems provide simple motion detection at short ranges.
- Frequency Modulated Radar:FMCW modulation enables precise range measurement with low probability of intercept.
The dominant share belongs to Pulse Doppler Radar, while Phased Array Radar is closing the gap fastest.
Technology:
Solid-state transmit chains now displace tube-based legacy systems across NATO-aligned inventories, compressing maintenance intervals and field logistics burdens.
- GaN:Gallium nitride power amplifiers integrate phase control and thermal management on monolithic die substrates. Border patrol agencies deploy GaN-based systems for drone detection at extended ranges. Wolfspeed and Coherent dominate epitaxial wafer supply, creating single-source vulnerability for transmitter modules.
- Software Defined:Software-defined radio architectures compress electronic warfare and surveillance functions onto common processing backplanes. U.S. Department of Defense MIL-STD-461 interoperability mandates accelerate platform modernization toward these reconfigurable payloads.
- Solid State:Transistor-based transmitters replace vacuum tubes in legacy system retrofits.
- Gallium Arsenide:Mature semiconductor technology serves cost-sensitive applications with moderate power requirements.
- MEMS:Micro-electromechanical systems enable miniaturized beam steering elements.
GaN holds the installed base advantage, though Software Defined architectures are expanding most quickly as multi-mission requirements proliferate.
Application:
Maritime navigation and border surveillance applications concentrate procurement volumes where littoral environments demand salt-spray corrosion resistance and stabilized mounting platforms.
- Border Surveillance:Ground-mobile detection systems monitor perimeter breaches across archipelago and desert terrain. Philippine and Indonesian maritime enforcement agencies procure sub-15-kilogram systems for island chain monitoring where conventional fixed-site radar cannot deploy.
- Maritime Navigation:Harbor approach and coastal route surveillance requires all-weather operation in high-humidity environments. Ku-band and W-band effectiveness degrades in tropical climates due to rain fade, constraining deployment geography for millimeter-wave variants.
- Search & Rescue:Rapid deployment for disaster response and missing personnel location.
- Counter-IED:Ground-penetrating and forward-looking detection for route clearance operations.
- Threat Detection:Force protection against unmanned aerial systems and indirect fire.
Border Surveillance maintains the largest contract awards, while Maritime Navigation is gaining share fastest as Indo-Pacific littoral enforcement budgets expand.
End User:
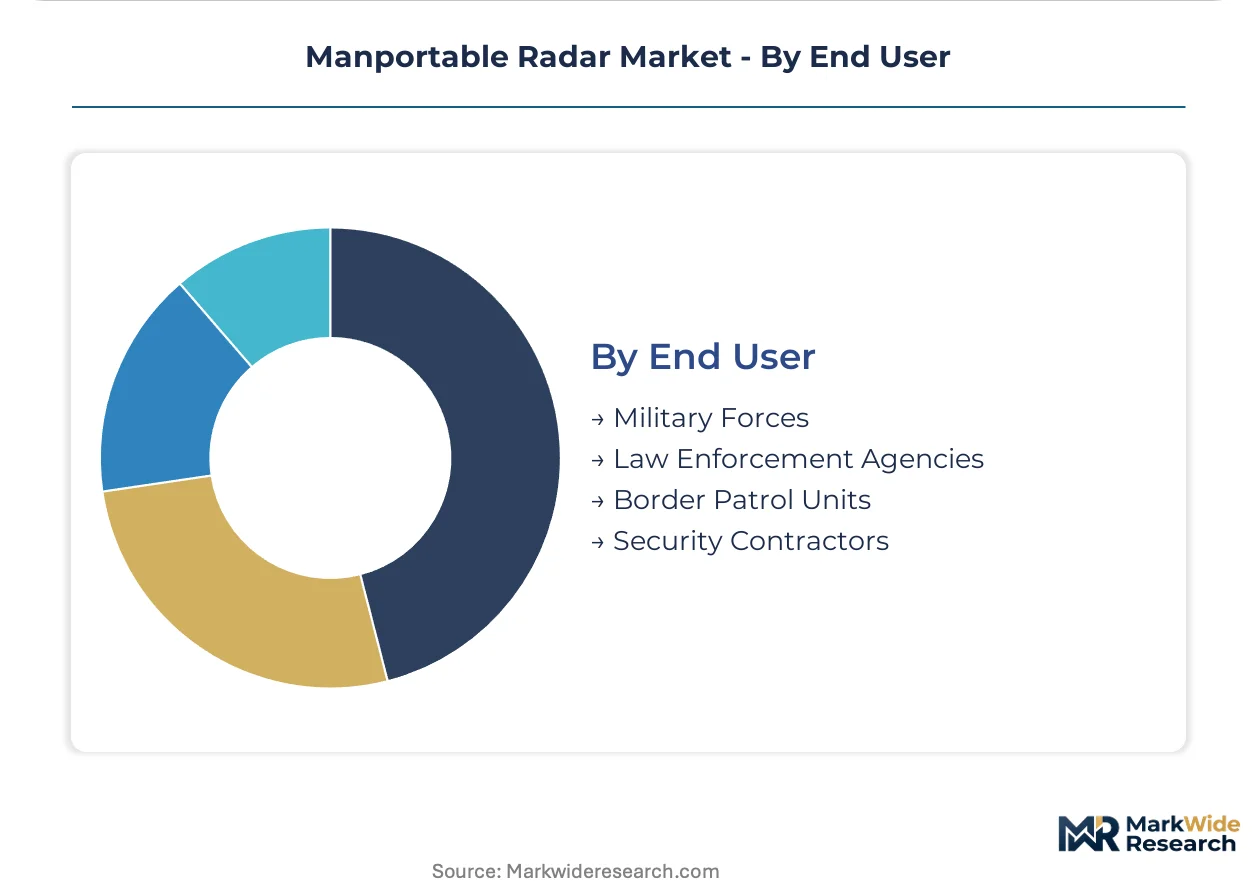
Military forces and border patrol units operate under distinct procurement regulations that shape vendor qualification timelines and payment terms.
- Military Forces:National defense ministries impose NSA Type-1 encryption and MIL-STD-461 electromagnetic compatibility standards. Danish and Norwegian defense forces require 10-year availability guarantees with performance-based payment terms tied to operational readiness metrics.
- Border Patrol Units:Paramilitary agencies adopt military-grade perimeter detection for migrant route monitoring. Italian and Greek coast guard procurement channels expand demand for lightweight threat detection systems with simplified export licensing compared to full military specifications.
- Law Enforcement Agencies:Domestic security applications prioritize rapid deployment and minimal training requirements.
- Security Contractors:Private sector demand concentrates on protective services for critical infrastructure.
Military Forces control the dominant procurement volume, while Border Patrol Units are climbing the fastest as Mediterranean and Indo-Pacific enforcement budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries and border enforcement agencies concentrate procurement authority in national capitals, with program offices in Washington, Paris, Stockholm, and Tel Aviv shaping specification standards that cascade to peripheral markets through alliance procurement frameworks.
United States
U.S. Border Patrol units in Arizona and Texas drive demand for desert-qualified perimeter detection systems. The Department of Defense imposes NSA Type-1 encryption and MIL-STD-461 electromagnetic compatibility standards that filter non-compliant vendors from federal channels. Boston-area defense electronics clusters anchor GaN transmitter module development for next-generation payloads.
Sweden
Swedish territorial defense forces prioritize sub-15-kilogram AESA variants for Arctic border surveillance against dismounted threats. The country's defense procurement agency coordinates interoperability requirements with Finnish counterparts under Nordic defense cooperation frameworks. Stockholm-based engineering clusters specialize in phased array antenna design and thermal management for extreme cold environments.
France
French defense ministries emphasize vendors with pre-certified ethical AI governance under the EU AI Act's risk classification framework. Thales Group leverages its European defense electronics heritage to sustain dual-use product lines spanning military and paramilitary channels. Toulouse-area RF engineering clusters concentrate phased array expertise that limits hiring pools for new entrants.
Israel
Israeli defense procurement prioritizes software-defined architectures that compress electronic warfare and surveillance functions into lightweight payloads. Elbit Systems Ltd. specializes in multi-mission processing backplanes that enable rapid mission reconfiguration. Tel Aviv-area defense electronics clusters anchor development of solid-state transmit chains displacing tube-based legacy systems.
Finland
Finnish territorial defense integration with Swedish systems creates captive demand for NATO-compatible manportable radar networks. The defense forces require 10-year availability guarantees with performance-based payment terms tied to operational readiness metrics. Helsinki-region procurement offices coordinate Arctic border surveillance requirements with Stockholm through formalized alliance structures.
Manportable Radar Market Competitive Landscape
Player mix skews toward diversified defense electronics conglomerates with established military-aerospace testing infrastructure. The vendor base concentrates among European and Israeli specialists with deep integration into national territorial defense architectures. Two strategic archetypes dominate: heritage defense electronics houses leveraging dual-use product lines, and software-defined specialists compressing multi-mission functions into reduced payload weights. Competitive moves center on MIL-STD-810 qualification revalidation and strategic partnerships for GaN substrate supply security.
Within the heritage defense electronics tier, Thales Group and Leonardo S.p.A represent European specialists with established paramilitary channel access. Saab AB anchors Nordic market positioning through deep integration with Swedish and Finnish territorial defense procurement. Elbit Systems Ltd. exemplifies the software-defined specialist archetype, with Israeli defense electronics heritage supporting multi-mission payload development.
| Leading Market Players |
|---|
| Thales Group |
| Leonardo S.p.A |
| Saab AB |
| Telefunken Racoms |
| FLIR Systems |
| Elbit Systems Ltd. |
| ASELSAN A.S |
| BAE Systems PLC |
| HENSOLDT |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month MIL-STD-461 recertification timelines concentrate pricing power among incumbents with defense-aerospace testing infrastructure, compressing procurement negotiation windows for buyers dependent on NSA Type-1 compliant systems. Danish and Norwegian defense forces now demand 10-year availability guarantees with performance-based payment terms, shifting contract structures toward service-attach models that bundle hardware with sustainment obligations.
Pricing Analysis
Cost-plus contracts with gallium nitride substrate indexation dominate procurement channels for AESA variants, passing epitaxial wafer volatility through to defense ministries. Three-tier pricing structure across MIL-STD-810 qualified, CE-marked, and uncertified commercial tiers reflects certification investment amortization. Price differentiation centers on encryption grade and thermal qualification breadth. Cost compression in commercial-tier pulse Doppler systems intensifies as paramilitary buyers in Mediterranean markets prioritize rapid deployment over full military specification. Border patrol units exhibit highest price sensitivity; Nordic territorial defense forces accept premium positioning for Arctic-qualified sub-15-kilogram payloads.
Supply Chain Analysis
Strategic stockpiling of GaN epitaxial wafers supersedes just-in-time preferences as Wolfspeed and Coherent production bottlenecks extend transmitter module lead times. Manufacturing concentrates in the United States, Sweden, and Israel, drawing from silicon carbide substrate foundries in North Carolina and New York. Supply chain risk stems from single-source vulnerability in epitaxial wafer supply for power amplification stages. Distribution runs through national defense procurement agencies with NATO-aligned interoperability mandates filtering non-compliant vendors from coalition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated logistics support contracts now expand faster than hardware unit sales as Danish, Norwegian, and Finnish defense forces mandate decade-long availability guarantees with operational readiness penalties. This service-layer acceleration creates recurring revenue pools that alter competitive economics for vendors with field engineering infrastructure.
For Market Incumbents: Consolidate GaN substrate supply security through backward integration or long-term offtake agreements with Wolfspeed and Coherent to defend against phased array cost curve compression. Deepen MIL-STD-810 qualification moats by revalidating thermal and shock specifications ahead of Nordic territorial defense integration deadlines, excluding testing-infrastructure-poor entrants from Swedish-Finnish procurement channels.
For New Entrants and Emerging Players: CE marking fast-track through French ANSM or German BSI pre-certification opens paramilitary channels in Italy, Spain, and Greece with simplified export licensing compared to full NSA Type-1 military specifications. Target Mediterranean coast guard drone detection deployments as the most penetrable white-space segment. Pursue software-defined radio convergence as go-to-market angle, compressing electronic warfare and surveillance functions onto common processing backplanes that reduce payload weight below incumbent mechanical gimbal architectures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense electronics conglomerates seeking to monetize non-core manportable radar divisions amid portfolio rationalization pressures. Long-term viability hinges on software-defined architecture transition completion and GaN supply chain captive access. Watch Swedish-Finnish territorial defense procurement synchronization as inflection indicator for NATO-compatible AESA demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Supply Security Partnership | Long-term wafer offtake with Wolfspeed insulates transmitter module costs from epitaxial production bottlenecks. |
| MIL-STD-810 Revalidation Investment | Pre-emptive shock and thermal qualification extends incumbency in U.S. Border Patrol desert deployment channels. |
| Software-Defined Payload Integration | Multi-mission processing backplanes enable rapid electronic warfare reconfiguration without hardware swaps. |
| Nordic Defense Cooperation Alignment | Swedish-Finnish interoperability standardization creates captive demand for sub-15-kilogram AESA variants. |
| Paramilitary Channel Certification | CE marking pathway accelerates Mediterranean coast guard access with reduced EU dual-use licensing delays. |
Research Methodology
The analysis maps pulse Doppler, phased array, synthetic aperture, and continuous wave architectures, each validated through defense procurement officers, RF engineering directors, GaN substrate supply managers, and territorial defense planners. Primary interviews with program executives at national defense ministries combine with secondary validation against NATO procurement databases, EU dual-use export control filings, SEC 10-K defense segment disclosures, and semiconductor foundry capacity reports. Bottom-up unit deployment estimates triangulate against top-down defense budget allocation analysis.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, semiconductor technology tier, application mission profile, and end-user procurement channel. CAGRs derive from deployment trajectory analysis and budget authorization patterns. Forecast inputs incorporate GaN power amplifier adoption curves and software-defined radio interoperability mandate implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained Indo-Pacific littoral surveillance budget expansion and stable NATO alliance procurement frameworks; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal defense adaptation framework licensing delays and millimeter-wave tropical deployment constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
UXO Detection Market
Military Surveillance
Military Radar Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market