
 Air-To-Air Refueling Market | 2026-2036
Air-To-Air Refueling Market Size, Share, and Industry Trends Forecast 2026-2036
Air-To-Air Refueling Market Analysis
The gap between premium integrated refueling systems and commodity aftermarket components is expanding. The Boeing Company leverages its position as prime contractor on major tanker programs to sustain long-term revenue visibility. Airbus SE competes through the A330 MRTT platform, which dominates European and Middle Eastern operator fleets. Lockheed Martin Corporation specializes in advanced aerial systems and extends its reach through classified defense contracts.
Air-to-air refueling encompasses the transfer of aviation fuel from a tanker aircraft to a receiver aircraft during flight, typically conducted at altitudes between 15,000 and 35,000 feet and speeds of 200 to 400 knots to extend operational range and endurance. The technology serves military power projection, humanitarian logistics, and emerging commercial long-haul applications where ground infrastructure remains limited. Probe and drogue systems lead in fighter jet compatibility due to simpler receiver modifications and multi-point capability, while boom systems command premium positioning in bomber and transport aircraft segments where fuel transfer rates determine mission efficiency. Equipment and systems categories capture the dominant margin pool as platform integration complexity rises.
The FAA mandates airworthiness standards under Part 25 and Part 29 certification pathways, while the EASA enforces CS-25 requirements that shape transatlantic supplier qualification. Military procurement further channels demand through NAVAIR and USAF technical directives that specify boom control precision and hose-drogue stability parameters. Stakeholders must weigh certification investment timelines against the accelerating shift toward autonomous refueling demonstrations and multi-domain operational concepts.
Market Dynamics
The air-to-air refueling market is experiencing fundamental pressure from autonomous refueling demonstrations that promise to reduce crew requirements and extend operational tempo beyond human physiological limits. Military procurement offices are rewriting technical specifications to accommodate unmanned tanker-receiver coordination, forcing incumbent suppliers to retool development roadmaps or risk disqualification from next-generation programs.
Growth Catalysts
- USAF Tanker Fleet Recapitalization:The Air Force's KC-46 and follow-on programs are replacing Eisenhower-era KC-135 platforms, creating sustained demand for integrated boom systems and receiver certification services.
- EASA CS-25 Certification Harmonization:Brussels-aligned safety standards are reducing duplicate qualification costs for European suppliers seeking transatlantic contracts, accelerating cross-border equipment approvals.
- Probe-Drogue Retrofit Cycles:NATO fighter squadrons are upgrading legacy fleets with multi-point refueling capability, driving aftermarket hose and drogue hardware consumption across European and Pacific bases.
Market Restraints
- Aerospace-Grade Titanium Input Volatility:Boom construction relies on Russian-sourced VSMPO-AVISMA sponge titanium, exposing prime contractors to supply interruption and price spikes under sanctions regimes.
- Single-Source Actuator Concentration:Precision flight control actuators for boom positioning concentrate among two German and Japanese suppliers, creating chokepoint vulnerability for platform integrators.
- FAA Part 25 Certification Timeline:New aerial refueling system approvals require 18-36 months of flight testing, freezing product development capital and compressing competitive windows for mid-tier entrants.
Strategic Opportunities
- India Defense Modernization:The Indian Air Force's pending multi-role tanker transport tender represents a greenfield opportunity for probe-drogue specialists to establish regional maintenance infrastructure.
- Commercial Long-Haul Cargo:Amazon Air and express freight operators are evaluating tanker-enabled trans-Pacific routes where ground infrastructure gaps currently limit payload-range economics.
- Autonomous-Digital Convergence:Machine vision and precision GPS fusion is enabling formation-keeping algorithms that reduce receiver pilot workload and expand refueling envelope safety margins.
Industry Challenges
- Flight Test Engineer Scarcity:Boom control software validation requires specialized crews with military test pilot backgrounds; retirements are outpacing training pipeline output at Pax River and Edwards.
- Legacy Platform Integration Complexity:Retrofitting 1970s-era transport aircraft with modern digital refueling interfaces demands bespoke avionics bridges that extend program timelines and erode fixed-price margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-To-Air Refueling Market |
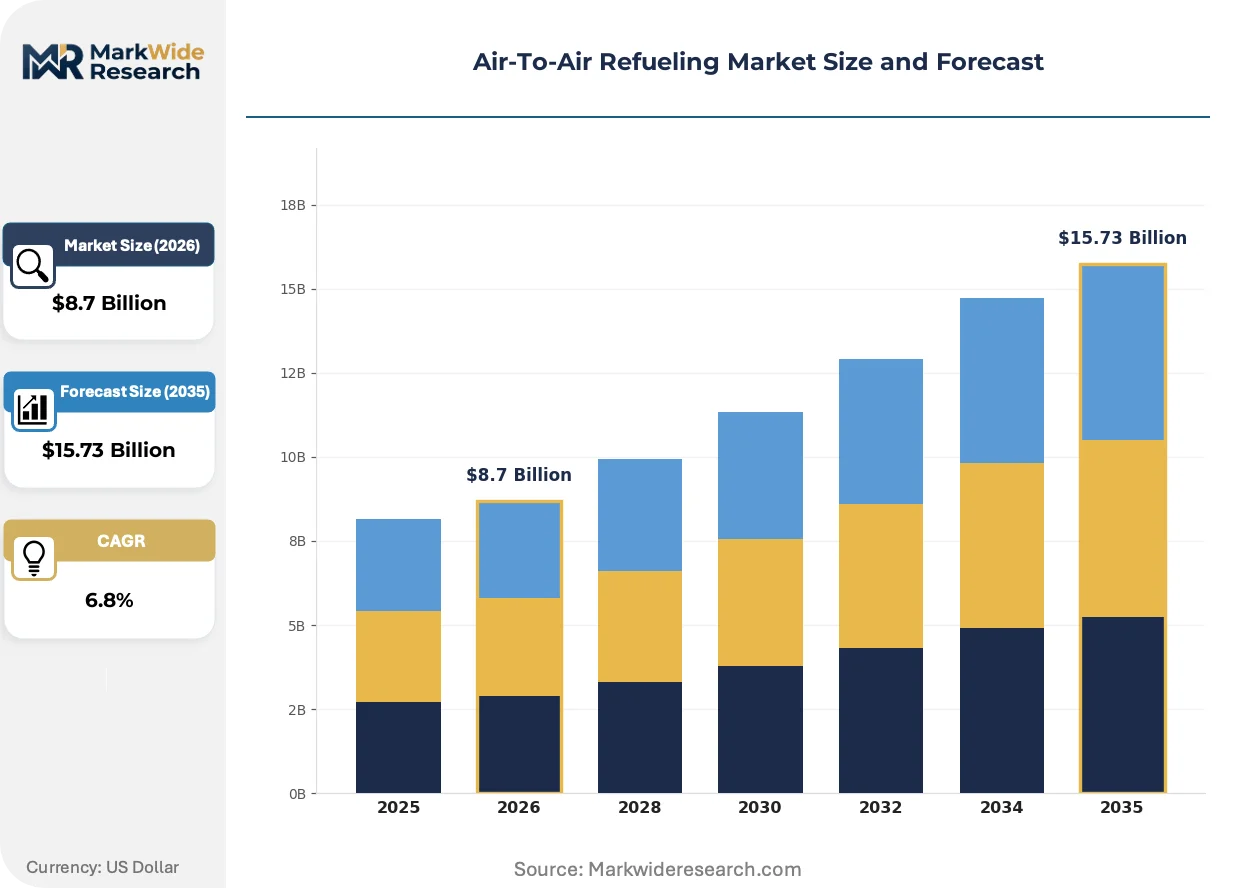
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Probe & Drogue, Boom, Flying Boom, Manual End User: Military, Commercial, Government, Private Application: Fighter Jets, Bombers, Transport Aircraft, Tankers Product Type: Equipment, Software, Systems, Services |
| Companies Covered | The Boeing Company, Airbus SE, Lockheed Martin Corporation, Eaton Corporation plc, Cobham plc, GE Aviation, Safran, Israel Aerospace Industries Ltd., BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-To-Air Refueling Market Emerging Trajectories
Autonomous systems architecture is displacing crew-centric design assumptions across tanker development programs. Three parallel developments are compressing traditional procurement cycles and rewriting supplier qualification criteria.
Modular refueling pods are modularizing platform economics by separating fuel transfer hardware from airframe-specific integration. European defense ministries are procuring these units under five-year rolling contracts rather than platform-locked programs. This architecture is modularizing supplier tiers, allowing specialized hose-drogue manufacturers to compete directly with prime contractors for subsystem awards.
Brussels is tightening F-Gas Regulation enforcement on tanker aircraft refrigerants and fire suppression systems, forcing fleet operators to accelerate C-130 and A400M environmental retrofits. The industrial consequence is a certification backlog at European maintenance, repair, and overhaul facilities. Transport aircraft segments face the steepest compliance cost escalation, with operators diverting modernization budgets from avionics to environmental hardware.
Buyer consolidation among NATO procurement agencies is compressing supplier negotiation leverage. The NATO Support and Procurement Agency now coordinates tanker spare parts purchasing for twelve member states, displacing bilateral national contracts. French and German air forces have transferred category management authority to this centralized entity, standardizing specifications and collapsing price differentiation across hardware tiers.
Air-To-Air Refueling Market Segmentation
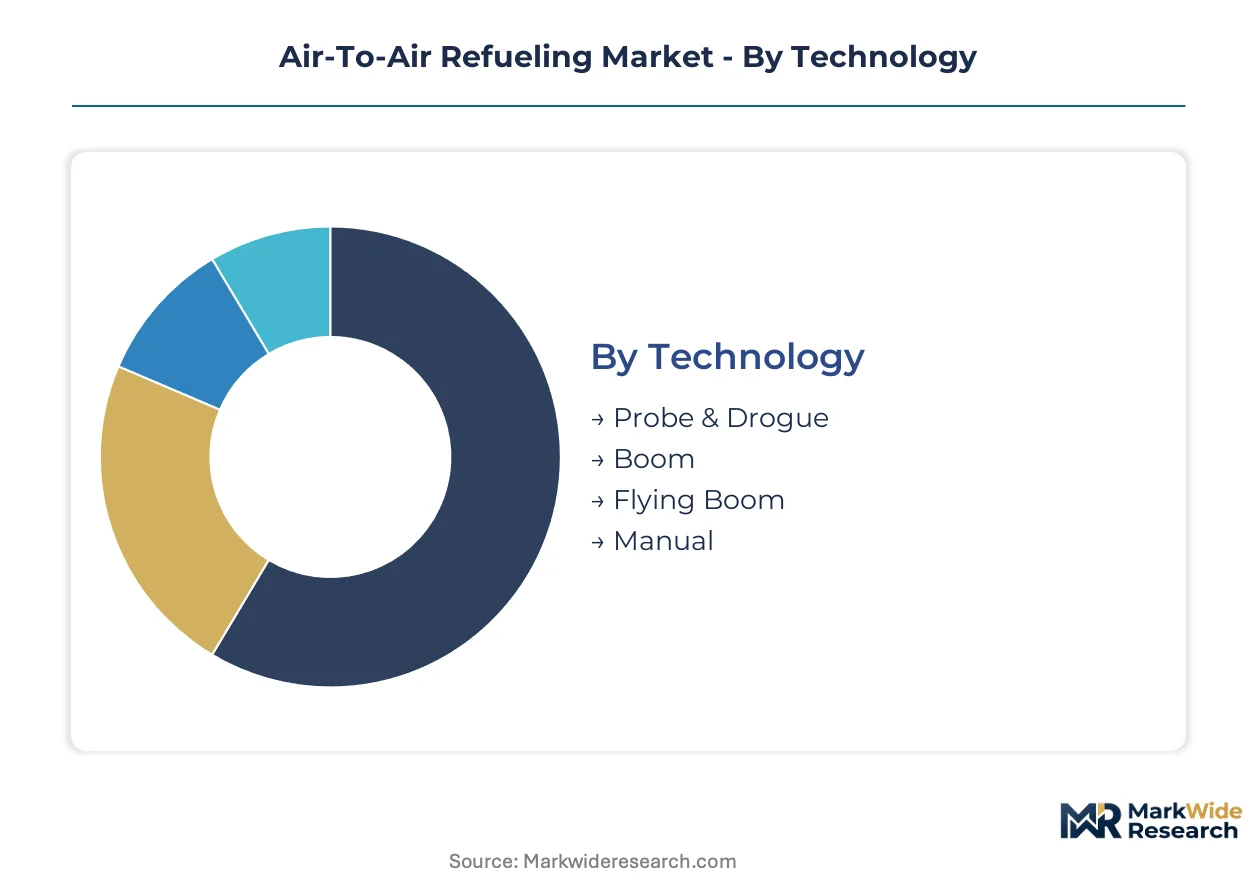
Technology integration depth determines margin capture and certification burden across air-to-air refueling supply tiers. Standalone hardware segments face commoditization pressure while embedded software and integrated systems command premium positioning.
Technology:
Probe and drogue systems operate as standalone retrofit kits with minimal airframe modification, while boom architectures embed deeply into tanker platform design.
- Probe & Drogue:Hose-reel units with trailing drogue baskets enable multi-point simultaneous refueling for fighter formations. NATO Pacific squadrons drive replacement cycles as corrosion-prone rubber hoses reach service limits in maritime environments.
- Boom:Telescoping rigid booms with fly-by-wire control achieve transfer rates exceeding probe systems by 3-4x for heavy transport missions. USAF KC-46 program specifications embed boom suppliers into 30-year platform support contracts, locking out aftermarket competitors.
- Flying Boom:Hydraulically actuated boom variants with manual backup modes serve legacy tanker fleets.
- Manual:Human-operated boom control stations persist in training aircraft and reserve fleet conversions.
Probe and drogue leads volumes today; boom systems are gaining share fastest through tanker fleet recapitalization programs.
End User:
Cost tiers separate price-insensitive defense procurement from margin-constrained commercial operators seeking lease-based tanker access.
- Military:Defense procurement offices specify MIL-STD-1553 data bus integration and electromagnetic hardening for contested airspace operations. Multi-year indefinite-delivery contracts amortize development costs across platform generations.
- Commercial:Cargo airlines evaluate wet-lease tanker arrangements for ultra-long-haul routes where fuel stops erode schedule reliability. Payload-range economics determine adoption thresholds.
- Government:Coast guard and border patrol agencies procure probe-drogue kits for maritime patrol extensions.
- Private:Corporate flight departments explore tanker-enabled global reach for ultra-long-range business jets.
Military end users dominate absolute spend; commercial segments are climbing the fastest as freight operators test tanker economics.
Application:
Receiver aircraft mission profiles dictate fuel transfer rate requirements and boom compatibility constraints.
- Fighter Jets:Single-engine fighters with probe receivers demand drogue stability in turbulent wingtip vortices. Carrier-based operations impose salt-spray corrosion standards on all exposed hardware.
- Bombers:Strategic bomber fleets require extended-duration refueling contacts at reduced airspeeds.
- Transport Aircraft:Tactical airlifters with internal fuel tanks accept boom transfers for rapid ground-time minimization.
- Tankers:Receiver-capable tanker-to-tanker refueling extends loiter time for airborne alert missions.
Fighter jet applications anchor current installed base; bomber segments show steepest expansion trajectory through next-generation platform introductions.
Product Type:
Supply concentration varies sharply between capital-intensive hardware and recurring-revenue software and service streams.
- Equipment:Aerial refueling pods, drogue assemblies, and hose reels constitute discrete capital purchases with 15-20 year replacement cycles. EASA CS-25 certification requirements elevate entry barriers for new hardware suppliers.
- Systems:Integrated boom control and fuel management architectures embed across tanker platforms. Prime contractors retain proprietary interfaces that foreclose third-party subsystem competition.
- Software:Formation-keeping algorithms and automated contact prediction tools transition to machine-learning architectures.
- Services:Flight test validation and receiver certification consulting capture value from scarce engineering talent pools.
Equipment categories dominate current revenue; software and services are expanding most quickly as autonomy investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense aerospace engineering talent clusters in Southern California, Greater Seattle, and the Ile-de-France region anchor platform integration capabilities. These concentrations sustain boom system development and flight test validation infrastructure.
United States
The USAF tanker recapitalization program drives sustained demand for integrated boom systems and receiver certification services. FAA Part 25 certification pathways govern civil-military hybrid approvals for tanker platforms. Wichita, Kansas hosts specialized flight test engineering clusters supporting boom control software validation.
France
Airbus Defence and Space maintains A330 MRTT final assembly lines serving European and export customers. EASA CS-25 certification requirements shape transatlantic supplier qualification standards. The Toulouse aerospace cluster concentrates probe-drogue subsystem manufacturing and platform integration expertise.
United Kingdom
Royal Air Force Voyager fleet operations sustain aftermarket demand for hose-reel units and drogue refurbishment. Military procurement through the Defence Equipment and Support agency channels specifications for multi-point refueling capability. Cobham's Dorset facilities anchor specialized aerial refueling pod production.
Germany
Luftwaffe A400M tanker conversions drive demand for modular refueling pod architectures. The country's national aerospace regulator enforces EASA-aligned military certification standards. Munich and Hamburg host precision actuator suppliers concentrated in boom flight control systems.
Israel
Israel Aerospace Industries develops probe-drogue retrofit solutions for fighter jet applications. The country's defense export licensing framework shapes technology transfer protocols for aerial refueling systems. Tel Aviv metropolitan engineering clusters specialize in autonomous formation-keeping algorithm development.
Air-To-Air Refueling Market Vendor Landscape
Capital-heavy platform integrators compete with asset-light subsystem specialists across the supply tier. The market structure concentrates around prime contractors holding 30-year platform support contracts, while mid-tier suppliers vie for modular pod and hose-drogue awards. Two strategic archetypes dominate: vertically integrated airframers leveraging tanker programs for long-term revenue visibility, and specialized component houses capturing aftermarket replacement cycles. Competitive moves center on strategic partnerships for flight test validation and geographic expansion into Indian and Middle Eastern procurement markets.
Among US-based defense conglomerates, The Boeing Company and Lockheed Martin Corporation occupy positions as prime platform integrators with embedded boom system franchises. Airbus SE represents the European vertically integrated archetype competing through multi-role tanker transport offerings. These three anchors exemplify the split between American and European procurement blocs, with each sitting within distinct regulatory spheres shaped by FAA and EASA certification requirements respectively.
| Leading Market Players |
|---|
| The Boeing Company |
| Airbus SE |
| Lockheed Martin Corporation |
| Eaton Corporation plc |
| Cobham plc |
| GE Aviation |
| Safran |
| Israel Aerospace Industries Ltd. |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Bifurcation between integrated boom systems and commodity hose-drogue hardware manifests in divergent pricing architectures and supply chain footprints across the air-to-air refueling market. Premium boom suppliers capture value through 30-year platform support contracts that embed flight control software and receiver certification services, while probe-drogue manufacturers compete on unit economics and regional logistics reach.
Pricing Analysis
Bundled platform integration contracts versus unbundled aftermarket component sales split pricing models across supplier tiers. Boom system pricing stratifies across performance tiers tied to USAF NAVAIR technical directive compliance and FAA Part 25 certification grades, with prime contractors commanding substantial premiums for electromagnetic-hardened architectures. Cost compression in hose-drogue hardware intensifies as NATO Support and Procurement Agency category management collapses price differentiation across European member states. Commercial cargo operators exhibit highest price sensitivity through wet-lease tanker arrangements, while defense procurement offices remain least sensitive due to mission-critical specifications and multi-year indefinite-delivery vehicles.
Supply Chain Analysis
Regional distribution centers in Wichita, Toulouse, and Hamburg anchor hub-and-spoke patterns for flight control actuators and precision boom components. Manufacturing concentration centers on the United States, France, and Germany for platform integration, with specialized hose-reel production drawing from the United Kingdom and Israel. Aerospace-grade titanium sponge from Russian-sourced VSMPO-AVISMA and precision actuators from German and Japanese suppliers constitute critical input dependencies. Single-source actuator concentration creates chokepoint vulnerability for boom positioning systems. Distribution runs through military procurement agencies and OEM captive service networks rather than open aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air-to-air refueling market functions as a stable compounder anchored by irreplaceable defense modernization cycles and tanker fleet recapitalization programs that extend across multiple platform generations.
For Market Incumbents: Acquire flight test engineering talent pools to counter retirements outpacing training pipeline output at Pax River and Edwards. Lock in 30-year platform support contracts before autonomous refueling demonstrations rewrite technical specifications, and deepen backward integration into precision actuator supply to mitigate German and Japanese single-source concentration risk. For New Entrants and Emerging Players: Capture aftermarket hose-drogue replacement cycles across NATO Pacific squadrons where corrosion-prone rubber hoses reach service limits in maritime environments. Target India's pending multi-role tanker transport tender as a greenfield opportunity to establish regional maintenance infrastructure, and pursue modular refueling pod architectures that separate hardware from airframe-specific integration under five-year rolling contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where autonomous-digital convergence demands machine vision and precision GPS fusion capabilities beyond legacy supplier competencies. Five-to-ten-year viability favors vertically integrated platform integrators with embedded boom franchises over standalone component houses facing commoditization. Watch for FAA Part 25 certification timeline compression as an inflection indicator that would accelerate competitive windows for mid-tier entrants with validated flight test infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Refueling Capability Development | Machine vision fusion with GPS formation-keeping algorithms reduces receiver pilot workload and extends operational tempo. |
| Modular Refueling Pod Architecture | Separating fuel transfer hardware from airframe integration allows specialized manufacturers to compete for subsystem awards. |
| Precision Actuator Supply Security | Mitigating German and Japanese single-source concentration protects boom flight control system availability for platform integrators. |
| India Defense Market Entry | Establishing regional maintenance infrastructure captures greenfield demand from the Indian Air Force's multi-role tanker transport tender. |
| EASA CS-25 Certification Harmonization | Reducing duplicate qualification costs accelerates cross-border equipment approvals for European suppliers seeking transatlantic contracts. |
Methodological Framework
Multiple input streams — primary interviews with tanker program managers, flight test engineers, and defense procurement officers; secondary validation through USAF technical directives, FAA Part 25 certification filings, and EASA CS-25 regulatory databases; plus customs and trade data on aerospace-grade titanium flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged platform integration specialists at Boeing, Airbus Defence and Space, and Lockheed Martin, alongside subsystem suppliers at Cobham and Israel Aerospace Industries. Secondary sources encompassed NAVAIR program documentation, NATO Support and Procurement Agency category management records, and bilateral defense ministry tender announcements.
Historical program expenditure patterns were cross-referenced against expert panel inputs on autonomous refueling development timelines and tanker fleet recapitalization schedules. Segmentation modeling spanned technology architecture, end-user procurement tier, receiver aircraft application, and product type across the projection horizon. CAGRs were derived from platform delivery schedules, aftermarket replacement cycle analysis, and defense budget trajectory assumptions. Industry-specific forecast inputs included KC-46 program ramp rates, A330 MRTT export order pipelines, and probe-drogue retrofit penetration across NATO fighter squadrons.
Underlying measurement precision varies by segment; integrated boom systems with 30-year contract visibility carry tighter precision than emerging commercial cargo applications where tanker-enabled route economics remain unproven. Forecasts reflect documented assumptions on defense budget continuity, certification timeline stability, and titanium supply chain resiliency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market