
 Global Mine Detection System Market | 2026-2036
Global Mine Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mine Detection System Market Analysis
Software-defined signal processing is repositioning how detection capabilities get packaged and sold, shifting value from hardware acquisition to algorithmic performance guarantees. BAE Systems leverages its electronic warfare heritage to anchor premium positioning in electromagnetic detection subsystems. Northrop Grumman Corporation sustains R&D intensity across integrated sensor fusion architectures. Israel Aerospace Industries specializes in compact airborne platforms that extend operational reach for remote monitoring deployments.
A mine detection system integrates multiple sensor modalities to locate and characterize buried or concealed explosive hazards without triggering detonation. Ground-penetrating radar arrays operate at frequencies between 100 MHz and 2.6 GHz to resolve metallic and non-metallic threats at depths exceeding 30 centimeters in varied soil conditions, serving military clearance operations and humanitarian demining programs. Electromagnetic detection and ground-penetrating radar currently occupy the largest installed base, while chemical sensors represent the fastest-expanding technology segment as vapor-sensing sensitivity improves. Vehicle-mounted systems command the dominant share of product-type value, though drone-based platforms are displacing legacy approaches in inaccessible terrain.
The U.S. Department of Defense mandates MIL-STD-810 environmental testing and MIL-STD-461 electromagnetic compatibility certification for fielded detection equipment, directly shaping product development roadmaps and supplier qualification timelines. The EU Green Deal's land restoration targets, enforced through ECHA contamination assessment protocols, create parallel civilian demand streams for post-conflict environmental verification. Stakeholders must monitor how NATO standardization agreements evolve to accommodate AI-enabled autonomous detection, as interoperability certification will determine market access across allied procurement programs.
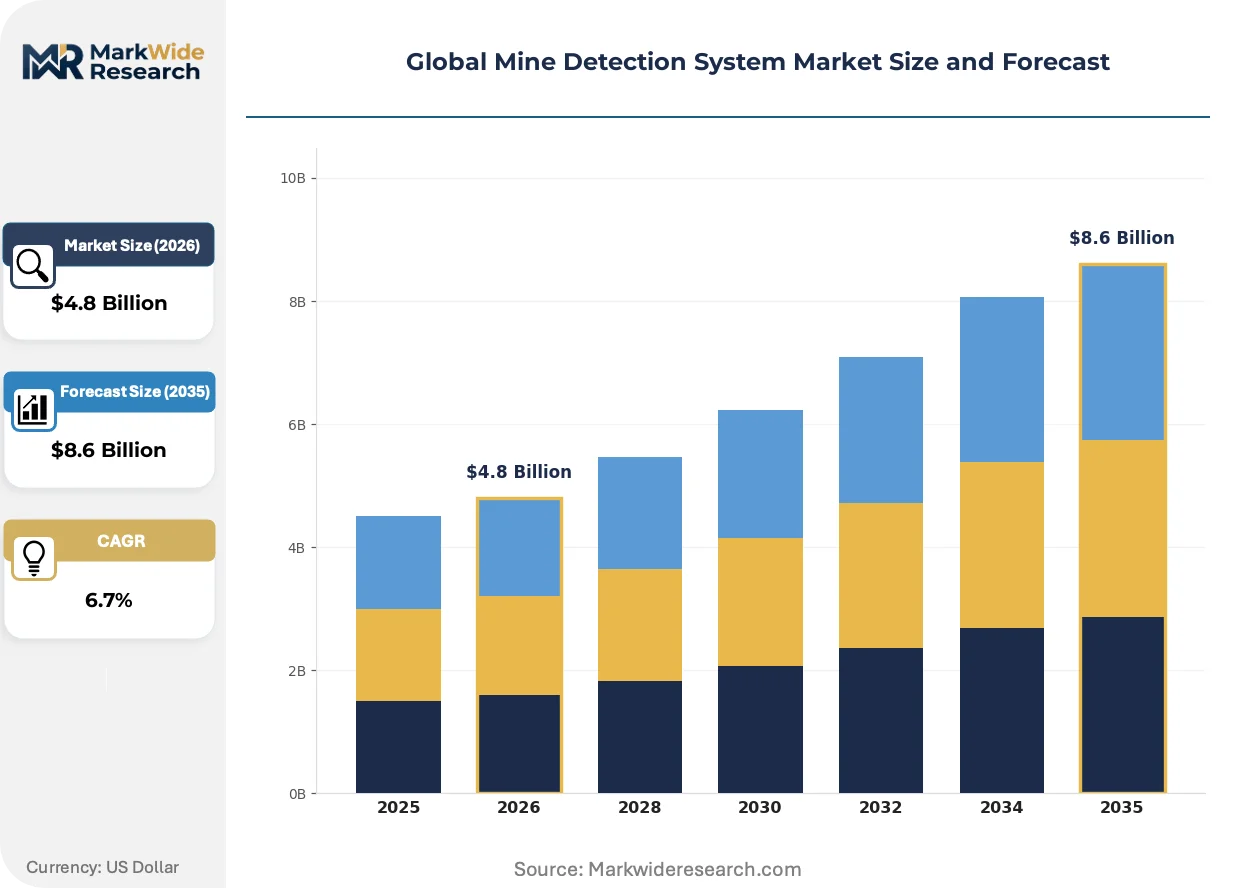
Market Dynamics
Software-defined signal processing is collapsing traditional hardware margins while NATO interoperability mandates force architectural convergence across allied procurement programs.
Growth Catalysts
- EU Green Deal land restoration mandates:ECHA contamination assessment protocols create civilian demand streams for post-conflict environmental verification systems.
- Drone-based platform adoption:Military operators in inaccessible terrain are retiring vehicle-mounted legacy systems for compact airborne detection architectures.
- NATO standardization agreements:AI-enabled autonomous detection certification requirements are harmonizing cross-border procurement specifications.
Market Restraints
- Rare earth magnet supply concentration:Electromagnetic sensor production depends on neodymium processing capacity concentrated in China.
- MIL-STD-810 environmental testing costs:Extended qualification timelines for U.S. Department of Defense certification compress vendor cash conversion cycles.
- Ground-penetrating radar performance ceilings:Clay-rich soil attenuation limits detection reliability below 30 centimeters in tropical laterite regions.
Strategic Opportunities
- Chemical sensor vapor-sensing sensitivity improvements:Picogram-level detection thresholds open non-metallic threat identification previously invisible to electromagnetic methods.
- Humanitarian demining procurement in Southeast Asia:Post-conflict clearance programs in Cambodia and Laos represent underpenetrated demand for integrated detection platforms.
- Algorithmic performance guarantee contracts:Software-defined architectures enable outcome-based pricing models displacing capital equipment sales.
Industry Challenges
- Electromagnetic compatibility engineering talent scarcity:MIL-STD-461 certification expertise concentrates among defense electronics veterans nearing retirement.
- Multi-sensor fusion integration complexity:Ground-penetrating radar, electromagnetic, and chemical data streams require specialized signal processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mine Detection System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ground Penetrating Radar, Electromagnetic Detection, Acoustic Detection, Chemical Sensors Deployment: On-Site, Remote Monitoring, Mobile Platforms, Integrated Systems End User: Military, Humanitarian Agencies, Government, Private Security Product Type: Handheld Devices, Vehicle-Mounted Systems, Drones, Fixed Installations |
| Companies Covered | BAE Systems, Israel Aerospace Industries, Northrop Grumman Corporation, L3Harris Technologies, Lockheed Martin Corporation, Raytheon Technologies Corporation, Chemring Group, MBDA, DCD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mine Detection System Market Emerging Trajectories
Detection architectures are decoupling from fixed hardware platforms as computational workloads migrate to edge processors and cloud-based training pipelines.
Multi-static ground-penetrating radar arrays operating between 100 MHz and 2.6 GHz are overtaking single-channel systems in military clearance contracts. German federal defense procurement offices now specify adaptive frequency-hopping modalities for metallic and non-metallic threat discrimination. This compression of hardware differentiation into software-tunable parameters is collapsing premium pricing for fixed-frequency legacy equipment.
The EU AI Act risk classification framework is redefining liability allocation for autonomous detection decisions in humanitarian demining operations. Equipment vendors must now document algorithmic training data provenance and decision audit trails for CE marking eligibility. French and Belgian procurement agencies are requiring conformity assessment body involvement at the design stage rather than post-manufacturing verification.
Performance-based service contracts are displacing capital purchase agreements in NATO allied interoperability programs. Danish and Norwegian defense ministries now contract for cleared lane kilometers rather than detector unit deliveries. This shift concentrates vendor risk on operational outcomes while transferring sensor obsolescence exposure from government balance sheets to supplier portfolios.
Global Mine Detection System Market Segmentation
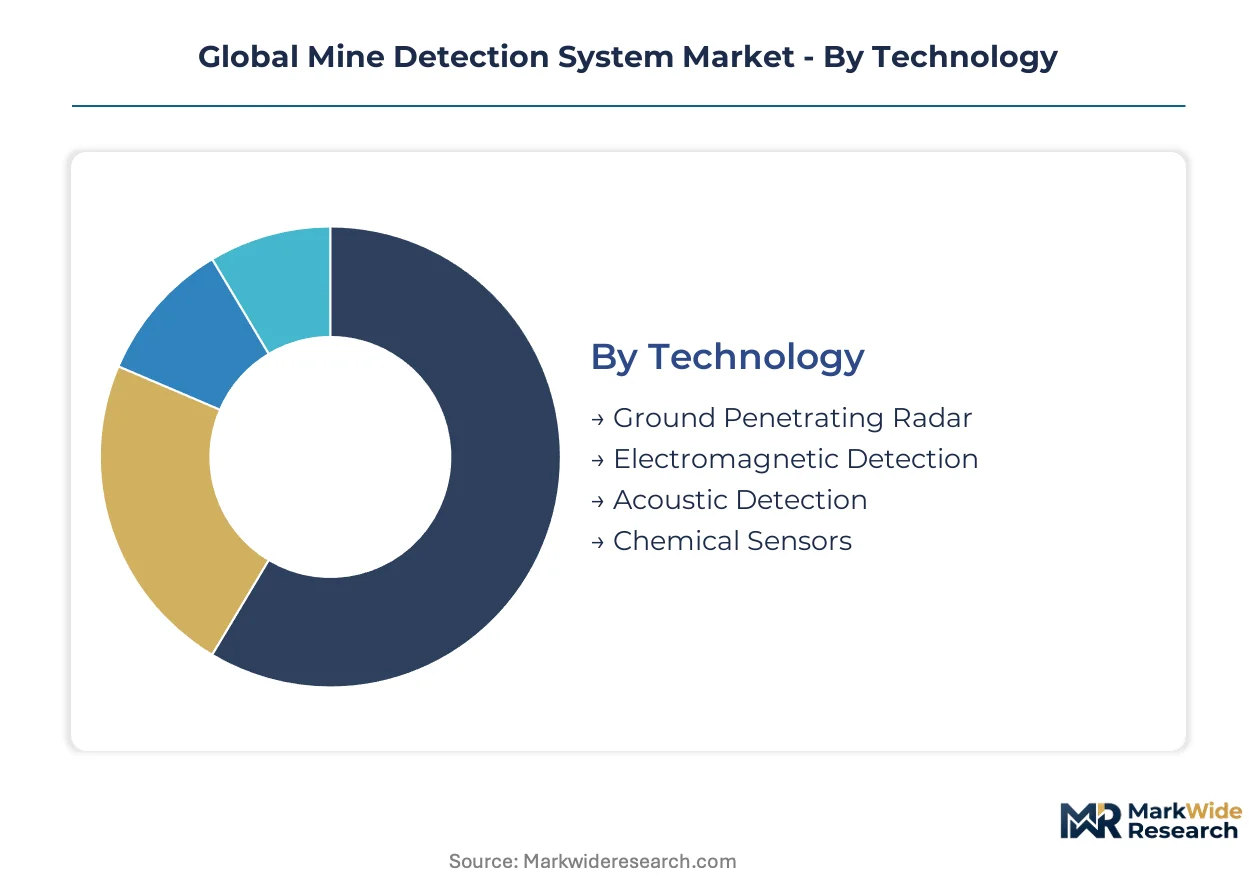
Technology modality determines procurement specifications across NATO interoperability programs. Deployment architecture shapes operational cost structures and sensor refresh cycles. End-user classification governs certification requirements and liability frameworks.
Technology:
Procurement officers weigh detection depth against false-alarm rates when specifying sensor modality.
- Ground Penetrating Radar:Arrays operating between 100 MHz and 2.6 GHz resolve metallic and non-metallic threats below 30 centimeters in varied soil conditions. German federal defense budgets prioritize adaptive frequency-hopping modalities for allied interoperability certification.
- Electromagnetic Detection:Neodymium-dependent sensor coils identify ferrous anomalies through magnetic field distortion. Clay-rich tropical laterite regions constrain reliability, driving R&D intensity toward multi-static array architectures.
- Acoustic Detection:Seismic signature analysis discriminates buried ordnance from geological clutter in rock-dominated terrain.
- Chemical Sensors:Picogram-level vapor-sensing thresholds now detect non-metallic explosive compounds invisible to electromagnetic methods.
Volume sits with Electromagnetic Detection; growth tilts toward Chemical Sensors.
Deployment:
Operational tempo and personnel risk exposure dictate platform selection across clearance programs.
- On-Site:Personnel-operated detectors for lane verification and quality assurance in humanitarian demining contracts.
- Remote Monitoring:Satellite-linked sensor networks enable persistent surveillance of contested corridors without ground presence. Cambodian and Laotian clearance programs contract for airborne remote architectures in inaccessible terrain.
- Mobile Platforms:Vehicle-mounted arrays integrate ground-penetrating radar with electromagnetic coils for route clearance at convoy speeds.
- Integrated Systems:Multi-sensor fusion architectures combine radar, electromagnetic, and chemical data streams through edge processors. Danish and Norwegian defense ministries now contract for cleared lane kilometers rather than discrete unit deliveries.
Procurement volume concentrates in Mobile Platforms; Integrated Systems are climbing the fastest on NATO standardization alignment.
End User:
Budget cycle predictability and liability exposure shape vendor engagement strategies.
- Military:MIL-STD-810 environmental testing and MIL-STD-461 electromagnetic compatibility certification mandate extended qualification timelines. U.S. Department of Defense procurement compresses vendor cash conversion cycles.
- Humanitarian Agencies:EU Green Deal land restoration targets enforce ECHA contamination assessment protocols for post-conflict environmental verification.
- Government:Federal defense ministries balance interoperability requirements against sovereign industrial base preservation.
- Private Security:Commercial site protection contracts prioritize rapid deployment over depth penetration.
Military commands procurement volume; Humanitarian Agencies are gaining share fastest on EU remediation mandates.
Product Type:
Platform mobility determines sensor payload constraints and algorithmic processing location.
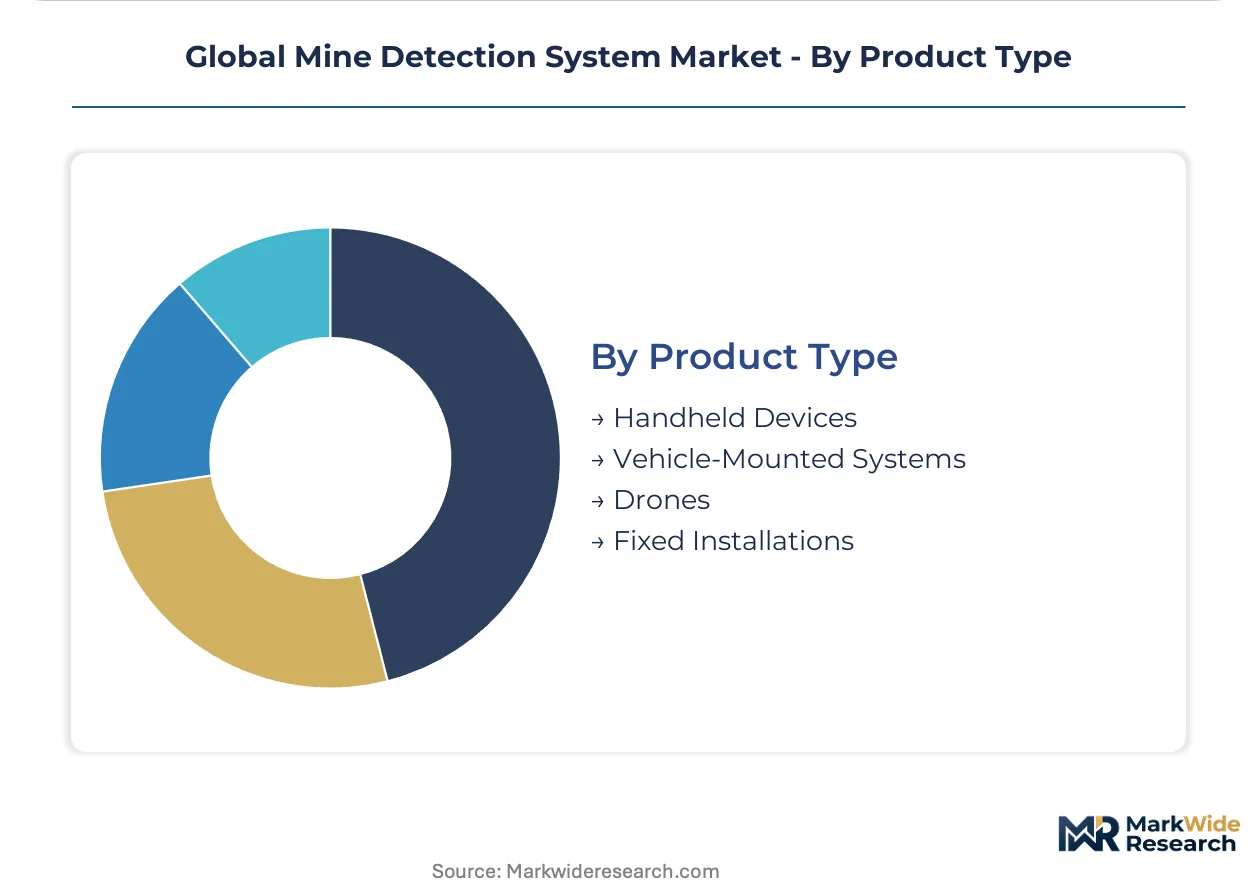
- Handheld Devices:Single-operator detectors for final verification and technical survey in dense vegetation.
- Vehicle-Mounted Systems:Dominant installed base for military route clearance with integrated ground-penetrating radar arrays. Germany specifies adaptive frequency-hopping modalities for threat discrimination at convoy speeds.
- Drones:Compact airborne platforms extend operational reach for remote monitoring deployments. Israel Aerospace Industries specializes in battery-optimized architectures for tropical laterite regions.
- Fixed Installations:Perimeter monitoring arrays for permanent base protection and border corridor surveillance.
Revenue concentrates in Vehicle-Mounted Systems; Drones show the steepest expansion trajectory on terrain accessibility demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin anchors European procurement coordination for NATO interoperability programs, while Tel Aviv and Huntsville, Alabama drive parallel development clusters for electromagnetic and radar subsystems. Federal defense budgets in Germany and the United States concentrate vendor qualification activity in these metropolitan corridors.
United States
The U.S. Department of Defense sustains the largest military procurement volume for vehicle-mounted detection arrays. MIL-STD-810 environmental testing and MIL-STD-461 electromagnetic compatibility certification mandates compress vendor cash conversion cycles. Huntsville, Alabama hosts concentrated defense electronics engineering talent serving route clearance modernization programs.
Germany
Federal defense budgets prioritize demining technology modernization alongside allied interoperability requirements. The EU Green Deal's land restoration targets enforce ECHA contamination assessment protocols for post-conflict environmental verification. Berlin coordinates NATO standardization agreement negotiations for AI-enabled autonomous detection certification.
Israel
Israel Aerospace Industries specializes in compact airborne platforms that extend operational reach for remote monitoring deployments. The country's defense procurement offices specify battery-optimized architectures for tropical laterite regions. Tel Aviv's electronics cluster concentrates electromagnetic sensor fusion expertise for drone-based detection systems.
United Kingdom
BAE Systems leverages its electronic warfare heritage to anchor premium positioning in electromagnetic detection subsystems. The Ministry of Defence contracts for cleared lane kilometers rather than discrete unit deliveries under performance-based service models. London coordinates Chemring Group and MBDA integration into NATO allied interoperability programs.
France
The EU AI Act risk classification framework redefines liability allocation for autonomous detection decisions in humanitarian demining operations. French procurement agencies require conformity assessment body involvement at the design stage rather than post-manufacturing verification. Paris anchors ANSM and CNIL regulatory coordination for algorithmic training data provenance documentation.
Global Mine Detection System Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the detection architecture value chain. The market exhibits tiered concentration with defense primes controlling integrated system contracts and specialized subcontractors supplying sensor subassemblies. Three archetypes dominate: electronic warfare heritage primes, compact airborne platform specialists, and multi-sensor fusion integrators. Competitive dynamics center on NATO interoperability certification attainment and algorithmic performance guarantee contract structures.
Within the electronic warfare heritage tier, BAE Systems exemplifies premium positioning through electromagnetic subsystem anchoring. Northrop Grumman Corporation occupies a position sustaining R&D intensity across integrated sensor fusion architectures. Israel Aerospace Industries represents the compact airborne platform specialist archetype, with battery-optimized architectures serving remote monitoring deployments in tropical terrain.
| Leading Market Players |
|---|
| BAE Systems |
| Israel Aerospace Industries |
| Northrop Grumman Corporation |
| L3Harris Technologies |
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| Chemring Group |
| MBDA |
| DCD |
| Others |
Supply Flow & Price Mechanics
Electromagnetic compatibility engineering talent concentrated in Huntsville, Alabama and Tel Aviv drives labor-cost differentials that widen pricing-tier spreads between MIL-STD-461 certified integrated systems and uncertified component sales.
Pricing Analysis
Cleared-lane-kilometer guarantees anchor value-based pricing in Danish and Norwegian defense contracts, displacing per-unit equipment transactions. Pricing stratifies across NATO interoperability certification tiers, algorithmic performance thresholds, and after-sales service bundling. Cost compression in vehicle-mounted legacy systems intensifies as drone-based platforms capture inaccessible-terrain contracts. Humanitarian agencies in Southeast Asia exhibit highest price sensitivity; military procurement offices in Germany and the United States demonstrate lowest sensitivity due to sovereign capability requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium processing capacity for electromagnetic sensor coil production. Manufacturing draws from Germany, Israel, and the United States for final system integration, with sensor subassemblies sourced from the United Kingdom and France. Tariff exposure on rare earth magnet imports presents structural risk to electromagnetic detection margins. Distribution runs through defense prime contractors holding NATO interoperability certification rather than direct vendor-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined signal processing architectures are displacing fixed-frequency hardware platforms, compressing margins for legacy equipment vendors while concentrating value in algorithmic performance guarantees.
For Market Incumbents: Acquire specialized signal processing engineering teams to anchor MIL-STD-461 certification capacity before electromagnetic compatibility talent attrition accelerates. Consolidate multi-sensor fusion IP through targeted asset purchases in ground-penetrating radar array design. Drone-based platform entrants threaten vehicle-mounted system incumbents; defend through backward integration into compact airborne payload engineering.
For New Entrants and Emerging Players: Humanitarian demining procurement offices in Cambodia and Laos represent channel partners with lowest incumbent penetration. Target chemical sensor vapor-sensing sensitivity improvements for non-metallic threat identification white space. Pursue algorithmic performance guarantee contracts as the go-to-market angle to bypass capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with multi-sensor fusion integrators given NATO standardization agreement harmonization for AI-enabled autonomous detection. Long-term viability favors vendors with demonstrated ECHA contamination assessment protocol compliance for EU Green Deal land restoration contracts. Watch Danish and Norwegian defense ministry procurement shifts toward cleared-lane-kilometer service models as inflection indicator for outcome-based pricing adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Performance Guarantee Contracts | Shifts revenue from capital equipment to outcome-based service models in NATO procurement. |
| Multi-Sensor Fusion Architecture Development | Integrates ground-penetrating radar, electromagnetic, and chemical data streams through edge processors. |
| MIL-STD-461 Certification Investment | Qualifies vendors for U.S. Department of Defense electromagnetic compatibility mandates. |
| Humanitarian Demining Channel Partnership | Opens access to Cambodia and Laos post-conflict clearance programs with limited incumbent presence. |
| Chemical Sensor Vapor-Sensing R&D | Enables picogram-level detection thresholds for non-metallic explosive compounds. |
Methodological Framework
Multi-period observation of NATO procurement specification evolution and EU regulatory framework development anchored the trend analysis, supplemented by interviews with defense procurement officers, electromagnetic subsystem engineers, humanitarian demining program directors, and ECHA regulatory compliance specialists. Secondary validation drew from U.S. Department of Defense contract announcements, EU Green Deal implementation documents, NATO standardization agreement publications, and defense electronics SEC filings. Bottom-up vendor revenue triangulation against top-down military expenditure allocation models calibrated market sizing.
Input-output matrices mapped sensor modality adoption rates to deployment platform procurement flows across the projection horizon. Segmentation dimensions modeled include technology modality, deployment architecture, end-user classification, and product type mobility tier. CAGRs derived from fitted growth curves applied to military modernization budget trajectories and EU land restoration mandate enforcement timelines. Forecast inputs incorporated rare earth magnet supply concentration scenarios and algorithmic training data provenance requirements under the EU AI Act.
Caveats apply where NATO interoperability certification timeline delays or ECHA contamination assessment protocol revisions could materially shift the outlook. Forecasts reflect assumptions regarding electromagnetic compatibility engineering talent availability and Chinese neodymium export policy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Military Radar Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market