
 Europe Hydrographic Survey Equipment Market | 2026-2036
Europe Hydrographic Survey Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydrographic Survey Equipment Market Insights
Premium multibeam sonar suites is decoupling from commodity singlebeam offerings as offshore wind developers demand centimetric bathymetric precision. Kongsberg Gruppen ASA leverages its integrated Seapath and SIS software ecosystem to dominate high-end vessel-based deployments. Teledyne Marine sustains competitive pressure through its distributed transducer manufacturing across Scandinavian facilities. Innomar Technologie GmbH specializes in parametric sub-bottom profiler technology for shallow-water geotechnical surveys.
Europe hydrographic survey equipment encompasses integrated sensor platforms that measure water depth, seabed topography, and sub-surface stratigraphy using acoustic propagation principles, typically operating at frequencies between 12 kHz and 400 kHz depending on resolution requirements. These systems serve commercial and governmental end users conducting marine construction feasibility studies, environmental compliance monitoring, and nautical chart production. Multibeam echo sounding technology leads product development investment as port authorities and cable-lay contractors replace legacy singlebeam inventories. Autonomous underwater vehicles represent the fastest-expanding technology segment as battery endurance and navigation accuracy improve for long-duration seabed mapping missions. Government agencies anchor steady demand through hydrographic office modernization programs and exclusive economic zone boundary delineation.
EMA's marine equipment directives and the EU Marine Strategy Framework Directive shape product certification requirements and environmental survey scope across member states. REACH compliance governs transducer piezoelectric material composition and anti-fouling coating chemistries deployed in European waters. Norway's national hydrographic service and the UK's Maritime and Coastguard Agency enforce IHO S-44 survey standards for all publicly funded seabed mapping. Stakeholders must monitor evolving EU seabed mining regulations and their associated baseline survey obligations to anticipate procurement shifts among research institutions and marine contractors.
Market Dynamics
The EU Marine Strategy Framework Directive is compressing survey timelines for subsea infrastructure developers. Offshore wind farm operators now commission centimetric-precision bathymetric studies before cable-lay operations, forcing equipment upgrades across North Sea survey fleets.
Growth Catalysts
- Offshore wind expansion:Developers in the North Sea basin require multibeam sonar systems for seabed characterization prior to turbine foundation installation. Norwegian, UK, and Danish territorial waters concentrate procurement activity.
- EMA marine equipment directives:Certification mandates for acoustic transducers deployed in European waters sustain replacement demand. Piezoelectric material compliance under REACH regulations accelerates hardware refresh cycles.
- Autonomous underwater vehicles:Battery endurance improvements enable long-duration seabed mapping missions. Port authorities and cable contractors deploy AUV swarms to reduce vessel-day costs.
Market Restraints
- Transducer supply concentration:Piezoelectric ceramic fabrication concentrates in specialized European foundries. Raw material volatility for lead zirconate titanate compounds creates input cost pressure.
- Technical resolution trade-offs:Higher-frequency multibeam arrays deliver precision but sacrifice water-column penetration. Deep-water geotechnical surveys require redundant singlebeam backup systems.
- REACH regulatory friction:Anti-fouling coating chemistries face restricted substance lists. Transducer manufacturers reformulate protective layers, extending product validation timelines.
Strategic Opportunities
- Baltic Sea underpenetration:Polish and German offshore wind leasing rounds generate new survey demand. Shallow-water parametric profiler deployments lag North Sea adoption rates.
- EU seabed mining regulations:Anticipated baseline survey obligations for polymetallic nodule exploration create procurement pipelines. Research institutions pre-position equipment for environmental monitoring mandates.
- LiDAR-bathymetry convergence:Topobathymetric sensors integrate airborne laser with acoustic depth measurement. Coastal zone management agencies consolidate mapping contracts under unified platforms.
Industry Challenges
- Multibeam calibration expertise scarcity:IHO S-44 standard compliance requires specialized hydrographic surveyors. Training pipelines for patch test execution and uncertainty budgeting remain underdeveloped.
- Legacy singlebeam integration:Port authorities maintain decades-old echo sounder inventories. Hybrid fleet operations demand software bridges between analog and digital acquisition systems.
- Capex intensity for AUV docking:LARS (launch and recovery systems) infrastructure requires dedicated vessel modifications. Survey contractors defer autonomous platform investments pending charter rate recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydrographic Survey Equipment Market |
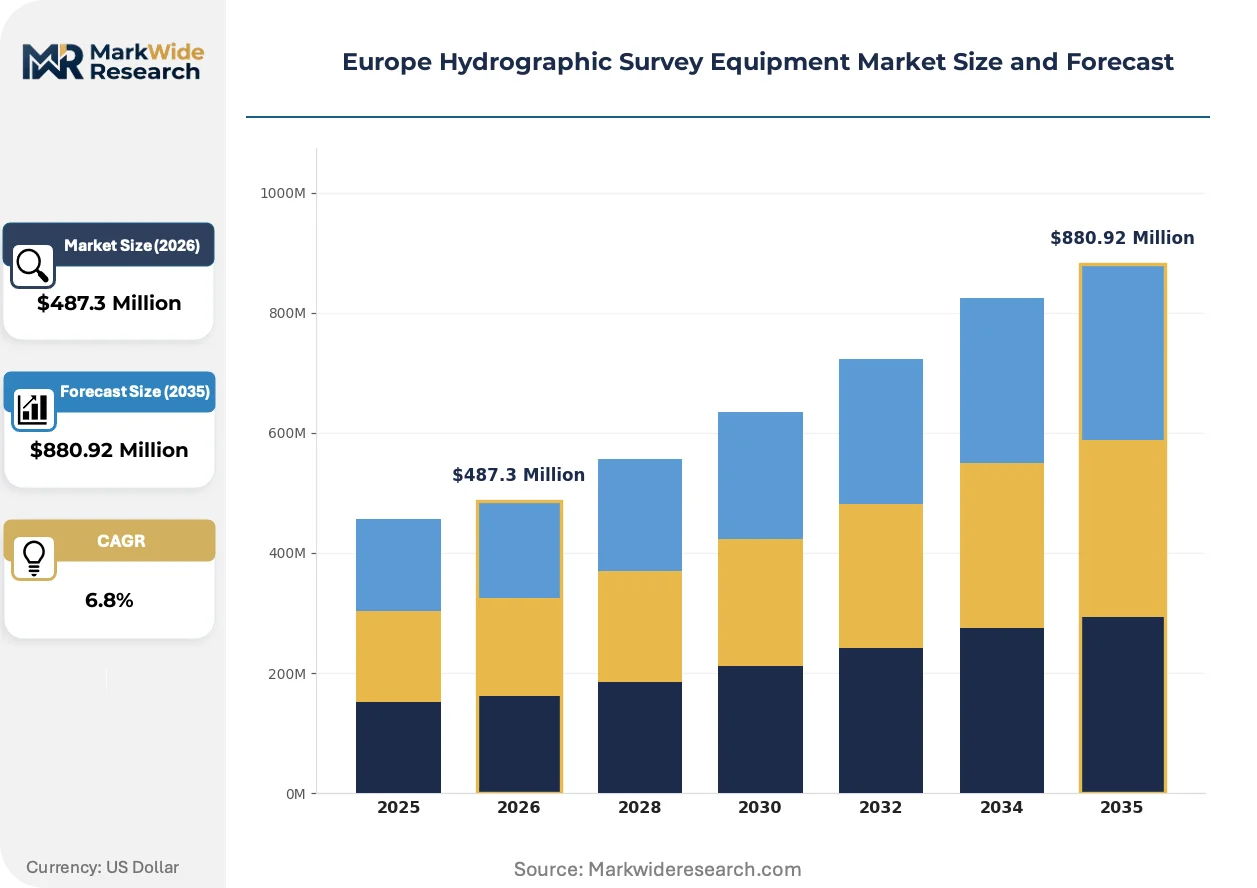
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sonar Systems, GPS Equipment, Data Acquisition Systems, Survey Boats Technology: Multibeam Echo Sounding, Singlebeam Echo Sounding, LiDAR, Autonomous Underwater Vehicles Application: Marine Construction, Environmental Monitoring, Dredging Operations, Fishery Management End User: Government Agencies, Research Institutions, Marine Services, Contractors |
| Companies Covered | Kongsberg Gruppen ASA, Teledyne Marine, Fugro N.V., Trimble Inc., Hexagon AB, Sonardyne International Ltd., iXblue, Innomar Technologie GmbH, Norbit ASA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydrographic Survey Equipment Market Trends and Innovations
Acoustic sensor architectures are fragmenting along precision-grade lines. Vessel-based multibeam suites diverge from portable singlebeam units as end-use specifications tighten.
Multibeam echo sounding technology is overtaking singlebeam systems in commercial seabed mapping contracts. Offshore wind developers specify centimetric vertical uncertainty for turbine foundation sites. Port authorities in Rotterdam and Hamburg are compressing their singlebeam replacement schedules to meet IHO S-44 Special Order standards.
REACH compliance is reshaping transducer manufacturing workflows across European facilities. Piezoelectric material composition now requires full substance registration dossiers. Danish and Norwegian survey equipment distributors are prioritizing suppliers with pre-certified ceramic supply chains to avoid customs delays.
Charter-based survey contracting is displacing permanent vessel ownership among marine construction firms. Cable-lay contractors in the North Sea basin now source vessel-plus-sensor packages on project-specific terms. This procurement compression is most visible in UK territorial waters, where offshore wind round allocations create surge demand spikes.
Europe Hydrographic Survey Equipment Market Segmentation
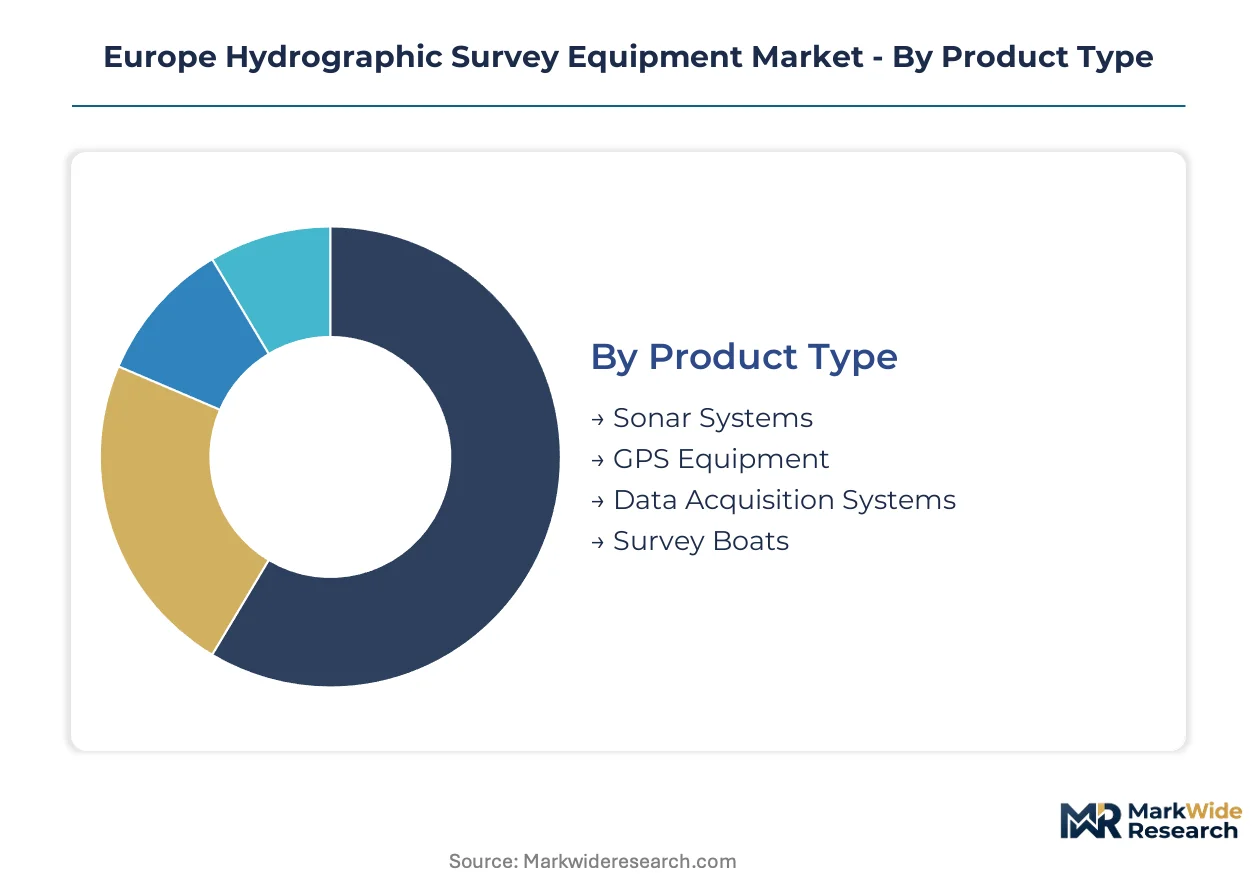
Equipment segmentation in European hydrographic surveying reflects divergent precision requirements across offshore wind, port modernization, and environmental compliance mandates. Procurement patterns split between integrated vessel-based suites for capital projects and portable systems for rapid-deployment surveys.
Product Type:
Standardization dominates sonar and GPS hardware, while survey boats and data acquisition systems fragment across custom vessel integrations.
- Sonar Systems:Multibeam and parametric sub-bottom profilers constitute the technical core of seabed characterization. Norwegian and UK offshore wind developers specify Kongsberg and Teledyne suites for turbine foundation surveys, driving premium-tier procurement.
- Data Acquisition Systems:Software-integrated sensor fusion platforms coordinate position, motion, and acoustic data streams. Port authorities in Rotterdam and Hamburg prioritize IHO S-44 compliant acquisition architectures to compress chart production cycles.
- GPS Equipment:RTK-GNSS and inertial motion units provide centimetric positioning for multibeam swath coverage.
- Survey Boats:Custom aluminum and RIB configurations vary by draft requirements and payload capacity.
Leading the category by volume: Sonar Systems. Growing fastest: Data Acquisition Systems.
Technology:
Frequency selection and platform autonomy create distinct cost tiers, from vessel-towed multibeam arrays to battery-powered AUV swarms.
- Multibeam Echo Sounding:High-frequency acoustic arrays deliver centimetric vertical uncertainty across wide swath coverage. North Sea cable-lay contractors mandate multibeam pre-surveys, displacing legacy singlebeam inventories.
- Autonomous Underwater Vehicles:Long-endurance battery systems and improved navigation accuracy enable uncrewed seabed mapping missions. Danish and UK survey contractors deploy AUV swarms to reduce vessel-day costs on repetitive route surveys.
- Singlebeam Echo Sounding:Lower-cost depth measurement persists in shallow-water reconnaissance and backup applications.
- LiDAR:Airborne laser bathymetry penetrates clear coastal waters for topobathymetric fusion.
Multibeam Echo Sounding commands the largest installed base. Autonomous Underwater Vehicles are climbing the fastest as charter-based contracting spreads.
Application:
Capital intensity separates marine construction from recurring environmental monitoring workflows.
- Marine Construction:Offshore wind foundation installation and subsea cable routes demand Special Order survey precision. UK Round 4 and 5 lease allocations concentrate multibeam procurement among North Sea installation contractors.
- Environmental Monitoring:EU Marine Strategy Framework Directive baseline studies require repeat surveys at fixed stations. German and Polish Baltic Sea wind zones generate new parametric profiler demand for benthic habitat mapping.
- Dredging Operations:Volume measurement and channel maintenance sustain singlebeam and multibeam utilization.
- Fishery Management:Habitat classification supports quota allocation and marine protected zone delineation.
Marine Construction generates the highest equipment revenue per project. Environmental Monitoring is expanding most quickly as regulatory survey obligations multiply.
End User:
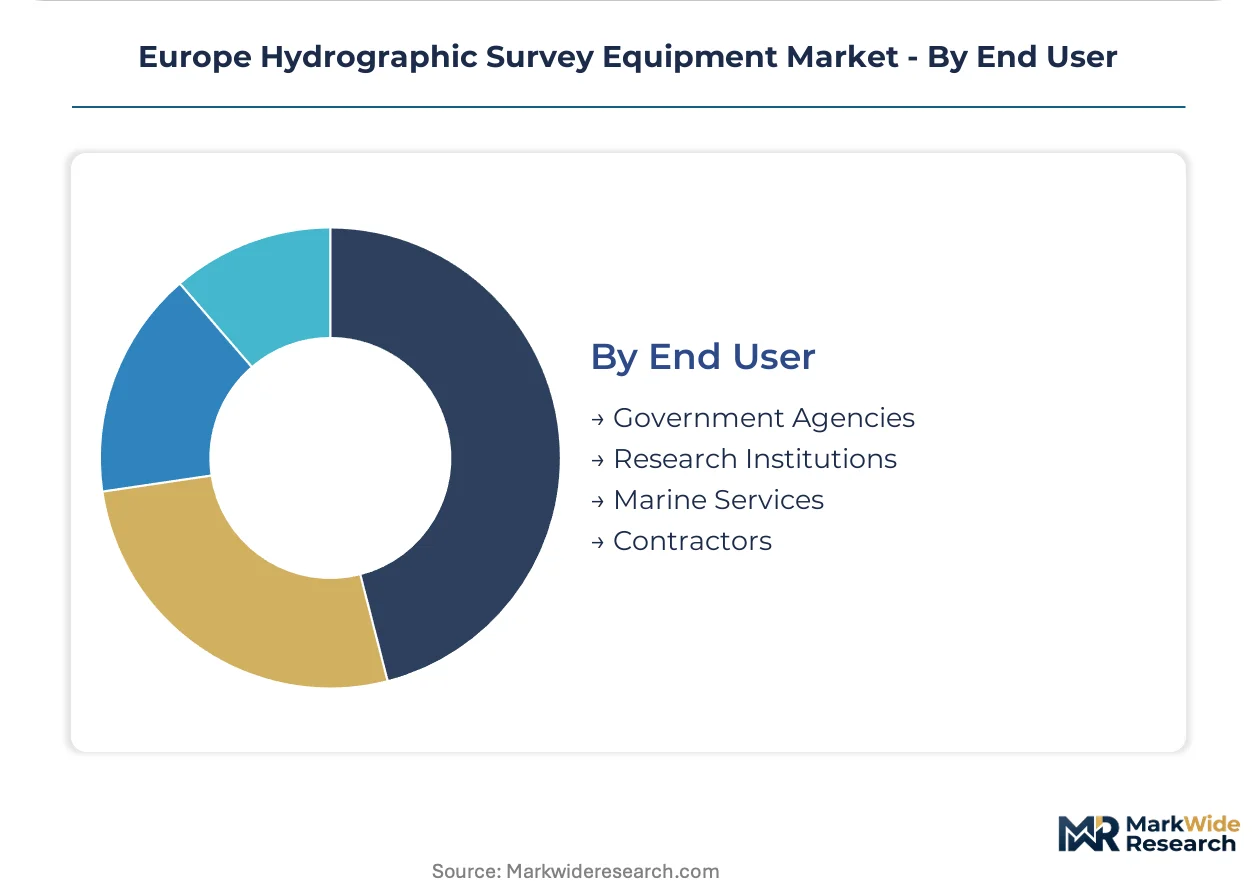
Procurement authority splits between public hydrographic offices with multi-year modernization budgets and private contractors with project-driven equipment sourcing.
- Government Agencies:National hydrographic services in Norway, the UK, and Denmark execute exclusive economic zone mapping and nautical chart updates. IHO S-44 standard enforcement sustains predictable replacement cycles for vessel-based sensor suites.
- Marine Services and Contractors:Charter-based survey firms source equipment on project terms to match offshore wind construction timelines. UK territorial waters show the most pronounced surge-demand patterns from lease round allocations.
- Research Institutions:Universities and oceanographic institutes acquire specialized parametric and sub-bottom systems for academic seabed studies.
Government Agencies anchor steady baseline demand. Marine Services and Contractors are gaining share fastest as vessel-plus-sensor procurement compression accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors European hydrographic survey procurement as the continent's largest port complex drives multibeam sonar replacement cycles. North Sea offshore wind leasing concentrates equipment demand across five territorial basins. REACH compliance and IHO S-44 standard enforcement create divergent certification timelines across member states.
Norway
Stavanger and Bergen harbor clusters sustain vessel-based multibeam deployment for North Sea energy infrastructure. The Norwegian Mapping Authority enforces IHO S-44 Special Order standards for all publicly funded seabed surveys. Kongsberg's integrated Seapath ecosystem dominates high-end installations along the western fjord corridors.
United Kingdom
UK Round 4 and 5 offshore wind allocations generate surge demand spikes for cable-route characterization. The Maritime and Coastguard Agency mandates centimetric bathymetric precision for subsea infrastructure permits. Aberdeen and Great Yarmouth survey contractors compress procurement timelines to match construction windows.
Germany
Baltic Sea wind zone leasing in Mecklenburg-Vorpommern creates new shallow-water parametric profiler demand. ECHA REACH compliance governs piezoelectric ceramic importation for transducer fabrication. Hamburg port authorities accelerate singlebeam replacement schedules to meet Special Order chart production targets.
Denmark
Ørsted and Copenhagen Infrastructure Partners drive AUV swarm deployment for repetitive route surveys. The Danish Maritime Authority enforces EU Marine Strategy Framework Directive baseline studies for cable corridors. Esbjerg serves as the primary North Sea installation staging point for multibeam-equipped charter fleets.
Netherlands
Rotterdam and Amsterdam port modernization sustains steady data acquisition system procurement. Rijkswaterstaat mandates topobathymetric LiDAR fusion for coastal zone management contracts. Delft-based research institutions pre-position parametric systems for anticipated EU seabed mining monitoring obligations.
Europe Hydrographic Survey Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and integration-depth dimensions. The vendor base concentrates around three archetypes: integrated platform specialists commanding vessel-based suites, distributed transducer fabricators supplying component tiers, and autonomous platform developers capturing charter-contractor procurement. Consolidation pressure intensifies as offshore wind developers consolidate preferred supplier lists. Strategic partnerships between sensor manufacturers and survey vessel operators displace arm's-length equipment sales.
Within the integrated platform tier, Kongsberg Gruppen ASA exemplifies Nordic-origin conglomerate positioning through captive software-hardware ecosystems. Teledyne Marine and Innomar Technologie GmbH occupy complementary specialist positions—one representing transatlantic distributed manufacturing scale, the other embodying German parametric technology depth. These three anchors illustrate how geographic clustering around North Sea demand shapes competitive differentiation without requiring uniform scale or vertical scope.
| Leading Market Players |
|---|
| Kongsberg Gruppen ASA |
| Teledyne Marine |
| Fugro N.V. |
| Trimble Inc. |
| Hexagon AB |
| Sonardyne International Ltd. |
| iXblue |
| Innomar Technologie GmbH |
| Norbit ASA |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between IHO S-44 Special Order multibeam suites and commodity singlebeam systems manifests in both pricing premiums and supply chain fragmentation across European hydrographic equipment markets. Premium-tier vessel-based deployments command three-tier pricing structures across premium, standard, and economy levels, while REACH-compliant piezoelectric ceramic sourcing concentrates manufacturing authorization in Scandinavian and German foundries.
Pricing Analysis
Outcome-linked pricing anchors multibeam procurement contracts to survey precision guarantees and chart production cycle compression. Three-tier pricing structure across premium, standard, and economy levels differentiates by IHO certification tier and software integration depth. Cost compression in portable singlebeam tiers intensifies because charter-based contracting squeezes hardware margins. Marine construction contractors exhibit highest price sensitivity; national hydrographic services demonstrate lowest sensitivity due to multi-year modernization budgets.
Supply Chain Analysis
CE marking and REACH substance registration requirements gate transducer supply to pre-certified European ceramic foundries. Manufacturing concentrates in Norway, Denmark, and Germany. Lead zirconate titanate piezoelectric compounds and anti-fouling coating precursors draw from specialized chemical suppliers. Single-source vulnerability persists in high-frequency transducer array fabrication. Distribution runs through national survey equipment distributors with customs clearance expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as sensor manufacturers pursue captive software-hardware ecosystems to lock in charter-contractor procurement. Control over Seapath-class positioning integration represents the decisive downstream lever.
For Market Incumbents: Anticipate AUV swarm deployment compression by securing LARS infrastructure partnerships with North Sea vessel operators. Defensive consolidation through backward integration into piezoelectric ceramic supply chains mitigates REACH registration bottlenecks. Prioritize Seapath-SIS ecosystem deepening against Teledyne's distributed manufacturing scale. For New Entrants and Emerging Players: Direct sales platforms to Baltic Sea wind zone contractors bypass incumbent distributor networks. Polish and German shallow-water parametric profiler deployments offer lowest competitive density. White-space capture through portable sub-bottom systems for benthic habitat mapping accelerates entry before EU seabed mining regulations finalize. For Investors and Strategic Acquirers: Re-rating potential sits with autonomous platform developers given battery endurance improvements and charter-rate recovery catalysts. Five-to-ten-year viability favors AUV specialists with proven docking infrastructure. Monitor Ørsted and Copenhagen Infrastructure Partners procurement patterns as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Supply | REACH pre-certification secures customs clearance advantage for Danish and Norwegian distributors. |
| AUV Docking Infrastructure Partnership | LARS vessel modifications capture charter-contractor procurement compression in UK territorial waters. |
| Parametric Profiler Baltic Expansion | Mecklenburg-Vorpommern wind zones generate shallow-water equipment demand lagging North Sea adoption. |
| Software-Hardware Ecosystem Deepening | Seapath-SIS integration locks in premium multibeam procurement against distributed transducer competitors. |
| EU Seabed Mining Pre-Positioning | Research institution equipment pipelines anticipate baseline survey obligations for polymetallic exploration. |
Research Methodology
Document review covered EU Marine Strategy Framework Directive implementation guidance, ECHA REACH substance registration dossiers, and IHO S-44 standard technical specifications, complemented by interviews with hydrographic survey fleet managers, port authority procurement officers, offshore wind foundation contractors, and transducer manufacturing quality leads. Secondary validation drew from Norwegian Mapping Authority annual reports, UK Maritime and Coastguard Agency permit filings, and customs trade data for piezoelectric ceramic imports. Bottom-up equipment unit demand estimates triangulated against top-down offshore wind construction pipeline valuations.
Installed base projections and replacement cycle analysis across the analysis window incorporated segmentation by product type, technology platform, application intensity, and end-user procurement authority. CAGRs derived from multibeam echo sounding displacement rates for singlebeam inventories, AUV battery endurance improvement curves, and Baltic Sea wind zone leasing acceleration. Industry-specific inputs included IHO S-44 Special Order compliance timelines and REACH substance restriction phase-in schedules.
The model holds under stable EU regulatory enforcement and continued North Sea offshore wind allocation; deviation in seabed mining regulation timing or transducer ceramic supply disruption would shift equipment procurement trajectories. Forecasts reflect assumptions regarding charter-contractor market share expansion and AUV swarm deployment cost thresholds. A model refresh is warranted upon material change in EU seabed mining baseline survey mandates or IHO S-44 standard revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
UXO Detection Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Military Jammer Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Global Airborne Surveillance Market