
 Japan Space Electronics Market | 2026-2036
Japan Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Space Electronics Market Insights
Aerospace engineering talent is rotating from legacy aviation programs into satellite and launch vehicle electronics, loosening a long-standing bottleneck for domestic suppliers. NEC leverages its heritage in government satellite systems to anchor high-reliability contract flows. Mitsubishi Heavy Industries sustains vertical integration across launch vehicle avionics and ground control infrastructure. Canon Electronics specializes in compact optical payloads and miniature attitude control systems for small satellites.
Japan space electronics encompass radiation-hardened components, high-efficiency power conditioning units, and Ka-band communication modules engineered for orbital thermal cycling and single-event upset immunity, serving missions from low-Earth orbit to lunar transfer trajectories. Power systems and communication systems dominate current procurement volumes, reflecting the satellite replenishment cycle and defense relay programs. Gallium nitride technology is displacing silicon-based RF amplifiers in next-generation payloads due to superior power density and thermal performance at millimeter-wave frequencies.
METI's Space Industry Vision 2030 and JAXA's technical standards shape component qualification pathways, while Japan's Industrial Standards Committee maintains JIS benchmarks for space-grade manufacturing traceability. METI's funding mechanisms and JAXA's mission roadmaps collectively determine which domestic suppliers gain access to qualification programs and flight heritage. Stakeholders must monitor how Japan's integration with U.S. Artemis accords and bilateral technology control agreements will reshape component sourcing rules and export licensing for space electronics.
Market Dynamics
Gallium nitride RF amplifiers are compressing silicon's dominance in satellite payloads, forcing a wholesale recalibration of power system architectures across Japanese supply chains.
Growth Catalysts
- METI's Space Industry Vision 2030:Public-private funding mechanisms are de-risking domestic qualification programs for radiation-hardened components, accelerating supplier onboarding.
- Earth observation constellations:Government agency procurement for climate monitoring and defense relay missions is generating sustained demand for Ka-band communication modules.
- Kyushu's launch site cluster:Geographic concentration of vertical launch infrastructure is creating captive demand for avionics and ground control systems within a 200-kilometer radius.
Market Restraints
- Specialized substrate costs:Silicon carbide and gallium nitride wafer prices remain elevated due to limited Japanese domestic foundry capacity, constraining margin expansion for power module suppliers.
- Single-source dependencies:Certain radiation-hardened ASICs rely on qualified overseas packaging houses, creating vulnerability in qualification continuity.
- Dual-use export controls:Bilateral technology control agreements with the United States impose licensing friction on components with potential military applications, elongating sales cycles.
Strategic Opportunities
- Tokyo orbital manufacturing corridor:Underutilized precision manufacturing assets from legacy electronics sectors offer conversion potential for miniature attitude control systems.
- Lunar transfer trajectories:JAXA's Artemis-aligned roadmap is opening qualification pathways for deep-space power conditioning units with heritage requirements distinct from low-Earth orbit.
- Optical payload miniaturization:Convergence of consumer imaging sensors with space-grade thermal management is enabling new entrants in compact Earth observation cameras.
Industry Challenges
- Radiation effects engineering talent:The specialized skill set for single-event upset mitigation and total ionizing dose analysis remains concentrated among a handful of JAXA-affiliated researchers.
- Flight heritage accumulation:New component suppliers face a catch-22 where mission integrators require proven orbital performance, but heritage requires initial flight opportunities that established vendors control.
- Legacy avionics integration:Replacing silicon-based systems in operational satellites with gallium nitride alternatives requires thermal and electrical interface requalification that compresses mission schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Space Electronics Market |
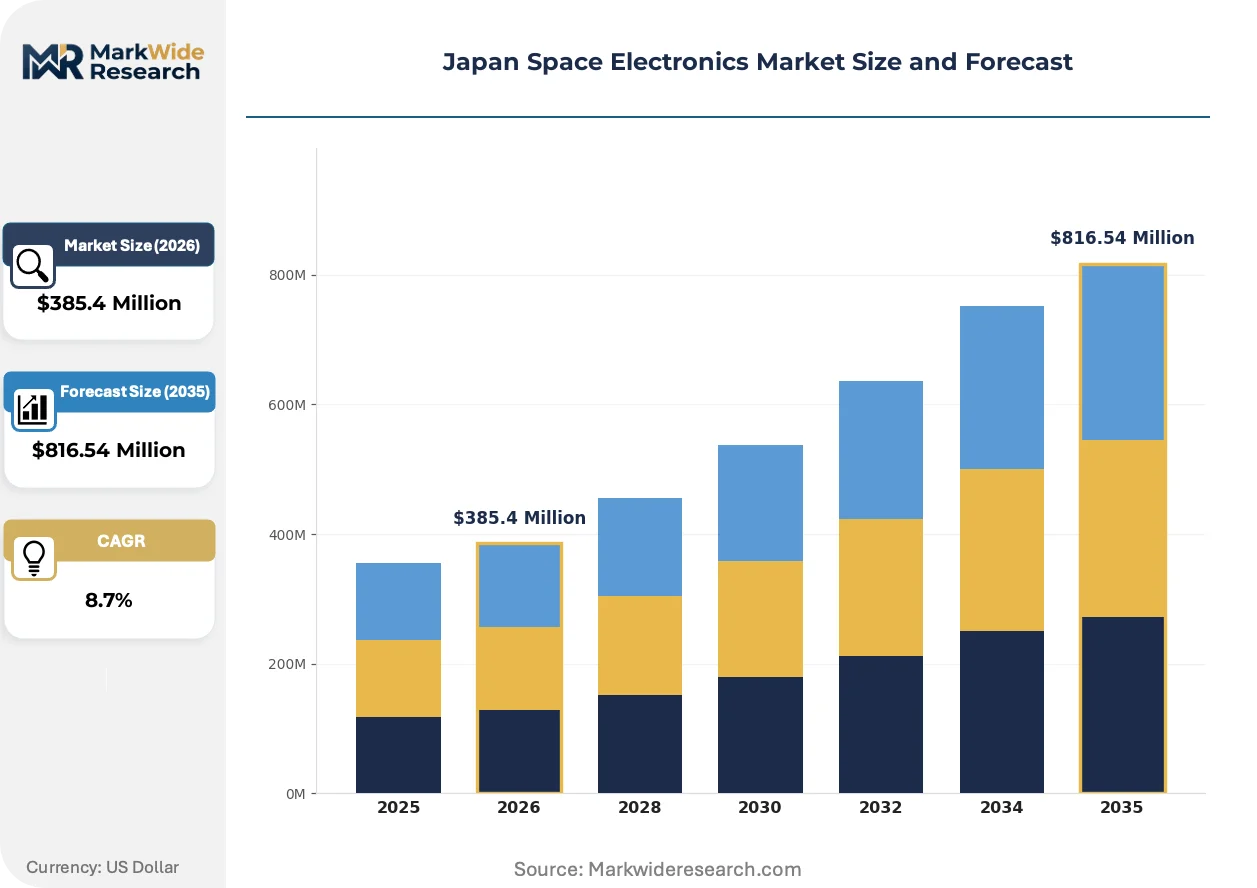
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Systems, Communication Systems, Payload Systems, Control Systems Technology: Silicon-Based, GaN, SiC, Hybrid Application: Satellite, Launch Vehicles, Deep Space Exploration, Space Science End User: Government Agencies, Private Companies, Research Institutions, Defense Organizations |
| Companies Covered | NEC, Mitsubishi Heavy Industries, Kawasaki Heavy Industries, Axelspace Corporation, Astroscale, IHI Corporation, Canon Electronics, Interstellar Technologies Inc., Space One Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Space Electronics Market Trends and Innovations
Japanese space electronics are undergoing a materials-driven performance revolution, with regulatory frameworks and procurement behaviors adapting to accommodate higher-frequency, higher-power orbital systems.
Gallium nitride high-electron-mobility transistors deliver superior power density and thermal efficiency at millimeter-wave frequencies compared to legacy gallium arsenide and silicon LDMOS alternatives. Satellite manufacturers in Tokyo's orbital manufacturing corridor are adopting these devices for next-generation Ka-band and Q-band payloads. Gallium nitride is supplanting silicon-based RF amplifiers in qualification programs, compressing the addressable market for legacy suppliers and rewarding early movers with captive design wins.
METI's Space Industry Vision 2030 establishes domestic qualification pathways independent of traditional JAXA-centered processes, reducing dependency on flight heritage accumulation through government missions. The framework mandates traceability standards aligned with JIS benchmarks while opening public procurement to commercial-grade components meeting equivalent reliability thresholds. Small satellite integrators in Kyushu's launch site cluster are leveraging this regulatory tailwind to source from non-traditional domestic suppliers previously excluded from government satellite programs.
Defense and civilian agencies are consolidating procurement through multi-year framework contracts rather than mission-specific competitive bidding, concentrating volume with suppliers demonstrating sustained qualification capacity. This buyer concentration is displacing fragmented spot-market purchasing for radiation-hardened components and power systems. The shift is most visible in Tokyo, where prime contractors are absorbing subsystem suppliers to secure long-term allocation agreements for gallium nitride modules and optical payloads.
Japan Space Electronics Market Segmentation
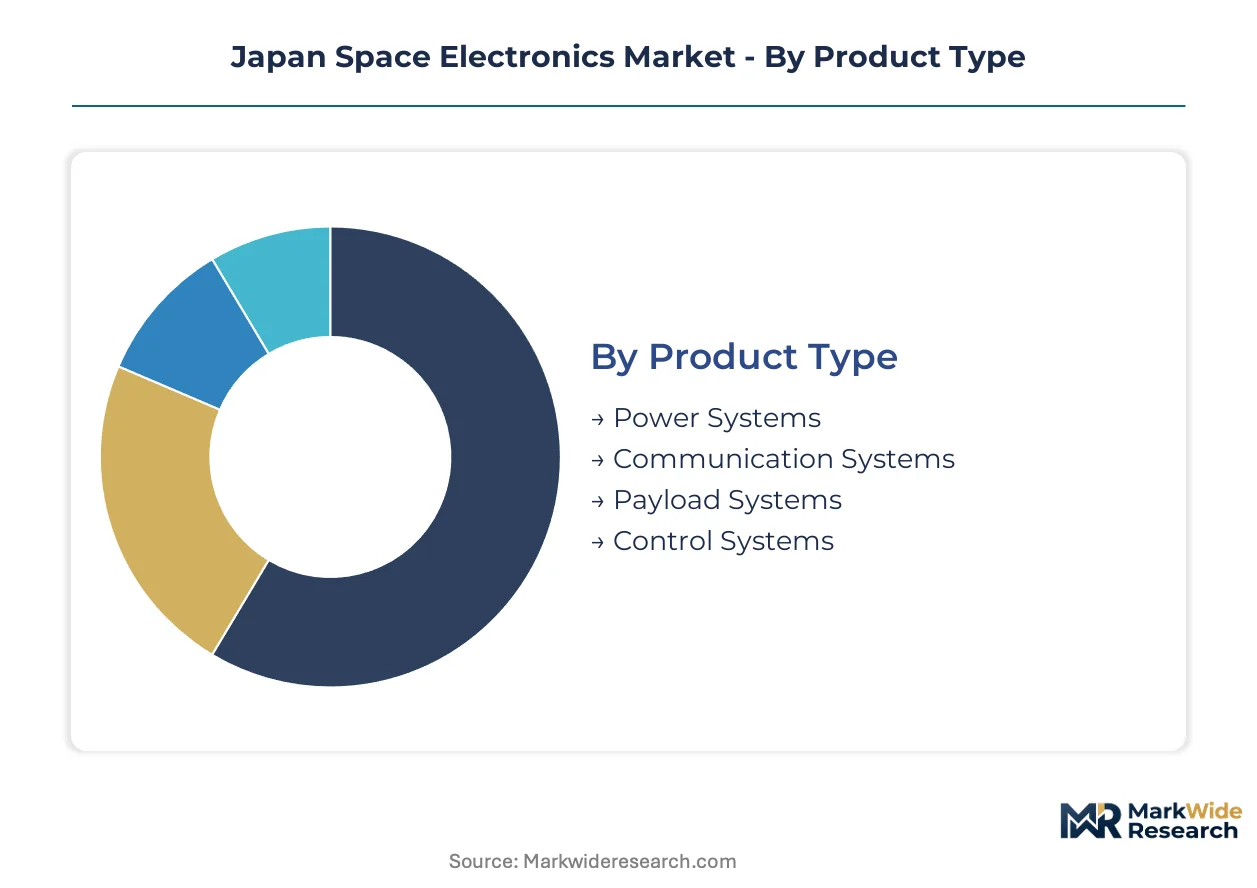
Segmentation in Japan's space electronics market reveals how METI's qualification pathways and JAXA's mission roadmaps concentrate procurement across specific product categories and end-user channels. Understanding these divisions exposes where domestic suppliers compete for flight heritage and where technology transitions create entry points for new vendors.
Product Type:
METI's Space Industry Vision 2030 establishes distinct qualification tiers for each product category, with radiation-hardening requirements varying by orbital environment and mission duration.
- Power Systems:High-efficiency power conditioning units manage orbital thermal cycling and single-event upset immunity for missions ranging from low-Earth orbit to lunar transfer trajectories. Demand concentrates in Kyushu's launch site cluster, where vertical launch infrastructure creates captive procurement for avionics suppliers within a 200-kilometer radius. METI's funding mechanisms de-risk qualification programs for domestic vendors seeking flight heritage in this category.
- Communication Systems:Ka-band communication modules and Q-band payloads incorporate gallium nitride high-electron-mobility transistors for superior power density at millimeter-wave frequencies. Tokyo's orbital manufacturing corridor dominates procurement volume as satellite integrators consolidate multi-year framework contracts with prime contractors demonstrating sustained qualification capacity.
- Payload Systems:Compact optical payloads and miniature attitude control systems serve Earth observation constellations.
- Control Systems:Radiation-hardened ASICs and guidance electronics face single-source packaging dependencies.
Power Systems handles the majority of throughput; Communication Systems is the fastest mover on share.
Technology:
Materials science differentiation drives cost tier stratification, with substrate prices and foundry capacity determining which technologies penetrate government versus commercial procurement channels.
- GaN:Gallium nitride RF amplifiers deliver superior thermal efficiency and power density, displacing silicon-based alternatives in next-generation qualification programs. Tokyo's prime contractors absorb subsystem suppliers to secure long-term allocation agreements for these modules, compressing the addressable market for legacy vendors.
- Silicon-Based:Legacy silicon LDMOS alternatives retain position in operational satellites requiring thermal and electrical interface stability. Kyushu's small satellite integrators face compressed margins here due to limited domestic foundry capacity and elevated wafer costs.
- SiC:Silicon carbide substrates enable high-temperature power conversion for deep-space missions.
- Hybrid:Mixed-technology architectures bridge qualification gaps during technology transitions.
Silicon-Based retains volume leadership through installed base replacement cycles; GaN is climbing the fastest as design wins concentrate in next-generation payloads.
Application:
Application segmentation tracks how JAXA's Artemis-aligned roadmap and defense relay programs distribute procurement across orbital regimes with distinct heritage requirements.
- Satellite:Earth observation constellations and defense relay missions generate sustained demand for radiation-hardened components across multiple orbital planes. Government agency procurement flows through METI's public-private funding mechanisms, channeling volume toward domestic suppliers meeting JIS traceability benchmarks.
- Deep Space Exploration:Lunar transfer trajectories and interplanetary missions require power conditioning units with qualification pathways distinct from low-Earth orbit heritage. JAXA's technical standards for deep-space thermal management and radiation effects engineering create specialized entry barriers.
- Launch Vehicles:Vertical launch infrastructure in Kyushu demands avionics with rapid requalification cycles.
- Space Science:Research missions impose unique instrument integration requirements.
Satellite commands the dominant procurement volume; Deep Space Exploration is expanding most quickly as Artemis-aligned missions accelerate.
End User:
Customer type segmentation exposes how procurement centralization and dual-use export controls reshape competitive access across Japan's domestic supply base.
- Government Agencies:METI and JAXA consolidate purchasing through multi-year framework contracts rather than mission-specific competitive bidding, concentrating volume with suppliers demonstrating sustained qualification capacity. This buyer concentration displaces fragmented spot-market purchasing for radiation-hardened components.
- Private Companies:Small satellite integrators in Tokyo's orbital manufacturing corridor leverage METI's regulatory tailwind to source from non-traditional domestic suppliers previously excluded from government programs. Commercial-grade components meeting equivalent reliability thresholds gain access through streamlined qualification pathways.
- Defense Organizations:Bilateral technology control agreements with the United States impose licensing friction on components with potential military applications.
- Research Institutions:University and laboratory procurement operates through JAXA-affiliated research networks.
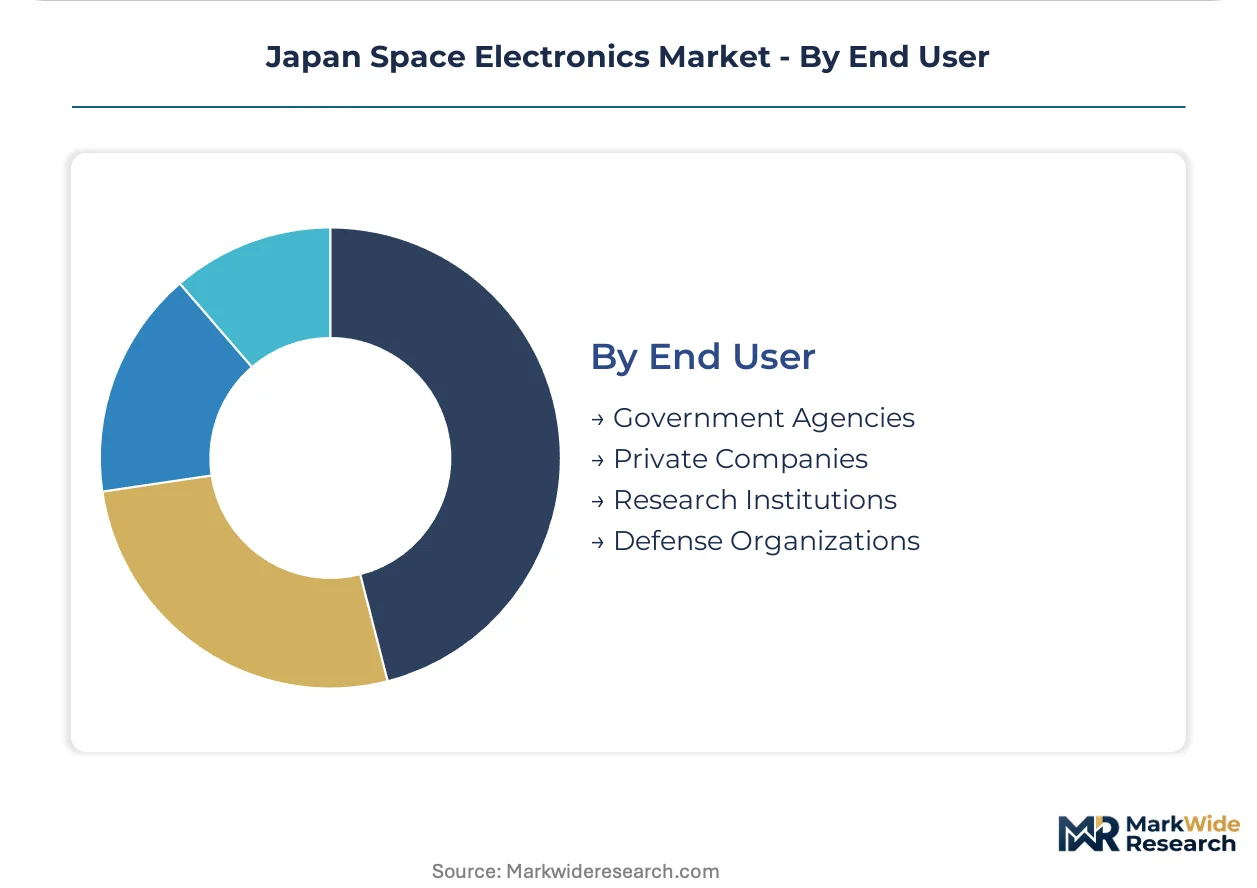
Government Agencies anchor procurement volume through consolidated framework contracts; Private Companies is gaining share fastest as commercial qualification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI anchors procurement concentration across Japan's domestic space electronics supply chain, channeling public-private investment toward specific industrial corridors and sub-regional manufacturing clusters.
Kanto/Tokyo
Earth observation constellation procurement and defense relay programs drive component demand in the capital region. METI's Space Industry Vision 2030 establishes qualification pathways for radiation-hardened suppliers operating within this corridor. Tokyo's orbital manufacturing corridor concentrates prime contractor activity for Ka-band communication modules and gallium nitride RF amplifiers.
Kyushu
Vertical launch infrastructure creates captive demand for avionics and ground control systems within a 200-kilometer radius of active sites. JAXA's technical standards shape component qualification requirements for launch vehicle electronics manufactured here. Small satellite integrators leverage streamlined regulatory pathways to source from non-traditional domestic suppliers previously excluded from government programs.
Kansai/Osaka
Legacy precision manufacturing assets from consumer electronics sectors offer conversion potential for space-grade component production. Japan's Industrial Standards Committee maintains JIS benchmarks for manufacturing traceability that suppliers here must satisfy. The region's industrial base supports subsystem suppliers seeking backward integration into power conditioning units.
Chubu/Nagoya
Aerospace engineering talent rotation from legacy aviation programs into satellite electronics loosens supply bottlenecks for domestic vendors. METI funding mechanisms de-risk qualification programs for regional suppliers seeking flight heritage. Manufacturing clusters here specialize in thermal management systems for orbital environments.
Japan Space Electronics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's space electronics supply base. The market structure consolidates around prime contractors with sustained qualification capacity, while fragmenting among subsystem specialists serving specific orbital regimes. Three archetypes dominate: vertically integrated aerospace conglomerates with captive avionics production, precision electronics specialists leveraging consumer technology heritage, and emerging small satellite integrators exploiting regulatory tailwinds. Competitive moves concentrate on strategic partnerships for gallium nitride module allocation and geographic co-location with launch infrastructure to secure captive demand.
Among established Japanese suppliers, NEC and Mitsubishi Heavy Industries occupy positions within the prime contractor tier, while Canon Electronics exemplifies the precision specialist archetype converting imaging technology heritage into optical payload capabilities. These companies represent distinct competitive vectors—government satellite systems integration, launch vehicle vertical integration, and commercial miniaturization—rather than overlapping market contests.
| Leading Market Players |
|---|
| NEC |
| Mitsubishi Heavy Industries |
| Kawasaki Heavy Industries |
| Axelspace Corporation |
| Astroscale |
| IHI Corporation |
| Canon Electronics |
| Interstellar Technologies Inc. |
| Space One Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Twenty-four-month qualification lead times for radiation-hardened components concentrate pricing power with established Japanese suppliers holding JAXA flight heritage, while METI's streamlined pathways for commercial-grade alternatives introduce competitive tension into procurement negotiations for new entrants.
Pricing Analysis
Kyushu's launch site cluster commands a 15-20% premium over Tokyo orbital manufacturing corridor pricing for comparable avionics, reflecting captive demand within the 200-kilometer radius and limited qualified supplier alternatives. Three-tier pricing structure across heritage-qualified, METI-fast-tracked, and commercial-grade reliability tiers differentiates procurement channels, with certification level and volume scale as primary price drivers. Cost compression in commercial-grade tiers intensifies because small satellite integrators leverage regulatory tailwinds to source from non-traditional domestic vendors. Defense organizations exhibit lowest price sensitivity due to bilateral technology control agreement constraints, while private companies in Earth observation constellations drive hardest bargain negotiations.
Supply Chain Analysis
Strategic stockpiling of gallium nitride wafers and silicon carbide substrates prevails over just-in-time approaches, given limited Japanese domestic foundry capacity and single-source packaging dependencies for certain radiation-hardened ASICs. Supply concentrates in Japan for prime contractor avionics, the United States for qualified packaging houses, and Taiwan for advanced semiconductor substrates. Raw material dependencies span gallium nitride wafers, silicon carbide substrates, and specialized radiation-hardened packaging materials. Single-source vulnerability in overseas packaging creates qualification continuity risk for domestic suppliers. Distribution runs through METI-consolidated framework contracts rather than fragmented spot-market purchasing, channeling volume toward prime contractors with sustained qualification capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's space electronics market exhibits cyclical recovery characteristics anchored to the satellite replenishment cycle, with Earth observation constellation procurement generating sustained demand acceleration through government agency frameworks.
For Market Incumbents: Consolidate gallium nitride module allocation agreements through backward integration into substrate sourcing, securing captive supply against foundry capacity constraints. Absorb subsystem suppliers in Tokyo's orbital manufacturing corridor to lock in long-term framework contract positioning. METI's regulatory tailwind for commercial-grade alternatives threatens heritage-premium pricing; defend through accelerated qualification of next-generation Ka-band payloads.
For New Entrants and Emerging Players: METI's Space Industry Vision 2030 qualification fast-track opens procurement access previously gated by JAXA-centered heritage requirements. Target compact optical payloads and miniature attitude control systems for Earth observation constellations in Kyushu's launch site cluster, where geographic proximity to launch infrastructure creates captive demand. Pursue white-label partnerships with Tokyo prime contractors seeking non-traditional domestic suppliers for commercial-grade component tiers.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy precision electronics conglomerates with underutilized manufacturing assets convertible to space-grade thermal management systems. Five-to-ten-year viability hinges on Artemis-aligned deep-space mission acceleration and gallium nitride technology transition completion. Monitor JAXA lunar transfer trajectory roadmap announcements as inflection indicator for deep-space power conditioning unit qualification pathway openings.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Module Allocation Agreement | Secures captive supply of gallium nitride RF amplifiers against Taiwan foundry constraints. |
| METI Fast-Track Qualification | Opens government procurement to commercial-grade components meeting JIS traceability benchmarks. |
| Kyushu Geographic Co-location | Positions suppliers within 200-kilometer radius of vertical launch infrastructure for captive demand. |
| Optical Payload Miniaturization | Converts consumer imaging sensor heritage into compact Earth observation camera capabilities. |
| Deep-Space Power Conditioning | Qualifies units for lunar transfer trajectories with thermal management distinct from low-Earth orbit. |
Research Methodology
Desk research of JAXA technical standards documentation, METI policy filings, and JIS benchmark specifications preceded structured interviews with satellite systems integrators, radiation effects engineers, prime contractor procurement leads, and small satellite startup founders. Secondary validation drew from customs trade data for space-grade component imports, METI funding disbursement records, and launch manifest databases. Bottom-up triangulation across supplier qualification pipelines and top-down reconciliation against government procurement frameworks ensured coverage completeness.
Variance decomposition across technology transitions, regulatory pathway shifts, and mission profile evolution shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, substrate technology, orbital application, and end-user procurement channel. CAGRs derived from satellite replenishment cycle timing, constellation deployment schedules, and gallium nitride penetration curves. Industry-specific inputs encompassed radiation-hardening qualification duration distributions and METI funding mechanism disbursement velocities.
Underlying assumptions cover sustained Earth observation constellation procurement, gallium nitride foundry capacity expansion trajectories, and bilateral technology control agreement stability, with deviation risk concentrated in single-source packaging house disruptions and Artemis roadmap timeline adjustments. Revision becomes warranted when Kyushu launch site operational delays cross threshold levels affecting captive demand projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
LAMEA Space As a Service Market
Space
US Space Launch Services Market
Space
Space Transportation Market
Space
Space Debris Monitoring Market
Space
Private Space Travel Market
Space
Space Designing Market
Space
US Space Electronics Market
Space
Rocket Launchpad Market
Space
Africa Space Electronics Market
Space
Spacesuit Market
Space
Space Travel Market
Space
Space Traffic Management Market
Space
Space in Orbit Refueling Market
Space
Near Space Robotics Market
Space
Asia-Pacific Space Electronics Market
Space
Space Lander and Rover Market