
 Global Airport Surveillance Radar Market | 2026-2036
Global Airport Surveillance Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Global Airport Surveillance Radar Market Intelligence
North American radar manufacturing capacity is tilting toward dual-use architectures that serve both civilian air traffic control and defense applications. Raytheon Technologies leverages its pedigree in phased-array development to sustain premium positioning in airport modernization tenders. Thales Group anchors European supply through its integrated tower solutions, while Indra Sistemas competes aggressively on price-performance in Mediterranean and Latin American bids.
Airport surveillance radar denotes ground-based sensor systems emitting radio frequency pulses to detect, track, and identify aircraft position, altitude, and velocity within terminal airspace and on movement areas; typical X-band units operate at 8.5–10.68 GHz with instrumented ranges from 60 to 110 nautical miles for primary surveillance. These systems enable safe aircraft separation, runway incursion prevention, and efficient gate-to-gate traffic sequencing. Secondary surveillance radar commands the largest installed base among product categories, though surface movement radar generates superior margins due to specialized shorter-range requirements and integration complexity with airfield lighting systems. Phased array technology leads new procurement specifications, displacing mechanically scanned architectures in major hub upgrades.
FAA NextGen mandates and ICAO Annex 10 standards shape product certification requirements, forcing manufacturers to demonstrate interoperability with automatic dependent surveillance-broadcast networks. EASA's certification framework under CS-ACNS and national military specifications from Germany's BAAINBw create parallel compliance tracks that fragment vendor qualification costs. Stakeholders must monitor how quantum radar and passive coherent location prototypes mature from laboratory demonstrations into deployable alternatives that could redefine sensor network economics.
Market Dynamics
Phased array architectures are compressing procurement cycles for airport surveillance radar as civil aviation authorities mandate solid-state replacements of mechanically scanned systems ahead of regulatory deadlines.
Growth Catalysts
- FAA NextGen Mandate:The Federal Aviation Administration's modernization program requires primary and secondary surveillance radar interoperability with automatic dependent surveillance-broadcast networks, forcing technology refresh across US terminal airspace.
- India Airport Privatization:Greenfield airport construction and brownfield upgrades under the Airports Authority of India's asset monetization program create sustained demand for surface movement radar and integrated tower solutions.
- Solid-State Transmitters:Gallium nitride-based power amplification delivers superior reliability and reduced maintenance intervals compared to magnetron-based systems, lowering total cost of ownership for airport operators.
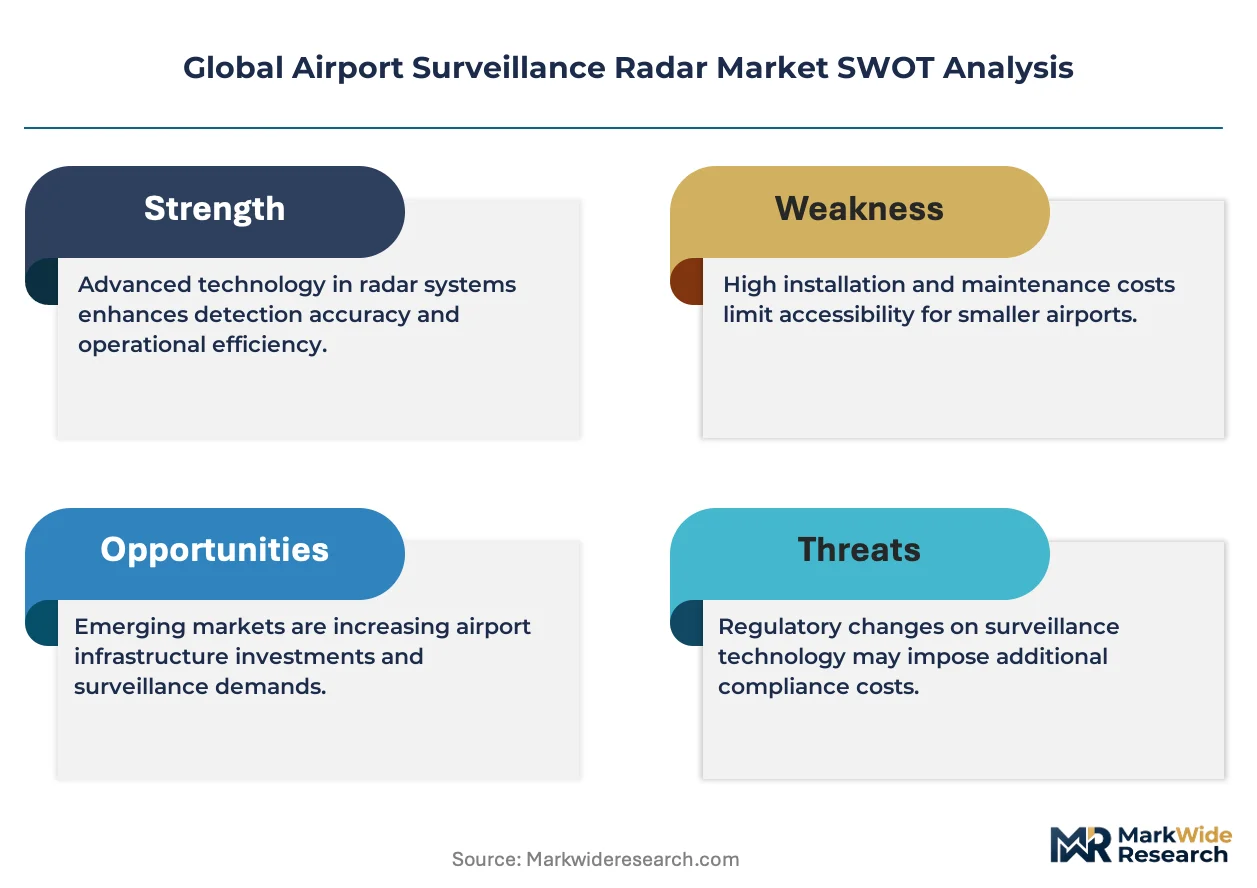
Market Restraints
- Gallium Nitride Supply Concentration:Substrate manufacturing for high-power RF components concentrates among Japanese and US suppliers, exposing radar OEMs to input cost volatility and allocation risk.
- EASA CS-ACNS Certification Timeline:European airworthiness standards for communications, navigation, and surveillance equipment impose multi-year qualification periods that delay product launches and freeze development budgets.
- Passive Coherent Location Threat:Emerging passive radar prototypes using commercial broadcast signals threaten to displace active primary surveillance radar in cost-sensitive secondary airport deployments.
Strategic Opportunities
- Indonesia Archipelago Expansion:The Ministry of Transportation's remote aerodrome development program across 17,000 islands requires portable, low-power surveillance solutions absent legacy infrastructure.
- Dual-Use Defense Convergence:Military-grade active electronically scanned array technology from naval and ground-based air defense programs transfers to civilian terminal radar applications with modified waveforms.
- EU Green Deal Procurement Incentives:The European Commission's sustainable aviation framework prioritizes energy-efficient solid-state radar in public tender scoring, advantaging next-generation suppliers.
Industry Challenges
- RF Engineer Scarcity:Specialized expertise in microwave circuit design and antenna pattern optimization concentrates among aging workforces at defense primes, constraining product development velocity at mid-tier vendors.
- Legacy System Integration Complexity:New phased array deployments must interface with 1980s-era air traffic management software through proprietary protocols, extending commissioning timelines and requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Airport Surveillance Radar Market |
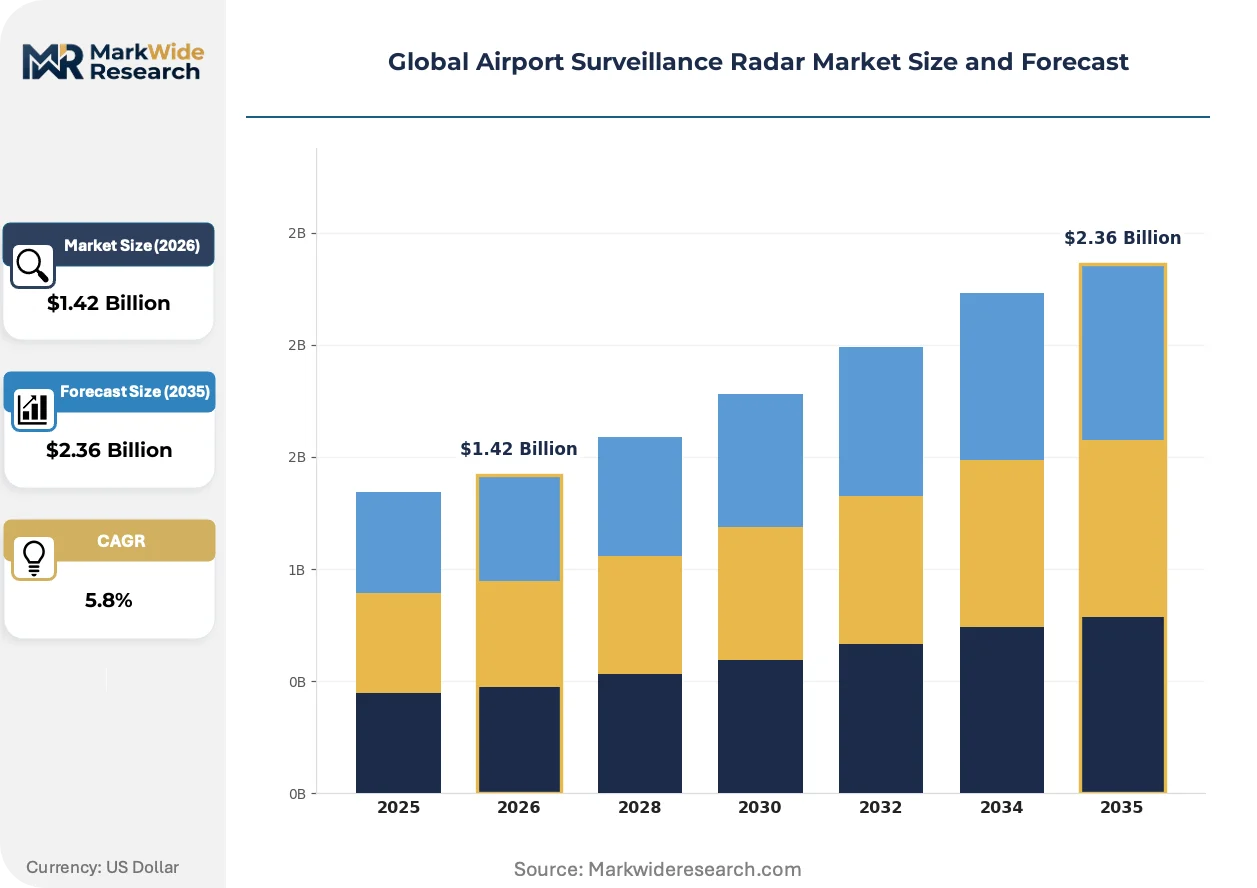
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Surveillance Radar, Secondary Surveillance Radar, Surface Movement Radar, Weather Radar, Multimode Radar Technology: Pulse Doppler, Continuous Wave, Phased Array, Frequency Modulated Continuous Wave, Synthetic Aperture Application: Air Traffic Control, Ground Vehicle Detection, Intrusion Detection, Wildlife Monitoring, Weather Observation, Runway Safety End User: Airport Authorities, Air Navigation Service Providers, Defense Agencies, Aviation Safety Organizations, Airfield Operators |
| Companies Covered | Leonardo S.p.A., Hensoldt, Raytheon Technologies, Saab AB, General Dynamics, Thales Group, Indra Sistemas, Boeing, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Airport Surveillance Radar Market Strategic Shifts & Innovations
Software-defined architectures are decoupling hardware refresh cycles from capability upgrades, allowing airport operators to field new detection algorithms through firmware rather than full system replacement.
Digital beamforming is virtualizing the traditional rotating antenna pedestal by employing stationary active electronically scanned arrays with electronic steering. Major hub airports in Germany and the United Kingdom are piloting these configurations to eliminate mechanical maintenance and enable simultaneous multi-beam tracking. This virtualization is compressing the vendor landscape by privileging semiconductor and software competencies over precision mechanical engineering heritage.
Europe's Single European Sky ATM Research program mandates harmonized surveillance performance requirements across member states, forcing national air navigation service providers to consolidate procurement specifications. The industrial consequence is standardization of interface protocols and data formats, reducing customization revenue for radar OEMs. Mediterranean and Eastern European airports are responding by pooling tender processes through regional consortiums to extract volume pricing.
Lifecycle service contracts are displacing capital purchase models as dominant transaction structures, with Brazilian and Saudi Arabian airport authorities leading the shift toward availability-based payment terms. System integrators are capturing recurring revenue streams that previously flowed to in-house maintenance teams. This transition is most visible in greenfield Middle Eastern hub developments where sovereign wealth funds prefer operational expenditure treatment for infrastructure assets.
Global Airport Surveillance Radar Market Segmentation
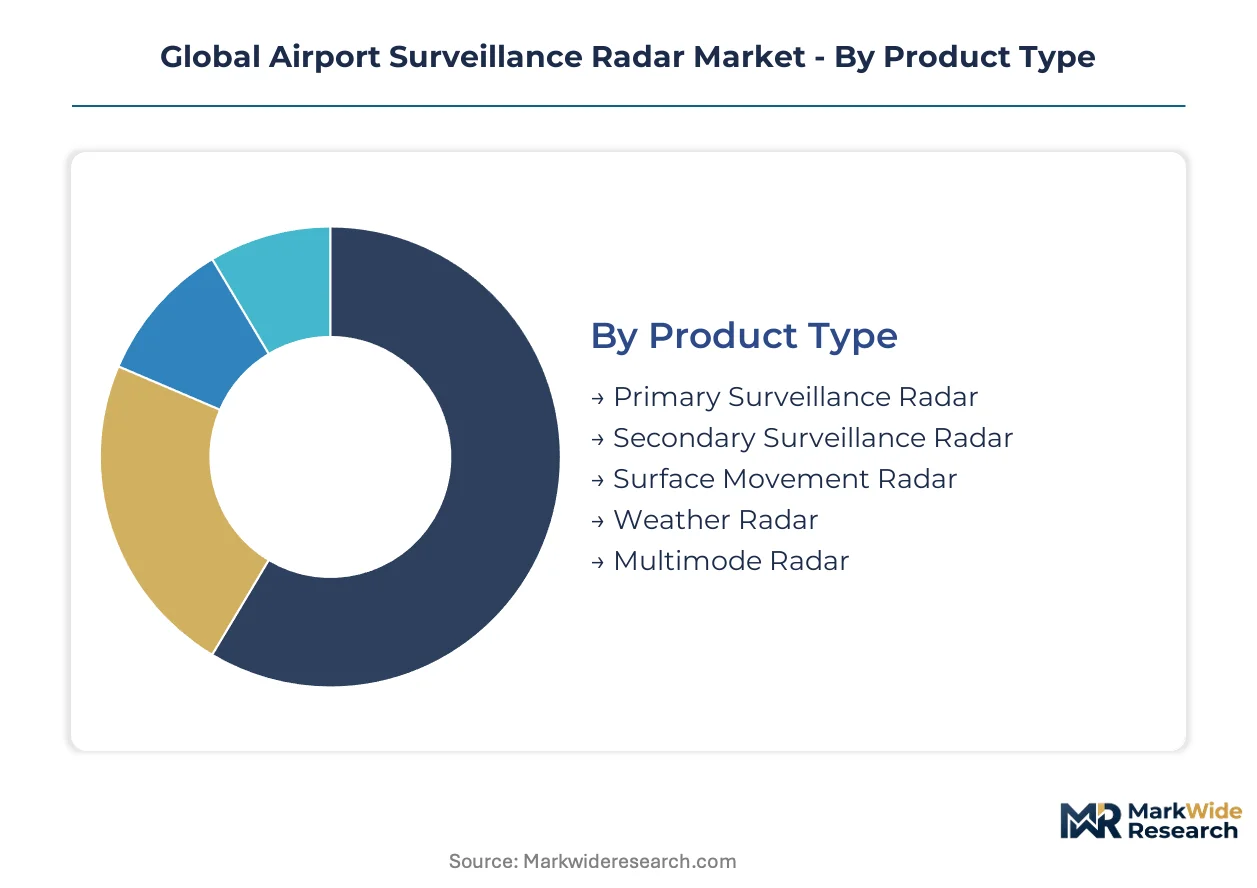
Airport surveillance radar procurement splits across multiple technical and operational dimensions, with product architecture and signal processing method determining integration complexity and lifecycle economics. Understanding these segment boundaries clarifies why phased array and solid-state configurations command premium positioning against legacy mechanically scanned alternatives.
Product Type:
Terminal airspace coverage requirements span from long-range en route separation to precise surface movement tracking, creating distinct procurement categories with divergent performance specifications and price points.
- Secondary Surveillance Radar:Interrogates aircraft transponders to retrieve identity, altitude, and emergency status alongside positional data. The FAA's NextGen mandate for ADS-B interoperability concentrates replacement demand across US terminal facilities, though magnetron-to-solid-state transmitter upgrades extend deployment timelines.
- Surface Movement Radar:X-band or Ku-band systems with sub-meter resolution track aircraft and vehicles on taxiways and aprons in low-visibility conditions. Greenfield airport construction in India and Indonesia drives procurement, where integration with A-SMGCS lighting protocols adds engineering complexity and margin capture for tower solution integrators.
- Primary Surveillance Radar:Independent echo detection without aircraft cooperation remains mandatory for non-equipped traffic and runway incursion backup.
- Weather Radar:Doppler-capable terminal systems detect wind shear, microbursts, and precipitation intensity for approach sequencing adjustments.
- Multimode Radar:Software-defined architectures combine surveillance and weather functions through waveform agility, reducing antenna count at consolidated facilities.
The dominant share belongs to Secondary Surveillance Radar, while Surface Movement Radar is closing the gap fastest.
Technology:
Transmitter architecture and beam steering method determine reliability metrics, maintenance intervals, and electromagnetic compatibility profiles across cluttered airport environments.
- Phased Array:Active electronically scanned arrays eliminate mechanical rotation through solid-state TR module arrays, enabling simultaneous multi-beam tracking and adaptive null steering against wind turbine interference. Germany's DFS and UK's NATS pilot deployments at Frankfurt and Heathrow validate operational maturity for major hub certification.
- Pulse Doppler:Range-velocity resolution through coherent processing remains the workhorse for primary surveillance, with magnetron transmitters yielding to gallium nitride solid-state alternatives in refresh programs.
- Frequency Modulated Continuous Wave:Low-power continuous illumination suits short-range surface applications with reduced spectral congestion.
- Synthetic Aperture:Post-processing range-Doppler imaging delivers high-resolution mapping for ground surveillance and foreign object debris detection.
- Continuous Wave:Unmodulated carrier systems serve specialized Doppler-only velocity measurement roles in hybrid configurations.
Phased Array claims the technology leadership position, with Pulse Doppler retaining the broadest installed base across secondary airports.
Application:
Functional deployment scope ranges from core air traffic separation to emerging safety and environmental monitoring roles that expand sensor network utilization rates.
- Air Traffic Control:Terminal area surveillance for approach, departure, and en route handoff constitutes the foundational revenue pool, with ICAO Annex 10 compliance mandating minimum performance specifications that constrain vendor qualification.
- Runway Safety:Incursion prevention through correlated multilateration and radar fusion addresses the FAA's most-wanted safety improvement priority, driving integration contracts at US Category X airports.
- Ground Vehicle Detection:Apron and perimeter monitoring for unauthorized movement supports automated alerting in low-visibility operations.
- Intrusion Detection:Perimeter radar layers augment fence sensors and video analytics for security-critical facilities.
- Wildlife Monitoring:Avian radar tracks flock movements for habitat management and strike risk assessment near wetland approach corridors.
- Weather Observation:Terminal Doppler weather radar supplements meteorological agency data for local microclimate characterization.
Air Traffic Control maintains the largest application footprint, though Runway Safety is expanding most quickly as regulatory pressure intensifies.
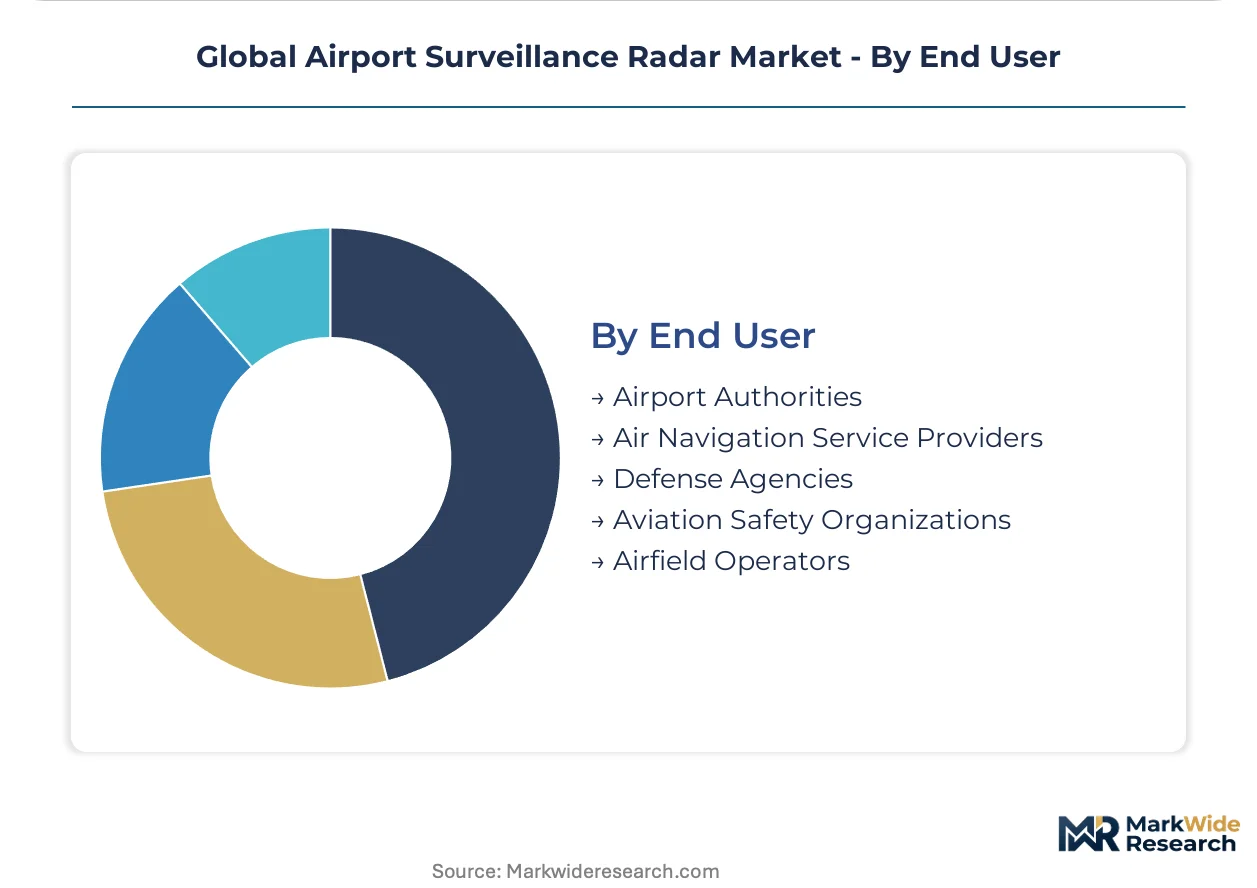
End User:
Procurement authority fragmentation across civil aviation authorities, military commands, and privatized airport operators creates divergent tender processes and technical specification cultures.
- Air Navigation Service Providers:Eurocontrol member organizations and FAA-contracted terminal radar approach control facilities consolidate multi-airport procurement through framework agreements, privileging interoperability certification and lifecycle cost models.
- Airport Authorities:Privatized operators in India, Brazil, and Saudi Arabia exercise direct capital authority for surface movement and tower-integrated systems, with availability-based service contracts displacing purchase models at greenfield developments.
- Defense Agencies:Military airfield requirements for joint-use civil-military facilities impose dual-use certification tracks that extend qualification timelines.
- Airfield Operators:Regional and general aviation airports with limited traffic density seek portable or passive radar alternatives to active primary surveillance.
- Aviation Safety Organizations:Regulatory demonstration and research radar installations support certification methodology development and alternative technology validation.
Air Navigation Service Providers command the dominant procurement volume, while Airport Authorities are gaining share fastest through privatization waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Airport's phased array deployment anchors Germany's surveillance modernization, while Heathrow's digital beamforming trials validate next-generation terminal radar architectures for major European hubs.
United States
FAA NextGen mandates drive primary and secondary surveillance radar replacements across terminal radar approach control facilities. The FAA's ADS-B interoperability requirements compress procurement timelines for magnetron-to-solid-state transmitter upgrades. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor demand concentration as Category X airports prioritize runway incursion prevention systems.
Germany
DFS Deutsche Flugsicherung pilots active electronically scanned arrays at Frankfurt and Munich airports under Europe's Single European Sky ATM Research harmonization mandate. The BAAINBw military specification creates dual-use certification tracks that extend vendor qualification periods. Bavaria's radar manufacturing cluster around Munich supplies gallium nitride transmitter modules for civilian and defense applications.
India
Airports Authority of India asset monetization and greenfield construction under the regional connectivity scheme sustain procurement pipelines for surface movement radar. DGCA mandates for A-SMGCS integration with airfield lighting systems drive tower solution specifications. Mumbai and Delhi NCR privatized airports anchor demand concentration for integrated surveillance systems.
United Kingdom
NATS digital tower programs at London City and remote aerodrome sites validate software-defined surveillance architectures. CAA certification alignment with EASA CS-ACNS standards streamlines equipment approval timelines. The Southeast England air traffic management cluster around Swanwick integrates phased array trials with legacy air traffic management infrastructure.
Indonesia
Ministry of Transportation remote aerodrome development across the archipelago requires portable, low-power surveillance solutions absent legacy infrastructure. National aviation safety committee mandates for non-precision approach capabilities drive secondary radar deployments. Java and Sumatra airport clusters anchor procurement volume as tourism corridor expansion accelerates.
Global Airport Surveillance Radar Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying gallium nitride transmitters and antenna modules. The vendor base concentrates among defense-aerospace conglomerates with dual-use radar pedigrees, creating tiered competition between full-tower solution providers and subsystem specialists. Two strategic archetypes dominate: integrated tower solution vendors capturing lifecycle service contracts, and phased array technology specialists licensing semiconductor architectures. Consolidation through defense program technology transfer and geographic expansion through regional airport privatization waves represent the dominant competitive vectors.
Within the integrated platform tier, Raytheon Technologies and Thales Group exemplify full-system providers leveraging phased-array development heritage for civilian terminal applications. Hensoldt occupies a position bridging European defense specifications and civil aviation certification tracks. These three anchors demonstrate how dual-use technology transfer from naval and ground-based air defense programs reshapes civilian radar procurement economics.
| Leading Market Players |
|---|
| Leonardo S.p.A. |
| Hensoldt |
| Raytheon Technologies |
| Saab AB |
| General Dynamics |
| Thales Group |
| Indra Sistemas |
| Boeing |
| Northrop Grumman |
| Others |
Cost & Logistics Intelligence
Gallium nitride substrate concentration among Japanese and US suppliers creates simultaneous pricing tier compression and supply chain vulnerability for radar OEMs, forcing volume-discount tiering that separates integrated tower solution providers from component specialists.
Pricing Analysis
Volume-discount tiering structures procurement across three performance levels: premium phased-array systems with full lifecycle service contracts, standard solid-state replacements for mid-tier airports, and economy magnetron-based units for regional facilities. Price differentiation hinges on certification complexity under FAA NextGen and EASA CS-ACNS standards alongside after-sales service bundling. Pricing pressure intensifies in the standard tier as Indian and Indonesian airport authorities consolidate tender processes for volume leverage. Air navigation service providers exhibit lowest price sensitivity due to framework agreement structures, while privatized airport operators in emerging economies drive hardest bargain.
Supply Chain Analysis
Export-control regimes under US ITAR and Japan's foreign exchange restrictions limit gallium nitride TR module and phased-array component flows to non-allied end users. Manufacturing concentrates in Germany, the United Kingdom, and the United States for final system integration, with substrate fabrication drawing from Japanese and US semiconductor foundries. Raw material dependencies span high-purity silicon carbide substrates, rare-earth permanent magnets for antenna positioning, and specialized aluminum alloys for radar enclosures. Single-source vulnerability in GaN epitaxial wafer supply creates allocation risk during defense program surges. Distribution runs through prime contractor-direct models for major hub deployments and regional system integrators for secondary airport retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lifecycle service contracts now expand faster than hardware shipments as Brazilian and Saudi Arabian authorities shift to availability-based payment terms, transforming capital equipment vendors into recurring-revenue service platforms.
For Market Incumbents: Entrench through captive gallium nitride module production and CS-ACNS certification pre-qualification to neutralize emerging passive radar substitutes. Vertical integration into semiconductor fabrication insulates against Japanese substrate allocation constraints. Lock in multi-airport framework agreements with Eurocontrol members before regional consortium tender pooling accelerates. For New Entrants and Emerging Players: Pursue portable low-power radar deployments across Indonesia's 17,000-island remote aerodrome program where legacy infrastructure gaps eliminate incumbent switching costs. Target surface movement radar integration contracts at Indian greenfield airports where A-SMGCS lighting protocol expertise remains scarce. Lead with software-defined architectures that decouple hardware refresh from capability upgrades. For Investors and Strategic Acquirers: The market sits at a technology-refresh phase that favors semiconductor-competent platform integrators over mechanical-heritage specialists. Long-term viability hinges on dual-use defense technology transfer pipelines and service contract recurring revenue durability. Acquisition targets should display active electronically scanned array IP and established FAA or EASA certification tracks. Watch for passive coherent location prototypes achieving operational maturity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Transmitter Vertical Integration | Captive substrate supply secures margin against Japanese allocation volatility. |
| Software-Defined Architecture Deployment | Firmware-upgradable detection algorithms extend system lifecycle without antenna replacement. |
| Dual-Use Defense Technology Transfer | Naval AESA radar modules adapt to civilian terminal applications with modified waveforms. |
| Availability-Based Service Contracting | Brazilian and Saudi sovereign wealth funds prefer operational expenditure treatment. |
| Regional Consortium Tender Participation | Mediterranean and Eastern European airport pooling extracts volume pricing from vendors. |
Research Approach
Desk research of ICAO surveillance standards documentation, FAA NextGen implementation reports, and EASA CS-ACNS certification frameworks preceded structured interviews with air traffic control system procurement directors, radar OEM product managers, and ANSP engineering leads. Secondary validation drew from Eurocontrol performance review reports, Airports Authority of India tender disclosures, and defense ministry radar program budgets. Bottom-up unit deployment tracking across 45 countries triangulated against top-down market size estimates from aviation infrastructure spending databases.
Assumptions held FAA NextGen and SESAR harmonization timelines constant while varying emerging economy privatization velocity and GaN substrate supply elasticity across scenarios. Segmentation modeling spanned product architecture, transmitter technology, application scope, and end-user procurement authority. CAGRs derived from logistic diffusion curves fitted to solid-state replacement penetration rates and greenfield airport construction pipelines. Forecast inputs included ADS-B interoperability mandates and wind turbine interference mitigation requirements.
Sensitivities concentrate around gallium nitride supply allocation shifts and passive radar technology maturation timelines. Forecasts reflect documented assumptions regarding regulatory deadline adherence and defense program technology transfer rates. Material acceleration in passive coherent location deployment or export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
UXO Detection Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Military Radar Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Global Radar Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
Tactical Scope Market